
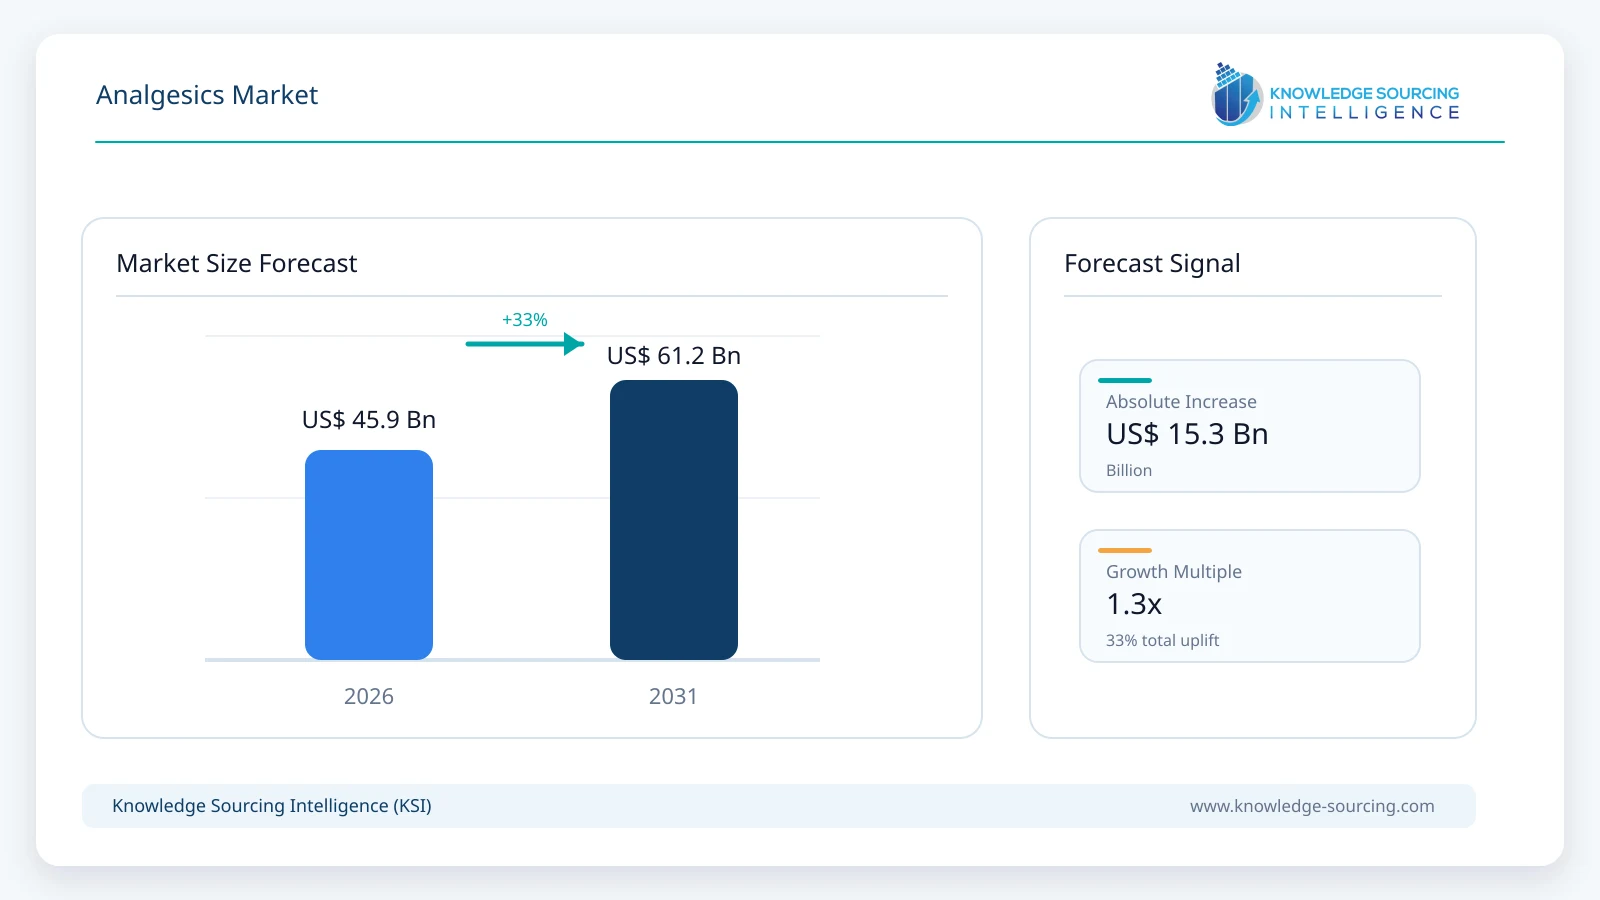
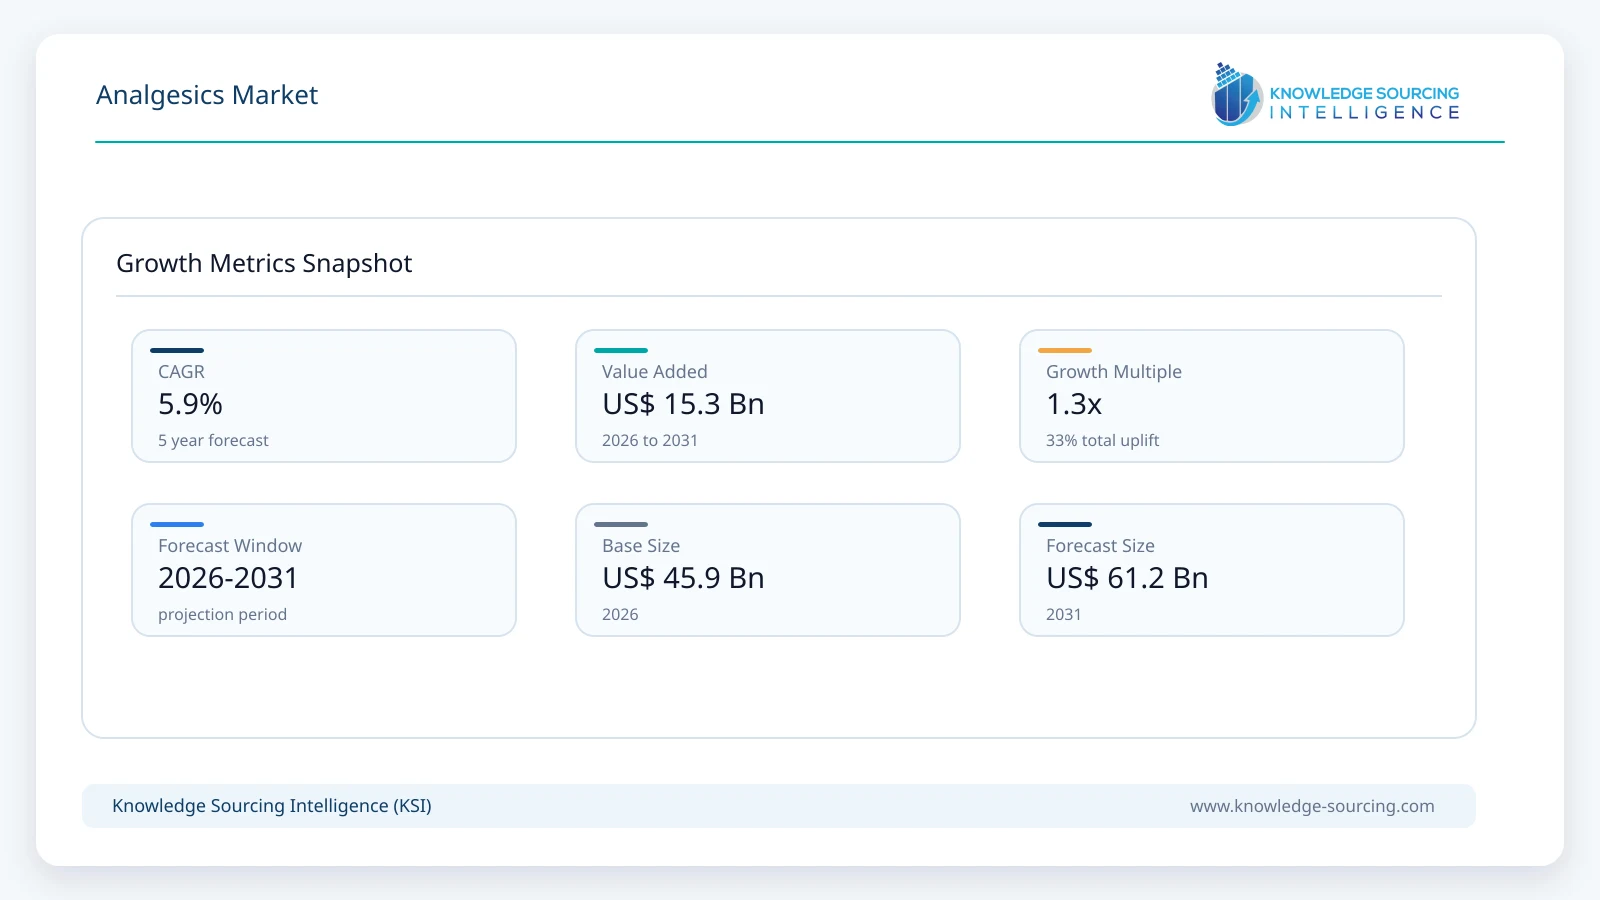
The global Analgesics Market is forecast to grow at a CAGR of 5.92%, reaching USD 61.2 billion in 2031 from USD 45.9 billion in 2026.
Highlights:
- 1Non-opioid medicines lead market revenue, supported by OTC demand and newer targeted therapies.
- 2Oral formulations remain central, while transdermal products address selected persistent-pain requirements.
- 3Migraine medicines benefit from CGRP innovation and expanding preventive and acute-treatment options.
- 4Pharmacy distribution remains dominant, with online channels gaining convenience-oriented consumer purchases.
- 5North America anchors specialist drug commercialization; Asia Pacific expands through access and demand.
- 6Safety labeling, reimbursement, and generic substitution materially influence manufacturers’ pricing power.
The analgesics market encompasses finished medicines used to relieve acute or chronic pain, including non-opioid compounds, opioid medicines and multi-ingredient formulations. Treatment extends from over-the-counter tablets and topical gels to prescription oral products, injectable hospital medicines, transdermal preparations and targeted migraine or neuropathic-pain therapies. The economic structure ranges from large generic volumes to specialist drugs whose uptake depends on clinical differentiation, prescribing rules and health-plan reimbursement.
Patient care increasingly combines medicines with rehabilitation, psychological and procedural interventions. Analgesic suppliers nevertheless retain an important role wherever appropriate pharmacological relief enables function, recovery or continuing treatment. Manufacturers compete through recognized brands, distribution reach, formulation quality, supply reliability, and evidence supporting particular indications. Changing reimbursement and safety expectations shape the relative opportunity for premium medicines and commodity products.
Market Overview
In the United States, 24.3% of adults reported chronic pain in 2023, including 8.5% whose pain frequently limited work or daily activities, according to the CDC. These figures help explain the continuing need for varied treatment pathways, but they do not translate directly into analgesic prescriptions. Patients with recurrent musculoskeletal pain, migraine, cancer-related symptoms and postoperative pain differ in treatment duration, monitoring requirements and response to individual medicines.
Two 2025 product approvals broadened the commercial landscape for non-opioid treatments. Vertex received FDA approval for JOURNAVX (suzetrigine) for moderate-to-severe acute pain, while Tonix launched TONMYA (cyclobenzaprine hydrochloride sublingual tablets) in November for adult fibromyalgia. Each product addresses a defined indication; neither replaces inexpensive nonprescription analgesics across the broader pain spectrum. Their launches make prescriber education, formulary placement and demonstrated real-world value more consequential.
Established consumer-health companies continue developing the delivery and brand architecture of familiar drugs. Haleon's Advil, Panadol and Voltaren portfolios and Bayer's Aleve and Aspirin franchises operate alongside Kenvue's Tylenol and Motrin ranges. Prescription specialists such as AbbVie, Pfizer and Grünenthal compete more directly through molecule-specific clinical evidence, licensed geographical rights and reimbursement access.
Market Trends
Selective Non-Opioid Mechanisms Are Expanding Acute-Pain Choices
Vertex's JOURNAVX targets the NaV1.8 peripheral pain-signaling channel and received FDA approval in January 2025. During the second quarter of 2026, Vertex reported USD 50 million in product revenue and approximately 535,000 filled prescriptions. Those figures reveal commercial traction but also show that a new mechanism must establish routine use across hospitals and retail pharmacies before it can materially alter a large generic market.
The economic opportunity lies in clinical pathways where opioid avoidance is valuable, and an alternative can justify its acquisition price. Hospitals examine approved indications, comparative evidence, pharmacy-benefit access, and discharge protocols. Successful commercialization therefore depends on more than physician interest; it also requires dependable formulary inclusion and cost-effective deployment across commonly treated surgical and trauma-related conditions.
Migraine Therapy Is Becoming More Segmented by Treatment Objective
CGRP-targeted therapies distinguish acute relief from attack prevention, allowing companies to compete on the frequency and severity of migraine symptoms rather than on headache treatment alone. AbbVie reported second-quarter 2026 combined UBRELVY and QULIPTA revenue of USD 742 million. The European Commission's June 2026 approval added acute treatment to AQUIPTA's existing preventive indication in adults, providing a broader European prescribing role.
Specialist therapies raise the value of disease-specific evidence but introduce prior-authorization and affordability challenges. Migraine patients may require both a rescue medicine and a preventive regimen, and providers evaluate the contribution of each separately. This favors suppliers with clear labeling and patient-support arrangements rather than simply the largest selection of dosage forms.
Topical and Alternative Delivery Formats Address Persistent Pain
Topical diclofenac gels, capsaicin patches and transdermal opioid products serve clinical or consumer use cases where a conventional oral tablet is not optimal. Haleon noted 2026 introductions of Voltaren 2% Gel in India and Saudi Arabia, while Grünenthal continued pursuing country-level rights for Qutenza, a topical capsaicin patch for peripheral neuropathic pain. These products have very different safety profiles and dispensing requirements despite the shared skin-applied route.
Localized delivery can be attractive for patients seeking targeted treatment or those with limitations on systemic medicines. Manufacturers must still demonstrate correct application, exposure controls, and clinically appropriate use. For prescription patches, administration facilities and trained staff may affect access as much as product availability; in OTC gels, shelf visibility and brand recognition matter more.
Combination Products Are Competing on Convenience and Multimodal Care
Consumer pain portfolios increasingly offer formulations combining established analgesic molecules or altering release and dosing convenience. Haleon markets Advil Dual Action with acetaminophen and ibuprofen, illustrating how two familiar mechanisms can be offered in one product. Combination positioning responds to users who seek straightforward relief without managing multiple products, although clinical benefits and dose limitations remain formulation-specific.
Manufacturers face a demanding labeling task. A patient may already be taking acetaminophen in cold remedies or another NSAID, increasing the consequences of duplicate dosing. Packaging, pharmacy guidance and clear ingredient declarations are therefore commercial differentiators as well as safety responsibilities, particularly where an online sale reduces direct pharmacist interaction.
Market Access and Local Partnerships Determine Premium-Drug Reach
Grünenthal agreed in September 2026 to work with DKSH on bringing Qutenza, Vimovo, Palexia and Zomig to eight Asia-Pacific markets, subject to local approvals. Tonix also reported expanded US payer arrangements for TONMYA during 2026. Such developments show that a product's addressable population is not equivalent to its reimbursed, prescription-ready patient base.
Companies entering additional markets must establish registration, pharmacovigilance, pricing and distribution arrangements adapted to each country. Distribution rights can accelerate launch without requiring a new owned sales organization, but delayed authorizations and local reimbursement restrictions affect realized revenue. As a result, international commercial coverage is more useful to forecast than headline counts of theoretical patients.
Segment Analysis
By Drug Type: Non-opioid
Non-opioid medicines account for the majority of analyst-estimated market value because high-volume acetaminophen and NSAID use is reinforced by branded OTC distribution and the growth of specialist alternatives. The category covers products with markedly different price points and clinical purposes, from short-course ibuprofen for common pain to suzetrigine for moderate-to-severe acute pain and targeted migraine medicines.
Non-opioid revenue is projected to approach USD 42.846 billion in 2031. Expansion will reflect both patient demand and changes in product mix as premium non-opioid prescriptions grow alongside established generics. The category's commercial strength should not obscure constraints on NSAID use or the fact that newer products require distinct evidence and payer access.
By Route of Administration: Oral
Oral tablets, capsules and dissolving formulations remain the default route for a large share of outpatient analgesic use. Their convenience supports OTC self-care and the prescribing of oral migraine drugs such as rimegepant and atogepant. Manufacturers benefit from established manufacturing and distribution infrastructures, though product success increasingly depends on whether a new formulation improves dosing, adherence, or the patient's treatment experience.
The oral category is expected to reach approximately USD 35.501 billion by 2031. Hospital injections remain necessary for selected acute and postoperative cases, and transdermal or topical medicines serve different clinical needs. A patient's pain severity, gastrointestinal tolerability, swallowing ability, and treatment setting determine the route more directly than supplier preference.
By Application: Surgical and Trauma
Postoperative and trauma-related pain generate significant demand for short-duration analgesic treatment, including combinations of non-opioid and opioid medicines used under clinical protocols. Hospitals make product selections according to onset, duration, adverse-event risks, and safe discharge planning. The introduction of suzetrigine has widened choices for certain patients, but adoption must be supported by comparative clinical evidence and reimbursement economics.
Surgical and Trauma applications represent an estimated USD 11.005 billion in 2026. Demand is closely tied to procedure volume, injury burden and perioperative care practice rather than a steady chronic prescription base. Buyers place greater weight on dependable supply, dose flexibility and hospital formulary decisions than on consumer advertising.
By Distribution Channel: Offline
Community pharmacies, hospital pharmacies and clinics retain the principal commercial role because prescription validation and counseling are central to many analgesic purchases. Opioids and selected specialist medicines require controlled dispensing and insurance authorization; even common OTC products benefit from face-to-face guidance where customers have complex conditions or take several drugs.
Offline distribution is modeled at approximately USD 50.803 billion in 2031, although online channels are growing more rapidly from a smaller base. Regulated pharmacy e-commerce offers refill and convenience advantages, but the legal status of online supply differs substantially by country. The distinction matters for manufacturers allocating marketing expenditure and for distributors assessing their addressable patient base.
Market Drivers
Chronic Musculoskeletal and Neuropathic Disease
The CDC's 2023 survey found a high prevalence of chronic pain among US adults, especially in older age groups. WHO also estimated 619 million people experienced low back pain globally in 2020. These conditions create recurring clinical demand, although not every patient requires long-term medication, and nonpharmacological treatment remains important.
Analgesic manufacturers benefit when medicines address a clearly identified component of the patient's symptoms. Neuropathic pain, inflammatory pain, and mechanical discomfort may require different mechanisms, making broad portfolio coverage more valuable than a single undifferentiated pain claim.
Broader Evidence-Based Non-Opioid Options
Newly approved non-opioid medicines are giving clinicians alternatives in selected acute and persistent pain conditions. Vertex's suzetrigine approval and Tonix's fibromyalgia product launch demonstrate different innovation routes, one based on peripheral sodium-channel inhibition and another on a specialized sublingual formulation.
The growth mechanism is commercially meaningful where an improved risk-benefit profile encourages inclusion in treatment pathways. However, medical acceptance depends on label scope, patient eligibility, comparative data, and total treatment cost; new prescriptions should not be inferred from approval alone.
Higher Demand for Condition-Specific Migraine Treatment
Migraine treatment has shifted toward targeted CGRP agents and differentiated acute and preventive regimens. AbbVie's 2026 AQUIPTA European label expansion and its UBRELVY and QULIPTA sales illustrate the commercial attraction of specialized indications with substantial functional impact on patients.
Payers may accept higher prices when treatment reduces disabling attacks or addresses unmet needs under documented criteria. Manufacturers that support neurologist prescribing and appropriate reimbursement can gain share, while generics remain relevant for patients who respond to conventional analgesics.
Accessible Pharmacy Networks and Responsible Self-Care
A large OTC analgesics category relies on dependable community-pharmacy and retail distribution of established products such as acetaminophen, ibuprofen and naproxen. Brand familiarity and convenient pack sizes support demand for short episodes of headache, musculoskeletal discomfort and fever-associated pain where appropriate.
Online pharmacy services can widen access, particularly to repeat products, but verified supply chains and clear labeling are necessary to limit counterfeit medicines or inappropriate use. Producers with reliable stock availability and differentiated formulations retain a competitive edge even in mature generic categories.
New Partnerships Extend Geographical Commercial Reach
Grünenthal's September 2026 DKSH agreement was structured to seek approvals and commercialize up to four pain medicines in eight Asia-Pacific markets. Such agreements allow originators to reach customers without replicating full local infrastructure while giving distributors access to established prescription portfolios.
The same expansion logic supports OTC brands through regional retailers and local manufacturing arrangements. Actual growth follows marketing authorizations, prescriber familiarity, and payer decisions, not the signing of an agreement alone; country rollout and pricing conditions influence when revenue appears.
Market Restraints
Safety Limits for NSAIDs and Acetaminophen
NSAIDs carry gastrointestinal, renal, and cardiovascular considerations, particularly with certain patient histories or prolonged exposure. Excess acetaminophen can cause serious liver injury, and concurrent use of multiple products containing the same ingredient increases the risk of unintentional overdose. Such limitations complicate self-medication even when products are legally sold without a prescription.
Manufacturers must invest in clear labeling and pharmacovigilance while pharmacists and clinicians guide patients toward suitable products. Product availability does not necessarily increase usage in higher-risk groups, limiting the addressable market for some formulations.
Opioid Misuse Risks and Prescribing Controls
Opioid medicines remain important for selected severe pain but are associated with dependence, misuse and overdose risks. Controlled prescribing, dispensing restrictions and scrutiny of dose duration constrain volume growth and increase compliance requirements for producers and distributors.
Reimbursement policy, clinical guidelines and risk-mitigation programs favor careful patient selection and monitoring. Market competitors consequently focus on appropriately indicated formulations and safer alternatives rather than assuming continued expansion of high-strength opioid volumes.
Generic Competition and Purchasing Pressure
Many widely used analgesic ingredients are off-patent, and hospital tenders or pharmacy substitution can pressure prices despite stable treatment demand. Scale, manufacturing quality, and availability determine competitiveness for commodity tablets and injectables, often leaving narrow margins on standard presentations.
Higher-value brands and novel molecules may counter this pressure through convenience or clinical differentiation, but their price premiums need evidence. Portfolio economics increasingly depend on a mix of volume products and specialty medicines rather than relying on unit-price growth across the market.
Insurance Restrictions on Innovative Therapies
New non-opioid prescriptions and targeted migraine agents may require formulary review, prior authorization, or patient cost sharing. Vertex and Tonix have publicized payer-coverage expansion during 2026, underscoring the effort required between regulatory approval and routine treatment access.
Coverage does not guarantee utilization: physicians must adopt protocols and patients must find the medication affordable and suitable. The resulting delay can lengthen commercialization cycles, especially for therapies competing with low-cost generic comparators.
Non-Drug Modalities and Uneven Treatment Response
Physiotherapy, exercise-based rehabilitation, psychological approaches and interventional procedures remain important elements of pain care. WHO's chronic low-back-pain guidance emphasizes comprehensive assessment rather than a default medicine-only response, limiting the assumption that every increase in pain prevalence leads to an equivalent increase in drug sales.
Pain mechanisms vary between patients, and a therapy effective for one indication may offer limited benefit for another. Clinicians therefore adjust or discontinue treatments based on response and adverse effects, leaving manufacturers reliant on well-defined indications and real-world treatment persistence.
Regional Outlook
North America
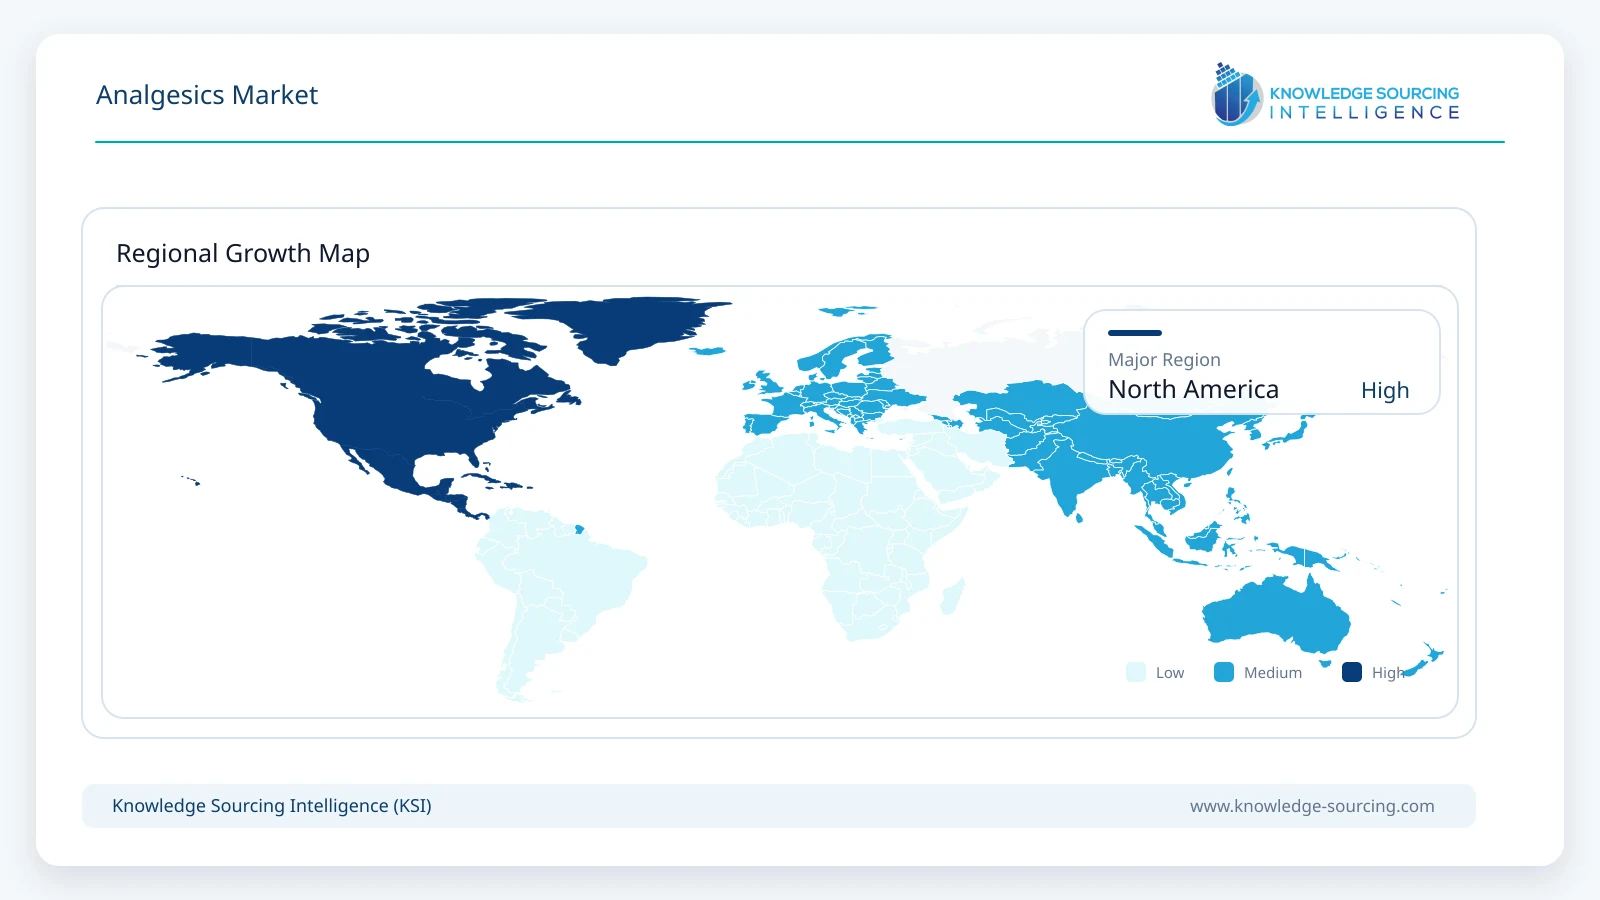
North America remains the largest estimated analgesics market because of its substantial branded prescription sector, OTC pharmacy sales, and established specialist pain-management pathways. An estimated 39% of global revenue is attributed to the region in 2026, equivalent to approximately USD 17.884 billion. The United States accounts for most of that value, with approved novel drugs receiving intensive commercial efforts around insurance coverage and hospital protocols.
The US market combines mature low-cost analgesics with targeted growth opportunities in migraine, postoperative pain and fibromyalgia. Vertex's 2026 JOURNAVX performance and Tonix's launch experience indicate the value of payer coverage and prescriber outreach. Canada and Mexico have different pricing and reimbursement structures; manufacturers seeking regional expansion must account for those differences rather than assume uniform US-equivalent economics.
Asia Pacific
Asia Pacific is estimated to have the fastest revenue growth among the modeled regions, with a 2026–2031 CAGR of roughly 9.6%. The forecast reflects broader pharmacy distribution, population scale and gradual adoption of specialty pain treatments, alongside continued high-volume generic consumption. China, India and Japan are distinct commercial markets, while Southeast Asian markets often depend more strongly on local registration and distribution partners.
Grünenthal's September 2026 agreement to commercialize selected medicines across eight Asia-Pacific territories illustrates this country-specific expansion model. Manufacturers need to balance affordability for common analgesics with the clinical and regulatory investment required for premium treatments. Differences in prescription access, reimbursement and medical infrastructure will make growth uneven across the region, even where the burden of pain is substantial.
Competitive Landscape
The competitive structure has two overlapping groups with different sources of advantage. Consumer-health companies such as Haleon, Kenvue and Bayer compete through widely recognized brands, pharmacy relationships and practical product formats. Generic manufacturers and API suppliers emphasize cost discipline, production scale and quality assurance. Specialty pharmaceutical companies differentiate through patented molecules, clinical trial evidence, payer access and country licensing rights.
Vertex's JOURNAVX entry establishes a newer non-opioid mechanism in acute pain, whereas AbbVie and Pfizer participate in CGRP-based migraine treatment. Grünenthal has a concentrated prescription pain portfolio encompassing topical capsaicin, opioids and other therapies, and Tonix is building a fibromyalgia franchise around TONMYA. These products cannot be compared using a single price or unit-volume metric because they serve different indications, duration of therapy, and procurement pathways.
Competitive positioning also depends on current corporate identity. Tylenol is a Kenvue brand rather than an independent listed manufacturer, and pharmacies or hospitals are customers and care intermediaries rather than medicine makers. Manufacturers serving multiple countries must manage product registrations, adverse-event reporting and distribution agreements; no individual company market-share percentage has been inferred from public information.
Recent Developments
28 September 2026: Grünenthal and DKSH agreed to expand access to Qutenza, Vimovo, Palexia and Zomig in eight Asia-Pacific markets. Local approvals remain pending where required; the agreement extends the potential distribution footprint rather than confirming immediate sales.
22 September 2026: Tonix Pharmaceuticals announced additional managed-Medicare coverage for TONMYA, taking its stated commercial and government payer access to approximately 166 million covered US lives. Payer inclusion strengthens commercialization of the fibromyalgia medicine.
3 August 2026: Vertex Pharmaceuticals reported USD 50 million of second-quarter JOURNAVX revenue, with approximately 535,000 prescriptions filled that quarter. The figures show measurable uptake of a new non-opioid acute-pain class after its 2025 approval.
31 July 2026: AbbVie disclosed second-quarter global UBRELVY sales of USD 392 million and QULIPTA sales of USD 350 million, illustrating the expanding commercial importance of targeted migraine treatment.
2 June 2026: AbbVie announced European Commission approval for AQUIPTA (atogepant) as an as-needed acute migraine treatment in adults, adding to its preventive indication and broadening its European use.
6 May 2026: Tonix Pharmaceuticals reported an agreement covering approximately 35 million US commercial lives for TONMYA. The access step followed its November 2025 launch and demonstrates the role of reimbursement in new pain medicines.
Market Outlook
Analgesic demand through 2031 is likely to be supported by a persistent need for treatment of common pain, postoperative symptoms, migraine and chronic disorders. The fastest value migration is likely in therapies whose mechanisms and outcomes justify specialist reimbursement, particularly non-opioid prescription alternatives and migraine-focused medicines. Established OTC products will remain economically important, with branding, convenient formats and distribution efficiency determining performance in mature markets.
Longer-term supplier advantage will depend on clinical differentiation, safety and access rather than product count alone. Branded innovators must convert approvals into repeat prescriptions, while high-volume manufacturers need dependable quality and competitive production costs. Asia Pacific distribution partnerships could broaden access to specialized therapies, but regional policy differences and the continued role of non-drug care will temper any expectation of uniform growth.
Analgesics Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 45.9 billion |
| Total Market Size in 2031 | USD 61.2 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 5.92% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Drug Type, Route Of Administration, Application, Distribution Channel |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Drug Type
Opioid
Non-opioid
Compound Medication
By Route Of Administration
Oral
Parenteral
Transdermal
Others
By Application
Surgical and Trauma
Cancer
Neuropathic
Migraine
Pediatric
Others
By Distribution Channel
Offline
Online
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Chronic Musculoskeletal and Neuropathic Disease
3.1.2. Broader Evidence-Based Non-Opioid Options
3.1.3. Higher Demand for Condition-Specific Migraine Treatment
3.1.4. Accessible Pharmacy Networks and Responsible Self-Care
3.1.5. New Partnerships Extend Geographical Commercial Reach
3.2. Market Restraints
3.2.1. Safety Limits for NSAIDs and Acetaminophen
3.2.2. Opioid Misuse Risks and Prescribing Controls
3.2.3. Generic Competition and Purchasing Pressure
3.2.4. Insurance Restrictions on Innovative Therapies
3.2.5. Non-Drug Modalities and Uneven Treatment Response
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Peripheral Sodium-Channel Inhibition
4.2. CGRP Receptor Antagonism and Preventive Treatment
4.3. Topical and Controlled-Delivery Formulations
5. ANALGESICS MARKET BY DRUG TYPE
5.1. Introduction
5.2. Opioid
5.3. Non-opioid
5.4. Compound Medication
6. ANALGESICS MARKET BY ROUTE OF ADMINISTRATION
6.1. Introduction
6.2. Oral
6.3. Parenteral
6.4. Transdermal
6.5. Others
7. ANALGESICS MARKET BY APPLICATION
7.1. Introduction
7.2. Surgical and Trauma
7.3. Cancer
7.4. Neuropathic
7.5. Migraine
7.6. Pediatric
7.7. Others
8. ANALGESICS MARKET BY DISTRIBUTION CHANNEL
8.1. Introduction
8.2. Offline
8.3. Online
9. ANALGESICS MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. Germany
9.4.2. France
9.4.3. United Kingdom
9.4.4. Spain
9.4.5. Others
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. UAE
9.5.3. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. India
9.6.3. Japan
9.6.4. South Korea
9.6.5. Indonesia
9.6.6. Thailand
9.6.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Haleon plc
11.2. Kenvue Inc.
11.3. Bayer AG
11.4. Vertex Pharmaceuticals Incorporated
11.5. AbbVie Inc.
11.6. Pfizer Inc.
11.7. Grünenthal GmbH
11.8. Tonix Pharmaceuticals Holding Corp.
11.9. Eli Lilly and Company
11.10. Teva Pharmaceutical Industries Ltd.
11.11. Farmson Basic Drugs Private Limited
11.12. Hikma Pharmaceuticals PLC
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES





Frequently asked questions
What is the projected Analgesics Market size and CAGR by 2031?
Market projected to reach USD 61.2 billion in 2031, growing at 5.92% CAGR.
Which product type leads Analgesics Market revenue?
Non-opioid medicines lead market revenue, supported by OTC demand and therapies.
Which region anchors specialist drug commercialization?
North America anchors specialist drug commercialization; Asia Pacific expands access.
What is the dominant distribution channel for analgesics?
Pharmacy distribution remains dominant; online channels gaining convenience-oriented purchases.
What influences manufacturers' pricing power in this market?
Safety labeling, reimbursement, and generic substitution influence manufacturers' pricing power.
How do CGRP innovations impact migraine treatments?
Migraine medicines benefit from CGRP innovation and expanding treatment options.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Analgesics Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/analgesics-market