
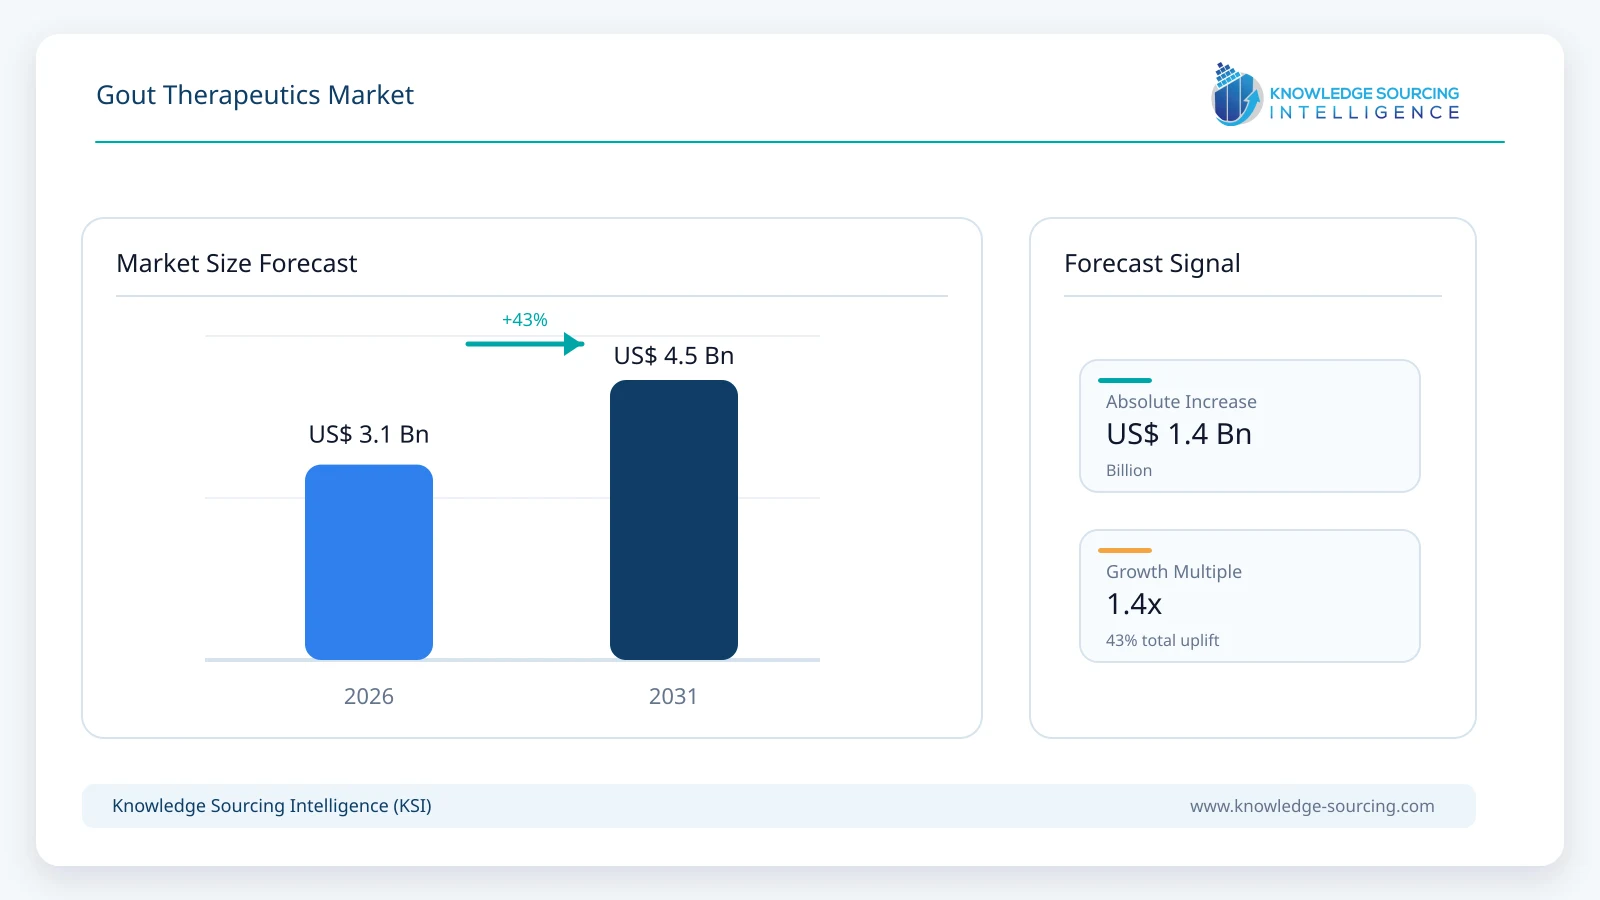
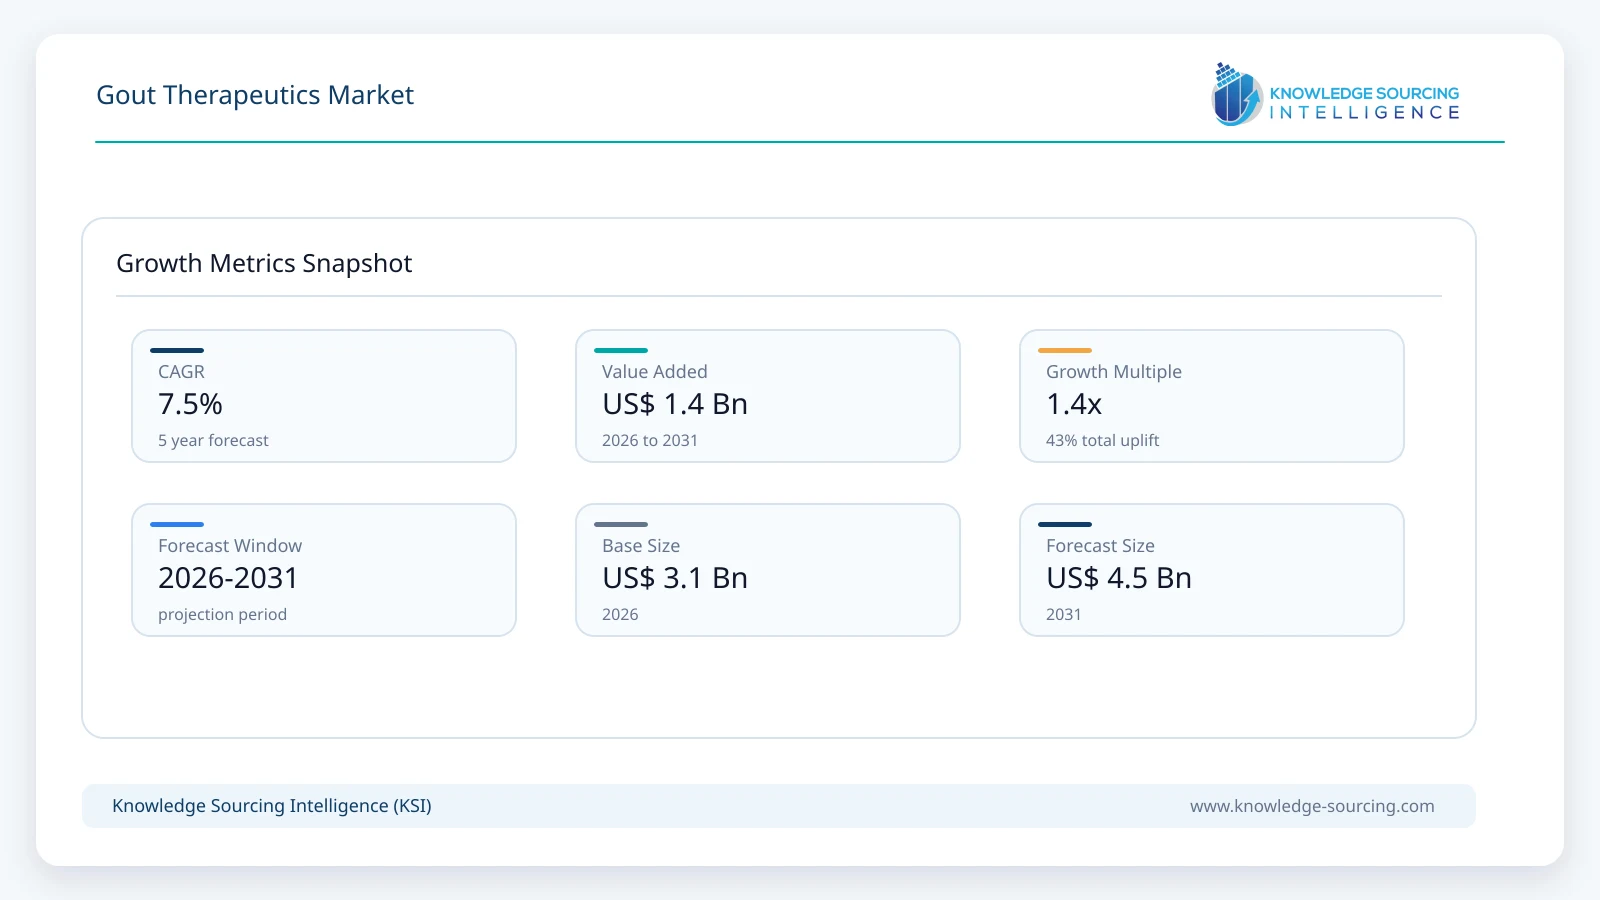
The gout therapeutics market is forecast to grow at a CAGR of 7.5%, reaching USD 4.50 billion in 2031 from USD 3.14 billion in 2026.
Highlights:
- 1The increasing global burden of gout, alongside population ageing and metabolic risk factors, is expanding demand for acute-flare management and long-term urate-lowering therapies.
- 2Rising obesity prevalence, chronic kidney disease, and associated metabolic disorders are strengthening the need for individualized gout treatment and sustained serum uric acid control.
- 3Greater clinical awareness, improved diagnostic capabilities, and guideline-supported treatment strategies are encouraging earlier intervention and more consistent long-term disease management.
- 4Clinical advances in selective uric acid transporter inhibitors, alternative xanthine oxidase inhibitors, and biologic therapies are expanding the pipeline for patients with difficult-to-treat gout.
Gout therapeutics comprise pharmaceutical treatments used to relieve acute gout attacks, reduce elevated serum uric acid concentrations, prevent recurrent inflammatory episodes, and manage advanced disease. Gout develops when monosodium urate crystals accumulate in and around joints, triggering inflammation, severe pain, swelling, and restricted movement. Repeated episodes can lead to tophi, joint damage, and chronic disability if the underlying hyperuricemia remains inadequately controlled.
The gout therapeutics market is supported by the growing global disease burden, increasing recognition of gout as a chronic condition requiring sustained management, and continued research into medicines that improve urate control. According to a 2024 analysis published in The Lancet Rheumatology, based on Global Burden of Disease Study 2021 estimates, approximately 55.8 million people worldwide had gout in 2020. The study projected that the number of prevalent cases could reach approximately 95.8 million by 2050, primarily because of population growth and ageing. These estimates highlight the long-term need for accessible diagnosis, effective flare management, and preventive treatment.
The market also benefits from the development of medicines targeting different mechanisms of uric acid regulation. Established xanthine oxidase inhibitors, uricosuric agents, anti-inflammatory medicines, and intravenous uricase-based treatments address different clinical requirements. Meanwhile, investigational therapies are exploring alternative approaches for patients who cannot tolerate existing medicines or do not achieve adequate disease control.
However, market expansion depends on factors beyond disease prevalence. Treatment affordability, reimbursement coverage, adherence to long-term medication, product safety, and the ability of new therapies to demonstrate meaningful clinical benefits will influence adoption. Investigational medicines must also complete the required clinical and regulatory processes before they can be marketed.
Gout Therapeutics Market Growth Drivers:
Rising Prevalence of Gout
The increasing global burden of gout is a major driver of demand for pharmaceutical treatments. Population ageing, metabolic disorders, kidney dysfunction, and other factors affecting uric acid production and excretion contribute to the growing number of people requiring clinical assessment and disease management.
The Global Burden of Disease Study 2021 analysis published in 2024 estimated that gout affected approximately 55.8 million people worldwide in 2020. The age-standardized prevalence rate increased by 22.5% between 1990 and 2020. The researchers also estimated that the number of cases could rise to approximately 95.8 million by 2050. These are modeled epidemiological estimates rather than a direct count of every affected individual.
The same study identified a substantially greater gout burden among men than women, with global age-standardized prevalence approximately 3.26 times higher among men in 2020. Prevalence also increased with age, emphasizing the importance of treatment strategies for older adults and patients with multiple chronic conditions.
This growing patient population supports demand for medicines that manage acute attacks and reduce serum uric acid over the longer term. Allopurinol and febuxostat remain established urate-lowering treatment options, while colchicine, nonsteroidal anti-inflammatory drugs (NSAIDs), and corticosteroids are used to control acute inflammation according to individual patient circumstances.
The clinical need is particularly important for patients experiencing recurrent attacks, developing tophi, or failing to achieve their serum urate targets with conventional treatment. These patients may require dose optimization, alternative oral medicines, or specialist-administered therapies. Consequently, the combination of an expanding patient population and continuing unmet treatment needs is supporting research and commercial opportunities across the gout therapeutics market.
Increasing Prevalence of Obesity
Obesity is an important metabolic risk factor associated with gout and can complicate disease management. Excess body weight is associated with changes in uric acid metabolism and is frequently accompanied by insulin resistance, hypertension, diabetes, and kidney-related disorders. These conditions can contribute to hyperuricemia or complicate treatment selection.
According to the World Health Organization's October 2026 fact sheet, approximately 2.6 billion adults aged 18 years and older were overweight in 2024, including around 940 million living with obesity. Approximately 16% of the global adult population was living with obesity that year. These figures demonstrate the scale of a major metabolic health challenge associated with several chronic diseases, including gout risk factors.
The relationship between obesity and gout creates opportunities for healthcare providers to integrate weight management, dietary counseling, physical activity, and pharmacological treatment into comprehensive care plans. However, obesity statistics should not be interpreted as a direct measure of gout prevalence, because not every person living with obesity develops gout.
For pharmaceutical manufacturers, the clinical implications include demand for therapies that maintain urate control in patients with multiple comorbidities and treatment regimens that can be sustained over time. Treatment selection must account for renal function, cardiovascular risk, concomitant medicines, and other individual clinical considerations.
Lifestyle management remains an important complement to medication rather than a substitute for indicated urate-lowering therapy. Patients with established gout may continue to require long-term pharmacological treatment even when they improve their diet, increase physical activity, or achieve weight reduction.
Changing Lifestyle and Dietary Patterns
Dietary habits, alcohol consumption, physical inactivity, and increasing rates of metabolic disorders can influence the risk and management of gout. Alcohol, particularly beer and spirits, and foods or beverages that contribute to elevated uric acid levels may increase the likelihood of gout attacks in susceptible individuals. Dehydration and abrupt changes in diet can also complicate management.
Changing dietary patterns and increasingly sedentary lifestyles are relevant to gout prevention because they can contribute to weight gain and related metabolic abnormalities. Nevertheless, gout is a multifactorial disease, and lifestyle choices alone do not explain its occurrence. Genetic susceptibility, age, kidney function, and medication use can also affect serum uric acid concentrations.
These factors are encouraging a broader approach to gout care that combines pharmacological treatment with patient education and risk-factor management. Healthcare professionals may recommend moderating alcohol intake, maintaining a healthy weight, consuming a balanced diet, and reviewing medicines that influence uric acid levels when clinically appropriate.
From a market perspective, the need for both immediate symptom relief and long-term prevention supports demand for multiple therapeutic categories. Acute-flare treatments address inflammation and pain, while urate-lowering medicines target the underlying biochemical condition responsible for crystal formation.
Long-term adherence remains essential because stopping urate-lowering therapy without appropriate medical guidance can allow serum uric acid to rise again. Therefore, treatment convenience, tolerability, patient education, and regular monitoring are important factors influencing the effectiveness of gout management and the continued use of prescribed medicines.
Increasing Awareness and Diagnosis
Greater awareness of gout as a treatable chronic inflammatory disease is supporting demand for diagnosis and appropriate pharmaceutical intervention. Patients may initially interpret recurring joint pain as an isolated injury or temporary inflammatory episode. Delayed assessment can result in repeated attacks, prolonged symptoms, and progression to more complicated disease.
Clinical evaluation may involve the patient's medical history, physical examination, serum uric acid measurement, and, when necessary, identification of monosodium urate crystals in joint fluid or appropriate imaging. A serum uric acid measurement alone does not establish or exclude gout in every clinical situation, particularly during an acute attack.
The U.S. Centers for Disease Control and Prevention promotes arthritis self-management approaches that include physical activity, maintaining a healthy weight, and working with healthcare professionals to manage symptoms and functional limitations. These approaches are relevant to gout care when adapted to individual needs, although they do not replace gout-specific medical treatment.
Improved diagnosis can increase the number of patients receiving appropriate treatment, including those who previously relied on intermittent symptom relief without sustained urate control. It also creates opportunities for clinicians to identify patients who require specialist assessment because of recurrent attacks, tophi, kidney disease, or inadequate response to existing therapy.
Pharmaceutical companies and healthcare organizations can support this process through scientifically accurate educational materials, clinical research, and collaboration with healthcare professionals. The expansion of patient education and disease-management programs may improve adherence and encourage more consistent monitoring of serum uric acid levels.
Increasing Research and Clinical Development
Research into gout therapeutics is progressing beyond established medicines toward alternative mechanisms of uric acid regulation and improved treatment options for difficult-to-treat disease. Drug developers are investigating selective uric acid transporter 1 (URAT1) inhibitors, alternative xanthine oxidase inhibitors, and biologic approaches designed to lower serum uric acid or reduce the burden of established urate crystals.
One area of interest is the development of oral uricosuric medicines that inhibit URAT1, a transporter involved in uric acid reabsorption in the kidneys. By reducing reabsorption, these agents are designed to increase uric acid excretion. Their clinical suitability depends on demonstrated efficacy, safety, kidney function, and other patient-specific factors.
In August 2026, JW Pharmaceutical reported that its investigational URC102, also known as epaminurad, met the primary efficacy endpoint at the 6 mg dose in a multinational Phase 3 trial and demonstrated statistical superiority to febuxostat 40 mg for the reported serum uric acid response measure. The company reported that the trial enrolled 612 patients across 52 centers in five Asian countries. Epaminurad remained an investigational medicine at the time of the announcement.
Another development area involves alternative xanthine oxidase inhibitors for patients who cannot tolerate established options. In October 2026, XORTX Therapeutics outlined a planned Health Canada clinical trial application for XRx-026, its investigational oxypurinol formulation, XORLO. The company described a proposed clinical study intended to support further development and a potential U.S. regulatory submission. These plans represent development milestones rather than marketing authorization.
These developments demonstrate continued investment in oral medicines and alternative treatment mechanisms. However, investigational products must demonstrate appropriate clinical benefits and acceptable safety before regulatory authorities can authorize their use. Clinical-trial results, future approvals, and commercial adoption therefore remain important uncertainties for the gout therapeutics market.
Gout Therapeutics Market Restraints:
The gout therapeutics market faces several challenges despite the growing patient population and continued clinical research. One of the principal restraints is the difficulty of maintaining adherence to long-term urate-lowering therapy. Patients may discontinue treatment when symptoms improve, experience adverse effects, or struggle with medication costs and the need for regular monitoring.
Gout management generally requires a distinction between treating an acute inflammatory attack and lowering serum uric acid over time. Patients may require anti-inflammatory treatment during a flare, while urate-lowering therapy is used to reduce crystal accumulation and prevent future attacks. Because these objectives differ, patients may misunderstand why treatment should continue after pain subsides.
Safety and tolerability also influence prescribing decisions. NSAIDs can present gastrointestinal, cardiovascular, and kidney-related risks in susceptible patients. Colchicine may cause gastrointestinal adverse effects and can interact with certain medicines. Allopurinol requires appropriate dosing and monitoring, while febuxostat prescribing requires consideration of its product-specific safety information and the patient's cardiovascular history. Corticosteroids may cause metabolic and other adverse effects, particularly with repeated or prolonged use.
Biologic treatment for severe refractory gout presents additional considerations, including infusion requirements, monitoring, treatment costs, and potential serious adverse reactions. For example, the U.S. prescribing information for pegloticase, marketed as KRYSTEXXA, includes warnings concerning anaphylaxis, infusion reactions, glucose-6-phosphate dehydrogenase deficiency-associated hemolysis and methemoglobinemia, gout flares, and congestive heart failure.
Another restraint is unequal access to specialist care and newer medicines. Generic oral therapies can be more affordable than specialized biologic treatments, while reimbursement policies, insurance coverage, and healthcare infrastructure differ across markets. These differences may limit the adoption of premium-priced therapies, particularly where diagnosis and long-term monitoring are difficult to access.
Clinical development also carries substantial uncertainty. Candidate medicines must demonstrate suitable efficacy and safety in controlled studies, satisfy regulatory requirements, and establish an appropriate benefit-risk profile. A positive early-stage result does not guarantee Phase 3 success or regulatory approval. These factors can delay product launches and increase development costs.
Gout Therapeutics Market Geographical Outlook:
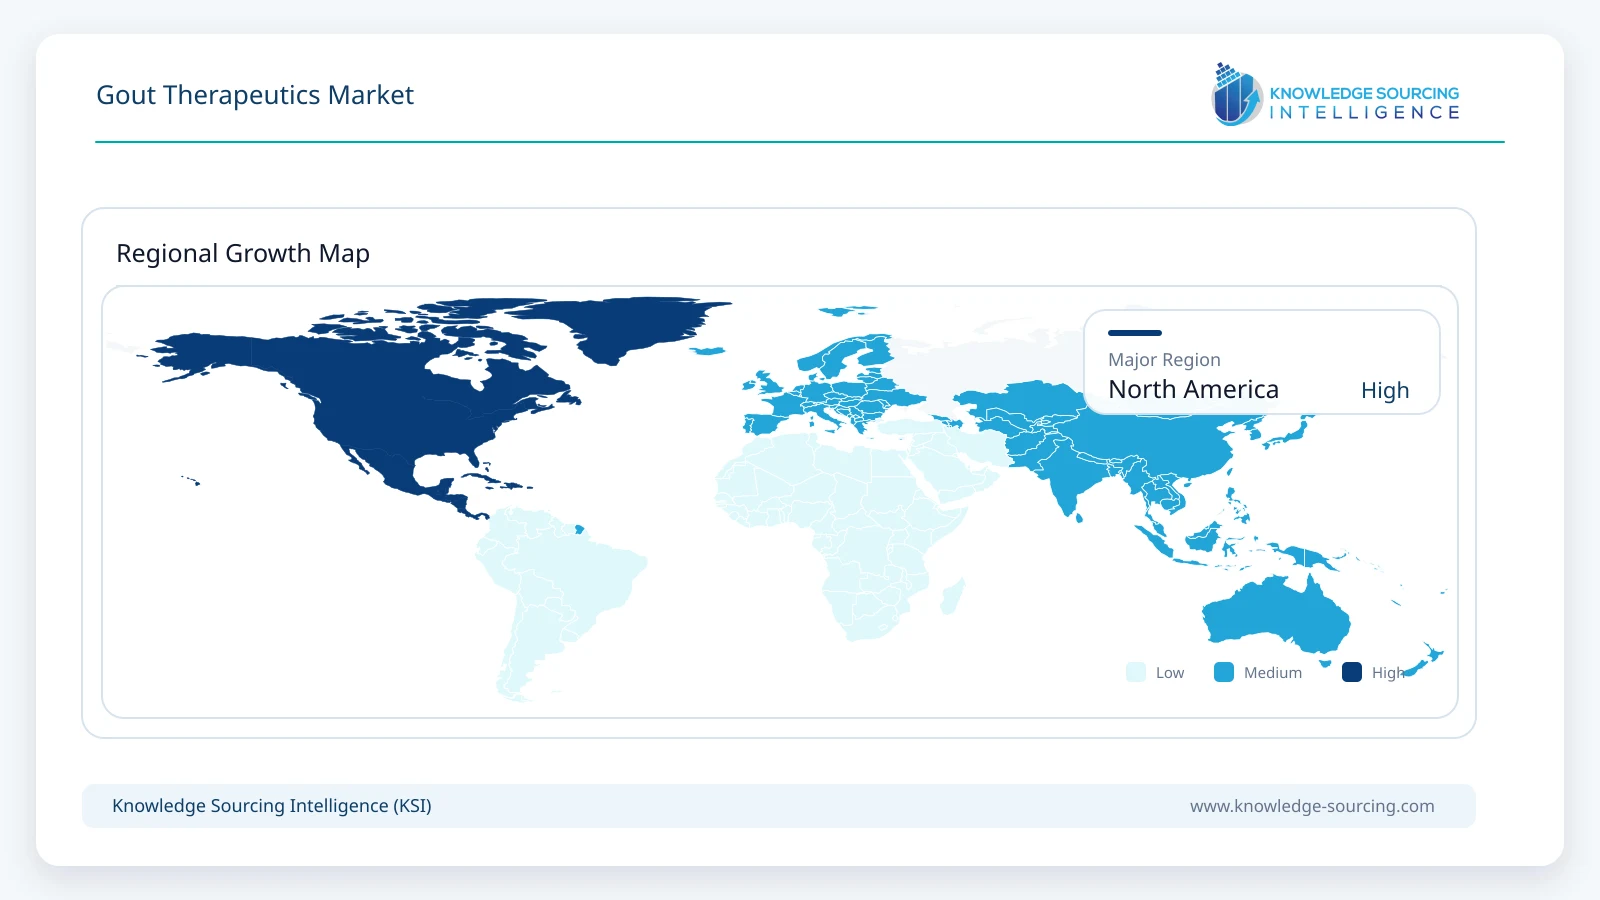
North America is Expected to Maintain a Significant Market Position
North America is expected to remain an important region in the gout therapeutics market because of its established healthcare infrastructure, access to prescription medicines, specialist rheumatology services, and pharmaceutical research capabilities. The United States is a key market for established urate-lowering drugs and advanced treatments for patients with severe or refractory gout.
Demand is supported by the coexistence of gout with obesity, cardiovascular conditions, diabetes, and kidney disease. The region also benefits from established drug approval pathways, clinical-trial infrastructure, and healthcare systems capable of providing specialist-administered treatments. However, access to newer therapies can vary according to insurance coverage, reimbursement requirements, and patients' ability to afford treatment.
North America's research environment supports the development of medicines targeting alternative mechanisms of uric acid control. The clinical pipeline includes oral uricosuric candidates, alternative xanthine oxidase inhibitors, and therapies designed for patients who do not achieve adequate disease control with existing treatment.
The United States Food and Drug Administration plays a central role in evaluating the safety and efficacy of medicines before marketing authorization. Regulatory requirements, including clinical evidence, manufacturing quality, and product-specific safety monitoring, influence the timing and commercial potential of new gout treatments.
Canada also contributes to the regional landscape through healthcare services and clinical development activity. In October 2026, XORTX Therapeutics outlined a planned Health Canada clinical trial application for its investigational XRx-026 program, reflecting continued interest in developing alternative treatment options. The proposed application should not be interpreted as evidence that the medicine has been approved or that the trial has already been authorized.
North American market expansion will depend on the availability of effective treatments, continued clinical innovation, and improved long-term disease management. While established oral medicines are likely to remain important because of their clinical experience and accessibility, advanced therapies may offer opportunities in selected patient populations with difficult-to-treat disease.
Other regions are also expected to contribute to market growth. Europe has established rheumatology services and regulatory infrastructure, while Asia-Pacific offers opportunities associated with large populations, evolving healthcare access, and clinical development activity. Market adoption across these regions will depend on local disease burden, diagnostic capacity, medicine affordability, regulatory requirements, and reimbursement policies.
Gout Therapeutics Market Major Players:
Novartis AG is a global pharmaceutical company headquartered in Switzerland, with operations spanning several therapeutic areas. Its broader pharmaceutical and research capabilities provide relevant industry context; however, its inclusion as a company in the gout therapeutics landscape should not be interpreted as confirmation that it currently markets a dedicated gout medicine.
Horizon Therapeutics was a biopharmaceutical company known for developing and commercializing treatments for rare diseases and inflammatory conditions. Amgen completed its acquisition of Horizon Therapeutics in October 2023. KRYSTEXXA (pegloticase), used to treat chronic gout in adults whose disease is refractory to conventional therapy, is therefore associated with Amgen's portfolio rather than an independent Horizon Therapeutics business.
AstraZeneca plc is a multinational pharmaceutical company engaged in the development and commercialization of prescription medicines across multiple therapeutic areas. Its historical association with ZURAMPIC (lesinurad), a medicine previously authorized for use with a xanthine oxidase inhibitor in selected patients with gout, should be distinguished from current product availability and marketing status in individual countries.
Gout Therapeutics Market Key Developments:
October 2026: XORTX Therapeutics outlined a planned Health Canada clinical trial application for XRx-026, its investigational oxypurinol formulation XORLO, to support further gout-treatment development and a potential regulatory pathway.
July 2026: Crystalys Therapeutics announced USD 130 million in Series B financing to advance global Phase 3 development and commercialization preparations for dotinurad, its investigational oral treatment for gout.
May 2026: Swedish Orphan Biovitrum (Sobi) reported positive topline Phase 3 REDUCE 2 results for pozdeutinurad, an investigational oral URAT1 inhibitor. The company reported that 69.2% of patients receiving 75 mg and 56.6% receiving 50 mg achieved serum uric acid below 6 mg/dL at month six, compared with 8.1% receiving placebo.
February 2026: Crystalys Therapeutics reported that the first patients had been dosed at European sites in its Phase 3 RUBY study of dotinurad, expanding the clinical development program geographically.
Gout Therapeutics Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 3.14 billion |
| Total Market Size in 2031 | USD 4.50 billion |
| Forecast Unit | Billion |
| Growth Rate | 7.5% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Drug Class, Disease Condition, Distribution Channel, Geography |
| Companies |
|
Market Segmentation
By Drug Class
NSAIDs
Corticosteroids
Colchicine
Urate-Lowering Agents
Others
By Disease Condition
Acute Gout
Chronic Gout
By Distribution Channel
Hospital Pharmacy
Retail Pharmacy
Online Pharmacy
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. GOUT THERAPEUTICS MARKET BY DRUG CLASS
5.1. Introduction
5.2. NSAIDs
5.3. Corticosteroids
5.4. Colchicine
5.5. Urate-Lowering Agents
5.6. Others
6. GOUT THERAPEUTICS MARKET BY DISEASE CONDITION
6.1. Introduction
6.2. Acute Gout
6.3. Chronic Gout
7. GOUT THERAPEUTICS MARKET BY DISTRIBUTION CHANNEL
7.1. Introduction
7.2. Hospital Pharmacy
7.3. Retail Pharmacy
7.4. Online Pharmacy
8. GOUT THERAPEUTICS MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. Germany
8.4.2. France
8.4.3. United Kingdom
8.4.4. Spain
8.4.5. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Indonesia
8.6.6. Thailand
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Takeda Pharmaceutical Company Ltd.
10.2. Novartis AG
10.3. AstraZeneca plc
10.4. Horizon Therapeutics plc
10.5. Merck & Co. Inc.
10.6. Teijin Pharma Ltd.
10.7. GlaxoSmithKline, Plc.
10.8. Arthrosi
10.9. Mayo Clinic
10.10. Johns Hopkins Arthritis Center
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key benefits for the stakeholders
11.5. Research Methodology
11.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES
Navigate
Trusted by the world's leading organizations











