
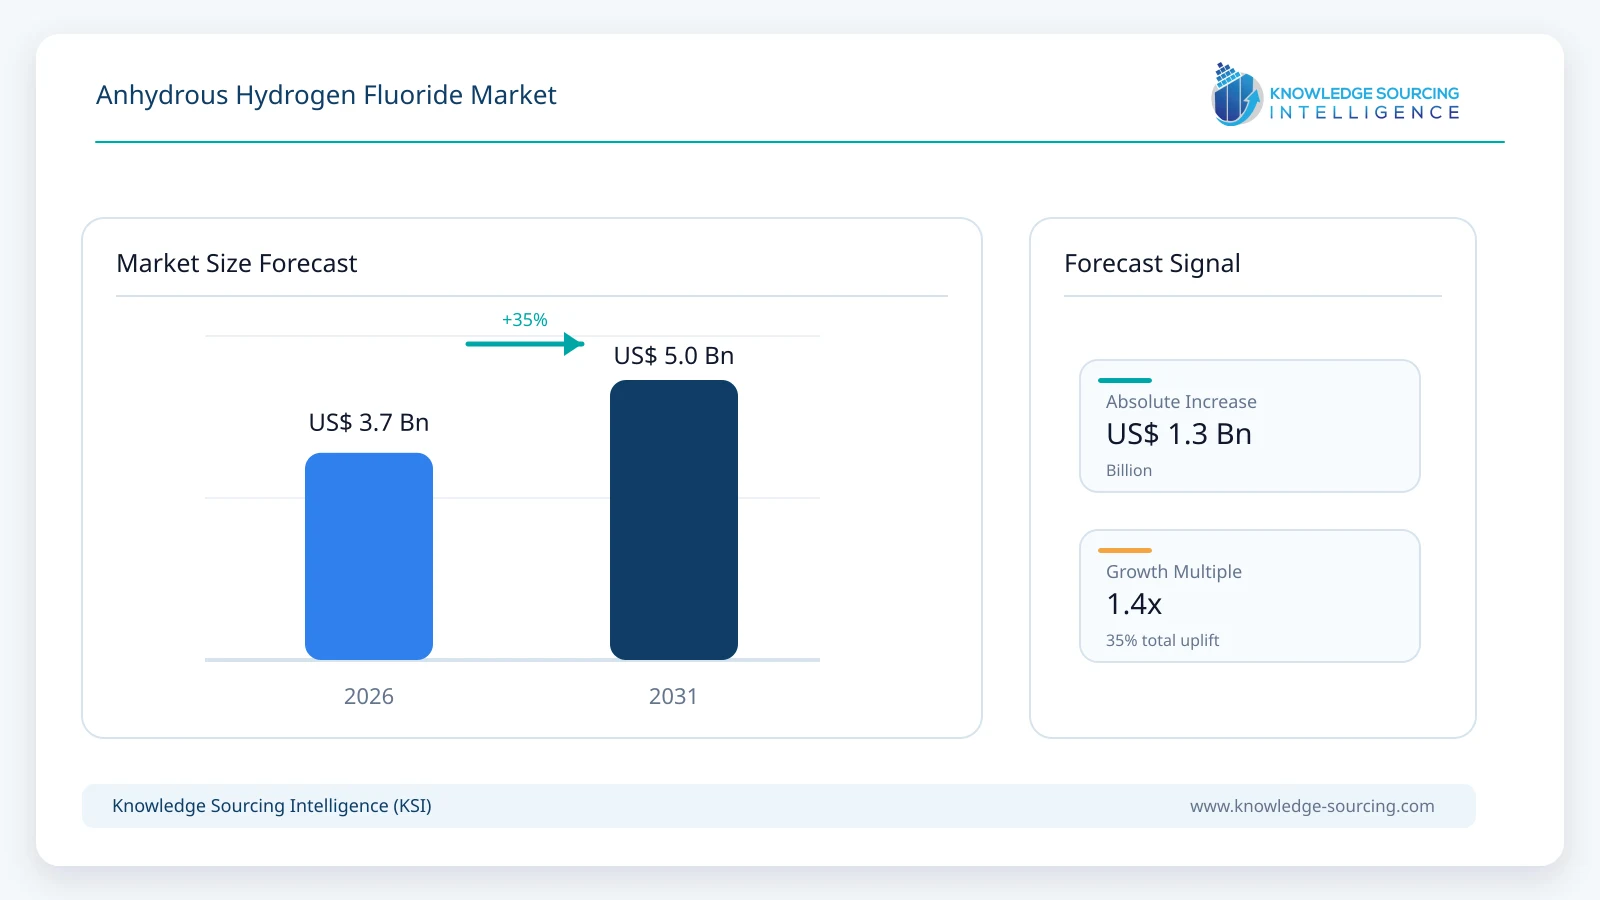
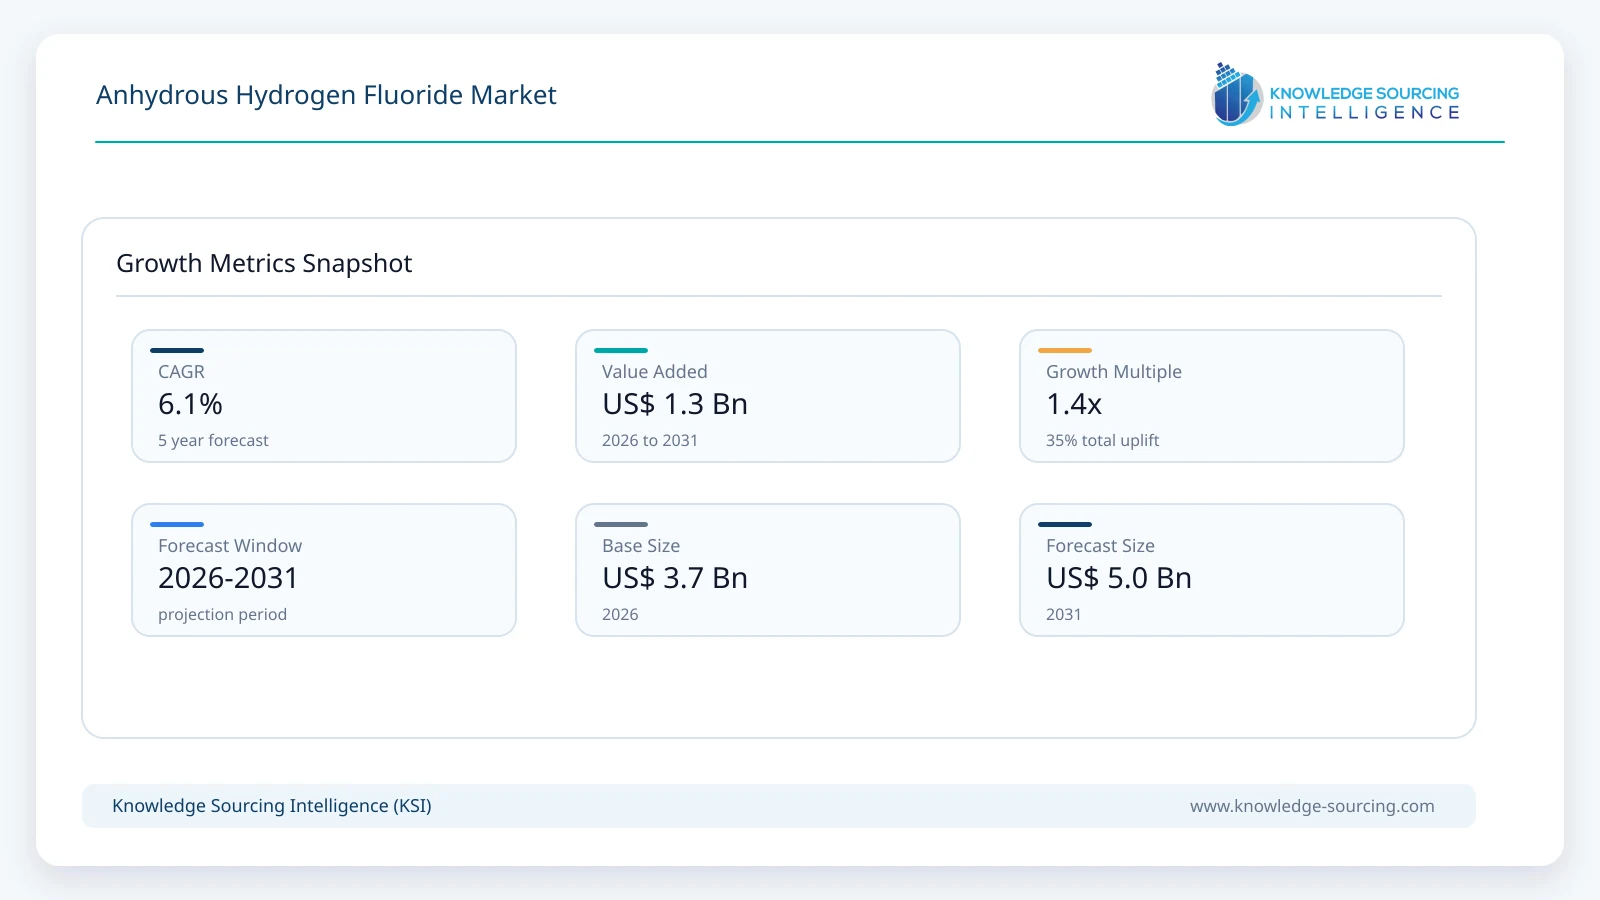
The global anhydrous hydrogen fluoride market is forecast to grow at a CAGR of 6.1%, reaching USD 5.0 billion in 2031 from USD 3.7 billion in 2026.
Highlights:
- 1Industrial-grade AHF accounts for approximately 88% of global market revenue in 2026.
- 2High-purity AHF is projected to grow at approximately 8.0% annually through 2031.
- 3Fluorochemicals and fluoropolymer production generate about USD 2.16 billion of AHF demand in 2026.
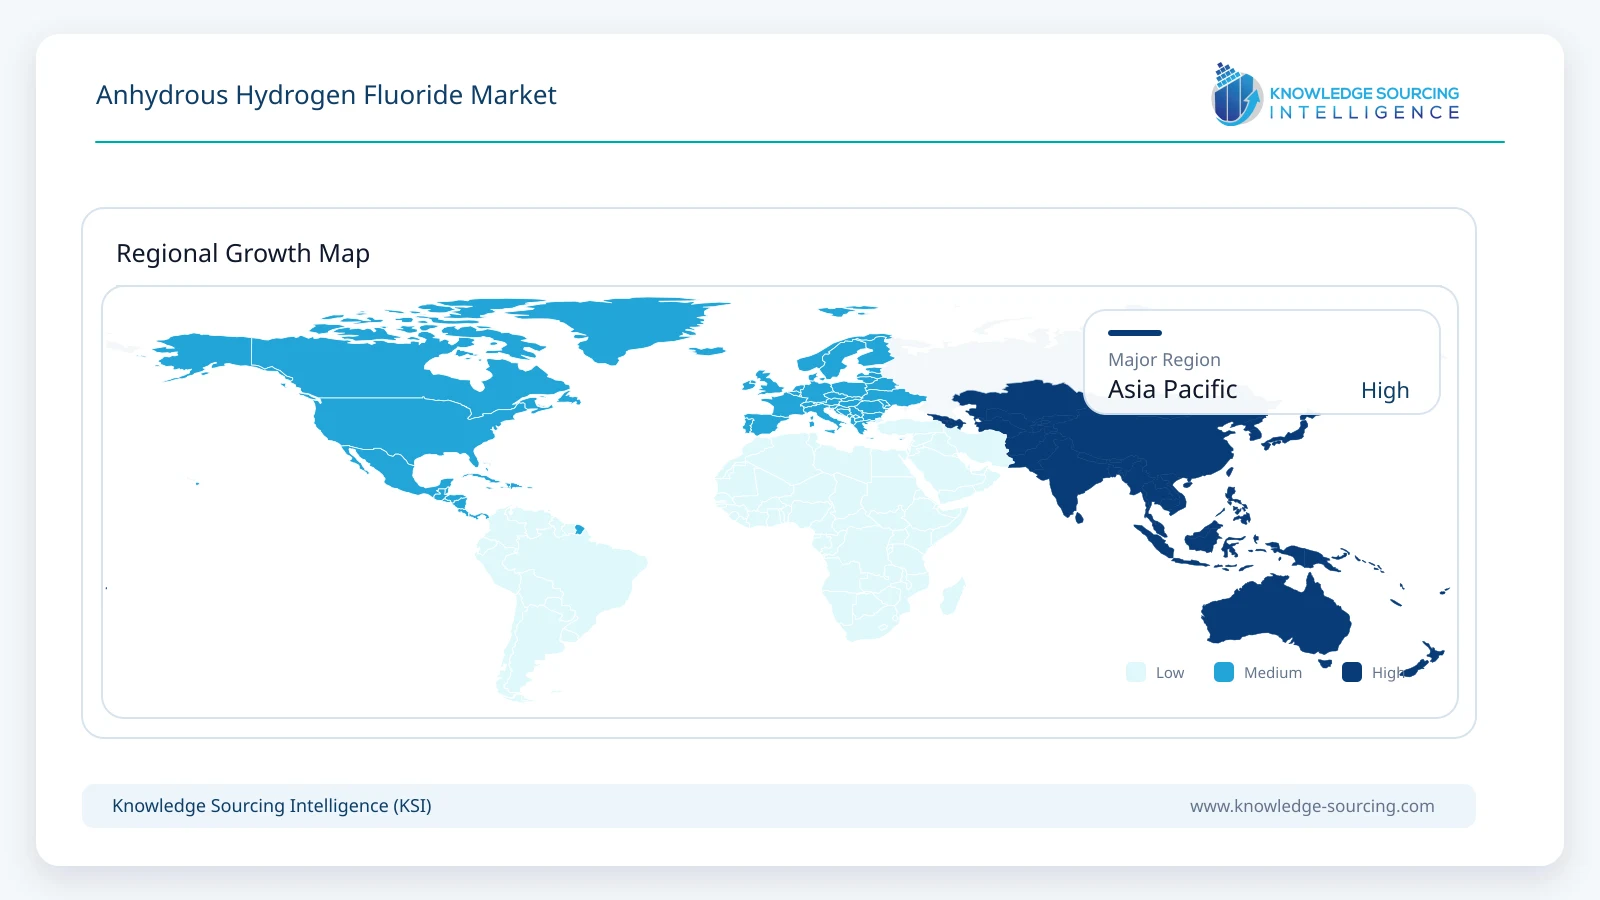
- 4Asia Pacific accounts for approximately 51% of global AHF market revenue in 2026.
- 5China represented 71% of global HF production in 2025, highlighting the market’s supply concentration.
- 6Battery, semiconductor and low-GWP fluorine applications are raising purity and supply-security requirements.
Market Overview
AHF sits near the beginning of the fluorine value chain. The conventional production route reacts acid-grade fluorspar, or calcium fluoride, with sulfuric acid to generate gaseous hydrogen fluoride, which is then purified and condensed. LANXESS describes HF as a basic raw material for fluorinated salts, fluoropolymers, petrochemical alkylation, nuclear applications, agrochemicals and electronics. Derivados del Fluor similarly positions AHF as a feedstock for fluoropolymers, refrigerants and specialty fluorochemicals, as well as a catalyst in petroleum refining. The product is therefore linked to a wide range of downstream industries even though direct AHF consumption is concentrated among large chemical and refining customers.
Supply is unusually concentrated. Orbia estimated total global HF production capacity at 4.997 million tonnes in 2025, of which China represented about 3.988 million tonnes. North America, Europe and Mexico together accounted for less than one-fifth of capacity. Outside China, Orbia Fluor & Energy Materials is one of the largest integrated producers, supported by its fluorspar position in Mexico and HF production at Matamoros. Honeywell operates a large U.S. HF facility in Geismar, Louisiana, while LANXESS, Solvay, ALKEEMIA and Derivados del Fluor maintain established positions in Europe and North America. China has a broader producer base that includes Dongyue, Zhejiang Sanmei, Do-Fluoride, Sinochem-linked operations and regional manufacturers.
Market Trends
AHF capacity is becoming more closely integrated with downstream fluorine chemistry
New investments increasingly place AHF production alongside fluoropolymers, refrigerants, battery electrolytes and specialty fluorine chemistry rather than treating AHF as a standalone merchant chemical. Navin Fluorine commissioned 40,000 tonnes per year of new AHF capacity in FY2025-26, giving the company manufacturing capability at both Surat and Dahej and improving feedstock security for its downstream fluorochemicals. Dongyue has similarly expanded AHF alongside fluoropolymer and refrigerant operations, while Orbia combines fluorspar mining, HF, refrigerants and energy-material activities across the same fluorine chain. This integration reduces exposure to merchant AHF availability and allows producers to capture more value from the same fluorine unit.
Higher-purity fluorine demand is increasing the value of impurity control
AHF is no longer differentiated only by concentration. Semiconductor, battery, and advanced fluorochemical customers require tighter limits on water, sulfur compounds, metals, and other impurities. Foosung specifies standard AHF above 99.9% purity and also markets high-purity HF above 99.99% for semiconductor diffusion and wafer-cleaning applications. Zhejiang Sanmei offers multiple AHF grades ranging from qualified industrial product to 99.98% special grade. Derivados del Fluor states that its AHF portfolio extends from industrial to semiconductor grades. This shift supports faster value growth for purified material even though industrial-grade AHF remains dominant in volume.
Market Drivers
Fluoropolymers, refrigerants and specialty fluorochemicals sustain the largest AHF demand base
AHF remains the principal fluorine-building-block input for many fluoropolymers, refrigerant molecules and fluorinated intermediates. These products serve refrigeration and air conditioning, electronics, chemical processing, automotive systems, coatings, membranes and industrial equipment. Honeywell identifies anhydrous HF as the foundation for its next-generation fluorine molecules, while Arkema has used long-term AHF supply investments to support fluoropolymers, specialty derivatives and low-GWP fluorogases. Regulatory pressure is reducing demand for some legacy high-global-warming-potential refrigerants, but it does not remove the need for fluorine chemistry. Instead, product mix is shifting toward lower-GWP molecules and higher-value fluorinated materials, preserving AHF as an essential upstream feedstock.
Electronics, batteries and energy applications are broadening high-value fluorine demand
Battery electrolytes, semiconductor process chemicals, photovoltaic manufacturing and nuclear fuel conversion are strengthening demand outside conventional refrigerants. Foosung identifies AHF as a raw material for secondary-cell electrolytes and specialty semiconductor gases. Orbia completed a major expansion of its U.S. custom electrolyte facility in late 2025, tripling production capacity for lithium-ion and emerging battery chemistries, while Tanfac commissioned 10,000 tonnes per year of solar-grade dilute HF capacity on an AHF-equivalent basis during 2025. Nuclear applications also remain structurally important because HF is used in the production of uranium fluorides, including uranium tetrafluoride and uranium hexafluoride. These uses support a growing premium for secure, traceable and low-impurity fluorine supply.
Market Restraint
Fluorspar concentration, hazardous logistics and regulatory controls constrain merchant supply flexibility
Most AHF production depends on acid-grade fluorspar, so availability and price are closely linked to mining conditions. USGS estimated global fluorspar mine production at about 10 million tonnes in 2025 and noted continuing supply constraints in China, where mine-safety rectification measures led to temporary suspensions and higher imports. The same year also saw new or restarted acidspar projects in Canada and China, illustrating the market response to feedstock tightness. AHF itself is acutely toxic and highly corrosive, requiring specialized railcars, ISO tanks, cylinders, unloading systems and emergency-response procedures. These requirements raise logistics costs and limit the number of suppliers that can reliably serve distant customers. Producers with captive fluorspar, integrated downstream consumption or dedicated transport fleets therefore hold an advantage over standalone merchant suppliers.
Segment Analysis
By Grade - Industrial Grade AHF
Industrial-grade AHF is projected to generate approximately USD 4.28 billion in market revenue by 2031. It remains the core product used in fluorocarbon and fluoropolymer production, petroleum alkylation, inorganic fluorides, agrochemical and pharmaceutical intermediates, and other large-scale chemical processes. Commercial specifications typically exceed 99% HF, with tighter limits on water, sulfuric acid and fluorosilicic acid depending on the downstream reaction. High-purity grades remain smaller in absolute value but are growing more rapidly because semiconductor, battery and electronic-material customers impose narrower impurity limits and support a higher value per tonne.
By Application - Fluorochemicals and Fluoropolymers
Fluorochemicals and fluoropolymers are projected to reach approximately USD 2.87 billion of AHF demand by 2031. This category includes refrigerants, fluorinated intermediates, PTFE and other fluoropolymers, specialty fluorochemicals and related derivatives. The segment benefits from a large installed fluorochemical manufacturing base in China, the United States, Mexico, Europe, India, Japan and South Korea. The product mix is changing as older refrigerants are phased down, but low-GWP refrigerants, high-performance polymers, pharmaceutical intermediates and battery-related fluorine chemistry are taking a larger share of downstream investment. Petroleum alkylation remains an important separate use, particularly in North America, while agrochemicals, pharmaceuticals, nuclear conversion and advanced electronics provide additional demand.
By Geography - Asia Pacific
Asia Pacific is projected to reach approximately USD 2.68 billion in AHF revenue by 2031. China dominates regional supply and consumption through its scale in refrigerants, fluoropolymers, electronics, batteries and other fluorinated chemicals. Orbia estimated China at 71% of world HF production in 2025, while official Chinese standards for industrial AHF list a broad base of domestic producers and technology participants. India is strengthening its position through capacity additions by Navin Fluorine and downstream solar-grade HF investment by Tanfac. South Korea contributes through Foosung and semiconductor-linked high-purity demand, while Japan remains a significant specialty fluorochemical and electronics market. North America retains substantial strategic demand in refining, refrigerants, fluoropolymers and uranium-related applications, while Europe remains important in specialty fluorochemistry despite a smaller production base.
Competitive Environment
The market combines globally integrated fluorochemical producers with regional AHF specialists and large Chinese manufacturers. Orbia Fluor & Energy Materials benefits from upstream fluorspar ownership and downstream refrigerant and energy-material operations. Honeywell combines a large U.S. HF production site with captive fluorine chemistry, while LANXESS and Solvay maintain established industrial HF supply positions. ALKEEMIA operates 27,000 tonnes per year of AHF capacity at Porto Marghera, and Derivados del Fluor competes through integrated fluorspar access, specialty grades and dedicated international logistics. In Asia, Dongyue, Zhejiang Sanmei, Foosung, Navin Fluorine, Tanfac and several Chinese fluorochemical companies link AHF production with refrigerants, fluoropolymers or battery materials.
Competitive advantage depends on more than nominal capacity. Customers place high value on consistent impurity specifications, secure fluorspar access, safety performance, dedicated transport equipment, emergency-response capability and the ability to support long-term supply agreements. Captive downstream consumption can reduce merchant availability even when headline capacity is high, while regional safety rules make cross-border logistics complex. Producers able to combine feedstock security, purification capability and downstream integration are therefore better positioned to protect margins than suppliers competing only on commodity-grade AHF volume.
Recent Developments
FY2025-26: Navin Fluorine commissioned 40,000 tonnes per year of additional AHF capacity during the fourth quarter, adding a second manufacturing location at Dahej alongside Surat.
December 2025: Orbia Fluor & Energy Materials announced completion of a U.S. custom-electrolyte facility expansion in Madison, Wisconsin, that increased production capacity by roughly 300%, supporting downstream battery-material demand for lithium-ion and emerging chemistries.
October 2025: Tanfac Industries commissioned the second 5,000-tonne-per-year phase of its solar-grade dilute HF plant, taking total capacity to 10,000 tonnes per year on an AHF-equivalent basis.
August 2025: A Canadian fluorspar mine restarted shipments of acid-grade material and targeted a ramp-up to 200,000 tonnes per year, improving non-Chinese feedstock availability for HF production.
September 2025: A new fluorspar mine in Xinjiang, China, began operations with projected acid-grade output of 300,000 tonnes per year, adding upstream supply to the world’s largest HF-producing country.
Anhydrous Hydrogen Fluoride Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 3.7 billion |
| Total Market Size in 2031 | USD 5.0 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.1% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Grade, Application, Geography |
| Companies |
|
Market Segmentation
By Grade
Industrial Grade
High-Purity Grade
By Application
Fluorochemicals and Refrigerants
Fluoropolymers
Oil Refining and Petrochemicals
Agrochemicals and Pharmaceuticals
Electronics and Semiconductor Materials
Nuclear and Other Applications
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Fluoropolymers, Refrigerants and Specialty Fluorochemicals Sustain the Largest AHF Demand Base
3.1.2. Electronics, Batteries and Energy Applications Are Broadening High-Value Fluorine Demand
3.2. Market Restraint
3.2.1. Fluorspar Concentration, Hazardous Logistics and Regulatory Controls Constrain Merchant Supply Flexibility
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Conventional Fluorspar-Based AHF Production
4.2. High-Purity and Electronic-Grade HF
4.3. Alternative Fluorine Feedstock Routes
4.4. Process Safety and Closed-Loop Handling Systems
5. ANHYDROUS HYDROGEN FLUORIDE MARKET BY GRADE
5.1. Introduction
5.2. Industrial Grade
5.3. High-Purity Grade
6. ANHYDROUS HYDROGEN FLUORIDE MARKET BY APPLICATION
6.1. Introduction
6.2. Fluorochemicals and Refrigerants
6.3. Fluoropolymers
6.4. Oil Refining and Petrochemicals
6.5. Agrochemicals and Pharmaceuticals
6.6. Electronics and Semiconductor Materials
6.7. Nuclear and Other Applications
7. ANHYDROUS HYDROGEN FLUORIDE MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. USA
7.2.2. Canada
7.2.3. Mexico
7.3. South America
7.3.1. Brazil
7.3.2. Argentina
7.3.3. Others
7.4. Europe
7.4.1. Germany
7.4.2. France
7.4.3. United Kingdom
7.4.4. Spain
7.4.5. Italy
7.4.6. Others
7.5. Middle East and Africa
7.5.1. Saudi Arabia
7.5.2. UAE
7.5.3. Others
7.6. Asia Pacific
7.6.1. China
7.6.2. India
7.6.3. Japan
7.6.4. South Korea
7.6.5. Indonesia
7.6.6. Thailand
7.6.7. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Orbia Fluor & Energy Materials
9.2. Honeywell International Inc.
9.3. LANXESS AG
9.4. Solvay SA
9.5. Arkema S.A.
9.6. ALKEEMIA S.p.A.
9.7. Derivados del Fluor S.A.
9.8. Foosung Co., Ltd.
9.9. Navin Fluorine International Limited
9.10. Tanfac Industries Limited
9.11. Dongyue Group Limited
9.12. Zhejiang Sanmei Chemical Industry Co., Ltd.
9.13. Do-Fluoride New Materials Co., Ltd.
9.14. Sinochem Holdings / Sinochem Lantian
9.15. NGF Chemical Co., Ltd.
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key Benefits for Stakeholders
10.5. Research Methodology
10.6. Abbreviations
Navigate
Trusted by the world's leading organizations











