
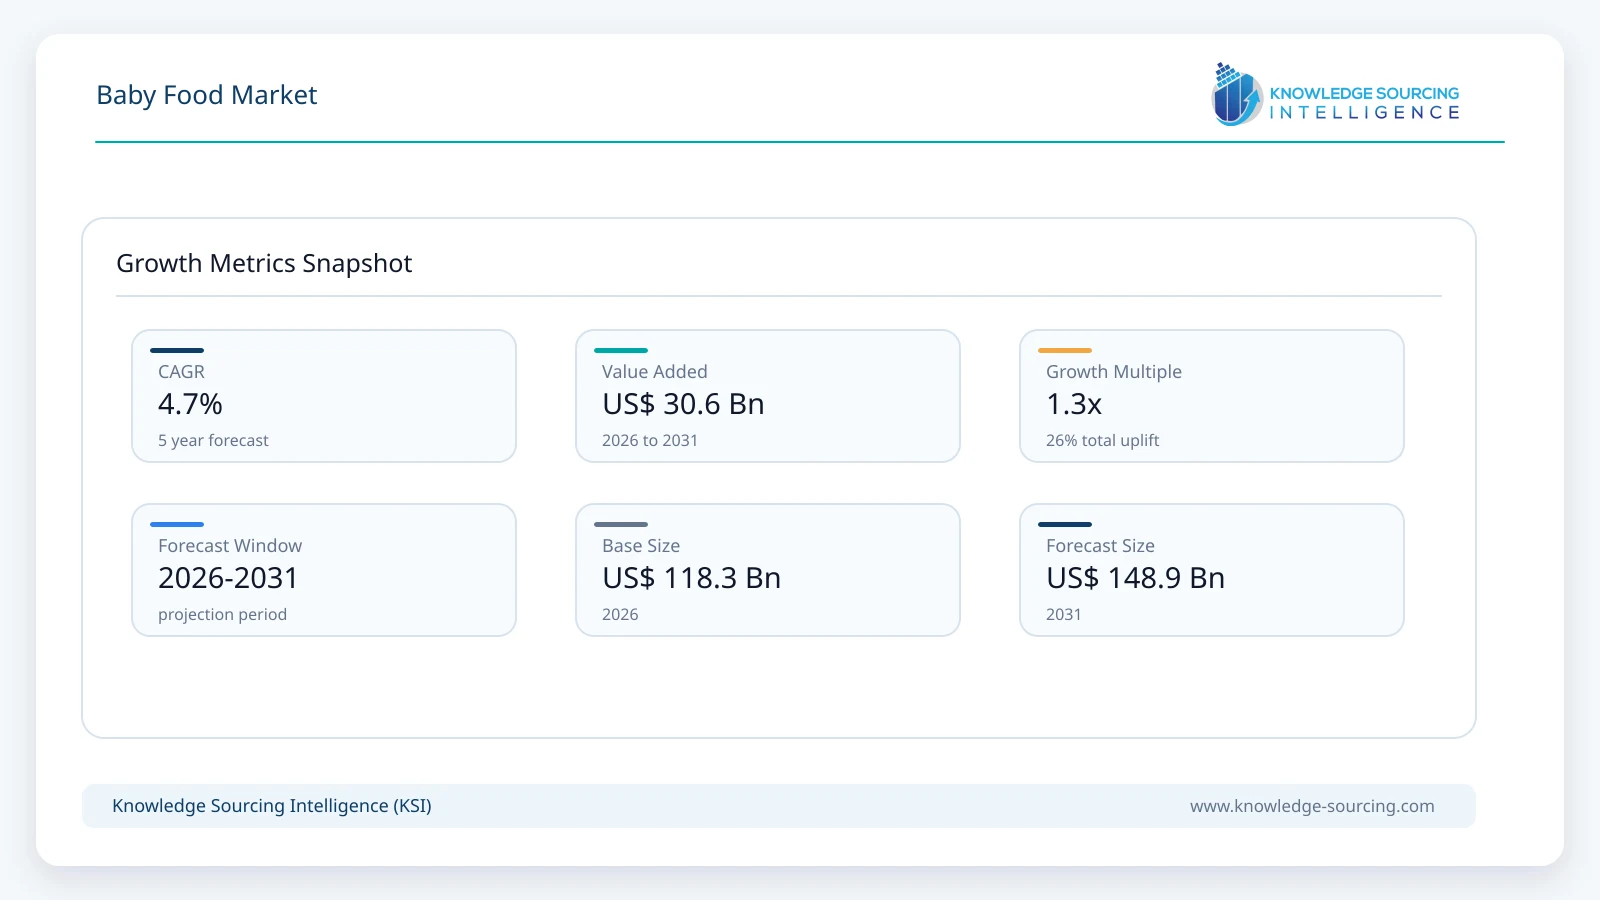
The Global Baby Food Market is projected to grow at a CAGR of 4.71%, reaching USD 148.9 billion by 2031 from USD 118.3 billion in 2026.
Highlights:
- 1Milk Formula remains the largest product segment, accounting for approximately 56% of market value in 2026.
- 2Prepared Baby Food is projected to grow at approximately 6.7% annually through 2031, making it the fastest-growing major product category.
- 3Non-Organic products continue to account for the majority of market value, while Organic baby food is projected to grow at approximately 7.9% annually.
- 4Offline channels remain the largest distribution route, while Online sales are projected to record approximately 8.5% CAGR through 2031.
- 5Asia Pacific represents approximately 43% of global market value in 2026 and retains the leading regional position.
- 6Middle East and Africa is projected to record one of the strongest regional growth rates from a smaller base.
- 7Product safety, contaminant testing and responsible marketing requirements are becoming increasingly important competitive factors in infant and young-child nutrition.
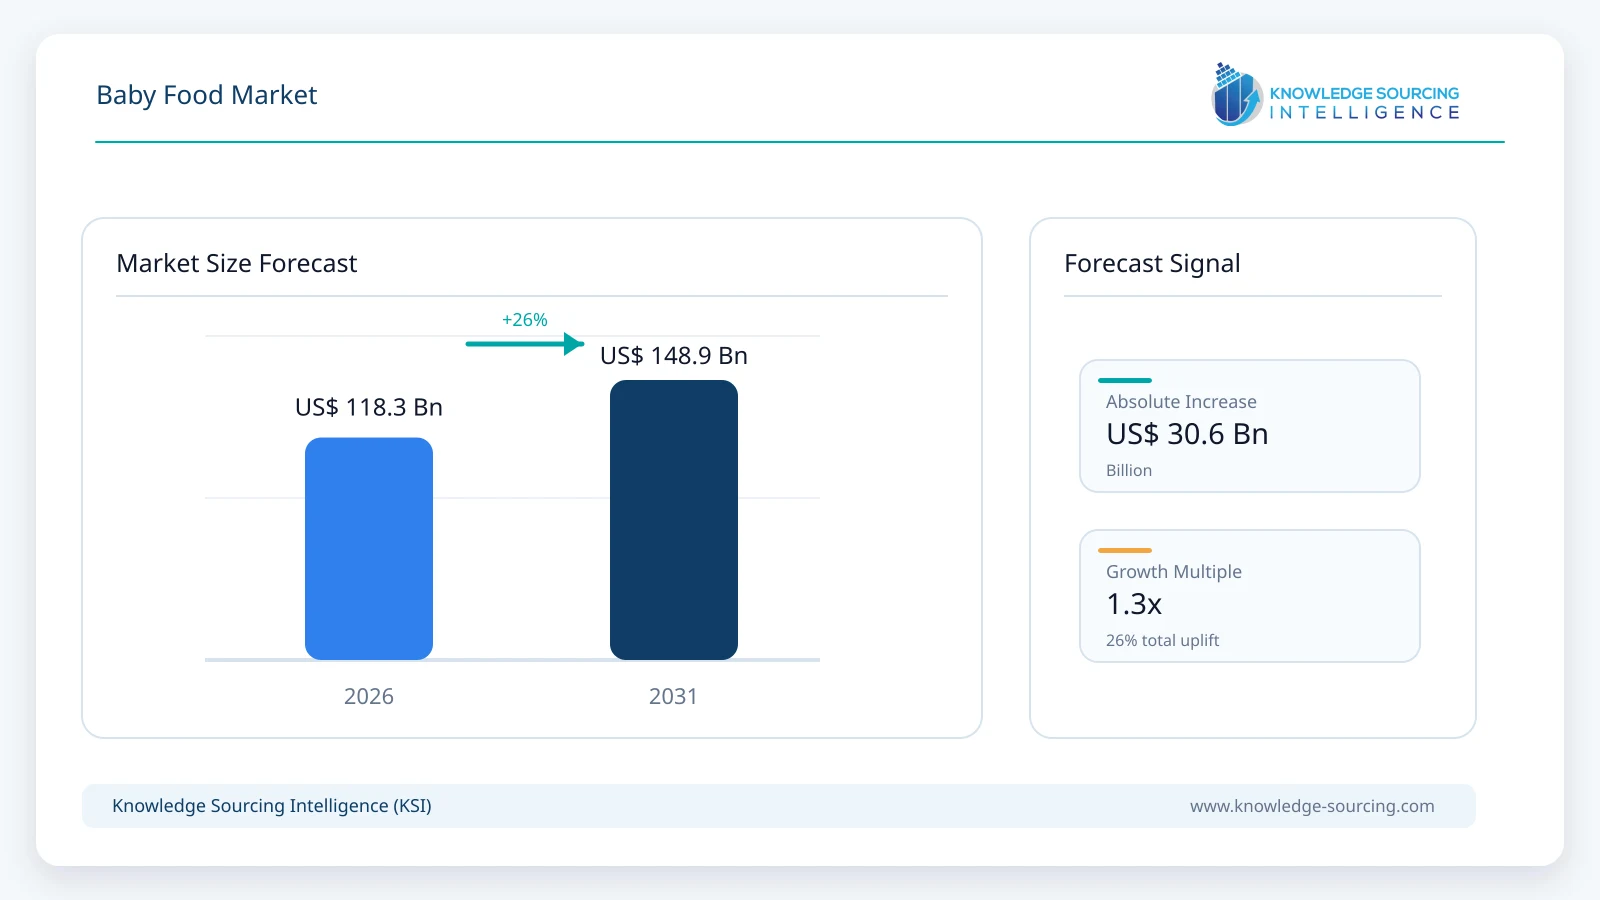
The market includes infant formula, dried baby food, prepared baby food and other commercially manufactured nutrition products intended for infants and young children. Growth is being shaped less by expansion in the global infant population alone and increasingly by higher expenditure per child, demand for convenient complementary foods, formulation innovation, premium and organic positioning, and wider retail access across developing markets.
Milk Formula remains the largest product segment, accounting for approximately 56% of market value in 2026. Its scale reflects comparatively high unit values, widespread commercial use where breastfeeding is not possible or chosen, and extensive portfolios covering standard formula, follow-on products and specialized nutritional requirements. Formula manufacturers are increasingly differentiating through human milk oligosaccharides, probiotics, whole-milk formulations and products addressing digestive or allergy-related requirements. Nestlé expects its NAN Sinergity range, combining probiotics with six HMOs, to reach 50 countries by the end of 2026, while Abbott introduced Similac 360 Total Care Made With Whole Milk in the United States in August 2026 as a commercially sterile ready-to-feed product.
The market for complementary foods is developing alongside, rather than in place of, breastfeeding. WHO and UNICEF recommend exclusive breastfeeding for the first six months, followed by nutritionally adequate complementary foods from around six months while breastfeeding continues up to two years or beyond. Global feeding quality remains uneven: WHO reported in August 2026 that fewer than one-third of children aged 6–23 months met minimum dietary diversity requirements over 2018–2024. This creates a large nutrition requirement but does not automatically translate into packaged-food consumption, making affordability, regulation, local feeding practices and product trust central to market development.
Asia Pacific remains the largest geographic market, supported by large child populations, established infant-formula industries in China and Japan, rapid packaged-food expansion in India and Southeast Asia, and increasingly sophisticated premium nutrition portfolios. At the same time, slower birth growth in several major economies is shifting competition toward higher-value formulations, convenient complementary foods and increased spending per child rather than simple volume expansion.
Market Growth Drivers and Trends
Increasing Attention to Complementary Nutrition Supports Category Development
The first two years of life are critical for physical and cognitive development, and feeding requirements change substantially after six months. WHO states that breast milk alone is no longer sufficient to meet all energy and nutrient requirements at around six months, when safe and nutritionally adequate complementary foods should be introduced while breastfeeding continues. Commercial baby food participates in this requirement through cereals, purees, meals and other complementary foods, particularly where caregivers require convenient, portion-controlled or fortified options.
The nutrition gap remains substantial. WHO estimates that only 30.8% of children aged 6–23 months received minimum dietary diversity during 2018–2024, while UNICEF estimates that 181 million children under five live in severe child food poverty. These statistics do not imply that packaged baby food is itself the solution to malnutrition, but they demonstrate the scale of unmet nutrition requirements and the importance of affordable nutrient-dense complementary foods across both commercial and public-health systems.
Manufacturers are consequently placing greater emphasis on micronutrient fortification, age-appropriate textures and formulations aligned with developmental stages. The strongest commercial opportunities are likely to remain in markets where improved household purchasing power, modern retail and nutritional awareness develop together.
Convenience Is Expanding Prepared Baby Food Demand
Prepared baby food is benefiting from urban lifestyles, dual-income households and demand for foods that require minimal preparation while maintaining controlled portions and consistent formulation. Pouches, jars, tubs and ready-to-feed products are easier to transport and use outside the home than traditionally prepared complementary foods, making convenience a significant purchasing factor for working households and travel occasions.
The trend is particularly important after six months, when feeding frequency increases and infants gradually move from purees and mashed foods toward more varied textures. WHO recommends complementary foods two to three times daily between six and eight months and three to four times daily thereafter, increasing the number of eating occasions during which convenience can influence purchasing behaviour.
Prepared Baby Food is therefore projected to grow at approximately 6.7% annually through 2031, faster than the overall market. Growth is strongest where manufacturers combine convenience with ingredient transparency, appropriate texture progression and formulations that parents consider sufficiently close to foods they would otherwise prepare at home.
Formula Innovation Is Shifting Toward More Specialized Nutrition
Infant-formula competition increasingly centres on composition and clinical or nutritional differentiation rather than basic calorie and protein delivery. HMOs, probiotics, prebiotics, whole-milk ingredients and formulations for allergies or digestive requirements are becoming more prominent within premium portfolios.
Nestlé is extending NAN Sinergity, which combines probiotics with six HMOs, while its June 2026 collaboration with biotechnology company Helaina is focused on bioactive proteins and early-life nutrition. Danone continues to position Specialized Nutrition as a major global business, reporting €9.3 billion of sales in the category during 2025 and describing itself as a global leader in baby formula. Specialized Nutrition also supported Danone’s APAC performance during 2026, including competitive infant milk formula growth in China.
Abbott’s August 2026 launch of a ready-to-feed Similac formula made with whole milk illustrates a parallel trend toward ingredient differentiation combined with convenience. These innovations support premium value growth even where birth rates are relatively weak, although they also increase R&D, clinical substantiation and quality-control requirements.
Organic and Ingredient-Transparent Products Gain Share
Organic products remain a minority of the global market but are growing faster as some parents seek certified sourcing, simpler ingredient lists and reduced exposure to specified agricultural chemicals. The opportunity extends across infant formula, cereals, purees and toddler foods, with companies including HiPP, Holle, Bellamy’s Organic and Earth’s Best maintaining portfolios built strongly around organic positioning.
Organic growth should not be interpreted as evidence that certified-organic baby food is inherently nutritionally superior to conventional products. Certification primarily defines how ingredients are produced and processed. The commercial advantage comes from trust, sourcing transparency and premium positioning among consumers willing to pay more for specified production standards.
Organic baby food is projected to grow at approximately 7.9% annually through 2031, allowing it to gain share gradually while Non-Organic products continue to represent the large majority of global value.
E-Commerce Broadens Access to Specialized Products
Baby food is well suited to digital retail because many products have relatively long shelf lives, parents frequently repurchase known brands and online channels make it easier to compare formulations, age stages and ingredient claims. E-commerce is particularly useful for specialized formula, organic products and products targeting allergies or specific nutritional requirements that may not be stocked widely in smaller physical stores.
Major food and nutrition groups are seeing strong digital growth more broadly. Nestlé reported organic e-commerce sales growth of 15.4% in the first quarter of 2026, with e-commerce reaching 21.5% of total group sales. While this figure is not specific to baby food, it demonstrates the broader shift in packaged-food purchasing behaviour that supports infant-nutrition availability through digital channels.
Online baby food sales are projected to grow materially faster than Offline channels through 2031, although supermarkets, pharmacies, specialist baby retailers and other physical stores remain central to the category because formula and baby nutrition purchases are highly trust sensitive.
Market Restraints
Breastfeeding Recommendations Limit the Addressable Formula Opportunity
WHO and UNICEF recommend exclusive breastfeeding for the first six months and continued breastfeeding alongside complementary food up to two years or beyond. Around 47% of infants aged 0–6 months were exclusively breastfed globally over 2018–2025, and WHO’s current objective is to increase exclusive breastfeeding further.
This appropriately limits the role that infant formula should play in market expansion and places strict expectations on how manufacturers communicate breast-milk substitutes. Formula companies therefore cannot treat infant feeding as a conventional packaged-food marketing category and increasingly maintain formal responsible-marketing standards aligned with national regulation and WHO principles.
Declining Birth Rates Restrict Volume Growth in Major Markets
Several large baby-food markets are experiencing declining birth cohorts, particularly China, Japan, South Korea and much of Europe. Fewer births directly reduce the number of new consumers entering the category each year and make sustained volume expansion difficult even where household incomes remain high.
The industry response is increasingly centred on premiumization, specialized formulas, organic products and broader feeding-stage portfolios. These strategies can increase value per child but do not remove the underlying demographic constraint, making the global market a moderate-growth category rather than a high-volume expansion market.
Food-Safety Requirements Continue to Tighten
Baby food is subjected to particularly high scrutiny because infants and young children are more vulnerable to microbiological and chemical hazards. The U.S. FDA issued final guidance in January 2025 establishing lead action levels of 10 ppb for several categories of processed baby food and 20 ppb for root vegetables and dry infant cereals. In April 2026, the FDA also published results from expanded testing of infant formula for arsenic, lead, cadmium and mercury under Operation Stork Speed and its Closer to Zero programme.
This increases requirements for supplier qualification, agricultural sourcing, analytical testing and traceability. Large companies can distribute these costs across global production networks, while smaller brands may face comparatively higher compliance costs per unit.
Recalls Can Rapidly Damage Consumer Confidence
Consumer trust is particularly fragile in infant nutrition because even precautionary recalls receive significant attention. Nestlé initiated a precautionary infant-formula recall during the first quarter of 2026 after detecting cereulide associated with an ingredient from an external supplier. The company reported that the event reduced first-quarter organic growth by around 90 basis points at group level and caused a temporary decline in Nutrition performance.
Danone also conducted precautionary recalls of selected Aptamil batches in 2026. These events highlight the commercial consequences of ingredient and supplier risk and increase pressure on manufacturers to extend testing beyond minimum regulatory requirements.
Homemade Foods Remain a Strong Substitute
Prepared baby food competes directly with fruits, vegetables, cereals and family foods prepared at home. WHO guidance specifically recognizes the transition toward ordinary family foods as children develop, with most children capable of eating similar types of food to the rest of the household by around 12 months when texture and nutritional requirements are considered.
Packaged products therefore need to justify their price through convenience, safety assurance, fortification, portability or specialized formulation. This restraint is strongest in markets where households have established home-preparation traditions and packaged baby food represents a significant premium over locally prepared meals.
Global Baby Food Market Segmentation Analysis
By Product Type
Milk Formula Remains the Largest Product Segment
Milk Formula accounts for approximately 56% of global market value in 2026. Its leading position reflects higher average selling prices than most cereals and prepared foods, recurring consumption during applicable feeding stages and a large specialized-nutrition portfolio covering standard, follow-on, allergy and medically oriented products.
Competition is led by companies with substantial nutritional-science and quality-control capabilities. Nestlé, Danone, Abbott, Reckitt and FrieslandCampina operate internationally, while Feihe, Yili, Junlebao, H&H Group, Ausnutria and other companies maintain particularly strong positions in Asian markets. Continued innovation in HMOs, probiotics, whole-milk formulation and specialized protein systems supports value growth, although demographic pressure and breastfeeding policy constrain volume expansion.
Prepared Baby Food is the fastest-growing major product category at approximately 6.7% CAGR through 2031. Purees, pouches and ready meals benefit from convenience and increasingly diverse ingredient combinations, and they also allow manufacturers to participate in feeding occasions after six months without relying exclusively on the formula category.
By Type
Non-Organic Products Retain the Majority of Market Value
Non-Organic baby food accounts for approximately 82% of market value in 2026 because conventional formula, cereals and complementary foods remain more widely available and generally more affordable. Large multinational and domestic brands continue to serve broad income groups through conventional product ranges, making this segment essential to total market volume.
Organic baby food is projected to grow at approximately 7.9% annually through 2031, supported by premium households seeking certified ingredient sourcing and greater supply across formula, cereals, purees and snacks. The segment gains share steadily but remains significantly smaller because certification costs and premium pricing limit penetration in price-sensitive markets.
By Distribution Channel
Offline Retail Remains the Primary Channel
Offline channels account for approximately 76% of global market value in 2026. Supermarkets, pharmacies, specialist stores and other physical retailers remain especially important for infant formula because parents frequently value immediate availability, product inspection and trusted retail environments when purchasing infant nutrition.
Online Distribution is projected to grow at approximately 8.5% annually through 2031. E-commerce improves access to specialized, organic and imported products and supports recurring purchases after a household has selected a preferred formulation. Growth is particularly strong in digitally developed Asian markets and among urban households using online grocery and marketplace services, although Offline retail remains larger at the end of the forecast period.
Geographical Outlook
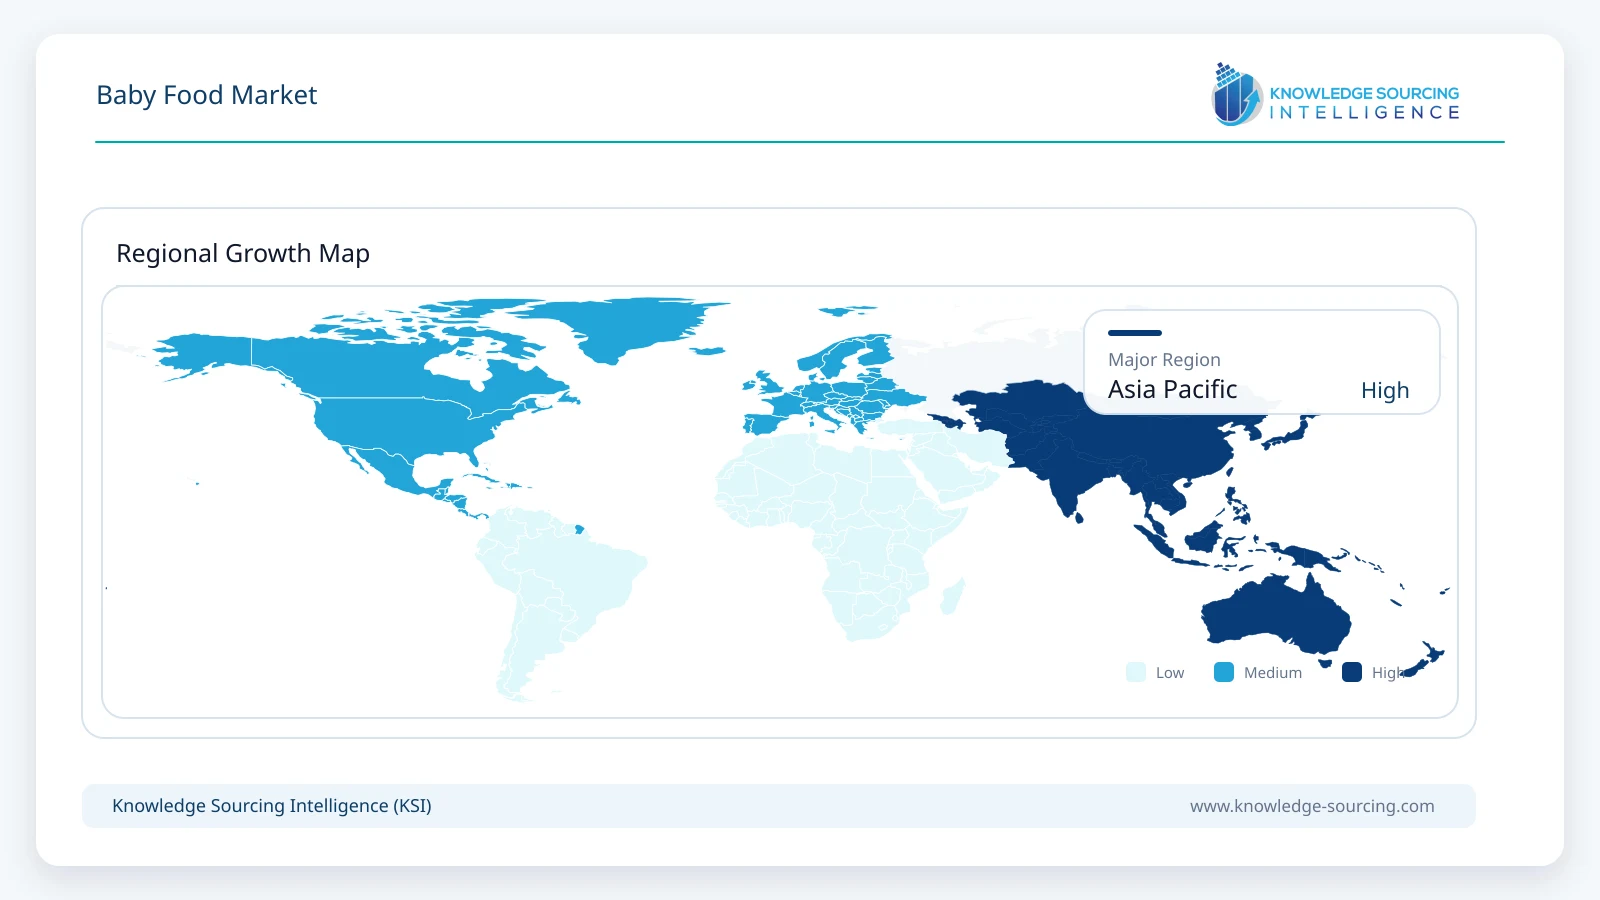
Asia Pacific Remains the Largest Regional Market
Asia Pacific accounts for approximately 43% of global baby food value in 2026. China remains one of the world’s largest infant-nutrition markets despite demographic pressure, while India and parts of Southeast Asia provide stronger child-population and packaged-food growth. Japan and South Korea contribute high-value premium markets, and the region also contains a substantial domestic manufacturing base.
Competition is particularly intense because international suppliers operate alongside large Asian companies. Danone reported competitive growth in infant milk formula in China during the second quarter of 2026, while Nestlé’s Nutrition business showed recovery in Asia, Oceania and Africa following its first-quarter recall.
Middle East & Africa is projected to record approximately 6.6% annual growth through 2031, making it one of the fastest-growing regional markets from a smaller base. Population growth, urban retail development and increased availability of packaged complementary nutrition support demand, but affordability remains a major constraint and the region contains substantial variation in household purchasing power and feeding practices.
Recent Developments
August 2026, Abbott introduced Similac 360 Total Care Made With Whole Milk in the United States, describing it as the country’s first commercially sterile ready-to-feed infant formula made with whole milk. The launch combines ingredient differentiation with the convenience of a liquid format.
June 2026, Nestlé entered a multi-year innovation collaboration with biotechnology company Helaina focused on bioactive proteins and their potential role in science-based early-life nutrition.
April 2026, the U.S. FDA released results from expanded testing of infant formula for arsenic, lead, cadmium and mercury as part of Operation Stork Speed and Closer to Zero, reinforcing the industry’s growing emphasis on contaminant monitoring and supply-chain assurance.
During 2026, Nestlé continued the international rollout of NAN Sinergity, with the company expecting the product containing probiotics and six HMOs to reach 50 countries by the end of the year.
At the end of December 2025, NewPrinces completed the acquisition of Plasmon and related infant and specialty-nutrition brands from Kraft Heinz, including the associated Italian production operation. The transaction strengthened NewPrinces’ position in European baby food and specialized nutrition.
Competitive Environment
The Global Baby Food Market combines multinational nutrition groups with strong regional formula manufacturers and specialist organic baby-food companies. Nestlé remains one of the broadest participants through NAN, Gerber, Cerelac and specialized infant-nutrition products, while Danone operates globally through Aptamil, Nutrilon, Bledina and other early-life nutrition brands. Danone’s Specialized Nutrition business generated approximately €9.3 billion in sales during 2025, illustrating the scale of nutrition as a strategic category within the company.
Abbott and Reckitt remain important in infant formula through Similac and Mead Johnson/Enfamil, while FrieslandCampina participates through Friso and related specialized nutrition. China has developed a substantial domestic competitive base through Feihe, Yili, Junlebao, H&H/Biostime and Ausnutria, reducing the historical dependence of premium infant nutrition on Western multinational brands.
HiPP, Holle, Bellamy’s Organic and Earth’s Best have stronger positions in organic and ingredient-led product segments, while Hero Group and NewPrinces/Plasmon participate across cereals, biscuits, purees and complementary food. The competitive structure therefore varies materially by product type and geography rather than being dominated by a single global group.
Through 2031, competitive advantage is likely to depend on quality assurance, nutritional science, trusted sourcing, responsible marketing, regulatory compliance and channel reach. Product innovation alone is insufficient in a category where recalls or compliance failures can rapidly undermine consumer confidence.
Analyst View
The Global Baby Food Market is projected to grow, but the composition of growth is changing. Demographics are becoming less supportive in several mature and high-value infant-nutrition markets, making premiumization, product specialization and greater expenditure per child increasingly important.
Milk Formula continues to generate the largest share of market value, but growth is stronger in Prepared Baby Food as urban households seek convenient complementary foods after six months. Organic products and online distribution similarly grow faster from smaller bases, reflecting demand for ingredient transparency and easier access to specialized products.
The industry’s regulatory environment is becoming more demanding at the same time. Lead action levels, expanded contaminant testing, responsible formula-marketing standards and recent recalls demonstrate that quality assurance and supplier control are becoming as important commercially as formulation innovation. The largest manufacturers retain an advantage because they can combine R&D and testing capability with global distribution, while specialist brands can compete effectively where organic certification, local feeding preferences or differentiated ingredients matter more than scale.
Asia Pacific remains central to the market because it combines the world’s largest concentration of infant-nutrition consumers with a strong domestic manufacturing base. Growth opportunities nevertheless vary significantly by country, and suppliers increasingly need localized product portfolios rather than a single global feeding proposition.
Baby Food Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 118.3 billion |
| Total Market Size in 2031 | USD 148.9 billion |
| Forecast Unit | Billion |
| Growth Rate | 4.71% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Type, Distribution Channel, Geography |
| Companies |
|
Market Segmentation
By Product Type
Dried Baby Food
Milk Formula
Prepared Baby Food
Others
By Type
Organic
Non-Organic
By Distribution Channel
Online
Offline
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. GLOBAL BABY FOOD MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Dried Baby Food
5.3. Milk Formula
5.4. Prepared Baby Food
5.5. Others
6. GLOBAL BABY FOOD MARKET BY TYPE
6.1. Introduction
6.2. Organic
6.3. Non-Organic
7. GLOBAL BABY FOOD MARKET BY DISTRIBUTION CHANNEL
7.1. Introduction
7.2. Online
7.3. Offline
8. GLOBAL BABY FOOD MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. Germany
8.4.2. France
8.4.3. United Kingdom
8.4.4. Spain
8.4.5. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Indonesia
8.6.6. Thailand
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Nestlé S.A.
10.2. Danone S.A.
10.3. Abbott Laboratories
10.4. Reckitt Benckiser Group plc
10.5. HiPP GmbH & Co. Vertrieb KG
10.6. Hero Group
10.7. The Hain Celestial Group, Inc.
10.8. China Mengniu Dairy Company Limited
10.9. H&H Group
10.10. Royal FrieslandCampina N.V.
10.11. China Feihe Limited
10.12. Inner Mongolia Yili Industrial Group Co., Ltd.
10.13. Junlebao Dairy Group
10.14. Ausnutria Dairy Corporation Ltd.
10.15. Holle baby food AG
10.16. Perrigo Company plc
10.17. NewPrinces S.p.A.
10.18. Meiji Holdings Co., Ltd.
10.19. Maeil Dairies Co., Ltd.
10.20. DMK Group
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











