
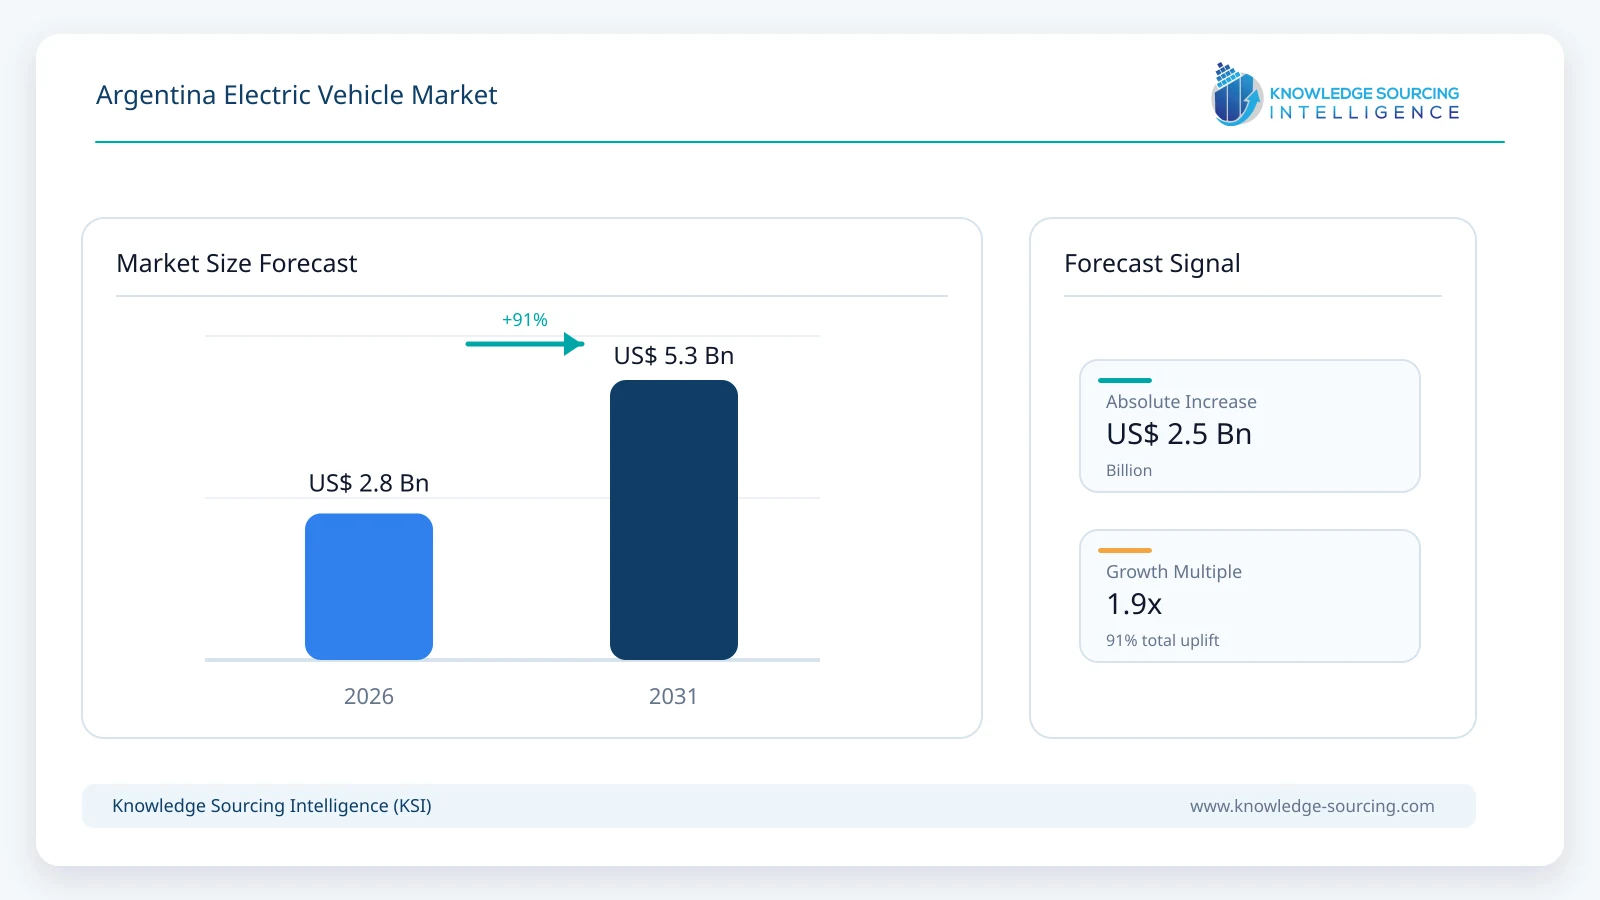
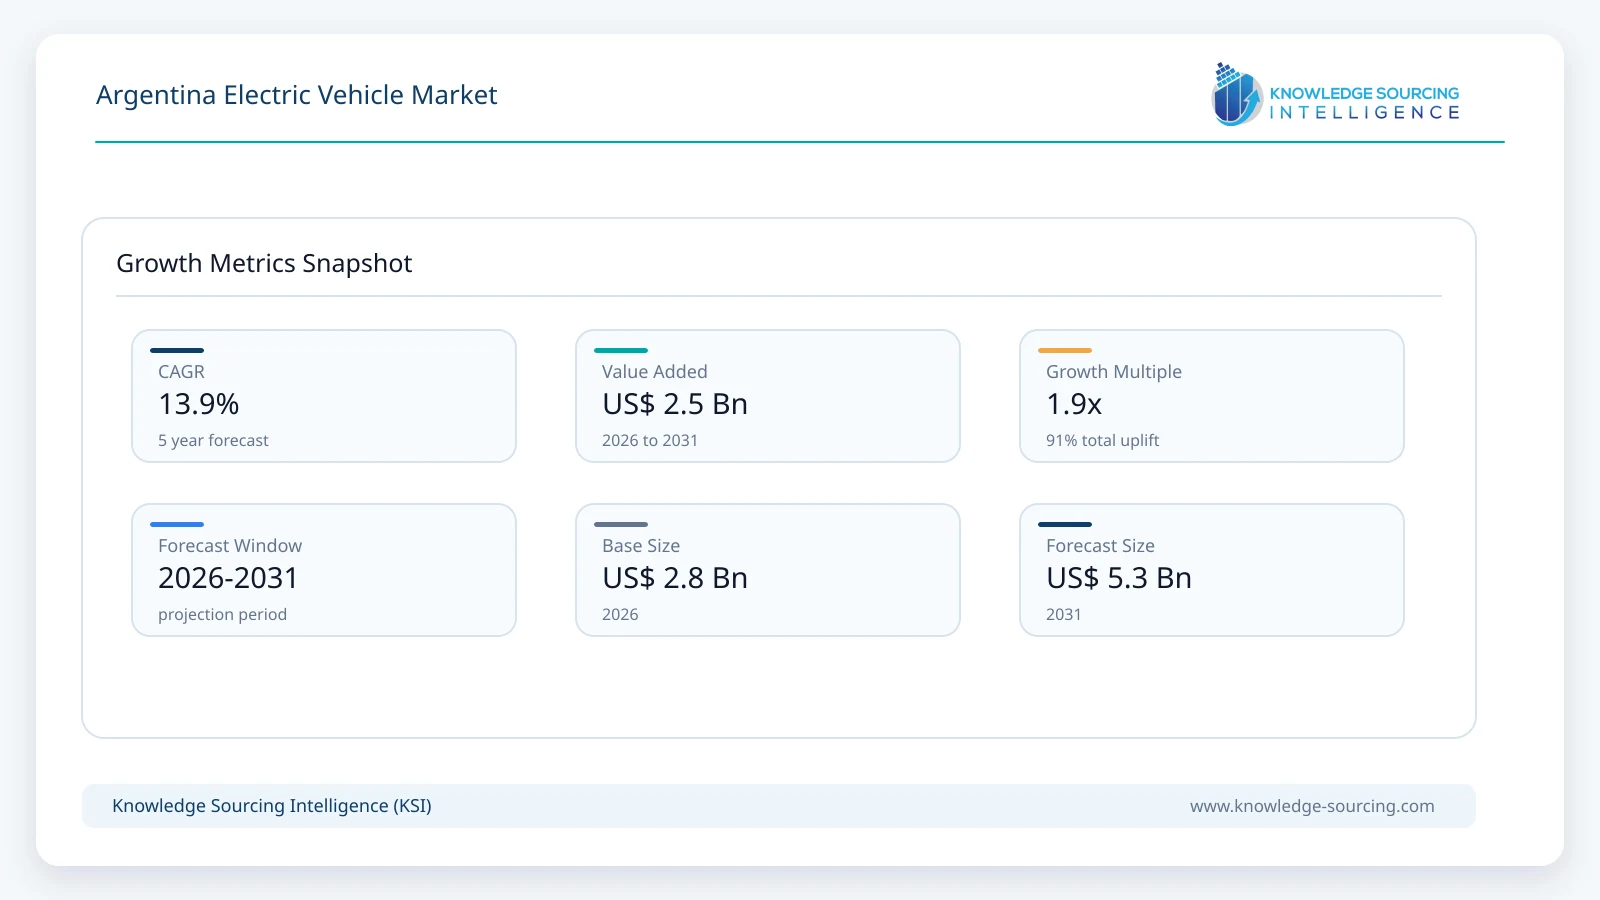
The Argentina Electric Vehicle Market is forecast to expand at a CAGR of 13.9%, reaching a value of USD 5.33 billion in 2031 from USD 2.79 billion in 2026.
Highlights:
- 1Hybrid electric vehicles remain the largest propulsion category, supported by established retail and servicing channels.
- 2Plug-in hybrids benefit from electric urban operation without relying exclusively on public charging.
- 3Passenger vehicles dominate sales value as electrified SUVs and compact cars expand model choice.
- 4Front-wheel-drive layouts lead demand, while all-wheel-drive SUVs raise future powertrain content.
- 5Buenos Aires Province anchors purchasing, with Córdoba developing a faster-growing regional base.
- 6Product availability and finance terms increasingly determine competition beyond headline vehicle range.
The Argentina electric vehicle market covers the value of newly sold passenger and commercial vehicles propelled by full-hybrid electric systems, externally chargeable plug-in hybrid systems, battery-electric systems and fuel cells. That definition includes self-charging hybrids alongside externally chargeable vehicles. Light hybrids that cannot propel the vehicle substantially using the traction motor alone are outside this market boundary. Technology differentiation depends on the traction battery, electric-drive architecture, software and final vehicle configuration.
Argentina’s tariff-free import regime, which permits qualifying non-Mercosur vehicles within an annual volume ceiling, changed the commercial economics of lower-priced electrified models. At the same time, Toyota and Ford compete through conventional hybrid vehicles, whereas BYD, Chevrolet and Leapmotor have enlarged the choices available to purchasers seeking plug-in operation. The resulting market remains heavily exposed to exchange rates, import administration and the reach of charging and service networks, making conversion from showroom interest to sustained registration volumes uneven across vehicle classes and provinces.
Market Overview
SIOMAA reported 42,238 registrations of broadly electrified vehicles in the first half of 2026, including 23,222 conventional hybrids, 8,979 plug-in hybrids and 3,877 battery-electric vehicles. A further 6,160 were mild hybrids; these are part of the broader industry statistic but not the defined full-hybrid, plug-in and battery-electric market analyzed here. The distinction matters because the headline count has risen sharply as import restrictions were eased, while plug-in vehicles still represent a minority of electrified registrations. Ford’s Territory hybrid, Toyota’s established hybrid sedans and SUVs, and imported BYD models illustrate the different ownership propositions underlying that mix.
Decree 49/2025 provides a zero extra-zone import duty for qualifying electrified passenger cars meeting an original USD 16,000 FOB ceiling and a 50,000-unit annual quota. The government awarded the 2026 quota to 71 models across 32 brands, substantially widening the potential sales portfolio. Quota assignments should not be confused with completed customer deliveries; inventory arrival, homologation, pricing in pesos and dealer throughput determine registrations. Cars supplied through Mercosur arrangements and higher-priced imports also compete outside that quota, so the program influences rather than defines total market volume.
The country possesses substantial lithium resources but remains reliant on imported finished vehicles, traction batteries and much of the associated electronics. Purchasing decisions are therefore governed primarily by the delivered vehicle package, warranty coverage, financing and accessible maintenance. Full hybrids avoid charging requirements, plug-in hybrids accommodate longer journeys with an internal-combustion backup, and battery-electric owners depend more directly on home, workplace or public charging access. Supplier investments in service training and provincial distribution should have a stronger near-term effect on adoption than assumptions about a fully localized battery-to-vehicle supply chain.
Market Trends
Hybrid Leadership Is Giving Way to a Broader Propulsion Mix
Non-plug-in hybrids still supply the largest share of Argentina’s electrified vehicle demand. Their established fuelling pattern suits households that travel outside major cities and gives manufacturers an easier entry into conventional dealer networks. SIOMAA’s first-half 2026 registrations nevertheless show plug-in hybrids becoming a material second category rather than a marginal premium option. BYD’s Song Pro and Seal 5 DM-i put larger electric-capable battery systems into price segments previously served mainly by conventional hybrids.
The shift creates different service requirements. Plug-in vehicles need battery diagnostics, charging interfaces and high-voltage technician training, while full hybrids can use more of the existing workshop footprint. Brands that scale after-sales capability alongside shipments should be better placed to retain customers as ownership moves beyond early adopters.
Vehicle Pricing Is Increasingly Shaped by Import Qualification
The 2025 import-duty reform reduced a substantial tariff burden for eligible vehicles below the prescribed FOB threshold. By December 2025, authorities had assigned the 2026 quota, prompting importers to launch additional vehicle lines and reconsider entry-level prices. A quota slot affects landed cost, but manufacturer positioning, freight, inventory finance and dealer margins still determine the final transaction value.
The commercial effect is not limited to vehicles entering through the concession. A more competitive entry price for one imported model can pressure conventionally imported and Mercosur-supplied rivals to revise trim levels or financing. That interaction makes model mix and realized prices as important as unit registrations when evaluating market revenue.
Plug-in Availability Is Expanding Faster Than Nationwide Charging Coverage
Chevrolet’s Spark EUV and BYD’s Dolphin Mini illustrate a broader selection of battery-electric models with urban-sized footprints. However, the suitability of a pure-electric vehicle differs sharply between an owner with off-street charging in Greater Buenos Aires and a household dependent on public infrastructure during intercity travel. Advertised driving range also varies with speed, weather, load and charging conditions, complicating comparisons based on single certification-cycle figures.
Dealers increasingly need to explain charging installation, battery warranty terms and travel planning at the point of sale. Until corridor charging becomes more predictable, plug-in hybrids can capture consumers who seek electric operation for daily use but are unwilling to accept a charging-only propulsion system for longer journeys.
Dealer Networks and Credit Offers Are Becoming Competitive Assets
BYD reported a network exceeding 20 sales points after its first year in Argentina and introduced new financing arrangements in September 2026. These investments address concerns beyond vehicle capability: parts availability, warranty administration, credit affordability and residual values. For new entrants with limited brand history in the country, service confidence can determine whether consumer interest converts to a purchase.
Established manufacturers retain an advantage in their large service networks, although rapid portfolio expansion can allow specialized electric-vehicle producers to close that gap in major urban centers. Distribution economics will increasingly differentiate national leaders from brands capable of selling only in the largest metropolitan areas.
Segment Analysis
By Vehicle Type: Passenger Vehicle
Passenger vehicles represent an estimated 86% of Argentine electric-vehicle market value in 2026. Demand is led by compact cars and sport-utility vehicles that can be registered and maintained through established retail channels. The imported BYD Dolphin Mini and Yuan Pro compete with hybrid products from Toyota and Ford, widening the choice between externally chargeable and self-charging vehicles. Sales incentives directed at qualifying passenger imports have also had a more immediate impact on this category than on heavier commercial applications.
Small electrified vans and other commercial formats may gain importance where urban routes are predictable and centralized depots can support charging, but most fleet buyers still demand proof of durability, total operating cost and service support. Passenger vehicles are expected to remain the primary revenue source even as the commercial share rises over the forecast horizon.
By Propulsion Type: Hybrid Electric Vehicle
Full hybrids account for USD 1.53 billion of modeled 2026 sales value and remain the largest propulsion segment. Their demand base is underpinned by households seeking lower fuel consumption without adding charging infrastructure to an apartment block or private property. Ford’s Territory hybrid and Toyota’s locally marketed hybrid portfolio offer relatively familiar ownership arrangements within dealerships already equipped to serve combustion-engine vehicles.
The category’s revenue weight moderates as plug-in hybrids and battery-electric vehicles gain model diversity and broader dealer coverage. The difference is not necessarily a retreat in hybrid unit sales; both total hybrid deliveries and the proportion of customers choosing plug-in vehicles can increase over the same period. Fuel prices, residual values and the continuation of lower-tariff imports will influence the pace of that change.
By Drive Type: Front Wheel Drive
Front-wheel drive is expected to remain the predominant architecture because most affordable electrified sedans and crossovers use compact transverse drivetrains. A front-drive system allows suppliers to share vehicle packaging, suspension layouts and production platforms with established models while containing drivetrain cost. It is therefore especially relevant to the entry-price bands targeted by new imported full hybrids and battery-electric cars.
Front-wheel-drive vehicles are expected to represent approximately 66% of market value by 2031 as higher-priced plug-in SUVs with multiple driven axles become more visible. All-wheel-drive capability is commercially useful for performance and larger SUVs, but it carries additional cost and need not deliver an equivalent benefit for urban buyers concerned chiefly with purchase price and energy consumption.
By Component: Battery Cells and Packs
Battery cells and packs account for an estimated 22% of the allocated 2026 vehicle value in the component view, reflecting the importance of energy storage in plug-in and battery-electric models. The proportion varies materially by propulsion: a full hybrid may use only a small battery, while a battery-electric car relies on a much larger traction pack. This makes battery chemistry, energy density and supplier qualification important to the vehicle’s final selling price.
Pack safety, thermal management, warranty coverage and sustained charging performance matter to both purchase decisions and residual value. Argentina’s lithium resources do not yet ensure local battery-pack supply for the automobiles sold domestically, so imported cell and pack economics remain central to automaker pricing and procurement strategies.
By End User: Private Buyers
Private purchases dominate this market and are modeled at approximately 77% of vehicle value in 2031. Household demand spans self-charging hybrids chosen for conventional long-distance use and plug-in vehicles purchased for predictable daily travel. The financing and servicing package remains important because most electric-vehicle buyers compare total monthly ownership expense rather than the powertrain technology in isolation.
Commercial fleets should gain share where recurring routes, energy prices and depot access allow savings to be measured reliably. Public procurement remains a smaller opportunity and is sensitive to tenders, fiscal budgets and maintenance arrangements. Neither fleet electrification plans nor government announcements can be treated as firm revenue before vehicle orders and registrations occur.
Market Drivers
Lower Import Duties and a Wider Eligible Model Portfolio
Argentina's zero-duty regime for qualifying extra-zone imports directly reduces one part of the cost stack that historically disadvantaged electrified passenger vehicles. The allocation of the 2026 quota across 71 models extends those benefits beyond a few established manufacturers and permits new Chinese and international brands to compete in the same price bands.
Import eligibility improves purchase economics but does not guarantee delivery. Manufacturer allocation choices, customs clearance, working capital and final dealer prices still determine the realized result. The policy creates the strongest demand response when qualifying models are backed by reliable local after-sales capability.
Expansion of Full-Hybrid and Plug-in Vehicle Choice
Competition now spans conventional full hybrids, externally chargeable plug-in SUVs, battery-electric compact cars and new range-extender designs. BYD's 2026 Argentine portfolio expansion and Leapmotor's B10 introduction illustrate how local buyers can compare vehicle technologies at multiple price points rather than choosing between an established hybrid and an expensive imported BEV.
Wider choice makes electrification relevant to different usage patterns. Full hybrids work without plug-in facilities; PHEVs provide electric operation for daily trips; BEVs suit consumers with dependable charging. The breadth of the product catalogue should sustain demand beyond the first wave of tariff-led registrations.
Urban Fuel-Expense Savings and Commuter Patterns
Congested metropolitan routes and recurrent commuting create circumstances where regenerative braking and electric traction are economically valuable. Households driving a largely predictable daily distance can evaluate battery-electric and plug-in hybrid models against gasoline vehicles on fuel, scheduled maintenance and energy spending over several years.
Cost comparisons remain sensitive to how and where a vehicle is charged and the price paid to acquire it. Suppliers able to quantify realistic urban savings without overstating national charging convenience are better positioned to convert efficiency claims into purchase decisions.
Greater OEM Commitment to Distribution and Support
New entrants are building authorized dealerships, parts operations and high-voltage technical services in Argentina. BYD's network expansion and the participation of established manufacturers such as General Motors and Ford reduce the perceived risk of buying a vehicle with unfamiliar components or software requirements.
Financing programs and warranty administration matter almost as much as model introductions. Higher conversion rates and repeat purchases depend on dealer capacity to diagnose traction systems, explain battery guarantees and provide timely service, particularly outside Buenos Aires.
Fleet Interest in Predictable Urban Operating Cycles
Delivery, corporate and municipal fleets with known daily mileage can compare the operating cost of plug-in vehicles with conventional models using actual route data. Battery-electric vans and urban passenger fleets have a stronger business case where overnight depot charging avoids dependence on intermittent public chargers.
Large-scale deployment remains conditional on procurement budgets, vehicle availability and downtime allowances. Nonetheless, fleets can provide steady orders and improved asset utilization once charging and workshop operations are organized around predictable schedules.
Market Restraints
Limited Reliable Charging Beyond the Main Urban Corridors
Battery-electric vehicles require more than nominal charger availability: connectors must be operational, accessible and compatible with the vehicle, while sites need adequate electrical supply. Sparse coverage outside the leading metropolitan areas makes long-distance ownership less convenient and increases the appeal of conventional or plug-in hybrids.
A buyer with home charging faces a very different practical cost from one dependent on publicly available fast charging. The resulting geographic disparity may restrict BEV adoption even when vehicle prices decline and model specifications improve.
Currency Exposure and Import-Dependent Vehicle Pricing
Argentina imports most finished plug-in vehicles and critical traction components, exposing transaction prices to exchange rates, international shipping costs and changes in border procedures. A lower import tariff does not remove these influences, particularly for models priced above the qualifying ceiling or purchased outside the preferential quota.
Rapid price changes can delay household purchases and complicate distributor inventory management. Brands with diversified sourcing and stronger financing relationships may be better able to maintain stable offers through changes in the peso and broader credit conditions.
Finite Import Quotas and Uncertain Incentive Continuity
The annual zero-duty program supports a finite number of eligible models and vehicles. Demand may increase faster than qualifying allocations, while unsuccessful applicants must trade under a different landed-cost structure. Allocations are administrative permissions and can be consumed unevenly during the year.
The scheme also has a defined policy horizon rather than constituting an unlimited permanent subsidy. Importers must assess replacement demand and pricing beyond preferential treatment, which makes future sales forecasts sensitive to regulatory continuity.
Battery-Service Skills and Residual-Value Questions
Battery-electric and plug-in vehicles require trained technicians, diagnostic systems, isolation procedures and parts supply that may not be available across all of Argentina's provinces. A short product-launch cycle can leave repair networks servicing battery packs, high-voltage electronics and proprietary software with limited local repair experience.
Used-vehicle valuation adds another obstacle. Buyers and finance providers need confidence in battery health, warranty transfer and prospective replacement costs. Weak residual-value visibility can raise the perceived cost of ownership even when routine energy consumption is lower.
Limited Domestic EV Manufacturing and Supplier Depth
Argentina has a developed conventional automotive sector and substantial lithium resources, but domestic battery-electric vehicle production remains limited compared with the imported model portfolio. Local lithium extraction does not by itself provide commercially available cells, packs, motors or inverters for locally assembled cars.
Developing those links requires repeatable vehicle volumes, supply agreements, engineering qualification and significant capital expenditure. Without them, automakers remain exposed to imported high-value components and may prioritize product distribution over domestic battery manufacturing.
Regional Outlook
Buenos Aires Province
Buenos Aires Province is projected to account for approximately 31% of Argentine electric-vehicle sales value in 2026. Its large population, substantial vehicle-registration base and extensive metropolitan commuting economy support purchases across mainstream hybrid SUVs, plug-in cars and commercial vehicle fleets. The province also benefits from access to vehicle import logistics and dealership capacity around the Greater Buenos Aires urban network, although customers in more distant districts face less consistent public charging coverage.
Its modeled share moderates to 29% by 2031 as sales expand faster outside the traditional largest urban market. Dealers with high-voltage repair capabilities and predictable supply of parts should retain an advantage, while demand from buyers without dedicated parking remains more tilted toward non-plug-in hybrids. The commercial base therefore combines strong buying power with differences in charging readiness across its districts.
Córdoba Province
Córdoba is forecast to grow at approximately 20.6% annually through 2031, supported by an expanding network of vehicle buyers beyond Greater Buenos Aires and the province's established automotive business ecosystem. Córdoba city and surrounding industrial areas present a mix of commuter usage, family SUV demand and fleet opportunities where hybrids already fit existing servicing and refuelling patterns. The province's broader automotive workforce can also help develop high-voltage maintenance capability.
The province’s estimated share rises from 12% in 2026 to 16% by 2031. Capturing that growth depends on chargers and dealerships extending beyond the provincial capital, with plug-in adoption benefiting most where employers and private residences can provide routine charging. Córdoba's trajectory is therefore stronger in the model than its present share, not evidence of an already mature plug-in ecosystem.
Competitive Landscape
Competition is divided between automakers with established distribution networks and entrants using new electric or plug-in platforms to gain access to Argentine customers. Toyota's hybrid offerings and Ford's Territory hybrid compete on reliability, dealer reach and the ability to operate without external charging. BYD targets the growing plug-in market with battery-electric cars, plug-in hybrid SUVs and sedans; General Motors offers the Spark EUV to extend its presence into affordable urban battery-electric products. Leapmotor introduces a further electrified alternative through its partnership with Stellantis.
The most consequential purchasing differences are not restricted to nominal battery range or acceleration. Import qualification, vehicle list price, financing availability, service-network geography and expected resale value can determine how quickly a model becomes a sustained registration contributor. Suppliers also face a need to explain test-cycle range and home-charger installation realistically rather than relying on specifications developed for different road conditions.
Brands entering with relatively low vehicle prices face costs associated with warranty management, high-voltage technician training, replacement parts and certified repair procedures. Established OEM networks can reduce these costs at the retail level but may compete against purpose-designed electric platforms with better packaging efficiency or lower battery costs. Market leadership is consequently likely to be segmented by HEV, PHEV and BEV rather than captured through a single unqualified electrified-vehicle ranking.
Recent Developments
8 October 2026: BYD reported expansion of its Argentine electric and plug-in hybrid vehicle lineup and authorized retail and service network after its first year of local operations.
15 September 2026: BYD introduced the Ti7 plug-in hybrid SUV in Argentina, adding an all-wheel-drive model to its local electrified portfolio.
3 September 2026: BYD launched the Seal 5 DM-i plug-in hybrid sedan in Argentina, widening its offering beyond SUVs and compact battery-electric cars.
15-17 July 2026: Leapmotor, distributed through the Stellantis ecosystem, presented its B10 range-extender SUV to Argentine customers.
24 July 2025: Chevrolet announced the start of Argentine sales of its fully electric Spark EUV, extending the battery-electric offering in the compact SUV segment.
Market Outlook
Argentina's electrified vehicle market is likely to remain a mixed-propulsion business throughout the forecast period. Full hybrids can grow within existing refuelling and service systems, while a larger share of plug-in hybrids and battery-electric vehicles will depend on a more consistent supply of appropriately priced models, credible warranty support and practical charging options. The industry’s acceleration in 2026 reflects genuine pent-up demand but cannot be extended indefinitely without regard to vehicle affordability and the finite tariff concession.
Major automotive producers and importers will compete over ownership economics, distribution reach and customer confidence. Brands that integrate vehicle pricing with financing, after-sales support and battery diagnostics are better placed to create recurring demand. The opportunity for localized assembly and battery manufacturing remains longer term; current market revenue is primarily earned on finished vehicle sales, regardless of where their upstream minerals originated.
Argentina Electric Vehicle Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.79 billion |
| Total Market Size in 2031 | USD 5.33 billion |
| Forecast Unit | Billion |
| Growth Rate | 13.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Vehicle Type, Propulsion Type, Drive Type, Component, End User |
| Companies |
|
Market Segmentation
By Vehicle Type
Passenger Vehicle
Commercial Vehicle
Others
By Propulsion Type
Battery Electric Vehicle (BEV)
Hybrid Electric Vehicle (HEV)
Plug-in Hybrid Electric Vehicle (PHEV)
Fuel Cell Electric Vehicle (FCEV)
By Drive Type
Front Wheel Drive
Rear Wheel Drive
All Wheel Drive
By Component
Battery Cells & Packs
Onboard Chargers & Motor
Brake, Wheel & Suspension
Others
By End User
Public
Private
Commercial
By Geography
Buenos Aires Province
Autonomous City of Buenos Aires (CABA)
Córdoba Province
Santa Fe Province
Mendoza Province
Other Provinces
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Lower Import Duties and a Wider Eligible Model Portfolio
3.1.2. Expansion of Full-Hybrid and Plug-in Vehicle Choice
3.1.3. Urban Fuel-Expense Savings and Commuter Patterns
3.1.4. Greater OEM Commitment to Distribution and Support
3.1.5. Fleet Interest in Predictable Urban Operating Cycles
3.2. Market Restraints
3.2.1. Limited Reliable Charging Beyond the Main Urban Corridors
3.2.2. Currency Exposure and Import-Dependent Vehicle Pricing
3.2.3. Finite Import Quotas and Uncertain Incentive Continuity
3.2.4. Battery-Service Skills and Residual-Value Questions
3.2.5. Limited Domestic EV Manufacturing and Supplier Depth
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Hybrid Powertrain Architecture
4.2. Plug-in Hybrid and Range Extender Technology
4.3. Battery-Electric Drivetrains and Charging
4.4. Battery Systems and Vehicle Software
5. ARGENTINA ELECTRIC VEHICLE MARKET BY VEHICLE TYPE
5.1. Introduction
5.2. Passenger Vehicle
5.3. Commercial Vehicle
5.4. Others
6. ARGENTINA ELECTRIC VEHICLE MARKET BY PROPULSION TYPE
6.1. Introduction
6.2. Battery Electric Vehicle (BEV)
6.3. Hybrid Electric Vehicle (HEV)
6.4. Plug-in Hybrid Electric Vehicle (PHEV)
6.5. Fuel Cell Electric Vehicle (FCEV)
7. ARGENTINA ELECTRIC VEHICLE MARKET BY DRIVE TYPE
7.1. Introduction
7.2. Front Wheel Drive
7.3. Rear Wheel Drive
7.4. All Wheel Drive
8. ARGENTINA ELECTRIC VEHICLE MARKET BY COMPONENT
8.1. Introduction
8.2. Battery Cells & Packs
8.3. Onboard Chargers & Motor
8.4. Brake, Wheel & Suspension
8.5. Others
9. ARGENTINA ELECTRIC VEHICLE MARKET BY END USER
9.1. Introduction
9.2. Public
9.3. Private
9.4. Commercial
10. ARGENTINA ELECTRIC VEHICLE MARKET BY GEOGRAPHY
10.1. Introduction
10.2. Buenos Aires Province
10.3. Autonomous City of Buenos Aires (CABA)
10.4. Córdoba Province
10.5. Santa Fe Province
10.6. Mendoza Province
10.7. Other Provinces
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Major Players and Strategy Analysis
11.2. Market Share Analysis
11.3. Mergers, Acquisitions, Agreements, and Collaborations
11.4. Competitive Dashboard
12. COMPANY PROFILES
12.1. Toyota Motor Corporation
12.2. Ford Motor Company
12.3. BYD Company Limited
12.4. General Motors Company
12.5. Great Wall Motor Company Limited
12.6. Renault Group
12.7. Stellantis N.V.
12.8. Leapmotor Technology Co., Ltd.
12.9. Nissan Motor Co., Ltd.
12.10. BMW AG
12.11. Mercedes-Benz Group AG
12.12. Coradir S.A.
13. APPENDIX
13.1. Currency
13.2. Assumptions
13.3. Base and Forecast Years Timeline
13.4. Key Benefits for Stakeholders
13.5. Research Methodology
13.6. Abbreviations
Navigate
Trusted by the world's leading organizations











