
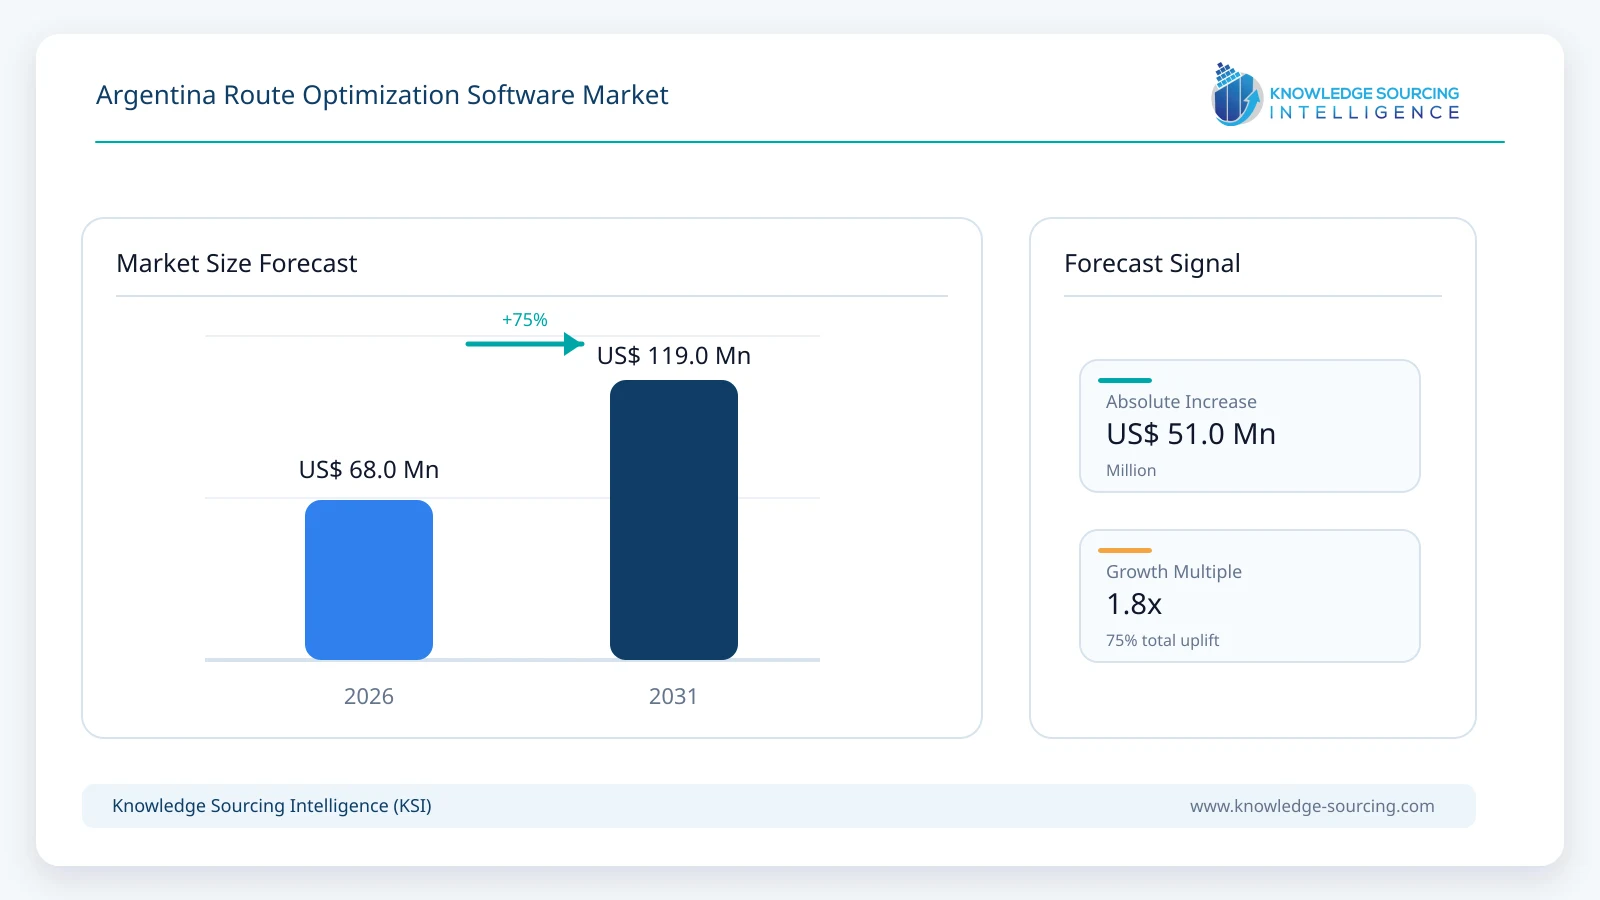
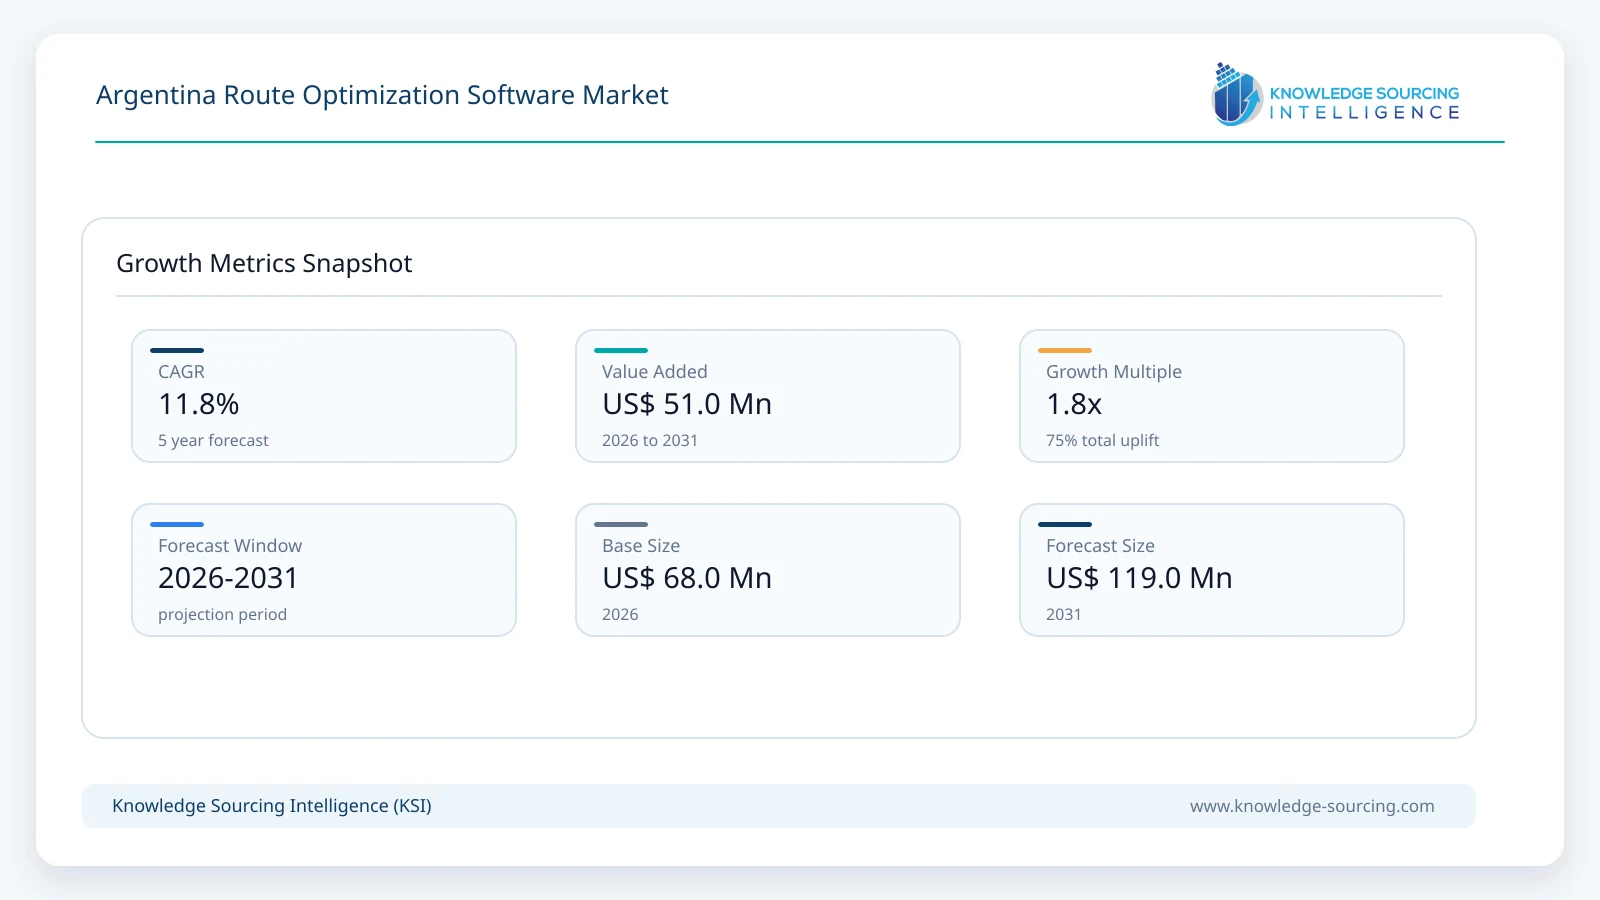
The Argentina Route Optimization Software Market is forecast to expand at a CAGR of 11.8%, reaching USD 119.0 million in 2031 from USD 68.0 million in 2026.
Highlights:
- 1Cloud deployment leads new subscriptions as smaller operators avoid dedicated routing infrastructure.
- 2E-commerce delivery is the largest individually identified application, supported by dense multi-stop demand.
- 3Software generates most supplier revenue, while integration services remain important for established fleets.
- 4Buenos Aires and the capital anchor purchasing; Córdoba benefits from manufacturing and distribution investment.
- 5Routing vendors increasingly compete on operational integration, constraint handling and delivery analytics.
Route optimization software calculates delivery and collection sequences using destination coordinates, vehicle capacity, customer time windows, driver shifts, traffic conditions, and service priorities. Commercial offerings combine recurring licenses, usage-based optimization services and implementation work for dispatch, order-management and warehouse-system integration. A route plan may be generated before departure or revised during operations when orders, traffic or vehicle availability change.
In Argentina, procurement spans retail and e-commerce fulfillment, food distribution, field services and contracted transport fleets. Local and regional specialists such as QuadMinds, SimpliRoute and Drivin compete with international platforms offering route planning, dispatch coordination and delivery execution. The economic benefit is most apparent where a business controls many stops each day and can measure fewer vehicle kilometres, lower dispatcher workload or greater delivery reliability.
Market Overview
Argentina’s route-optimization software demand is closely tied to the complexity of delivery operations rather than simply the number of registered trucks. Retail distributors serving supermarkets and neighborhood stores must repeatedly allocate orders across vehicles with different load limits and changing delivery windows. Software capable of sequencing stops across several depots and preserving proof-of-delivery information is more valuable to these operators than a basic shortest-path mapping tool. QuadMinds reported in May 2026 that an Argentine consumer-goods manufacturer standardized routing across a network of 170 exclusive distributors, demonstrating the operational scale that can justify enterprise deployment.
The country’s online commerce activity adds a second source of recurring scheduling work. The Argentine Chamber of Electronic Commerce reported 181.5 million online orders in the first half of 2026, an increase of 21% over the corresponding period of 2025. Those orders are not equivalent to paid route-optimization transactions: parcels may be consolidated, delivered through in-house systems or managed by carriers using established software. Nevertheless, the continuing order flow creates demand for route planning, capacity allocation, live ETA management, and delivery-exception handling in dense urban markets.
Supplier economics depend on how route planning is purchased. A mid-sized fleet may pay for a monthly driver-based subscription, while a national distributor may contract an enterprise routing platform with integration, configuration, and support. OptimoRoute publicly lists annual-billed plans priced per driver per month, establishing a practical reference for the lower end of commercial software pricing; enterprise implementations typically involve different contracts. The addressable revenue pool therefore includes the actual routing value within multifunctional logistics platforms, but excludes the wider price of vehicles, courier services and generic transport-management software when routing cannot be separately identified.
Market Trends
Routing Decisions Are Being Linked to Delivery Execution
Route planning is increasingly purchased together with dispatch instructions, driver apps and proof-of-delivery workflows. The value of an optimized stop sequence can be lost when vehicle loading, customer absence or site restrictions are not reflected in execution. QuadMinds’ documented Argentine distributor deployment illustrates how common routing practices across independently operated distribution territories can improve network oversight without requiring an entirely centralized delivery fleet.
Onfleet’s October 2026 software update added flexibility for hub-and-spoke assignments, enabling linked collection and delivery activities to be allocated to different drivers. The function is relevant to urban carriers using consolidation hubs rather than a single depot-to-customer route. Integration between the planning engine and live execution increasingly determines how much of the theoretical route saving can be retained.
APIs Are Taking a Larger Role in Route Planning
Large distribution clients often want routing decisions to appear inside their own order-management, ERP or warehouse software. SimpliRoute documents interfaces for vehicle constraints, backhaul pickups and distance outputs, allowing route calculations to form part of a wider operational workflow. Onfleet’s July 2026 product release introduced API parameters for stop priority, vehicle suitability and maximum route distance in its newer routing engine.
These interfaces make the commercial relationship more durable because the software becomes part of daily order release and delivery confirmation. They also raise implementation requirements: inconsistent address data, missing loading constraints or poorly synchronized order statuses can undermine optimization results even when the algorithm itself works correctly.
Distribution Networks Are Using More Detailed Routing Constraints
Argentina’s consumer-goods distributors must plan around road restrictions, collection windows, vehicle loading limits and variable service times. Refrigerated vehicles cannot automatically substitute for ordinary trucks, and high-priority orders may need to override a distance-minimizing result. Platforms including SimpliRoute and Onfleet explicitly allow vehicle capabilities and stop priority to shape route assignments.
This shift favors providers able to handle local delivery conditions through configurable software rather than custom code for every customer. It also limits the attraction of low-cost navigation applications for enterprises that require audit trails, shared dispatch visibility and reliable interfaces with invoicing and inventory systems.
Routing Economics Are Moving Beyond Fuel Savings
A route with fewer kilometres can still perform poorly if it increases late deliveries, overloads a driver or creates excessive dispatcher intervention. Onfleet’s July 2026 release added plan-versus-actual charts for route distance and duration, enabling clients to identify where forecast schedules diverge from operating conditions. Such metrics support decisions about staffing, service promises and depot allocation, not just fuel use.
For Argentine retailers and logistics providers, the purchasing argument is therefore strongest when software changes a measurable operational outcome. Providers that can demonstrate fewer failed stops, better use of vehicle capacity or reduced route-planning time can defend subscription pricing more effectively than vendors offering generic claims about artificial intelligence.
Segment Analysis
By Product: Software
Software contributes an estimated 80% of market revenue in 2026 as recurring cloud subscriptions, enterprise route engines and optimization APIs account for most contractual spending. Providers sell scheduling logic, dispatch interfaces and driver-facing tools under subscriptions or wider logistics-platform agreements. Their value is linked to the volume of route calculations, users or managed fleets, rather than to the monetary value of transported goods.
The software portion is expected to reach approximately USD 98.8 million in 2031. Integration and support remain relevant for larger operators, but standardized APIs and reusable configuration are expected to allow software revenue to grow more quickly than bespoke deployment services. Competition consequently turns on routing accuracy, uptime, application integration and the efficiency of maintaining the customer’s operating rules.
By Application: E-Commerce
E-commerce represents the largest separately identified route-optimization application because parcel and retail networks repeatedly process deliveries to different addresses under specific service promises. Delivery density in the Buenos Aires metropolitan area and the expansion of regional fulfillment operations create a practical requirement to group orders, assign vehicles and revise routes as consignments become available. CACE’s growth in order counts supports the operational case without implying that every order triggers a separately billed optimization request.
At an estimated 38% of the market in 2031, e-commerce gains share as direct-to-consumer delivery becomes more integrated with warehouse release and driver execution. Food delivery and ride-hailing are retained as separate categories, while the broader Other applications pool includes wholesale distribution, healthcare and field service. For suppliers, the main challenge is converting high activity volumes into contracted routing value rather than competing solely on free or low-cost mapping.
By Deployment: Cloud
Cloud deployment is expected to represent approximately USD 100.0 million by 2031, reflecting a growing preference for centrally maintained route engines that can serve multiple depots and mobile users. Regional software vendors can deliver updated algorithms and dispatch interfaces without requiring individual customers to operate dedicated routing servers. Small fleets benefit from faster installation, while multi-site enterprises can share common routing rules across locations.
Some established distributors continue to favor on-premises integrations where order systems or connectivity conditions require tighter control. Cloud adoption is not simply a technology choice: customers also assess availability, access permissions, ownership of location data and the reliability of offline driver workflows. The ability to support hybrid operational requirements will remain important for large contracts.
Market Drivers
Sustained Growth in Online Order Fulfillment
CACE recorded 181.5 million online orders during the first six months of 2026, with home delivery remaining the preferred fulfillment option among surveyed buyers. A growing number of shipment destinations increases daily route variability, even where order volumes are consolidated by major carriers. This creates work for optimization engines that can handle stop sequencing, service windows and delivery capacity.
The direct software opportunity arises where retailers and contracted couriers purchase route planning instead of relying on manually prepared driver itineraries. Adoption will depend on shipment density, software pricing and how effectively a platform integrates into existing fulfillment systems.
Greater Complexity in Consumer-Goods Distribution
FMCG distribution networks often use several independent carriers or distributors to reach retail customers across Argentina. QuadMinds described a May 2026 deployment covering 170 exclusive distributors for a major consumer-goods producer, with common rules for route creation and service-area planning. Such networks need consistent operating information without necessarily owning each transport asset.
A provider that can standardize planning across franchisees or contracted fleets may win a longer-term enterprise agreement. Implementation expenditure is justified when the customer can compare routes, service levels and capacity use across distributors rather than managing each territory independently.
Need to Control Delivery Cost and Fleet Utilization
Variable transport expense makes route sequencing a significant operating decision for fleets with numerous stops. Empty running, incomplete vehicle loads and repeated visits can erode margins even where freight volumes are stable. Route-planning software can choose more efficient stop combinations subject to load, timing and service constraints, provided the operator supplies reliable input data.
The strongest business case is not a theoretical distance reduction but a repeatable reduction in dispatch effort or unnecessary kilometres. This gives vendors room to price according to operational scale while requiring clients to monitor realized benefits over time.
Accessible Cloud-Based Subscription Models
Driver-based subscription models reduce the need for route-planning software to be purchased through a large capital IT project. OptimoRoute publishes monthly per-driver prices for standard planning tiers, while regional vendors offer configurable platforms suited to multi-stop distribution. This makes structured routing accessible to companies that cannot justify a custom transportation-management system.
Cloud procurement also supports staged expansion, from a limited number of routes to additional depots and vehicle classes. Renewal depends on the platform sustaining useful route quality and support, rather than on the ease of an initial trial alone.
Improved Integration with Enterprise Order Systems
Routing APIs can be connected to warehouse releases, order prioritization, customer notifications, and delivery confirmation. Onfleet and SimpliRoute publish interfaces that permit route calculations to incorporate different operating restrictions. Argentine enterprises with many branches gain from this integration because the same order information can drive planning and later execution records.
This raises the value of suppliers that offer both reliable optimization and a manageable integration architecture. The improvement is incremental rather than automatic: data cleansing, workflow redesign and cross-system ownership are often required before operational savings appear.
Market Restraints
Inconsistent Delivery Address and Location Data
Routing engines depend on reliable geocoding and a realistic representation of service points. Informal addresses, duplicate customer records, and missing delivery instructions can produce infeasible schedules, especially outside dense metropolitan districts. Errors may require drivers or dispatchers to correct routes manually, diluting the expected productivity benefit.
For suppliers, implementation therefore involves address validation, customer master-data updates and manual exception procedures. These costs can discourage smaller fleets if initial data preparation exceeds the perceived benefit of automated sequencing.
Integration Burden in Established Distribution Systems
National distributors frequently use legacy ERP and warehouse applications configured around existing picking and invoicing cycles. Routing software cannot reliably generate executable plans when shipment release times, vehicle capacities or order changes are transmitted late. Custom interfaces and testing may be necessary before a vendor can provide automated dispatch at scale.
The issue is particularly material for mixed own-fleet and outsourced networks where operators use different systems. Extended commissioning cycles can shift spending from license subscriptions into services and delay full operational adoption.
Macroeconomic and Currency-Related Procurement Sensitivity
Argentine fleet operators often evaluate imported or dollar-linked software subscriptions against local-currency operating budgets. Exchange-rate movements and changes in business volumes can make a recurring platform fee less predictable than manual dispatch costs. Smaller carriers may postpone upgrades when fuel, wages and financing needs absorb available cash.
Software suppliers may need local payment arrangements, contract flexibility or demonstrable short-payback use cases. The market is therefore unlikely to convert every eligible vehicle into a paid optimized endpoint within the forecast period.
Delivery-Data Privacy and Contractual Responsibilities
Route platforms process driver location, recipient contact details, addresses and sometimes service-history information. Argentina’s Personal Data Protection Law 25,326 establishes obligations relevant to identifiable information, requiring customers and providers to define access, use and security arrangements. This does not prohibit cloud route optimization, but it makes governance part of enterprise procurement.
Large buyers may require contract provisions for data retention, international transfers, access control and incident response. Providers that cannot explain how operational data are managed face longer qualification cycles, particularly in healthcare or other sensitive delivery networks.
Competition from Embedded and Internally Developed Routing
Large marketplaces and freight platforms may build route allocation into their proprietary operating systems rather than purchase separate third-party software. Other firms obtain basic sequencing from existing transport-management products or use simple navigation applications for low-stop routes. Those alternatives reduce the number of customers willing to pay a standalone routing subscription.
Independent vendors therefore need differentiated constraint handling, integration or execution analytics to justify their price. Bundling also creates price pressure when a customer already pays for dispatch and vehicle tracking within a broader software contract.
Regional Outlook
Buenos Aires Province and the Autonomous City of Buenos Aires — Dominant Market
Buenos Aires Province and the capital account for an estimated 52% of Argentine route-optimization revenue in 2026. Their concentration of retail outlets, distribution centers, parcel activity, and commercial service fleets generates dense delivery routes with frequent stops and narrow customer time windows. CACE’s reporting identifies the metropolitan area as a leading center of online commerce, although e-commerce sales concentration is not a direct measure of software spending.
The combined market is modeled at approximately USD 60.7 million in 2031, retaining the largest domestic position. Operators in the metropolitan area are comparatively well placed to quantify the savings from fewer unnecessary stops and better driver allocation. Growth also depends on how far large carriers develop optimization internally instead of buying from independent platforms.
Córdoba — Fastest-Growing Major Provincial Market
Córdoba’s software market is modeled to grow at approximately 14.6% annually through 2031, supported by manufacturing supply chains, agricultural-input distribution, retail logistics and cross-provincial transportation links. The province’s operating profile favors route-planning systems that reconcile warehouse releases with multiple delivery territories and different vehicle capacities.
Its projected market share increases from approximately 11.5% in 2026 to 13.0% by 2031. That change rests on faster enterprise adoption and distributor-network standardization rather than an assumption that Córdoba’s delivery volumes will exceed the Buenos Aires metropolitan area. Deployment outcomes will depend on local implementation expertise and the economics of replacing spreadsheet-based planning.
Competitive Landscape
The supplier field combines Argentine-founded logistics technology specialists with regional and international route-planning platforms. QuadMinds is especially relevant to enterprise distribution networks requiring route allocation across depots and independent carriers. SimpliRoute competes through configurable planning software and published optimization interfaces, while Drivin offers delivery management with route planning and execution visibility. Descartes’ July 2026 acquisition of Drivin brings those regional capabilities into a larger international logistics-software portfolio.
Onfleet, OptimoRoute and Routific focus more directly on structured route planning and delivery workflows for operators with recurring multi-stop demand. PTV Logistics and ORTEC offer advanced optimization for complex fleet planning, while DispatchTrack and FarEye compete where execution, customer communication and scheduling are closely combined. Providers that price by driver, route or enterprise subscription serve different purchasing needs; supplier size alone does not establish market share in Argentina.
The principal competitive test is the ability to produce executable schedules under actual local constraints. Address data, vehicle capabilities, dispatch workflows and system integrations matter as much as optimization algorithms. Suppliers able to combine reliable route outcomes with low implementation effort should be better placed to retain recurring revenue, although large shippers may continue to develop portions of the planning function internally.
Recent Developments
8 October 2026: Onfleet announced Q3 product updates allowing hub-and-spoke pickup and drop-off legs to be assigned separately, alongside stronger proof-of-delivery controls and a faster operations dashboard.
17 July 2026: Onfleet introduced additional route-optimization API parameters covering stop priority, vehicle suitability, maximum distance and route clustering, together with plan-versus-actual analytics.
7 July 2026: Descartes announced its acquisition of Drivin, expanding its Latin American last-mile delivery-management and route-optimization capabilities.
20 May 2026: QuadMinds published the deployment of standardized route planning across 170 distributors for an Argentine consumer-goods manufacturer, reporting more than two million deliveries managed monthly through the network.
16 April 2026: Onfleet reported Q1 updates to route loading, performance analysis and operational dashboards for delivery management users.
22 January 2026: SimpliRoute documented improvements to ETA calculations and visit/route handling in its software API changelog, addressing timing reliability in daily delivery planning.
Market Outlook
Recurring route-planning expenditure in Argentina is expected to shift further toward cloud delivery, integrated optimization APIs and reporting that compares plan quality with actual operations. Companies managing high stop counts have the strongest incentive to replace manual dispatch, particularly when they must coordinate multiple fleets or service territories. The pace of conversion will nevertheless vary considerably by fleet size, system maturity and available implementation resources.
Córdoba and other regional distribution centers should account for a gradually larger share of spending, while Buenos Aires remains the main revenue base. Competition is likely to intensify between specialized optimizers and logistics platforms that include routing within broader execution software. Sustainable supplier differentiation will come from delivering workable schedules, dependable interfaces and measurable operating savings rather than treating artificial intelligence as a standalone purchasing reason.
Argentina Route Optimization Software Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 68.0 million |
| Total Market Size in 2031 | USD 119.0 million |
| Forecast Unit | Million |
| Growth Rate | 11.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Solution, Application, Deployment, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Product
Software
Services
By Application
Food Delivery
Ride-Hailing and Taxi Services
E-Commerce
Others (Retail Distribution, Wholesale, Field Service and Other Uses)
By Deployment
On-Premises
Cloud
By Geography
Buenos Aires Province
Autonomous City of Buenos Aires (CABA)
Córdoba
Santa Fe
Mendoza
Entre Ríos
Tucumán
Other Provinces
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Key Findings
1.2. Argentina Route Optimization Software Market Size, 2026–2031
1.3. Principal Market Opportunities
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Sustained Growth in Online Order Fulfillment
3.1.2. Greater Complexity in Consumer-Goods Distribution
3.1.3. Need to Control Delivery Cost and Fleet Utilization
3.1.4. Accessible Cloud-Based Subscription Models
3.1.5. Improved Integration with Enterprise Order Systems
3.2. Market Restraints
3.2.1. Inconsistent Delivery Address and Location Data
3.2.2. Integration Burden in Established Distribution Systems
3.2.3. Macroeconomic and Currency-Related Procurement Sensitivity
3.2.4. Delivery-Data Privacy and Contractual Responsibilities
3.2.5. Competition from Embedded and Internally Developed Routing
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Vehicle Routing and Time-Window Optimization
4.2. Cloud-Native Planning and Routing APIs
4.3. Real-Time Reoptimization
4.4. Delivery Execution and Analytics
5. ARGENTINA ROUTE OPTIMIZATION SOFTWARE MARKET, BY PRODUCT
5.1. Software
5.2. Services
6. ARGENTINA ROUTE OPTIMIZATION SOFTWARE MARKET, BY APPLICATION
6.1. Food Delivery
6.2. Ride-Hailing and Taxi Services
6.3. E-Commerce
6.4. Others (Retail Distribution, Wholesale, Field Service and Other Uses)
7. ARGENTINA ROUTE OPTIMIZATION SOFTWARE MARKET, BY DEPLOYMENT
7.1. On-Premises
7.2. Cloud
8. ARGENTINA ROUTE OPTIMIZATION SOFTWARE MARKET, BY GEOGRAPHY
8.1. Buenos Aires Province
8.2. Autonomous City of Buenos Aires (CABA)
8.3. Córdoba
8.4. Santa Fe
8.5. Mendoza
8.6. Entre Ríos
8.7. Tucumán
8.8. Other Provinces
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. QuadMinds
10.2. SimpliRoute
10.3. Drivin (Descartes)
10.4. Onfleet
10.5. OptimoRoute
10.6. Routific
10.7. ORTEC
10.8. PTV Logistics
10.9. DispatchTrack
10.10. FarEye
10.11. NextBillion.ai
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations





Frequently asked questions
What is the forecasted market size and growth trajectory for the Argentina Route Optimization Software Market between 2026 and 2031?
The Argentina route optimization software market is projected to grow from USD 44.2 million in 2026 to USD 65.9 million by 2031. This growth represents a Compound Annual Growth Rate (CAGR) of 8.3% during the forecast period.
Which specific industry verticals are the primary drivers of demand for route optimization software in Argentina?
Transportation and logistics remains the most commercially important industry vertical for software adoption in Argentina. Significant demand also stems from logistics operators, retail distributors, food delivery platforms, utilities, healthcare distributors, and field service organizations.
What advanced technologies and functionalities are becoming crucial for buyers when evaluating route optimization solutions in Argentina?
Buyers are increasingly prioritizing AI-enabled route optimization, which is expanding beyond basic navigation into dispatch, workforce scheduling, and delivery analytics. Cloud-native deployment, real-time fleet visibility, fuel optimization, and delivery predictability are also key features reshaping purchasing criteria.
What are the key purchasing criteria influencing buyer decisions for route optimization software in the Argentine market?
Purchasing decisions increasingly prioritize integration capability, cloud deployment, API availability, and proof-of-delivery functionality. Buyers also place growing emphasis on AI-assisted scheduling, real-time visibility, implementation speed, cybersecurity, recurring software support, and compatibility with existing enterprise systems.
How does Argentina's unique logistics environment impact the commercial relevance and adoption of route optimization technologies?
Argentina's logistics environment, characterized by large metropolitan delivery volumes coexisting with long-distance freight corridors, directly influences operating margins. This scenario strengthens the commercial relevance of route optimization technologies for improving vehicle utilization, fuel expenditure, delivery reliability, and workforce productivity.
What are the main factors fueling the demand for route optimization software solutions in Argentina?
The primary demand drivers include growing e-commerce fulfillment requirements and the need for measurable reductions in transportation costs while maintaining service reliability. Broader digitalization across logistics operations, coupled with over 90% internet penetration and continuous national road freight regulation, further supports the adoption of these solutions.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Argentina Route Optimization Software Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/argentina-route-optimization-market