
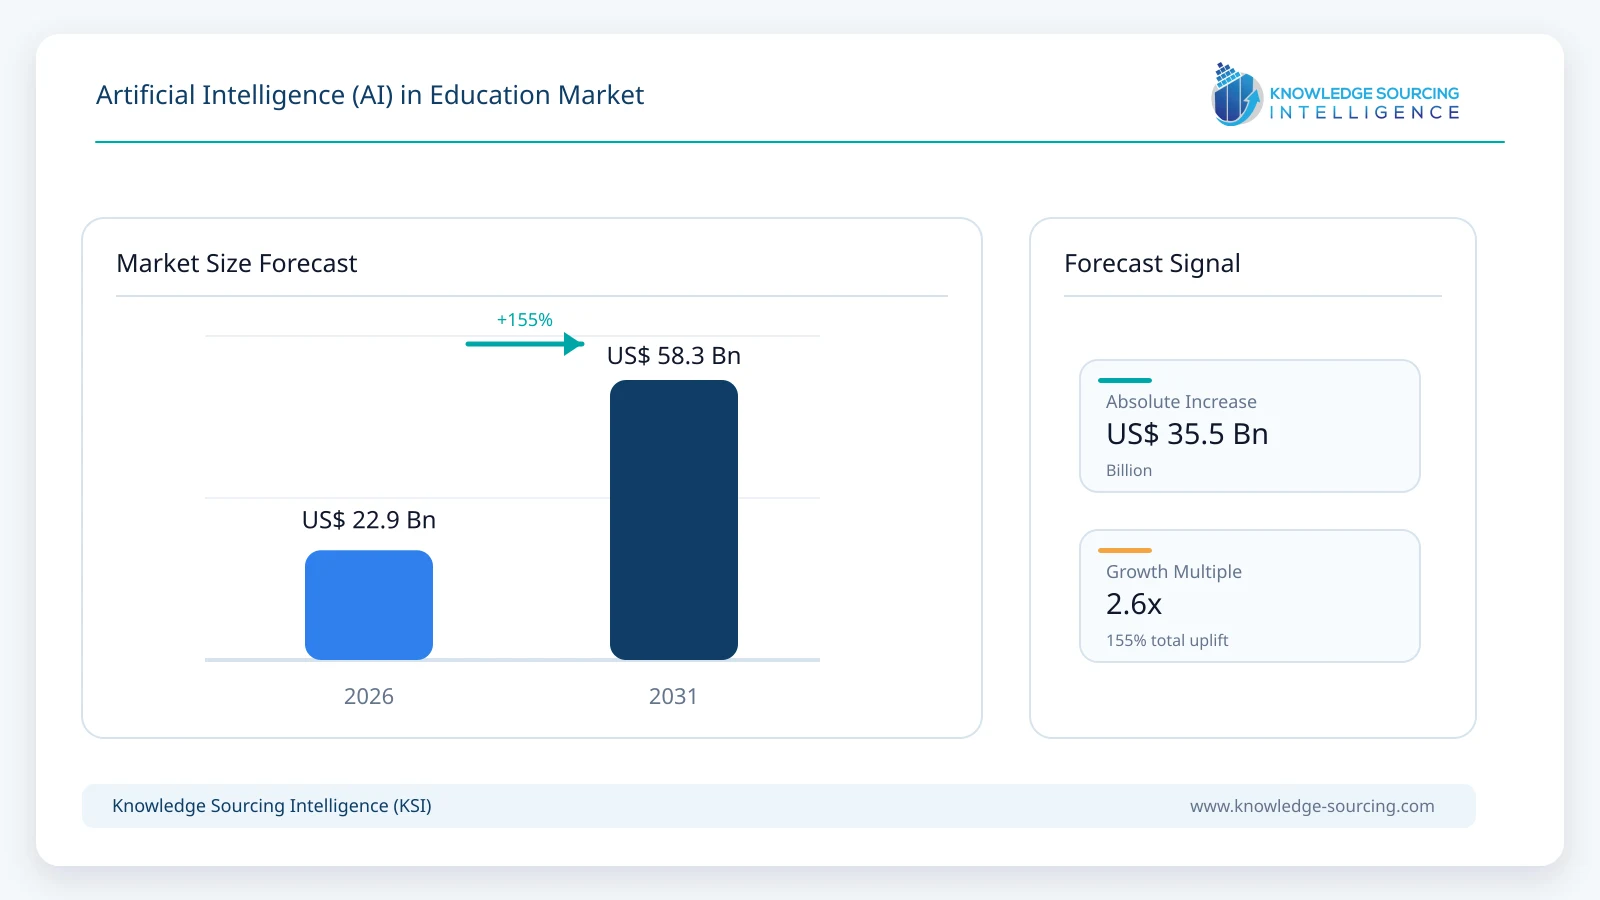
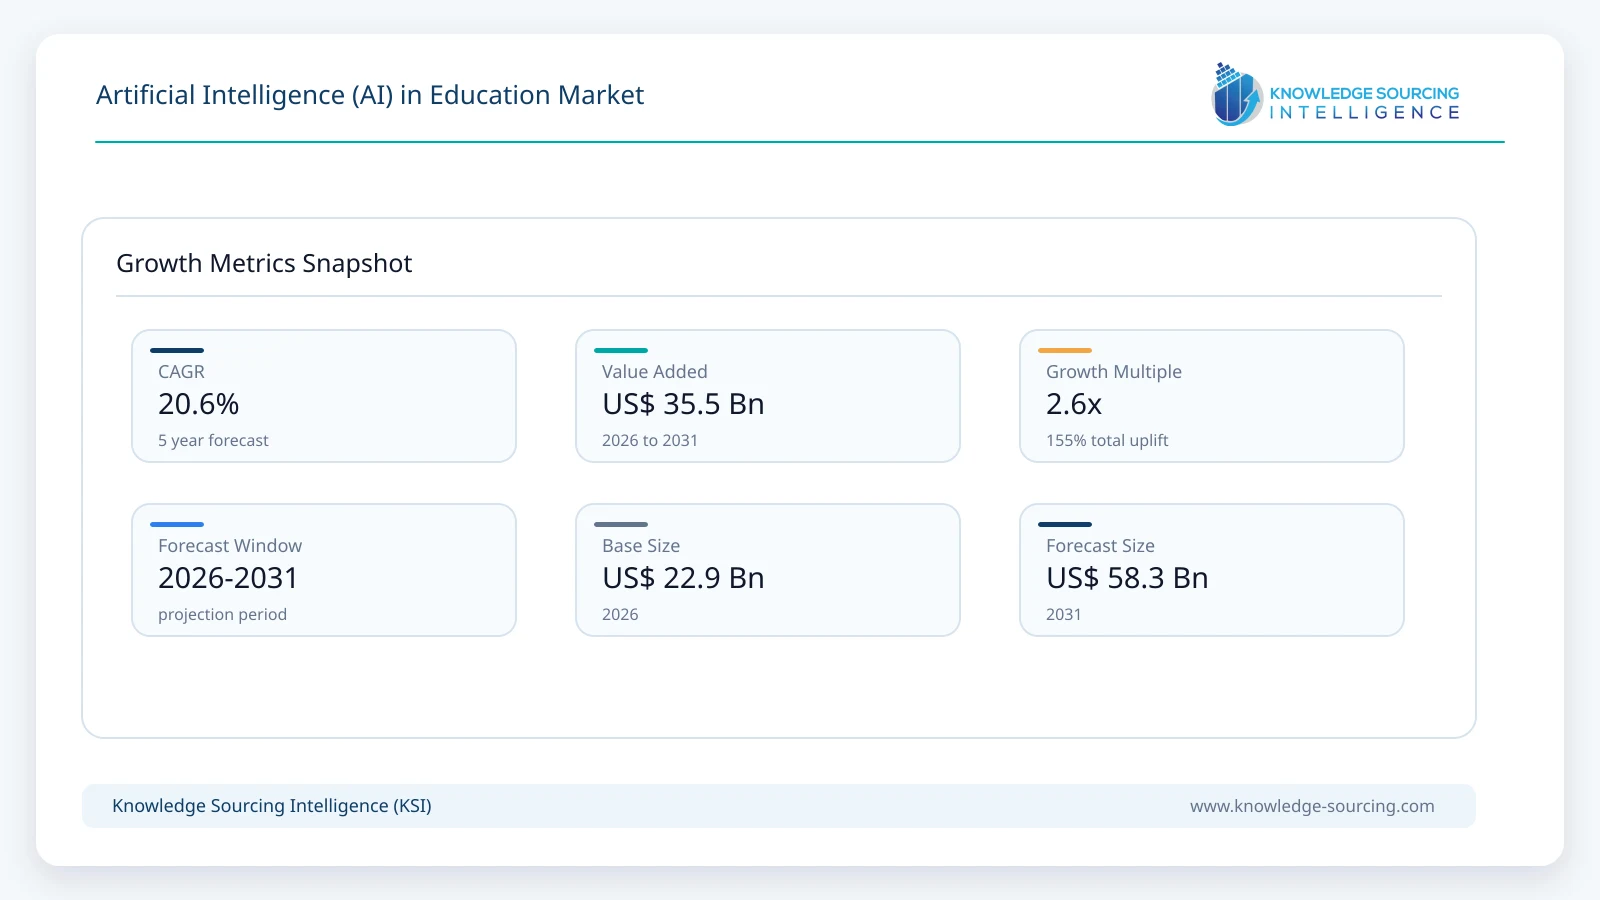
The Artificial Intelligence (AI) in Education market is forecast to grow at a CAGR of 20.61%, reaching USD 58.31 billion in 2031 from USD 22.85 billion in 2026.
Highlights:
- 1Rising demand for personalized learning experiences continues to accelerate institutional investment in AI-enabled education platforms.
- 2Cloud deployment represents the preferred implementation model because it reduces infrastructure costs and simplifies software updates.
- 3North America maintains strong commercial demand through established education technology ecosystems and higher institutional technology spending.
- 4Generative AI is expanding beyond content creation into assessment support, tutoring assistance, curriculum development, and administrative automation.
- 5Data privacy regulations and responsible AI frameworks increasingly shape procurement decisions across public education systems.
- 6Competition centers on platform integration, learning analytics, ecosystem partnerships, and trusted AI governance capabilities.
The Artificial Intelligence (AI) in Education market encompasses software platforms, intelligent tutoring systems, content generation tools, assessment solutions, learning analytics, virtual assistants, and supporting infrastructure that apply AI technologies to improve educational delivery, administration, and learner outcomes. The market serves educational institutions, corporate learning organizations, training providers, government agencies, and education technology vendors seeking to improve instructional efficiency while addressing growing learner expectations for personalized experiences.
Demand has shifted from experimental deployments toward institution-wide implementation as educational organizations seek measurable improvements in student engagement, administrative productivity, and learning performance. AI adoption is no longer confined to digital-native institutions. Traditional universities, K-12 school systems, and enterprise learning departments increasingly include AI capabilities within broader digital education procurement strategies. Purchasing decisions are now influenced by integration with existing learning management systems, compliance with data privacy regulations, multilingual capabilities, explainability of AI recommendations, and total cost of ownership rather than standalone algorithm performance.
The commercial structure includes global technology companies, education software providers, cloud infrastructure vendors, learning management platform developers, and specialist AI application providers. Software remains the largest revenue contributor because institutions typically deploy AI through existing digital learning environments rather than replacing physical infrastructure. Services continue to gain importance as organizations require implementation support, curriculum integration, educator training, cybersecurity assessments, and AI governance consulting. Hardware demand is concentrated in high-performance computing environments, classroom devices, and edge computing infrastructure supporting AI-enabled learning applications.
Technology adoption varies according to institutional maturity and funding availability. Universities with established digital ecosystems typically prioritize predictive analytics, automated assessment, and research assistance, while K-12 institutions emphasize adaptive learning and teacher productivity tools. Corporate training organizations focus on personalized content delivery, competency mapping, and workforce upskilling, reflecting stronger pressure to demonstrate measurable learning outcomes.
Growing public investment in digital education infrastructure, expanding cloud availability, and advances in generative AI have widened the range of commercially viable applications. At the same time, institutions remain cautious regarding student data protection, algorithmic bias, academic integrity, and regulatory compliance, making governance capabilities an increasingly important procurement criterion.
Market Drivers
Expansion of personalized learning initiatives
Educational institutions are under pressure to improve student retention, academic achievement, and learner engagement despite increasingly diverse student populations. AI enables adaptive learning paths that adjust instructional content according to individual performance, learning pace, and competency gaps.
Buyers increasingly prioritize platforms capable of demonstrating measurable educational outcomes instead of simply digitizing classroom materials. Vendors therefore compete by developing recommendation engines, intelligent tutoring capabilities, and predictive analytics that integrate seamlessly with existing learning environments. Institutions that can improve completion rates and reduce intervention costs often justify larger technology investments.
Administrative automation improves institutional efficiency
Administrative workloads continue to expand as educational organizations manage admissions, scheduling, grading, compliance reporting, student support, and faculty administration. AI reduces repetitive manual activities while improving response times for students and staff.
Educational buyers frequently evaluate solutions based on operational savings in addition to instructional value. Providers have responded by integrating AI-powered virtual assistants, automated document processing, scheduling optimization, and workflow automation into broader education management platforms. This increases software utilization while strengthening long-term customer retention.
Enterprise demand for workforce reskilling
Corporate learning departments increasingly require scalable training platforms capable of supporting rapidly changing workforce skill requirements. AI enables competency mapping, personalized learning recommendations, automated assessment, and multilingual content generation for geographically distributed employees.
Organizations purchasing enterprise learning platforms increasingly seek measurable productivity improvements linked to training investments. Suppliers differentiate through analytics dashboards, skills intelligence, certification management, and integration with human capital management systems.
Public investment in digital education infrastructure
Many governments continue expanding broadband connectivity, classroom digitization, and national digital learning initiatives. These investments improve the technological foundation necessary for AI deployment across public education systems.
Public procurement increasingly emphasizes interoperability, cybersecurity, accessibility standards, and long-term vendor support. Companies capable of satisfying government procurement requirements often secure large multi-year contracts that provide recurring software revenue.
Market Restraints and Challenges
Student data privacy and regulatory compliance
Educational institutions manage highly sensitive personal information involving minors, academic records, and behavioral data. Regulatory obligations create additional implementation complexity, particularly for cloud-based AI platforms.
Buyers therefore conduct extensive compliance assessments before procurement. Vendors must invest in encryption, identity management, data localization, audit capabilities, and transparent governance frameworks, increasing development and compliance costs.
Academic integrity concerns
Generative AI introduces uncertainty regarding original student work, assessment validity, and examination integrity. Institutions remain cautious when integrating AI into teaching and assessment processes.
Technology providers have expanded plagiarism detection, citation support, AI content identification, and educator oversight tools to address institutional concerns. Nevertheless, uncertainty regarding acceptable classroom use continues to slow adoption in some educational environments.
Uneven digital infrastructure
Many schools continue operating with limited broadband capacity, aging hardware, or insufficient technical support resources. These constraints reduce the effectiveness of AI applications requiring continuous connectivity or substantial computing resources.
Suppliers increasingly offer lightweight cloud architectures, hybrid deployment options, and scalable subscription models to improve accessibility. However, infrastructure disparities continue influencing regional adoption rates.
Educator readiness and organizational change
Successful AI implementation depends on faculty confidence, digital literacy, and curriculum adaptation rather than software deployment alone. Resistance to workflow changes may reduce technology utilization after procurement.
Institutions increasingly allocate budgets toward professional development, implementation consulting, and change management. Vendors that provide comprehensive training services often achieve higher customer retention and stronger platform adoption.
Major Segment Analysis
Cloud Deployment
Cloud deployment represents the most commercially significant deployment model because it enables educational institutions to implement AI capabilities without substantial capital investment in local computing infrastructure. Schools and universities increasingly prefer subscription-based cloud services that provide continuous feature updates, centralized security management, and flexible scalability according to enrollment changes.
Buyer priorities extend beyond infrastructure costs. Institutions require high system availability, secure data storage, integration with learning management systems, identity management compatibility, and compliance with regional privacy regulations. Multi-campus universities particularly value centralized administration and standardized learning environments across geographically dispersed locations.
Competition within this segment increasingly depends on ecosystem integration rather than standalone infrastructure. Vendors differentiate by supporting third-party education applications, developer ecosystems, analytics capabilities, and AI model deployment within existing institutional workflows. The recurring subscription model also provides predictable revenue streams while encouraging long-term customer relationships through continuous platform enhancements.
Regional Analysis
North America
North America represents a mature commercial environment supported by established education technology companies, extensive cloud infrastructure, and substantial institutional technology spending. Universities and corporate learning organizations continue investing in predictive analytics, personalized learning platforms, and AI-supported administrative operations. Procurement increasingly emphasizes cybersecurity, interoperability, and regulatory compliance.
Europe
European demand is strongly influenced by data protection requirements, responsible AI governance, and public investment in digital education initiatives. Educational buyers prioritize transparent algorithms, privacy safeguards, multilingual functionality, and accessibility standards. Cross-border research collaboration also supports AI adoption within higher education institutions.
Asia Pacific
Asia Pacific demonstrates broad adoption potential due to expanding internet connectivity, large student populations, government-supported digital education programs, and growing private investment in educational technology. China, India, Japan, South Korea, and Taiwan continue investing in intelligent learning platforms, teacher support tools, and workforce development initiatives. Market conditions vary according to infrastructure maturity and education funding.
Middle East & Africa
Governments across the Gulf region continue modernizing education systems through national digital transformation programs, smart campus investments, and workforce diversification strategies. African markets present long-term opportunities supported by mobile learning expansion, although infrastructure limitations, connectivity challenges, and funding constraints continue affecting implementation speed.
Competitive Landscape
The Artificial Intelligence (AI) in Education market demonstrates moderate concentration, with competition occurring between diversified technology companies, education platform providers, AI developers, and specialized learning software vendors. Market participants compete through platform integration, cloud capabilities, proprietary AI models, learning analytics, enterprise scalability, cybersecurity, and ecosystem partnerships rather than price alone.
Product differentiation increasingly depends on responsible AI capabilities, multilingual support, adaptive learning performance, integration with institutional information systems, and compliance with evolving privacy regulations. Strategic partnerships among cloud providers, universities, education publishers, and enterprise learning organizations continue expanding solution capabilities and market reach. Companies including Microsoft Corporation, Alphabet Inc., OpenAI, LLC, IBM Corporation, Oracle Corporation, NVIDIA Corporation, Pearson plc, Anthology Inc., Instructure Holdings, Inc., and Coursera, Inc. continue strengthening their education portfolios through product innovation, platform integration, and collaborative ecosystem development.
Recent Developments
March 2026: Instructure expanded AI functionality within its Canvas learning platform, introducing enhanced instructional assistance and workflow automation. The enhancement increased competitive differentiation within higher education learning management systems.
February 2026: Microsoft launched Microsoft Elevate for Educators in India, committing to train two million teachers by 2030 and extend AI readiness programs to approximately 200,000 schools and educational institutions.
January 2026: Pearson announced expanded AI-powered learning and assessment capabilities across its digital education portfolio to improve personalized instruction and educator support. The development reinforced recurring digital services revenue opportunities.
Regulatory and Policy Environment
AI deployment in education is increasingly influenced by privacy legislation, cybersecurity requirements, accessibility standards, and emerging AI governance frameworks. Educational institutions must comply with national and regional regulations governing student information, digital records, consent management, and secure cloud services. Procurement processes increasingly include cybersecurity certifications, data residency requirements, and contractual provisions addressing algorithm transparency and vendor accountability.
Government programs supporting digital classrooms, teacher training, broadband expansion, and AI literacy continue encouraging technology adoption across public education systems. At the same time, responsible AI guidelines increasingly require institutions to establish governance policies covering academic integrity, human oversight, explainability, and ethical use of automated decision-making. Vendors that demonstrate regulatory readiness gain stronger positions during public-sector procurement.
Outlook and Strategic Implications
Over the next five years, institutional investment is expected to concentrate on integrated AI ecosystems rather than isolated applications. Buyers will increasingly evaluate platforms according to measurable educational outcomes, interoperability, cybersecurity, governance capabilities, and long-term operating costs. Procurement strategies are likely to favor vendors capable of supporting complete educational workflows, from curriculum development and learner engagement to institutional administration and workforce analytics.
Generative AI will continue expanding beyond content generation toward intelligent tutoring, curriculum personalization, multilingual learning support, automated feedback, and educator productivity. However, responsible deployment will remain essential as educational institutions strengthen governance frameworks addressing transparency, copyright, assessment integrity, and student privacy.
Competitive positioning will increasingly depend on trusted partnerships, regulatory compliance, scalable cloud infrastructure, and continuous platform enhancement. Organizations capable of combining advanced AI functionality with secure implementation, educator support, and measurable educational value are expected to strengthen their commercial position as AI becomes an established component of modern education systems.
Artificial Intelligence In Education Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 22.85 billion |
| Total Market Size in 2031 | USD 58.31 billion |
| Forecast Unit | Billion |
| Growth Rate | 20.61% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Technology, Deployment, Solution, End-User, Delivery Mode, Geography |
| Companies |
|
Market Segmentation
By Technology
- Machine Learning
- Deep Learning
- Natural Language Processing
- Computer Vision
- Generative AI
By Deployment
- Cloud
- On-Premise
By Solution
- Software
- Hardware
- Services
By End-User
- K-12 Schools
- Higher Education Institutions
- Corporate Training
By Delivery Mode
- Web-Based Platforms
- Mobile Applications
By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Others
- Europe
- United Kingdom
- Germany
- France
- Spain
- Others
- Middle East and Africa
- Saudi Arabia
- UAE
- Others
- Asia Pacific
- China
- Japan
- India
- South Korea
- Taiwan
- Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits for Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Process
3. EXECUTIVE SUMMARY
3.1. Key Findings
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter's Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
4.5. Analyst View
5. ARTIFICIAL INTELLIGENCE (AI) IN EDUCATION MARKET BY TECHNOLOGY
5.1. Introduction
5.2. Machine Learning
5.3. Deep Learning
5.4. Natural Language Processing
5.5. Computer Vision
5.6. Generative AI
6. ARTIFICIAL INTELLIGENCE (AI) IN EDUCATION MARKET BY DEPLOYMENT
6.1. Introduction
6.2. Cloud
6.3. On-Premise
7. ARTIFICIAL INTELLIGENCE (AI) IN EDUCATION MARKET BY SOLUTION
7.1. Introduction
7.2. Software
7.3. Hardware
7.4. Services
8. ARTIFICIAL INTELLIGENCE (AI) IN EDUCATION MARKET BY END-USER
8.1. Introduction
8.2. K-12 Schools
8.3. Higher Education Institutions
8.4. Corporate Training
9. ARTIFICIAL INTELLIGENCE (AI) IN EDUCATION MARKET BY DELIVERY MODE
9.1. Introduction
9.2. Web-Based Platforms
9.3. Mobile Applications
10. ARTIFICIAL INTELLIGENCE (AI) IN EDUCATION MARKET BY GEOGRAPHY
10.1. Introduction
10.2. North America
10.2.1. By Technology
10.2.2. By Deployment
10.2.3. By Solution
10.2.4. By End-User
10.2.5. By Delivery Mode
10.2.6. By Country
10.2.6.1. United States
10.2.6.2. Canada
10.2.6.3. Mexico
10.3. South America
10.3.1. By Technology
10.3.2. By Deployment
10.3.3. By Solution
10.3.4. By End-User
10.3.5. By Delivery Mode
10.3.6. By Country
10.3.6.1. Brazil
10.3.6.2. Argentina
10.3.6.3. Others
10.4. Europe
10.4.1. By Technology
10.4.2. By Deployment
10.4.3. By Solution
10.4.4. By End-User
10.4.5. By Delivery Mode
10.4.6. By Country
10.4.6.1. United Kingdom
10.4.6.2. Germany
10.4.6.3. France
10.4.6.4. Spain
10.4.6.5. Others
10.5. Middle East and Africa
10.5.1. By Technology
10.5.2. By Deployment
10.5.3. By Solution
10.5.4. By End-User
10.5.5. By Delivery Mode
10.5.6. By Country
10.5.6.1. Saudi Arabia
10.5.6.2. UAE
10.5.6.3. Others
10.6. Asia Pacific
10.6.1. By Technology
10.6.2. By Deployment
10.6.3. By Solution
10.6.4. By End-User
10.6.5. By Delivery Mode
10.6.6. By Country
10.6.6.1. China
10.6.6.2. Japan
10.6.6.3. India
10.6.6.4. South Korea
10.6.6.5. Taiwan
10.6.6.6. Others
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Major Players and Strategy Analysis
11.2. Market Share Analysis
11.3. Mergers, Acquisitions, Agreements, and Collaborations
11.4. Competitive Dashboard
12. COMPANY PROFILES
12.1. Microsoft Corporation
12.2. Alphabet Inc.
12.3. OpenAI, LLC
12.4. IBM Corporation
12.5. Oracle Corporation
12.6. NVIDIA Corporation
12.7. Pearson plc
12.8. Anthology Inc.
12.9. Instructure Holdings, Inc.
12.10. Coursera, Inc.
13. APPENDIX
13.1. Currency
13.2. Assumptions
13.3. Base and Forecast Years Timeline
13.4. Key Benefits for Stakeholders
13.5. Research Methodology
13.6. Abbreviations
Navigate
Trusted by the world's leading organizations











