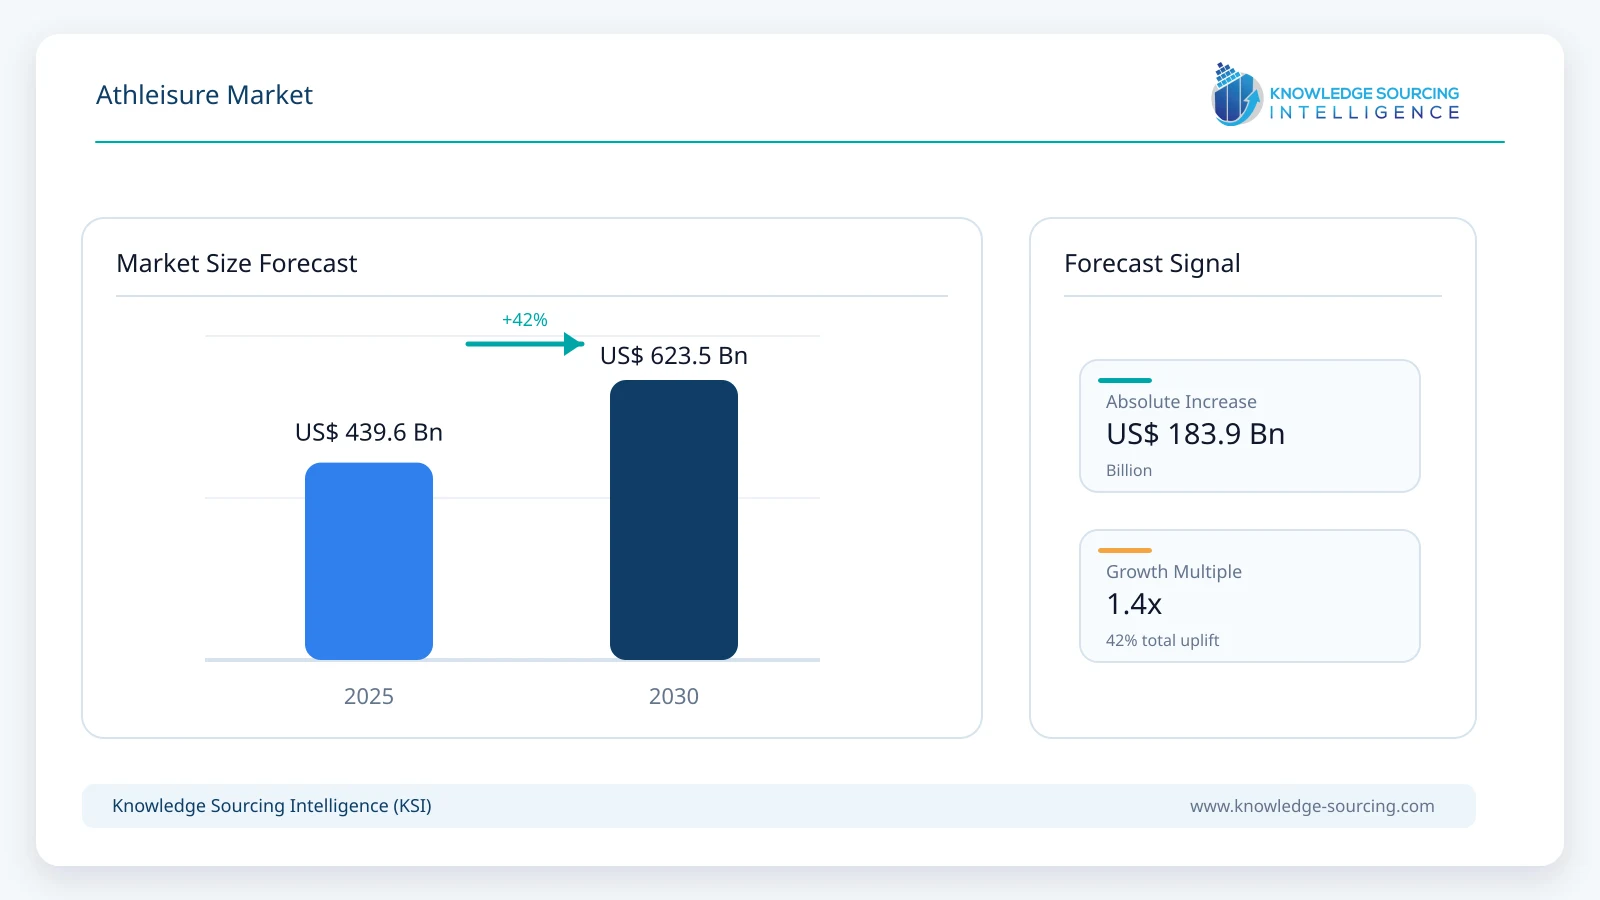
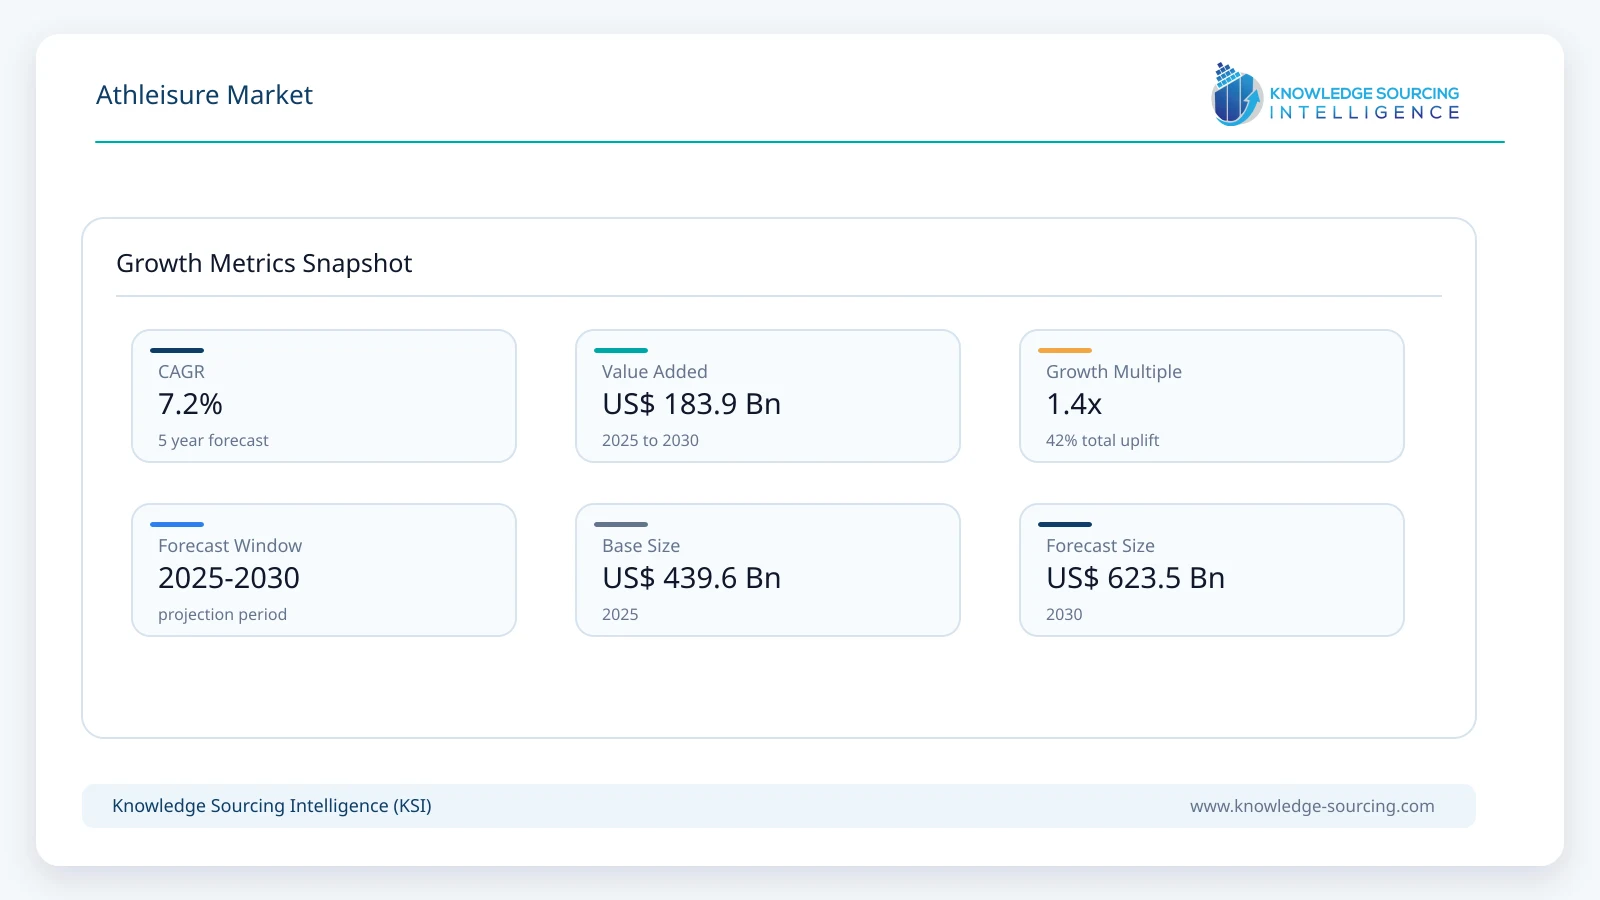
The Athleisure market is forecast to grow at a CAGR of 7.27%, reaching USD 669.4 billion in 2031 from USD 471.3 billion in 2026.
Highlights:
1
Top Wear accounts for approximately 38% of market value in 2026, making it the largest product group.
2
Footwear increases from approximately 33% of market value in 2026 to 34% by 2031, supported by sport-inspired sneakers and lifestyle running products.
3
Leggings are projected to grow at approximately 9.0% annually, increasing their share as women’s athleisure and training apparel expand.
4
Online distribution accounts for approximately 35% of sales in 2026 and is projected to reach around 40% by 2031.
5
Women represent approximately 46% of market value in 2026 and remain the largest end-user segment.
6
Asia Pacific increases from approximately 30% of global market value in 2026 to 34% by 2031, supported by rising sportswear consumption and local-market product development.
Demand is supported by the continued use of athletic apparel and footwear outside formal sporting activity, with consumers increasingly selecting clothing that can be used for exercise, travel, commuting and casual daily wear. Major sportswear companies now treat this overlap between performance and lifestyle as a core product category rather than a secondary extension of sports apparel.
The market is being shaped by both performance innovation and fashion cycles. adidas reported that Lifestyle revenues increased 12% in 2025, with double-digit growth in both Originals and Sportswear, while its lifestyle offering increasingly combines running, football and archive-based designs with streetwear and casual use. PUMA similarly identifies athleisure as an established part of everyday clothing and expects underlying sporting-goods demand to remain supported by active lifestyles and consumer preference for comfort.
Product development is moving beyond conventional tracksuits and basic athletic clothing. Nike’s 24.7 collection combines technical materials and four-way stretch with clothing designed for daily wear, while its 2026 Studio Fleece collection was developed around performance, comfort and everyday use. lululemon’s 2026 collaboration with Saul Nash follows the same approach by combining technical construction with lifestyle silhouettes. These launches indicate that the distinction between performance wear and casual clothing is narrowing across both premium and mass-market brands.
Market Growth Drivers and Trends
Athletic Clothing Is Becoming Part of Everyday Wardrobes
Athleisure growth is increasingly linked to the use of sportswear outside sport rather than only to increases in formal exercise participation. adidas defines its Lifestyle category as footwear, apparel and accessories that originate in sport but are worn for style, while PUMA’s 2026 strategy explicitly combines performance categories with Sportstyle products designed to be worn off the pitch. This broadens the addressable consumer base because the same product can be purchased for commuting, travel, casual work environments and social use in addition to exercise.
The effect can be seen in product development. Nike 24.7 uses technical stretch materials in items such as trousers, skirts and woven shirts rather than limiting performance fabrics to gym wear, while adidas has expanded sports-derived silhouettes into lifestyle running and fashion-led footwear. Athleisure therefore gains from both sport participation and the continued substitution of more formal casual clothing with comfortable athletic designs.
Performance Materials Are Moving Into Lifestyle Products
Technical fabrics are becoming more important outside conventional training clothing. Nike’s 24.7 range uses four-way stretch and Dri-FIT technology in daily-wear products, while lululemon’s 2026 SLNSH collections combine mesh, perforation, lightweight construction and modular features with clothing intended for everyday use. These developments allow brands to justify higher price points through comfort, stretch, moisture management and durability while retaining a fashion-led appearance.
This material shift also affects the internal market mix. Polyester remains the largest material category because of its widespread use in technical and mass-market garments, but nylon and other blends grow faster as brands use softer, lighter and more elastic materials. The Others category is expected to gain share as recycled fibres, engineered blends and alternative textiles become more common across premium collections.
Footwear Is Increasingly Designed for Both Performance and Lifestyle Use
Athletic footwear is becoming less dependent on a single sport or training purpose. adidas reported continued demand for Terrace, retro running and lifestyle-running products during 2025, while its 2026 Lifestyle business continued to expand through Originals, Sportswear and new footwear formats. The company’s first-quarter 2026 results also showed growth across its lifestyle business as sport-derived designs continued to be adapted for everyday use.
This supports a moderate increase in footwear share from approximately 33% of the athleisure market in 2026 to 34% by 2031. Footwear provides brands with strong product recognition and frequent design refresh cycles, while retro running, low-profile sneakers and sport-inspired casual shoes allow athletic brands to compete directly with conventional fashion footwear.
Direct-to-Consumer and Online Sales Are Increasing
Online channels allow athleisure brands to launch products more frequently, control merchandising and collect consumer data without depending entirely on wholesale retail. adidas reported that e-commerce revenue increased 25% in the first quarter of 2026 and 26% during the first half, while own-retail sales also increased strongly. The company maintained wholesale growth at the same time, indicating that digital and physical distribution remain complementary rather than mutually exclusive.
KSI estimates that online channels account for approximately 35% of market value in 2026 and increase to around 40% by 2031. Offline stores remain the larger channel because fit, footwear sizing, product trial and brand experience remain important, but digital channels gain share as large brands expand direct-to-consumer platforms and smaller specialist labels use online distribution to reach consumers without large store networks.
Women’s Athleisure Continues to Expand
Women represent the largest end-user category because leggings, training apparel, studio wear, running clothing and lifestyle sportswear have developed into distinct product categories with frequent seasonal and style updates. Nike’s 2026 Studio Fleece collection was based on input from more than 300 women and includes hoodies, sweatshirts, shorts and sweatpants positioned for both comfort and everyday use. lululemon also continues to extend technical construction into fashion-led products across women’s and men’s collections.
Women account for approximately 46% of the market in 2026 and are projected to reach around 47% by 2031. The gain is relatively modest because men’s athleisure also expands rapidly, but women’s products continue to lead in leggings, studio apparel and coordinated lifestyle collections.
Market Restraints
Consumer Spending Remains Sensitive to Economic Conditions
Athleisure includes a significant discretionary component, particularly in premium footwear and branded apparel. adidas expects sporting-goods demand to remain structurally supported in 2026 but also notes subdued consumer confidence and continued pressure on disposable income in North America, Europe and Greater China. PUMA similarly expects macroeconomic and geopolitical uncertainty to affect demand and is using 2026 as a transition year while reducing inventory and simplifying its product portfolio.
Premium athleisure brands can partly offset weaker unit demand through product innovation and pricing, but mid-market and fashion-led products remain exposed to promotional activity. This is particularly important when consumers already own multiple pairs of sneakers, leggings or hoodies and can postpone replacement purchases.
Fashion Cycles Can Shorten Product Lifecycles
Athleisure combines sportswear economics with fashion risk. Retro running shoes, terrace footwear, oversized silhouettes and particular colour trends can expand quickly but can also lose demand if consumers move to a different look. adidas has responded by refreshing successful franchises through new materials, collaborations and locally developed products rather than relying on a single design cycle.
Brands therefore need to maintain product freshness without creating excessive inventory. PUMA’s current restructuring, which includes reducing the number of new product items launched each season and managing excess stock more tightly, demonstrates the operational risk created when assortment complexity moves ahead of demand.
Promotional Activity Can Reduce Brand and Retail Margins
The market contains a large number of global brands, fashion retailers and digital-first specialists competing across similar product types. Discounting becomes particularly aggressive when inventories rise or trends change, reducing gross margins and weakening full-price positioning.
adidas has continued to emphasize disciplined wholesale sell-in and full-price sales despite an overall promotional marketplace, while PUMA is actively reducing inventory following its 2025 reset. These actions show that revenue growth alone does not determine category economics; inventory quality and the ability to maintain full-price selling remain important through 2031.
Sustainability Requirements Increase Material and Supply-Chain Complexity
Athleisure relies heavily on polyester, nylon and blended synthetic textiles because these materials provide stretch, durability and moisture management. Brands are under increasing pressure to reduce virgin-material use, improve recyclability and provide greater supply-chain traceability, but technical garments can be difficult to recycle because they combine fibres, elastane, coatings and trims.
Alternative materials and recycled content can reduce dependence on virgin synthetics but may increase sourcing complexity or production cost. Material innovation therefore creates product differentiation while also increasing development and compliance requirements.
Counterfeit and Low-Cost Competition Affects Branded Products
The combination of recognizable logos, repeatable silhouettes and strong online demand makes athleisure vulnerable to counterfeit and imitation products. Premium sneakers, leggings, hoodies and sports-inspired fashion are particularly exposed when consumers can purchase similar-looking products through online marketplaces at significantly lower prices.
Global brands retain advantages in product technology, endorsement, distribution and brand recognition, but low-cost competition places pressure on entry-level pricing and increases the importance of direct consumer relationships.
Athleisure Market Segmentation Analysis
By Product Type
Top Wear
Top Wear accounts for approximately USD 179.09 billion, or 38% of market value, in 2026. T-shirts and hoodies remain widely used across both active and casual settings because they require little behavioural change from conventional everyday clothing. The segment is projected to reach approximately USD 247.68 billion by 2031, although its share moderates to around 37% as footwear grows slightly faster.
T-shirts account for approximately 18% of the total market in 2026 and remain the largest individual top-wear category. Hoodies represent approximately 11%, supported by year-round casual use and continued overlap between athletic and streetwear styling. Other top-wear products include jackets, sports bras, sweatshirts and related performance-lifestyle garments.
Bottom Wear
Bottom Wear represents approximately USD 136.68 billion, or 29% of the market, in 2026 and maintains broadly the same share through 2031. The category includes joggers, leggings and shorts, with performance attributes such as stretch, moisture management and fit remaining important even when products are used primarily for casual wear.
Leggings are the fastest-growing bottom-wear category and increase from approximately 12% of market value in 2026 to 13% by 2031. Joggers continue to grow in absolute value but lose modest share as demand normalizes after several years of strong casualwear adoption. Shorts maintain approximately 7% share through the forecast period.
Footwear
Footwear accounts for approximately USD 155.53 billion, or 33% of the athleisure market, in 2026 and is projected to reach around USD 227.60 billion by 2031. The segment benefits from running-derived cushioning, retro sport designs and sneakers developed specifically for lifestyle use.
adidas’ recent growth in Terrace, retro-running and lifestyle-running products illustrates how footwear platforms can move between performance heritage and fashion demand. The category increases to approximately 34% of market value by 2031 as athletic brands continue to compete for everyday footwear spending.
By Material
Polyester accounts for approximately 43% of market value in 2026 and remains the largest material category because it combines durability, moisture management and low manufacturing cost. Its share is projected to decline to around 41% by 2031 as brands increase the use of alternative blends and technical materials.
Nylon accounts for approximately 21% of the market in 2026 and increases to around 22% by 2031. Its softness, elasticity and durability make it important in premium leggings, lightweight outerwear and high-stretch products. Cotton represents approximately 26% in 2026 but grows more slowly because it lacks some of the moisture-management and stretch properties required in technical athleisure products.
Other materials increase from approximately 10% to 14% of market value through 2031. The category captures recycled fibres, engineered blends and alternative material systems being introduced as brands seek different combinations of performance, comfort and sustainability.
By Distribution Channel
Offline channels account for approximately 65% of market value in 2026 because consumers continue to use stores for footwear sizing, product trial and fit assessment. Brand stores, sporting-goods retailers and multi-brand fashion outlets also provide manufacturers with physical merchandising and product-launch visibility.
Online distribution increases from approximately 35% in 2026 to 40% by 2031. adidas reported 26% e-commerce growth during the first half of 2026, while major brands continue to invest in digital infrastructure and direct-to-consumer distribution. The channel gains share, but physical retail remains material because athleisure purchasing still involves fit and product handling.
By End-User
Women account for approximately USD 216.80 billion, or 46% of market value, in 2026 and remain the largest end-user group through 2031. Leggings, studio clothing, running apparel, sports bras, fleece products and lifestyle footwear provide a broad product base, while brands continue introducing women’s ranges designed for use beyond exercise.
Men represent approximately 42% of the market in 2026 and remain close to that level throughout the forecast period. Growth is supported by running, training, hoodies, joggers and sport-inspired footwear, while collections such as Nike 24.7 demonstrate the extension of technical materials into men’s everyday trousers and shirts.
Children account for approximately 12% of market value. The segment grows broadly in line with the overall market as athletic footwear, school-age sportswear and branded casual clothing remain common purchases.
Geographical Outlook
North America represents approximately 34% of global athleisure value in 2026 and remains the largest regional market at the beginning of the forecast period. The United States has high penetration of athletic footwear, leggings, performance clothing and direct-to-consumer sportswear brands, but market maturity results in slower growth than Asia Pacific. North America’s share moderates to approximately 31% by 2031.
Asia Pacific accounts for approximately 30% of market value in 2026 and is projected to reach around 34% by 2031. adidas reported double-digit first-half 2026 sales growth in Greater China and Japan/South Korea, while global brands are increasingly developing products and campaigns around local consumer preferences. Local companies including ANTA Sports and Li Ning also increase competitive intensity across China and other regional markets.
Europe accounts for approximately 25% of market value in 2026. Demand remains supported by strong sportswear penetration and large apparel retail markets, but slower population and consumption growth keeps the regional CAGR below the global average.
South America represents around 6% of market value and grows in line with the overall market, with Brazil providing the principal consumer base. Middle East & Africa accounts for approximately 5%, with Gulf markets supporting premium sportswear demand while broader regional growth depends on income, urbanization and organized retail development.
Recent Developments
September 2026, adidas Originals and Simone Rocha introduced a Fall/Winter 2026 collection as part of an ongoing collaboration. The launch extends the use of sportswear brands within fashion-led collections and supports continued convergence between athletic and lifestyle apparel.
July 2026, Nike introduced Studio Fleece, a women’s sportswear range covering sweatshirts, hoodies, shorts and sweatpants developed from research involving more than 300 women. The range combines comfort and performance features with clothing intended for everyday use.
July 2026, adidas introduced Originals Sport, a training range designed to bring Originals styling into performance products. The launch demonstrates the movement of lifestyle design into technical training rather than treating performance and fashion as separate portfolios.
During the second quarter of 2026, adidas reported 35% currency-neutral growth in apparel revenue, with increases across Football, Originals, Running, Training, Motorsport and other categories. Direct-to-consumer sales grew 23% during the first half, including 26% e-commerce growth.
June 2026, H&M MOVE and Solar Club launched a collection spanning technical sportswear, running apparel, swimwear, oversized T-shirts and hoodies. The range combines performance-oriented products with broader lifestyle positioning.
Summer 2026, lululemon and Saul Nash released the final SLNSH collection, combining technical mesh, perforated construction and close-to-body silhouettes with lifestyle products. The range was sold across North America, Europe and Asia Pacific.
PUMA’s 2026 product strategy continues to focus on Running, Training and Sportstyle alongside Football, with the company describing sport-inspired products as relevant both on and off the pitch. The strategy follows a 2025 reset aimed at reducing inventory and concentrating the product portfolio on fewer core categories.
Competitive Environment
The market contains global sportswear groups, specialist performance brands, fashion retailers and digital-first athleisure companies. Nike and adidas operate across footwear, apparel and lifestyle products at global scale, while lululemon has a particularly strong position in premium technical apparel. PUMA, Under Armour, ASICS and New Balance combine performance categories with lifestyle ranges, while VF Corporation and Columbia participate through outdoor and casual-performance brands.
Competition has expanded beyond traditional sportswear companies. H&M uses H&M MOVE to combine technical clothing with fashion retail, while Athleta, Alo Yoga, Vuori, Gymshark and Fabletics compete through specialist women’s, training or digitally led propositions. Asian companies including ANTA Sports and Li Ning add scale in China and increasingly participate in international sporting-goods markets.
Product cycles, brand positioning and distribution discipline remain important because athleisure demand can move quickly between silhouettes and brands. Companies with broad direct-to-consumer capability can adjust assortments and product storytelling more rapidly, but wholesale remains important for reach. adidas’ 2026 results demonstrate that strong DTC growth can coexist with expanding wholesale sales when product demand remains high.
Athleisure Market Scope:
Report Metric
Details
Total Market Size in 2026
USD 471.3 billion
Total Market Size in 2031
USD 669.4 billion
Forecast Unit
Billion
Growth Rate
7.27%
Study Period
2021 to 2031
Historical Data
2021 to 2024
Base Year
2025
Forecast Period
2026 – 2031
Segmentation
Product Type, Material, Distribution Channel, End-User, Geography
Companies
Nike Inc.
adidas AG
lululemon athletica inc.
PUMA SE
Under Armour Inc.
Market Segmentation
By Product Type
Top Wear
T-Shirts
Hoodies
Others
Bottom Wear
Joggers
Leggings
Shorts
Footwear
By Material
Polyester
Nylon
Cotton
Others
By Distribution Channel
Online
Offline
By End-User
Men
Women
Children
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Spain
Others
Middle East & Africa
Saudi Arabia
UAE
Israel
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Taiwan
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Increasing Use of Athletic Apparel and Footwear as Everyday Clothing
3.1.2. Wider Application of Performance Materials in Lifestyle Products
3.1.3. Continued Convergence of Athletic Footwear and Casual Fashion
3.1.4. Expansion of Direct-to-Consumer and E-Commerce Distribution
3.1.5. Growth of Women's Technical and Lifestyle Sportswear
3.2. Market Restraints
3.2.1. Consumer Spending Pressure on Premium Apparel and Footwear
3.2.2. Shorter Fashion Cycles and Higher Inventory Risk
3.2.3. Promotional Activity and Margin Pressure Across Sportswear Retail
3.2.4. Material Sustainability and Supply-Chain Compliance Costs
3.2.5. Counterfeit and Low-Cost Competition in Branded Athleisure
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Sustainable Materials and Circular Fashion Trends
4.2. Smart Fabrics and Performance Textile Innovations
5. GLOBAL ATHLEISURE MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Top Wear
5.2.1. T-Shirts
5.2.2. Hoodies
5.2.3. Others
5.3. Bottom Wear
5.3.1. Joggers
5.3.2. Leggings
5.3.3. Shorts
5.4. Footwear
6. GLOBAL ATHLEISURE MARKET BY MATERIAL
6.1. Introduction
6.2. Polyester
6.3. Nylon
6.4. Cotton
6.5. Others
7. GLOBAL ATHLEISURE MARKET BY DISTRIBUTION CHANNEL
7.1. Introduction
7.2. Online
7.3. Offline
8. GLOBAL ATHLEISURE MARKET BY END-USER
8.1. Introduction
8.2. Men
8.3. Women
8.4. Children
9. GLOBAL ATHLEISURE MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. By Product Type
9.2.2. By Material
9.2.3. By Distribution Channel
9.2.4. By End-User
9.2.5. By Country
9.2.5.1. United States
9.2.5.2. Canada
9.2.5.3. Mexico
9.3. South America
9.3.1. By Product Type
9.3.2. By Material
9.3.3. By Distribution Channel
9.3.4. By End-User
9.3.5. By Country
9.3.5.1. Brazil
9.3.5.2. Argentina
9.3.5.3. Others
9.4. Europe
9.4.1. By Product Type
9.4.2. By Material
9.4.3. By Distribution Channel
9.4.4. By End-User
9.4.5. By Country
9.4.5.1. Germany
9.4.5.2. France
9.4.5.3. United Kingdom
9.4.5.4. Italy
9.4.5.5. Spain
9.4.5.6. Others
9.5. Middle East & Africa
9.5.1. By Product Type
9.5.2. By Material
9.5.3. By Distribution Channel
9.5.4. By End-User
9.5.5. By Country
9.5.5.1. Saudi Arabia
9.5.5.2. UAE
9.5.5.3. Israel
9.5.5.4. Others
9.6. Asia Pacific
9.6.1. By Product Type
9.6.2. By Material
9.6.3. By Distribution Channel
9.6.4. By End-User
9.6.5. By Country
9.6.5.1. China
9.6.5.2. India
9.6.5.3. Japan
9.6.5.4. South Korea
9.6.5.5. Indonesia
9.6.5.6. Thailand
9.6.5.7. Taiwan
9.6.5.8. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
The Athleisure market is forecast to grow at a Compound Annual Growth Rate (CAGR) of 7.27%. This growth will see the market expand from USD 471.3 billion in 2026 to an estimated USD 669.4 billion by 2031, driven by the continued integration of athletic apparel into daily consumer lifestyles.
Top Wear accounts for approximately 38% of market value in 2026, making it the largest product group. Footwear is projected to increase its share from 33% to 34% by 2031, supported by sport-inspired sneakers. Leggings are a significant growth segment, projected to grow at approximately 9.0% annually, while women remain the largest end-user segment, representing about 46% of market value in 2026.
Asia Pacific is projected to be a key region for growth, increasing its share from approximately 30% of global market value in 2026 to 34% by 2031. This expansion is primarily supported by rising sportswear consumption and robust local-market product development within the region.
Major sportswear companies, including adidas and PUMA, are treating the overlap between performance and lifestyle as a core product category, with adidas reporting double-digit growth in its Lifestyle revenues in 2025. Brands like Nike and lululemon are developing collections that combine technical materials and performance features with designs for daily wear, blurring the distinction between performance wear and casual clothing.
Online distribution is set to significantly increase its market share within the athleisure sector. It accounted for approximately 35% of sales in 2026 and is projected to reach around 40% by 2031, indicating a growing importance of e-commerce channels for product distribution.
The market's growth is increasingly linked to the widespread use of sportswear for everyday activities such as travel, commuting, and casual wear, rather than solely formal exercise. This shift reflects a consumer preference for comfort and versatility, driving brands to develop products that seamlessly combine performance innovation with fashion cycles for daily use.