Global Commercial Fitness Equipment Market - Strategic Insights and Forecasts (2026-2031)
Commercial Fitness Equipment Market Size, Growth & Trends By Equipment Type (Cardio Equipment, Strength Training Equipment, Bodyweight and Functional Training Equipment, Gymnastics and Specialty Training Equipment, Others), Distribution Channel (Direct Sales to Commercial Facilities, Distributors and Wholesalers, Specialty Fitness Dealers, Online and Digital Sales, Others), and Geography
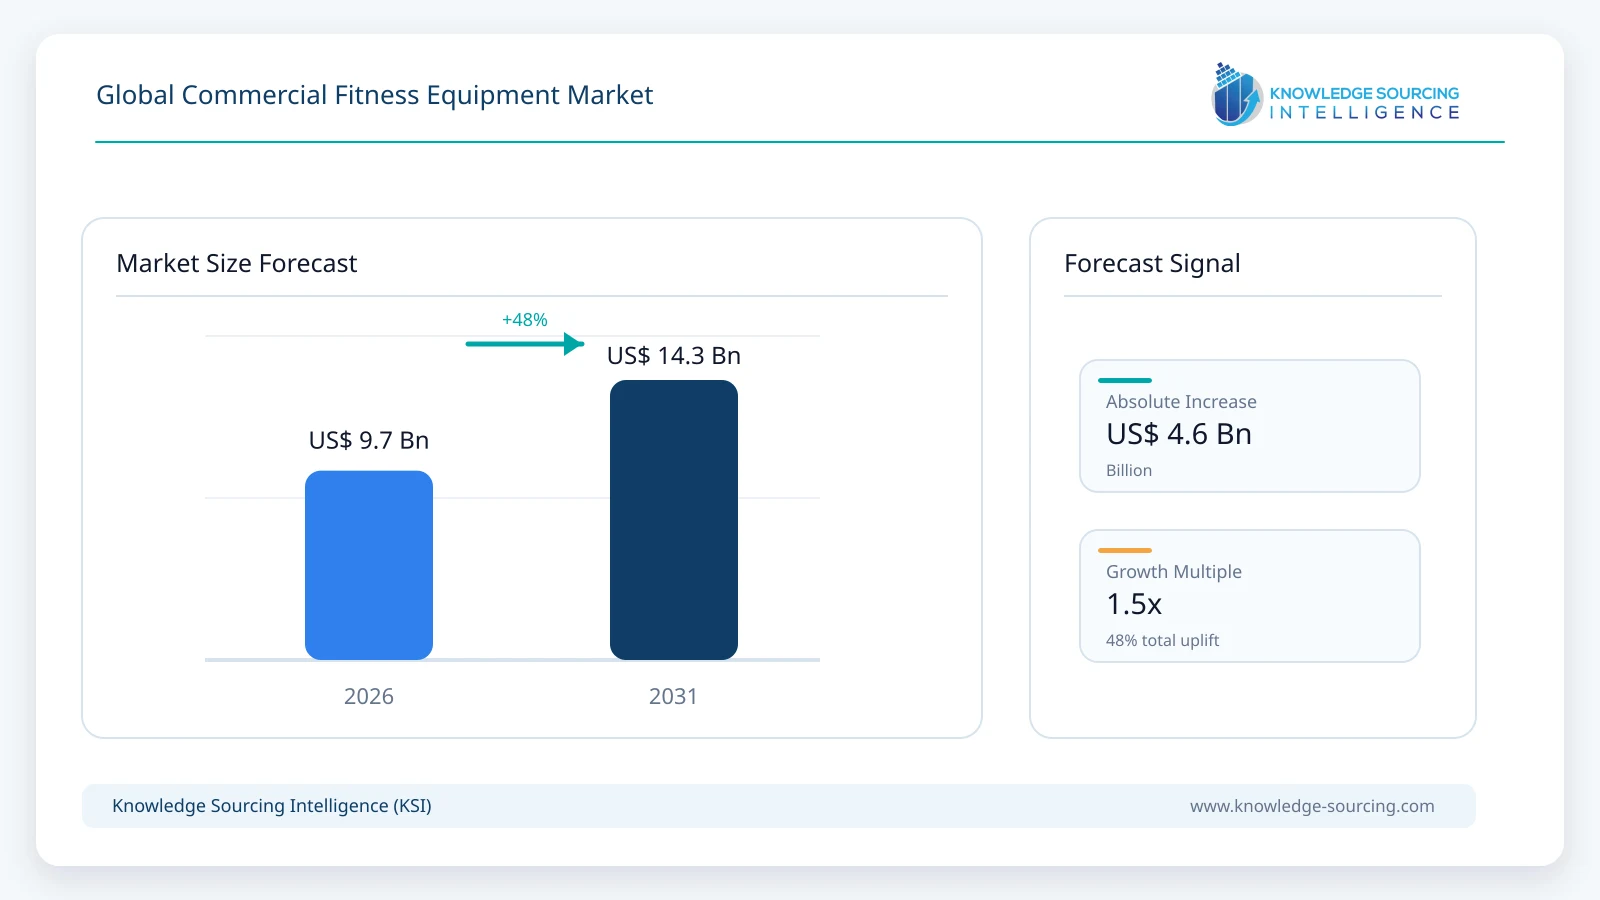
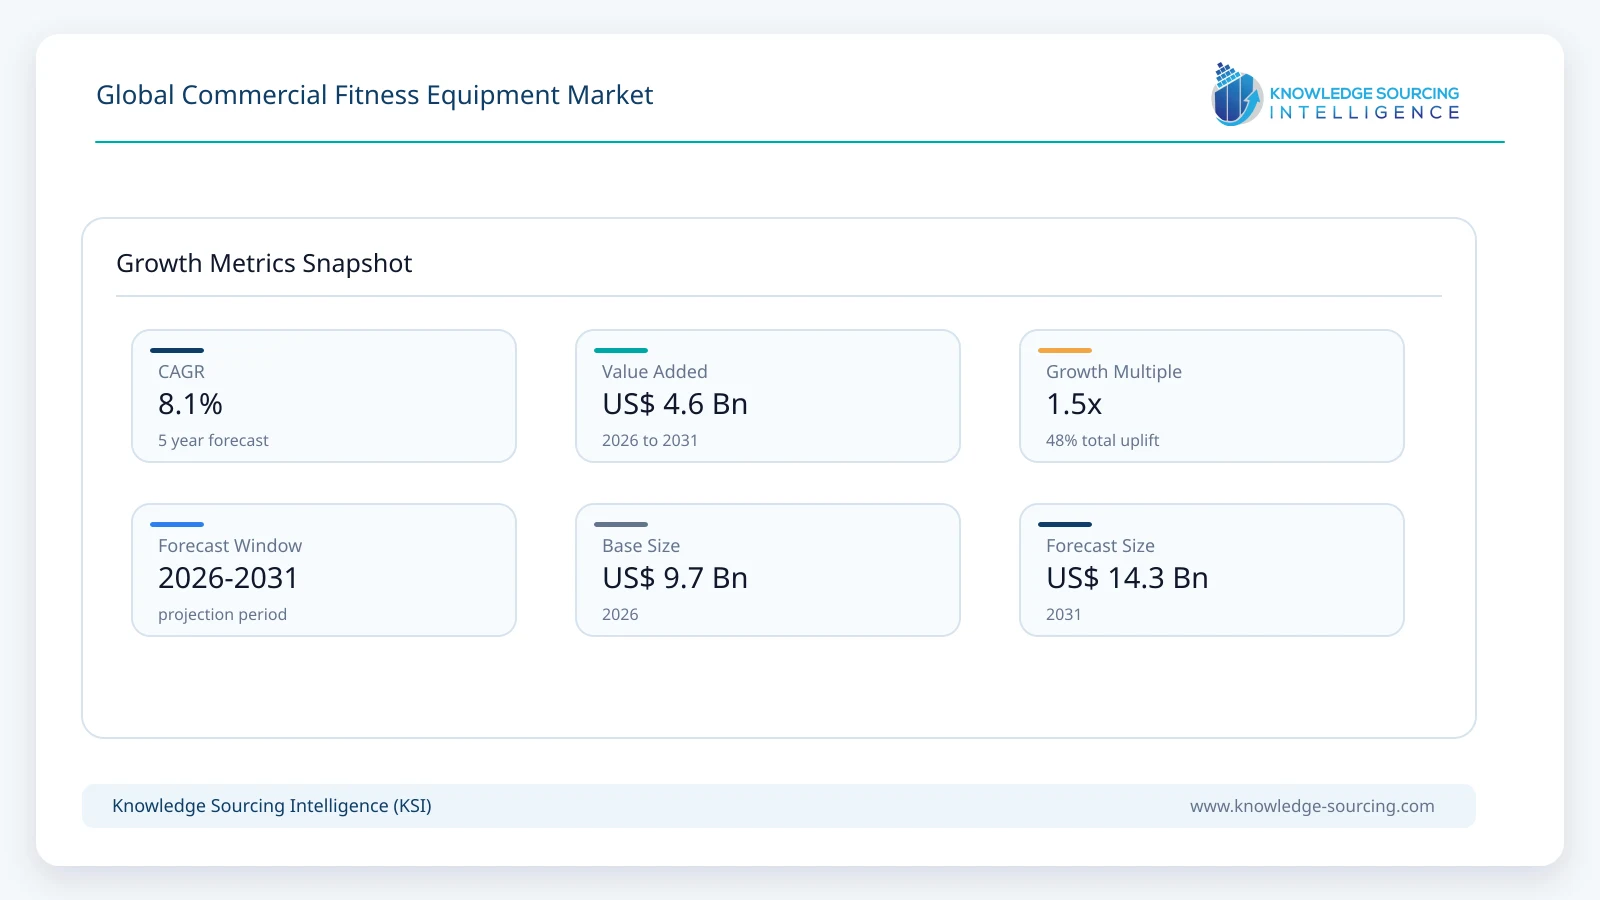
The global commercial fitness equipment market is forecast to grow from USD 9.65 billion in 2026 to USD 14.27 billion in 2031, representing a CAGR of 8.14% during the forecast period.
Highlights:
1
Cardio equipment is expected to remain the largest equipment category, accounting for approximately 43.0% of global commercial fitness equipment revenue in 2026.
2
Direct sales to commercial facilities are estimated to represent approximately 52.0% of 2026 market revenue, reflecting the importance of project-based procurement, facility planning, installation and after-sales service.
3
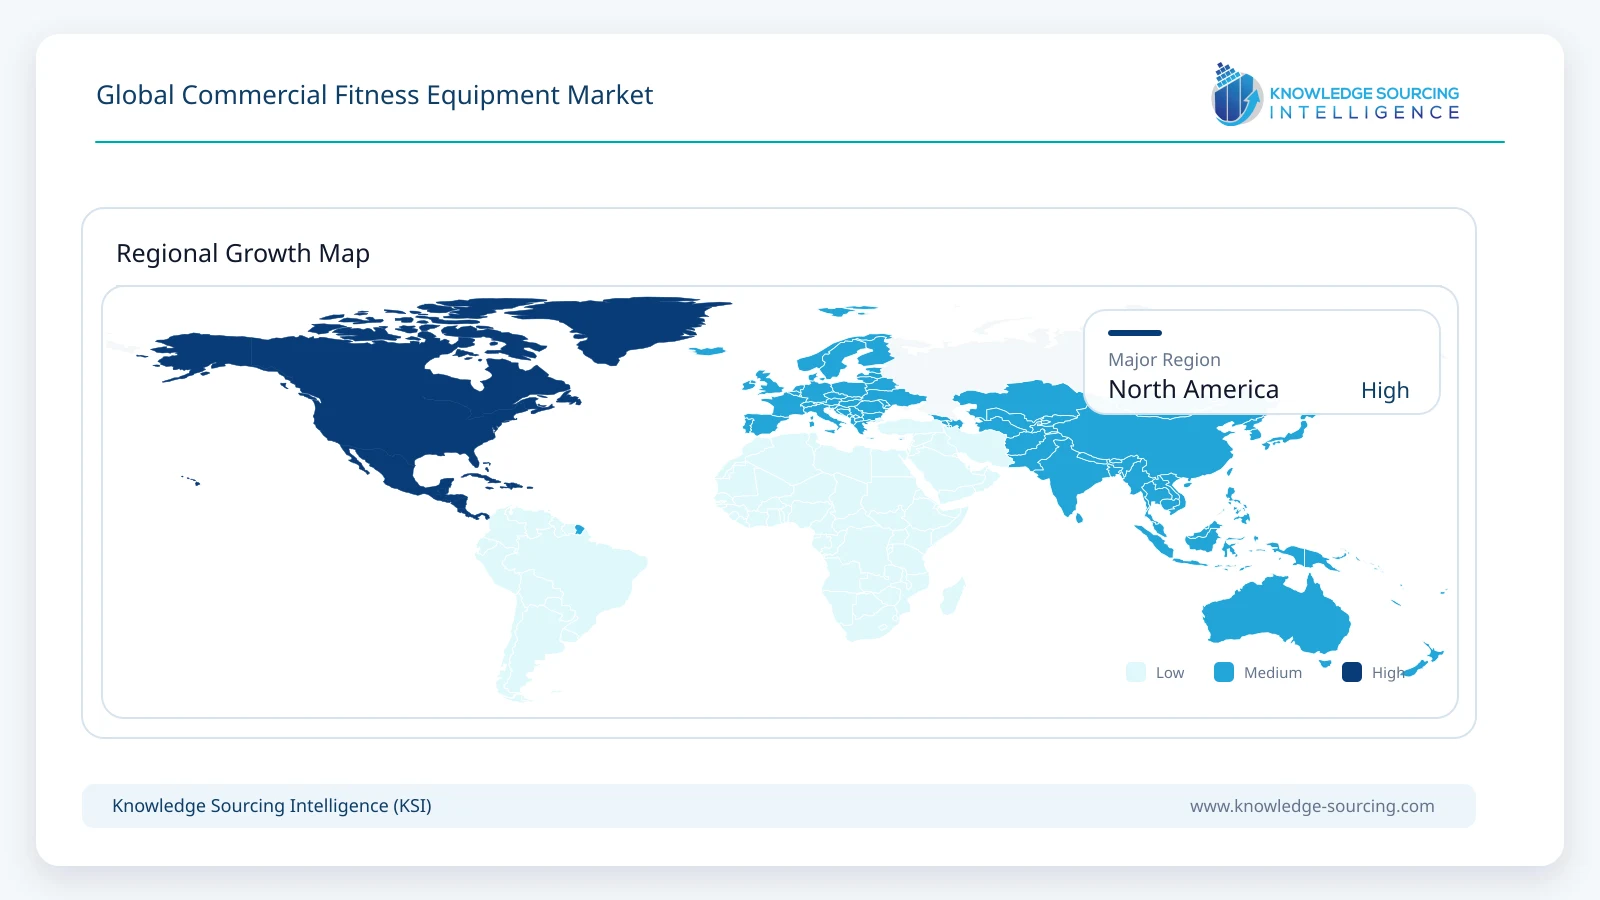
North America is estimated to account for approximately 35.0% of global commercial fitness equipment revenue in 2026, supported by a large installed base of health clubs, studios, recreation centers and fitness amenities.
4
Commercial operators are shifting equipment budgets toward integrated strength zones, connected cardio, asset-management software and more flexible training formats rather than replacing like-for-like equipment.
5
Strength-oriented training continues to gain space on commercial gym floors, encouraging suppliers to expand plate-loaded, selectorized, cable and functional-training portfolios alongside cardio equipment.
6
Product development in 2026 is increasingly focused on high-use durability, connected experiences, accessibility, facility management and equipment designed for hospitality, multi-housing and institutional fitness settings.
Market Overview
Commercial fitness equipment includes cardio, strength, bodyweight, functional and related exercise systems designed for repeated use in health clubs, fitness centers, hotels, residential amenity spaces, corporate wellness facilities, education, sports performance and rehabilitation settings. Commercial systems differ from home equipment through heavier-duty frames, higher duty cycles, serviceability, operator-focused warranties, facility management requirements and greater emphasis on uptime.
The market is benefiting from continued growth in structured fitness participation and from a broader definition of where commercial exercise takes place. Health clubs remain the largest source of demand, but hotels, multi-family developments, universities, municipal recreation facilities and corporate wellness environments are increasingly specifying professional equipment as a standard amenity. This broadening of the customer base is reducing dependence on any single club format.
The United States illustrates the depth of facility-based demand. The Health & Fitness Association reported that 77 million Americans belonged to a gym, studio or other fitness facility in 2024, while nearly 96 million people used such facilities when non-members were included. Higher utilization increases wear and replacement requirements while also encouraging operators to refresh floors with newer strength, cardio and connected products.
Supplier performance also indicates continued commercial demand. Technogym exceeded EUR 1.0 billion in consolidated revenue in 2025 and reported double-digit growth in its B2B business during the first quarter of 2026. Johnson Health Tech reported 2025 revenue of TWD 54.33 billion across its fitness and wellness portfolio, while Peloton reported double-digit year-on-year growth in its Commercial Business Unit during fiscal 2026. These signals support a market characterized by replacement cycles, new facility openings and higher-value technology content.
The competitive model is changing from the sale of individual machines toward integrated facility solutions. Major suppliers combine hardware with floor planning, digital consoles, workout content, connectivity, preventive maintenance and asset-management tools. This creates opportunities for higher recurring service revenue and also raises customer expectations regarding interoperability, equipment uptime and long-term support.
Commercial Fitness Equipment Market Trends
Strength Training Gains a Larger Share of the Fitness Floor
Commercial facilities are reallocating space toward selectorized strength, plate-loaded equipment, cable systems, racks and functional training. The shift reflects demand from younger members, athletic-performance users and general consumers who increasingly combine resistance training with cardio rather than treating strength as a specialist activity.
Manufacturers are responding with wider strength portfolios and products designed to increase exercise variety per square meter. Life Fitness and Hammer Strength have expanded plate-loaded and cable offerings, while specialist suppliers such as Panatta, gym80, Keiser and Core Health & Fitness continue to deepen strength-focused ranges. For operators, the commercial value comes from member engagement, lower mechanical complexity in many strength products and the ability to create differentiated training zones.
Connected fitness in commercial environments is moving beyond entertainment screens. Operators increasingly expect equipment to support user login, workout tracking, preventive maintenance, utilization analytics and integration with broader digital membership experiences. This changes the value proposition from a standalone machine to a managed equipment fleet.
Life Fitness has continued to develop its Facility Connect ecosystem, Precor and Peloton are combining commercial engineering with connected content, and Freemotion integrates iFIT content directly into commercial cardio and strength equipment. The competitive advantage increasingly depends on how hardware, software and service work together across the life of the installation.
Commercial Fitness Expands Beyond Traditional Health Clubs
Hospitality, multi-housing, corporate wellness, campus recreation and medical-wellness facilities are becoming more important commercial customers. These environments often require compact footprints, intuitive interfaces, lower staffing requirements and equipment that can serve users with widely different fitness experience.
Suppliers are adapting product architecture accordingly. Life Fitness introduced the Atmos cardio line for hospitality and multi-unit housing, while the Precor and Peloton commercial combination is targeting both high-use gym floors and lighter-use hospitality, residential and corporate environments. The result is a more segmented commercial market in which product durability, footprint and digital functionality are matched to the specific operating environment.
Market Segmentation by Equipment Type
Cardio Equipment
Cardio equipment is estimated at approximately USD 4.15 billion in 2026. The category includes commercial treadmills, exercise bikes, ellipticals, climbers, rowers and other endurance-training systems installed across health clubs and institutional fitness environments.
The segment benefits from broad user familiarity, high utilization and continued replacement demand. Commercial cardio is also one of the areas where digital functionality is most visible, including connected consoles, entertainment, workout programming, asset monitoring and integration with member applications. New product development is increasingly focused on combining these features with lower maintenance requirements and improved biomechanics.
Treadmills and bikes remain core fixtures, but the cardio mix is becoming more diverse as operators add climbers, rowers and specialty products to reduce floor repetition. High-use facilities also place strong emphasis on serviceability because downtime directly affects member experience. This favors suppliers with established service networks and remote diagnostics capabilities.
Market Segmentation by Distribution Channel
Direct Sales to Commercial Facilities
Direct sales to commercial facilities are estimated at approximately USD 5.02 billion in 2026. This channel includes manufacturer-led sales to health clubs, hotel groups, universities, corporate facilities, developers and other institutional buyers where equipment procurement is frequently tied to facility design, installation and multi-year service requirements.
Direct engagement is particularly important for large installations because customers require space planning, equipment mix optimization, financing, logistics, installation, staff training and after-sales support. Commercial operators also increasingly evaluate suppliers on fleet-management capability and service response, making the relationship broader than a one-time hardware purchase.
Distributors and specialty dealers remain important in fragmented regional markets, but leading manufacturers continue to strengthen direct account management for strategic customers. This allows suppliers to participate in replacement cycles, expansions and new-site rollouts while maintaining visibility into product utilization and future procurement needs.
Market Drivers
Growth in Fitness Facility Participation and Utilization
Rising participation in gyms, studios and other fitness facilities increases both the installed equipment base and the utilization intensity of existing machines. Higher traffic accelerates wear, raises maintenance requirements and shortens practical replacement cycles for high-use equipment.
The record level of U.S. facility participation reported by the Health & Fitness Association demonstrates continued demand for structured exercise environments. Similar trends in urban centers across Europe, Asia Pacific and the Middle East are supporting new clubs and higher-specification fitness amenities.
Strength Training and Functional Fitness Adoption
Resistance training is becoming more central to mainstream fitness programs. Commercial operators are responding by increasing the share of floor space allocated to strength, cable, rack and functional systems.
This supports demand for both large multi-station installations and compact systems that increase exercise variety in constrained spaces. Strength equipment also provides suppliers with opportunities to serve health clubs, athletic-performance centers, education and rehabilitation settings using differentiated product families.
Replacement and Modernization of Installed Equipment
Commercial equipment has finite service lives because of intensive daily use, mechanical wear, console obsolescence and changing member expectations. Replacement spending therefore creates a recurring demand base even in mature facility markets.
Modernization is increasingly driven by both physical condition and digital capability. Operators may replace functional equipment earlier when newer systems improve engagement, energy efficiency, maintenance visibility or compatibility with digital membership platforms.
Expansion of Fitness Amenities in Hospitality and Real Estate
Fitness rooms are increasingly treated as a competitive amenity in hotels, premium residential developments and multi-family properties. Corporate campuses and universities are also investing in wellness infrastructure to support employee and student experience.
These buyers favor equipment designed for unattended or lightly supervised use, compact footprints and simple maintenance. The expansion of these non-club channels increases the addressable market for commercial-grade products beyond traditional membership gyms.
Technology-Enabled Facility Management
Connected equipment can provide operators with usage data, service alerts and fleet-level visibility. This supports preventive maintenance and helps facilities understand which machines are under- or over-utilized.
As digital tools become integrated into procurement decisions, manufacturers with connected ecosystems can differentiate on total operating value rather than only equipment specifications. This encourages higher software content and supports deeper customer relationships.
Market Restraints
High Upfront Capital Cost
Commercial-grade treadmills, strength systems and connected equipment require materially higher investment than consumer products. Large club openings or complete equipment refreshes can therefore require significant capital commitments.
Smaller independent facilities may extend replacement cycles or use refurbished equipment when financing costs are high. This can moderate new-equipment demand during periods of weaker consumer spending or tighter credit conditions.
Long Replacement Cycles for Durable Equipment
Commercial fitness products are designed for repeated use over several years. Durable frames and serviceable components are important selling points, but they also mean that a substantial portion of the installed base does not require annual replacement.
Suppliers therefore depend on a combination of new facility openings, floor redesigns, technology upgrades and scheduled replacement programs rather than simple annual unit turnover.
Competition from Low-Cost and Refurbished Equipment
The market contains a broad range of equipment quality and price points. Used and professionally refurbished products can meet the needs of budget-sensitive operators, especially for mechanically simple strength equipment.
Lower-cost manufacturers also compete aggressively in emerging markets. Premium suppliers must justify higher pricing through durability, biomechanics, service coverage, brand reputation, digital capability and lower lifetime operating cost.
Service and Maintenance Complexity
Connected consoles, motorized systems and sophisticated mechanical assemblies can increase maintenance requirements. Commercial buyers place strong value on uptime because unavailable equipment is immediately visible to members.
Manufacturers need dependable parts availability, technician networks and remote support. Weak service coverage can limit market penetration even when product specifications are competitive.
Facility Economics and Membership Volatility
Equipment purchases are linked to the financial health of fitness operators. Membership pressure, rent increases, wage costs or changes in consumer spending can delay capital expenditure.
Large chains may continue expansion during weaker cycles, but smaller facilities often prioritize cash preservation. This makes commercial equipment demand more cyclical than consumer interest in fitness alone would suggest.
Regional Outlook
North America
North America is estimated at approximately USD 3.38 billion in 2026. The region has a large installed base of health clubs, studios, college recreation centers, hotels, corporate fitness facilities and residential amenity gyms, creating recurring demand for replacement and modernization.
The United States remains the core regional market. High facility participation, dense commercial gym networks and strong adoption of both cardio and strength equipment support demand. The region is also an important testing ground for connected fitness, low-cost gym formats and premium clubs, resulting in a wide range of equipment specifications and price points.
Supplier investment remains active. Precor and Peloton introduced an integrated Commercial Business Unit in 2026, while Life Fitness continued to expand commercial cardio and strength solutions. North American buyers increasingly emphasize connected fleet management, serviceability and space efficiency alongside traditional durability.
Competitive Landscape
The market combines global full-line suppliers, specialist strength manufacturers, connected-fitness companies and regional equipment producers. Technogym, Life Fitness / Hammer Strength, Johnson Health Tech, Precor / Peloton and Core Health & Fitness compete across multiple facility categories, while companies such as TRUE Fitness, Keiser, Panatta, gym80 and SportsArt maintain strong positions in selected product segments and regions.
Competition increasingly centers on breadth of portfolio, biomechanics, durability, digital integration and service coverage. Full-line suppliers can offer cardio, strength, connected software and facility planning under a single commercial relationship. Specialist manufacturers compete through distinctive movement patterns, strength engineering, customization or niche market expertise.
The importance of software and content is increasing but hardware reliability remains fundamental. Commercial customers evaluate lifecycle cost, maintenance response, parts availability and equipment uptime because these factors affect member satisfaction and operating economics. As a result, suppliers with strong after-sales infrastructure retain an advantage in large multi-site accounts.
Recent Developments
August 2026: Technogym continued to report strong commercial momentum following double-digit B2B growth in the first quarter of 2026, reinforcing demand for premium equipment and connected wellness solutions across multiple regions.
March 2026: Precor and Peloton presented their integrated Commercial Business Unit at HFA and FIBO 2026. The combined offer brings Precor commercial engineering together with Peloton connected fitness, including new products designed for high-use commercial gym environments.
March 2026: Life Fitness / Hammer Strength announced an exclusive U.S. partnership with Merrithew to add premium Pilates equipment and studio solutions to its commercial portfolio across health clubs, hospitality, corporate wellness and institutional markets.
February 2026: Life Fitness / Hammer Strength showcased integrated commercial solutions at HFA 2026, including new cardio, strength and connected products developed for operator requirements such as space efficiency, member engagement and durability.
January 2026: Life Fitness / Hammer Strength opened the Nieto-Jones Innovation Center in Illinois, bringing mechanical, electrical, software, quality and reliability teams together to accelerate commercial fitness product development.
Market Outlook
Commercial fitness equipment demand is expected to remain structurally positive through 2031 as facility participation, strength training, replacement cycles and non-traditional fitness locations expand the installed base. Growth is likely to be strongest for suppliers that can combine durable hardware with connected services, facility planning and responsive after-sales support.
The market is also becoming more segmented by operating environment. High-volume health clubs require exceptional durability and serviceability, while hospitality and multi-housing customers prioritize compact footprints, intuitive interfaces and attractive design. Athletic-performance and strength-focused facilities demand specialized biomechanics and heavy-duty systems.
Over the forecast period, the distinction between equipment and digital service is expected to narrow. Operators increasingly purchase an integrated fitness-floor experience rather than isolated machines. Manufacturers able to support hardware, software, data and service across the equipment lifecycle are positioned to capture a larger share of commercial investment.
Global Commercial Fitness Equipment Market Scope:
Report Metric
Details
Total Market Size in 2026
USD 9.65 billion
Total Market Size in 2031
USD 14.27 billion
Forecast Unit
Billion
Growth Rate
8.14%
Study Period
2021 to 2031
Historical Data
2021 to 2024
Base Year
2025
Forecast Period
2026 – 2031
Segmentation
Equipment Type, Distribution Channel, Geography
Companies
Technogym S.p.A.
Life Fitness / Hammer Strength
Johnson Health Tech Co. Ltd. (Matrix Fitness)
Peloton Interactive Inc. / Precor
Core Health & Fitness
Market Segmentation
By Equipment Type
Cardio Equipment
Strength Training Equipment
Bodyweight and Functional Training Equipment
Gymnastics and Specialty Training Equipment
Others
By Distribution Channel
Direct Sales to Commercial Facilities
Distributors and Wholesalers
Specialty Fitness Dealers
Online and Digital Sales
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Australia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Validation
2.4. Market Estimation and Forecasting
2.5. Data Triangulation and Quality Control
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
3.3. Major Market Opportunities
3.4. Segment and Regional Summary
3.5. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Growth in Fitness Facility Participation and Utilization
4.1.2. Strength Training and Functional Fitness Adoption
4.1.3. Replacement and Modernization of Installed Equipment
4.1.4. Expansion of Fitness Amenities in Hospitality and Real Estate
4.1.5. Technology-Enabled Facility Management
4.2. Market Restraints
4.2.1. High Upfront Capital Cost
4.2.2. Long Replacement Cycles for Durable Equipment
4.2.3. Competition from Low-Cost and Refurbished Equipment
4.2.4. Service and Maintenance Complexity
4.2.5. Facility Economics and Membership Volatility
4.3. Porter’s Five Forces Analysis
4.4. Industry Value Chain Analysis
5. GLOBAL COMMERCIAL FITNESS EQUIPMENT MARKET BY EQUIPMENT TYPE
5.1. Introduction
5.2. Cardio Equipment
5.3. Strength Training Equipment
5.4. Bodyweight and Functional Training Equipment
5.5. Gymnastics and Specialty Training Equipment
5.6. Others
6. GLOBAL COMMERCIAL FITNESS EQUIPMENT MARKET BY DISTRIBUTION CHANNEL
6.1. Introduction
6.2. Direct Sales to Commercial Facilities
6.3. Distributors and Wholesalers
6.4. Specialty Fitness Dealers
6.5. Online and Digital Sales
6.6. Others
7. GLOBAL COMMERCIAL FITNESS EQUIPMENT MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. United States
7.2.2. Canada
7.2.3. Mexico
7.3. South America
7.3.1. Brazil
7.3.2. Argentina
7.3.3. Others
7.4. Europe
7.4.1. United Kingdom
7.4.2. Germany
7.4.3. France
7.4.4. Italy
7.4.5. Spain
7.4.6. Others
7.5. Middle East and Africa
7.5.1. Saudi Arabia
7.5.2. UAE
7.5.3. South Africa
7.5.4. Others
7.6. Asia Pacific
7.6.1. China
7.6.2. Japan
7.6.3. India
7.6.4. South Korea
7.6.5. Australia
7.6.6. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Product Portfolio and Technology Positioning
8.3. Distribution and Service Networks
8.4. Mergers, Acquisitions, Agreements and Partnerships
8.5. Competitive Dashboard
9. COMPANY PROFILES
9.1. Technogym S.p.A.
9.2. Life Fitness / Hammer Strength
9.3. Johnson Health Tech Co., Ltd. (Matrix Fitness)