
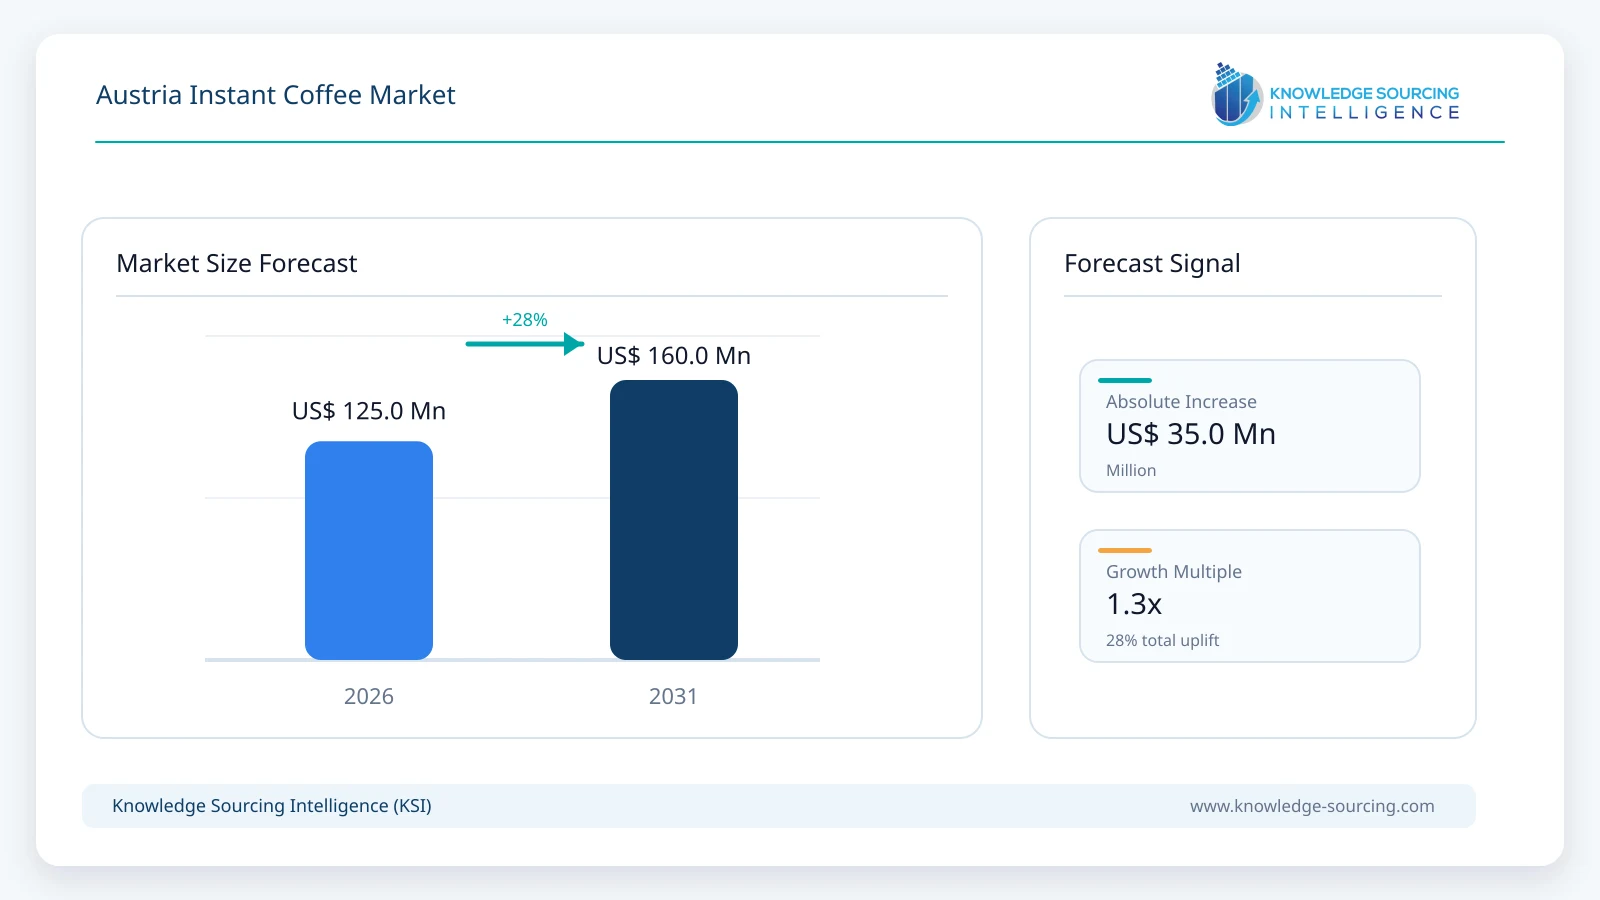
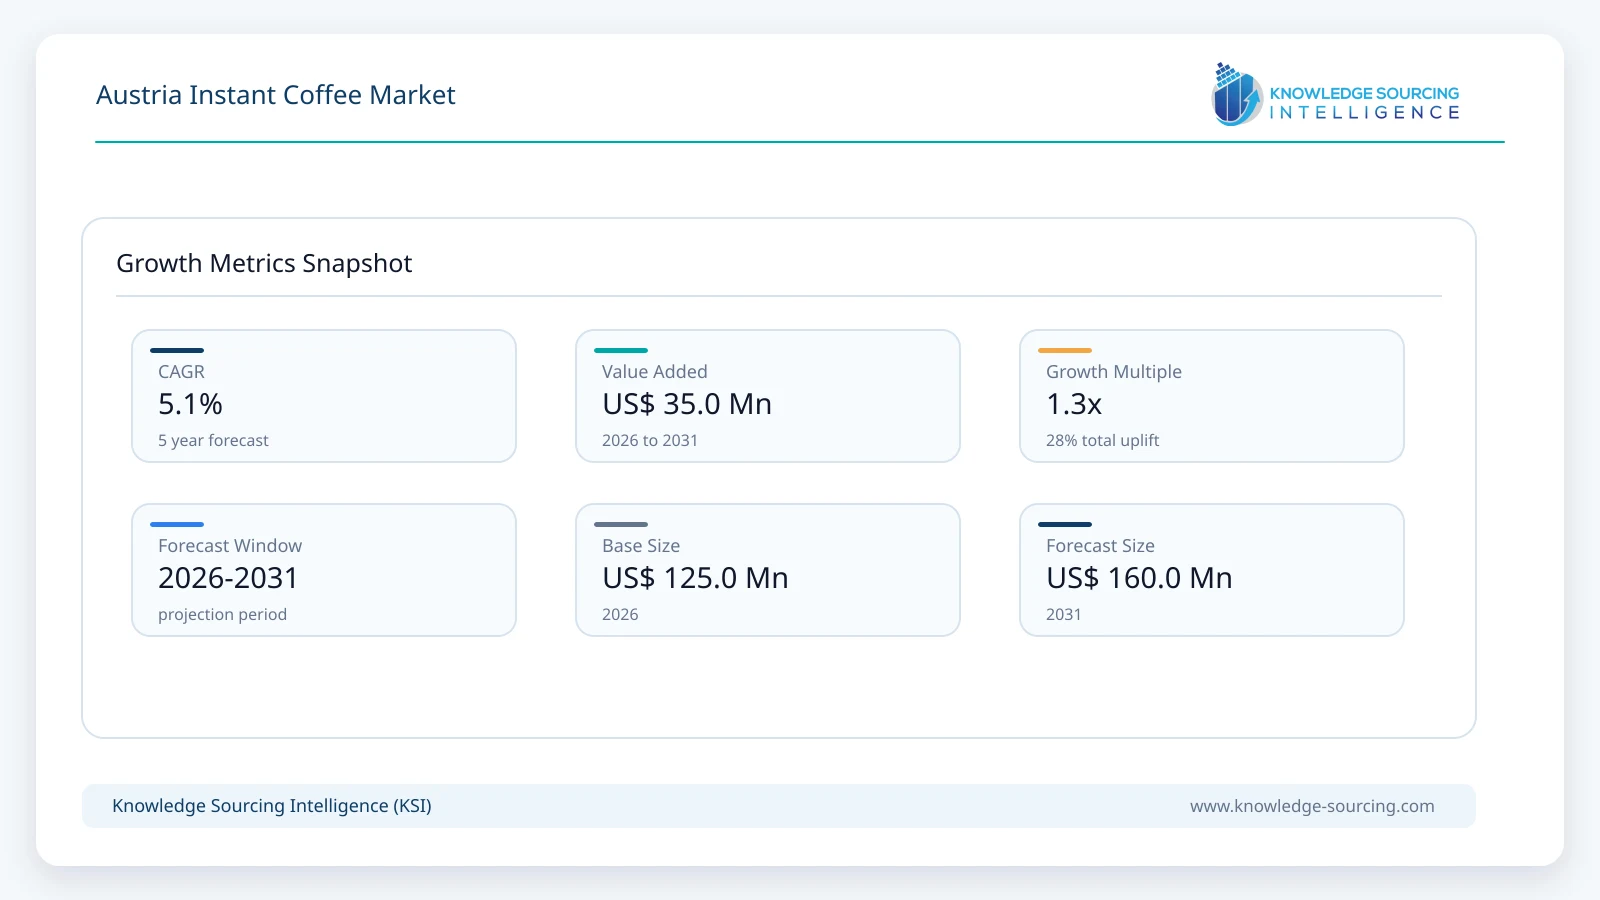
The Austria Instant Coffee Market is expected to grow at a CAGR of 5.06%, reaching USD 160.0 million in 2031 from USD 125.0 million in 2026.
Highlights:
- 1Freeze-dried coffee accounts for an estimated 52% of market value in 2026.
- 2Grocery retail remains the principal route to consumers, supported by familiar brands.
- 3Cold-soluble formulations are extending usage beyond traditional hot coffee preparation.
- 4Online sales are gaining relevance for repeat purchases and multipack formats.
- 5Vienna remains the largest individual city market, while Graz offers faster growth.
Instant coffee in Austria covers soluble coffee granules, powders and related coffee-based instant preparations sold through retail, online channels and foodservice. Freeze-dried and spray-dried products differ in texture, production cost and perceived aroma retention, while the purchase decision depends on taste, convenience, portion format and price per prepared cup. Ready-to-drink coffee, capsules, roasted beans and ground coffee are distinct markets and are not included in the category’s revenue.
Retail shelves carry global soluble-coffee brands alongside retailer-specific ranges, and much of the value chain is connected to European manufacturing networks rather than domestic coffee growing. Coffee price inflation during 2025 raised the value of Austrian coffee sales, but higher shelf prices should not be confused with equivalent growth in physical consumption. Future demand is therefore shaped by the balance between household affordability, premium freeze-dried formats and convenient new uses for soluble coffee.
Market Overview
Austrian consumers encounter soluble coffee mainly as an easy-to-store alternative to brewed coffee. Its appeal is strongest in households seeking speed, occasional coffee drinkers, workplaces, and situations without espresso equipment. Retail price comparisons are consequently made across coffee formats rather than only between instant brands. A jar may carry a relatively high price per kilogram yet yield numerous portions, making the cost per cup a more relevant purchasing measure for some households. Quality expectations are nevertheless substantial in Austria, where freshly prepared coffee remains integral to consumer habits.
Commercial product differentiation is visible in established instant portfolios. Nescafé Classic and Gold support broad availability, Jacobs Krönung supplies a recognisable premium soluble offering, and Dallmayr sells Gold and Crema Gold instant products through its Austrian-facing portfolio. Freeze-drying can protect some volatile aroma characteristics better than lower-cost alternatives, although ingredient quality, extraction and reconstitution also influence taste. These differences matter as manufacturers seek to hold branded shelf space against private labels without relying on promotional discounts alone.
Trade and price evidence points to a market influenced by international supply conditions. Austrian imports under the broader coffee-extracts and preparations tariff group increased in value between 2024 and 2025 even as the recorded quantity fell; the classification includes products beyond finished retail instant coffee. Statistics Austria separately reported sharp wholesale inflation for coffee, tea, cocoa and spices in 2025. Together, these indicators demonstrate why nominal market turnover can increase even when household demand grows slowly, and why future competitive performance will depend on the quality of the sales mix.
Market Trends
Premium Instant Is Being Positioned as a Quality Alternative
Freeze-dried coffee is increasingly differentiated through granule quality, aroma, blend description and the assurance of convenient preparation. The premium proposition matters in Austria because consumers can readily switch to roasted coffee when a soluble product is considered weak or overly bitter. Dallmayr’s Austrian instant portfolio and Jacobs Krönung provide examples of brands attaching familiar coffee credentials to the soluble format rather than treating it only as a low-cost substitute.
Premiumisation is not synonymous with unlimited pricing power. Higher green-coffee costs flow into production and shelf prices, while promotion-driven supermarket purchasing encourages consumers to compare branded and private-label alternatives. Producers that maintain dependable flavour across batches and offer sensible pack sizes are better positioned to preserve volume as commodity inflation moderates.
Cold Preparation Is Extending Soluble Coffee Occasions
Nestlé has developed freeze-drying and formulation techniques intended to let soluble coffee dissolve more effectively in cold liquids. Its 2024 launch of hot-and-cold Nescafé Classic flavours in Central and Eastern Europe demonstrates the technical direction, although product availability in those countries does not prove identical distribution in Austria. The broader opportunity is to sell instant coffee as an ingredient for chilled drinks, flavoured recipes and occasional at-home coffee preparation.
Cold-soluble products can help manufacturers reach consumers who do not routinely make hot instant coffee. Execution depends on flavour performance after dilution, pack communication and shelf placement alongside competing coffee formats. The incremental value will remain limited if cold-soluble variants merely substitute for existing soluble jars rather than attract new consumption occasions.
Online Grocery Is Changing Replenishment Economics
Instant coffee has a long shelf life and predictable purchase frequency, allowing households to compare pack sizes and reorder without inspecting fresh produce or chilled goods. Online grocery platforms are particularly well suited to familiar branded jars, refills and multipacks. Producers must still manage search visibility, digital shelf availability and promotional prices set by major retail partners rather than assume online sales represent a separate consumer base.
As online purchases gain share, the economic emphasis shifts toward packaging that survives parcel handling and consistent SKU availability. Physical retail remains decisive because supermarket promotions and immediate purchase behaviour continue to shape brand switching. Suppliers therefore need compatible pricing and assortment strategies across the two channels.
Refill Formats Are Becoming More Relevant to Packaging Strategy
Glass jars remain recognisable and protect soluble coffee from moisture, but they impose weight and transport costs. Nestlé’s 2025 Nescafé Plan reporting describes the development of lightweight paper-based refill packs in another European market and the moisture-barrier requirements that made that change difficult. The innovation illustrates the packaging choices facing instant manufacturers, not a confirmed Austrian product rollout.
Refill systems can appeal to households already using a branded jar, provided resealability preserves aroma, and consumers can understand the weight and price benefit. Packaging changes must also satisfy Austrian and European waste, labelling and food-contact obligations. These requirements add qualification effort but can help firms protect margins as glass, freight and energy costs fluctuate.
Retailers Are Pressing for Clearer Value at Different Price Points
Austria’s concentrated grocery structure encourages active price negotiation and prominent private-label display. Instant coffee faces an unusual assortment challenge: consumers compare a premium jar with low-price soluble powders as well as ground coffee, capsules and beans. Manufacturers must decide whether to defend an entry-level format, offer a premium freeze-dried alternative or participate through private-label production.
Promotional depth can stimulate trial but also train repeat customers to wait for discounts. A more durable commercial position comes from distinct flavour and pack architecture, stable manufacturing quality and a convincing cost per prepared cup. Those characteristics matter more to long-term supplier economics than frequent cosmetic product extensions.
Segment Analysis
By Type: Freeze-Dried Instant Coffee
Freeze-dried products represent the main value pool among Austrian soluble-coffee types, despite their higher manufacturing and typically higher retail cost. Premium jars are purchased for aroma and texture as well as convenience; visible coarse granules also help distinguish them from standard powders. Brand owners use this format to defend a price premium against inexpensive instant coffee while offering a relatively easy alternative to capsule or espresso equipment.
Freeze-dried instant coffee is forecast to contribute approximately USD 88.00 million in 2031. Producers capable of controlling extraction, drying and moisture protection can use differentiated aroma and cold-solubility properties to expand the category. The constraint is the strength of fresh-coffee habits, which makes this segment particularly sensitive to whether its flavour promise can justify the retail price.
By Distribution Channel: Online
Online sales are projected to grow at approximately 11.68% annually through 2031, faster than the total instant-coffee category. Repeat purchases, access to larger packs and the ability to compare products across merchants support digital ordering. The channel is still smaller than supermarket-based retail, so growth should be interpreted as a shift in where existing household demand is fulfilled rather than as evidence of a comparable rise in national coffee consumption.
Manufacturers face a different set of requirements in online listings. Product descriptions need to distinguish freeze-dried coffee, spray-dried coffee, and mixed coffee preparations; packaging must tolerate shipment; and reliable inventory data matters for recurring orders. Multipacks can improve fulfilment economics, although overly aggressive online discounts risk undermining the same brands in conventional grocery stores.
Market Drivers
Demand for Convenient Preparation
Instant coffee remains useful to consumers who want a hot beverage without grinding beans, operating a machine or disposing of used coffee grounds. A small jar occupies limited storage space and can support intermittent consumption in households where freshly brewed coffee is the preferred everyday format. This secondary-use role is important in a mature market because the category does not need to displace espresso preparation entirely to maintain sales.
Convenience also supports travel, smaller workplaces and occasional hospitality use. Suppliers can reinforce the benefit with clear dosage instructions, consistent solubility and smaller package sizes. The growth effect is primarily a stable consumption base complemented by targeted formats for occasions when brewing equipment is unavailable.
Premium Freeze-Dried Product Development
Freeze-drying provides manufacturers with a route to improve the perceived quality of soluble coffee through granular appearance, aroma management and more flexible beverage preparation. In Austria, where roasted-coffee alternatives are widely available, perceived taste improvement is essential for sustaining a branded instant-coffee premium. Dallmayr and Jacobs demonstrate how established coffee identities are carried into soluble products.
Investment in processing control and packaging can support higher value per purchased unit even when category volumes advance gradually. The opportunity is most defensible for producers that can document flavour consistency and manage the higher energy and capital requirements of premium production.
Expansion of Digital Grocery Purchasing
Consumers buying the same instant-coffee brand repeatedly are well positioned to move some purchases online. Dry grocery shipments do not require cold-chain infrastructure, and assortment tools allow comparison of unit prices and jar sizes before checkout. E-commerce therefore provides producers with additional visibility for premium and less frequently stocked variants.
Conversion, however, remains dependent on product availability and fulfilment costs rather than simply on a brand’s digital marketing. Manufacturers can benefit from robust product data, clear imagery and packs designed for transport, while continuing to supply conventional supermarkets where most transactions occur.
Use of Instant Coffee in Cold and Flavoured Beverages
Coffee prepared with cold milk or water creates a distinct formulation requirement: granules should disperse without substantial heat or prolonged agitation. Nestlé’s soluble-coffee development indicates that the category can respond to this preference through processing improvements rather than relying solely on added flavours. Austrian manufacturers and brand owners can adapt similar concepts where consumer testing supports demand.
Cold applications offer incremental occasions outside the morning hot-drink routine. They also permit recipe-based marketing and trial among consumers seeking convenient chilled beverages. Commercial returns will depend on actual repeat purchases, since cold-coffee interest also benefits ready-to-drink products and liquid concentrates outside this market’s scope.
Value Growth Through Coffee Price and Mix Changes
Coffee commodity costs materially affect soluble-coffee pricing because substantial quantities of green coffee are needed to produce concentrated extracts. Statistics Austria recorded pronounced increases in the wholesale prices of coffee, tea, cocoa and spices in 2025. Retailers and manufacturers consequently had to negotiate changes in shelf prices and promotional funding.
The forecast reflects some continued nominal-value support from premium product mixes and modest price inflation, not a repetition of the exceptional 2025 price shock. Suppliers able to stabilize procurement and offer multiple price tiers are better placed to preserve household purchasing as commodity markets normalise.
Market Restraints
Established Preference for Freshly Prepared Coffee
Austrian coffee consumption includes deeply established demand for roasted beans, ground coffee and espresso-based beverages. These products offer sensory characteristics and preparation rituals that some consumers do not associate with soluble granules. Instant-coffee producers therefore face a direct substitution risk even among households that value convenience.
Premiumising the category helps, but it does not remove the comparison with freshly brewed coffee. Manufacturers must demonstrate a credible taste proposition for specific occasions rather than assume rising national coffee consumption will translate proportionately into soluble-coffee sales.
Sensitivity to Coffee Input Costs
Soluble-coffee manufacturing is exposed to green-coffee price changes, particularly when bean-quality requirements are high and extraction yields vary. Significant cost increases may be passed through to retail prices only gradually because supermarket promotions and annual negotiations constrain immediate adjustments.
Rapid shelf-price changes can discourage repeat purchasing or trigger brand substitution. As a result, nominal market growth caused by inflation can coincide with weaker volumes, increasing the importance of separating price and physical demand when evaluating supplier performance.
Retailer Concentration and Private-Label Competition
Major Austrian grocery groups command substantial purchasing influence and give consumers direct access to private-label ranges. Shelf position, promotional calendars and pack sizes can determine whether a premium instant brand reaches households consistently. Producers face pressure to fund discounts while maintaining manufacturing quality and packaging integrity.
Private labels are particularly competitive where shoppers prioritise the cost per cup over aroma differentiation. Brands can respond with distinctive formulations or trusted product identities, but a broad product portfolio alone does not guarantee an advantage in consolidated retail chains.
Packaging Protection and Compliance Costs
Instant-coffee granules absorb moisture readily, so manufacturers need containers and closure systems that preserve product quality after repeated opening. Alternative packs may reduce material consumption but require technical validation to protect aroma, flowability and shelf life. Glass jars provide reliable barriers, though weight increases transportation costs.
European packaging obligations and food-contact rules add development and compliance requirements. New refill formats must work with existing production equipment and meet retailer expectations; these steps can dilute near-term savings for smaller manufacturers.
Limited Growth of Consumption Volumes in a Mature Market
Austria’s high coffee familiarity and slow population expansion limit the scope for rapid increases in servings sold to entirely new consumer groups. Statistics Austria reported only modest national population growth during 2025. Many innovations are consequently more likely to move existing customers between coffee formats and price tiers than create large new volume pools.
For producers, the central forecast risk is confusing portfolio premiumisation with category expansion. Better-soluble products, cold variants and online distribution can add value, but each must be assessed against potential cannibalisation and the price sensitivity of regular household buyers.
Regional Outlook
Vienna: Largest Individual City Market
Vienna accounts for an estimated 31% of Austria’s instant-coffee market value in 2026, the largest allocation to any single city. Its population, concentration of employment, tourist accommodation and dense grocery coverage provide a broad addressable consumer base. The city’s well-known coffeehouse tradition primarily supports freshly prepared beverages, however, and should not be mistaken for direct proof of instant-coffee purchases in cafés.
Household instant demand in Vienna is supported by mixed living arrangements and access to both premium and value retail ranges. The city also offers favourable economics for online grocery fulfilment because orders are distributed across a dense urban area. Market development is expected to be driven by product mix and channel shifts rather than a major increase in coffee consumption per resident.
Graz: Fastest-Growing Named City Segment
Graz has a smaller instant-coffee base than Vienna but benefits from its university population, working households and accessible urban retail networks. The market is expected to respond to smaller packs, premium freeze-dried variants and digital grocery delivery. These demand characteristics support faster proportional development from the city’s lower starting revenue base.
The Graz segment is projected to expand at approximately 7.57% annually from 2026 to 2031. This pace reflects a stronger online and premium-mix contribution within the city rather than an assumption that its population or total coffee-drinking volume will grow at the same rate. Other Austrian towns and regions remain important collectively and are included in the full geographical allocation.
Competitive Landscape
Austria’s instant-coffee competition is led by companies with established coffee brands and access to large-scale soluble-coffee manufacturing. Nestlé participates through Nescafé, while JDE Peet’s markets Jacobs soluble products. Dallmayr’s Gold and Crema Gold ranges provide a premium alternative supported by a familiar coffee identity. These businesses compete not only on bean sourcing and taste but also on extraction consistency, drying technology, moisture-protective packaging and distribution breadth.
The market also includes branded and contract-manufactured products serving different price points. Independent suppliers such as ofi manufacture freeze-dried and spray-dried soluble coffee for downstream beverage customers, although an ingredient supplier’s international manufacturing investment is not evidence of a specific Austrian retail market share. Retailer-owned brands compete on price and shelf visibility; retailers themselves are not classified as instant-coffee manufacturers.
Portfolio positioning is likely to determine competitive performance more than rapid changes in the number of suppliers. Established brands can defend premium shelves through sensory quality and product reliability, whereas contract manufacturing and private-label procurement maintain pressure in entry-level formats. Manufacturers that link premium soluble coffee with convenient cold preparation may attract incremental interest, provided claims are supported by the actual products sold in Austria.
Recent Developments
22 October 2026: Nestlé reported third-quarter coffee growth led by Nescafé and other global brands, while noting improved real internal growth. The disclosure demonstrates continued manufacturer investment in coffee formats but does not provide Austrian soluble-coffee sales.
9 July 2026: Nestlé announced a CHF 563 million investment in a new Nescafé facility in Thailand, scheduled to produce soluble coffee, coffee mixes and ready-to-drink products beginning in late 2028. The project concerns global manufacturing capacity rather than confirmed Austrian supply.
13 May 2025: ofi announced the inauguration of its Linhares soluble-coffee manufacturing facility in Brazil, adding freeze-dried and spray-dried capacity for international customers.
8 May 2025: Nestlé described a new freeze-drying technique intended to enable premium soluble coffee to dissolve effectively in cold liquids, strengthening the technical basis for new preparation occasions.
6 November 2024: Nestlé introduced a Nescafé Classic soluble-coffee range in Central and Eastern Europe, developed for both hot and cold beverages and offered in caramel and hazelnut varieties.
Market Outlook
Austrian soluble coffee will remain a comparatively mature category, with value growth driven by a combination of premium products, incremental digital grocery sales and selective new consumption occasions. Freeze-dried coffee should maintain a leading position in value terms because aroma, granule quality and ease of preparation provide a clearer basis for differentiated pricing than the basic soluble-coffee format alone. Entry-level products will remain relevant for price-conscious households, particularly while coffee costs remain volatile.
Manufacturers face a demanding competitive environment in which stronger consumer interest in quality can benefit both premium instant products and freshly brewed coffee. Cold-soluble formulations and refill packaging offer viable innovation routes, but neither guarantees sustained category growth without good product performance and repeat purchasing. The most defensible expansion opportunities are likely to come from suppliers capable of combining formulation expertise, efficient production and stable retailer relationships.
Vienna will continue to provide the largest individual city demand pool, while Graz offers stronger percentage growth from a smaller base. Across the country, greater e-commerce penetration is likely to affect ordering and pack configuration faster than it alters total coffee consumption. As input-cost volatility eases, the balance between real sales growth and price-driven turnover will become a more important measure of commercial success.
Austria Instant Coffee Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 125.0 million |
| Total Market Size in 2031 | USD 160.0 million |
| Forecast Unit | Million |
| Growth Rate | 5.06% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Distribution Channel, City |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Freeze-Dried Instant Coffee
Spray-Dried Instant Coffee
Others
By Distribution Channel
Offline
Retail
Food Services
Online
By City
Vienna
Graz
Others
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Key Findings
1.2. Austria Instant Coffee Market Size, 2026–2031
1.3. Product and Channel Outlook
1.4. City Opportunity Summary
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Demand for Convenient Preparation
3.1.2. Premium Freeze-Dried Product Development
3.1.3. Expansion of Digital Grocery Purchasing
3.1.4. Use of Instant Coffee in Cold and Flavoured Beverages
3.1.5. Value Growth Through Coffee Price and Mix Changes
3.2. Market Restraints
3.2.1. Established Preference for Freshly Prepared Coffee
3.2.2. Sensitivity to Coffee Input Costs
3.2.3. Retailer Concentration and Private-Label Competition
3.2.4. Packaging Protection and Compliance Costs
3.2.5. Limited Growth of Consumption Volumes in a Mature Market
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Freeze-Drying and Aroma Retention
4.2. Spray-Drying Process Economics
4.3. Cold-Soluble Product Formulation
4.4. Moisture-Barrier Packaging
5. AUSTRIA INSTANT COFFEE MARKET BY TYPE
5.1. Introduction
5.2. Freeze-Dried Instant Coffee
5.3. Spray-Dried Instant Coffee
5.4. Others
6. AUSTRIA INSTANT COFFEE MARKET BY DISTRIBUTION CHANNEL
6.1. Introduction
6.2. Offline
6.2.1. Retail
6.2.2. Food Services
6.3. Online
7. AUSTRIA INSTANT COFFEE MARKET BY CITY
7.1. Introduction
7.2. Vienna
7.3. Graz
7.4. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Nestlé S.A.
9.2. JDE Peet’s N.V.
9.3. Alois Dallmayr KG
9.4. ofi
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key Benefits for Stakeholders
10.5. Research Methodology
10.6. Abbreviations





Frequently asked questions
What is the projected market value for Austria's instant coffee by 2031?
The Austria Instant Coffee Market is projected to reach USD 160.0 million by 2031.
What is the forecasted CAGR for the Austria instant coffee market?
The Austria Instant Coffee Market is expected to grow at a CAGR of 5.06%.
Which instant coffee format holds the largest market share in Austria?
Freeze-dried coffee accounts for an estimated 52% of market value in 2026.
What is the principal distribution channel for instant coffee in Austria?
Grocery retail remains the principal route, with online sales gaining relevance.
Which Austrian city is the largest instant coffee market?
Vienna remains the largest individual city market; Graz offers faster growth.
What factors drive future demand for instant coffee in Austria?
Household affordability, premium formats, and convenient new uses shape demand.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Austria Instant Coffee Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/austria-instant-coffee-market