
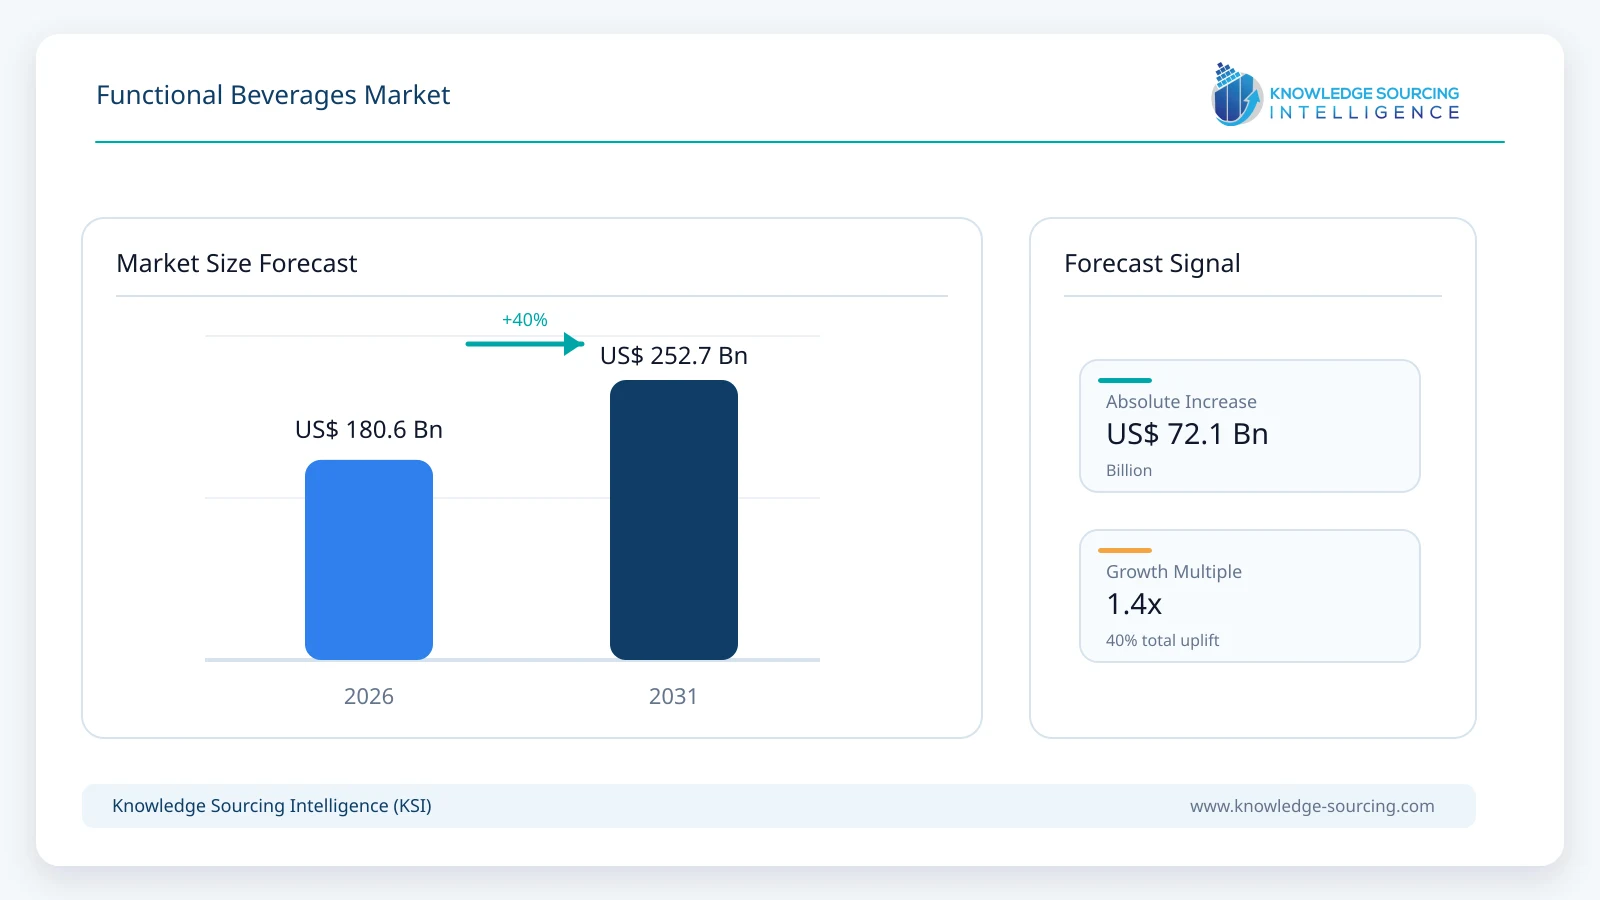
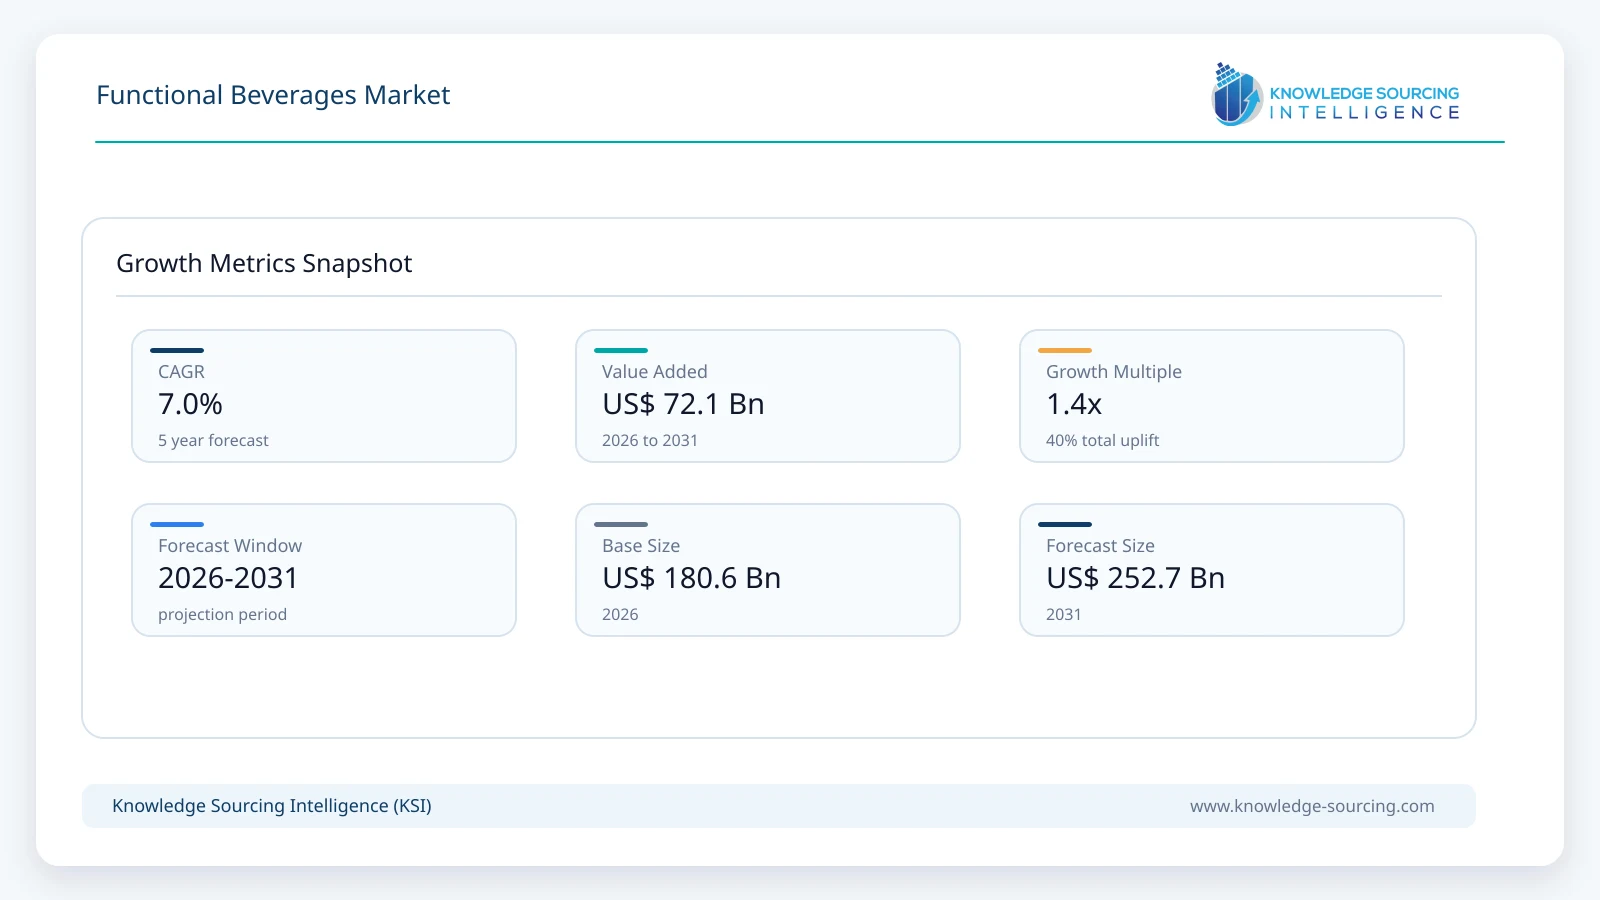
The Functional Beverages Market is growing at a CAGR of 7.0%, from USD 180.6 billion in 2026 to USD 252.7 billion by 2031.
Highlights:
- 1Energy drinks account for approximately 38% of global functional beverage revenue in 2026.
- 2Health and wellness applications generate about USD 54.2 billion of market value in 2026.
- 3Adult-focused functional beverages are projected to grow at approximately 6.5% annually through 2031.
- 4North America represents approximately 34% of global functional beverage revenue in 2026.
- 5Protein, gut-health and multifunctional hydration products are widening everyday consumption occasions.
- 6Online retail is gaining relevance through subscriptions, specialist brands and direct-to-consumer launches.
Functional beverages sit between traditional refreshment and nutrition products. The category is defined by a clear functional proposition rather than by the beverage base alone. An electrolyte drink, probiotic dairy beverage, vitamin water, protein coffee or prebiotic soda can therefore fall within the market when its formulation and positioning are built around a measurable wellness or performance benefit. The same product without that added functional purpose remains part of the broader beverage market rather than the functional segment.
Energy and sports drinks remain the largest established categories because they have high purchase frequency and strong convenience-store distribution. Newer growth is coming from protein, gut health and multifunctional hydration. PepsiCo launched Propel Clear Protein in May 2026 with protein, fiber and electrolytes in one formulation. The Coca-Cola Company expanded BODYARMOR into sparkling functional hydration in June 2026. Yakult continued to expand probiotic and fermented nutrition formats during 2026, including a peach probiotic drink in Singapore and Yakult Vitals, a fermented soy drink with vitamins and minerals, in Europe.
Market Trends
Protein is moving from shakes into lighter hydration and everyday beverage formats
Protein beverages are expanding beyond traditional dairy shakes and sports nutrition. Clear protein water, protein coffee and lighter ready-to-mix formats are gaining attention from consumers who want protein without a heavy texture. PepsiCo's Propel Clear Protein combines whey protein, fiber and electrolytes. Beyond Meat entered beverages in 2026 with Beyond Immerse, while smaller brands are introducing sparkling protein water and protein refreshers. This widens the category from post-workout nutrition toward general wellness, satiety and convenient nutrition.
Gut-health functionality is moving into mainstream beverage brands
Prebiotics and probiotics are becoming more visible outside specialist health channels. PepsiCo rolled out Pepsi Prebiotic Cola nationally in the United States in February 2026 with prebiotic fiber and lower sugar. Yakult continues to expand probiotic formats and flavors, while Danone maintains broad functional dairy positions through Activia and Actimel. The trend increases competition between traditional probiotic drinks, functional sodas, kombucha-style products and fiber-enhanced beverages. Taste remains critical because repeat purchase depends on the product working as an everyday beverage rather than as a supplement.
Energy drinks are becoming more segmented by occasion and consumer profile
The energy category is no longer built around a single high-caffeine proposition. Brands are differentiating through sugar-free formulations, flavor extensions, fitness positioning and lower-calorie options. Monster Beverage generated USD 7.67 billion from its Monster Energy Drinks segment in 2025. Celsius Holdings generated USD 2.52 billion of revenue in 2025 after expanding its portfolio with Alani Nu. Red Bull continues to use seasonal and permanent flavor editions to broaden consumption occasions. This creates a more competitive category but also expands consumer choice and usage frequency.
Market Drivers
Everyday wellness is broadening functional beverages beyond sports and fitness
Consumers increasingly use beverages to support hydration, energy, digestion, protein intake and micronutrient consumption during normal daily routines. This allows functional beverages to compete across breakfast, commuting, work, exercise and evening occasions. The result is a wider addressable market than traditional sports nutrition alone. Large beverage companies are reinforcing the trend by integrating functional ingredients into mainstream brands instead of relying only on specialist health products.
Low-sugar reformulation is improving the fit with health-oriented positioning
Functional claims can lose credibility when products contain high levels of added sugar. Manufacturers are therefore reformulating with lower sugar, non-nutritive sweeteners and smaller serving formats. Sugar taxes and front-of-pack nutrition rules in several markets strengthen this incentive. Energy and sports drink brands are now offering broader zero-sugar portfolios, while functional water and probiotic beverages can compete on naturally lower calorie profiles. The change supports category growth among consumers who previously avoided functional drinks because of sugar content.
Distribution scale is allowing niche functional concepts to reach mass retail faster
Functional beverage launches can move from direct-to-consumer testing into national retail more quickly than in the past. Large distributors provide access to convenience, grocery, club and foodservice channels, while online marketplaces reduce the dependence on physical shelf space. Beyond Immerse entered the New York market in 2026 through Big Geyser, which serves more than 26,000 outlets. PepsiCo and Coca-Cola can scale new concepts through existing bottling and distribution systems. Specialist brands use digital channels to build demand before expanding into national retail.
Market Restraint
Health-claim regulation and ingredient cost can slow innovation and raise launch risk
Functional beverages require greater regulatory discipline than standard refreshments because product claims can imply physiological benefits. Manufacturers must control wording, ingredient dosage and evidence across different jurisdictions. Probiotic products face additional stability and cold-chain requirements, while protein, botanical and vitamin formulations can introduce taste, solubility and shelf-life challenges. Specialized ingredients also cost more than the basic inputs used in ordinary soft drinks. These factors increase development cost and can make premium functional beverages vulnerable when consumers become more price sensitive.
Segment Analysis
By Product Type - Energy Drinks
Energy drinks remain the largest product segment because they combine high purchase frequency, strong convenience-store distribution and broad consumer awareness. The segment is estimated at approximately USD 68.6 billion in 2026. Growth is supported by zero-sugar variants, flavor extensions and wider use across work, travel, gaming and fitness occasions. Leading brands continue to differentiate through formulation, flavor, packaging and distribution reach.
By Application - Health and Wellness
Health and wellness is the largest application because functional beverages are increasingly consumed as part of everyday hydration, nutrition and wellness routines. The segment accounts for approximately 30% of global market value in 2026. Demand is supported by products positioned around hydration, protein intake, vitamins, minerals, digestive support and general wellbeing. The category benefits from broad consumption occasions that extend beyond exercise or clinical use.
By End User - Adults
Adults remain the largest end-user group because they account for most spending across energy, hydration, protein, probiotic and wellness-oriented beverages. The segment represents approximately 60% of global market value in 2026. Demand is spread across work, commuting, fitness, travel and at-home consumption. Product development increasingly targets convenience, lower sugar, portable nutrition and benefits that fit routine daily use.
By Distribution Channel - Supermarkets and Hypermarkets
Supermarkets and hypermarkets remain the largest distribution channel because they offer broad brand choice, multipack formats and regular household purchasing. The channel is estimated at approximately USD 65.0 billion in 2026. Large beverage companies benefit from established shelf presence, while specialist brands use major retailers to move beyond niche health and fitness channels. In-store visibility and promotional support remain important for trial and repeat purchase.
By Geography - North America
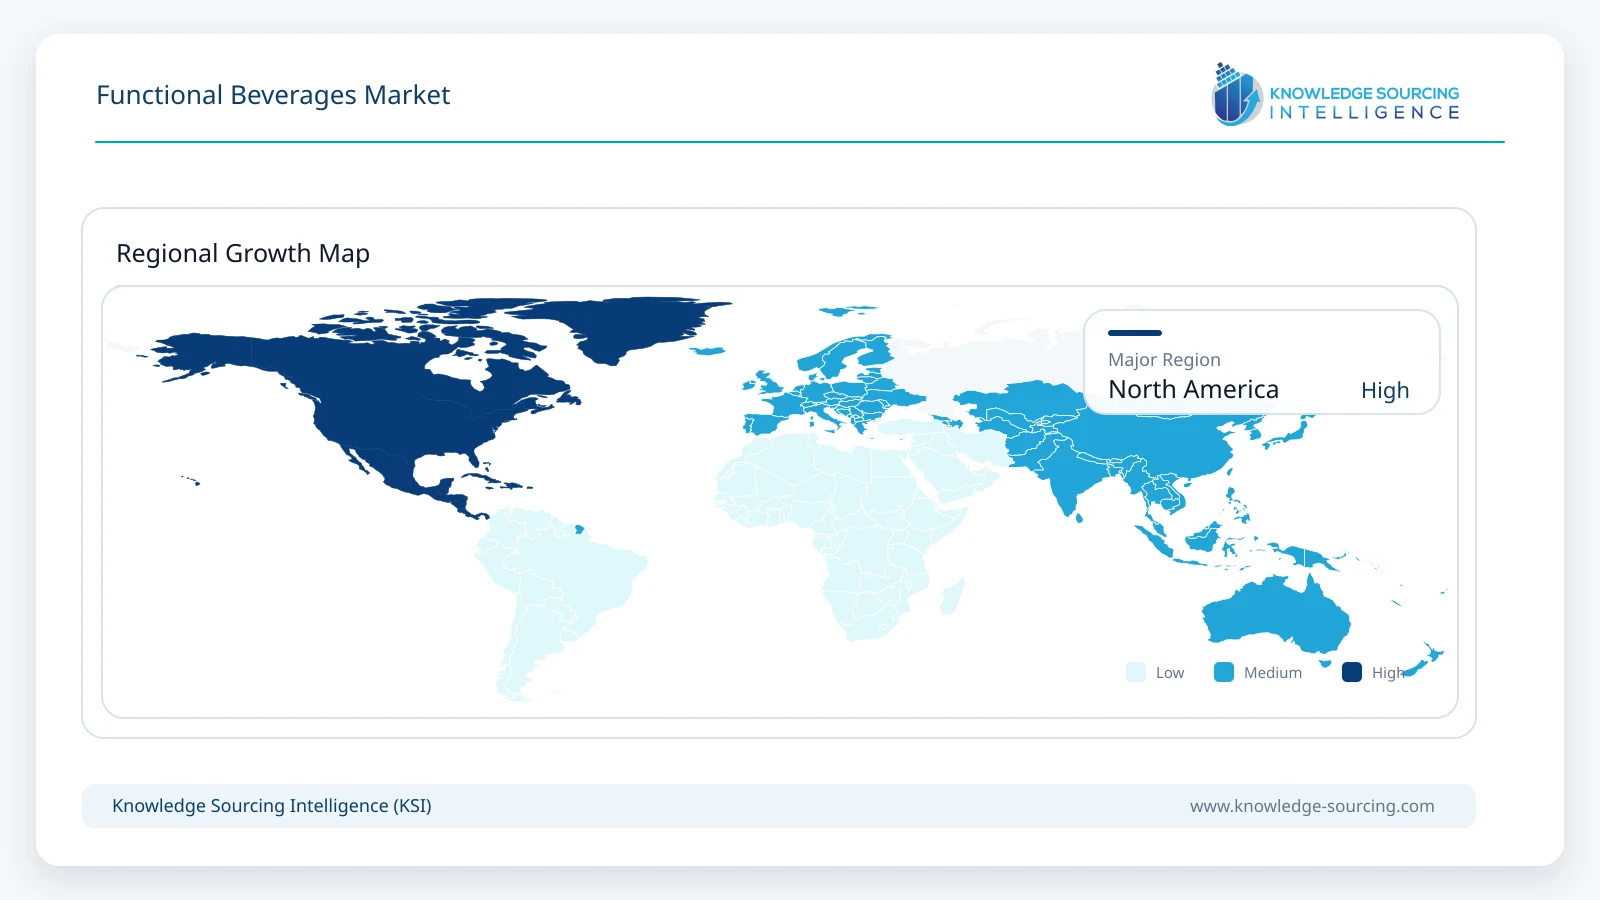
North America remains the largest regional market because energy drinks, sports hydration and newer functional formats have high retail penetration. The region is estimated at approximately USD 61.4 billion in 2026. The United States is the main contributor, supported by frequent product launches in prebiotic soda, protein beverages, functional hydration and zero-sugar energy drinks. Strong convenience, grocery and online channels help new concepts reach consumers quickly.
Competitive Environment
The Coca-Cola Company and PepsiCo compete across sports hydration, functional water and newer wellness formats. Coca-Cola owns BODYARMOR and Powerade and continues to expand functional hydration. PepsiCo combines Gatorade, Propel, Celsius partnerships and the acquired poppi prebiotic soda business. Their main advantage is the ability to place new products rapidly across grocery, convenience, club and foodservice channels.
Monster Beverage, Red Bull and Celsius Holdings are major specialist competitors in energy drinks. Monster remains one of the largest independent energy-drink companies globally. Celsius has expanded its scale through Alani Nu and PepsiCo distribution. Red Bull maintains a focused energy portfolio and continues to use flavor editions and event marketing to reinforce the brand.
Danone, Yakult, Otsuka and Suntory have strong positions in probiotic, hydration and wellness-oriented beverages. Danone competes through Actimel, Activia and functional water platforms. Yakult is extending its probiotic and fermented product range, while Otsuka continues to expand POCARI SWEAT internationally. Suntory is increasing investment behind wellness-oriented beverage concepts across its regional portfolio.
Recent Developments
August 2026: Red Bull made Fuji Apple & Ginger a permanent U.S. flavor under the Red Bull Apple Edition.
August 2026: PepsiCo highlighted protein coffee as an emerging functional beverage occasion combining caffeine and nutrition.
July 2026: Otsuka launched POCARI SWEAT ION WATER powder sticks for everyday electrolyte replenishment.
June 2026: BODYARMOR launched BODYARMOR FIT, its first sparkling sports drink with electrolytes, caffeine and zero sugar.
June 2026: Yakult Singapore launched a peach probiotic drink, its first new flavor in the market in 46 years.
June 2026: Beyond Meat launched Beyond Immerse, its first functional beverage line, in the New York market.
May 2026: PepsiCo launched Propel Clear Protein with protein, fiber and electrolytes in one functional hydration product.
February 2026: Yakult began selling Yakult Vitals, a fermented soy drink with vitamin D and minerals, in Europe.
February 2026: Pepsi Prebiotic Cola rolled out nationally in the United States with prebiotic fiber and lower sugar.
Functional Beverages Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 180.6 billion |
| Total Market Size in 2031 | USD 252.7 billion |
| Forecast Unit | Billion |
| Growth Rate | 7.0% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Application, End-user, Distribution Channel, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Product Type
Energy Drinks
Sports Drinks
Nutraceutical Drinks
Probiotic Drinks
Herbal and Fruit Teas
Functional Water
Functional Juices and Shots
By Application
Health and Wellness
Weight Management
Sports Nutrition
Clinical Nutrition
Cardiovascular Health
Digestive Health
Immune Health
By End User
Adults
Athletes and Sports Enthusiasts
Geriatric Population
Children
By Distribution Channel
Supermarkets and Hypermarkets
Convenience Stores
Online Retail
Pharmacies and Health Stores
Specialty Stores
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Australia
Indonesia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Everyday Wellness is Broadening Functional Beverages Beyond Sports and Fitness
3.1.2. Low-Sugar Reformulation is Improving the Fit with Health-Oriented Positioning
3.1.3. Distribution Scale is Allowing Niche Functional Concepts to Reach Mass Retail Faster
3.2. Market Restraint
3.2.1. Health-Claim Regulation and Ingredient Cost Can Slow Innovation and Raise Launch Risk
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. FUNCTIONAL BEVERAGES MARKET BY PRODUCT TYPE
4.1. Introduction
4.2. Energy Drinks
4.3. Sports Drinks
4.4. Nutraceutical Drinks
4.5. Probiotic Drinks
4.6. Herbal and Fruit Teas
4.7. Functional Water
4.8. Functional Juices and Shots
5. FUNCTIONAL BEVERAGES MARKET BY APPLICATION
5.1. Introduction
5.2. Health and Wellness
5.3. Weight Management
5.4. Sports Nutrition
5.5. Clinical Nutrition
5.6. Cardiovascular Health
5.7. Digestive Health
5.8. Immune Health
6. FUNCTIONAL BEVERAGES MARKET BY END USER
6.1. Introduction
6.2. Adults
6.3. Athletes and Sports Enthusiasts
6.4. Geriatric Population
6.5. Children
7. FUNCTIONAL BEVERAGES MARKET BY DISTRIBUTION CHANNEL
7.1. Introduction
7.2. Supermarkets and Hypermarkets
7.3. Convenience Stores
7.4. Online Retail
7.5. Pharmacies and Health Stores
7.6. Specialty Stores
8. FUNCTIONAL BEVERAGES MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. United States
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. Germany
8.4.2. France
8.4.3. United Kingdom
8.4.4. Italy
8.4.5. Spain
8.4.6. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. South Africa
8.5.4. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. Japan
8.6.3. India
8.6.4. South Korea
8.6.5. Australia
8.6.6. Indonesia
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Product and Innovation Positioning
9.4. Mergers, Acquisitions, Agreements and Collaborations
9.5. Competitive Dashboard
10. COMPANY PROFILES
10.1. The Coca-Cola Company
10.2. PepsiCo, Inc.
10.3. Red Bull GmbH
10.4. Monster Beverage Corporation
10.5. Celsius Holdings, Inc.
10.6. Danone S.A.
10.7. Nestlé S.A.
10.8. Keurig Dr Pepper Inc.
10.9. Otsuka Holdings Co., Ltd.
10.10. Suntory Beverage & Food Limited
10.11. Yakult Honsha Co., Ltd.
10.12. Kirin Holdings Company, Limited
10.13. Asahi Group Holdings, Ltd.
10.14. Glanbia plc
10.15. BellRing Brands, Inc.
10.16. Herbalife Ltd.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations





Frequently asked questions
What is the projected growth rate of the Functional Beverages Market?
The Functional Beverages Market is growing at a 7.0% CAGR through 2031.
What is the forecast market value for functional beverages by 2031?
The Functional Beverages Market is forecast to reach USD 252.7 billion by 2031.
Which functional beverage category generates the most revenue?
Energy drinks account for approximately 38% of global revenue in 2026.
Which region holds the largest share of the Functional Beverages Market?
North America represents approximately 34% of global revenue in 2026.
What are the key emerging growth areas in functional beverages?
Protein, gut-health, and multifunctional hydration are driving new growth.
How is protein consumption evolving in functional beverages?
Protein is moving into lighter hydration and everyday beverage formats.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Functional Beverages Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/functional-beverages-market