
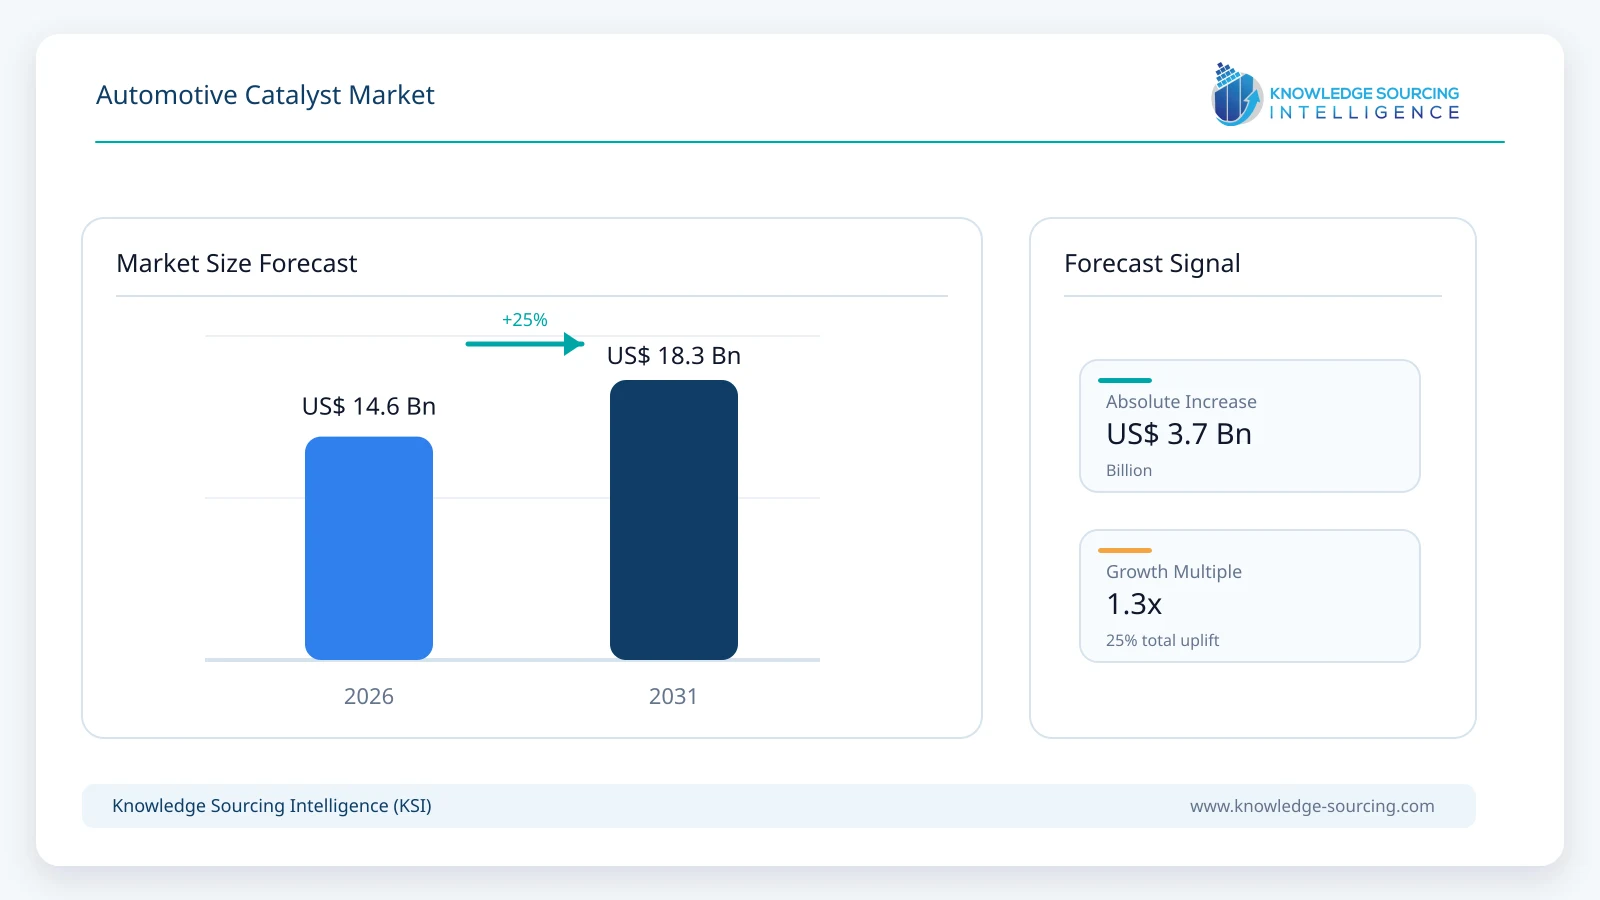
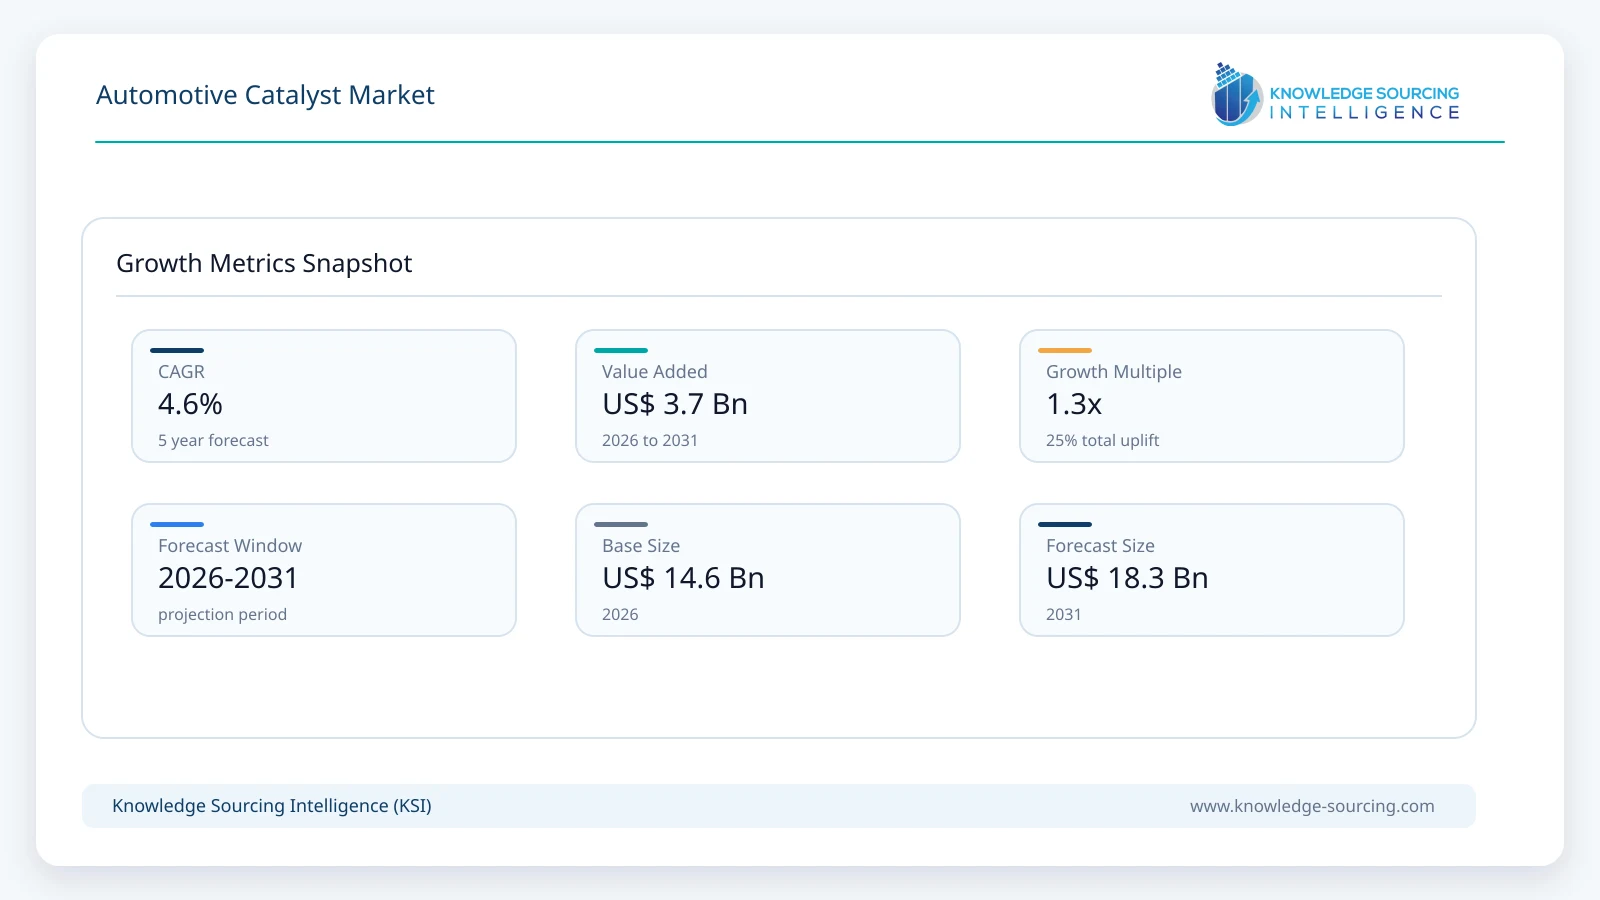
The Automotive Catalyst Market is projected to expand at a CAGR of 4.6%, reaching USD 18.3 billion in 2031 from USD 14.6 billion in 2026.
Highlights:
- 1Cold-start performance is becoming a central design requirement for gasoline and hybrid exhaust catalysts.
- 2Three-way catalysts are projected to generate approximately USD 9.88 billion by 2031.
- 3Heavy-duty catalyst specifications increasingly combine NOx reduction, oxidation, and ammonia-slip control.
- 4Asia Pacific remains the dominant production-linked region, despite rapid battery-electric vehicle penetration.
- 5Platinum-group-metal efficiency and validated durability increasingly shape supplier differentiation.
Automotive catalysts are coated chemical systems that convert or capture regulated exhaust pollutants before they leave the vehicle. Three-way conversion, diesel oxidation, NOx reduction, catalyzed particulate filtration, and related specialist formulations are supplied for original-equipment installation and qualifying replacement demand. As engine calibration and thermal management become more demanding, the coating formulation and its integration with the exhaust flow path are increasingly developed together.
Metivo, the automotive-catalyst operation historically known as BASF Environmental Catalyst and Metal Solutions, competes with Umicore, Johnson Matthey, Cataler and Heesung Catalysts across major vehicle-producing regions. Hybrid gasoline platforms preserve demand for rapid-light-off coatings even as pure battery-electric passenger-car production grows. Heavy-duty diesel applications require greater functional diversity and higher unit values, with SCR chemistry, oxidation catalysts and ammonia slip control calibrated as a coordinated aftertreatment package.
Market Overview
Global motor-vehicle production reached 96.4 million units in 2025 according to OICA, but vehicle output alone does not measure catalyst revenue. A battery-electric car has no combustion exhaust requiring a tailpipe catalyst; a hybrid does. Catalyst content also differs between a low-displacement motorcycle, a gasoline passenger car and a heavy-duty truck operating over a long emissions-compliance life. This uneven installation base explains why vehicle mix, exhaust architecture and catalyst formulation are more informative than total automotive production when assessing market value.
Three-way catalysts employ platinum-group-metal active sites and oxygen-storage materials to oxidize carbon monoxide and hydrocarbons while reducing nitrogen oxides. On gasoline direct-injection vehicles, they may operate alongside catalyzed particulate filters. Diesel applications combine oxidation, particulate filtration and selective catalytic reduction, often supported by ammonia slip catalysts. Umicore publishes a portfolio across these technologies, while Metivo describes its new GenV+ copper-zeolite SCR formulation for heavy-duty emissions control. Both illustrate how catalyst performance is assessed against engine-specific duty cycles rather than a universal material specification.
The regulatory timetable is becoming more differentiated. Euro 7 begins applying to newly type-approved passenger cars and vans on 29 November 2026, with new vehicles following one year later; heavy-duty implementation comes later. India has already introduced real-driving emissions conformity requirements under BS VI. In the United States, the 2027 heavy-duty program remains relevant for criteria pollutants, although proposals to amend aspects of implementation add uncertainty. These requirements support development expenditure but do not guarantee constant growth in supplier revenue, particularly where automakers reduce precious-metal loading or shift production to electric platforms.
Market Trends
Cold-start control is shifting catalyst design toward hybrid operating cycles
Engine restarts in hybrid vehicles create temperature and oxygen-management conditions that conventional steady-state conversion tests do not fully represent. Electrically heated catalysts, close-coupled converters and high-activity washcoats address emissions during the short period before an exhaust system reaches efficient operating temperature. Umicore identifies electrically heated three-way catalysts and secondary-emission catalysts in its gasoline and hybrid portfolio, showing that the design effort increasingly extends beyond the traditional TWC brick.
The purchasing consequence is a greater emphasis on vehicle-calibrated performance and thermal durability. A catalyst that requires less warm-up energy or remains effective after repeated stop-start operation can support emission compliance without oversized hardware. Suppliers must still substantiate performance in production conditions; an announced chemistry does not by itself establish high-volume fitment.
Heavy-duty SCR chemistry is being optimized for NOx and nitrous oxide together
Metivo describes its GenV+ copper-zeolite SCR catalyst as qualified with several global truck customers. The published technology comparison indicates lower nitrous oxide formation alongside stronger high-temperature NOx conversion than an earlier generation, an important distinction as truck-makers address multiple exhaust species simultaneously. Qualification establishes engineering maturity, although platform revenue depends on the subsequent production rollout.
Truck duty cycles also demand stable performance under variable exhaust temperature, sulfur exposure and long operating lives. The continuing evolution of SCR systems favours suppliers capable of controlling zeolite formulation, coating quality and substrate integration while limiting ammonia slip downstream.
Platinum-group-metal substitution is becoming a procurement discipline
Platinum, palladium and rhodium affect the cost of gasoline and diesel catalyst coatings differently. Changes in relative metal prices may encourage loading adjustments, but substitutions cannot be made independently of oxygen-storage performance, poisoning resistance and emissions certification. Metivo highlights precious-metal management and a closed-loop supply model as part of its customer offering.
Procurement teams increasingly consider the full metal lease, recovery and hedging arrangement alongside catalyst coating price. Recycling helps protect supply, but recovered-metal revenue is not additive to the new catalyst market unless it is the material cost embodied once in the sold product.
Local production remains important despite a maturing global market
Catalyst coating lines require qualification for each engine family and must operate within strict precious-metal accountability controls. Umicore reported relatively stable Automotive Catalysts volumes and revenues in the first half of 2026 despite a weaker broader combustion-vehicle trend. Supplier performance therefore reflects awarded platforms, regional customer mix and execution rather than uniform movement with global car sales.
China and India sustain significant vehicle production, while European and North American programs place greater emphasis on compliance testing and the durability of long-life aftertreatment systems. Firms with regional laboratories can make calibration and supply changes close to OEM production, but local footprint duplication can pressure capital returns.
Catalyzed filters and secondary emissions are widening the value per engine
Particulate filters can perform filtration and chemical conversion simultaneously when coated, enabling more compact exhaust layouts than separately installed devices. Heesung Catalysts describes gasoline particulate filter coatings that pair three-way activity with a wall-flow substrate, while Umicore has developed catalysts addressing ammonia and nitrous oxide emerging from gasoline operation.
An increasingly complex treatment train is not necessarily a larger mass of precious metal. Design wins may come from integrating multiple functions, limiting backpressure or reducing the total number of units. That shifts supplier differentiation toward system-level conversion efficiency and validated durability.
Segment Analysis
By Type: Three-Way Catalysts
Three-way catalysts account for an estimated 58% of 2026 market value, underpinned by high gasoline-vehicle volumes and the continued use of combustion engines in hybrid powertrains. The core chemistry simultaneously addresses carbon monoxide, hydrocarbons, and nitrogen oxides under near-stoichiometric combustion. For manufacturers, catalyst performance is closely linked to oxygen storage, washcoat dispersion, thermal ageing and engine controls; a reduction in platinum-group-metal content cannot compromise the certified tailpipe result.
Passenger-car programs support the largest production scale, but suppliers are also adapting three-way conversion to motorcycles and alternative-fuel engines. Cataler and Heesung Catalysts offer gasoline conversion catalysts alongside related particulate-control technologies. The segment will remain the largest product group through 2031 even as advanced diesel reduction and coated-filter products take a greater share of incremental value.
By Vehicle Type: Heavy-Duty Commercial Vehicles
Long-haul trucks and buses need catalysts that remain effective at high cumulative mileage, variable loads and frequent regeneration events. Their emissions-control systems typically use several catalytic functions, and production qualification involves thermal aging, urea dosing, ammonia slip and pressure-drop requirements. A supplier is competing for a coordinated emissions package, not simply an interchangeable coating commodity.
The heavy-duty commercial vehicle segment is modelled to reach approximately USD 3.11 billion in 2031. More stringent NOx requirements and greater catalyst functionality per truck can support value growth despite slower unit expansion than in passenger vehicles. Umicore offers diesel oxidation, SCR and ammonia slip catalysts, while Metivo has documented customer qualification of its next-generation copper-zeolite SCR chemistry.
Market Drivers
Real-world emissions compliance is increasing formulation requirements
Euro 7 moves passenger-car and van type approvals into a new regulatory phase from late November 2026, with further implementation steps for vehicles and heavy-duty categories. India’s BS VI real-driving emission requirements already require manufacturers to account for operation outside laboratory conditions. These programs keep catalytic conversion performance central to engine and exhaust certification.
The market benefit arises through tougher low-temperature, transient and durability performance rather than a simple increase in units produced. Formulations that maintain conversion across broader engine maps are more difficult to validate and can carry greater engineering value.
Hybrid vehicle programmes retain a large catalyst installation base
Plug-in and conventional hybrid vehicles continue to emit exhaust whenever their combustion engine operates. Frequent starts, cooling between engine-on periods and transient load changes can make catalyst warm-up more challenging than on a continuously operating gasoline vehicle. Johnson Matthey reported winning a major hybrid light-duty gasoline program during its 2025/26 financial year.
Automakers purchasing hybrid powertrains therefore still require coated exhaust catalysts and calibration support. The value attached to rapid light-off and secondary emissions control can partly offset pressure from declining combustion-only car volumes.
Heavy-duty aftertreatment value rises with chemical complexity
Heavy-duty exhaust lines frequently combine diesel oxidation, particulate filtration, selective catalytic reduction and ammonia slip control. The US heavy-duty criteria-pollutant programme for model year 2027 and the staged Euro 7 timetable require suppliers to design for extended use and broader operating conditions, subject to current and proposed implementation changes.
An engine manufacturer may purchase more advanced coated elements even if truck assembly volumes stay relatively stable. Metivo’s newly qualified GenV+ CuSCR illustrates supplier investment in simultaneous NOx conversion and nitrous oxide management.
Localized catalyst development shortens OEM qualification cycles
Automakers in China, India, Europe and North America calibrate engines for different fuels, ambient conditions, exhaust packaging requirements and certification tests. Catalyst makers with nearby development laboratories can modify washcoat loading and assess aging performance without moving every engineering iteration across borders.
Umicore’s broad production and technical-centre network and Metivo’s global manufacturing footprint make regional proximity an important competitive attribute. Local engineering wins can lead to multi-year supply programs, although qualification costs must be recovered over sufficient volume.
Replacement demand supports revenue outside vehicle assembly
High-mileage trucks, commercial fleets and aging passenger vehicles create demand for compliant replacement catalysts when original units fail, are damaged or no longer meet operating requirements. Replacement demand varies with local inspection rules, repair costs, vehicle age and the availability of properly specified parts.
Catalyst makers and specialized aftermarket suppliers can serve this demand without relying exclusively on new-vehicle production. In the model, only the catalyst product value is counted; repair labour and the collection value of spent precious metals are excluded to avoid double-counting.
Market Restraints
Battery-electric vehicle adoption removes tailpipe catalyst demand
Battery-electric cars have no combustion exhaust stream and do not require three-way, oxidation or SCR catalysts. The IEA reported more than 20 million electric-car sales in 2025 across battery-electric and plug-in hybrid categories, with further expansion expected in 2026. Since plug-in hybrids still need exhaust treatment, the impact depends on the mix within electric-vehicle sales rather than the headline electric total.
Where pure-electric penetration rises quickly, supplier opportunities decline unless engine-based vehicle production holds up elsewhere or the remaining installations carry greater catalyst value. This is the central long-run volume constraint for light-duty gasoline catalysts.
Precious-metal price fluctuations complicate quotations and inventory
Catalyst producers purchase or manage palladium, platinum and rhodium in tightly controlled manufacturing processes. Metal-price movements can overwhelm changes in coating-conversion cost, particularly where contracts do not pass the entire metal exposure directly to the OEM. A redesign that uses less rhodium may also require additional thermal-aging validation.
Suppliers respond through metal leasing, recovery programs, substitution and contractual pass-through arrangements. These actions limit exposure but do not eliminate working-capital burdens or the risk that a sudden price shift disrupts procurement planning.
Platform qualification creates substantial switching costs
A catalyst coating certified for one engine family cannot necessarily be substituted onto another without emissions and durability testing. Vehicle launches require washcoat controls, aging data, substrate compatibility and repeatable manufacturing quality. Under tighter compliance windows, a technical failure can delay a production launch or force expensive recalibration.
Qualification requirements protect incumbents with validated platforms, but they also slow the commercialization of new entrants and chemistry innovations. Suppliers must fund testing before a production award yields substantial revenue.
Changing regulations increase investment uncertainty
Euro 7 has a defined staged application schedule, whereas the US EPA proposed amendments in July 2026 to aspects of the model-year-2027 heavy-duty implementation rules. Rules governing greenhouse-gas emissions and criteria pollutants also differ. Product developers cannot assume that every proposed emissions provision will be enacted unchanged.
Divergent regulatory pathways make it costly to maintain several catalyst families and testing protocols. Where compliance timelines shift, automakers may defer sourcing decisions even while retaining the need for effective exhaust aftertreatment.
OEM cost reduction pressures coating economics
Engine manufacturers continually seek lower materials cost, smaller packaging volumes and reduced exhaust backpressure. They may press catalyst suppliers to cut precious-metal loadings or integrate several functions in one coated part. A design win can therefore expand volumes without proportionate growth in supplier margin.
Competition is particularly demanding where gasoline platforms are being consolidated across fewer engine families. Catalyst manufacturers must balance coating performance, metals exposure and plant utilization while protecting returns on specialized production assets.
Regional Outlook
Asia Pacific
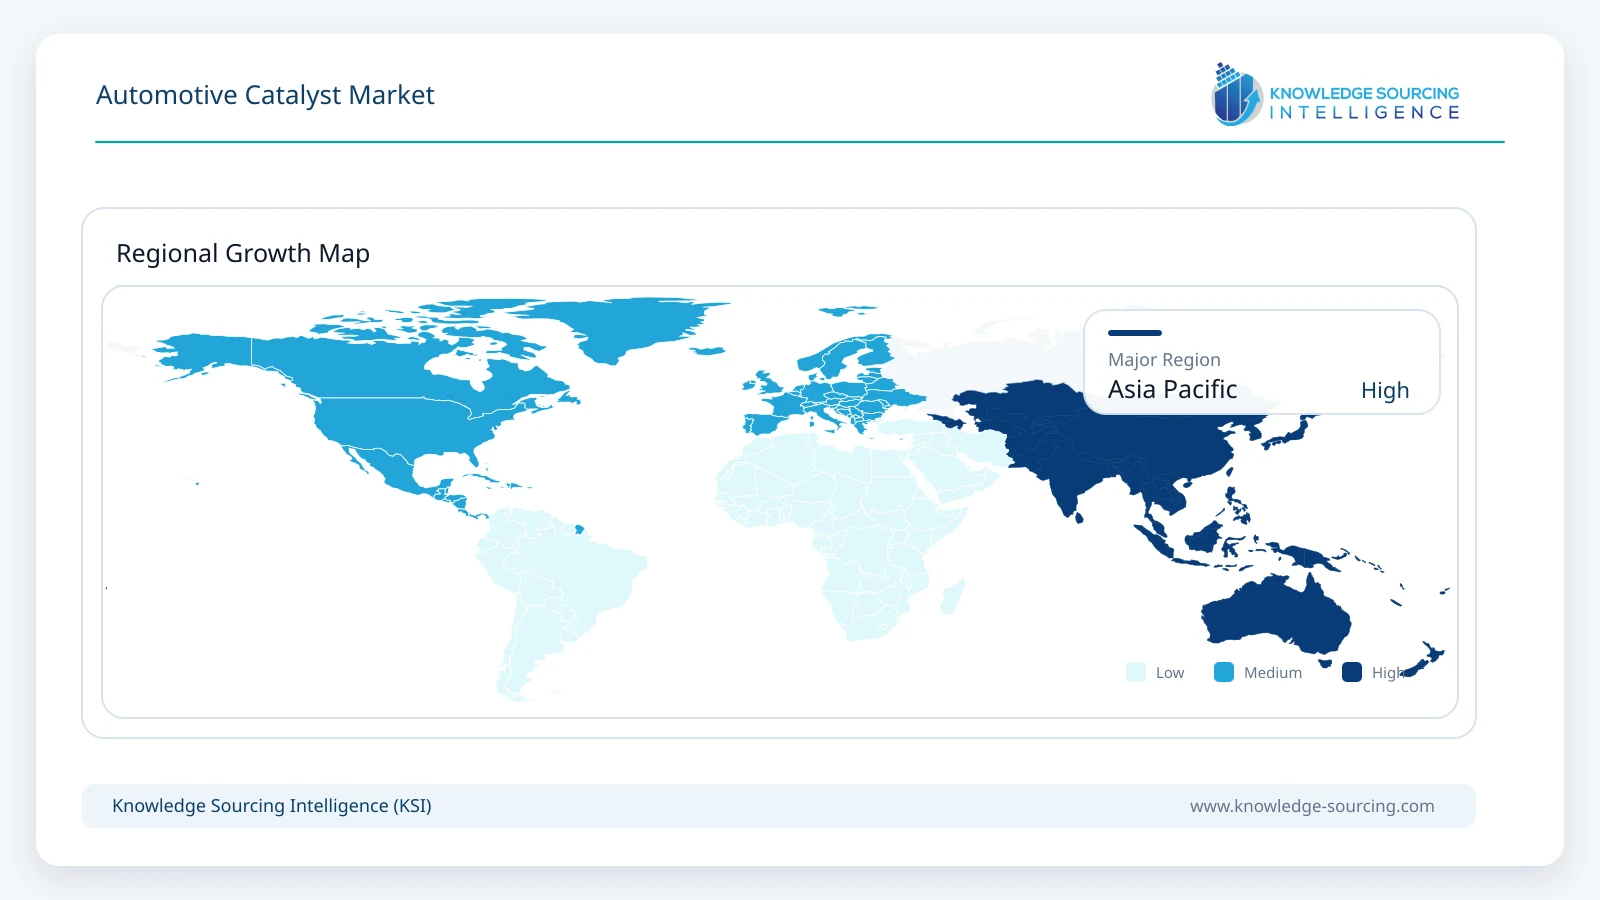
Asia Pacific accounts for an estimated 49% of global catalyst revenue in 2026. China’s scale in vehicle assembly and India’s expanding automotive production underpin regional demand, while Japan and South Korea host established powertrain and catalyst engineering capabilities. OICA places China and India among the largest vehicle-production centres in 2025, although their rising electric-vehicle output means that production volume cannot be directly converted into exhaust-catalyst sales.
The regional market is modelled at approximately USD 8.78 billion in 2031. India’s real-driving emissions requirements support technically sophisticated catalysts, and China’s large hybrid and commercial-vehicle base retains a meaningful combustion-exhaust opportunity. Competitive pricing, domestic supplier capability and rapid battery-electric adoption moderate the region’s value growth relative to its overall vehicle manufacturing weight.
South America
Brazil anchors South American automotive-catalyst demand, with Argentina adding a smaller but established vehicle-production and replacement base. Passenger-car and light-commercial programs provide the principal installation volumes, while heavy-duty trucks add value through larger aftertreatment assemblies. Different fuel blends and operating conditions create a need for regionally qualified coating solutions rather than wholesale adoption of a single global engine calibration.
The region is projected to expand at approximately 11.9% annually over 2026–2031, faster than the global market from a comparatively modest revenue base. A rising share of catalyst-equipped vehicles, modernized emissions compliance and the opportunity to localize higher-value supplier content support the scenario. Growth is not assured: exchange-rate volatility and uneven automotive output could materially alter its trajectory.
Competitive Landscape
Metivo, part of BASF Group, competes through its mobile emissions catalyst expertise and global materials-management network. The business adopted the Metivo brand in September 2026 while retaining its underlying legal entities. Its development portfolio spans gasoline and diesel catalysts and highlights a next-generation copper-zeolite SCR technology intended for forthcoming heavy-duty requirements. This combination of precious-metal management and washcoat engineering creates a broader customer relationship than coating supply alone.
Umicore operates across gasoline, diesel, heavy-duty and motorcycle catalysts, supported by recycling activities that allow recovered metals to re-enter supply. Its 2026 reporting indicates that Automotive Catalysts held volumes and revenues relatively steady despite the broader combustion-market headwind. Johnson Matthey retains a leading Clean Air automotive franchise and has disclosed a significant hybrid gasoline platform award. Cataler and Heesung Catalysts offer specialized coating portfolios, including gasoline TWC, particulate filtration and diesel SCR products.
Smaller specialist manufacturers include INTERKAT, which coats catalysts for on-road and retrofit applications, and DCL, whose vertically integrated operations include proprietary catalyst coatings for mobile and off-road engines. Mitsui Kinzoku has announced a future motorcycle catalyst manufacturing site in the Philippines, while N.E. CHEMCAT supplies automotive emissions catalysts. Klarius competes in compliant replacement catalytic converters. The distinction between a coated catalyst and a complete exhaust assembly remains material; catalyst share rankings cannot be deduced from group revenue that includes precious-metal trading or stationary systems.
Recent Developments
15 September 2026: Metivo, previously BASF Environmental Catalyst and Metal Solutions, announced its new operating brand while confirming it remained part of BASF Group. The change consolidates its identity across automotive catalyst technology and metals management.
31 July 2026: Umicore reported broadly stable Automotive Catalysts volumes and revenues in its first-half results, with performance ahead of the wider combustion-vehicle trend. The disclosure points to the role of vehicle-platform mix and awarded business in a mature market.
10 June 2026: Johnson Matthey published its 2026 annual report describing a major clean-air catalyst contract awarded during FY2025/26 for a global manufacturer’s hybrid light-duty gasoline platform. The program demonstrates continued OEM sourcing for hybrid-specific catalyst content.
28 May 2026: BASF’s Environmental Catalyst and Metal Solutions factbook update described GenV+ copper-zeolite SCR technology as technically qualified by several global truck customers, with intended application in future emissions-compliance platforms. Qualification does not itself establish series-production shipments.
13 May 2026: Mitsui Kinzoku announced plans to establish a motorcycle exhaust-catalyst manufacturing and sales base in the Philippines, with operations scheduled for November 2027. The decision targets Southeast Asian two-wheeler demand.
30 April 2026: Umicore reported that automotive-catalyst activity had exceeded the light-duty vehicle-market trend, supported by business in Europe, China and India, alongside increased heavy-duty diesel volumes in Europe and China.
Market Outlook
Catalyst manufacturers are moving toward a market in which the number of eligible combustion vehicles grows less reliably than the engineering value of their exhaust systems. Hybrid powertrains require dependable cold-start control; heavy-duty trucks need low-temperature reduction, prolonged durability and accurate ammonia management. Coating suppliers that can solve these requirements without excessive precious-metal consumption will be better positioned for multi-year OEM awards.
Asia Pacific remains the principal volume centre, while faster percentage growth in South America is feasible from a smaller base. Over the longer term, battery-electric adoption will reduce the installed opportunity for exhaust catalysts, particularly in light-duty vehicles. Suppliers able to operate efficient global plants, fund demanding qualification programmes and coordinate metals recovery should retain competitive advantages even as the overall industry becomes more selective.
Automotive Catalyst Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 14.6 billion |
| Total Market Size in 2031 | USD 18.3 billion |
| Forecast Unit | Billion |
| Growth Rate | 4.6% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Vehicle Type, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Three-way Catalyst
Oxidation Catalyst
Others: SCR, Catalysed Filters and Other Formulations
By Vehicle Type
Passenger Cars and SUVs
Light-duty Commercial Vehicle
Heavy-duty Commercial Vehicle
Utility Task Vehicle (UTV)
Motorbikes
Others
By Geography
Asia Pacific
China
India
Japan
South Korea
Others
Europe
Germany
United Kingdom
France
Spain
Others
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Middle East and Africa
Saudi Arabia
Israel
South Africa
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Real-world emissions compliance is increasing formulation requirements
3.1.2. Hybrid vehicle programmes retain a large catalyst installation base
3.1.3. Heavy-duty aftertreatment value rises with chemical complexity
3.1.4. Localized catalyst development shortens OEM qualification cycles
3.1.5. Replacement demand supports revenue outside vehicle assembly
3.2. Market Restraints
3.2.1. Battery-electric vehicle adoption removes tailpipe catalyst demand
3.2.2. Precious-metal price fluctuations complicate quotations and inventory
3.2.3. Platform qualification creates substantial switching costs
3.2.4. Changing regulations increase investment uncertainty
3.2.5. OEM cost reduction pressures coating economics
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Three-Way and Low-Temperature Catalyst Chemistry
4.2. Diesel Oxidation and Selective Catalytic Reduction
4.3. Catalyzed Particulate Filters and Secondary Emissions
5. AUTOMOTIVE CATALYST MARKET BY TYPE
5.1. Introduction
5.2. Three-way Catalyst
5.3. Oxidation Catalyst
5.4. Others: SCR, catalysed filters and other formulations
6. AUTOMOTIVE CATALYST MARKET BY VEHICLE TYPE
6.1. Introduction
6.2. Passenger Cars and SUVs
6.3. Light-duty Commercial Vehicle
6.4. Heavy-duty Commercial Vehicle
6.5. Utility Task Vehicle (UTV)
6.6. Motorbikes
6.7. Others
7. AUTOMOTIVE CATALYST MARKET BY GEOGRAPHY
7.1. Introduction
7.2. Asia Pacific
7.2.1. China
7.2.2. India
7.2.3. Japan
7.2.4. South Korea
7.2.5. Others
7.3. Europe
7.3.1. Germany
7.3.2. United Kingdom
7.3.3. France
7.3.4. Spain
7.3.5. Others
7.4. North America
7.4.1. United States
7.4.2. Canada
7.4.3. Mexico
7.5. South America
7.5.1. Brazil
7.5.2. Argentina
7.5.3. Others
7.6. Middle East and Africa
7.6.1. Saudi Arabia
7.6.2. Israel
7.6.3. South Africa
7.6.4. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Metivo (BASF Group)
9.2. Umicore SA
9.3. Johnson Matthey Plc
9.4. Cataler Corporation
9.5. Heesung Catalysts Corporation
9.6. Mitsui Kinzoku Company, Limited
9.7. N.E. CHEMCAT Corporation
9.8. INTERKAT Catalyst GmbH
9.9. Klarius Products Ltd
9.10. DCL International Inc.
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key Benefits for Stakeholders
10.5. Research Methodology
10.6. Abbreviations





Frequently asked questions
What is the projected market size and growth rate for automotive catalysts?
Market projected to reach USD 18.3 billion by 2031, growing at 4.6% CAGR.
Which region remains dominant in automotive catalyst production?
Asia Pacific remains the dominant production-linked region despite BEV penetration.
What factors increasingly shape supplier differentiation in the market?
Platinum-group-metal efficiency and validated durability increasingly shape supplier differentiation.
How do hybrid vehicles influence demand for automotive catalysts?
Hybrid gasoline platforms preserve demand for rapid-light-off coatings.
What are the key requirements for heavy-duty catalyst applications?
Heavy-duty specifications combine NOx reduction, oxidation, and ammonia-slip control.
Cite this report
Knowledge Sourcing Intelligence. (Nov 2026). Automotive Catalyst Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/automotive-catalyst-market