
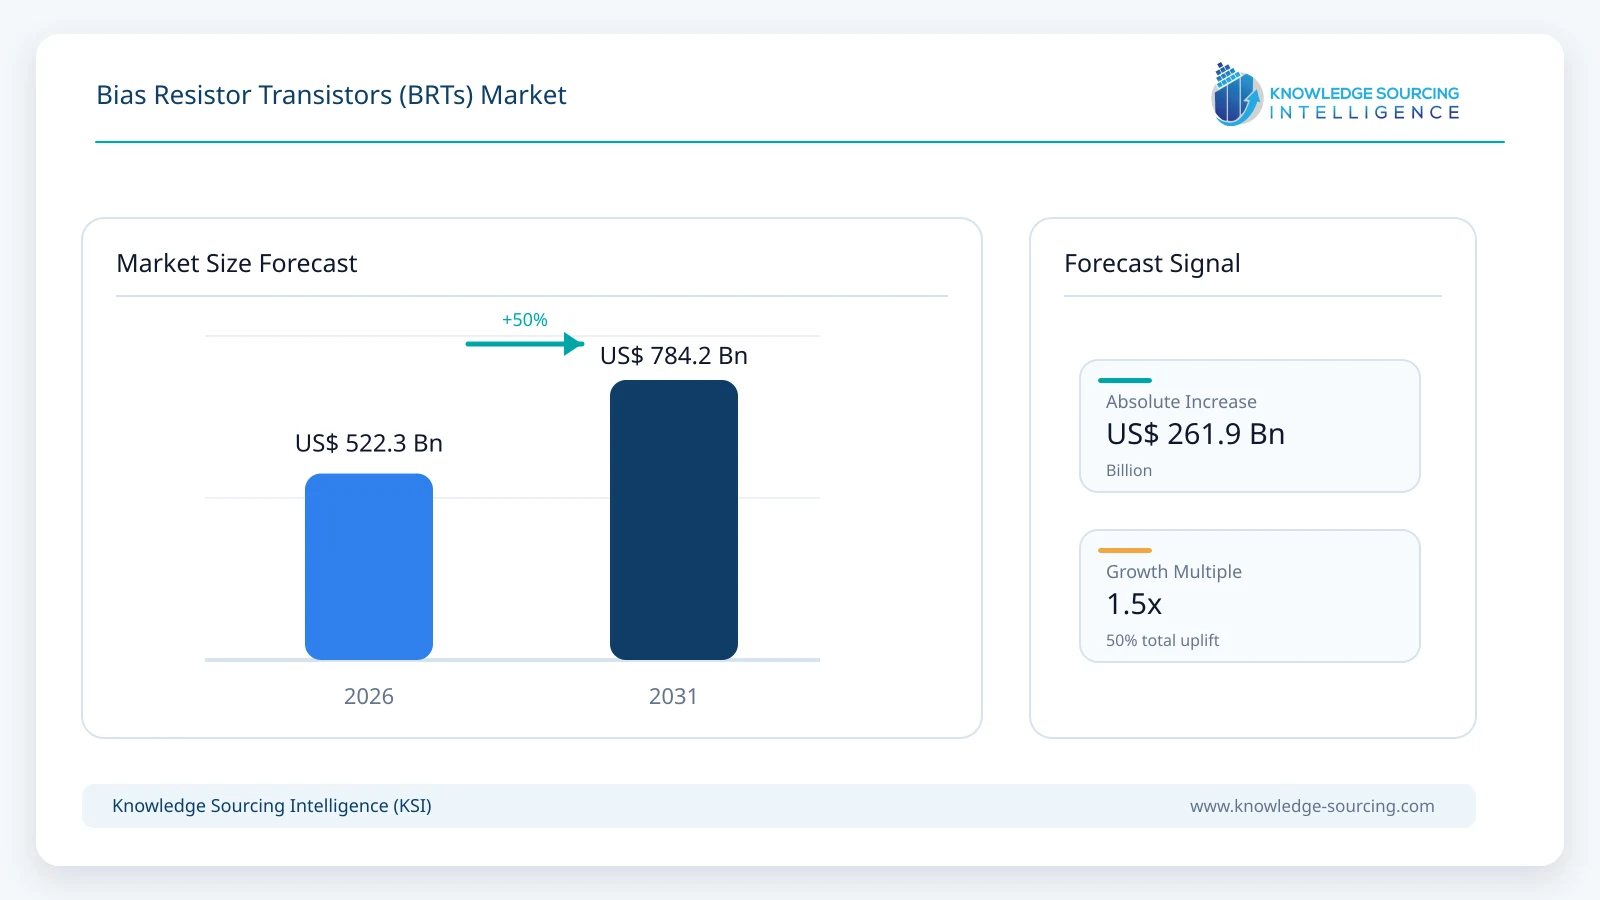
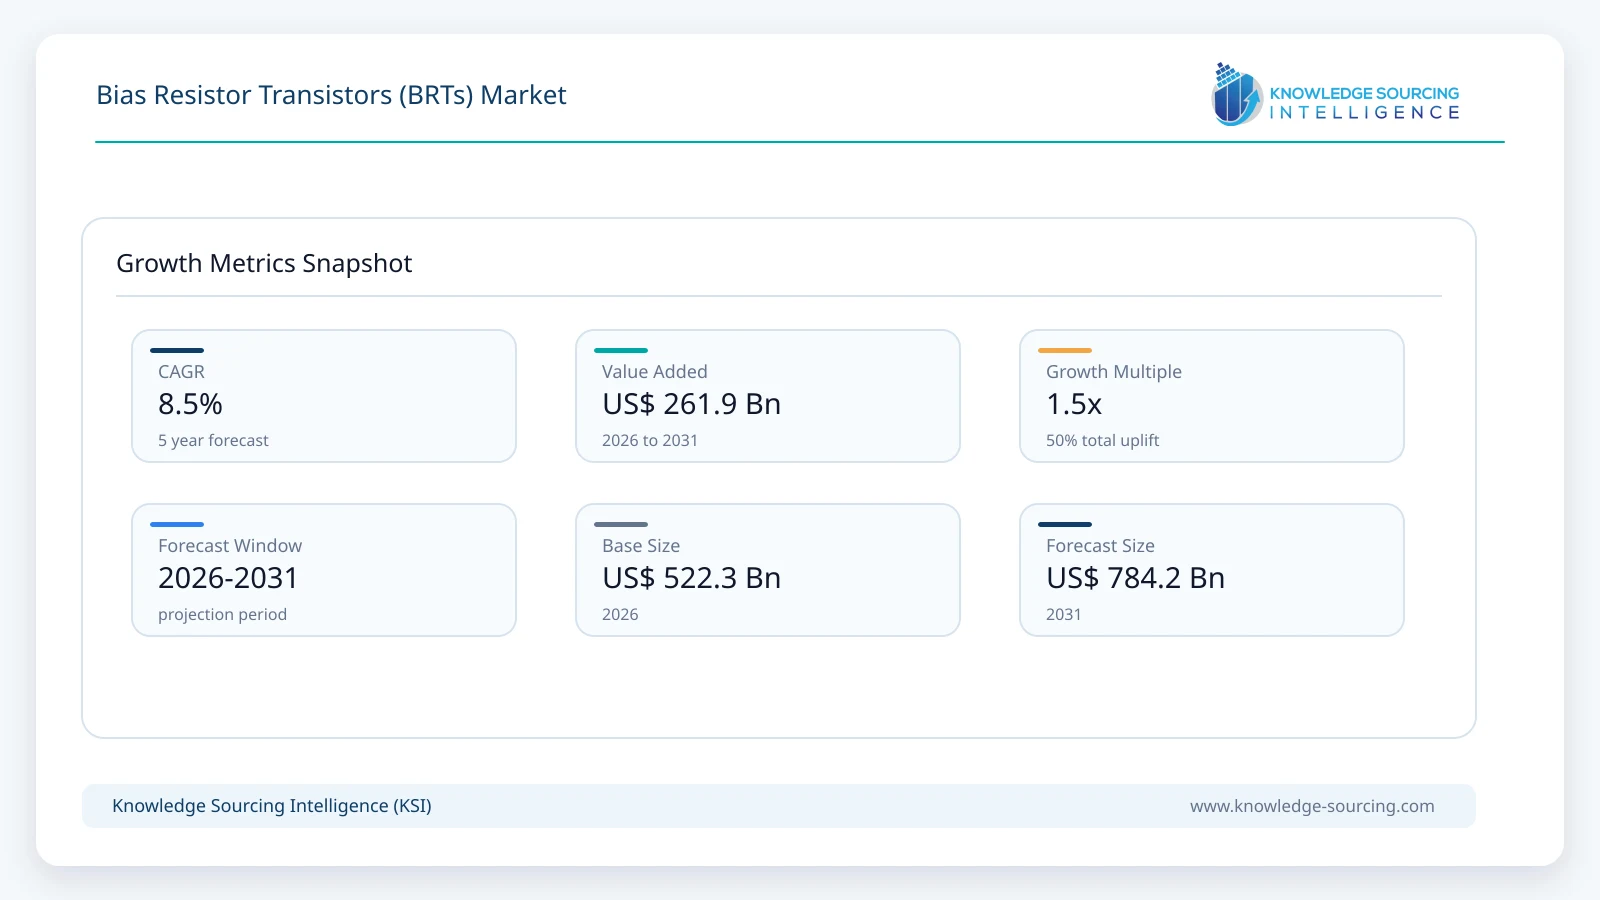
The Bias Resistor Transistors (BRTs) Market is forecast to grow at a CAGR of 8.5%, reaching USD 784.2 million in 2031 from USD 522.3 million in 2026.
Highlights:
- 1Integrated bias resistors reduce external component count, supporting compact electronic circuit designs.
- 2Automotive electronics and consumer devices remain the primary demand centers for BRT adoption.
- 3Asia Pacific benefits from concentrated semiconductor manufacturing and electronics assembly ecosystems.
- 4Product differentiation increasingly depends on package miniaturization, reliability, and automotive-grade qualification.
- 5Supply strategies emphasize long product lifecycles, stable component availability, and broad design support.
- 6Competition remains focused on discrete semiconductor portfolios rather than standalone BRT offerings.
Market Overview
The configuration simplifies circuit design, reduces printed circuit board (PCB) area, lowers assembly complexity, and minimizes component count for switching applications. Their commercial relevance is strongest in cost-sensitive, space-constrained electronic products where design simplicity, manufacturing efficiency, and long-term reliability remain important purchasing considerations.
Demand is primarily generated by manufacturers of automotive electronic control units, consumer electronics, industrial control systems, telecommunications equipment, computing peripherals, and medical devices. Purchasing decisions typically prioritize electrical characteristics, resistor tolerance, package dimensions, qualification standards, lifecycle availability, and compatibility with automated surface-mount manufacturing. Buyers generally favor suppliers capable of maintaining consistent product specifications across long production cycles, particularly in automotive and industrial applications where redesign costs are high.
Commercial value within the market extends beyond the semiconductor device itself. Suppliers compete by offering extensive package options, application support, qualification documentation, simulation models, and long-term product availability. The relatively modest selling price of individual BRT devices places greater emphasis on manufacturing efficiency, yield optimization, and broad distribution networks than on premium pricing.
Although low-power MOSFETs increasingly replace BRTs in selected switching applications because of lower power consumption and faster switching performance, integrated resistor transistors continue to provide an attractive solution where simplified circuitry, predictable switching behavior, and lower bill-of-material costs outweigh the benefits of alternative switching technologies. This balance continues to sustain demand across mature electronic product categories.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
Primary device function | Integrated switching transistor with built-in bias resistors | Eliminates external bias resistors, reducing PCB complexity. |
Typical application | Electronic switching circuits | Well suited for compact, cost-sensitive electronic assemblies. |
End-use industries | Automotive, consumer, industrial, communications | Demand depends on discrete semiconductor consumption across multiple equipment sectors. |
Technology trend | Partial substitution by low-power MOSFETs | Suppliers must differentiate through reliability, packaging, and lifecycle support rather than switching performance alone. |
Automotive qualification | AEC-Q qualified BRT families available | Automotive-grade products support higher-value applications and longer product lifecycles. |
Key indicator: BRTs integrate both a base resistor and a base-emitter resistor within a single transistor package.
Commercial meaning: Integration reduces assembly steps, lowers component count, and simplifies high-volume electronics manufacturing.
Market Drivers
Miniaturization of electronic assemblies and component count reduction.
Electronic manufacturers continue to reduce PCB size while increasing circuit density across automotive modules, wearable devices, industrial controllers, and consumer products. A BRT replaces multiple discrete components with a single package, lowering placement operations during automated assembly and improving manufacturing efficiency. Toshiba describes BRTs as devices specifically intended to simplify discrete circuit configurations through integrated bias resistors, making them attractive where board space and assembly cost remain critical design considerations. Suppliers continue expanding compact package portfolios to support these requirements across high-volume electronics production.
Growing electronic content in automotive systems.
Modern vehicles incorporate an increasing number of electronic control functions covering lighting, body electronics, infotainment, battery management, driver assistance, and powertrain control. Many of these systems require reliable low-power switching components with stable long-term performance. Automotive-qualified BRT portfolios demonstrate continued supplier commitment to this application segment. Manufacturers such as Toshiba and KEC offer AEC-qualified digital transistors designed for automotive operating environments, reflecting sustained customer demand for highly reliable discrete semiconductor solutions that simplify circuit design while meeting automotive quality requirements.
Continued production of mature consumer electronics platforms.
Although semiconductor innovation increasingly emphasizes advanced processors and power devices, high-volume consumer products continue to require dependable discrete switching components for power management, display control, signal switching, and interface circuits. Home appliances, television systems, chargers, adapters, and portable electronic products remain important end-use categories. Standardized BRT devices provide manufacturers with proven electrical characteristics, broad second-source availability, and simplified production processes, making them attractive for products where manufacturing cost and supply continuity receive greater priority than adopting newer switching architectures.
Broad product portfolios and long lifecycle support from semiconductor manufacturers.
Competition within discrete semiconductors increasingly depends on supporting customers throughout lengthy product development and manufacturing cycles. Established suppliers including Toshiba, ROHM Semiconductor, onsemi, Infineon Technologies, Diodes Incorporated, and Yea Shin Technology maintain extensive discrete semiconductor portfolios rather than offering isolated BRT products. Supporting documentation, simulation models, environmental compliance certificates, reliability reports, and long-term product availability reduce engineering risk and encourage repeat procurement from established suppliers. This ecosystem strengthens purchasing confidence, particularly among industrial and automotive equipment manufacturers managing products with operating lives extending beyond a decade.
Market Restraints and Challenges
Replacement by low-power MOSFETs in new electronic designs.
Design engineers increasingly evaluate low-power MOSFETs alongside BRTs because MOSFETs generally offer lower power consumption, higher switching speed, and reduced drive current in many low-voltage applications. Toshiba notes that MOSFETs can replace BRTs where improved switching efficiency and lower losses justify a circuit redesign. This substitution does not eliminate demand for BRTs, but it narrows opportunities in newly developed products. Suppliers therefore concentrate on applications where circuit simplicity, lower component count, and established design libraries remain more valuable than incremental performance gains.
Limited product differentiation and pricing pressure.
BRTs are standardized discrete semiconductor devices with relatively mature manufacturing processes. Electrical specifications, package options, and resistor configurations are comparable across several suppliers, making product substitution feasible after customer qualification. Automotive and industrial customers often negotiate long-term supply agreements that emphasize pricing stability and assured availability. As a result, manufacturers face pressure to improve production efficiency, manufacturing yield, and distribution coverage instead of relying on premium pricing. Companies increasingly differentiate through quality certifications, technical support, package miniaturization, and lifecycle management rather than device functionality alone.
Qualification requirements extend product introduction timelines.
Automotive, medical, and industrial equipment manufacturers impose rigorous validation before approving new semiconductor suppliers or component revisions. Compliance with standards such as AEC-Q qualification, reliability testing, environmental performance, and customer-specific validation can lengthen product approval cycles. These requirements increase development costs for suppliers while delaying revenue generation from newly introduced products. Although qualification creates barriers to entry that benefit established manufacturers, it also raises engineering and documentation costs across the industry.
Supply chain exposure within the broader semiconductor industry.
Although BRTs are relatively mature products, their manufacturing remains dependent on semiconductor fabrication capacity, assembly services, leadframe materials, packaging compounds, and logistics networks shared with other discrete semiconductor devices. Several global semiconductor manufacturers have identified supply-chain disruptions, geopolitical uncertainty, raw-material availability, and extended customer planning cycles as operational risks in recent annual reports. These factors can influence delivery schedules and inventory strategies, particularly for customers requiring long-term production continuity across automotive and industrial programs.
Major Segment Analysis
Automotive Application
Automotive electronics represent the most commercially important application segment for Bias Resistor Transistors because vehicle manufacturers continue expanding electronic control functions across lighting systems, body electronics, climate control modules, infotainment, battery management, and auxiliary switching circuits. In these applications, purchasing priorities extend beyond electrical performance to include long-term component availability, qualification status, reliability, and stable manufacturing support throughout vehicle production cycles. Suppliers offering AEC-Q-qualified BRT portfolios are better positioned to participate in automotive sourcing programs, where component replacement after design approval is both costly and time-consuming.
Unlike consumer electronics, where product lifecycles are relatively short and component redesign occurs frequently, automotive programs often remain in production for several years. This creates sustained demand for standardized BRT devices with proven field performance and comprehensive quality documentation. Competition therefore depends not only on pricing but also on manufacturing consistency, global distribution capability, and engineering support. While industrial equipment and telecommunications continue to provide steady demand, automotive applications generally require higher qualification standards and longer supplier commitments, making this segment strategically important for manufacturers participating in the broader discrete semiconductor market.
Regional Analysis
Region | Main Demand Signal | Principal Constraint |
North America | Automotive electronics, industrial automation, medical equipment | Dependence on global semiconductor supply chains |
Europe | Automotive manufacturing, industrial controls, functional safety requirements | High qualification and regulatory compliance costs |
Asia Pacific | Semiconductor manufacturing, consumer electronics production, automotive assembly | Pricing pressure from regional competition |
Middle East and Africa | Industrial infrastructure, telecommunications, medical equipment imports | Limited domestic semiconductor manufacturing |
North America maintains steady demand through its established automotive, aerospace, industrial automation, and medical device industries. The United States remains the principal regional market because domestic manufacturers require reliable discrete semiconductors for industrial control systems, electronic instrumentation, and vehicle electronics. Government initiatives supporting semiconductor manufacturing capacity, including implementation of the CHIPS and Science Act, are expected to strengthen regional supply resilience over the medium term, although discrete component production continues to rely on globally integrated manufacturing networks.
European demand is closely linked to automotive production, factory automation, renewable energy equipment, and industrial electronics. Germany serves as the region's primary manufacturing hub, while France and the United Kingdom contribute through automotive systems, telecommunications infrastructure, and industrial equipment development. Buyers in Europe generally emphasize product reliability, functional safety, environmental compliance, and long-term supplier support, encouraging manufacturers to maintain certified production processes and comprehensive technical documentation.
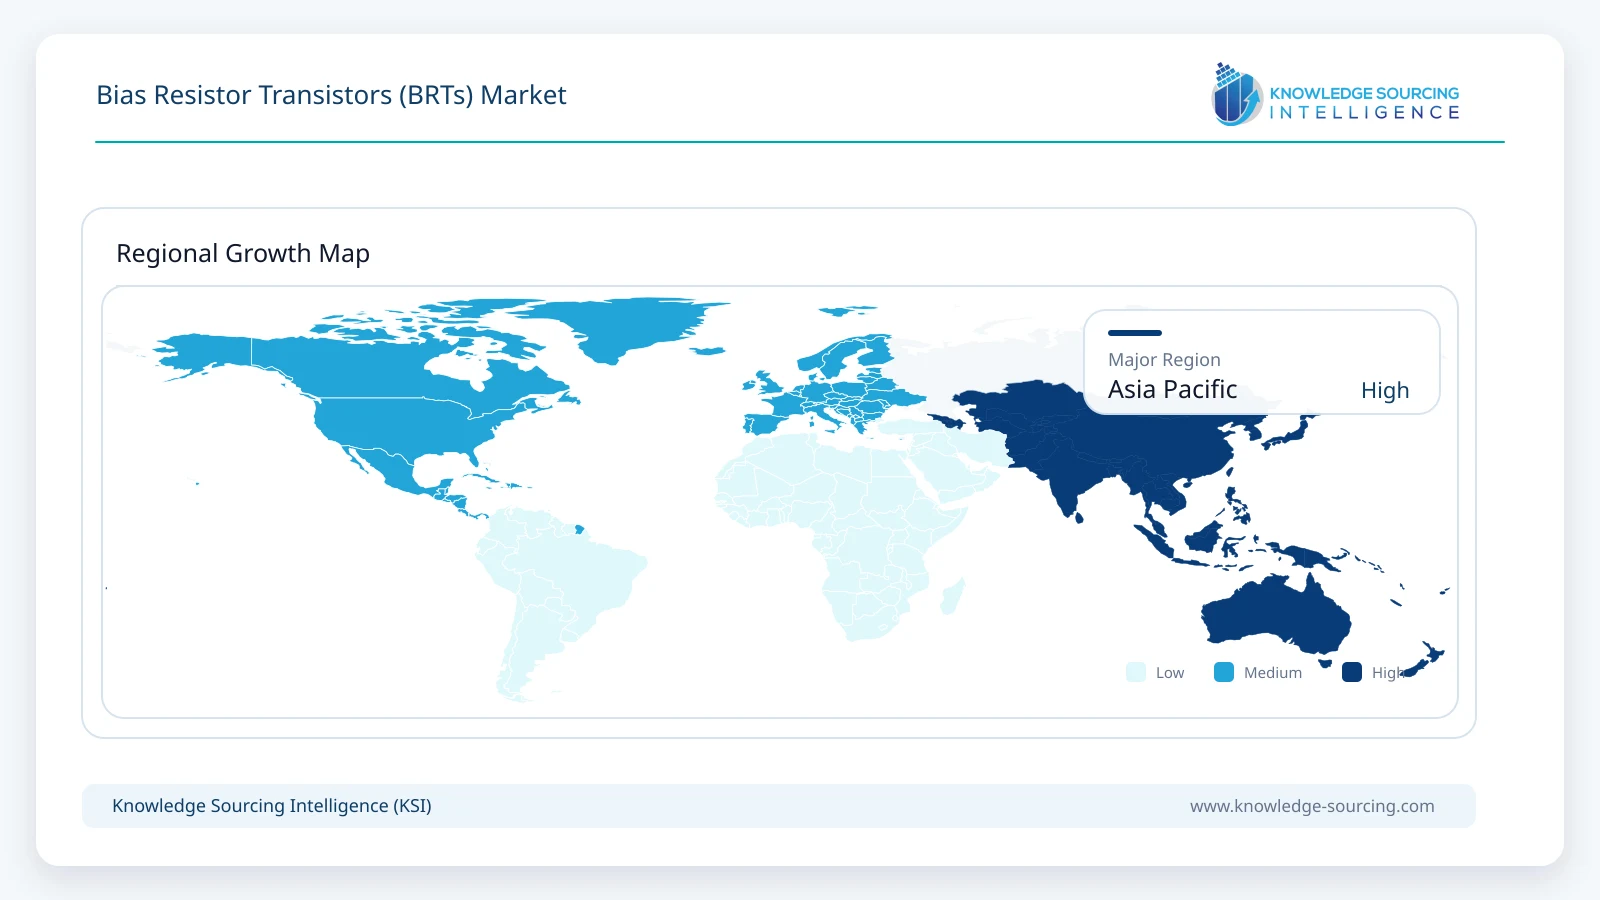
Asia Pacific remains the central manufacturing base for both semiconductor production and downstream electronics assembly. China, Japan, South Korea, and Taiwan host major semiconductor fabrication and packaging operations, while China, India, Indonesia, and other regional economies continue expanding consumer electronics and automotive manufacturing. The concentration of component suppliers, contract manufacturers, and electronics assemblers supports efficient procurement and shorter supply chains. At the same time, intense regional competition encourages suppliers to improve manufacturing efficiency while controlling production costs.
The Middle East and Africa represent a comparatively smaller but commercially relevant market, supported by investment in industrial automation, telecommunications infrastructure, healthcare equipment, and energy projects. Demand is concentrated in countries such as Saudi Arabia, the United Arab Emirates, and Israel, where industrial modernization and digital infrastructure projects continue to increase electronic component requirements. Most semiconductor devices are imported, making regional buyers more sensitive to supply-chain disruptions, logistics costs, and currency fluctuations than manufacturers in established semiconductor production centers.
Competitive Landscape
The Bias Resistor Transistors (BRTs) market is moderately concentrated, with competition shaped by diversified discrete semiconductor manufacturers rather than companies specializing exclusively in BRT devices. Toshiba, ROHM Semiconductor, onsemi, Infineon Technologies, Diodes Incorporated, and Yea Shin Technology compete through broad bipolar transistor portfolios, global distribution networks, automotive-qualified product families, and long-term supply commitments. Because BRTs are mature semiconductor components with standardized electrical characteristics, differentiation depends less on device architecture and more on package miniaturization, manufacturing consistency, reliability data, engineering support, and lifecycle management.
Automotive and industrial customers typically maintain lengthy qualification processes before approving alternative suppliers, creating moderate switching costs once a component has been designed into a product. Established manufacturers continue investing in production efficiency, automated packaging, environmental compliance, and expanded application support to strengthen customer retention. Global distributors also play an important role by ensuring inventory availability, technical documentation, and logistics support across multiple regions. New entrants face barriers associated with customer qualification, quality certification, manufacturing scale, and the ability to provide stable supply over extended product lifecycles rather than fundamental technological complexity.
Recent Developments
March 2026 – Toshiba, ROHM, and Mitsubishi Electric announce semiconductor integration discussions: Toshiba signed a memorandum of understanding with ROHM and Mitsubishi Electric to explore integrating their semiconductor businesses, strengthening discrete semiconductor portfolios that include digital transistors, bipolar devices, and power semiconductors.
December 2025 – ROHM and Tata Electronics establish semiconductor partnership: ROHM formed a strategic partnership with Tata Electronics to develop semiconductor manufacturing capabilities in India, expanding production infrastructure supporting discrete semiconductor devices, including digital transistors and other bipolar semiconductor products.
May 2025 – ROHM and DENSO announce strategic semiconductor partnership: ROHM and DENSO reached a basic agreement to deepen collaboration across semiconductor technologies, supporting long-term development and manufacturing of automotive semiconductor components, including discrete transistor technologies used in vehicle electronics.
Regulatory and Policy Environment
Bias Resistor Transistors are governed primarily by semiconductor quality, environmental, product safety, and automotive qualification standards rather than market-specific regulations. Compliance with AEC-Q101 qualification remains an important purchasing requirement for automotive applications, as vehicle manufacturers require semiconductor devices capable of operating under demanding environmental and reliability conditions. Suppliers serving this market must demonstrate extensive electrical, mechanical, and thermal qualification before components are accepted into production programs.
Environmental legislation also influences product development and manufacturing practices. Compliance with the Restriction of Hazardous Substances (RoHS) Directive in the European Union and REACH chemical regulations has become a standard commercial requirement across global electronics supply chains. Manufacturers must ensure that semiconductor packages, lead finishes, and manufacturing materials satisfy evolving environmental restrictions while maintaining long-term reliability.
Government policies supporting domestic semiconductor manufacturing are also reshaping industry investment patterns. Programs such as the United States CHIPS and Science Act, the European Chips Act, and semiconductor manufacturing initiatives across Japan, South Korea, Taiwan, and China encourage capacity expansion, supply-chain resilience, and local production. Although these initiatives target the broader semiconductor industry rather than BRTs specifically, increased investment in wafer fabrication, assembly, packaging, and testing benefits discrete semiconductor availability over the forecast period.
Outlook and Strategic Implications
Demand for Bias Resistor Transistors is expected to remain closely tied to production volumes across automotive electronics, industrial equipment, consumer devices, telecommunications hardware, and computing peripherals rather than the introduction of entirely new semiconductor architectures. The market will continue to benefit from applications where integrated bias resistors reduce circuit complexity, minimize assembly steps, and lower overall manufacturing costs. Mature electronic platforms, long product lifecycles, and replacement demand are expected to provide a stable commercial base despite increasing adoption of alternative switching technologies in selected applications.
Competitive priorities are likely to shift further toward manufacturing efficiency, qualification support, package miniaturization, and supply assurance. Automotive and industrial customers are expected to place greater emphasis on long-term availability, documented reliability, and regional supply resilience when selecting semiconductor suppliers. Companies capable of maintaining broad discrete semiconductor portfolios while offering consistent technical support and global distribution networks should remain well positioned.
Key strategic implications include:
Manufacturers: Expand automotive-qualified portfolios, improve manufacturing efficiency, and maintain long product lifecycle support.
Automotive and industrial OEMs: Prioritize suppliers with proven quality systems, stable production capacity, and comprehensive qualification documentation.
Distributors: Strengthen inventory management and technical support as customers seek dependable long-term component availability.
Investors: Monitor broader semiconductor capital investment and automotive electronics production, as these factors will influence future BRT demand more than standalone product innovation.
Policymakers: Continued support for semiconductor manufacturing and resilient supply chains can reduce sourcing risks for discrete electronic components used across multiple industrial sectors.
Rather than being driven by breakthrough device innovation, the Bias Resistor Transistors market is expected to evolve through incremental improvements in manufacturing quality, package design, qualification standards, and supply-chain resilience. These factors will continue to shape procurement decisions and competitive positioning throughout the 2026-2031 forecast period.
Bias Resistor Transistors (BRTs) Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 522.3 million |
| Total Market Size in 2031 | USD 784.2 million |
| Forecast Unit | USD Million |
| Growth Rate | 8.5% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Application, Geography |
| Companies |
|
Market Segmentation
By Type
PNP Type
NPN Type
By Application
Automobile
Consumer Electronics
Industrial Equipment
Telecommunications
Computing and Peripherals
Medical Devices
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
Others
Asia Pacific
China
Japan
India
South Korea
Indonesia
Taiwan
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits to the Stakeholder
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Process
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter’s Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
4.5. Analyst View
5. BIAS RESISTOR TRANSISTORS (BRTS) MARKET BY TYPE
5.1. Introduction
5.2. PNP Type
5.2.1. Market opportunities and trends
5.2.2. Growth prospects
5.2.3. Geographic lucrativeness
5.3. NPN Type
5.3.1. Market opportunities and trends
5.3.2. Growth prospects
5.3.3. Geographic lucrativeness
6. BIAS RESISTOR TRANSISTORS (BRTS) MARKET BY APPLICATION
6.1. Introduction
6.2. Automobile
6.2.1. Market opportunities and trends
6.2.2. Growth prospects
6.2.3. Geographic lucrativeness
6.3. Consumer Electronics
6.3.1. Market opportunities and trends
6.3.2. Growth prospects
6.3.3. Geographic lucrativeness
6.4 Industrial Equipment
6.4.1. Market opportunities and trends
6.4.2. Growth prospects
6.4.3. Geographic lucrativeness
6.5. Telecommunications
6.5.1. Market opportunities and trends
6.5.2. Growth prospects
6.5.3. Geographic lucrativeness
6.6. Computing and Peripherals
6.6.1. Market opportunities and trends
6.6.2. Growth prospects
6.6.3. Geographic lucrativeness
6.7. Medical Devices
6.7.1. Market opportunities and trends
6.7.2. Growth prospects
6.7.3. Geographic lucrativeness
6.8. Others
6.8.1. Market opportunities and trends
6.8.2. Growth prospects
6.8.3. Geographic lucrativeness
7. BIAS RESISTOR TRANSISTORS (BRTS) MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. By Type
7.2.2. By Application
7.2.3. By Country
7.2.3.1. United States
7.2.3.1.1. Market Trends and Opportunities
7.2.3.1.2. Growth Prospects
7.2.3.2. Canada
7.2.3.2.1. Market Trends and Opportunities
7.2.3.2.2. Growth Prospects
7.2.3.3. Mexico
7.2.3.3.1. Market Trends and Opportunities
7.2.3.3.2. Growth Prospects
7.3. South America
7.3.1. By Type
7.3.2. By Application
7.3.3. By Country
7.3.3.1. Brazil
7.3.3.1.1. Market Trends and Opportunities
7.3.3.1.2. Growth Prospects
7.3.3.2. Argentina
7.3.3.2.1. Market Trends and Opportunities
7.3.3.2.2. Growth Prospects
7.3.3.3. Others
7.3.3.3.1. Market Trends and Opportunities
7.3.3.3.2. Growth Prospects
7.4. Europe
7.4.1. By Type
7.4.2. By Application
7.4.3. By Country
7.4.3.1. Germany
7.4.3.1.1. Market Trends and Opportunities
7.4.3.1.2. Growth Prospects
7.4.3.2. France
7.4.3.2.1. Market Trends and Opportunities
7.4.3.2.2. Growth Prospects
7.4.3.3. United Kingdom
7.4.3.3.1. Market Trends and Opportunities
7.4.3.3.2. Growth Prospects
7.4.3.4. Spain
7.4.3.4.1. Market Trends and Opportunities
7.4.3.4.2. Growth Prospects
7.4.3.5. Others
7.4.3.5.1. Market Trends and Opportunities
7.4.3.5.2. Growth Prospects
7.5. Middle East and Africa
7.5.1. By Type
7.5.2. By Application
7.5.3. By Country
7.5.3.1. Saudi Arabia
7.5.3.1.1. Market Trends and Opportunities
7.5.3.1.2. Growth Prospects
7.5.3.2. UAE
7.5.3.2.1. Market Trends and Opportunities
7.5.3.2.2. Growth Prospects
7.5.3.3. Israel
7.5.3.3.1. Market Trends and Opportunities
7.5.3.3.2. Growth Prospects
7.5.3.4. Others
7.5.3.4.1. Market Trends and Opportunities
7.5.3.4.2. Growth Prospects
7.6. Asia Pacific
7.6.1. By Type
7.6.2. By Application
7.6.3. By Country
7.6.3.1. China
7.6.3.1.1. Market Trends and Opportunities
7.6.3.1.2. Growth Prospects
7.6.3.2. Japan
7.6.3.2.1. Market Trends and Opportunities
7.6.3.2.2. Growth Prospects
7.6.3.3. India
7.6.3.3.1. Market Trends and Opportunities
7.6.3.3.2. Growth Prospects
7.6.3.4. South Korea
7.6.3.4.1. Market Trends and Opportunities
7.6.3.4.2. Growth Prospects
7.6.3.5. Indonesia
7.6.3.5.1. Market Trends and Opportunities
7.6.3.5.2. Growth Prospects
7.6.3.6. Taiwan
7.6.3.6.1. Market Trends and Opportunities
7.6.3.6.2. Growth Prospects
7.6.3.7. Others
7.6.3.7.1. Market Trends and Opportunities
7.6.3.7.2. Growth Prospects
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisition, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Toshiba
9.2. Rohm Semiconductor
9.3. Onsemi
9.4. Infineon Technologies
9.5. Diode Incorporated
9.6. Yea Shin Technology
LIST OF FIGURES
LIST OF TABLES
Navigate
Trusted by the world's leading organizations











