
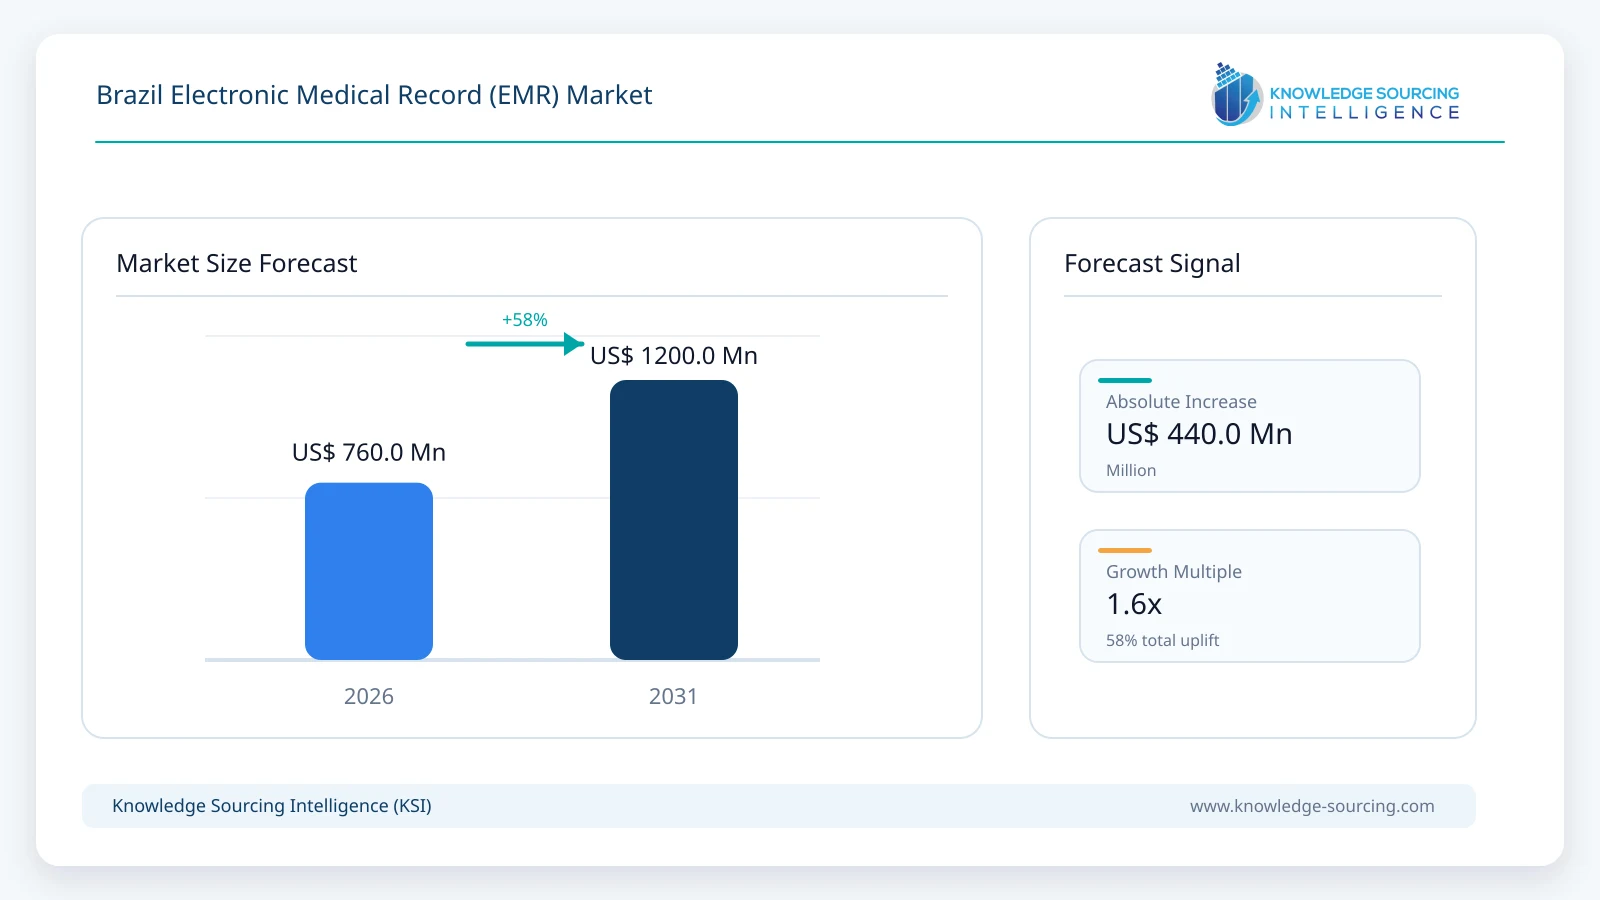
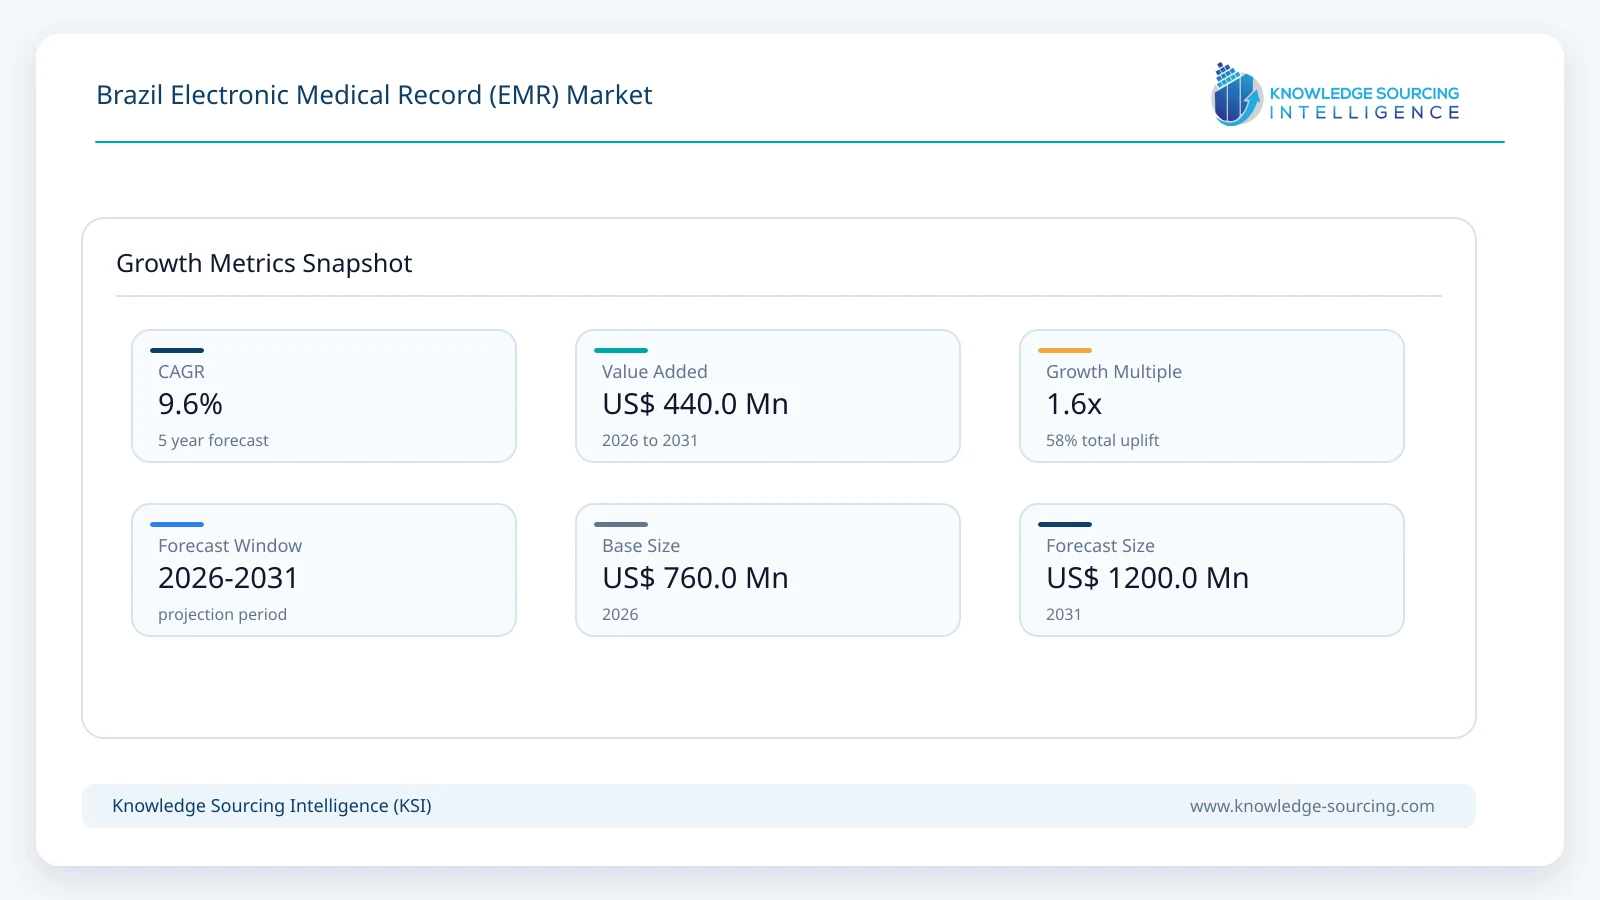
The Brazil electronic medical record market is forecast to grow at a CAGR of 9.6%, reaching USD 1,200.0 million in 2031 from USD 760.0 million in 2026.
Highlights:
- 1Web-based EMR platforms account for approximately 63% of market revenue in 2026.
- 2Hospitals generate about 45% of 2026 EMR spending across major end-user categories.
- 3Subscription-based services represent roughly 34% of market revenue in 2026.
- 4RNDS now contains more than five billion records across Brazil’s public digital-health infrastructure.
- 5Private medical plans covered more than 53 million beneficiaries during mid-2026.
- 6Interoperability, cloud migration and AI-assisted documentation are becoming core procurement requirements.
Market Overview
Brazil combines one of Latin America's largest healthcare systems with a rapidly maturing digital-health infrastructure. The RNDS has become the national interoperability layer for public health information and contained more than five billion records by August 2026. In primary care, the e-SUS APS electronic record continues to receive frequent updates covering prescriptions, vaccinations, maternal care, clinical measurements, and reporting. These public systems do not translate directly into commercial EMR revenue, but they raise the baseline expectation that patient information should be structured, portable and available across care settings. The August 2026 approval of a National Information and Digital Health Policy further reinforces integration of clinical information, telehealth and longitudinal patient histories across municipal, state and federal networks.
The private market is equally important. Brazil had approximately 53.1 million beneficiaries in medical health plans in mid-2026, supporting a large network of hospitals, clinics, laboratories and specialty providers that require clinical documentation and administrative integration. Large hospital groups increasingly operate across multiple cities and states, which favors platforms capable of standardizing records, orders, medication workflows, revenue-cycle processes, and reporting across sites. Philips expanded Tasy EMR across Rede D'Or in 2025, while domestic vendors such as MV, Pixeon, Wareline and SPDATA compete alongside Dedalus, TOTVS and specialist ambulatory platforms. The competitive focus is shifting from digitizing paper charts toward building a single operational and clinical record that can exchange data with diagnostic systems, payer workflows and national interoperability services. Growth through 2031 is expected to remain strongest in cloud migration, multi-site standardization, interoperability services and recurring software contracts, while first-time enterprise EMR adoption becomes a smaller part of total spending.
Selected Segment Estimates
Dimension | Selected Subsegment | 2026 Indicator | Forecast Interpretation |
Product | Web-Based | ~63% share | Remains the leading deployment model as providers prioritize remote access and lower infrastructure requirements. |
End User | Hospitals | ~45% share | Largest spending pool due to broad clinical workflows, integration depth and multi-department requirements. |
Services Offered | Subscriptions | ~34% share | Recurring subscription models gain share as cloud and SaaS adoption expands across hospitals and clinics. |
End User | Physician Clinics | ~18% share | Smaller deployments expand through cloud products, e-prescribing and integrated scheduling. |
Services Offered | Professional Services | ~22% share | Implementation, migration, integration and workflow redesign remain important in larger deployments. |
Market Dynamics
Interoperability Requirements Are Moving EMR Upgrades From Optional to Strategic
Brazil's digital-health architecture increasingly depends on standardized exchange between provider systems and wider public-health infrastructure. RNDS, e-SUS APS and newer SUS Digital services are designed around shared clinical information rather than isolated institutional databases. For hospitals and clinics, this raises the value of EMR platforms that can expose structured records through modern interfaces and connect with laboratory, imaging, pharmacy, billing, and patient-facing applications. Private providers face the same pressure from multi-site operations and payer workflows. The result is a market in which integration capability is becoming a purchasing criterion alongside usability and core clinical documentation.
Cloud Delivery Broadens Adoption Beyond the Largest Hospital Networks
Web-based and cloud-enabled EMR products reduce the need for each provider to maintain large on-site infrastructure and support centralized software updates across multiple locations. The commercial impact is strongest among clinics, ambulatory networks and smaller hospitals that require robust records but cannot support the implementation model traditionally associated with large enterprise hospital systems. Cloud delivery also supports mobile access, telehealth workflows, centralized backup, and faster rollout of new features. Major vendors increasingly combine hosted infrastructure with subscription pricing, creating a more predictable operating-cost model for customers and a larger recurring-revenue component for suppliers.
Integrated Clinical and Financial Workflows Increase Platform Value
EMR purchasing decisions are increasingly tied to hospital productivity rather than documentation alone. Providers want clinical records to connect directly with prescriptions, medication administration, laboratory results, imaging, bed management, surgical scheduling, billing and claims workflows. This reduces repeated data entry and allows operational information to follow the patient throughout the episode of care. Vendors such as MV, Philips Tasy, Pixeon, Dedalus and TOTVS position their systems around this broader integration model. As healthcare groups consolidate facilities and standardize processes, the economic value of a common clinical platform rises because workflow improvements can be replicated across the network.
Data Protection, Migration Complexity and Legacy Integration Remain Constraints
Healthcare records contain highly sensitive information and must remain available continuously, making EMR modernization operationally complex. Providers must manage access controls, audit trails, backups, cybersecurity, data retention and compliance with Brazil's General Data Protection Law while also protecting clinical continuity during system migrations. Large hospitals often operate a mixture of legacy hospital information systems, laboratory platforms, imaging archives and specialty applications that cannot be replaced simultaneously. Integration and data-conversion work can therefore represent a meaningful share of project cost and implementation time. Smaller providers face a different constraint: even lower-cost cloud systems require workflow redesign and staff training before productivity gains are realized.
Segment Analysis
By Product - Web-Based EMR
Web-based EMR is the largest product segment, representing approximately 63% of market value in 2026. Its lead reflects lower local infrastructure requirements, easier multi-site access and the ability to deliver software updates more consistently than traditional client-server deployments. Cloud-native and browser-based architectures are also better suited to distributed care networks, telehealth and mobile clinical access. Dedalus positions Medview EVO as a fully web-based, cloud-native hospital platform, while specialist clinic systems increasingly operate through software-as-a-service models. Client-server systems remain important in large institutions with established data centers and heavily customized workflows, but new procurement increasingly favors architectures that can support hybrid or cloud deployment.
By End User - Hospitals
Hospitals account for approximately 45% of Brazilian EMR revenue in 2026 because they require the deepest integration across clinical and administrative functions. A hospital record must support emergency, inpatient, surgery, nursing, pharmacy, laboratory, imaging, and discharge workflows while maintaining links to billing and payer authorization. Large hospital groups also require enterprise identity management, standardized clinical templates and consolidated reporting across facilities. Philips' continued expansion of Tasy EMR within Rede D'Or illustrates the scale available in multi-site networks, while MV's hospital platform is deployed across public and private institutions. Clinics and ambulatory providers remain a faster-moving volume opportunity, but their average contract value is materially lower.
By Services Offered - Subscriptions
Subscriptions represent approximately 34% of market value in 2026 and are gaining importance as providers move toward cloud delivery. Subscription contracts can bundle software access, hosting, updates, security and support into recurring payments, lowering the initial capital requirement for smaller customers. Larger hospitals continue to combine licensing, implementation and professional services because complex integrations and custom workflows require dedicated project work. Professional services therefore remain a substantial part of market value even as recurring subscriptions expand. Over the forecast period, suppliers with a strong installed base are positioned to grow recurring revenue through cloud migration, additional modules, interoperability services and ongoing support.
Market and Demand Indicators
Indicator | Latest Development | Market Impact |
National interoperability | RNDS held more than 5 billion records by August 2026. | Raises demand for standards-based exchange and longitudinal patient records. |
Primary-care digitization | e-SUS APS version 5.5.28 released in September 2026. | Shows continued expansion of electronic clinical workflows in the public system. |
Supplementary health | 53.1 million medical-plan beneficiaries in July 2026. | Supports a large private provider base requiring integrated clinical and billing systems. |
Hospital EMR scale | Philips Tasy is used in roughly 2,000 Latin American institutions. | Demonstrates the maturity and installed-base depth of enterprise EMR platforms. |
Domestic platform scale | MV reports more than 5,000 clients across Brazil, Latin America and Africa. | Provides a large base for upgrades, cloud services and interoperability products. |
Cloud-native hospital systems | Dedalus markets Medview EVO as web-based, cloud-native and multitenant. | Increases competitive pressure toward modern hosted architectures. |
Competitive Landscape
Brazil's EMR market is led by a mix of domestic hospital-software specialists, multinational healthcare-IT vendors and cloud-focused clinic platforms. MV has one of the largest installed bases and reported more than 5,000 clients across Brazil, Latin America and Africa; its electronic patient record was recognized by KLAS in 2026 for acute-care EHR in Latin America. Philips Tasy is deeply embedded in the Brazilian private hospital market and is expanding across Rede D'Or, while Pixeon, Wareline and SPDATA compete with integrated hospital information systems tailored to local billing and regulatory workflows. Dedalus is modernizing its Brazilian portfolio around the web-based Medview EVO platform, and TOTVS brings broader enterprise-resource-planning capabilities into hospital and clinic operations.
Competition is increasingly determined by ecosystem breadth rather than the record screen itself. Providers compare integration with diagnostic imaging, laboratory systems, e-prescribing, pharmacy, revenue cycle, mobile access, patient portals and analytics. Interoperability standards such as HL7 and FHIR are becoming more important as customers connect legacy systems and external networks. Artificial intelligence is entering documentation, workflow automation and clinical decision support, but the near-term commercial advantage comes from reducing administrative effort inside established workflows. Vendors with large installed bases can monetize upgrades and recurring services, while cloud-native challengers can compete on implementation speed, usability and lower infrastructure burden.
Recent Developments
September 2026: The Ministry of Health released e-SUS APS version 5.5.28 with prescription, reporting and child-growth updates.
August 2026: The Ministry of Health began moving RNDS infrastructure toward a sovereign SUS cloud; RNDS contained more than five billion records.
August 2026: Brazil’s National Health Council approved the National Information and Digital Health Policy, emphasizing integrated clinical histories and telehealth.
May 2026: MV presented Soul Agents and Linha da Vida at Hospitalar 2026, extending automation and longitudinal-record capabilities around its EMR ecosystem.
April 2026: Recife’s Hospital da Criança opened with an integrated MV digital-hospital platform and electronic patient record.
March 2026: MV’s electronic patient record received its ninth Best in KLAS recognition for acute-care EHR in Latin America.
August 2025: Philips announced an expanded Tasy EMR deployment across Rede D’Or, one of Brazil’s largest hospital networks.
Brazil Electronic Medical Record (EMR) Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 760.0 million |
| Total Market Size in 2031 | USD 1,200.0 million |
| Forecast Unit | Million |
| Growth Rate | 9.6% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product, End User, Services Offered |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Product
Client-Server Based
Web-Based
By End User
Hospitals
Ambulatory Care
Physician Clinics
Laboratories
Pharmacies
By Services Offered
Licensed Software
Technology Resale
Subscriptions
Professional Services
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Interoperability Requirements Are Moving EMR Upgrades From Optional to Strategic
3.1.2. Cloud Delivery Broadens Adoption Beyond the Largest Hospital Networks
3.1.3. Integrated Clinical and Financial Workflows Increase Platform Value
3.2. Market Restraints
3.2.1. Data Protection and Cybersecurity Requirements Increase Implementation Complexity
3.2.2. Legacy Integration, Migration and Training Extend Deployment Timelines
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Regulatory and Data-Protection Landscape
4. TECHNOLOGICAL OUTLOOK
4.1. Cloud-Native and SaaS EMR
4.2. Interoperability and FHIR-Based Data Exchange
4.3. AI-Assisted Clinical Documentation
4.4. Mobile Clinical Workspaces
4.5. Cybersecurity, Identity and Audit Controls
5. BRAZIL ELECTRONIC MEDICAL RECORD MARKET BY PRODUCT
5.1. Client-Server Based
5.2. Web-Based
6. BRAZIL ELECTRONIC MEDICAL RECORD MARKET BY END USER
6.1. Hospitals
6.2. Ambulatory Care
6.3. Physician Clinics
6.4. Laboratories
6.5. Pharmacies
7. BRAZIL ELECTRONIC MEDICAL RECORD MARKET BY SERVICES OFFERED
7.1. Licensed Software
7.2. Technology Resale
7.3. Subscriptions
7.4. Professional Services
7.5. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. MV Sistemas
9.2. Philips Tasy EMR
9.3. Pixeon
9.4. Wareline
9.5. SPDATA
9.6. Dedalus Brasil
9.7. TOTVS Saúde
9.8. Prontmed
9.9. Afya Limited
9.10. Amplimed
9.11. Doctoralia Brasil
9.12. InterSystems
9.13. Oracle Health
9.14. Benner Saúde
9.15. RT Medical Systems
9.16. Ommed
10. RECENT DEVELOPMENTS
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Research Methodology
11.5. Abbreviations





Frequently asked questions
What is Brazil's EMR market size forecast for 2031?
Projected to reach USD 1,200.0 million by 2031, with 9.6% CAGR.
Which EMR deployment model leads Brazil's market in 2026?
Web-based platforms hold approximately 63% of market revenue.
Which end-user category accounts for most EMR spending in Brazil?
Hospitals generate about 45% of EMR spending in 2026.
What is the share of subscription-based EMR services in Brazil?
Subscription services represent roughly 34% of market revenue in 2026.
What are the key growth trends in Brazil's EMR market?
Cloud migration, interoperability, and AI-assisted documentation are core requirements.
How does Brazil's RNDS impact the EMR market?
RNDS, with five billion records, is the national interoperability layer.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Brazil Electronic Medical Record (EMR) Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/brazil-emr-electronic-medical-record-market