
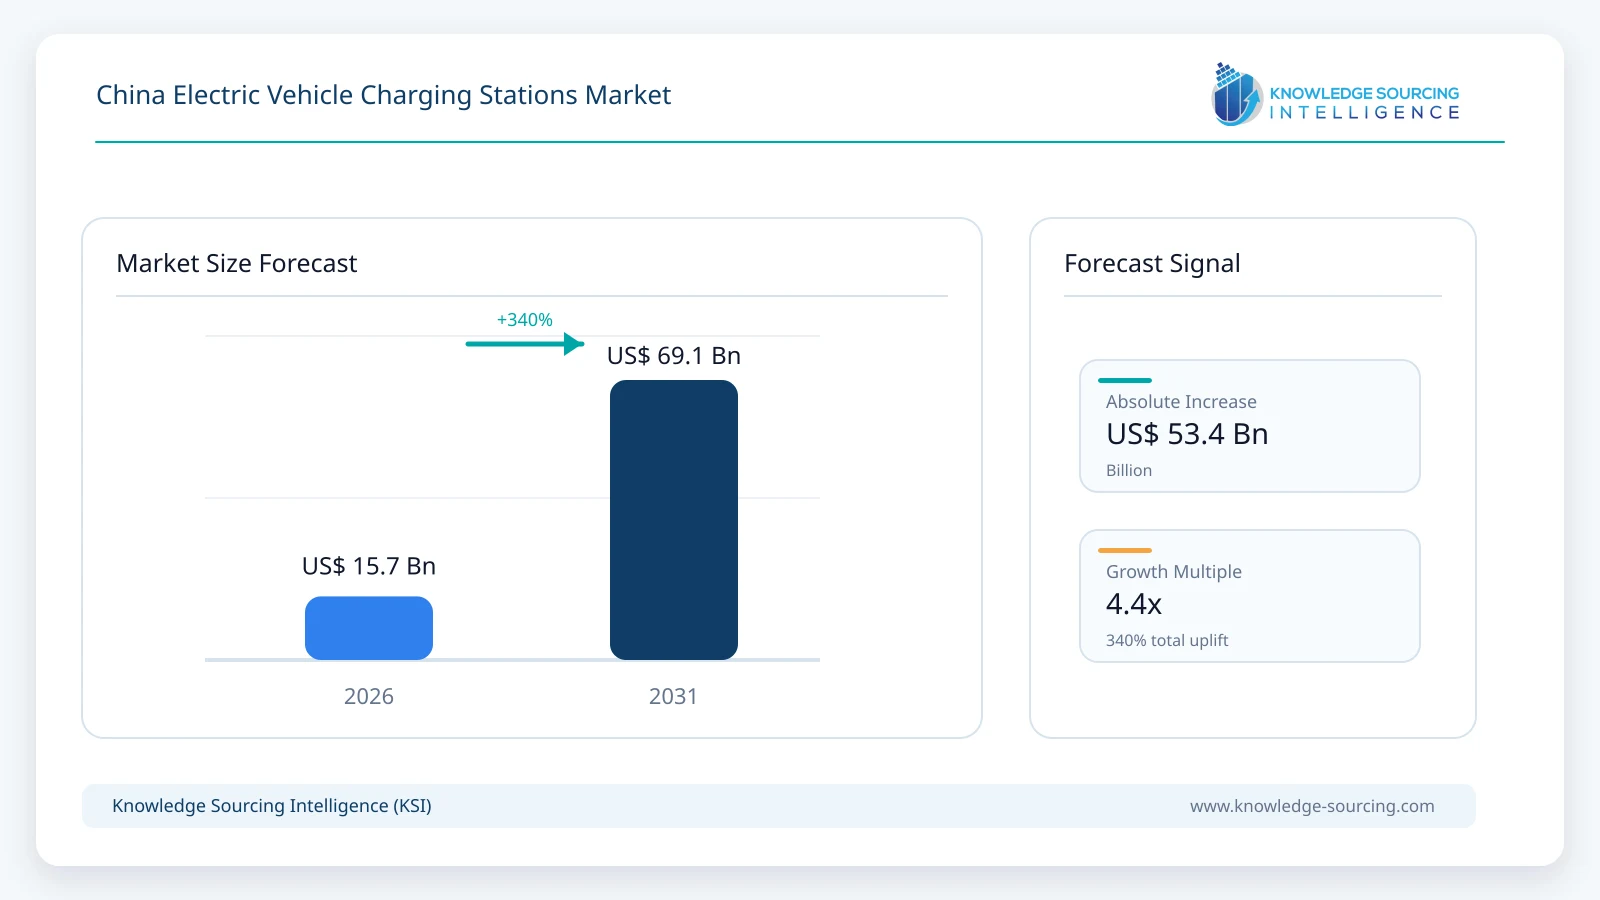
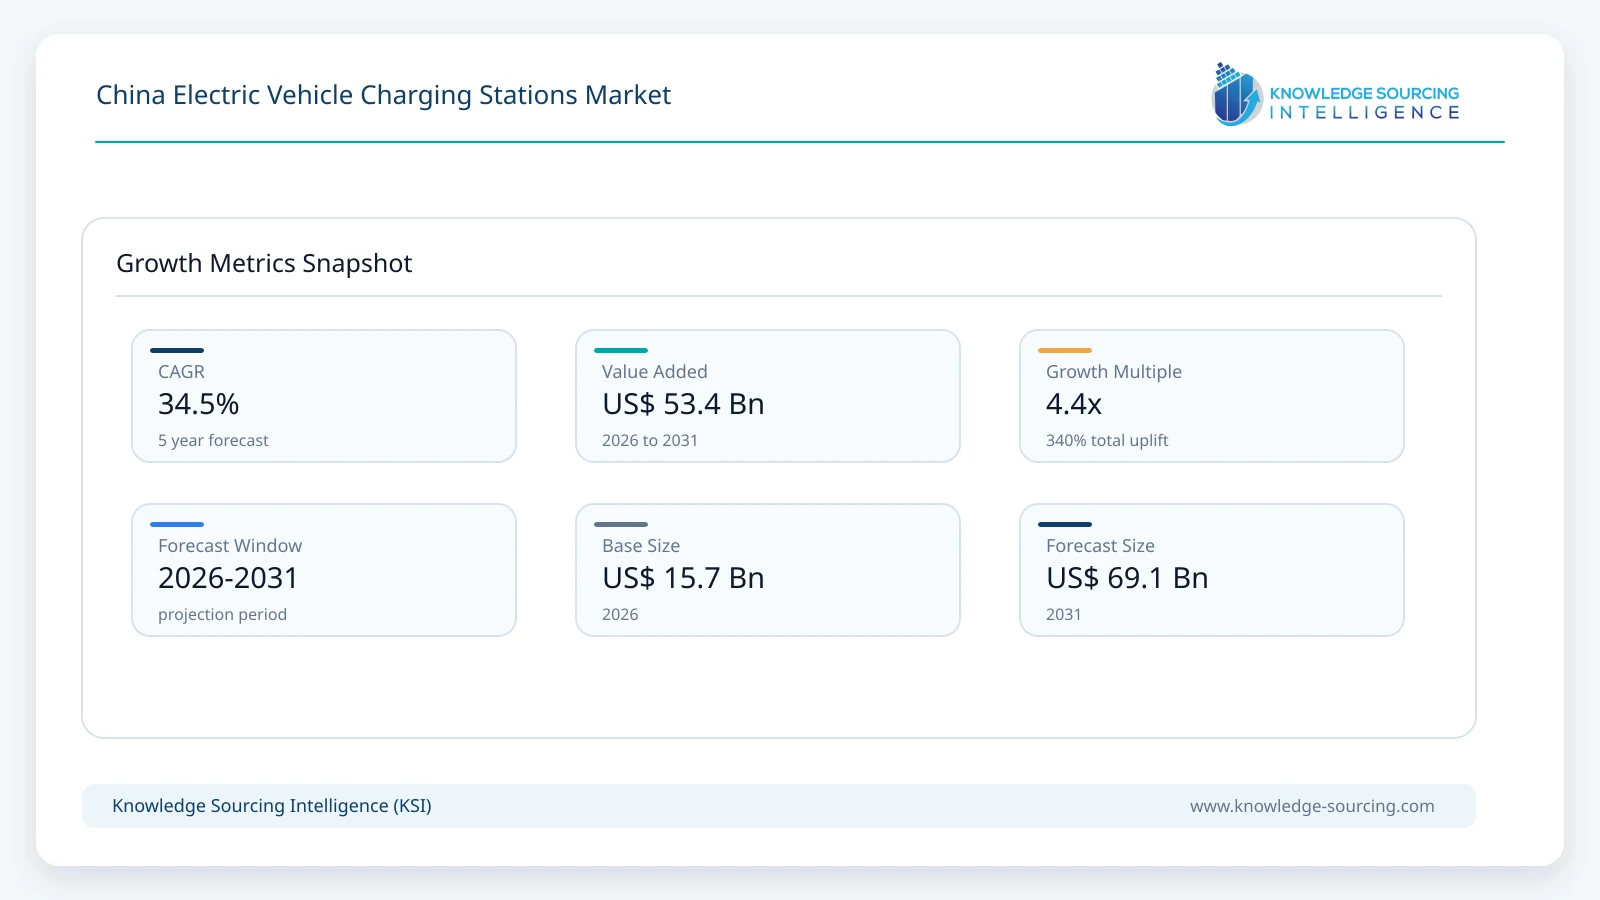
China’s electric vehicle charging stations market is anticipated to expand at a CAGR of 34.5% to attain USD 69.1 billion by 2031 from USD 15.7 billion in 2026.
Highlights:
- 1Passenger vehicles remain the principal demand segmentaccounting for approximately 77.0% of the market in 2026, supported by China’s large electric passenger-car fleet and continued requirement for home, destination and public charging.
- 2DC charging stations represent approximately 65.0% of market value in 2026.Their importance is increasing as charging operators and vehicle manufacturers move toward shorter charging times and higher-power public infrastructure.
- 3Ultra-fast DC charging above 350 kW is projected to grow at approximately 71.5% CAGR through 2031.The segment is moving from a relatively limited installed base toward a more important role in highway, premium passenger and high-utilization charging environments.
- 4Public charging accounts for an estimated 56.0% of market value in 2026,despite private charging representing the majority of installed charging facilities. The divergence reflects the higher equipment and supporting-infrastructure requirements of public charging locations.
- 5Bidirectional and V2G-capable charging infrastructure is projected to grow at approximately 85.4% CAGR,although it remains an emerging part of the overall market. Policy support and electricity-market integration are gradually expanding its commercial relevance.
- 6East China is the largest regional market, with an estimated 35.0% share in 2026,reflecting high EV penetration, dense urban mobility, substantial manufacturing activity and mature charging-network deployment.
China’s charging infrastructure market is entering a more capital-intensive phase. Expansion of the physical charging network remains important, particularly outside established urban centers, but future market value is increasingly being shaped by charging power, public-network upgrades, commercial vehicle requirements, grid capacity and intelligent energy management.
This change is becoming visible in current infrastructure data. China’s electric vehicle charging infrastructure reached approximately 23.68 million charging facilities by the end of July 2026, representing 41.9% year-on-year growth. Public facilities accounted for around 5.10 million units, while private facilities remained substantially larger in physical count. Public charging facilities nevertheless carried 255 million kW of rated capacity, illustrating why unit counts alone do not adequately describe the economic structure of the market.
China is also moving closer to the headline infrastructure targets established under the national 2025–2027 charging action plan. The policy targets 28 million charging facilities and more than 300 million kW of public charging capacity by the end of 2027. Importantly, the action plan goes beyond charger numbers. It emphasizes higher-power public charging, upgrades to aging equipment, rural coverage, residential charging availability, distribution-grid readiness and vehicle-to-grid applications.
KSI therefore expects the next stage of market development to differ materially from the initial charging buildout. The market is shifting toward higher-value DC infrastructure, faster charging, public and dedicated charging sites, more demanding commercial applications and closer integration between charging networks and the electricity system.
Market Growth Drivers and Industry Trends
The market is shifting from network availability to charging capability
China has already built one of the world’s most extensive EV charging networks, changing the investment priorities for the market. During the earlier stage of EV market development, the availability of charging infrastructure was a major constraint on electric vehicle adoption. As the network has expanded, however, the quality and performance of charging provision have become increasingly important. Operators are now evaluating charging speed, station throughput, reliability, power availability, and utilization rather than focusing solely on the number of chargers installed. The National Energy Administration reported that more than 180,000 high-power charging guns had been installed by the end of June 2026, while county-level charging-facility coverage had reached 98.61%. These figures indicate that infrastructure expansion is extending beyond major metropolitan areas, with higher-power charging capacity being developed in parallel. As a result, market expenditure is gradually shifting toward power electronics, cooling systems, transformers, distribution equipment, energy storage, and charging-management technologies that can improve the performance and efficiency of the existing charging network.
Higher charging power is becoming a competitive differentiator
Vehicle technology is raising expectations for charging infrastructure, particularly as automakers introduce vehicles capable of significantly higher charging power. In March 2026, BYD announced its second-generation Blade Battery and Flash Charging strategy, alongside plans to establish 20,000 flash-charging stations in China by the end of 2026. The company plans to develop most of these sites in cooperation with existing charging-network operators while also expanding coverage along major highways. This development has implications beyond BYD’s proprietary network, as faster vehicle-side charging capabilities increase pressure on infrastructure providers to deploy higher-output charging equipment at locations where rapid vehicle turnover can generate greater economic value. Huawei Digital Power is pursuing a similar infrastructure direction for commercial transport. In April 2026, the company introduced a new intelligent charging-network portfolio and emphasized megawatt charging for electric heavy-duty vehicles and logistics applications. Huawei is positioning charging infrastructure as an integration point connecting vehicles, charging equipment, and the power grid rather than as a standalone hardware asset. Together, these developments support KSI’s view that charging power, network capability, and system integration will become progressively more important during the forecast period.
Public charging economics are moving to the center of investment decisions
China’s large private charging base can make the market appear predominantly residential when measured only by the number of installed units, but market value follows a different pattern. Public charging sites frequently require higher-output equipment, larger grid connections, multiple charging guns, site development, payment infrastructure, network software, and ongoing operating support. As power ratings increase, these requirements become more substantial, making utilization per site an increasingly important consideration. An underutilized high-power charging station can carry substantial capital costs while generating insufficient charging revenue. Operators therefore place greater emphasis on traffic patterns, fleet demand, nearby EV density, electricity tariffs, charging duration, and competitive site availability when selecting locations and determining capacity. Consequently, the market is becoming less focused on indiscriminate network expansion and more on deploying the right power capacity at locations capable of sustaining sufficient utilization and revenue.
Grid readiness is becoming part of charging-market competitiveness
China’s charging infrastructure expansion is becoming increasingly integrated with distribution-grid planning. The national three-year action plan explicitly requires charging-infrastructure demand to be incorporated into distribution-grid planning, while also calling for network strengthening and transformer-capacity upgrades where required. The plan further identifies aging-equipment replacement and improvements in public charging quality as priority areas. These requirements create broader opportunities across the charging-infrastructure ecosystem, as high-power charging hubs may require upstream electrical upgrades extending well beyond the charging terminal itself. Consequently, charger manufacturers are increasingly operating within a wider ecosystem that includes utilities, electrical equipment manufacturers, energy-storage providers, software platforms, and infrastructure developers.
China EV Charging Stations Market Segmentation
By Vehicle Type
Passenger vehicles remain the core market
Passenger vehicles continue to account for the majority of charging-infrastructure demand, with KSI estimating the segment to expand at approximately 33.8% CAGR through 2031. This growth is supported by multiple charging environments, including private residential chargers for routine overnight charging, workplace and commercial locations for destination charging, and public DC networks for drivers without dedicated home charging or those requiring rapid replenishment. The passenger vehicle segment is also central to the shift toward high-power charging, as newer battery platforms support faster charging speeds and make infrastructure capability an increasingly important part of the overall ownership experience. However, passenger vehicle charging is not a uniform market, as residential AC equipment and ultra-fast public DC systems differ substantially in cost structures and utilization patterns. Therefore, the underlying opportunity depends not only on the size of the passenger vehicle fleet but also on where and how vehicles are charged.
Commercial vehicles require a different charging model
Commercial vehicles represent a smaller market than passenger vehicles, but they have distinct infrastructure requirements driven by fleet utilization and operating schedules. KSI projects the commercial vehicle segment to grow at approximately 36.9% CAGR during the forecast period. Fleet operators generally place greater emphasis on uptime, charging predictability, and total energy costs, making reliable and efficiently scheduled charging infrastructure particularly important. Delivery vehicles, ride-hailing fleets, buses, and heavy-duty trucks may require centralized charging facilities, higher charging power, or carefully managed charging windows to support regular operations. Heavy-duty vehicle electrification is particularly relevant to high-power charging infrastructure, as larger vehicles require more energy within limited operating periods. Huawei’s 2026 charging strategy specifically links megawatt charging technology with electric heavy-duty logistics, illustrating how charging equipment is increasingly being tailored to the operational requirements and duty cycles of commercial fleets.
By Charging Type
DC charging is taking a larger role in the market value
DC charging is projected to grow at approximately 40.2% CAGR through 2031, supported by the expansion of public charging hubs, highway charging networks, commercial fleets, and newer passenger EV architectures capable of accepting higher charging power. The economic importance of DC charging extends beyond faster charging times, as high-output stations require more advanced power conversion systems, thermal management, electrical protection, and upstream grid infrastructure. These requirements increase the value intensity of DC charging deployment and help explain why growth in market value can diverge from growth in the physical number of chargers.
AC charging remains important in long-dwell applications
AC charging continues to play an essential role in residential, workplace, and other locations where vehicles remain parked for extended periods, accounting for an approved 35.0% share of the 2026 market. The segment benefits from simpler infrastructure requirements and lower equipment costs compared with high-power DC charging. However, its relative market share is constrained by the faster increase in investment in public and high-power charging infrastructure. AC charging therefore remains structurally important, even as incremental market value increasingly shifts toward faster charging categories.
DC Charging by Power Level
The changing composition of DC charging infrastructure is one of the most important developments in China’s charging market. Standard and fast DC systems below 120 kW remain relevant in locations where moderate charging speeds provide adequate vehicle turnover, although their relative position is becoming more mature as higher-power systems expand. In contrast, high-power DC systems between 120 kW and 350 kW are projected to grow at approximately 39.4% CAGR, supported by urban fast-charging hubs, intercity travel, and higher-utilization charging locations. An even more significant emerging category is ultra-fast DC charging above 350 kW, which KSI projects to account for approximately 27.0% of total market value by 2031. This shift toward higher charging power is being reinforced by investments from vehicle manufacturers and charging-technology suppliers. BYD’s accelerated deployment strategy and Huawei’s focus on megawatt charging indicate that high-power charging is moving beyond isolated demonstration projects and becoming part of broader commercial infrastructure strategies.
By Access Type
Public charging is increasingly value-intensive
Public charging is projected to grow at approximately 38.6% CAGR through 2031, supported by demand from drivers without residential charging access, long-distance travellers, high-mileage vehicle users, and commercial operators requiring faster vehicle turnaround. The segment also benefits from higher investment per site, as multi-gun charging stations, higher charging power, grid infrastructure, and network-management systems increase the commercial value of each public charging location. As a result, public charging is expected to become increasingly important to market revenue, even though private infrastructure continues to account for the majority of physical charger installations.
Private and dedicated charging remain fundamental to daily charging demand
Private and dedicated charging infrastructure continues to expand substantially throughout the forecast period, although its approved share is expected to moderate to 35.0% by 2031. Residential charging remains particularly important because it provides convenient long-duration charging while allowing demand to shift toward off-peak periods. Workplace and dedicated installations further support predictable charging patterns and can increasingly incorporate smart load management to reduce the need for costly electrical upgrades. As a result, private charging is not being displaced by public infrastructure. Instead, the market is becoming more differentiated, with lower-power private charging serving routine and convenient charging needs, while higher-value public infrastructure addresses faster and more accessible charging requirements.
Installation Location Outlook
Residential infrastructure remains an important installation category, particularly for passenger vehicles with access to dedicated parking, where charging can be integrated into routine vehicle use. However, dedicated public charging stations are expanding more rapidly, with KSI projecting this segment to grow at approximately 40.6% CAGR through 2031. This expansion is supported by rising demand for high-throughput charging sites capable of serving multiple vehicles and supporting higher power ratings. Commercial and public parking locations also provide an important link between routine destination charging and dedicated rapid-charging hubs, as retail centers, offices, and mixed-use developments can combine vehicle dwell time with charging availability. Nevertheless, the economic viability of these installations remains closely tied to utilization rates. Highway and expressway charging represents another high-growth application, although China has already achieved broad infrastructure coverage, with more than 98% of expressway service areas equipped with charging infrastructure by the end of 2025. As a result, future investment is increasingly shifting toward expanding capacity and deploying faster charging rather than establishing first-time coverage. Fleet and depot charging remains a more specialized application, but its value is supported by predictable utilization and the ability to coordinate charging with vehicle operating schedules, particularly for logistics fleets and other high-mileage operations.
Smart Charging and Vehicle-to-Grid Development
Bidirectional charging remains an emerging application, but China is laying the foundations for broader vehicle-grid interaction. In October 2025, the National Energy Administration reported that vehicle-to-grid (V2G) pilots were underway across 17 provincial-level regions, supported by bidirectional charging facilities and aggregated vehicle-grid resources. KSI estimates that V2G-capable infrastructure accounted for only 1.0% of market value in 2026, indicating that commercial adoption remains at an early stage. Nevertheless, its strategic relevance is increasing as large EV fleets create flexible electrical loads that can support grid management. Smart charging can shift electricity demand away from peak periods, while bidirectional systems can enable compatible vehicles to participate in demand-response programs or potentially supply electricity back to the grid. However, wider commercial deployment will depend on the development of technical standards, battery compatibility, suitable tariff structures, market participation rules, and viable economic incentives for vehicle owners and aggregators.
Regional Outlook
East China retains market leadership
East China represents the largest regional charging market, supported by its dense urban population, strong EV adoption, mature charging networks, major automotive and technology clusters, and extensive transport infrastructure. KSI expects East China to remain the country’s largest market through 2031, although faster development in less mature regions is gradually broadening the geographic distribution of investment.
Inland regions gain importance as infrastructure coverage expands
Central, Southwest, and Northwest China are increasingly benefiting from the expansion of charging networks beyond the country’s original coastal concentration. The national policy framework is also seeking more balanced infrastructure coverage, particularly across rural and lower-density locations. By June 2026, county-level charging coverage had reached 98.61%, indicating that the remaining opportunity is increasingly shifting from basic regional presence toward greater network depth, equipment quality, and charging capability. Regional economics, however, continue to vary. Lower traffic density can limit site utilization, while long-distance transport routes may require charging infrastructure even where individual stations generate comparatively lower throughput. As a result, regional market growth depends on a combination of EV penetration, transport intensity, local policy support, grid availability, and the underlying economics of charging-network deployment and utilization.
Key Developments
August 2026: China’s official charging-monitoring data showed that total charging infrastructure had reached approximately 23.68 million facilities by the end of July, up 41.9% year on year. Public charging capacity also continued to increase. The data confirm that infrastructure expansion remains rapid even as the market begins shifting toward charging quality and power intensity.
April 2026: Huawei Digital Power launched a new intelligent charging-network portfolio and outlined a strategy centered on higher-quality charging networks and megawatt charging for commercial transport. The development is relevant to the China charging market because it links high-power equipment with logistics applications, grid interaction and charging-network operation rather than treating charging as standalone hardware.
March 2026: BYD launched its second-generation Blade Battery and Flash Charging strategy and announced plans to build 20,000 flash-charging stations across China by the end of the year. The planned rollout demonstrates how vehicle manufacturers are increasingly investing directly in charging capability as part of the EV ownership proposition.
February 2026: NIO reported its 100 millionth battery swap and stated that its charging and battery-swapping infrastructure would continue expanding during 2026. While battery swapping is distinct from conventional plug-in charging, NIO’s strategy illustrates the broader competitive pressure on charging operators to reduce replenishment time and integrate energy services with vehicle ownership.
Competitive Environment
China’s charging market comprises a diverse group of participants, including specialized charging-equipment manufacturers, charging-network operators, vehicle manufacturers, electrical equipment suppliers, utilities, and energy companies. As a result, competition is expanding beyond charger manufacturing toward integrated charging infrastructure and energy services. Equipment suppliers compete on factors such as power rating, conversion efficiency, reliability, thermal management, interoperability, and lifecycle support, while charging-network operators differentiate through network coverage, station uptime, utilization rates, pricing, and digital user experience.
Vehicle manufacturers are also becoming more active in charging infrastructure, with several developing proprietary charging or energy-replenishment networks to strengthen customer retention and differentiate their electric vehicle platforms. Private-sector participation is substantial. In October 2025, the National Energy Administration reported that eight of China’s ten largest charging operators were private enterprises, collectively accounting for 70.7% of the country’s public charging piles. This competitive structure increasingly favors companies that can integrate charging hardware with software, network management, and broader energy-system capabilities. Key companies considered in the China market include StarCharge, TGOOD, Sinexcel, NIO, XPeng, Tesla, Shell, Zhuhai PILOT Technology, and BESEN, alongside other domestic charging-infrastructure and power-electronics participants.
China Electric Vehicle Charging Stations Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 15.7 billion |
| Total Market Size in 2031 | USD 69.1 billion |
| Forecast Unit | Billion |
| Growth Rate | 34.5% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Vehicle Type, Charging Type, Access Type, Installation Location, Charging Functionality, Region |
| Companies |
|
Market Segmentation
By Vehicle Type
Passenger Vehicles
Commercial Vehicles
Others
By Charging Type
AC Charging Stations
DC Charging Stations
Standard/Fast DC (<120 kW)
High-Power DC (120–350 kW)
Ultra-Fast DC (>350 kW)
By Access Type
Public Charging
Private/Dedicated Charging
By Installation Location
Residential
Workplace
Commercial/Public Parking
Dedicated Public Charging Stations
Highway/Expressway Charging
Fleet/Depot Charging
By Charging Functionality
Unidirectional Charging Infrastructure
Bidirectional/V2G-Capable Charging Infrastructure
By Region
East China
South China
North China
Central China
Southwest China
Northwest China
Northeast China
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. National Transition Toward Charging-Service Capacity and Network Upgrades
3.1.2. Accelerated Deployment of High-Power and Ultra-Fast Charging Infrastructure
3.1.3. Expansion of Charging Networks Across Counties and Lower-Tier Markets
3.1.4. Development of Heavy-Duty, Logistics and Dedicated Commercial Charging Infrastructure
3.1.5. Commercialization of V2G and Grid-Interactive Charging
3.2. Market Restraints
3.2.1. Public Charging Overcapacity and Low Site Utilization Risk
3.2.2. Distribution-Grid Constraints for High-Power Charging Hubs
3.2.3. Residential Charging Constraints in Existing Urban Communities
3.2.4. Highway Charging Economics Under Highly Concentrated Peak Demand
3.2.5. Charging-Technology Upgrade Cycles and Asset Obsolescence Risk
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. CHINA ELECTRIC VEHICLE CHARGING STATION MARKET BY VEHICLE TYPE
5.1. Introduction
5.2. Passenger Vehicles
5.3. Commercial Vehicles
5.4. Others
6. CHINA ELECTRIC VEHICLE CHARGING STATION MARKET BY CHARGING TYPE
6.1. Introduction
6.2. AC Charging Stations
6.3. DC Charging Stations
6.3.1. Standard/Fast DC (<120 kW)
6.3.2. High-Power DC (120–350 kW)
6.3.3. Ultra-Fast DC (>350 kW)
7. CHINA ELECTRIC VEHICLE CHARGING STATION MARKET BY ACCESS TYPE
7.1. Introduction
7.2. Public Charging
7.3. Private/Dedicated Charging
8. CHINA ELECTRIC VEHICLE CHARGING STATION MARKET BY INSTALLATION LOCATION
8.1. Introduction
8.2. Residential
8.3. Workplace
8.4. Commercial/Public Parking
8.5. Dedicated Public Charging Stations
8.6. Highway/Expressway Charging
8.7. Fleet/Depot Charging
9. CHINA ELECTRIC VEHICLE CHARGING STATION MARKET BY CHARGING FUNCTIONALITY
9.1. Introduction
9.2. Unidirectional Charging Infrastructure
9.3. Bidirectional/V2G-Capable Charging Infrastructure
10. CHINA ELECTRIC VEHICLE CHARGING STATION MARKET BY REGION
10.1. Introduction
10.2. East China
10.3. South China
10.4. North China
10.5. Central China
10.6. Southwest China
10.7. Northwest China
10.8. Northeast China
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Major Players and Strategy Analysis
11.2. Market Share Analysis
11.3. Mergers, Acquisitions, Agreements, and Collaborations
11.4. Competitive Dashboard
12. COMPANY PROFILES
12.1. TELD New Energy Co., Ltd.
12.2. StarCharge
12.3. YKC
12.4. Xiaoju Charging
12.5. State Grid EV Service Co., Ltd.
12.6. China Southern Power Grid Electric Vehicle Service Co., Ltd.
12.7. Shenzhen Sinexcel Electric Co., Ltd.
12.8. Shenzhen Infypower Co., Ltd.
12.9. Zhuhai PILOT Technology Co., Ltd.
12.10. Shenzhen Increase Technology Co., Ltd.
12.11. Shijiazhuang Tonhe Electronics Technologies Co., Ltd.
12.12. UU GreenPower
12.13. XCharge
12.14. Huawei Digital Power Technologies Co., Ltd.
12.15. BYD Company Limited
12.16. NIO
12.17. XPeng Inc.
12.18. Tesla China
12.19. Sinopec
12.20. Shell China
13. APPENDIX
13.1. Currency
13.2. Assumptions
13.3. Base and Forecast Years Timeline
13.4. Key Benefits for the Stakeholders
13.5. Research Methodology
13.6. Abbreviations
Navigate
Trusted by the world's leading organizations











