
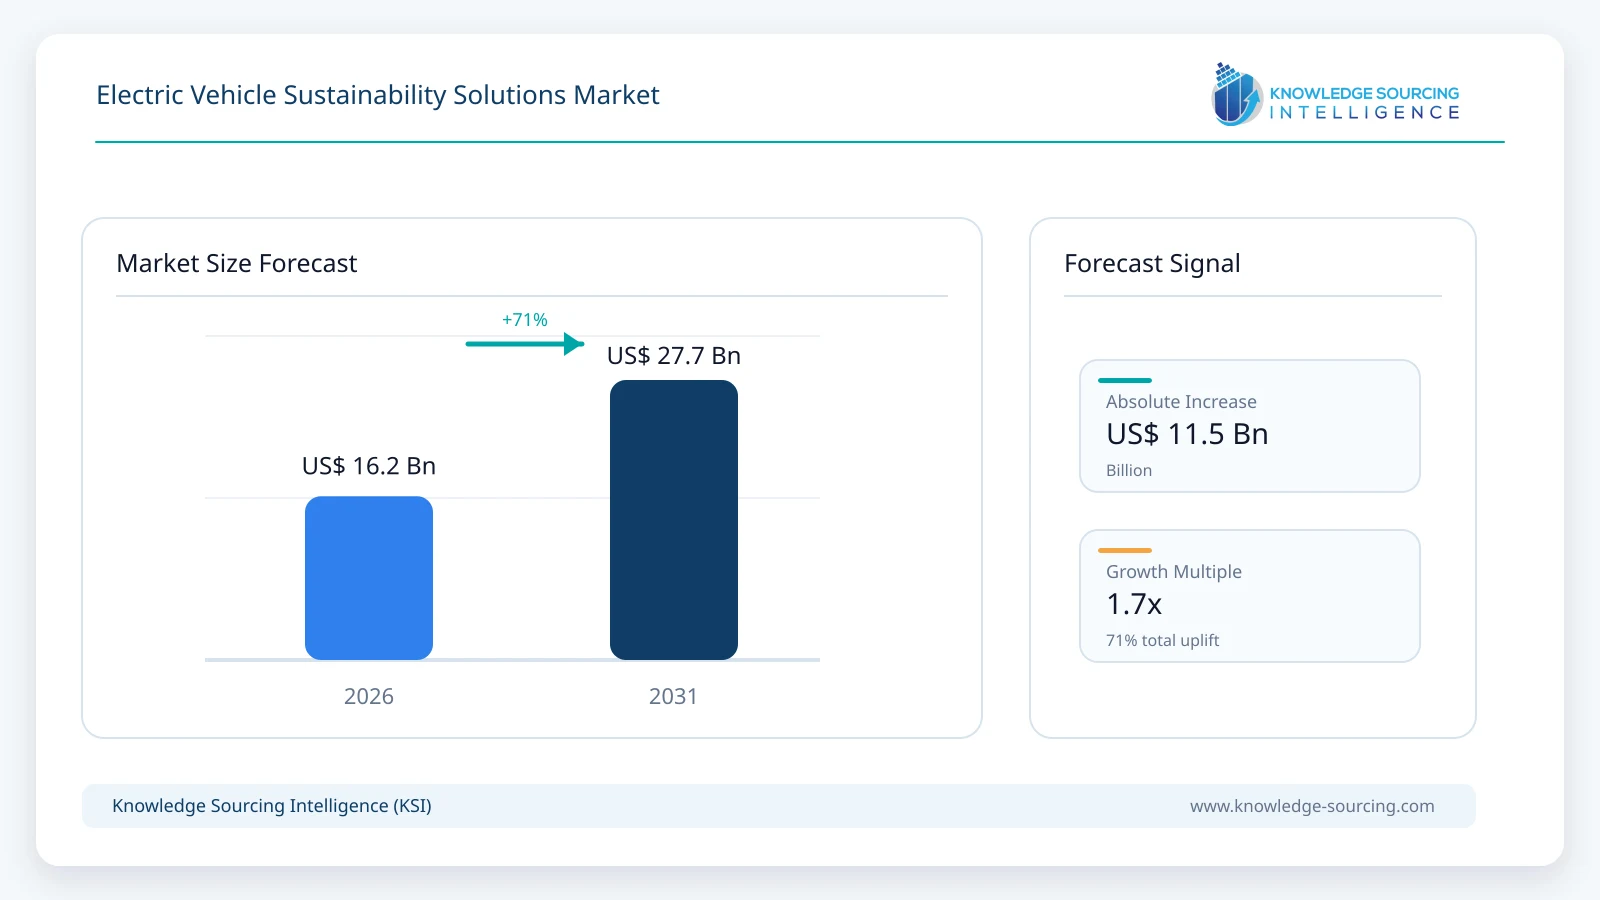
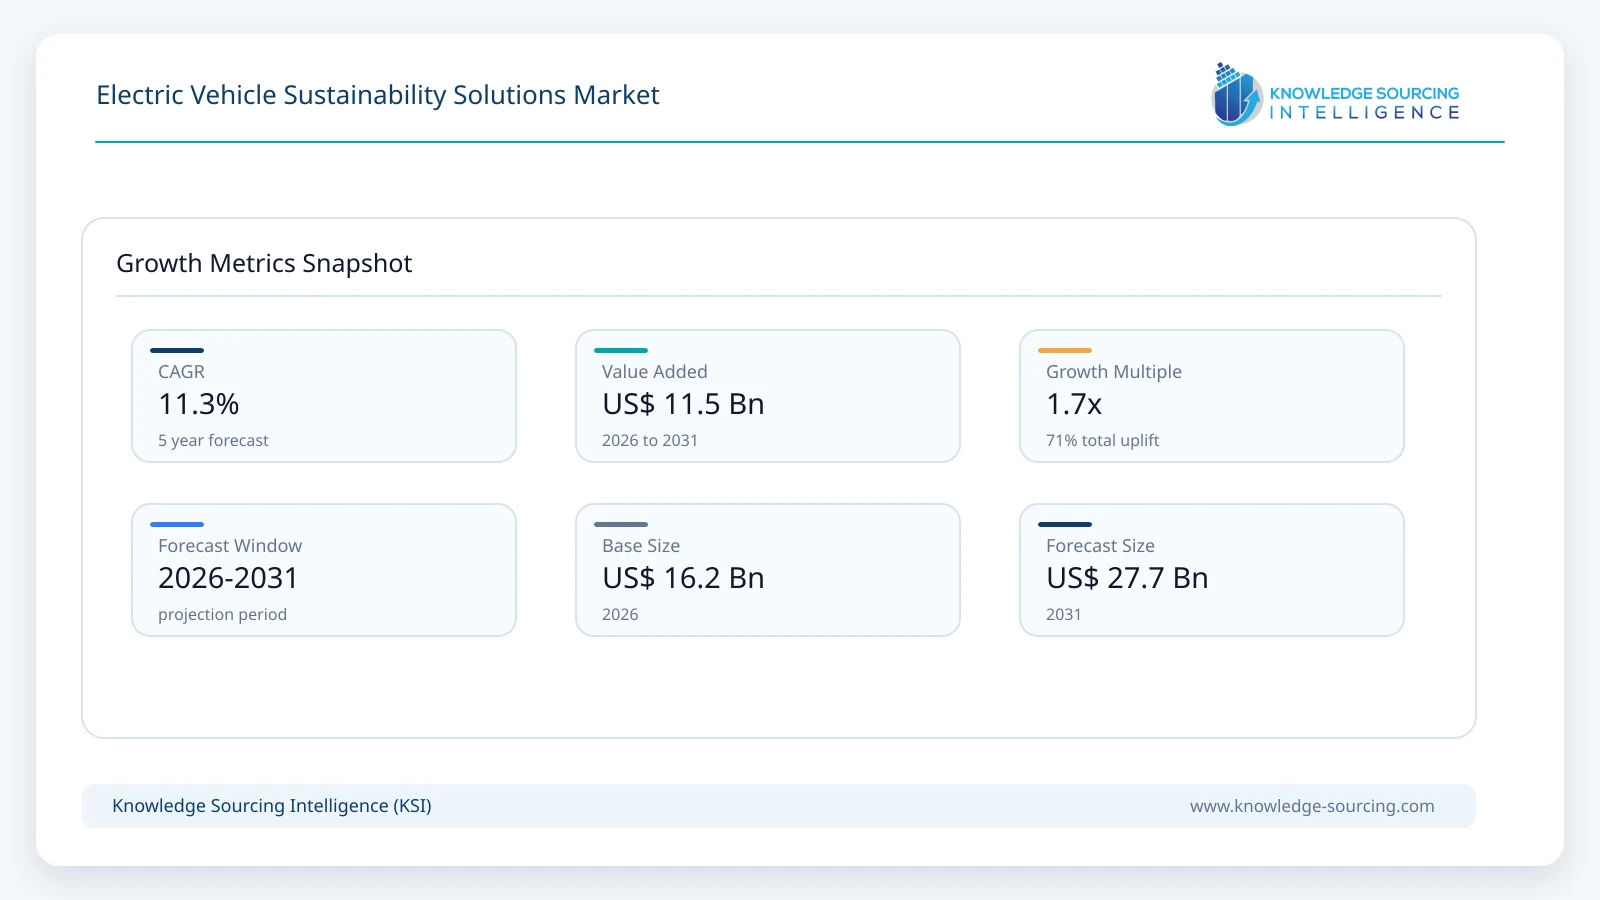
The electric vehicle sustainability solutions market is forecast to grow at a CAGR of 11.3%, reaching USD 27.7 billion in 2031 from USD 16.2 billion in 2026.
Highlights:
- 1Global electric car sales exceeded 20 million units in 2025, with electric cars accounting for 25% of new car sales worldwide, strengthening demand for charging, energy management, battery lifecycle, and circularity solutions.
- 2The International Energy Agency expects global electric car sales to reach about 23 million units in 2026, equivalent to approximately 28% of total car sales, creating a larger installed base for sustainability-focused infrastructure and services.
- 3Governments are increasingly supporting EV charging infrastructure, grid integration, battery circularity, and domestic EV supply chains through financial incentives, infrastructure programmes, technical standards, and sustainability regulations.
- 4Battery lifecycle management is becoming a core sustainability opportunity as automakers and energy companies develop second-life, recycling, material recovery, and closed-loop battery systems.
- 5Smart charging and Vehicle-to-Grid (V2G) technologies are gaining importance because they can coordinate EV charging with electricity demand, renewable generation, tariffs, and grid conditions.
- 6Companies are increasingly combining EVs, bidirectional charging, stationary storage, renewable energy, and digital energy-management platforms to create integrated sustainability solutions rather than standalone vehicle technologies.
The electric vehicle sustainability solutions market is moving beyond the initial objective of replacing internal combustion engine vehicles with electric alternatives. The market increasingly encompasses the technologies and services that improve the environmental, energy, and resource performance of electric mobility throughout the vehicle and battery lifecycle. This includes smart charging, bidirectional charging, Vehicle-to-Grid (V2G) systems, charging infrastructure optimization, battery lifecycle management, battery recycling, second-life battery applications, renewable-energy integration, and digital energy-management solutions.
The underlying EV market provides an important demand base for these solutions. According to the International Energy Agency (IEA), global electric car sales exceeded 20 million in 2025, increasing by 20% from 2024 and representing one-quarter of all new cars sold worldwide. The IEA estimates that global electric car sales could reach approximately 23 million in 2026, representing about 28% of total car sales. The organization also reports that around 5% of the global car stock was electrified at the end of 2025. This expanding installed base increases the need for efficient charging, battery monitoring, grid integration, recycling, and other sustainability-oriented solutions.
The sustainability opportunity is also becoming more closely connected to the electricity system. EV charging can increase electricity demand, but managed charging and bidirectional charging can provide flexibility when charging is coordinated with grid conditions. The IEA's 2026 analysis highlights the role of smart charging and Vehicle-to-Grid technology in managing electricity demand and improving grid flexibility. This creates an opportunity for charging operators, utilities, automakers, energy companies, and software providers to develop integrated solutions that connect EVs with the wider energy system.
Battery circularity is another important part of the market. EV batteries contain valuable materials and represent a substantial share of the environmental footprint associated with electric mobility. Extending battery life through diagnostics, repair, remanufacturing, repurposing, and second-life applications can improve resource utilization before final recycling. The European Union's Batteries Regulation is reinforcing this transition through requirements covering battery sustainability, recycled content, carbon-footprint information, due diligence, recycling, and battery passports. The European Commission's current implementation timeline indicates that the battery passport becomes mandatory for relevant batteries placed on the EU market from February 2027, while 2026 includes important implementation milestones for the digital product passport infrastructure.
Government support is also expanding the physical infrastructure required for sustainable electric mobility. In India, the Ministry of Heavy Industries reported in July 2026 that 52,718 public EV charging stations were listed through the BHEL portal, including 16,561 public charging stations equipped with fast chargers for cars. The government has also allocated ?2,000 crore under the PM E-DRIVE Scheme for public EV charging infrastructure. These measures demonstrate how charging infrastructure is becoming a major part of the sustainability solutions ecosystem.
The market is therefore increasingly defined by the interaction between transportation, electricity, batteries, digital platforms, and circular-economy systems. Rather than measuring only the deployment of electric vehicles, sustainability solutions focus on improving how EVs are charged, powered, managed, maintained, reused, and ultimately recovered at the end of their useful life.
Electric Vehicle Sustainability Solutions Market Overview & Scope:
The electric vehicle sustainability solutions market is segmented by:
Solution Type: Smart charging solutions, Vehicle-to-Grid and bidirectional charging solutions, charging infrastructure optimization solutions, battery lifecycle management solutions, battery recycling and material recovery solutions, second-life battery solutions, renewable energy integration and energy management solutions, and other sustainability solutions form the primary segmentation. This approach better reflects the commercial scope of the market because these categories represent technologies and services designed to improve the sustainability, efficiency, flexibility, and resource utilization of electric mobility.
Vehicle Type: Battery Electric Vehicles (BEVs), Plug-in Hybrid Electric Vehicles (PHEVs), and Fuel Cell Electric Vehicles (FCEVs) represent the vehicle-level application base. BEVs are expected to remain the principal demand source because they depend directly on charging infrastructure and large traction batteries. PHEVs also require charging and battery management solutions, while FCEVs create a separate opportunity around sustainable hydrogen mobility and energy infrastructure.
Technology: Smart charging technology, V2G technology, bidirectional charging technology, advanced battery technologies, battery management and diagnostic technologies, renewable-energy integration technologies, and other technologies constitute the technology segmentation. This structure separates the commercial solution from the underlying technology and reduces overlap between categories such as solid-state batteries and broad advanced battery technologies.
Region: The market is analyzed across North America, South America, Europe, Middle East & Africa, and Asia Pacific, with country-level analysis covering the major EV and sustainability markets within each region.
Major Segment Analysis – Solution Type: Smart charging and bidirectional charging solutions are expected to represent a major growth opportunity because the increasing number of EVs is creating a larger flexible electricity load. Conventional unmanaged charging can concentrate electricity demand at particular periods, whereas smart charging can shift charging activity according to electricity prices, renewable generation, grid constraints, or user preferences. V2G extends this concept by allowing compatible EVs to export electricity back to the grid. The IEA identifies smart charging and V2G as important tools for integrating growing EV demand into electricity systems, although deployment depends on suitable market rules, charging standards, vehicle compatibility, consumer incentives, and electricity tariffs.
Major Segment Analysis – Battery Lifecycle and Circularity Solutions: Battery lifecycle management, recycling, material recovery, and second-life applications represent another major opportunity. These solutions address sustainability beyond the point of vehicle operation by improving battery utilization and reducing dependence on newly extracted materials. The European Union's regulatory framework is particularly significant because it establishes requirements for sustainability, traceability, recycled content, material recovery, and battery information. Under the Batteries Regulation, future recycled-content requirements for EV batteries include minimum shares of recovered cobalt, lithium, and nickel, while recovery and recycling targets also increase over time. These requirements encourage automakers, battery manufacturers, recyclers, and material suppliers to develop more traceable and circular battery supply chains.
India is also expanding the infrastructure foundation for sustainable EV adoption. In March 2026, the Ministry of Heavy Industries reported that 29,151 public EV charging stations had been installed nationally based on BHEL inputs, while a separate March update showed 6,645 FAME-II charging stations operational against 9,332 sanctioned. The government has also established technical and interoperability requirements through the Ministry of Power's 2024 EV charging infrastructure guidelines.
The PM E-DRIVE programme further strengthens the demand environment. As of June 30, 2026, the Ministry of Heavy Industries reported 26.59 lakh EVs supported under the PM E-DRIVE Scheme. The government also reported that EV adoption had increased from 0.08% in FY 2015-16 to 8.26% in FY 2025-26. The scheme includes support for public charging infrastructure and electric buses, providing a wider platform for charging, fleet energy management, and related sustainability solutions.
Top Trends Shaping the Electric Vehicle Sustainability Solutions Market:
1. Battery Circularity and Second-Life Applications: Battery sustainability is increasingly shifting from a recycling-only model toward a broader lifecycle approach. Companies are examining how batteries can be monitored, repaired, repurposed, and reused before final material recovery. In June 2026, Waymo announced a strategic collaboration with B2U Storage Solutions to repurpose batteries from its retired electric fleet into grid-connected stationary energy storage. The companies stated that the initial deployments would focus on California and Texas and could ultimately involve hundreds of megawatts of storage capacity. This development demonstrates the growing connection between EV battery lifecycle management and stationary energy storage.
2. Smart, Bidirectional, and Grid-Integrated Charging: EV charging is increasingly being treated as an energy-management activity rather than simply a method of replenishing vehicle batteries. Smart charging can coordinate charging with grid demand and electricity prices, while bidirectional charging allows energy to move from the grid to the vehicle and, where supported, from the vehicle back to the grid or a building. Volkswagen and Elli announced in April 2026 that they were preparing a fully integrated V2G offer for private customers in Germany, combining the EV, app, electricity tariff, smart meter, bidirectional charger, and installation. The planned market launch is targeted for the fourth quarter of 2026.
3. Renewable-Powered Charging and Energy Integration: Sustainability solutions are increasingly connecting EV charging with solar generation, stationary storage, and local energy-management systems. This trend is particularly relevant for fleets, commercial facilities, remote sites, and locations where grid capacity is constrained. In February 2026, Beam Global and HEVO announced an integrated autonomous wireless charging solution based on Beam's solar-powered, off-grid EV ARC infrastructure and HEVO's wireless charging technology. The system is designed for autonomous vehicles and commercial EV fleet applications where automated charging can reduce dependence on manual plug-in operations.
4. Digital Battery Management and Predictive Optimization: Battery-management and diagnostic technologies are becoming increasingly important as EV fleets mature. Digital monitoring can support battery health assessment, charging optimization, maintenance planning, residual-value assessment, and end-of-life decisions. These capabilities can improve the useful life of batteries while providing data required for reuse, repurposing, and recycling. The emerging battery-passport framework in Europe further strengthens the importance of lifecycle information and traceability.
5. Sustainable Battery Manufacturing and Advanced Recycling: Battery sustainability is moving upstream into cell manufacturing. In January 2026, BMW Group announced the commissioning of its Cell Recycling Competence Centre in Salching, Germany, where it is implementing direct mechanical recycling of battery materials. The company stated that the process is designed to return materials directly into the battery-cell production cycle while reducing the need for energy-intensive treatment. BMW also reported that the facility is expected to recover tens of tonnes of battery-cell materials annually once fully operational.
Electric Vehicle Sustainability Solutions Market Growth Drivers vs. Challenges:
Drivers:
Rapid Growth in Global EV Deployment: The expansion of the EV fleet is the fundamental demand driver for sustainability solutions. The IEA reports that electric car sales exceeded 20 million units in 2025, with electric cars accounting for 25% of global new-car sales. The IEA expects sales to reach approximately 23 million units in 2026, representing about 28% of global car sales. As the installed fleet increases, the addressable base for charging optimization, battery diagnostics, energy management, recycling, and second-life applications also expands.
Government Support for Charging and Sustainable Mobility: Government programmes are encouraging the development of EV infrastructure and supporting the broader transition to clean transportation. India's PM E-DRIVE Scheme includes ?2,000 crore for EV public charging infrastructure, while the government has established operational guidelines for deployment of charging stations. By July 2026, India had 52,718 public charging stations listed through the BHEL portal, including 16,561 fast charging stations for cars. Such investments increase demand for charging management, interoperability, grid integration, and energy optimization technologies.
Regulatory Pressure for Battery Circularity: Regulations are creating a stronger commercial requirement for battery traceability, recycling, recovered materials, and lifecycle information. The EU Batteries Regulation includes requirements relating to sustainability, carbon footprint, recycled content, material recovery, due diligence, and battery information. The European Commission's digital product passport framework identifies electric vehicle batteries as a key category and states that the battery passport will become mandatory for relevant batteries from February 2027. These requirements are encouraging manufacturers and supply-chain participants to invest in circularity and data-management capabilities.
Growing Value of EVs as Distributed Energy Assets: The increasing number of EV batteries creates an opportunity to use vehicles as flexible energy resources. Smart charging can shift electricity consumption, while V2G can potentially provide grid services. The commercial development of integrated V2G packages, including Volkswagen and Elli's 2026 German offering, demonstrates that automakers and energy companies are moving toward business models that combine mobility and electricity services.
Challenges:
Uneven Charging Infrastructure Development: Charging infrastructure remains uneven across countries, regions, and settlement types. Fast-charging availability is particularly important for long-distance travel, commercial fleets, and high-utilization vehicles, but grid connections, land availability, permitting, equipment costs, and utilization rates can affect project economics. India's 2026 charging data demonstrates both the rapid expansion of infrastructure and the continued need for additional deployment across cities and highways.
Grid Capacity and Interconnection Constraints: Large-scale EV charging can create localized electricity demand that requires distribution-network upgrades. The sustainability value of EVs therefore depends partly on how charging demand is managed. Smart charging, energy storage, distributed renewable generation, and demand-response systems can reduce peak-load pressure, but their deployment requires coordination among utilities, charging operators, vehicle manufacturers, software providers, and regulators.
High Complexity of Battery Lifecycle Management: Battery reuse and recycling require accurate information about battery chemistry, condition, remaining useful life, safety, and ownership. Batteries can differ significantly in chemistry, form factor, thermal history, and state of health. This makes standardized testing, traceability, transportation, disassembly, and processing important considerations. Regulatory requirements are increasing the need for data and compliance systems, but they also increase implementation costs for manufacturers and other economic operators.
Technology and Interoperability Fragmentation: Charging connectors, communication protocols, payment systems, vehicle capabilities, electricity tariffs, and grid-service rules can differ across markets. V2G deployment is particularly dependent on compatibility between vehicles, chargers, software platforms, utilities, and electricity-market mechanisms. The absence of uniform commercial arrangements can slow adoption even when the underlying technology is technically available.
Electric Vehicle Sustainability Solutions Market Regional Analysis:
China: China remains the world's largest electric car market and the leading manufacturing hub. The IEA reports that more than 13 million electric cars were sold in China in 2025, accounting for nearly 55% of all car sales in the country. China also accounted for nearly 75% of global electric-car production in 2025. This scale supports demand for battery lifecycle management, charging infrastructure, advanced batteries, energy-management technologies, and recycling systems. The country's large EV fleet also creates a substantial future feedstock for second-life and recycling applications.
United States: The United States remains an important market for EV charging, fleet electrification, battery reuse, energy storage, and digital charging management. Although EV sales were relatively stable in 2025 compared with other major markets, the country has a large installed EV base and substantial investment in charging and energy infrastructure. California and Texas are particularly relevant to battery second-life applications. In June 2026, Waymo and B2U announced plans to repurpose retired Waymo EV batteries for grid-scale storage in these states, linking EV lifecycle management with renewable-energy and grid-storage applications.
Canada: Canada represents an emerging opportunity for sustainable EV infrastructure, particularly through charging deployment, battery supply-chain development, clean electricity integration, and fleet electrification. The country's relatively low-carbon electricity mix in several provinces can strengthen the emissions-reduction potential of EV adoption, while cold-weather conditions increase the importance of battery thermal management, energy efficiency, and charging optimization.
Germany: Germany is a major European market for EV technologies, battery manufacturing, charging, and circularity. EU battery and vehicle-emission requirements are creating stronger incentives for manufacturers to improve lifecycle sustainability. Volkswagen and Elli's April 2026 V2G announcement is particularly relevant because the planned German offering combines a vehicle, bidirectional charger, smart meter, electricity tariff, software, and installation into one integrated energy solution.
United Kingdom: The United Kingdom is an important market for smart charging, charging-network development, and energy-system integration. The IEA reports that electric car sales increased by more than 25% in 2025 and exceeded one-third of new-car sales. The growing share of EVs increases the importance of managed charging and grid-aware energy services, particularly as the country expands renewable electricity generation.
India: India is one of the most important high-growth markets for EV sustainability solutions in Asia Pacific. Government programmes are supporting EV adoption, charging infrastructure, domestic manufacturing, and electric public transport. As of June 30, 2026, the Ministry of Heavy Industries reported 26.59 lakh EVs supported under PM E-DRIVE and an EV adoption rate of 8.26% in FY 2025-26. By July 2026, 52,718 public charging stations were reported through the BHEL portal, including 16,561 fast chargers for cars. The government's ?2,000 crore allocation for public EV charging under PM E-DRIVE further supports the infrastructure opportunity.
Japan: Japan has strong capabilities in automotive engineering, battery technologies, charging systems, and energy management. Its mature automotive industry and emphasis on energy resilience create opportunities for advanced charging, battery management, hybrid and plug-in hybrid technologies, and distributed energy systems.
South Korea: South Korea is strategically important because of its automotive and battery industries. Strong domestic capabilities in battery cells, materials, electronics, and vehicle manufacturing support the development of battery lifecycle technologies, advanced batteries, charging systems, and recycling infrastructure.
South America: Brazil and other Latin American markets are becoming increasingly relevant to EV sustainability solutions as electric-car sales expand. The IEA reports that electric-car sales across Latin America increased by 75% in 2025, led by Brazil and Mexico. Rising EV penetration is expected to increase demand for charging infrastructure, fleet electrification, battery management, and renewable-powered charging.
Middle East & Africa: The region represents a developing opportunity for EV charging infrastructure, fleet electrification, renewable-powered charging, and energy-storage integration. Countries with strong renewable-energy investment and high solar potential can combine EV charging with distributed solar and stationary storage, while major urban markets provide opportunities for fleet and public-transport electrification.
Electric Vehicle Sustainability Solutions Market Competitive Landscape:
The competitive environment is becoming more diverse as the market expands beyond vehicle manufacturers into charging, energy management, battery circularity, and grid integration. Major participants and relevant technology providers include Tesla, Inc., BYD, Rivian Automotive, Inc., Lucid Group, Inc., Volkswagen Group, Hyundai Motor Group, General Motors Company, NIO Inc., BMW Group, and ChargePoint Holdings, Inc., among others.
Competition is increasingly based on the ability to provide integrated sustainability solutions rather than only electric vehicles. Automakers are developing charging and energy-management ecosystems, while charging companies are expanding hardware, software, network-management, and fleet solutions. Battery manufacturers and recycling companies are developing closed-loop material systems, and energy-storage providers are increasingly using retired EV batteries in stationary applications.
Volkswagen and Elli illustrate the move toward integrated mobility-energy platforms through their planned V2G offering in Germany, which combines the vehicle, electricity tariff, smart meter, bidirectional charger, installation, and energy-management software.
BMW Group is strengthening the circular-economy segment through direct battery recycling. Its Cell Recycling Competence Centre in Salching is designed to return recovered battery-cell materials directly to the production cycle, reinforcing the company's focus on closed-loop material use.
ChargePoint is strengthening the charging-management segment through network expansion and software development. In 2026, the company announced partnerships and product initiatives covering highway fast charging, charger management, fleet charging, and residential charging, demonstrating the increasing importance of integrated charging-network services.
Competitive differentiation is therefore expected to increasingly depend on charging-network coverage, interoperability, energy optimization, battery lifecycle capabilities, software integration, partnerships with utilities and fleets, and the ability to create measurable sustainability benefits.
Key Developments
June 2026: Waymo and B2U Storage Solutions announced a strategic collaboration to repurpose batteries from Waymo's retired electric vehicle fleet for grid-connected energy storage. The companies said the initial focus would be on California and Texas and that the programme could deploy hundreds of megawatts of storage capacity. The initiative strengthens the second-life battery segment by connecting EV battery retirement with stationary storage, renewable-energy utilization, and grid services.
April 2026: Volkswagen Group and Elli announced preparations for an integrated Vehicle-to-Grid offering for private customers in Germany. The planned solution combines an electric vehicle, mobile application, electricity tariff, smart meter, bidirectional charger, and installation, with market launch targeted for the fourth quarter of 2026. The development strengthens the integration of EVs with electricity markets and demonstrates the commercialization of vehicle-based energy storage services.
February 2026: Beam Global and HEVO Inc. announced the launch of an integrated autonomous wireless EV charging platform combining HEVO's wireless charging technology with Beam Global's solar-powered, off-grid EV ARC infrastructure. The system targets autonomous vehicles and commercial EV fleets and demonstrates the convergence of renewable-powered charging, wireless charging, and automated fleet energy management.
January 2026: BMW Group and Encory announced the commissioning of BMW's Cell Recycling Competence Centre in Salching, Germany, focused on direct mechanical recycling of battery materials. BMW stated that the facility is designed to process battery-cell manufacturing residues and complete cells from pilot production and return recovered materials directly to the battery production cycle.
Electric Vehicle Sustainability Solutions Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 16.2 billion |
| Total Market Size in 2031 | USD 27.7 billion |
| Forecast Unit | Billion |
| Growth Rate | 11.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Solution Type, Vehicle Type, Technology, Geography |
| Companies |
|
Market Segmentation
By Solution Type
By Vehicle Type
By Technology
By Geography
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. ELECTRIC VEHICLE SUSTAINABILITY SOLUTIONS MARKET BY SOLUTION TYPE
5.1. Introduction
5.2. Smart Charging Solutions
5.3. Vehicle-to-Grid and Bidirectional Charging Solutions
5.4. Charging Infrastructure Optimization Solutions
5.5. Battery Lifecycle Management Solutions
5.6. Battery Recycling and Material Recovery Solutions
5.7. Second-Life Battery Solutions
5.8. Renewable Energy Integration and Energy Management Solutions
5.9. Other Sustainability Solutions
6. ELECTRIC VEHICLE SUSTAINABILITY SOLUTIONS MARKET BY VEHICLE TYPE
6.1. Introduction
6.2. Battery Electric Vehicles
6.3. Plug-in Hybrid Electric Vehicles
6.4. Fuel Cell Electric Vehicles
7. ELECTRIC VEHICLE SUSTAINABILITY SOLUTIONS MARKET BY TECHNOLOGY
7.1. Introduction
7.2. Smart Charging Technology
7.3. Vehicle-to-Grid (V2G) Technology
7.4. Bidirectional Charging Technology
7.5. Advanced Battery Technologies
7.6. Battery Management and Diagnostic Technologies
7.7. Renewable Energy Integration Technologies
7.8. Other Technologies
8. ELECTRIC VEHICLE SUSTAINABILITY SOLUTIONS MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. United Kingdom
8.4.2. Germany
8.4.3. France
8.4.4. Italy
8.4.5. Spain
8.4.6. Others
8.5. Middle East & Africa
8.5.1. Saudi Arabia
8.5.2. United Arab Emirates
8.5.3. South Africa
8.5.4. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Thailand
8.6.6. Indonesia
8.6.7. Australia
8.6.8. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Tesla, Inc.
10.2. BYD
10.3. Rivian Automotive, Inc.
10.4. Lucid Group, Inc.
10.5. Volkswagen Group
10.6. Hyundai Motor Group
10.7. General Motors Company
10.8. NIO Inc.
10.9. BMW Group
10.10. ChargePoint Holdings, Inc.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











