
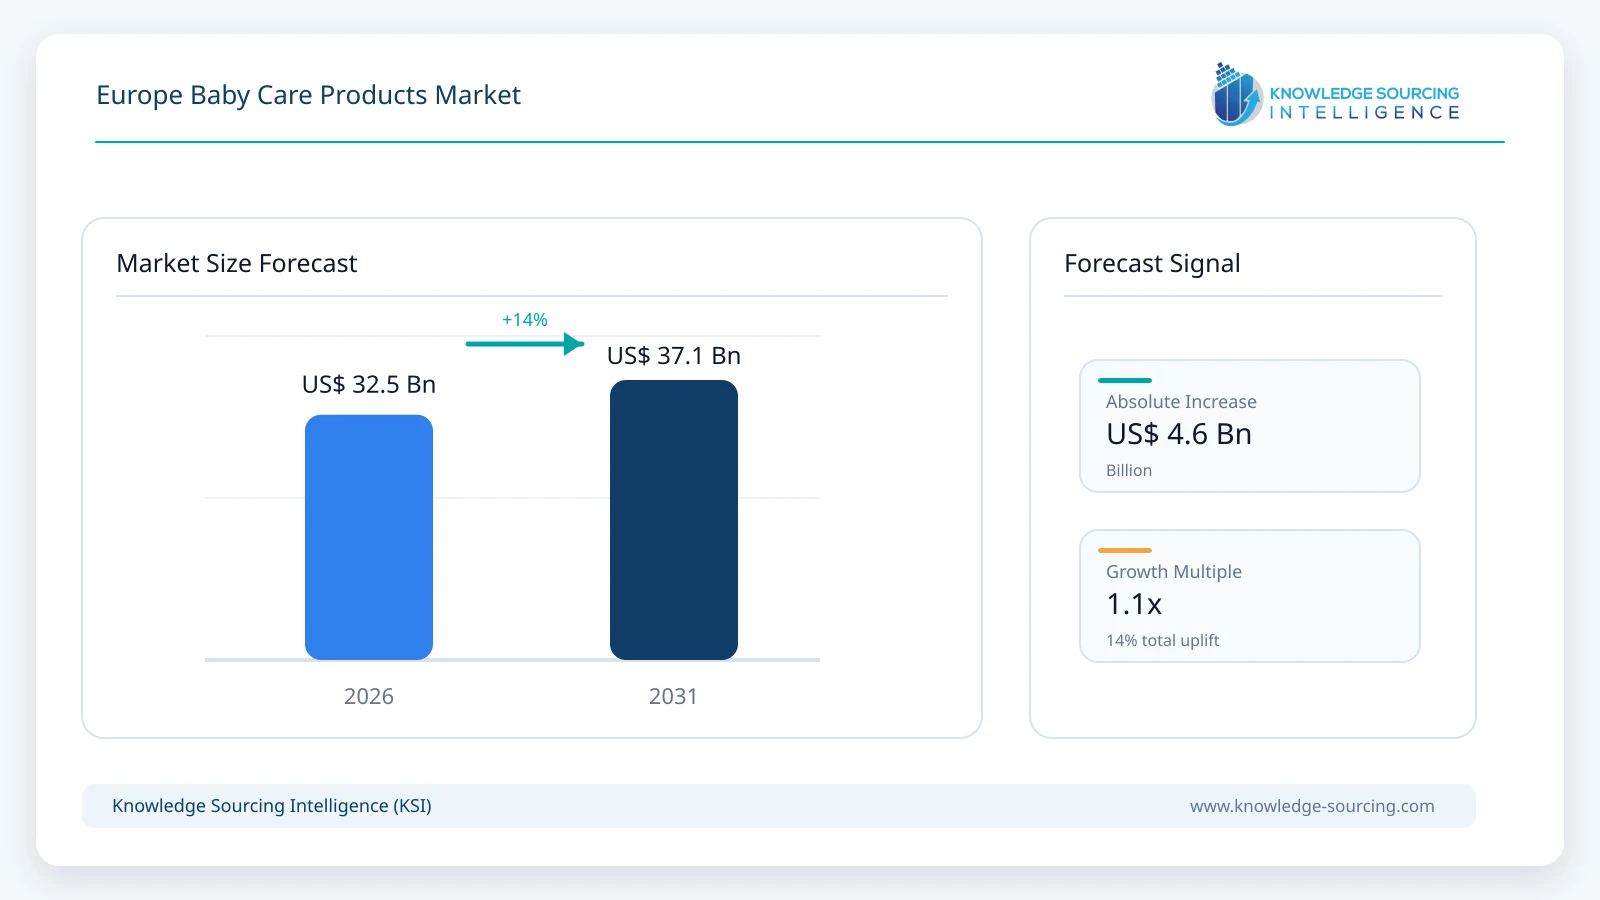
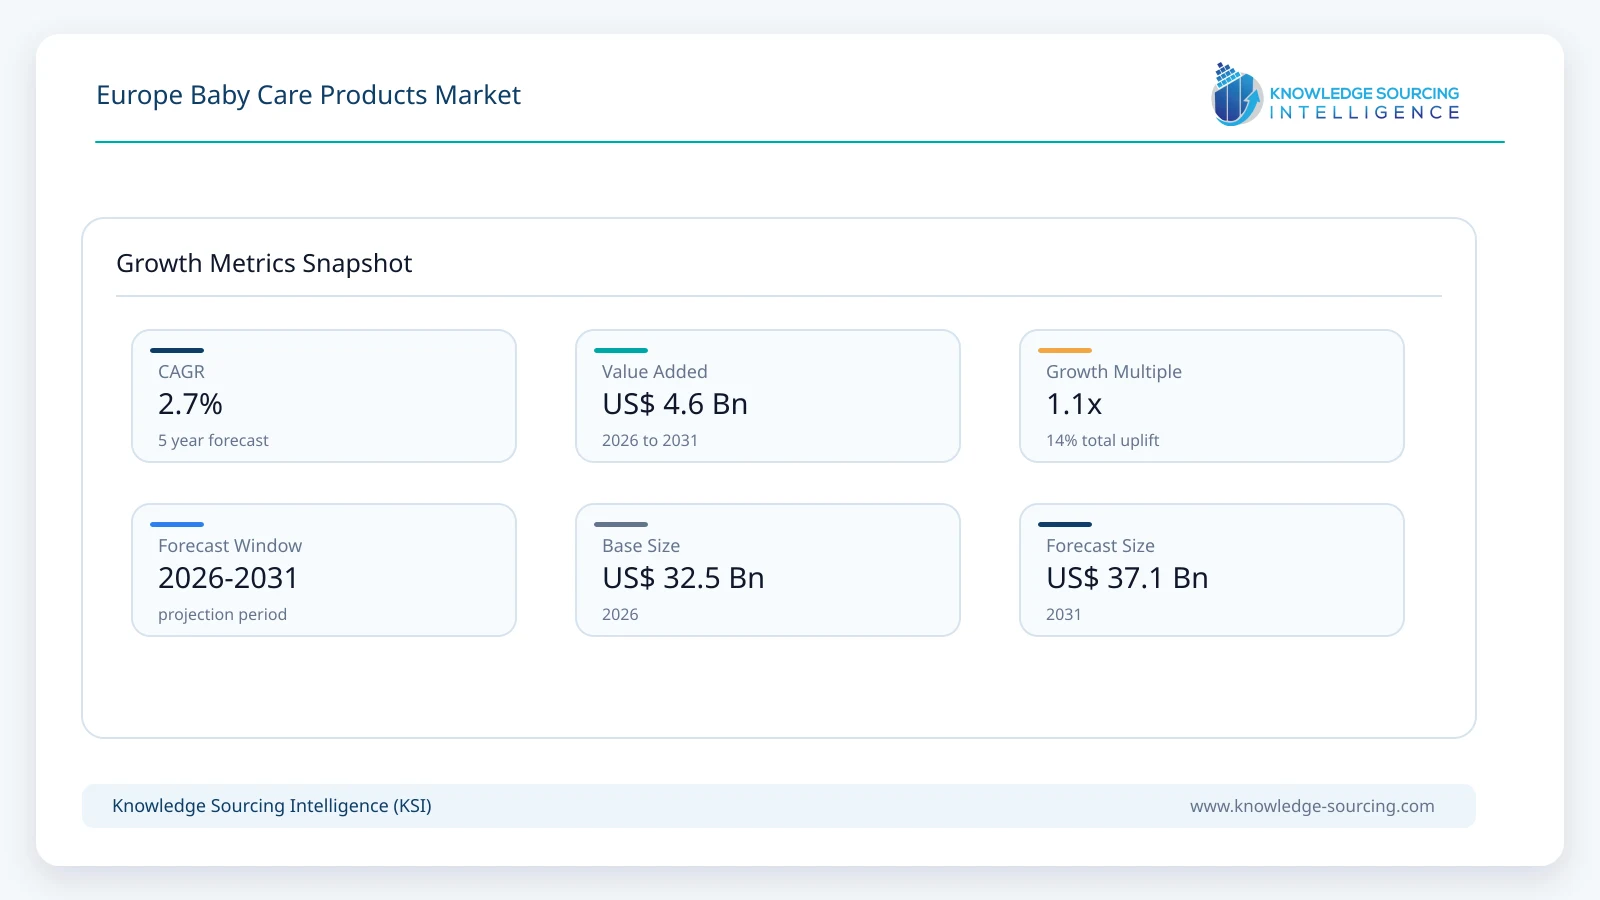
The Europe baby care products market is forecast to grow from USD 32.5 billion in 2026 to USD 37.1 billion in 2031, representing a CAGR of approximately 2.7% during the forecast period.
Highlights:
- 1Baby food and early-life nutrition remain the largest product category, accounting for approximately 34% of the European baby care products market in 2026. Growth remains comparatively moderate because of declining birth rates, but specialized infant formula, premium complementary foods and science-led formulations continue to support value expansion.
- 2Diapers and wipes account for approximately 27% of market revenue in 2026, making them the second-largest product category. Disposable diapers remain dominant, while training pants, reusable diapers and plastic-free wipes provide faster-growing niches within the broader absorbent hygiene segment.
- 3Safety and travel equipment is expected to gain market share through 2031, supported by premium strollers, advanced child car seats, modular travel systems and higher expenditure per child. Child car seats and baby carriers are expected to outperform the broader market as safety features and convenience influence purchasing decisions.
- 4Online retail is the fastest-growing distribution channel. Its share is estimated at approximately 22% in 2026 and is projected to approach 29% by 2031 as consumers increasingly purchase diapers, skincare, specialist nutrition and baby equipment through marketplaces, online pharmacies and brand-owned platforms.
- 5Germany remains the largest country market, accounting for approximately 19% of European revenue in 2026. The United Kingdom and France follow, while Italy, Spain and Poland are expected to record slower growth because of weaker demographic conditions.
- 6Market growth is increasingly value-led rather than population-led. Declining births across Europe limit unit demand, while premium nutrition, skin-sensitive products, high-performance diapers, advanced child safety equipment and sustainable materials support higher spending per child.
The European baby care products market is a mature consumer market with high penetration across infant nutrition, diapers, personal care, feeding products and durable baby equipment. Growth is increasingly shaped by product mix rather than expansion in the number of children entering the market. Birth rates have declined across most major European economies, making volume expansion structurally difficult, particularly in Italy, Spain, Poland and several Eastern European countries. Manufacturers are responding by concentrating on premium formulations, convenience, safety and products designed for specific nutritional or dermatological requirements. Older average parental age in several European markets also supports higher expenditure on selected baby products, particularly premium nutrition, strollers, child car seats and specialist skincare.
The market covers products with very different purchasing patterns. Diapers, wipes, infant formula and toiletries generate recurring household expenditure, while strollers and car seats have longer replacement cycles but significantly higher transaction values. Feeding products sit between these categories, benefiting from replacement, developmental stages and product-system purchasing. Treating these products as one uniform market therefore obscures the commercial structure. Baby food and early-life nutrition remain the largest value pool, while absorbent hygiene provides a large recurring-consumption base and durable baby equipment captures a disproportionate share of premium discretionary spending.
Europe Baby Care Products Market Trends
Premiumisation Is Offsetting Weak Demographics
Fewer births do not translate directly into an equivalent reduction in baby care expenditure. European households are increasingly concentrating spending on fewer children, particularly in high-income markets such as Germany, France, the United Kingdom, Switzerland and the Nordic countries. Premiumisation is most visible where consumers perceive a clear functional difference between products, including specialized infant nutrition, dermatological skincare, high-absorbency diapers and advanced child restraint systems. Parents may remain price-sensitive toward frequently purchased consumables while simultaneously paying a substantial premium for a stroller or car seat with stronger safety, design or durability credentials. Manufacturers are therefore increasingly managing price tiers within individual categories rather than positioning entire portfolios as either premium or mass-market.
Infant Nutrition Is Becoming More Science-Led
Early-life nutrition continues to move beyond conventional infant formula into specialized formulations designed around digestive tolerance, allergies, probiotics, human milk oligosaccharides and specific developmental requirements. Large suppliers are increasingly linking product development to clinical research and healthcare-professional engagement, while European regulation creates high barriers around composition, labelling and marketing. Nestlé has expanded its NAN Sinergity platform incorporating probiotics and multiple HMOs, while Danone continues to invest across early-life and specialized nutrition. These developments are important because traditional formula volumes face demographic pressure, making formulation quality, specialist applications and premium positioning more important sources of value growth than basic category penetration.
Diapers and Wipes Are Shifting Toward Material Efficiency
Disposable diapers remain one of the largest recurring baby care purchases in Europe, but innovation is becoming more focused on fit, absorbency, softness, skin protection and material efficiency than on entirely new product formats. Manufacturers are reducing product bulk while improving absorbent performance, which lowers transport requirements and helps support sustainability positioning. Wipes are undergoing a more visible materials transition. England’s ban on the sale and supply of plastic-containing single-use wet wipes from May 2027 places additional pressure on manufacturers and retailers to move toward plastic-free substrates. Several brands have already introduced biodegradable or plant-based alternatives, making regulatory change an accelerator of an existing commercial shift.
Baby Equipment Is Moving Toward Modular and Longer-Life Design
Strollers, child car seats and related equipment are increasingly designed around modularity, product longevity and cross-stage usage. Premium manufacturers are using recycled aluminium, certified wood, bio-based plastics and recycled fabrics while also improving repairability and accessory compatibility. These characteristics matter commercially because durable baby equipment increasingly competes with a growing second-hand market. Products that retain quality and resale value can strengthen brand perception even if they remain in circulation for longer. Modular travel systems combining stroller frames, bassinets and compatible child seats also increase the value of ecosystem-based purchasing, allowing manufacturers to capture a larger share of household spending through coordinated product platforms.
Europe Baby Care Products Market Drivers
Higher Spending per Child
Europe’s demographic contraction has increased the commercial importance of expenditure per child. Parents having fewer children can allocate more discretionary spending toward premium equipment, specialist nutrition and personal care, particularly in higher-income households. The effect is most visible in categories where quality differences are easy to communicate, such as child car seats, premium strollers and science-led nutrition.
Development of Specialized Infant Nutrition
Specialized early-life nutrition enables manufacturers to move beyond conventional formula and address allergies, digestive sensitivity, premature birth and specific nutritional requirements. Research intensity and regulatory complexity support premium pricing while reducing direct competition from smaller suppliers.
Continued Product Improvement in Diapers
Diaper manufacturers continue to improve absorbency, fit and material efficiency even in a mature market. Small performance improvements matter because diapers are used repeatedly every day, allowing brands to justify product upgrades through dryness, comfort and leak protection rather than relying on completely new product formats.
Expansion of E-Commerce
Online retail is particularly compatible with baby care because many products are purchased repeatedly or require significant product research before purchase. Subscription models improve convenience for recurring categories, while reviews and comparison tools influence premium equipment and skincare decisions.
Greater Focus on Safety and Ingredient Transparency
Parents increasingly expect clear information about ingredients, materials, chemical safety and product testing. European regulation reinforces this demand through stronger product-safety obligations, chemical restrictions and marketplace accountability, increasing the commercial value of documented compliance and trusted brands.
Europe Baby Care Products Market Restraints
Declining Birth Rates
Europe’s demographic trajectory remains the strongest structural limitation on the market. Births have continued to fall across the EU, reducing the annual number of new consumers entering baby care categories. The pressure is particularly significant for products used during relatively short infant stages because lost births cannot easily be offset through longer product usage.
Price Sensitivity in Recurring Purchases
Diapers, wipes, formula and prepared baby food account for substantial recurring household expenditure. Consumers therefore compare prices actively and may move between brands, promotions and private labels more readily than in occasional premium purchases. Retailer brands remain particularly strong in absorbent hygiene.
Complex Regulatory Requirements
Baby care companies operate under several regulatory regimes because food, cosmetics, feeding products and durable child equipment have different compliance requirements. Testing, documentation, ingredient restrictions, labelling and product-safety obligations increase the cost of launching and maintaining products across multiple European markets.
Product Recall and Reputation Risk
Infant nutrition and baby safety products face unusually high reputational risk because product failures affect vulnerable consumers. A recall involving formula, child restraints or another safety-critical product can affect retailer confidence and purchasing behaviour beyond the individual SKU involved. Manufacturers therefore maintain extensive quality assurance and traceability systems.
Second-Hand Competition in Durable Equipment
Premium strollers and other durable products retain substantial value after their first user. Online resale platforms make used premium equipment more accessible, giving households an alternative to buying new. Child car seats are less affected because safety history can influence second-hand purchasing, while strollers and high chairs face stronger resale competition.
Europe Baby Care Products Market Segmentation Analysis
By Product Type
Baby Food and Early-Life Nutrition
Baby food and early-life nutrition represent approximately 34% of European baby care product revenue in 2026, making the category the largest product group. Infant formula accounts for the largest portion, followed by prepared baby food, toddler milk, cereals and complementary snacks. Demographic pressure keeps overall category growth relatively restrained, particularly for traditional infant formula and cereals, but premium and specialist products continue to perform more strongly. Prepared baby meals and complementary foods benefit from convenience, while specialist formula products address allergies, digestive sensitivity and specific nutritional requirements. Scientific formulation, regulatory compliance and healthcare relationships create higher barriers to entry than in most other baby care categories, favouring companies with established nutrition research and manufacturing capabilities.
Diapers and Wipes
Diapers and wipes represent approximately 27% of market revenue in 2026. Disposable diapers remain the dominant subsegment because of convenience, performance and extensive distribution through supermarkets, drugstores, pharmacies and online channels. Market maturity and declining births restrict volume growth, but manufacturers continue to improve absorbency, fit, skin comfort and material efficiency. Training pants grow faster as parents spend more on convenience during later developmental stages, while reusable diapers remain a small but expanding niche. Baby wipes benefit from high usage frequency and broader applications around feeding, travel and general infant hygiene, although plastic-reduction requirements are pushing manufacturers toward alternative materials and reformulated product structures.
Baby Skincare and Toiletries
Baby skincare and toiletries represent a smaller but more dynamic value pool than traditional diapers or infant nutrition. The segment covers creams, lotions, oils, shampoos, bath products, cleansing products and diaper rash care. Parents increasingly examine ingredient lists and seek products positioned around sensitive skin, fragrance reduction and dermatological testing. Pharmacy distribution remains particularly important in France, Germany and several continental European markets, where baby skincare overlaps with dermocosmetics. Premium skincare can continue expanding even when the number of infants declines because parents are willing to use several differentiated products for bathing, moisturising, rash prevention and sensitive-skin care rather than relying on one general-purpose product.
Feeding and Nursing Products
Feeding and nursing products include bottles, nipples, cups, sterilisation products, breastfeeding accessories and other feeding equipment. Product demand changes as children progress through developmental stages, generating recurring replacement beyond the initial purchase. Growth is strongest in breastfeeding accessories and convenience-oriented feeding products rather than traditional sterilizers or basic bottles. Material safety remains particularly important because these products come into direct contact with food or children’s mouths, while anti-colic designs, cleaning convenience and compatibility between bottles, pumps and storage systems influence purchasing. Manufacturers increasingly develop complete feeding ecosystems rather than standalone products, allowing households to remain within one brand as feeding requirements change.
Safety and Travel Equipment
Safety and travel products account for approximately 16% of market value in 2026 and are projected to gain share through 2031. The category includes strollers, prams, child car seats, baby carriers and high chairs, with substantially higher average transaction values than most consumable baby products. Child car seats benefit from regulatory requirements and regular replacement as children move between weight and height categories, while premium strollers compete through folding systems, lightweight construction, manoeuvrability, design and modular compatibility. Baby carriers are growing from a smaller base as parents seek flexible mobility products suitable for urban travel. Product safety ratings, independent testing and brand reputation remain particularly influential in this segment.
Distribution Channel Outlook
Offline retail remains the largest channel in Europe because baby care purchasing spans supermarkets, pharmacies, drugstores, specialist stores and department stores. Supermarkets and hypermarkets retain an important role in diapers, wipes, baby food and mass-market toiletries, while pharmacies and drugstores have stronger positions in specialized nutrition, sensitive-skin products and products requiring greater consumer guidance. Specialist baby stores remain relevant for child car seats and strollers because consumers often want product demonstrations and fitting assistance before making a high-value purchase.
Online retail is gaining share substantially faster than physical channels and is expected to increase from approximately 22% of market revenue in 2026 to around 29% by 2031. Marketplaces provide price comparison and wide brand selection, while online pharmacies are becoming important for skincare and specialist nutrition. Brand-owned websites provide direct access to premium consumers and allow companies to manage subscriptions, product education and cross-category selling. The channel is particularly suitable for bulky recurring purchases such as diapers because scheduled ordering reduces shopping effort.
Country Outlook
Germany
Germany remains the largest European baby care products market, accounting for approximately 19% of regional revenue in 2026. The country combines a large consumer base with strong drugstore, supermarket and e-commerce channels. Premium skincare, infant nutrition and durable equipment coexist with highly competitive retailer brands in diapers and daily-use products. Germany’s comparatively high purchasing power supports premiumisation, although demographic weakness prevents rapid overall volume growth.
United Kingdom
The United Kingdom represents one of Europe’s most developed online baby care markets. Digital purchasing is particularly strong across diapers, skincare and durable equipment, while supermarkets and pharmacies retain important offline positions. Regulatory changes affecting plastic-containing wet wipes create an additional product transition during the forecast period, supporting reformulation and packaging changes.
France
France remains one of the largest regional markets and supports a strong pharmacy-led skincare channel alongside large infant nutrition and grocery categories. French consumers have access to established domestic and multinational suppliers across dermocosmetics, baby food and feeding products. The country’s comparatively stronger demographic position among major continental European markets provides some support to underlying category demand.
Italy and Spain
Italy and Spain remain sizeable markets but face some of Europe’s most challenging fertility trends. Market development is consequently concentrated around premiumisation, e-commerce and higher expenditure per child rather than volume expansion. Infant nutrition, skincare and premium equipment continue to offer opportunities where suppliers can justify higher prices through functional differentiation.
Poland and Central Europe
Poland and other Central European markets have experienced substantial improvement in retail infrastructure and access to international baby care brands. E-commerce has expanded product availability significantly, although weak demographics increasingly restrict market volume. Premium migration remains possible as household incomes rise, particularly in skincare, baby equipment and specialized nutrition.
Competitive Landscape
The Europe baby care products market is fragmented at the overall level because different companies lead individual product categories. Procter & Gamble and Essity maintain significant positions in diapers and absorbent hygiene, while Ontex is an important European manufacturer with strong retailer and private-label relationships. Competition in this category depends heavily on production scale, absorbent-material technology, retailer relationships and price architecture.
Early-life nutrition is more concentrated around companies with established scientific and regulatory capabilities. Danone, Nestlé and HiPP maintain strong positions across infant formula and complementary nutrition, while specialist and regional suppliers participate in selected country markets. Baby skincare includes global consumer-health companies alongside European dermocosmetic brands, while durable equipment remains more fragmented across stroller, child car seat and nursery-equipment specialists.
Competitive advantage therefore varies considerably by category. Scale and procurement matter strongly in diapers, research capability is critical in nutrition, brand trust influences skincare, and engineering, design and safety reputation shape durable equipment. Online distribution is becoming increasingly important across all of these categories, but physical retail remains important wherever professional advice, product fitting or immediate availability influences purchasing.
Recent Developments
September 2026: Bugaboo and Stella McCartney introduced a limited-edition stroller and accessories collaboration incorporating sustainability and design positioning.
August 2026: Nestlé reported continued effects from its infant formula recall in Europe while implementing additional testing and supply-chain quality measures.
May 2026: Procter & Gamble highlighted continuing Pampers development in neonatal care, skin protection, absorbency and consumer-led diaper design.
2026: Danone introduced updated Baby Formula Marketing Standards across its early-life nutrition operations.
November 2025: England enacted regulations prohibiting the sale and supply of single-use wet wipes containing plastic, including baby wipes, with implementation scheduled for May 2027.
June 2025: Nestlé expanded its NAN Sinergity early-life nutrition platform beyond its initial European markets, combining probiotics with multiple human milk oligosaccharides.
Market Outlook
The Europe baby care products market is expected to remain a moderate-growth market through 2031 because demographic contraction limits the potential for broad volume expansion. The strongest growth opportunities sit within categories where product functionality can raise spending per child, including specialized infant nutrition, skin-sensitive care, training pants, breastfeeding accessories, child car seats and premium mobility equipment. Baby food and diapers continue to represent the largest revenue pools, but their share of the overall market gradually moderates as faster-growing personal care and durable equipment categories expand.
Distribution is also becoming more digitally weighted. Online retail gains substantial share through subscriptions, marketplaces, online pharmacies and direct-to-consumer platforms, while supermarkets and specialist stores remain important for high-frequency purchases and high-value equipment.
Europe Baby Care Products Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 32.5 billion |
| Total Market Size in 2031 | USD 37.1 billion |
| Forecast Unit | Billion |
| Growth Rate | 2.7% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Distribution Channel, Country |
| Companies |
|
Market Segmentation
By Product Type
Baby Food and Early-Life Nutrition
Infant Formula
Follow-On and Toddler Milk
Baby Cereals
Prepared Baby Food
Snacks and Other Complementary Foods
Diapers and Wipes
Disposable Diapers
Training Pants
Reusable Diapers
Baby Wipes
Baby Skincare and Toiletries
Creams and Lotions
Oils
Shampoo and Hair Care
Bath and Cleansing Products
Diaper Rash Care
Others
Feeding and Nursing Products
Feeding Bottles and Nipples
Cups and Feeding Accessories
Sterilizers
Breastfeeding Accessories
Others
Safety and Travel Equipment
Strollers and Prams
Child Car Seats
Baby Carriers
High Chairs
Others
By Distribution Channel
Online
Brand-Owned Websites
Online Marketplaces
Online Grocery and Pharmacy
Offline
Supermarkets and Hypermarkets
Pharmacies and Drugstores
Specialist Baby Stores
Department Stores
Others
By Country
Germany
United Kingdom
France
Italy
Spain
Poland
Netherlands
Sweden
Denmark
Norway
Belgium
Austria
Switzerland
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Research
2.4. Market Estimation
2.5. Forecast Methodology
2.6. Data Triangulation and Validation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Europe Baby Care Products Market Size, 2026-2031
3.3. Product Category Outlook
3.4. Distribution Channel Outlook
3.5. Country Opportunity Summary
3.6. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Higher Expenditure per Child
4.1.2. Development of Specialized Infant Nutrition
4.1.3. Continuous Improvement in Absorbent Hygiene Products
4.1.4. Expansion of E-Commerce and Subscription Purchasing
4.1.5. Increasing Focus on Safety and Ingredient Transparency
4.2. Market Restraints
4.2.1. Declining European Birth Rates
4.2.2. Price Sensitivity in Recurring Purchases
4.2.3. Complex Regulatory Requirements
4.2.4. Product Recall and Reputation Risk
4.2.5. Second-Hand Competition in Durable Baby Equipment
4.3. Market Opportunities
4.4. Porter’s Five Forces Analysis
4.5. Industry Value Chain Analysis
4.6. Infant Nutrition Regulatory Environment
4.7. Child Product Safety and Chemical Regulation
4.8. Sustainability and Materials Outlook
5. EUROPE BABY CARE PRODUCTS MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Baby Food and Early-Life Nutrition
5.2.1. Infant Formula
5.2.2. Follow-On and Toddler Milk
5.2.3. Baby Cereals
5.2.4. Prepared Baby Food
5.2.5. Snacks and Other Complementary Foods
5.3. Diapers and Wipes
5.3.1. Disposable Diapers
5.3.2. Training Pants
5.3.3. Reusable Diapers
5.3.4. Baby Wipes
5.4. Baby Skincare and Toiletries
5.4.1. Creams and Lotions
5.4.2. Oils
5.4.3. Shampoo and Hair Care
5.4.4. Bath and Cleansing Products
5.4.5. Diaper Rash Care
5.4.6. Others
5.5. Feeding and Nursing Products
5.5.1. Feeding Bottles and Nipples
5.5.2. Cups and Feeding Accessories
5.5.3. Sterilizers
5.5.4. Breastfeeding Accessories
5.5.5. Others
5.6. Safety and Travel Equipment
5.6.1. Strollers and Prams
5.6.2. Child Car Seats
5.6.3. Baby Carriers
5.6.4. High Chairs
5.6.5. Others
6. EUROPE BABY CARE PRODUCTS MARKET BY DISTRIBUTION CHANNEL
6.1. Introduction
6.2. Online
6.2.1. Brand-Owned Websites
6.2.2. Online Marketplaces
6.2.3. Online Grocery and Pharmacy
6.3. Offline
6.3.1. Supermarkets and Hypermarkets
6.3.2. Pharmacies and Drugstores
6.3.3. Specialist Baby Stores
6.3.4. Department Stores
6.3.5. Others
7. EUROPE BABY CARE PRODUCTS MARKET BY COUNTRY
7.1. Introduction
7.2. Germany
7.2.1. By Product Type
7.2.2. By Distribution Channel
7.3. United Kingdom
7.3.1. By Product Type
7.3.2. By Distribution Channel
7.4. France
7.4.1. By Product Type
7.4.2. By Distribution Channel
7.5. Italy
7.5.1. By Product Type
7.5.2. By Distribution Channel
7.6. Spain
7.6.1. By Product Type
7.6.2. By Distribution Channel
7.7. Poland
7.7.1. By Product Type
7.7.2. By Distribution Channel
7.8. Netherlands
7.9. Sweden
7.10. Denmark
7.11. Norway
7.12. Belgium
7.13. Austria
7.14. Switzerland
7.15. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Product Portfolio Positioning
8.3. Premium versus Mass-Market Competition
8.4. Private-Label Participation
8.5. Infant Nutrition Innovation
8.6. Diaper and Wipe Material Innovation
8.7. Baby Skincare and Sensitive-Skin Positioning
8.8. Durable Baby Equipment and Safety Positioning
8.9. E-Commerce and Direct-to-Consumer Strategies
8.10. Mergers, Acquisitions, Agreements and Collaborations
8.11. Competitive Dashboard
9. COMPANY PROFILES
9.1. Procter & Gamble Company
9.2. Essity AB
9.3. Ontex Group NV
9.4. Danone S.A.
9.5. Nestlé S.A.
9.6. HiPP GmbH & Co. Vertrieb KG
9.7. Kenvue Inc.
9.8. Laboratoires Expanscience S.A.
9.9. Artsana S.p.A.
9.10. Goodbaby International Holdings Limited
9.11. Bugaboo International B.V.
9.12. Stokke AS
10. APPENDIX
10.1. Market Definition and Scope
10.2. Product Inclusion and Exclusion Criteria
10.3. Currency and Conversion Assumptions
10.4. Base Year and Forecast Period
10.5. Market Estimation Approach
10.6. Primary and Secondary Research Framework
10.7. Forecast Assumptions
10.8. Data Triangulation and Validation
10.9. Abbreviations
10.10. Key Benefits for Stakeholders
Navigate
Trusted by the world's leading organizations











