
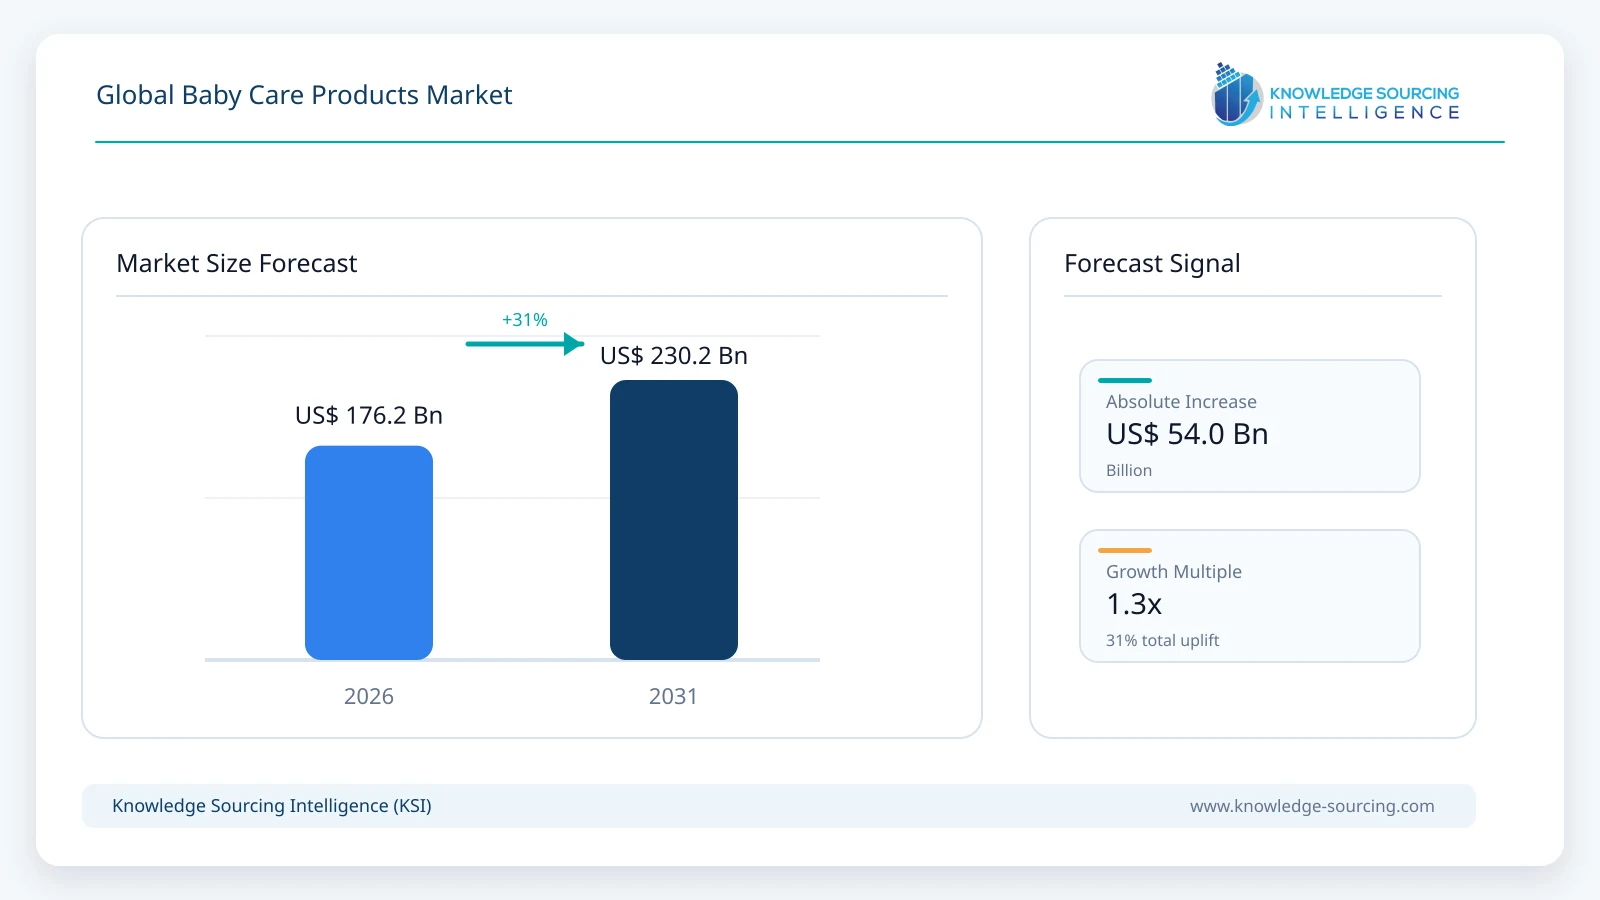
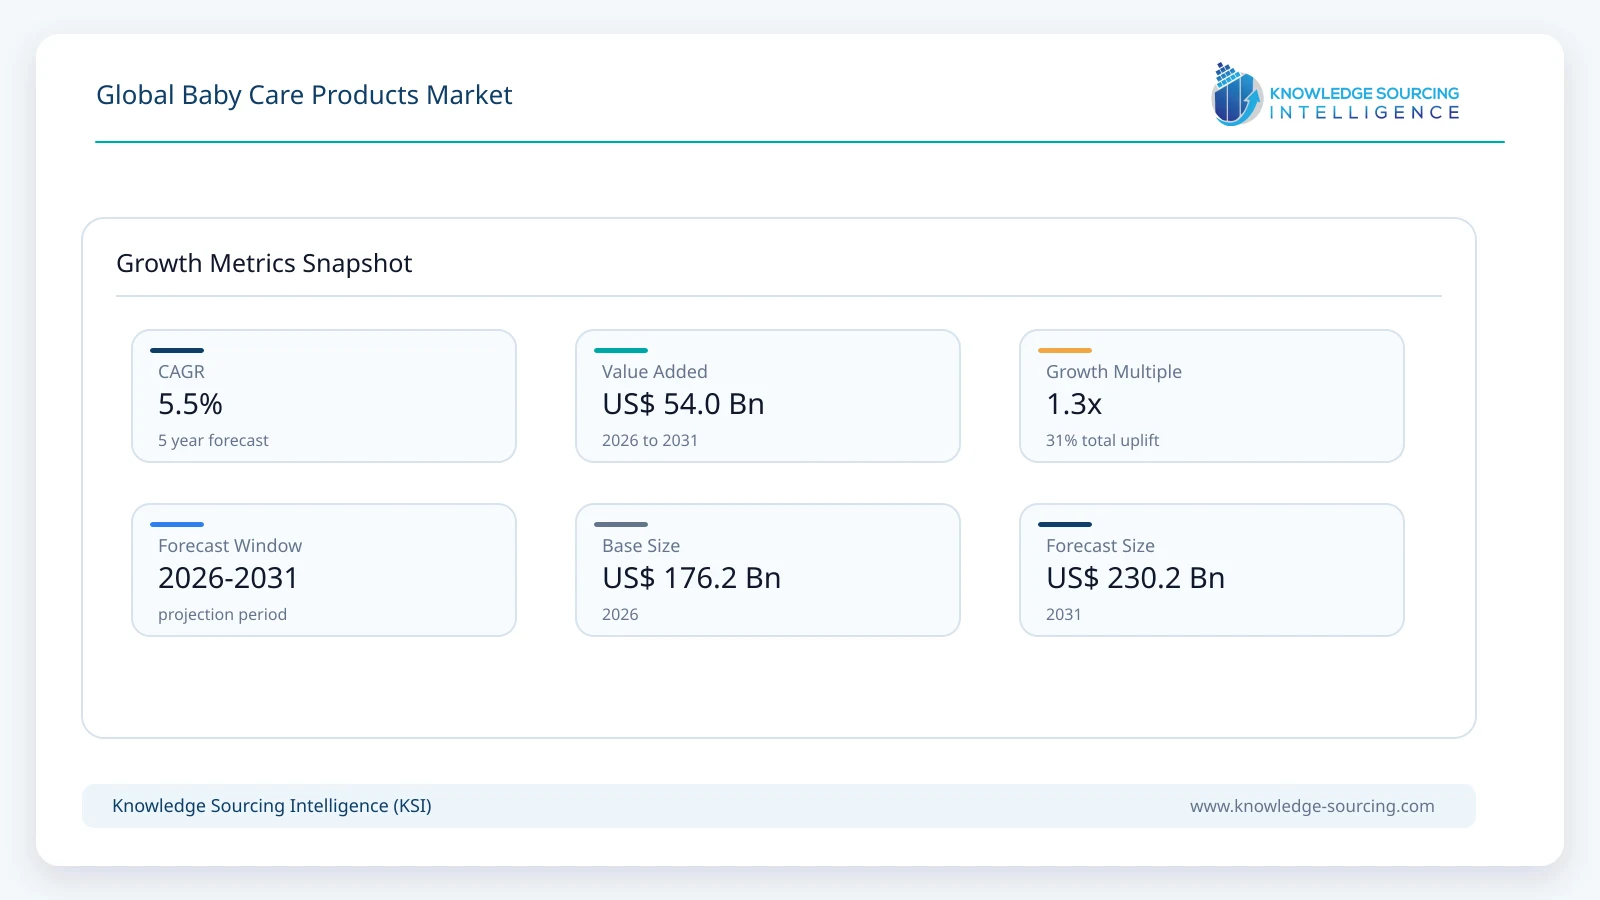
The global baby care products market is estimated at USD 176.2 billion in 2026 and is projected to reach USD 230.2 billion by 2031, representing an average annual growth rate of approximately 5.5% during the forecast period.
Highlights:
- 1Baby food and infant nutrition account for approximately 41.3% of the global market in 2026, supported by premium formula, functional nutrition and growing demand for convenient complementary foods.
- 2Diapers and wipes represent approximately USD 54.9 billion in 2026, although slower birth growth in China, Europe, Japan and South Korea limits volume expansion relative to other baby-care categories.
- 3Baby skin, hair, bath and body care is projected to be one of the faster-growing product groups through 2031, supported by premium dermatological formulations, sensitive-skin positioning and greater ingredient transparency.
- 4Asia Pacific represents the largest regional demand pool, with India and parts of Southeast Asia offsetting weaker infant-population trends in several Northeast Asian markets.
- 5Online channels continue gaining share from traditional specialty and mass-market retail, particularly for diapers, wipes, feeding products and premium baby-care subscriptions.
- 6Premiumization is becoming a more important growth mechanism than population growth alone, with parents spending more per child on convenience, safety, performance and specialized nutrition.
The market covers products purchased specifically for infants and young children, including baby food and infant nutrition, diapers and wipes, baby skin and personal care products, strollers and car seats, feeding and nursing products, and other safety and convenience products. Baby apparel and toys are excluded from the market definition to maintain consistency between consumer-care, nutrition, hygiene and infant-support categories.
Market Overview
The baby care products market is entering a period in which demographic expansion is no longer the primary growth engine in many major economies. Fertility rates have fallen in several developed and middle-income markets, while manufacturers are increasingly generating value through premium products, higher product performance, specialized nutrition, ingredient transparency and greater spending per child. The resulting market structure differs significantly by geography. Mature markets rely heavily on product replacement, premiumization and brand switching, while countries with larger younger populations continue to offer stronger opportunities for household penetration and first-time category adoption.
Large manufacturers are adapting accordingly. P&G reported that its Baby Care business returned to low-single-digit organic sales growth in fiscal 2026, supported by Greater China volume growth and favorable product mix. The company is simultaneously pushing the Pampers portfolio further into premium and super-premium formats. In March 2026, Pampers introduced AMORE in the United States, positioning the product around higher absorbency, skin comfort and premium materials. This illustrates the wider industry movement away from competing only on unit price toward functionality, dermatological claims, material performance and perceived safety.
The same pattern is visible among smaller challengers. Premium diaper brand Coterie exceeded USD 200 million in trailing revenue before its acquisition by Mammoth Brands, after rapid expansion through direct-to-consumer subscriptions and selective retail distribution. Its growth demonstrates that even mature disposable-diaper markets still allow new entrants to gain share when they differentiate through material quality, transparency, performance and recurring purchasing models.
Nutrition remains the largest value component of the market. Nestlé, Danone, Abbott and Reckitt continue to compete across infant formula, growing-up milk, specialized pediatric nutrition and complementary feeding products. Nestlé generated CHF 14.3 billion from its broader Nutrition and Health Science category in 2025 and continues the global rollout of NAN Sinergity, which incorporates probiotics and multiple human milk oligosaccharides. Danone generated approximately EUR 9.3 billion from Specialized Nutrition in 2025 and identifies itself as the world's second-largest early-life nutrition company. These investments reinforce the importance of nutritional science and premium formulation as value-growth drivers even where infant populations are stable or declining.
Baby Care Products Market Drivers
Rising expenditure per child is replacing population growth as a primary value driver
The baby-care industry is increasingly influenced by the amount families spend per child rather than the number of births alone. Lower fertility can, in some households, concentrate disposable income and parental attention on fewer children, supporting demand for premium diapers, clinically positioned skincare, advanced feeding products, higher-end strollers and specialized nutrition. This pattern is particularly visible in developed economies and affluent urban households in Asia, where product differentiation is increasingly based on comfort, safety, convenience, materials and scientific positioning.
P&G's premium Baby Care strategy in Greater China illustrates this change. The company is targeting premium and super-premium diaper segments with material and comfort improvements rather than relying solely on household penetration. CYBEX, part of Goodbaby International, also recorded 13% revenue growth in 2025 despite weak European consumer sentiment and falling birth rates, indicating continued demand for premium juvenile products when brands differentiate on design, functionality and safety.
This trend supports higher market value even when unit demand for basic products grows slowly. Premium disposable diapers, organic or science-backed baby foods, specialty skincare and technologically differentiated travel products can all increase average household expenditure. Manufacturers are therefore allocating R&D and marketing budgets toward higher-margin product architectures, targeted age groups and more specialized consumer needs.
Product safety and ingredient transparency are influencing purchasing decisions
Parents increasingly evaluate baby products according to materials, ingredients, dermatological testing, nutritional formulation and the absence of substances perceived as undesirable. In skincare and hygiene, this is supporting sensitive-skin, fragrance-free, hypoallergenic and naturally positioned products. In diapers, manufacturers are emphasizing softness, absorbency, breathability, skin protection and disclosure of materials. In nutrition, demand is shifting toward products with more sophisticated nutritional profiles, including probiotics, prebiotics, HMOs and age-specific formulations.
Kenvue continues to position Johnson's Baby around infant-skin research and mild formulations, while newer brands such as Coterie have built differentiation partly through third-party product testing and transparency. This is contributing to stronger value growth in baby skin, hair, bath and body care relative to conventional mass-market diaper categories.
Expansion of online purchasing is changing category economics
Baby care is particularly well suited to recurring e-commerce because several major categories are purchased frequently and predictably. Diapers, wipes, infant nutrition, skincare and feeding consumables can be replenished through subscriptions or automated ordering, reducing shopping friction for parents while improving customer retention for brands and retailers.
P&G reported that e-commerce represented approximately 20% of company sales in fiscal 2026 and grew by 6% during the year. DTC-led brands have also demonstrated that online channels can provide a route around conventional shelf-space barriers. Coterie's subscription-heavy business model became a significant component of its rapid revenue growth before expanding into broader retail distribution.
Online retail is therefore expected to gain share during the forecast period, although offline channels remain dominant because infant nutrition, pharmacy products, bulky baby equipment and urgent purchases continue to benefit from physical distribution.
Baby Care Products Market Restraints
Falling birth rates constrain volume growth in major markets
Declining birth rates are the most important structural restraint affecting the market. Japan, South Korea, China and multiple European countries face smaller cohorts of infants and young children, restricting unit demand for diapers, formula, feeding products and baby equipment. Unicharm has explicitly identified declining birth rates as a challenge in several Asian baby-care markets and is responding through premiumization, stronger market-share positions and expansion in higher-growth markets such as India.
The demographic effect is particularly significant for categories where consumption per child has a natural ceiling. A baby can consume only a limited number of diapers, bottles or car seats irrespective of household income. Consequently, manufacturers must increasingly generate growth through price mix, product upgrades, geographical expansion and adjacent products rather than assuming sustained volume growth across all mature markets.
Regulation of infant-formula marketing limits conventional promotional strategies
Infant nutrition is subject to substantially greater regulatory oversight than most consumer categories. WHO and UNICEF recommend exclusive breastfeeding for the first six months of life, followed by appropriate complementary foods while breastfeeding continues. The International Code of Marketing of Breast-milk Substitutes and national implementing regulations restrict how formula and related products can be marketed in many countries.
Regulation intensified further in 2025 when the World Health Assembly adopted measures addressing digital marketing of breast-milk substitutes. These requirements increase compliance complexity for nutrition manufacturers and reduce the extent to which conventional consumer-marketing techniques can be used in early-life nutrition.
Baby Care Products Market Segment Analysis
By Product Type
Baby Food and Infant Nutrition
Baby food and infant nutrition represent the largest product category, accounting for approximately USD 72.8 billion in 2026, or about 41.3% of total market value. The segment includes infant formula, growing-up milk, cereals, purees, prepared baby food, snacks, and specialized early-life nutritional products.
Growth is supported primarily by premium formulation, convenient complementary feeding products, urban working households and rising penetration of packaged baby foods in developing markets. Scientific differentiation has become particularly important in infant formula. Leading companies are increasingly incorporating probiotics, HMOs and other specialized ingredients intended to replicate selected functional characteristics of breast milk while complying with strict regulatory frameworks.
The category is projected to remain the largest product segment through 2031, reaching approximately USD 96.5 billion, although growth varies considerably by geography due to breastfeeding practices, regulation, income, cultural feeding preferences and infant-population trends.
Diapers and Wipes
Diapers and wipes account for approximately USD 54.9 billion in 2026, making them the second-largest product group. Demand is highly recurring but closely linked to the number of infants and toddlers, making this segment more exposed than skincare or accessories to falling birth rates.
Growth is increasingly concentrated in premium pants, high-absorbency products, sensitive-skin designs, environmentally differentiated materials and better fit and leak protection. Manufacturers are also creating wider price ladders to serve both premium urban consumers and price-sensitive households in developing markets.
The segment is projected to reach approximately USD 68.1 billion by 2031, with market value growing more slowly than baby skincare and specialized nutrition because basic diaper usage is already mature in many developed economies.
Baby Skin, Hair, Bath and Body Care
The baby personal-care segment includes moisturizers, creams, oils, shampoo, body wash, powder, rash treatments and related products specifically formulated for babies and toddlers.
The category is expected to grow from approximately USD 18.9 billion in 2026 to USD 26.0 billion by 2031, making it one of the faster-growing segments in the market. Demand increasingly favors mild formulations, skin-barrier protection, dermatologist-supported claims, minimal ingredients and natural or organic positioning.
Unlike diapers, skincare can expand through product assortment and usage occasions. Parents may purchase separate moisturizers, cleansers, rash products, sunscreens and specialty formulations, creating opportunities for brands to increase revenue per household.
Safety and Convenience
Safety and convenience products include prams and strollers, child car seats, baby monitors and selected mobility and safety equipment. The segment is estimated at approximately USD 20.3 billion in 2026.
Growth is driven by stricter safety expectations, replacement cycles, premium design and greater household expenditure on mobility products. Brands such as CYBEX, Chicco, Graco, Britax, Maxi-Cosi and Bugaboo compete on crash protection, ease of installation, weight, foldability, modular design and premium materials.
The segment is projected to reach around USD 27.0 billion by 2031, with value growth outpacing unit growth as premium travel systems and advanced child-safety products increase average selling prices.
Feeding, Nursing and Other Accessories
Feeding and nursing accessories include feeding bottles, nipples, breast-feeding accessories, sterilization products, cups and selected baby-care accessories not captured elsewhere.
The segment is estimated at USD 9.3 billion in 2026 and is expected to reach approximately USD 12.6 billion by 2031. Pigeon reported continued demand across nursing bottles, nipples, baby skincare and baby foods during 2025, demonstrating the resilience of specialized baby-accessory companies even in low-birth-rate markets such as Japan.
Baby Care Products Market Distribution Channel Analysis
The market is divided between offline and online distribution. Offline retail remains the larger channel in 2026, supported by supermarkets, pharmacies, baby-specialty stores, mass merchants and healthcare-linked outlets. Infant formula and health-oriented baby products particularly benefit from pharmacy and specialist distribution because parents often seek trusted brands and product guidance.
Online retail, however, is gaining share rapidly. Replenishment categories such as diapers, wipes and baby food generate recurring purchase frequency, while digital channels give smaller premium brands direct access to parents without the need to secure large-scale physical distribution immediately. Subscription models can further increase customer retention and improve demand predictability.
The online segment is therefore expected to increase its share of market value through 2031, while offline retail remains important for product discovery, urgent purchases, regulated nutrition products and large equipment such as strollers and car seats.
Baby Care Products Market Geographical Outlook
Asia Pacific
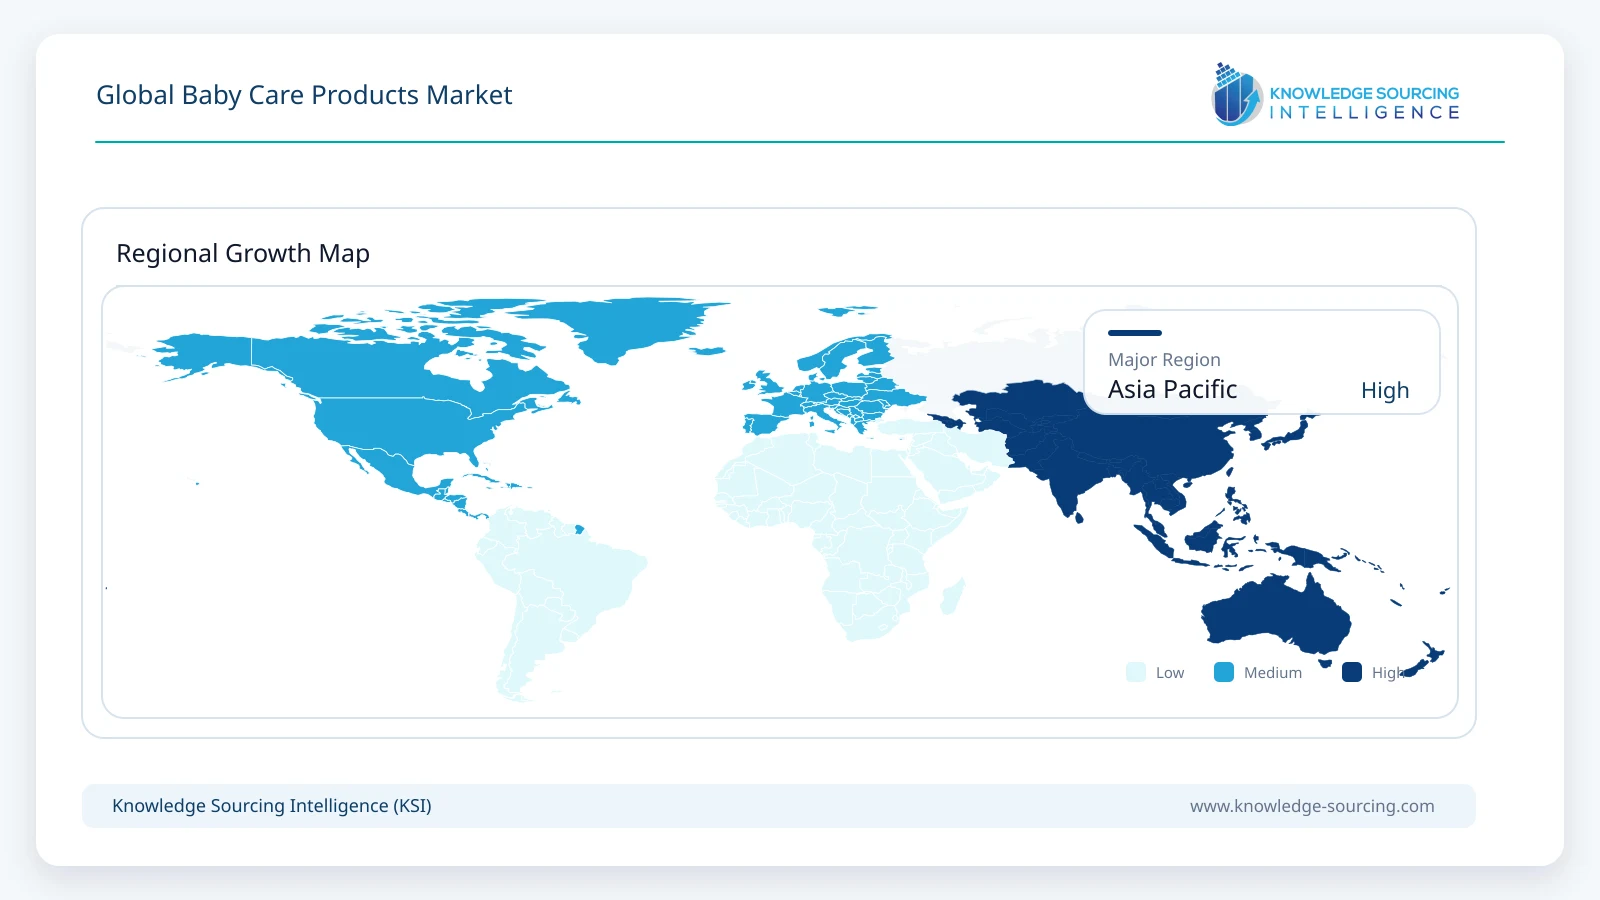
Asia Pacific represents the largest regional market in 2026, estimated at approximately USD 61.5 billion. The region contains sharply contrasting demographic and commercial conditions. China, Japan and South Korea face declining birth cohorts, while India and parts of Southeast Asia continue to provide stronger opportunities for category penetration and expenditure growth.
China remains highly important for premium diapers, nutrition and skincare despite demographic pressure. P&G specifically identifies Greater China Baby Care as an area where premium and super-premium innovation is supporting growth. India is becoming increasingly important for diapers, feeding products, baby skincare and packaged nutrition due to its large child population, urbanization, formal retail expansion and wider e-commerce access.
Asia Pacific is projected to remain the largest regional market through 2031, with growth increasingly shifting toward South and Southeast Asia rather than being evenly distributed across the region.
North America
North America is estimated at approximately USD 43.7 billion in 2026. The region is characterized by high household expenditure per child, established diaper penetration, strong packaged infant-nutrition demand and substantial adoption of premium baby equipment.
The United States is also an important market for new DTC and premium brands. Coterie's rapid expansion and P&G's 2026 launch of Pampers AMORE demonstrate continued willingness among some consumers to pay more for enhanced performance, softness, ingredient transparency and convenience.
Market growth through 2031 is expected to rely more heavily on premiumization, innovation and online retail than on population expansion.
Europe
Europe represents approximately USD 40.2 billion in 2026. Demographic pressure is significant in many European markets, limiting unit growth across diapers, formula and nursery products. However, relatively high disposable incomes, sophisticated retail channels, strict product standards and strong demand for premium safety and personal-care products sustain substantial market value.
Europe is also an important base for manufacturers including Danone, Nestlé, Beiersdorf, Artsana, Ontex, Essity and several premium stroller and car-seat brands. Value growth during the forecast period is expected to come largely from specialized nutrition, skincare, premium equipment and sustainable product design.
Middle East and Africa
The Middle East and Africa market is estimated at approximately USD 17.0 billion in 2026. Growth conditions vary considerably. Gulf economies support premium nutrition, personal care and imported baby equipment, while several African markets remain more dependent on affordable diapers, basic toiletries and packaged food products.
Longer-term population growth and urbanization provide substantial volume potential, although household purchasing power, distribution infrastructure and product affordability remain important constraints.
South America
South America represents approximately USD 13.8 billion in 2026, with Brazil accounting for the largest share. Market development is influenced by inflation, household purchasing power and local manufacturing, while online retail and modern grocery distribution are improving access to premium and imported products.
Competitive Environment
Competition differs considerably by product category. Infant nutrition is led by multinational nutrition companies, diapers by large absorbent-hygiene manufacturers, personal care by consumer-health and beauty companies, and baby equipment by specialist juvenile-product manufacturers.
The market is therefore fragmented at the total-market level despite strong concentration within individual categories.
Major companies operating across the market include:
Procter & Gamble Company
Kimberly-Clark Corporation
Unicharm Corporation
Nestlé S.A.
Danone S.A.
Abbott Laboratories
Reckitt Benckiser Group plc
Kenvue Inc.
Pigeon Corporation
Kao Corporation
Recent Developments
September 2026: Nestlé announced a CHF 310 million Brazil investment by 2028, including a new facility dedicated to infant formula production for domestic and export markets.
August 2026: Abbott launched Similac 360 Total Care Made With Whole Milk, the first commercially sterile, ready-to-feed whole-milk infant formula available in the U.S.
March 2026: P&G launched Pampers AMORE in the United States, its first new Pampers diaper brand for newborns and toddlers since 2018, targeting the premium segment with enhanced absorbency, softness and skin-oriented positioning.
Late 2025: Mammoth Brands acquired premium diaper and baby-care company Coterie after the brand exceeded USD 200 million in trailing revenue and recorded rapid year-over-year expansion.
2025–2026: P&G intensified its premium Baby Care strategy in Greater China through higher-end Pampers products focused on comfort, materials and dryness, while Baby Care returned to low-single-digit organic growth in fiscal 2026.
Baby Care Products Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 176.2 billion |
| Total Market Size in 2031 | USD 230.2 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.5% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Distribution Channel, Geography |
| Companies |
|
Market Segmentation
By Product Type
Baby Food and Infant Nutrition
Diapers and Wipes
Skin, Hair, Bath and Body Care
Safety and Convenience
Prams and Strollers
Car Seats
Baby Monitors and Other Safety Products
Feeding, Nursing and Other Accessories
By Distribution Channel
Online
Offline
Supermarkets and Hypermarkets
Pharmacies and Drug Stores
Baby and Specialty Stores
Other Retail Channels
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Indonesia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1 Market Overview
2.2 Market Definition
2.3 Scope of the Study
2.4 Market Segmentation
2.5 Market Size and Forecast, 2021–2031
3. BUSINESS LANDSCAPE
3.1 Market Drivers
3.2 Market Restraints
3.3 Market Opportunities
3.4 Market Trends
3.5 Porter’s Five Forces Analysis
3.6 Industry Value Chain Analysis
3.7 Pricing and Premiumization Trends
3.8 Regulatory Environment
3.9 E-Commerce and Omnichannel Development
4. CONSUMER AND PRODUCT TRENDS
4.1 Premiumization and Spending per Child
4.2 Natural, Organic and Sensitive-Skin Products
4.3 Infant Nutrition Innovation
4.4 Sustainable Diapers and Packaging
4.5 Subscription and Direct-to-Consumer Models
4.6 Child Safety and Smart Baby Products
5. GLOBAL BABY CARE PRODUCTS MARKET BY PRODUCT TYPE
5.1 Introduction
5.2 Baby Food and Infant Nutrition
5.3 Diapers and Wipes
5.4 Skin, Hair, Bath and Body Care
5.5 Safety and Convenience
5.5.1 Prams and Strollers
5.5.2 Car Seats
5.5.3 Baby Monitors and Other Safety Products
5.6 Feeding, Nursing and Other Accessories
6. GLOBAL BABY CARE PRODUCTS MARKET BY DISTRIBUTION CHANNEL
6.1 Introduction
6.2 Online
6.3 Offline
6.3.1 Supermarkets and Hypermarkets
6.3.2 Pharmacies and Drug Stores
6.3.3 Baby and Specialty Stores
6.3.4 Other Retail Channels
7. GLOBAL BABY CARE PRODUCTS MARKET BY GEOGRAPHY
7.1 Introduction
7.2 North America
7.2.1 By Product Type
7.2.2 By Distribution Channel
7.2.3 By Country
7.2.3.1 USA
7.2.3.2 Canada
7.2.3.3 Mexico
7.3 South America
7.3.1 By Product Type
7.3.2 By Distribution Channel
7.3.3 By Country
7.3.3.1 Brazil
7.3.3.2 Argentina
7.3.3.3 Others
7.4 Europe
7.4.1 By Product Type
7.4.2 By Distribution Channel
7.4.3 By Country
7.4.3.1 United Kingdom
7.4.3.2 Germany
7.4.3.3 France
7.4.3.4 Italy
7.4.3.5 Spain
7.4.3.6 Others
7.5 Middle East and Africa
7.5.1 By Product Type
7.5.2 By Distribution Channel
7.5.3 By Country
7.5.3.1 Saudi Arabia
7.5.3.2 UAE
7.5.3.3 South Africa
7.5.3.4 Others
7.6 Asia Pacific
7.6.1 By Product Type
7.6.2 By Distribution Channel
7.6.3 By Country
7.6.3.1 China
7.6.3.2 Japan
7.6.3.3 India
7.6.3.4 South Korea
7.6.3.5 Indonesia
7.6.3.6 Others
8. COMPETITIVE ENVIRONMENT
8.1 Market Positioning
8.2 Competitive Strategies
8.3 Product Innovation
8.4 Mergers, Acquisitions and Investments
8.5 Company Market Presence
9. COMPANY PROFILES
9.1 Procter & Gamble Company
9.2 Kimberly-Clark Corporation
9.3 Unicharm Corporation
9.4 Nestlé S.A.
9.5 Danone S.A.
9.6 Abbott Laboratories
9.7 Reckitt Benckiser Group plc
9.8 Kenvue Inc.
9.9 Pigeon Corporation
9.10 Kao Corporation
9.11 Beiersdorf AG
9.12 Hengan International Group Company Limited
9.13 Ontex Group NV
9.14 Essity AB
9.15 Artsana Group
9.16 Goodbaby International Holdings Limited
9.17 Newell Brands Inc.
9.18 Dorel Juvenile
9.19 Britax
9.20 Bugaboo International
9.21 Mammoth Brands / Coterie
9.22 The Honest Company
10. APPENDIX
10.1 Research Methodology
10.2 Assumptions
10.3 Currency
10.4 Base and Forecast Years
10.5 Abbreviations
10.6 Key Benefits for Stakeholders
Navigate
Trusted by the world's leading organizations











