
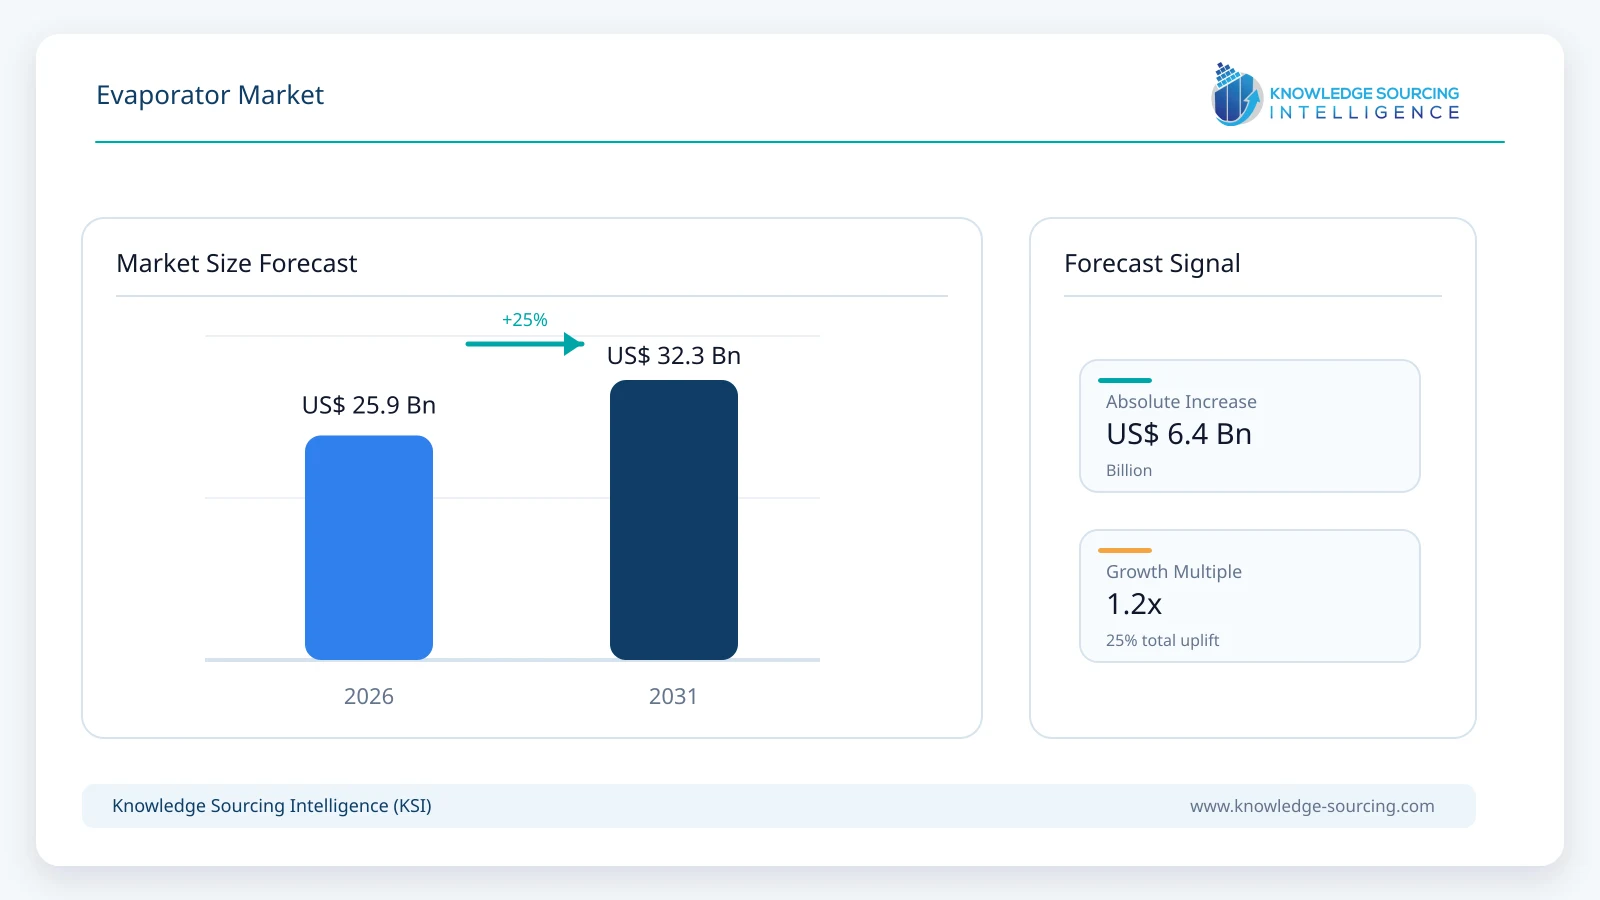
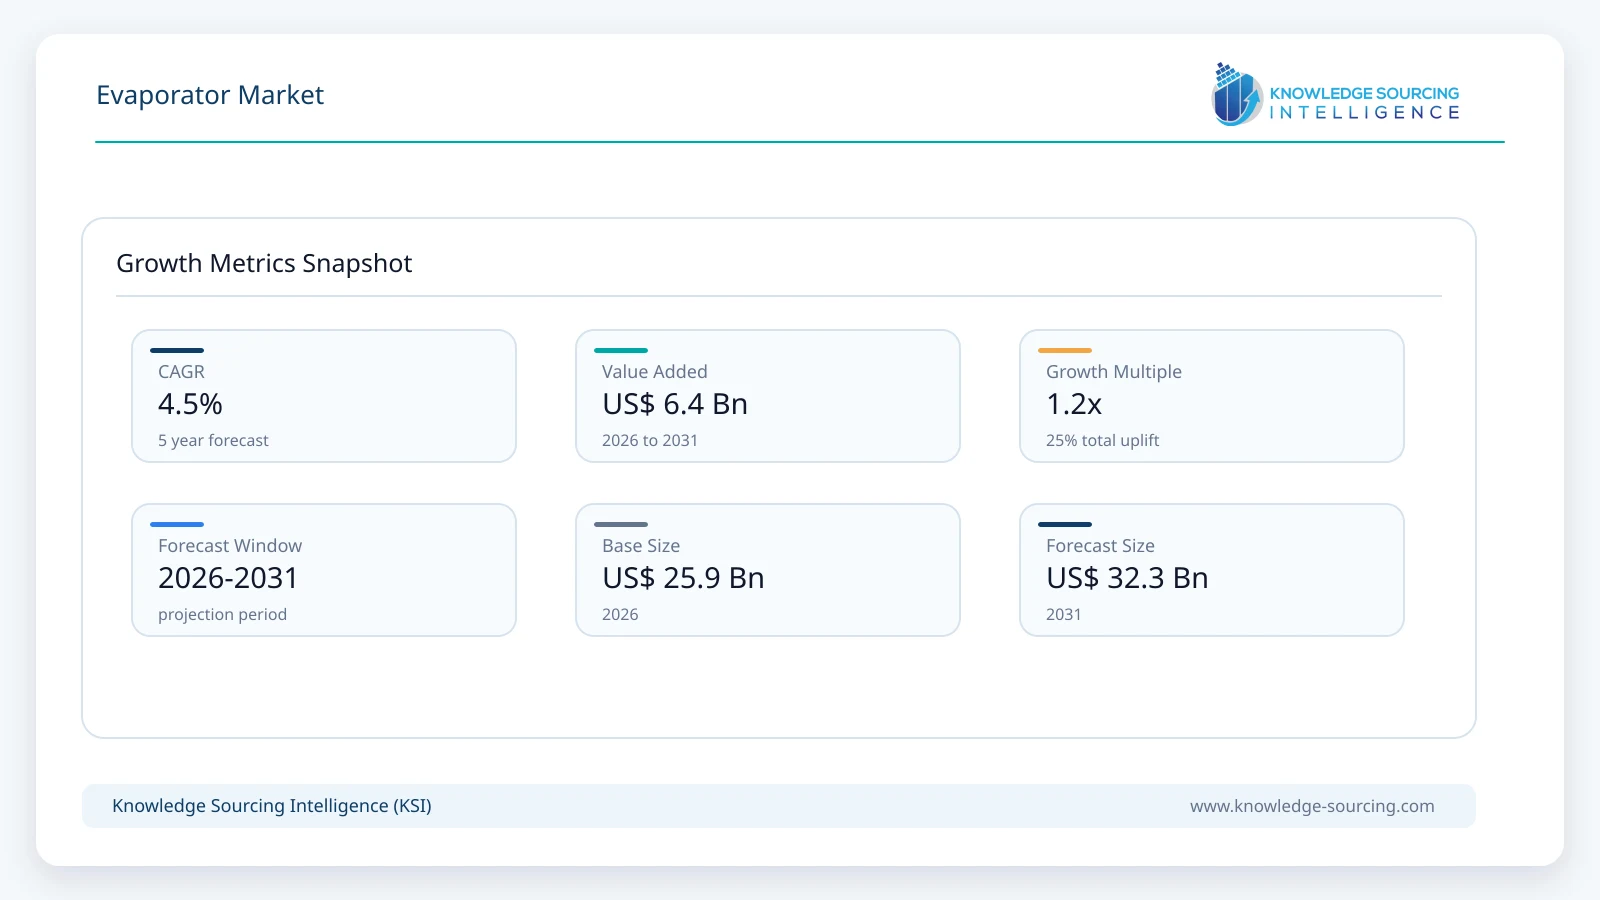
The Evaporator Market is projected to expand at a 4.5% CAGR, attaining USD 32.3 billion in 2031 from USD 25.9 billion in 2026.
Highlights:
- 1Food and beverage processing commands the largest segment share at roughly 30–33%, driven by dairy concentration, juice extracts, sweeteners, and ingredient production that require efficient thermal systems.
- 2Chemical and petrochemical applications account for about 22–25% of demand, relying on evaporators for solvent recovery, brine concentration, and handling corrosive or complex process streams.
- 3Pharmaceutical manufacturing holds nearly 19–20% share, supported by sanitary systems for API concentration, biologics, and strict validation needs in regulated facilities.
- 4Wastewater treatment and water-reuse applications represent a growing portion of demand as industries adopt evaporators for volume reduction and zero-liquid-discharge compliance.
- 5Falling film evaporators continue to lead technology preference in large-scale concentration due to high heat-transfer efficiency and shorter product residence times.
- 6Energy efficiency remains the dominant purchasing criterion across all major end-use segments, influencing selection of multiple-effect and vapor-recompression configurations.
Market Overview
Purchasing decisions increasingly extend beyond initial equipment cost. Industrial buyers evaluate energy efficiency, heat recovery capability, maintenance requirements, automation features, operating reliability, and lifecycle operating costs before selecting evaporator systems. Rising energy prices in many industrial regions have intensified scrutiny of thermal performance, particularly among large-volume processors where evaporation represents a substantial share of total process energy consumption.
Demand conditions remain supported by continued investment in food processing capacity, pharmaceutical manufacturing expansion, industrial water treatment infrastructure, and tightening wastewater discharge requirements. Process manufacturers are seeking technologies that reduce water consumption while improving recovery rates and lowering waste volumes. This shift has strengthened interest in advanced evaporation systems that support both production efficiency and environmental objectives.
Value creation within the market is distributed across equipment manufacturers, engineering contractors, automation providers, heat transfer specialists, service providers, and aftermarket maintenance networks. While equipment sales remain important, lifecycle service contracts, process optimization services, spare parts supply, and modernization projects increasingly contribute to supplier revenue streams. End users are extending asset life through upgrades and automation retrofits rather than relying solely on greenfield investments.
The competitive environment reflects a combination of global process equipment suppliers and specialized evaporation technology providers. Suppliers compete on thermal efficiency, process expertise, application-specific design capabilities, installed base, service support, and ability to integrate evaporation systems into broader processing environments. Industries with stringent hygiene, safety, or regulatory requirements often favor suppliers with established operational references and extensive validation experience.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
Global municipal wastewater is generated annually | More than 360 billion m³ (UNEP estimates) | Expands demand for concentration and wastewater minimization technologies. |
Industrial water demand share | Approximately 20% of global freshwater withdrawals (UN-Water) | Encourages investment in water recovery and reuse systems. |
Global food processing industry output | Multi-trillion-dollar industrial sector | Sustains long-term demand for concentration and dehydration processes. |
Pharmaceutical manufacturing expansion | Ongoing capacity additions across North America, Europe, India, and China | Supports demand for sanitary evaporation systems. |
Industrial energy costs | Elevated relative to pre-2020 levels in many regions | Makes thermal efficiency a critical purchasing criterion. |
Water reuse initiatives | Expanding regulatory adoption globally | Supports investment in advanced evaporation and zero-liquid-discharge systems. |
Key indicator: Industrial facilities account for a substantial share of global water consumption.
Commercial meaning: Water recovery economics increasingly influence evaporator procurement decisions.
Market Drivers
Expansion of processed food and dairy production capacity
Food and beverage manufacturers remain among the largest users of evaporation technologies because concentration processes are essential for dairy products, fruit preparations, coffee extracts, sweeteners, beverages, and ingredients. Capacity additions across dairy processing, infant nutrition, food ingredients, and beverage manufacturing continue to generate equipment demand.
Major processors are investing in higher-throughput facilities while seeking lower energy consumption per unit of output. This has increased demand for multiple-effect evaporators, mechanical vapor recompression systems, and advanced heat recovery configurations. Equipment suppliers capable of reducing operating costs while maintaining product quality are increasingly favored during procurement cycles.
Growing emphasis on industrial water recovery and wastewater reduction
Water scarcity concerns and stricter discharge requirements are altering industrial investment priorities. Manufacturers across chemicals, mining, food processing, pharmaceuticals, and power generation are investing in wastewater minimization technologies that reduce disposal volumes and recover reusable water.
Evaporators play an important role in zero-liquid-discharge and high-recovery treatment systems. Facilities facing higher wastewater treatment costs increasingly evaluate evaporation technologies as a means of reducing disposal expenses and improving environmental compliance. This trend is particularly evident in regions experiencing tightening water regulations and rising water procurement costs.
Increasing pharmaceutical manufacturing investment
Pharmaceutical production requires highly controlled concentration processes that preserve product integrity while meeting stringent quality standards. Expansion of biologics manufacturing, active pharmaceutical ingredient production, and specialty chemical synthesis continues to support demand for sanitary evaporation systems.
Several pharmaceutical manufacturers have announced manufacturing investments across North America, Europe, India, and Asia Pacific during recent years. These facilities require process equipment that complies with strict validation, hygiene, and operational standards. Suppliers with experience in regulated manufacturing environments maintain an advantage in this segment.
Rising focus on energy-efficient thermal processing
Energy consumption represents one of the largest operating expenses associated with evaporation systems. Industrial buyers increasingly evaluate total cost of ownership rather than initial capital expenditure alone. Equipment capable of lowering steam consumption can materially improve project economics.
This purchasing behavior has encouraged suppliers to invest in enhanced heat transfer technologies, vapor recompression systems, digital monitoring tools, and process optimization software. As energy costs remain a strategic concern for manufacturers, efficiency improvements continue to influence replacement and modernization decisions.
Growth of specialty chemical production
Chemical manufacturers rely on evaporation systems for concentration, solvent recovery, crystallization support, and waste reduction. Expansion of specialty chemicals, performance materials, and industrial intermediates has increased demand for process equipment capable of handling corrosive, viscous, and complex feed streams.
Chemical producers often prioritize reliability and operational flexibility because production interruptions can create substantial financial losses. This requirement supports demand for customized evaporation solutions designed for specific process conditions.
Market Restraints and Challenges
High capital requirements for large-scale installations
Industrial evaporation systems frequently require substantial upfront investment, particularly in applications involving multiple-effect configurations, vapor recompression technology, or zero-liquid-discharge infrastructure. Capital requirements extend beyond equipment costs and include engineering, installation, utility integration, and commissioning expenses.
Smaller manufacturers may delay projects when capital budgets are constrained. The challenge is particularly visible in emerging markets where financing conditions can limit investment in advanced processing technologies.
Energy intensity of thermal separation processes
Although modern systems have improved efficiency, evaporation remains an energy-intensive industrial operation. Facilities with limited access to affordable steam, electricity, or waste heat may experience less attractive project economics.
Equipment suppliers continue to address this challenge through heat recovery systems and process optimization technologies. Nevertheless, energy availability and pricing remain influential variables in procurement decisions.
Complex maintenance and operational requirements
Industrial evaporators operate under demanding thermal and mechanical conditions. Fouling, scaling, corrosion, and product buildup can reduce efficiency and increase maintenance frequency. Certain applications require periodic shutdowns for cleaning and inspection.
Maintenance complexity can influence buyer preferences, particularly among facilities operating with limited technical resources. Suppliers increasingly differentiate themselves through service capabilities, predictive maintenance tools, and lifecycle support programs.
Long qualification cycles in regulated industries
Food, pharmaceutical, and specialty chemical manufacturers often require extensive validation before introducing new processing equipment. Qualification procedures may involve performance testing, hygiene verification, regulatory documentation, and process integration assessments.
These requirements can extend project timelines and increase implementation costs. Suppliers with established industry references and compliance expertise are often better positioned to navigate lengthy procurement cycles.
Material and fabrication cost volatility
Manufacturing evaporators requires substantial quantities of stainless steel, specialty alloys, heat transfer components, and engineered systems. Fluctuations in raw material prices can affect project costs and supplier margins.
While manufacturers attempt to manage exposure through procurement strategies and pricing adjustments, prolonged cost volatility can influence purchasing decisions and project timing.
Major Segment Analysis
Food and Beverage End-user Segment
The food and beverage industry represents one of the most commercially important sources of evaporator demand because concentration processes are embedded within numerous production workflows. Dairy products, condensed milk, whey derivatives, fruit concentrates, coffee extracts, flavor ingredients, sugar products, and beverage formulations all rely on evaporation technologies to achieve target product specifications.
Purchasing decisions within this segment emphasize product quality preservation, energy efficiency, hygiene standards, and operational reliability. Food manufacturers face increasing pressure to control production costs while maintaining consistent product characteristics. As a result, buyers often prioritize systems capable of minimizing thermal damage while reducing steam consumption and downtime.
Falling film evaporators receive widespread adoption within food processing because they support efficient heat transfer and shorter product residence times. However, application requirements vary considerably according to product viscosity, fouling characteristics, and concentration targets. Suppliers therefore compete through application expertise rather than equipment supply alone.
Performance within the food and beverage segment has implications across the broader evaporator market. The sector supports recurring modernization activity, aftermarket services, replacement demand, and process optimization projects. Investment patterns among large food processors frequently influence technology adoption trends that later extend into adjacent industrial sectors.
Regional Analysis
Region | Main Demand Signal | Principal Constraint |
North America | Food processing, pharmaceuticals, and industrial water treatment | High project costs and labor expenses |
Europe | Sustainability regulations and resource efficiency mandates | Energy cost pressures |
Asia Pacific | Manufacturing expansion and food processing investment | Uneven technology adoption |
Middle East and Africa | Water reuse and desalination-related demand | Industrial diversification challenges |
South America | Agricultural processing and food exports | Economic volatility |
North America
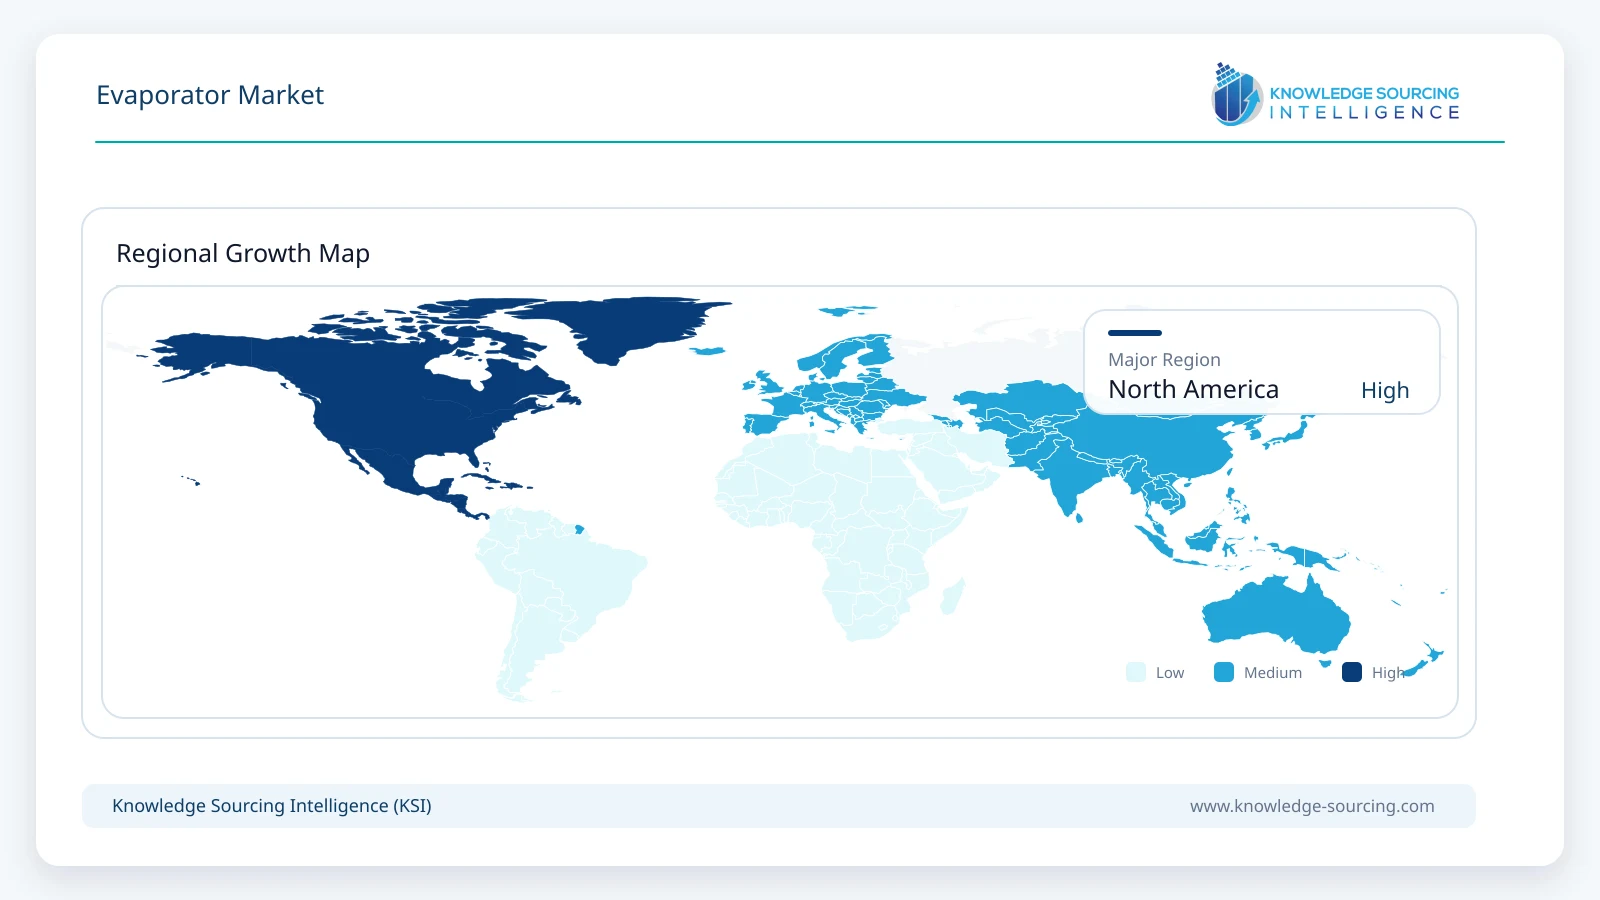
The United States remains the largest regional market contributor due to its extensive food processing, pharmaceutical manufacturing, chemical production, and wastewater treatment infrastructure. Industrial operators increasingly evaluate equipment based on lifecycle operating costs and energy performance. Water reuse initiatives across several states are creating additional opportunities for industrial evaporation technologies.
Canada supports demand through food processing, mining, and industrial water treatment applications. Mexico continues to attract manufacturing investment, creating opportunities for process equipment suppliers serving export-oriented industries.
Europe
European demand is strongly influenced by environmental regulations, industrial efficiency targets, and resource conservation initiatives. Food processing, dairy manufacturing, pharmaceuticals, and specialty chemicals remain important end-use sectors across Germany, France, Italy, and the United Kingdom.
Energy efficiency requirements have elevated interest in vapor recompression technologies and advanced heat recovery systems. Buyers increasingly seek solutions that align operational performance with sustainability objectives and carbon reduction commitments.
Asia Pacific
Asia Pacific represents the broadest industrial opportunity set due to expanding manufacturing activity and rising food processing capacity. China remains a substantial market for industrial process equipment because of its extensive chemical, pharmaceutical, and food production base.
India is experiencing increased investment in food processing, pharmaceutical manufacturing, and wastewater management infrastructure. Japan, South Korea, Taiwan, Thailand, and Indonesia continue to generate demand from specialized manufacturing sectors requiring efficient concentration and separation technologies.
Middle East and Africa
Water availability concerns are shaping procurement priorities across several countries in the region. Industrial facilities increasingly evaluate technologies capable of supporting water recovery, wastewater reduction, and resource optimization objectives.
Saudi Arabia and the UAE continue to invest in industrial diversification initiatives, creating opportunities for process equipment suppliers involved in food production, chemicals, and water treatment applications.
South America
Brazil remains the primary regional market due to its agricultural processing, food manufacturing, sugar production, and industrial processing sectors. Evaporation technologies are widely used in applications associated with food ingredients, beverages, and agricultural products.
Argentina and other regional markets provide additional opportunities, although investment activity may fluctuate according to economic conditions and industrial capital expenditure cycles.
Competitive Landscape
The evaporator market exhibits a moderately fragmented competitive structure characterized by a combination of diversified process equipment suppliers and specialized evaporation technology providers. Competition is influenced by engineering expertise, thermal efficiency, application knowledge, installed base, service capabilities, and project execution experience.
Alfa Laval AB, GEA Group Aktiengesellschaft, and Veolia Group benefit from broad process portfolios and global customer relationships. Their scale enables participation in complex projects involving food processing, water treatment, and industrial manufacturing applications.
SPX Flow Inc., Koch Separation Solutions, and Dedert Corporation maintain positions through specialized process expertise and application-focused engineering capabilities.
Competition increasingly centers on:
Energy efficiency improvements
Heat recovery technologies
Digital monitoring and process optimization
Lifecycle service offerings
Customized engineering solutions
Water recovery and sustainability applications
Barriers to entry remain meaningful because industrial buyers often require proven operating references, process validation expertise, engineering capability, and long-term service support. Supplier credibility becomes particularly important in regulated industries such as food processing and pharmaceuticals.
Manufacturers are responding to industry challenges through expanded service networks, investment in automation technologies, process optimization tools, and solutions designed to reduce energy consumption and operating costs. These strategies support customer retention while creating recurring aftermarket revenue opportunities.
Recent Developments
May 2026: GEA launches meVap® product family, introducing electrically driven mechanical vapor recompression solutions for evaporation, distillation, crystallization, and industrial steam generation, supporting energy efficiency and industrial decarbonization.
February 2026: Daikin Australia launched its DeVap evaporator range, enabling a complete turnkey refrigeration offering. Designed for local conditions, the range improves installation efficiency, maintenance simplicity, and commercial refrigeration performance.
January 2026: Alfa Laval supports ITC’s BCTMP black liquor evaporation project, developing an evaporator plant for India’s paper industry designed to support process integration and zero-liquid-discharge objectives at the new pulp mill.
October 2025: Kaltra introduced a new generation of microchannel evaporator coils engineered for reversible heat-pump operation. The design improves refrigerant distribution, condensate management, energy efficiency, and operational stability under demanding conditions.
Regulatory and Policy Environment
Industrial water management regulations are becoming increasingly important drivers of evaporator investment. Authorities in North America, Europe, the Middle East, and parts of Asia have strengthened requirements related to wastewater discharge, water reuse, and environmental performance. Facilities operating in water-stressed regions face growing pressure to reduce consumption and improve recovery rates.
Food and beverage applications are influenced by hygiene, safety, and processing standards established by national regulators and international food safety frameworks. Equipment suppliers serving these industries must demonstrate compliance with sanitation requirements, material standards, and validation procedures.
Pharmaceutical applications operate under even stricter controls. Manufacturing equipment must satisfy regulatory expectations regarding product quality, contamination prevention, traceability, and process consistency. Compliance requirements increase development and qualification costs but also create barriers to entry for less established suppliers.
Trade policies, industrial localization initiatives, and environmental regulations may influence future procurement patterns. Suppliers with geographically diversified manufacturing footprints and regional service capabilities are generally better positioned to adapt to changing regulatory requirements.
Outlook and Strategic Implications
Demand during the 2026-2031 period is expected to remain closely linked to industrial efficiency objectives, water management priorities, food processing expansion, and pharmaceutical manufacturing investment. Buyers are increasingly evaluating evaporation technologies through the lens of lifecycle economics rather than equipment acquisition cost alone.
Several strategic themes are expected to influence market performance:
Energy efficiency will remain a primary competitive differentiator.
Water recovery applications will receive greater investment attention.
Digital monitoring and predictive maintenance capabilities will become more common procurement requirements.
Service and aftermarket revenue will represent a larger share of supplier business models.
Regulatory compliance expertise will remain important in food and pharmaceutical applications.
For manufacturers, the ability to deliver measurable reductions in energy consumption and operating costs is likely to influence competitive positioning. For industrial buyers, equipment selection will increasingly balance production performance, environmental compliance, and long-term operating economics. Suppliers capable of integrating process expertise, thermal efficiency, automation, and lifecycle support are expected to remain well-positioned as investment priorities continue to evolve across global process industries.
Evaporator Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 25.9 billion |
| Total Market Size in 2031 | USD 32.3 billion |
| Forecast Unit | USD Billion |
| Growth Rate | 4.5% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Material, End-user, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Falling Film Evaporator
Rising Film Evaporator
Forced Circulation Evaporator
Others
By Material
Stainless Steel
Copper
Aluminum
By End-User
Food and Beverage
Pharmaceuticals
Chemicals
Water and Wastewater
Others
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Taiwan
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. EVAPORATOR MARKET BY TYPE
5.1. Introduction
5.2. Falling Film Evaporator
5.3. Rising Film Evaporator
5.4. Forced Circulation Evaporator
5.5. Others
6. EVAPORATOR MARKET BY MATERIAL
6.1. Introduction
6.2. Stainless Steel
6.3. Copper
6.4. Aluminum
7. EVAPORATOR MARKET BY END-USER
7.1. Introduction
7.2. Food and Beverage
7.3. Pharmaceuticals
7.4. Chemicals
7.5. Water and Wastewater
7.6. Others
8. EVAPORATOR MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. By Type
8.2.2. By Material
8.2.3. By End-User
8.2.4. By Country
8.2.4.1. USA
8.2.4.2. Canada
8.2.4.3. Mexico
8.3. South America
8.3.1. By Type
8.3.2. By Material
8.3.3. By End-User
8.3.4. By Country
8.3.4.1. Brazil
8.3.4.2. Argentina
8.3.4.3. Others
8.4. Europe
8.4.1. By Type
8.4.2. By Material
8.4.3. By End-User
8.4.4. By Country
8.4.4.1. Germany
8.4.4.2. France
8.4.4.3. United Kingdom
8.4.4.4. Spain
8.4.4.5. Italy
8.4.4.6. Others
8.5. Middle East and Africa
8.5.1. By Type
8.5.2. By Material
8.5.3. By End-User
8.5.4. By Country
8.5.4.1. Saudi Arabia
8.5.4.2. UAE
8.5.4.3. Others
8.6. Asia Pacific
8.6.1. By Type
8.6.2. By Material
8.6.3. By End-User
8.6.4. By Country
8.6.4.1. China
8.6.4.2. India
8.6.4.3. Japan
8.6.4.4. South Korea
8.6.4.5. Indonesia
8.6.4.6. Thailand
8.6.4.7. Taiwan
8.6.4.8. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. ENCON Evaporators
10.2. Alfa Laval AB
10.3. GEA Group Aktiengesellschaft
10.4. Koch Separation Solutions
10.5. SPX Flow Inc.
10.6. Sumitomo Heavy Industries, Ltd.
10.7. Veolia Group
10.8. Bucher Unipektin AG
10.9. DE DIETRICH
10.10. Organomation
10.11. Dedert Corporation
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key benefits for the stakeholders
11.5. Research Methodology
11.6. Abbreviations





Frequently asked questions
What is the projected Evaporator Market size by 2031?
The Evaporator Market is projected to attain USD 32.3 billion by 2031.
What is the forecasted CAGR for the Evaporator Market (2026-2031)?
The Evaporator Market is projected to expand at a 4.5% CAGR.
Which industry segment drives the largest evaporator demand?
Food and beverage processing remains the largest source of demand.
What are the primary growth drivers for the Evaporator Market?
Food processing, water treatment, and wastewater discharge requirements drive growth.
What are key purchasing considerations for evaporator systems?
Buyers prioritize energy efficiency, heat recovery, and lifecycle operating costs.
Which evaporator system type is preferred in large-scale concentration?
Falling film systems continue to receive preference in thermal concentration.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Evaporator Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/evaporator-market