
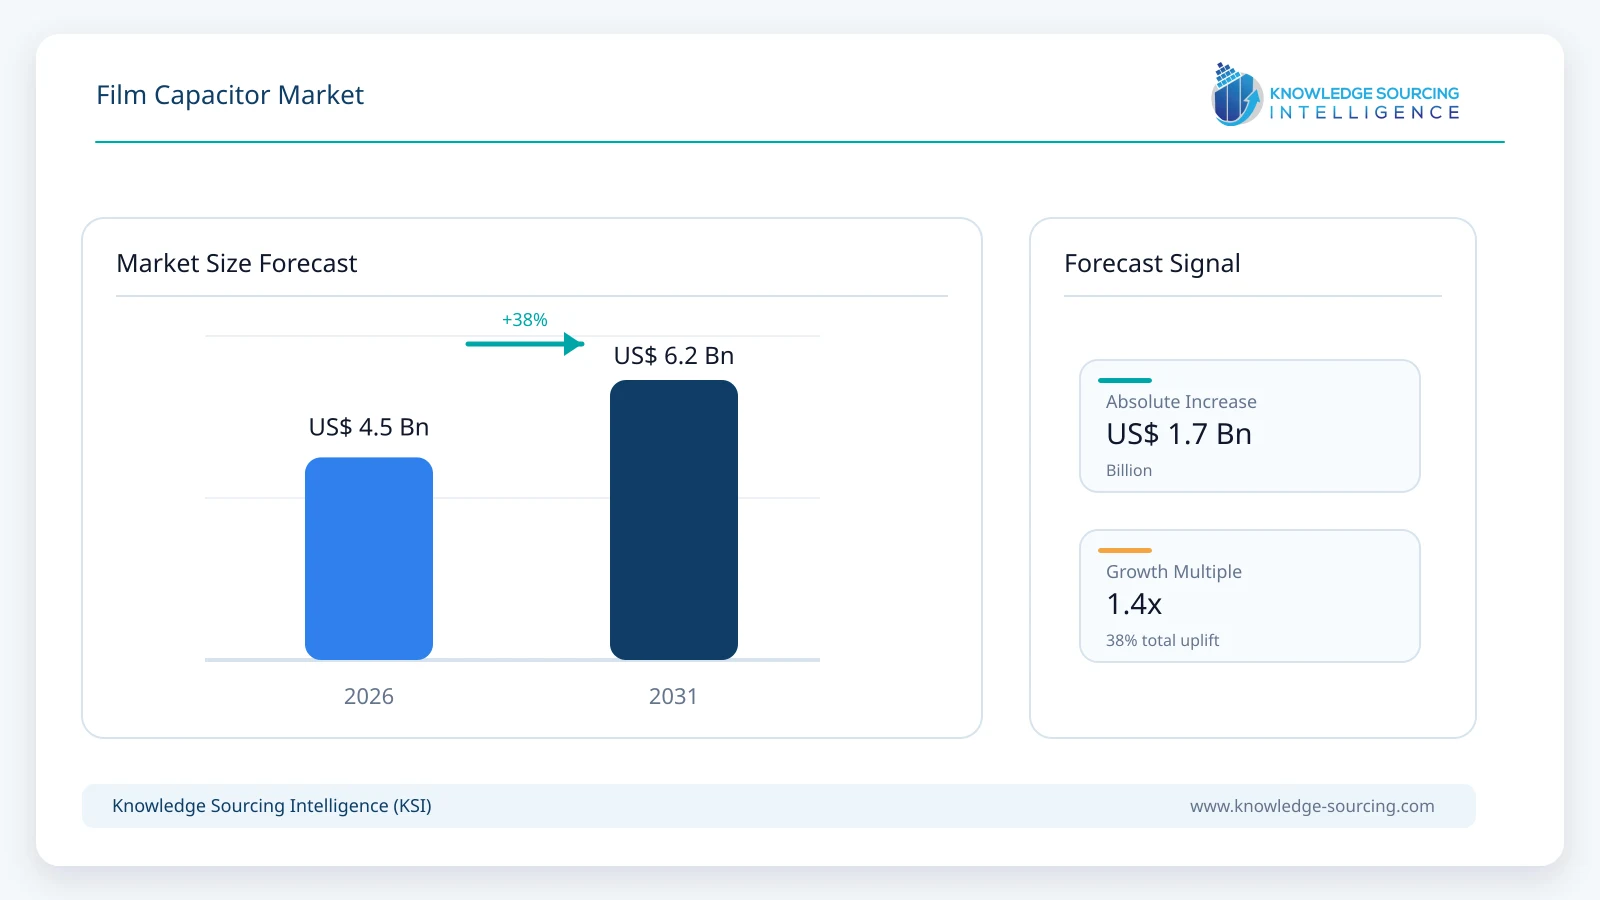
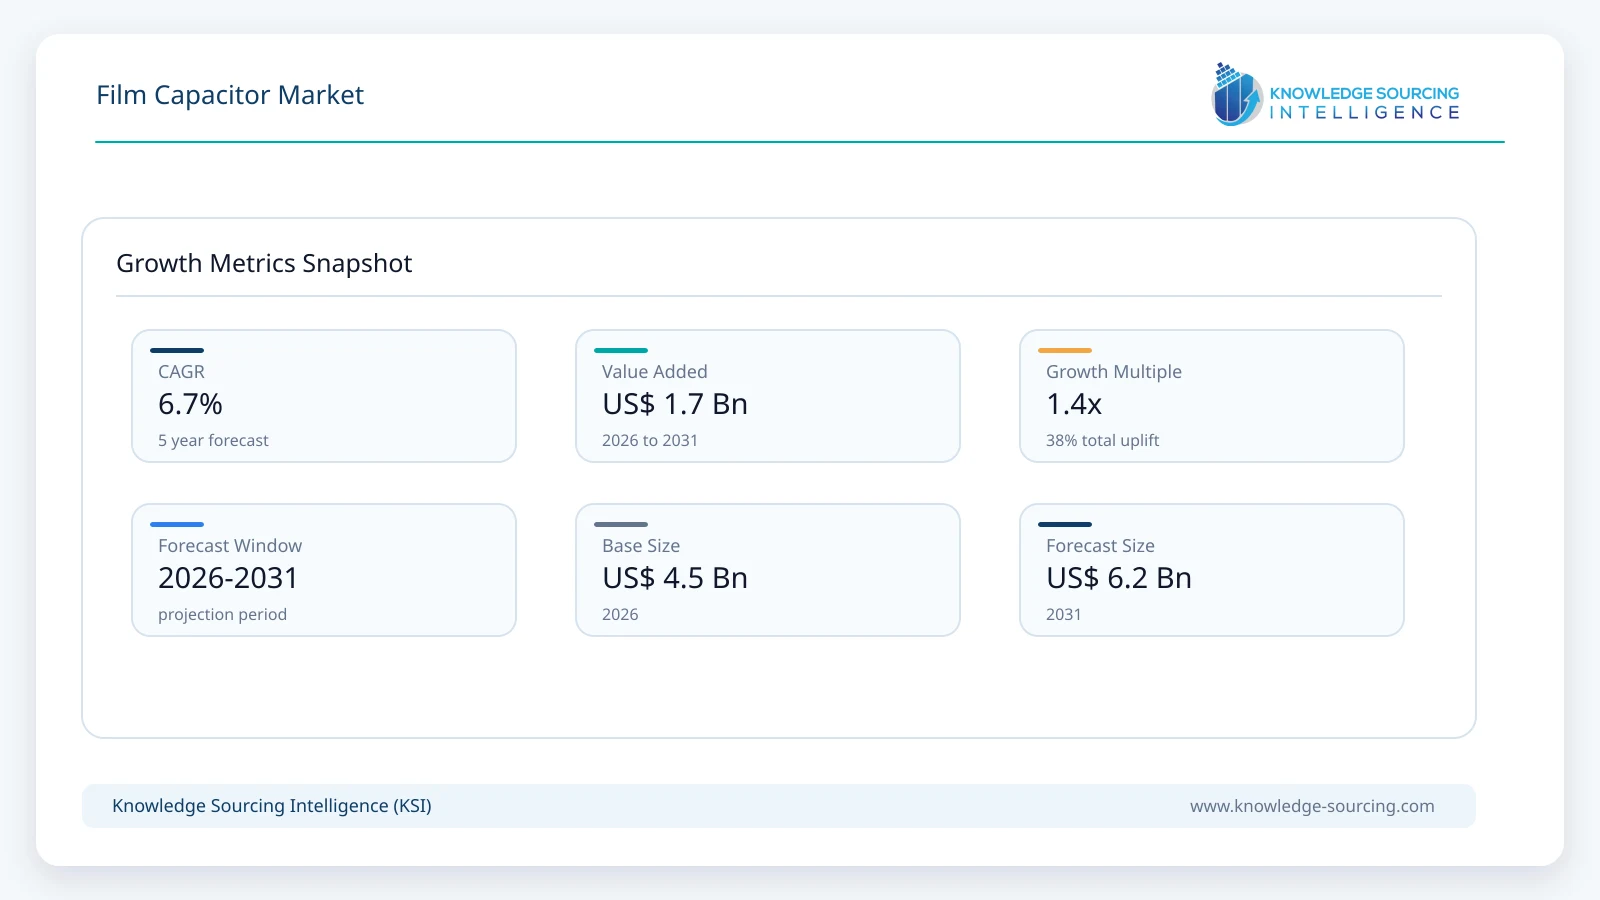
The film capacitor market is evaluated at USD 4.45 billion in 2026 growing at a CAGR of 6.68% reaching the market size of USD 6.15 billion by 2031.
Highlights:
- 1Increasing electrification across automotive and industrial systems is expanding demand for high-reliability film capacitors.
- 2Power electronics for renewable energy and grid infrastructure continue to strengthen procurement of polypropylene film capacitors.
- 3Automotive OEMs increasingly prioritize capacitors with higher temperature tolerance, longer operating life, and improved self-healing characteristics.
- 4Regional manufacturing expansion and supply-chain localization are reshaping sourcing strategies for passive electronic components.
- 5Product differentiation increasingly depends on reliability, miniaturization, safety certifications, and application-specific performance rather than price alone.
The use of film capacitors extends beyond conventional electronic circuits into electric mobility, renewable energy systems, industrial automation, telecommunications infrastructure, aerospace electronics, and medical equipment, where long operating life and predictable electrical performance remain essential purchasing criteria. Buyers increasingly evaluate total lifecycle performance rather than component cost alone, particularly in applications where capacitor failure may disrupt high-value equipment or critical infrastructure.
Demand is increasingly supported by power conversion applications that require efficient energy storage, filtering, voltage smoothing, and electromagnetic interference suppression. According to the International Energy Agency (IEA), continued additions of renewable power generation and expanding electrification across transport and industry are increasing deployment of power electronic equipment that depends on reliable passive components. At the same time, automotive manufacturers continue increasing electronic content per vehicle as electrified powertrains, onboard charging systems, advanced driver assistance systems (ADAS), and high-voltage architectures become more common.
Competition extends across material technology, manufacturing precision, application expertise, certification capability, and long-term supply reliability. Customers in automotive, industrial, and energy applications typically require extensive qualification processes before approving new suppliers, creating relatively high switching costs once production programs begin. Consequently, manufacturers compete through application engineering, product consistency, localized technical support, and manufacturing investments alongside continuous improvements in dielectric materials and capacitor packaging.
Supply-chain resilience has also become a commercial consideration. Manufacturers are expanding regional production capacity, strengthening supplier diversification, and increasing automation to improve delivery reliability while managing fluctuations in raw material availability and customer procurement cycles.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
Global renewable electricity capacity additions | Over 580 GW (2024) according to the International Energy Agency | Expanding inverter installations increase demand for DC-link and power conversion film capacitors. |
Global electric vehicle sales | More than 17 million vehicles (2024) according to the International Energy Agency | Higher EV production raises consumption of high-voltage film capacitors used in onboard chargers, traction inverters, and auxiliary electronics. |
Industrial robot installations | Over 540,000 units installed globally (2023) according to the International Federation of Robotics | Factory automation increases demand for motor drives, servo systems, and industrial power electronics incorporating film capacitors. |
Global data traffic | Continued annual expansion reported by major telecom infrastructure providers and network equipment manufacturers | Network modernization supports capacitor demand across telecommunications power supplies and base station equipment. |
Utility-scale renewable power investment | Continuing annual expansion supported by public and private infrastructure investment | Higher deployment of power conversion systems increases procurement of high-reliability capacitor technologies. |
Key indicator: Global EV sales exceeded 17 million vehicles in 2024, according to the International Energy Agency.
Commercial meaning: Higher vehicle electrification increases demand for high-voltage film capacitors across traction, charging, and power management systems.
Market Drivers
Expansion of electric vehicle power electronics is increasing demand for high-voltage film capacitors
Electric vehicle production continues to increase the use of high-performance film capacitors because traction inverters, DC-DC converters, onboard chargers, battery management systems, and auxiliary power modules require components capable of handling high voltages, elevated temperatures, and frequent switching cycles. The International Energy Agency reported that global electric vehicle sales surpassed 17 million units in 2024, reflecting sustained investment by vehicle manufacturers in electrified platforms. Automotive suppliers are simultaneously introducing higher-voltage architectures that require improved dielectric performance and thermal stability. Manufacturers including Panasonic Corporation, TDK Corporation, Vishay Intertechnology, and KYOCERA AVX continue expanding capacitor portfolios optimized for automotive qualification standards, reflecting sustained procurement from OEMs and Tier 1 suppliers rather than short-term replacement demand.
Renewable energy deployment is strengthening procurement across power conversion equipment
Utility-scale solar, wind, and energy storage installations rely extensively on power conversion systems where film capacitors perform DC-link filtering, voltage stabilization, harmonic suppression, and inverter protection. According to the International Energy Agency, renewable electricity capacity additions reached record levels during 2024, requiring continued deployment of inverters and power conditioning equipment throughout generation and grid infrastructure. Procurement decisions increasingly emphasize operating lifetime, thermal endurance, and maintenance requirements because inverter reliability directly affects plant availability and operating costs. Companies including WIMA GmbH & Co. KG, KEMET (YAGEO), and Cornell Dubilier continue expanding products designed for renewable energy, industrial drives, and high-power converter applications where long operating life supports lower lifecycle costs.
Industrial automation and variable-frequency drives are increasing replacement and new installation demand
Manufacturing facilities continue investing in automation to improve productivity, energy efficiency, and operational consistency. Variable-frequency drives, programmable automation systems, industrial robotics, and motor control equipment require film capacitors for power conditioning, electromagnetic interference suppression, and energy storage. According to the International Federation of Robotics, global industrial robot installations remained above half a million units annually, indicating sustained investment in automated manufacturing capacity. Equipment manufacturers increasingly specify capacitors capable of operating continuously under elevated temperatures and fluctuating electrical loads. Suppliers are responding by expanding application-specific product ranges, improving self-healing dielectric technologies, and increasing production efficiency to support long equipment operating cycles across industrial installations.
Miniaturization of electronic systems is raising performance requirements for passive components
Consumer electronics, telecommunications equipment, medical devices, and aerospace electronics continue to incorporate higher circuit density while maintaining strict reliability requirements. Design engineers increasingly seek capacitors offering stable capacitance, low equivalent series resistance, compact dimensions, and extended operational life within constrained board space. Telecommunications infrastructure upgrades and advanced medical electronics further increase demand for highly reliable passive components capable of continuous operation under demanding environmental conditions. Companies including Nichicon Corporation, Panasonic Corporation, and TDK Corporation continue investing in materials engineering and manufacturing technologies that improve volumetric efficiency without compromising electrical stability, enabling suppliers to address increasingly demanding customer specifications across multiple end-use industries.
Market Restraints and Challenges
Raw material cost fluctuations continue to pressure manufacturing economics.
Film capacitor production depends on polymer dielectric films, metallization materials such as aluminum and zinc, copper terminations, epoxy resins, and engineered plastics whose prices are influenced by petrochemical markets, energy costs, and metal supply conditions. Several capacitor manufacturers, including TDK Corporation, YAGEO, Vishay Intertechnology, and Panasonic Holdings, have identified raw material price movements and supply-chain volatility as recurring business risks in their annual reports. Although manufacturers increasingly adopt long-term sourcing agreements and manufacturing automation, sustained input-cost inflation can compress margins, particularly for standardized products where customer contracts limit immediate price adjustments.
Automotive and industrial qualification cycles slow supplier expansion.
Entering automotive, aerospace, medical, and industrial applications requires extensive qualification, reliability validation, and compliance with international quality standards before production approval. Customers generally evaluate component performance under temperature cycling, humidity exposure, vibration, electrical endurance, and long-term operating conditions. These approval processes often extend over several quarters, delaying revenue generation for newly introduced products. Established suppliers therefore benefit from existing customer relationships and proven field performance, while smaller manufacturers face higher certification costs and longer commercialization timelines before achieving production-scale orders.
Miniaturization requirements increase manufacturing complexity.
Electronic equipment manufacturers continue reducing product size while increasing operating voltage, switching frequency, and thermal performance. This combination places greater demands on dielectric film quality, metallization precision, winding technology, encapsulation processes, and production consistency. Even minor manufacturing defects can affect electrical performance or operational lifetime in high-reliability applications. To address these challenges, manufacturers continue investing in precision production equipment, automated inspection systems, and materials research. These investments improve product consistency but increase capital requirements and raise barriers for new entrants seeking to compete in premium application segments.
Trade restrictions and regional supply-chain adjustments affect procurement decisions.
Electronic component supply chains remain internationally integrated, with raw materials, dielectric films, metallization processes, and final assembly frequently distributed across multiple countries. Export controls, changing tariff policies, regional content requirements, and logistics disruptions have encouraged manufacturers to diversify production footprints and establish additional regional manufacturing capacity. While these initiatives strengthen long-term supply resilience, they also increase operating costs, inventory requirements, and capital investment during the transition period. Buyers increasingly assess supplier resilience alongside product performance when awarding long-term sourcing contracts.
Major Segment Analysis
Polypropylene (PP) Film Capacitors
Polypropylene (PP) film capacitors represent one of the most commercially important product categories because they combine low dielectric loss, excellent insulation resistance, strong self-healing capability, and long operational life under demanding electrical conditions. These characteristics make them particularly suitable for DC-link circuits, power factor correction equipment, renewable energy inverters, industrial motor drives, electric vehicle power electronics, and high-frequency switching applications where electrical stability directly influences overall system reliability.
Purchasing decisions within this segment extend well beyond capacitance ratings. Industrial equipment manufacturers, automotive suppliers, and renewable energy developers increasingly evaluate operating temperature, voltage endurance, expected service life, safety certification, and performance under continuous switching conditions before approving suppliers. Manufacturers including WIMA GmbH & Co. KG, TDK Corporation, Panasonic Corporation, KEMET (YAGEO), and Cornell Dubilier continue expanding polypropylene-based product portfolios designed for high-power applications. Although polyester and polyphenylene sulfide film capacitors remain suitable for compact electronic assemblies and specialized environments, polypropylene capacitors continue receiving sustained investment because their electrical performance aligns closely with evolving requirements in electrification, industrial automation, and renewable power conversion systems.
Regional Analysis
Region | Main Demand Signal | Principal Constraint |
North America | Electric vehicle production, renewable energy investment, industrial automation | Higher manufacturing costs and dependence on imported passive components |
Europe | Automotive electrification, industrial equipment manufacturing, renewable energy expansion | Energy costs and increasingly stringent environmental compliance requirements |
Asia Pacific | Electronics manufacturing, semiconductor production, EV supply chain expansion | Competitive pricing pressure and periodic supply-chain concentration risks |
Middle East and Africa | Grid modernization, industrial projects, renewable energy deployment | Limited local component manufacturing and import dependence |
North America maintains steady demand through investments in electric mobility, renewable electricity infrastructure, aerospace systems, industrial automation, and advanced manufacturing. The United States remains the largest regional consumer owing to its diversified electronics and automotive industries, while Canada and Mexico contribute through automotive manufacturing and integrated North American supply chains. Procurement increasingly emphasizes long-term supply reliability, technical support, and compliance with automotive and industrial quality standards rather than component pricing alone.
European demand is supported by strong automotive manufacturing, industrial automation, renewable energy deployment, and stringent energy-efficiency requirements. Germany continues to represent an important production and technology center for industrial electronics and electric mobility, while France, the United Kingdom, and Spain contribute through renewable energy projects, transportation electrification, and advanced manufacturing. European buyers generally place greater emphasis on product reliability, lifecycle performance, environmental compliance, and supplier traceability, encouraging manufacturers to strengthen regional engineering support and localized production capabilities.
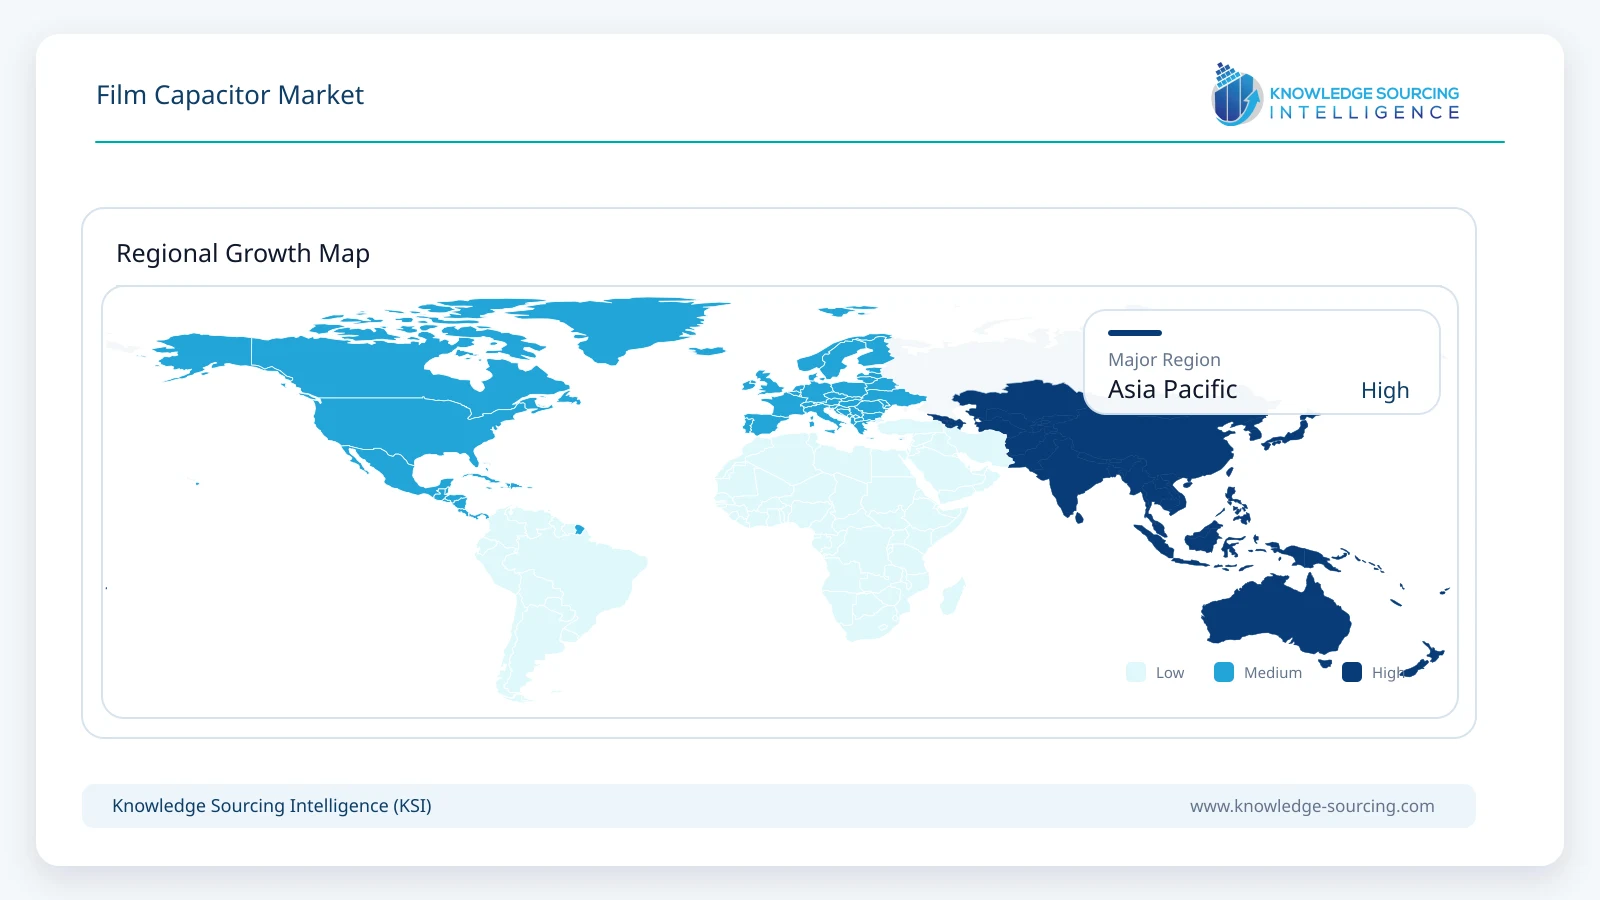
Asia Pacific remains the largest manufacturing base for electronic components, consumer electronics, industrial equipment, and electric vehicles. China, Japan, South Korea, Taiwan, and increasingly India serve as important production centers for semiconductor devices, automotive electronics, telecommunications equipment, and power conversion systems that incorporate film capacitors. Government initiatives supporting semiconductor manufacturing, domestic electronics production, renewable energy expansion, and electric mobility continue strengthening regional demand. At the same time, intense competition and customer expectations for shorter delivery times encourage suppliers to invest in automation, production efficiency, and localized supply chains.
The Middle East and Africa are gradually expanding demand through renewable energy installations, electricity transmission upgrades, industrial diversification programs, telecommunications infrastructure, and transportation modernization. Saudi Arabia and the United Arab Emirates continue investing in power infrastructure and industrial development, creating additional opportunities for high-reliability power electronic components. However, much of the region remains dependent on imported electronic components, making procurement sensitive to logistics costs, foreign exchange movements, and international supply-chain conditions.
Competitive Landscape
Competition in the film capacitor market is technology-led and application-driven rather than purely price-based. Suppliers differentiate through dielectric material expertise, manufacturing precision, product reliability, safety certifications, application engineering, and long-term supply capability. Automotive, industrial, aerospace, and medical customers typically maintain rigorous supplier qualification processes, creating relatively high switching costs once components are approved for production programs.
WIMA GmbH & Co. KG, KEMET (YAGEO), Cornell Dubilier, Panasonic Corporation, TDK Corporation, Vishay Intertechnology, KYOCERA AVX Components Corporation, and Nichicon Corporation continue expanding application-specific product portfolios for electric mobility, renewable energy systems, industrial automation, telecommunications, and high-performance electronic equipment. Competition increasingly centers on higher-temperature operation, improved self-healing characteristics, compact package designs, and extended operating life. Manufacturers are also investing in production automation, regional manufacturing capacity, digital quality control, and supply-chain diversification to improve delivery reliability while addressing customer expectations for shorter lead times and consistent product quality. These capabilities represent important competitive barriers, particularly in regulated industries where reliability and certification remain primary purchasing considerations.
Recent Developments
July 2026 – Knowles (Cornell Dubilier) launched Type PPH film capacitors. The new double-metallized polypropylene film capacitor series targets high-voltage automotive and industrial power applications, delivering enhanced pulse handling, high ripple-current capability, and improved reliability under demanding electrical stresses.
May 2026 – Exxelia introduced the CF-PP140 polypropylene film capacitor range. Designed for high-temperature, high-energy applications, the series supports 450–1500 V, energy density up to 250 J/L, and continuous operation at temperatures reaching 140°C.
April 2026 – KYOCERA AVX launched FFLK traction-grade DC filtering film capacitors. The series delivers high volumetric efficiency, durability, and long service life for electric vehicle traction systems and industrial motor drives requiring robust DC filtering performance.
February 2026 – TDK introduced the B3271xP DC-link film capacitor series. Featuring polypropylene dielectric technology, the capacitors support operating temperatures up to 125°C and target automotive inverters, onboard chargers, DC-DC converters, industrial power supplies, and solar inverters.
Regulatory and Policy Environment
Film capacitor manufacturers operate within a regulatory framework that combines electrical safety standards, environmental legislation, product quality requirements, and application-specific certification. International standards published by the International Electrotechnical Commission (IEC) establish widely recognized performance and testing requirements for fixed capacitors used in electronic equipment, enabling consistent qualification across multiple industries and geographic markets. Compliance with these standards remains a prerequisite for participation in many industrial and infrastructure projects.
Environmental legislation continues to influence material selection and manufacturing practices. The European Union's Restriction of Hazardous Substances (RoHS) Directive and Registration, Evaluation, Authorisation and Restriction of Chemicals (REACH) Regulation require manufacturers to control hazardous substances throughout product design and production. Similar environmental requirements have been adopted across several international markets, encouraging suppliers to redesign products, improve material traceability, and strengthen supplier auditing processes.
Automotive applications impose additional quality expectations through internationally recognized quality management systems such as IATF 16949, while aerospace, medical, and defense sectors require application-specific qualification procedures before commercial deployment. These certification requirements increase development costs and extend approval timelines but also reinforce barriers to entry by favoring manufacturers with established quality systems, engineering resources, and long-term compliance capabilities.
Government policies supporting renewable energy deployment, electric vehicle manufacturing, semiconductor production, and industrial modernization also contribute indirectly to demand for film capacitors. Investment incentives for renewable power generation, charging infrastructure, advanced manufacturing, and grid modernization increase procurement of power electronic systems where high-performance film capacitors remain essential components. Consequently, policy support affects market demand primarily through higher installation of electrical equipment rather than direct incentives for capacitor production.
Outlook and Strategic Implications
Demand during the 2026-2031 forecast period is expected to remain closely linked to the expansion of electrified transportation, renewable power infrastructure, industrial automation, and higher-performance electronic equipment. Procurement is likely to favor suppliers capable of delivering application-specific products that combine long operating life, stable electrical characteristics, compact dimensions, and reliable global supply. As electronic systems continue operating at higher voltages and switching frequencies, purchasing decisions will increasingly prioritize lifecycle performance instead of initial component cost.
Several structural factors are expected to shape competitive positioning over the medium term:
Automotive and renewable energy applications will continue raising technical requirements for high-voltage and high-temperature film capacitors.
Regional manufacturing expansion will reduce supply-chain concentration risks while improving delivery resilience for global customers.
Automation and digital quality control will become increasingly important for maintaining production consistency and reducing manufacturing defects.
Material innovation will focus on improving dielectric performance, thermal endurance, miniaturization, and operating lifetime across demanding applications.
Engineering support and application expertise will become stronger differentiators as customers seek customized capacitor solutions for increasingly complex power electronic systems.
Companies that combine manufacturing scale with materials expertise, certified quality systems, localized technical support, and diversified production networks are expected to strengthen their position in higher-value applications. Suppliers competing primarily through standardized products and price may face increasing margin pressure as customers continue emphasizing reliability, qualification history, and long-term supply assurance when selecting capacitor partners. The market is therefore expected to reward sustained investment in product development, manufacturing capability, and customer engineering rather than volume expansion alone.
Film Capacitor Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 4.45 billion |
| Total Market Size in 2031 | USD 6.15 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.68% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Voltage, Type, End-User Industry, Geography |
| Companies |
|
Market Segmentation
By Voltage
- Low Voltage
- High Voltage
By Type
- Polypropylene (PP) Film Capacitors
- Polyester (PET) Film Capacitors
- Polyphenylene Sulfide (PPS) Film Capacitors
- Paper Film Capacitors
- Others
By End-User Industry
- Automotive
- Consumer Electronics
- Industrial
- Energy and Power
- Telecommunications
- Medical
- Aerospace and Defense
- Others
By Geography
- North America
- USA
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Others
- Europe
- Germany
- France
- United Kingdom
- Spain
- Others
- Middle East and Africa
- Saudi Arabia
- UAE
- Israel
- Others
- Asia Pacific
- Japan
- China
- India
- South Korea
- Thailand
- Indonesia
- Taiwan
- Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits to the Stakeholder
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Processes
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. CXO Perspective
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter’s Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
4.5. Analyst View
5. FILM CAPACITOR MARKET, BY VOLTAGE
5.1. Introduction
5.2. Low Voltage
5.3. High Voltage
6. FILM CAPACITOR MARKET, BY TYPE
6.1. Introduction
6.2. Polypropylene (PP) Film Capacitors
6.3. Polyester (PET) Film Capacitors
6.4. Polyphenylene Sulfide (PPS) Film Capacitors
6.5. Paper Film Capacitors
6.6. Others
7. FILM CAPACITOR MARKET, BY END-USER INDUSTRY
7.1. Introduction
7.2. Automotive
7.3. Consumer Electronics
7.4. Industrial
7.5. Energy and Power
7.6. Telecommunications
7.7. Medical
7.8. Aerospace and Defense
7.9. Others
8. FILM CAPACITOR MARKET, BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. By Voltage
8.2.2. By Type
8.2.3. By End-User Industry
8.2.4. By Country
8.2.4.1. USA
8.2.4.1.1. Market Trends and Opportunities
8.2.4.1.2. Growth Prospects
8.2.4.2. Canada
8.2.4.2.1. Market Trends and Opportunities
8.2.4.2.2. Growth Prospects
8.2.4.3. Mexico
8.2.4.3.1. Market Trends and Opportunities
8.2.4.3.2. Growth Prospects
8.3. South America
8.3.1. By Voltage
8.3.2. By Type
8.3.3. By End-User Industry
8.3.4. By Country
8.3.4.1. Brazil
8.3.4.1.1. Market Trends and Opportunities
8.3.4.1.2. Growth Prospects
8.3.4.2. Argentina
8.3.4.2.1. Market Trends and Opportunities
8.3.4.2.2. Growth Prospects
8.3.4.3. Others
8.3.4.3.1. Market Trends and Opportunities
8.3.4.3.2. Growth Prospects
8.4. Europe
8.4.1. By Voltage
8.4.2. By Type
8.4.3. By End-User Industry
8.4.4. By Country
8.4.4.1. Germany
8.4.4.1.1. Market Trends and Opportunities
8.4.4.1.2. Growth Prospects
8.4.4.2. France
8.4.4.2.1. Market Trends and Opportunities
8.4.4.2.2. Growth Prospects
8.4.4.3. United Kingdom
8.4.4.3.1. Market Trends and Opportunities
8.4.4.3.2. Growth Prospects
8.4.4.4. Spain
8.4.4.4.1. Market Trends and Opportunities
8.4.4.4.2. Growth Prospects
8.4.4.5. Others
8.4.4.5.1. Market Trends and Opportunities
8.4.4.5.2. Growth Prospects
8.5. Middle East and Africa
8.5.1. By Voltage
8.5.2. By Type
8.5.3. By End-User Industry
8.5.4. By Country
8.5.4.1. Saudi Arabia
8.5.4.1.1. Market Trends and Opportunities
8.5.4.1.2. Growth Prospects
8.5.4.2. UAE
8.5.4.2.1. Market Trends and Opportunities
8.5.4.2.2. Growth Prospects
8.5.4.3. Israel
8.5.4.3.1. Market Trends and Opportunities
8.5.4.3.2. Growth Prospects
8.5.4.4. Others
8.5.4.4.1. Market Trends and Opportunities
8.5.4.4.2. Growth Prospects
8.6. Asia Pacific
8.6.1. By Voltage
8.6.2. By Type
8.6.3. By End-User Industry
8.6.4. By Country
8.6.4.1. Japan
8.6.4.1.1. Market Trends and Opportunities
8.6.4.1.2. Growth Prospects
8.6.4.2. China
8.6.4.2.1. Market Trends and Opportunities
8.6.4.2.2. Growth Prospects
8.6.4.3. India
8.6.4.3.1. Market Trends and Opportunities
8.6.4.3.2. Growth Prospects
8.6.4.4. South Korea
8.6.4.4.1. Market Trends and Opportunities
8.6.4.4.2. Growth Prospects
8.6.4.5. Thailand
8.6.4.5.1. Market Trends and Opportunities
8.6.4.5.2. Growth Prospects
8.6.4.6. Indonesia
8.6.4.6.1. Market Trends and Opportunities
8.6.4.6.2. Growth Prospects
8.6.4.7. Taiwan
8.6.4.7.1. Market Trends and Opportunities
8.6.4.7.2. Growth Prospects
8.6.4.8. Others
8.6.4.8.1. Market Trends and Opportunities
8.6.4.8.2. Growth Prospects
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Wima GmbH & Co. KG
10.2. Kemet (Yageo)
10.3. Cornell Dubilier
10.4. Panasonic Corporation
10.5. TDK Corporation
10.6. Vishay Intertechnology
10.7. Kyocera AVX Components Corporation
10.8. Nichicon Corporation
LIST OF FIGURES
LIST OF TABLES
Navigate
Trusted by the world's leading organizations











