
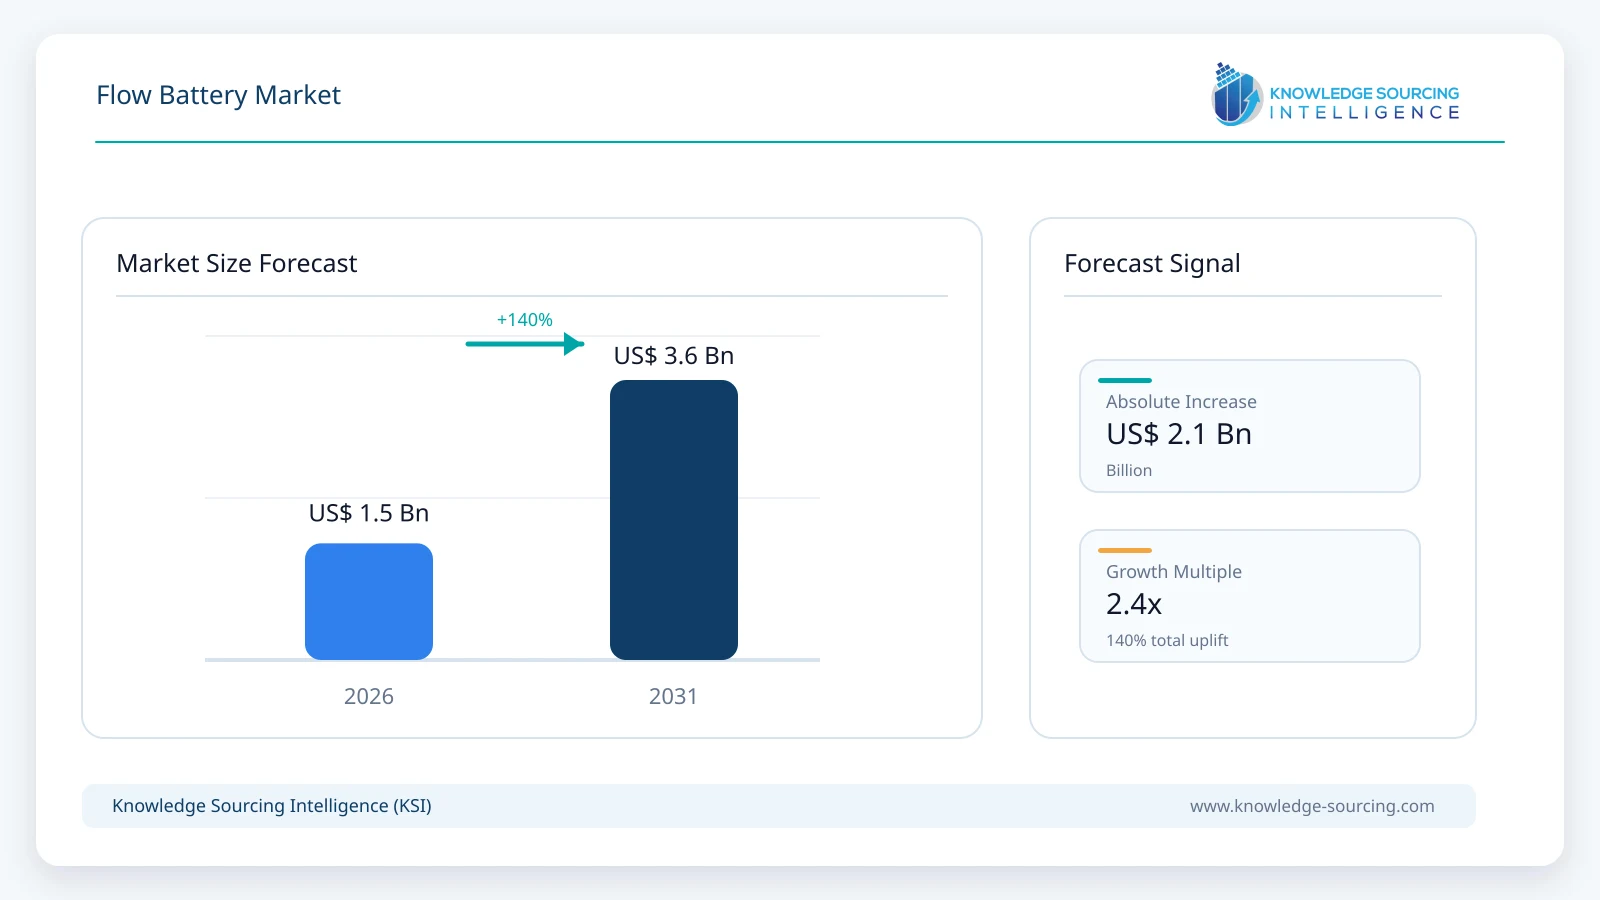
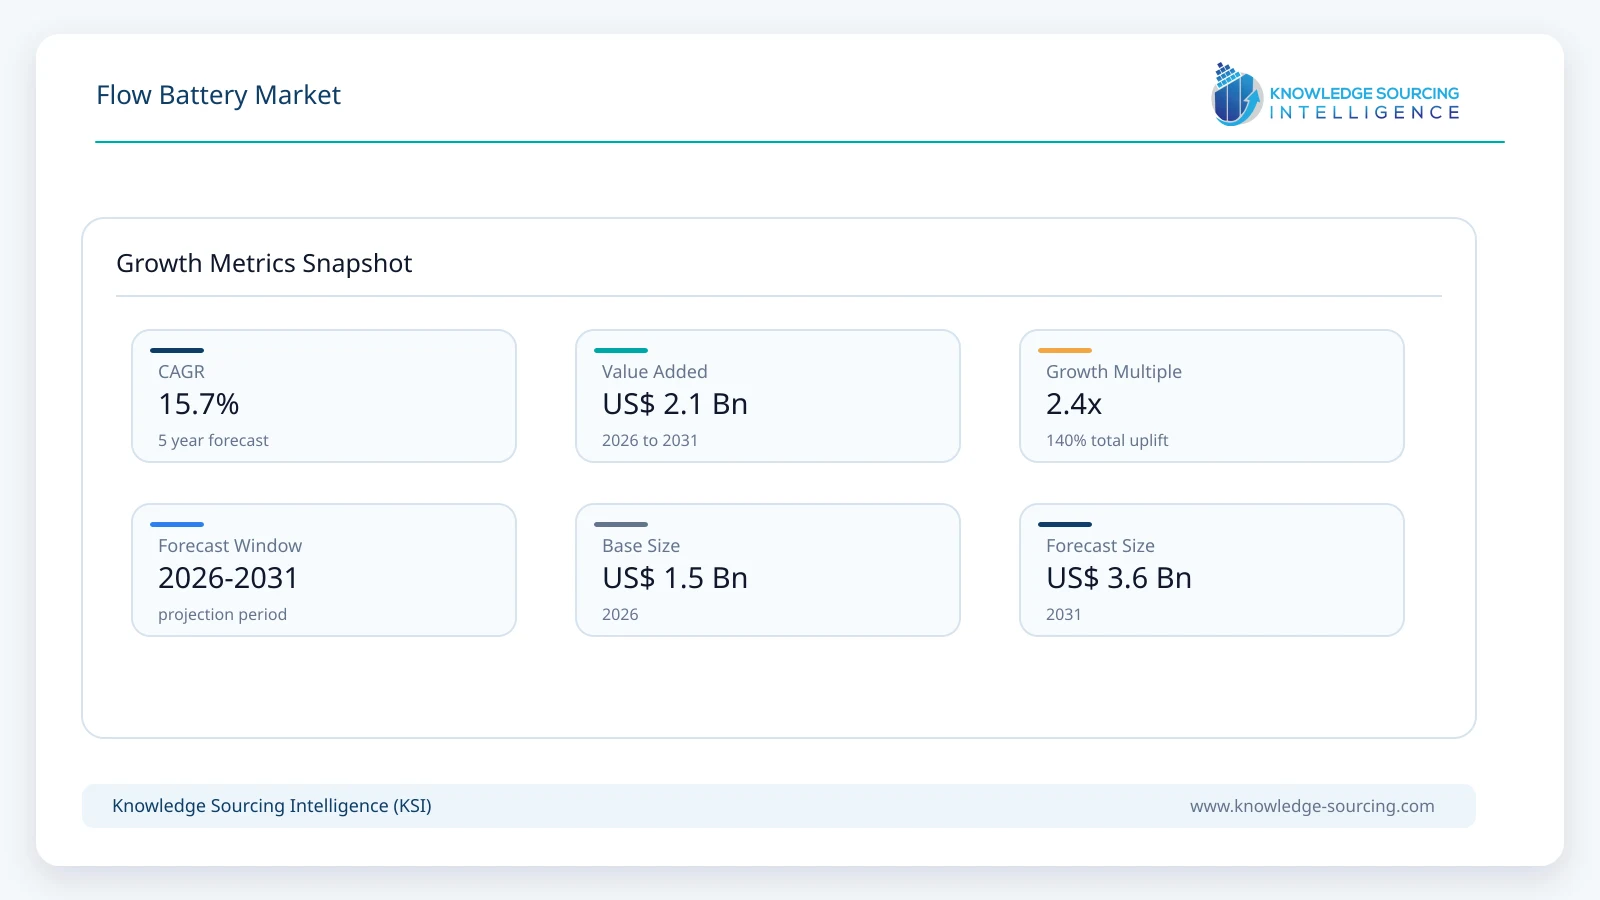
The flow battery market is estimated at USD 1.50 billion in 2026 and is projected to reach approximately USD 3.60 billion by 2032, equivalent to a 15.7% CAGR during the forecast period.
Highlights:
- 1Type leaderRedox flow batteries account for US$1.230 billion and 82.0% of 2026 revenue, reaching US$2.808 billion by 2032 at a 14.75% CAGR.
- 2Other typesHybrid systems represent US$0.180 billion and 12.0% in 2026 (17.26% CAGR); organic systems US$0.060 billion and 4.0% (23.80%); membraneless systems US$0.030 billion and 2.0% (23.80%).
- 3Application leaderUtilities generate US$1.005 billion and 67.0% of the 2026 market, rising to US$2.340 billion in 2032 at a 15.13% CAGR.
- 4Other applicationsCommercial and industrial contributes US$0.345 billion and 23.0% in 2026 (17.33% CAGR); defense US$0.090 billion and 6.0% (15.71%); other applications US$0.060 billion and 4.0% (15.71%).
- 5Regional leaderAsia Pacific accounts for US$0.750 billion and 50.0% in 2026, projected at US$1.728 billion in 2032 with a 14.92% CAGR.
- 6Other regionsEurope has US$0.330 billion and 22.0% in 2026 (16.57% CAGR); North America US$0.300 billion and 20.0% (16.65%). South America and the Middle East & Africa each hold US$0.060 billion and 4.0% (15.71%).
- 7Financing and executionWarranty coverage, electrolyte contracting, verified cycling performance and dependable EPC partners determine whether announced projects become bankable orders.
Demand is concentrated in stationary energy storage, where developers require repeated deep cycling, renewable power shifting and dependable discharge beyond short peak intervals. Flow batteries circulate liquid electrolytes through electrochemical stacks. In many designs, power output is determined by the stack, while energy duration can be increased through electrolyte capacity. This design separates two important purchasing decisions that are tightly linked in most conventional battery systems. The economic advantage is conditional, however. Buyers still need to account for tanks, pumps, electrical conversion, engineering work, maintenance, efficiency and project finance. Vanadium redox batteries have the strongest established commercial track record within the category, while iron-based, organic and hybrid systems seek different combinations of raw-material cost, durability and supply-chain independence. Flow batteries remain a specialized part of the stationary storage industry rather than a direct substitute for every lithium-ion project.
The commercial context is defined by the scale of lithium iron phosphate (LFP) deployment. The International Energy Agency reports 108 GW of new global battery storage additions in 2025, approximately 40% above 2024, with LFP representing about 90% of deployments. Most new battery projects still cluster near two hours of discharge, although durations are lengthening. This gives LFP suppliers substantial advantages in installed cost, integration experience and lender familiarity. Flow battery vendors therefore need applications where frequent cycling, calendar life, refurbishment options or different siting conditions justify a higher upfront investment. A credible project comparison uses lifetime delivered electricity and contracted operating obligations, not nominal battery chemistry or equipment pricing alone. Project announcements provide evidence of developer intent but do not establish commissioned capacity or market revenue. The distinction is particularly important as procurement programmes and design-stage opportunities expand ahead of completed flow battery installations.
Market Dynamics
Storage duration is the central commercial variable shaping adoption. A utility procuring a two-hour system mainly for fast power dispatch may prioritize low installed cost and familiar operating arrangements, areas in which lithium-ion is well established. A project designed to shift midday solar output into evening demand or cycle extensively over many years may place greater weight on equipment life, degradation, replacement intervals and operating flexibility. Flow battery economics consequently depend on levelized cost of storage, which combines capital spending with the usable electricity delivered over a project's life. Electrolyte prices, stack costs, auxiliary pumping electricity, round-trip efficiency, maintenance and financing all affect that calculation. The distinction between power and energy capacity offers design flexibility, but larger tanks and fluid-handling infrastructure also occupy land and require engineering attention. Developers must assess the complete installed system rather than compare the price of battery modules in isolation. This is particularly important when a project's advertised discharge duration differs from its commercially expected dispatch schedule, because the achievable revenue may depend on only a portion of the theoretical storage capability.
Project financing introduces another source of differentiation between technologies. Vanadium electrolyte can retain material value beyond the original operating period, creating the possibility of leasing, resale or reuse arrangements that reduce the initial capital burden for a buyer. These structures may improve cash flow, but their economic benefit depends on commodity prices, ownership rights, return conditions and the counterparty's ability to perform over a long contract. At the same time, developers must consider the expense of membranes, electrodes, balance-of-plant equipment and stack refurbishment. Higher initial expenditure can be justified only when lifetime savings or additional revenues compensate for it. Suppliers that quote attractive equipment prices but leave replacement obligations ambiguous are harder to finance than those offering transparent warranties, performance guarantees and credible service networks. The US Department of Energy's flow battery technology assessment identifies challenges related to system performance, standardization and the commercial valuation of long-duration storage. These constraints help explain why expanding technical feasibility does not automatically translate into immediate orders. Bankability is increasingly a product feature, not merely a concern for the financier after the engineering design is complete.
Government support can improve the revenue visibility needed to finance long-duration projects, but policy announcements require careful interpretation. On June 26, 2026, Britain's energy regulator Ofgem identified 16 projects as provisionally selected under its long-duration electricity storage cap-and-floor framework. The portfolio included pumped-storage hydropower, compressed-air storage, lithium-ion batteries and one proposed vanadium redox flow battery project in North Wales. A revenue floor can reduce downside exposure where market prices and storage utilization are uncertain, while an upper limit can protect customers from excess returns. Nevertheless, the announcement represented an intermediate selection stage, not 16 commissioned assets or firm equipment orders. Each project still faces development, approval, financing, engineering and procurement milestones before operation. For flow battery manufacturers, such frameworks can create a route into larger tenders, but they also intensify the need for proven performance data and delivery assurances. A supplier that can support revenue modelling, establish realistic commissioning schedules and accept clearly defined long-term service obligations is better positioned to convert policy eligibility into actual system sales.
Vanadium redox flow batteries represent one of the most commercially established flow battery architectures, with the same element used in different oxidation states on either side of the system. This chemistry reduces certain cross-contamination concerns found in systems using different active species, although membranes, pumps and fluid-management equipment still require careful maintenance. The technology's strengths include independent power and energy sizing, a water-based electrolyte and the potential to reuse electrolyte after equipment retirement. These advantages matter most where the buyer expects frequent cycling and is willing to finance a comparatively large stationary installation. Procurement exposure remains significant because vanadium pricing, electrolyte inventories and component specifications influence capital costs. Manufacturers seeking to narrow this disadvantage increasingly emphasize standardized stack configurations, more efficient balance-of-plant designs and predictable service agreements. The commercial challenge is to translate technical endurance into a cost profile that investors can compare directly with competing storage assets. Even when the electrolyte retains value, the project must still earn adequate returns after accounting for energy losses, site works, insurance, maintenance and any cost of capital attached to electrolyte ownership. Product reliability is therefore only one component of an investable proposition.
A concrete example of the technology's commercial position comes from Japan. In April 2026, Sumitomo Electric announced that Hokkaido Electric Power Network had selected an 11 MW, 33 MWh vanadium redox flow battery installation at its Minami-Hayakita substation, with completion scheduled for May 2029. The system's stated discharge duration is three hours, demonstrating that commercial flow battery opportunities are not restricted to eight-hour or longer projects. The procurement supports wind power grid interconnection and includes an intended 20-year operations and maintenance arrangement after completion. That service term is commercially important because long operating life creates obligations for spare parts, monitoring, maintenance personnel and eventual decommissioning. Suppliers willing to take on these obligations may differentiate themselves from vendors competing only on initial equipment price, but they must also account for the liability within their margin structure. For utilities, a long-term contract can clarify ownership of performance risks and improve operating-cost visibility. The project also illustrates the distinction between an announced award and installed capacity: its contribution to operational storage supply will depend on successful delivery and commissioning within the stated schedule.
Iron-based, zinc-based, organic and hybrid flow battery systems are pursuing different routes to lower material cost and greater application flexibility. Iron-based chemistries can reduce exposure to vanadium commodity pricing, yet the lower nominal cost of an active material does not guarantee cheaper electricity storage. Membrane performance, electrolyte stability, stack efficiency, pumping requirements and manufacturing yields can offset a material advantage. Zinc-based and hybrid approaches raise different engineering questions around electrode behaviour, chemical stability and maintenance, while organic formulations must establish long-term durability under real operating conditions. The competitive benchmark is an integrated storage plant that delivers contracted energy reliably, not a laboratory cell with an attractive raw-material specification. Emerging suppliers therefore face a difficult transition from technical demonstration to repeatable procurement: customers want independently observed operating hours, warranty commitments, standard equipment interfaces and verifiable lifecycle expenses. Smaller manufacturers may find early opportunities in controlled industrial or microgrid applications where a customer can closely monitor performance before wider deployment. Large utility contracts, by contrast, generally demand stronger balance sheets and evidence that a supplier can manufacture, install and service multiple plants without relying on one-off project engineering.
Market Segmentation
Redox Flow Batteries
Redox flow batteries represent an estimated US$1.230 billion, or 82.0% of global flow battery revenue in 2026, and are projected to reach US$2.808 billion by 2032. The corresponding 14.75% CAGR is below the broader market rate because emerging technologies gain share from considerably smaller starting positions. Vanadium-based systems provide an established procurement reference due to their operational history and the ability to increase energy duration through electrolyte volume. However, the presence of recoverable or reusable electrolyte does not remove capital requirements. Owners still face membrane replacement, stack refurbishment, auxiliary loads, site civil works and the financial cost of holding electrolyte inventory. The most credible suppliers are those that can translate operating life into documented warranty coverage and a bankable levelized cost of storage. Customers procuring multi-hour grid assets will evaluate efficiency, downtime, availability and the financial strength of long-term service counterparties alongside headline discharge duration.
Other Types and Applications
Hybrid flow systems are assigned a provisional 12.0% share of the 2026 market, while organic and membraneless flow systems represent smaller, less commercially mature categories. Their projected growth rates exceed that of redox flow technology because the modeled bases are limited, not because equivalent utility-scale qualification has been demonstrated. Material availability and low electrolyte cost can improve economics, yet electrode behavior, membrane life, chemical stability and manufacturing yields remain decisive. Across applications, utilities dominate at 67.0% of 2026 revenue as storage purchases are linked to renewable interconnection, network balancing and electricity shifting. Commercial and industrial users represent 23.0%, with opportunities involving onsite renewable generation, flexible electricity purchasing and industrial resilience. Defense and other applications are smaller and require distinct qualification, service and operating economics. These application categories represent alternative customer groups, not additional revenue on top of the global market.
Regional Outlook
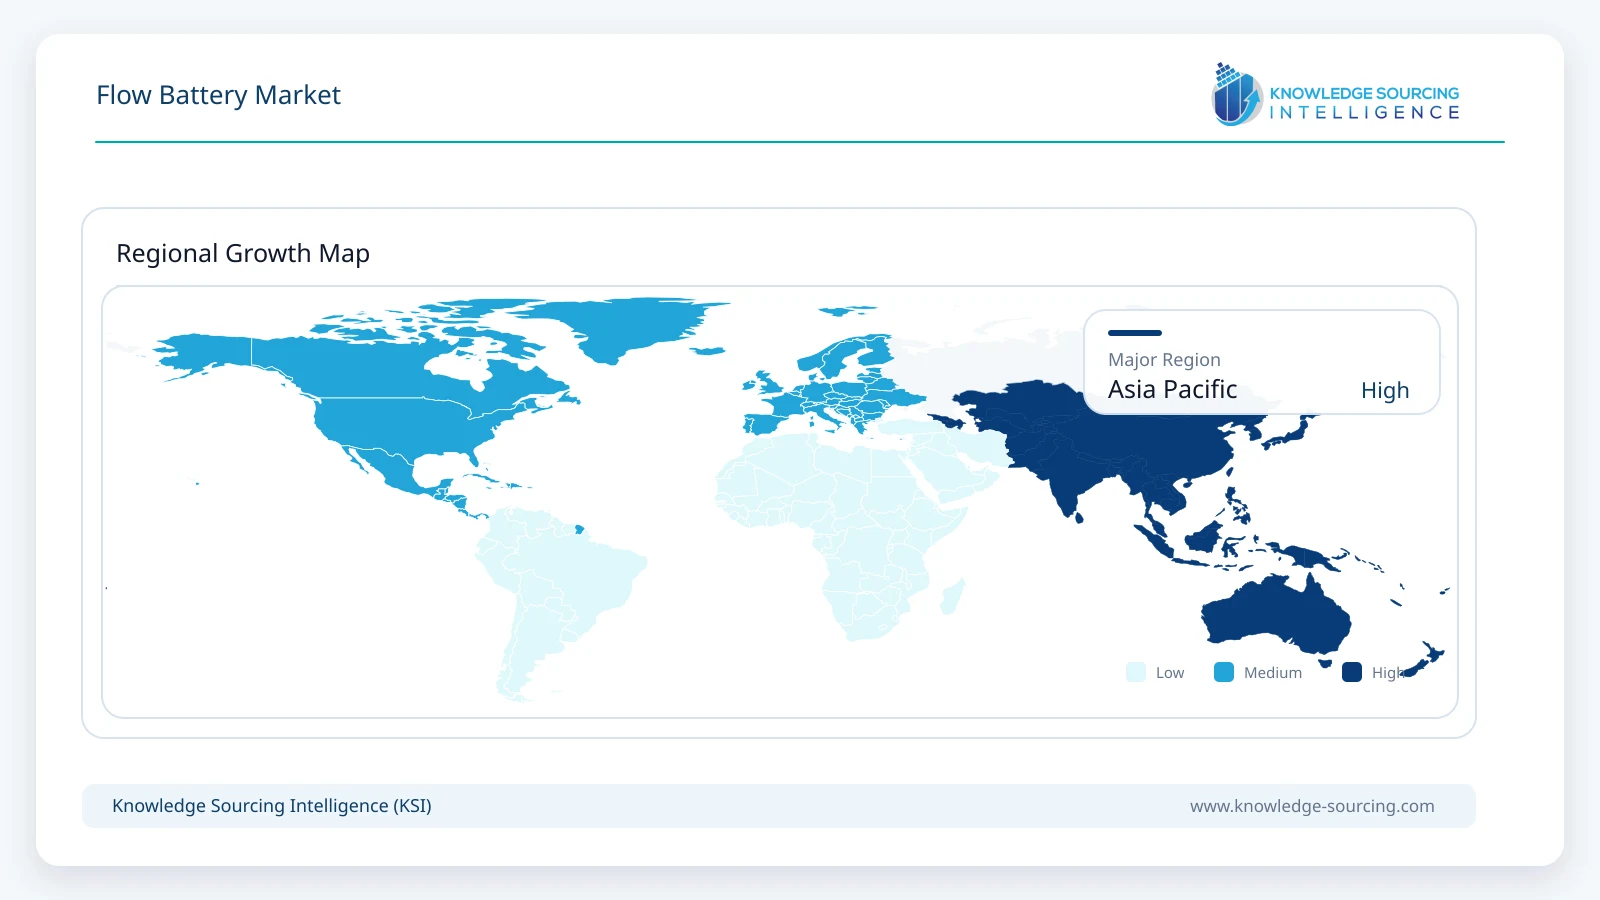
Asia Pacific combines major battery manufacturing ecosystems with substantial renewable integration requirements, making it a central region for flow battery commercialization. China provides an important manufacturing and project-development base, while Japan offers examples of utility procurement that links storage deployment to specific network requirements. However, these markets should not be treated as identical. Chinese projects may draw on larger domestic manufacturing supply chains and different procurement conditions, whereas Japanese utilities typically emphasize operating history, engineering qualification and long-term system responsibility. The selection of Sumitomo Electric's Hokkaido installation illustrates how network interconnection can create demand independently of a generic target for storage duration. Across the region, flow batteries face intense price competition from LFP systems and must demonstrate advantages tied to use case rather than chemistry alone. The main commercial opportunities therefore lie in applications where site-level energy shifting, cycling expectations or service-life requirements make alternative system economics credible. Suppliers seeking regional expansion also need to consider local content rules, electrolyte sourcing, installation capability and established utility relationships. Without these foundations, the ability to manufacture a technically sound stack does not necessarily translate into scalable market access.
Europe offers a contrasting route to growth through market-design reforms, long-duration procurement and projects linked directly to renewable generation. In May 2026, Invinity Energy Systems reported delivery of 20.7 MWh of vanadium flow batteries for the Copwood Energy Hub in East Sussex, pairing the installation with a 3 MW solar array. Delivery is an important commercial milestone, but it should not be confused with commissioning or proven operating performance. In the same month, Invinity announced its selection to design a proposed vanadium flow battery system of up to 1.5 GWh at the Technology Centre Laufenburg in Switzerland. That announcement concerns a design-stage opportunity rather than a completed battery order at the full stated capacity. Together, these projects show two distinct paths into the market: smaller installations demonstrating an integrated renewable-storage operating model and larger developments that may require extended engineering and financing before procurement. European suppliers must manage this difference carefully when describing their order pipeline. Project developers are increasingly interested in technology diversity, but the bankable market will be determined by final investment decisions, grid connections and the economics of delivering electricity when it is most valuable. (Invinity, May 2026) (Invinity, May 2026)
North America presents a combination of electricity-system needs, industrial technology development and difficult commercialization choices. Renewable additions and grid reliability requirements create potential opportunities for storage that can cycle regularly or support extended periods of demand, but lithium-ion systems remain highly competitive in many utility tenders. Flow battery suppliers must therefore connect their technical offerings to a measurable operational requirement, such as long daily discharge, limited appetite for routine capacity augmentation or a site-specific safety constraint. The economics can also vary substantially between regions because grid-service payments, electricity price spreads, permitting and land costs are not uniform. Manufacturers seeking to expand in the United States or Canada must demonstrate that their products can be installed and maintained through established local partners. Domestic manufacturing and supply-chain positioning can support customer interest, but neither is a substitute for performance guarantees or a credible installed-cost proposal. The most commercially useful approach is selective bidding and well-documented demonstration projects that lead to repeatable standards. As reference assets accumulate, their measured reliability, efficiency and maintenance expenses should become more important in financing decisions than broad claims about the promise of long-duration technology.
Competitive Environment
The competitive landscape includes established industrial suppliers, specialist vanadium battery manufacturers and developers of emerging electrochemical systems. Sumitomo Electric benefits from utility relationships and field experience, while Invinity Energy Systems emphasizes modular vanadium battery products and project partnerships. Other manufacturers are pursuing iron-based, zinc-based and alternative chemistries in an effort to improve material availability or tailor system behaviour to particular applications. These businesses do not compete on chemistry alone. Procurement teams compare delivered price, round-trip efficiency, footprint, expected maintenance, warranty support, construction risk and the supplier's ability to remain accountable over a long operating period. In project finance, the perceived strength of the manufacturer can materially affect the cost and availability of capital, especially where a developer relies on performance warranties extending over many years. A technically promising but thinly capitalized supplier can be disadvantaged against an incumbent with less aggressive equipment claims and stronger service capacity. This encourages partnerships between technology companies, engineering contractors and established energy-sector participants. Over time, suppliers that standardize designs and generate credible fleet operating data should gain an advantage in larger, repeat procurement programmes.
Competition also depends on which technology claims can be supported by independently observed operating records. Suppliers that make standardized designs, documented warranties and project-service interfaces available can lower a developer’s transaction burden, even if they do not quote the lowest initial equipment price. Vanadium-based vendors face procurement exposure to electrolyte pricing and component replacement. Iron-based developers seek alternative material economics but must still demonstrate reliable integrated plant performance. Emerging systems encounter higher qualification costs and a smaller base of lenders and EPC partners familiar with their products. Manufacturers therefore benefit from repeatable container, control-system and commissioning designs that can be reproduced across sites. Project partnerships are commercially useful where they allocate interconnection, maintenance and performance risks clearly. Market share claims should not be inferred from individual announced project capacities, because engineering awards, equipment delivery and commercial commissioning are different milestones.
Market Outlook
Looking toward 2032, the flow battery market is likely to expand where developers can establish a clear connection between storage duration and commercial revenue. The competitive benchmark is not whether a flow battery can store electricity for many hours; it is whether a specific system delivers contracted capacity more economically over its operating life than the alternatives. Electrolyte financing, procurement scale, stack durability, warranties and system efficiency will shape achievable margins. Long-duration support mechanisms may create tender opportunities, but provisional selection does not eliminate permitting, grid-connection or final investment risks. Utilities and industrial buyers will also increasingly expect evidence from operating fleets rather than laboratory cycle counts. Suppliers that reduce custom engineering, document replacement costs and establish dependable service networks should be better positioned for repeat orders. The base case reaches approximately US$3.60 billion in 2032, while the distribution among chemistries and regions remains dependent on project conversion and competitive battery prices.
Recent Developments
June 26, 2026: Ofgem provisionally selected 16 long-duration electricity storage projects under Great Britain’s cap-and-floor framework, including a proposed vanadium redox project in north Wales; the decision did not represent commissioned capacity.
May 12, 2026: Invinity Energy Systems reported delivery of 20.7 MWh of vanadium batteries to the Copwood Energy Hub in East Sussex, paired with a 3 MW solar installation. Delivery was ahead of commissioning.
April 28, 2026: Sumitomo Electric announced selection of an 11 MW / 33 MWh vanadium system for Hokkaido Electric Power Network, with completion planned for May 2029 and a proposed 20-year service arrangement.
Flow Battery Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.50 billion |
| Total Market Size in 2032 | USD 3.60 billion |
| Forecast Unit | Billion |
| Growth Rate | 15.7% |
| Study Period | 2021 to 2032 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2032 |
| Segmentation | Type, Application, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Organic Flow Battery
Redox Flow Battery
Hybrid Flow Battery
Membraneless Flow Battery
By Application
Utilities
Commercial & Industrial
Defense
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Italy
Others
Middle East & Africa
Saudi Arabia
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Taiwan
Thailand
Indonesia
Others
Table of Contents
1. EXECUTIVE SUMMARY
1.1 Market Overview
1.2 Key Findings
1.3 Global Market Size and Forecast, 2026–2032
2. RESEARCH SCOPE AND METHODOLOGY
2.1 Product and Revenue Definition
2.2 Historical Period and Forecast Period
2.3 Project Revenue, Installed Capacity and Supply Distinctions
2.4 Forecast Triangulation and Sensitivity Analysis
3. GLOBAL FLOW BATTERY MARKET OVERVIEW
3.1 Stationary Storage Demand and Commercial Economics
3.2 Technology Maturity and Procurement Requirements
3.3 Project Pipeline, Commissioning and Installed Base
4. MARKET DYNAMICS
4.1 Market Drivers
4.2 Market Restraints
4.3 Electrolyte Supply, System Costs and Financing
4.4 Long-Duration Procurement and Policy Support
4.5 Industry Value Chain and Porter’s Five Forces
5. GLOBAL FLOW BATTERY MARKET BY TYPE
5.1 Organic Flow Battery
5.2 Redox Flow Battery
5.3 Hybrid Flow Battery
5.4 Membraneless Flow Battery
6. GLOBAL FLOW BATTERY MARKET BY APPLICATION
6.1 Utilities
6.2 Commercial & Industrial
6.3 Defense
6.4 Others
7. GLOBAL FLOW BATTERY MARKET BY GEOGRAPHY
7.1 North America
7.1.1 United States
7.1.2 Canada
7.1.3 Mexico
7.2 South America
7.2.1 Brazil
7.2.2 Argentina
7.2.3 Others
7.3 Europe
7.3.1 United Kingdom
7.3.2 Germany
7.3.3 France
7.3.4 Italy
7.3.5 Others
7.4 Middle East & Africa
7.4.1 Saudi Arabia
7.4.2 South Africa
7.4.3 Others
7.5 Asia Pacific
7.5.1 China
7.5.2 Japan
7.5.3 India
7.5.4 South Korea
7.5.5 Taiwan
7.5.6 Thailand
7.5.7 Indonesia
7.5.8 Others
8. COMPETITIVE ENVIRONMENT
8.1 Competitive Overview
8.2 Company Profiles
8.2.1 Sumitomo Electric Industries
8.2.2 Invinity Energy Systems
8.2.3 Rongke Power
8.2.4 CellCube
8.2.5 ESS Tech, Inc.
8.2.6 VRB Energy
8.2.7 Stryten Energy
8.2.8 Storion Energy
8.2.9 CMBlu Energy
9. RECENT DEVELOPMENTS
10. APPENDIX AND RESEARCH SOURCES





Frequently asked questions
What is the projected size of the Flow Battery Market by 2032?
The Flow Battery Market is projected to reach $3.60 billion by 2032 at 15.7% CAGR.
Which flow battery type leads the market?
Redox flow batteries lead, accounting for 82.0% of 2026 revenue.
What is the leading application segment for flow batteries?
Utilities represent 67.0% of the market, growing to $2.340 billion by 2032.
Which region is dominant in the Flow Battery Market?
Asia Pacific leads, holding 50.0% of the 2026 market share.
What is the primary driver for flow battery demand?
Demand centers on stationary energy storage, requiring deep cycling and reliable discharge.
What type of flow battery has the strongest commercial track record?
Vanadium redox batteries have the strongest established commercial track record.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Flow Battery Market - Strategic Insights and Forecasts (2026-2032). https://www.knowledge-sourcing.com/report/flow-battery-market