
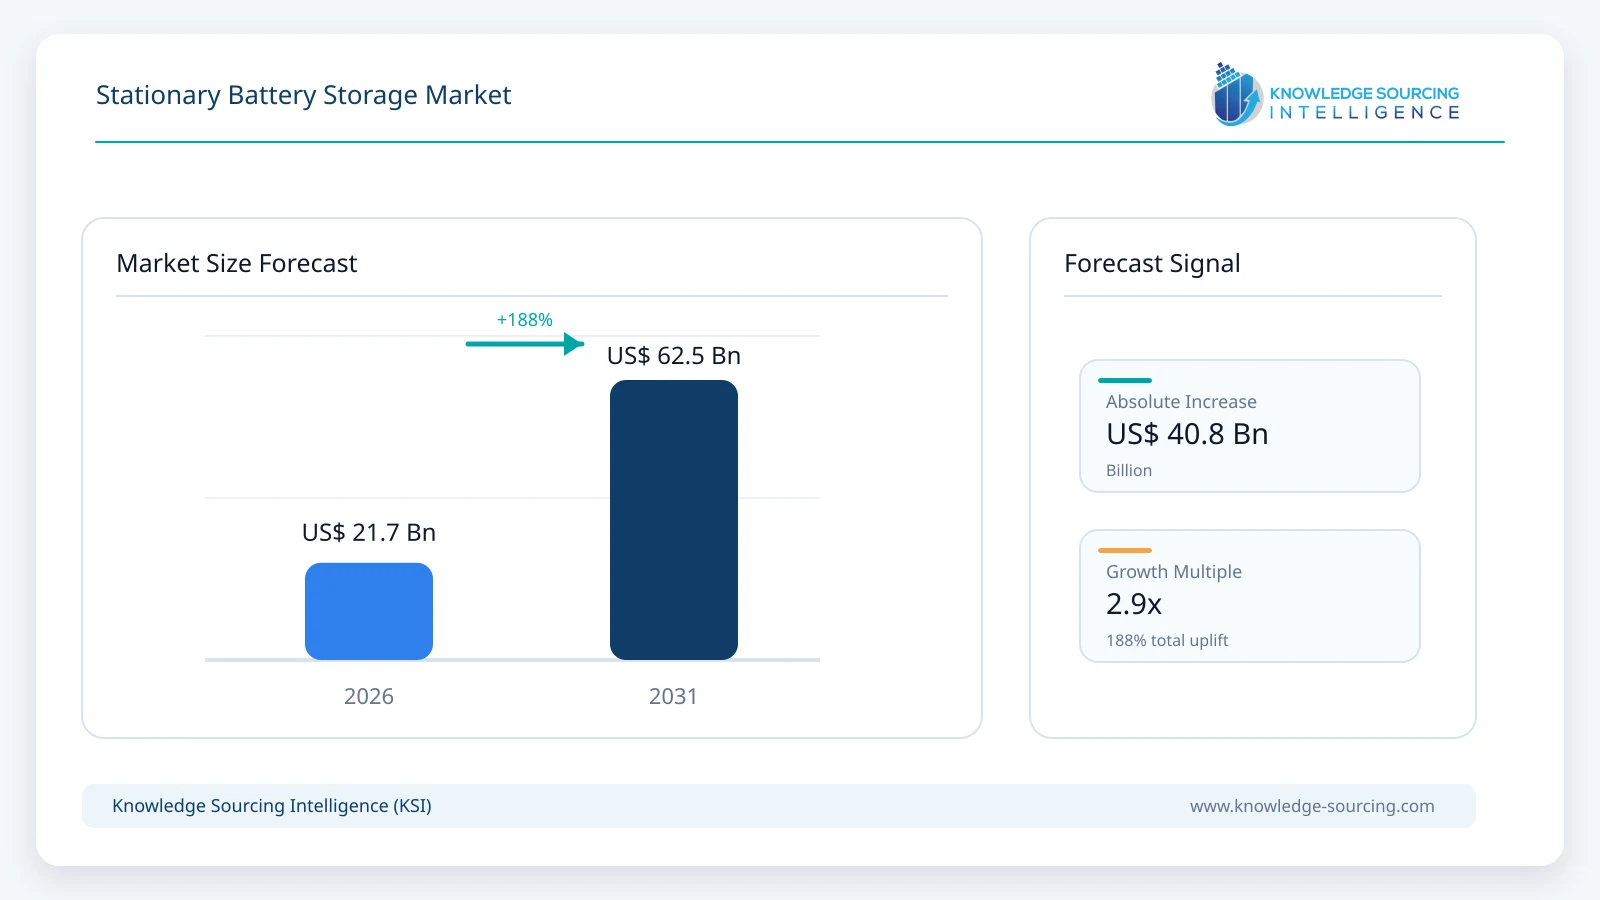
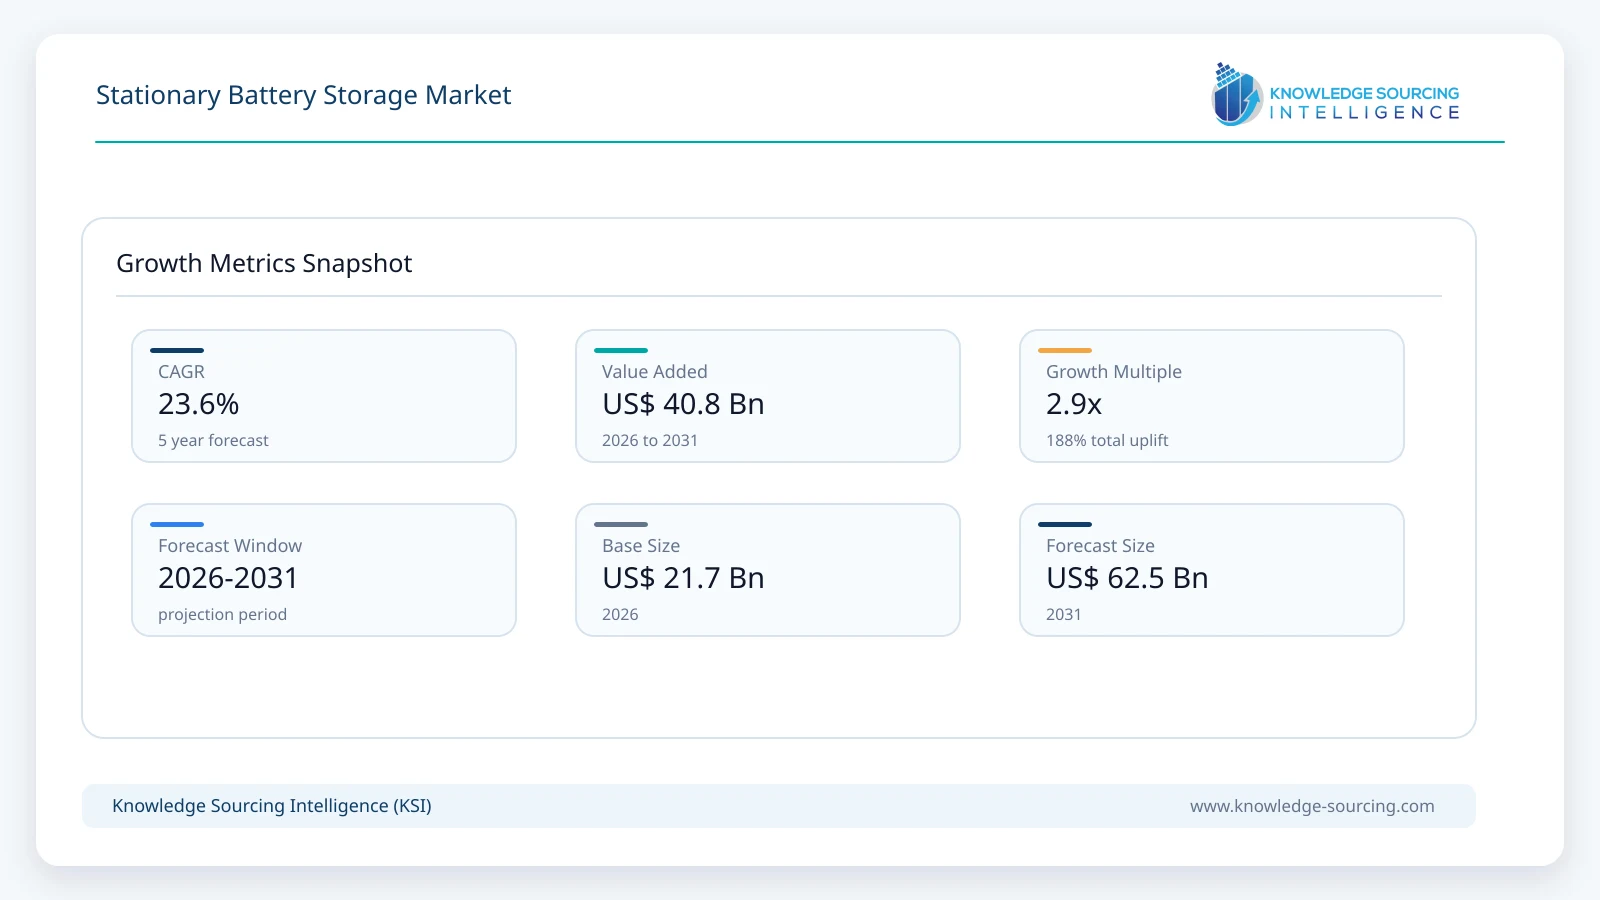
Stationary Battery Storage Market is set to reach USD 62.5 billion in 2031, growing at a CAGR of 23.6% from USD 21.7 billion in 2026.
Highlights:
- 1The market is projected to increase from USD 21.7 billion in 2026 to USD 62.5 billion by 2031.
- 2LFP batteries represented approximately 90% of global battery storage deployments in 2025, making chemistry economics central to supplier competition.
- 3Utility-scale systems represented about 80% of global battery storage additions in 2025, reinforcing grid applications as the largest demand base.
- 4China accounted for around 60% of global battery storage additions in 2025, concentrating manufacturing and project activity in Asia Pacific.
- 5The United States added 19 GW of battery capacity in 2025, while China added more than 63 GW during the year.
- 6Battery storage deployment is widening beyond established markets as Australia, the Middle East, and Chile add large grid-scale projects.
Stationary battery storage is becoming an important power-system asset as grids add more variable renewable generation, electricity demand rises, and utilities require faster sources of flexibility. The market covers batteries and associated systems used for grid services, behind-the-meter supply, microgrids, and off-grid power. Commercial deployment is increasingly supported by the need for reliable energy storage, peak-load management, renewable integration, and grid resilience. Demand is increasingly shaped by system duration, safety, lifecycle cost, grid connection, and project bankability, while improvements in battery technology, manufacturing capacity, and energy-storage project development are supporting broader adoption across utility, commercial, and distributed applications.
Market Overview
The stationary battery storage market is moving from small-scale backup applications toward large grid-connected systems that can shift electricity, provide ancillary services, defer network upgrades, and support renewable power. The International Energy Agency reported that global battery storage additions reached 108 GW in 2025, 40% above 2024, with utility-scale projects accounting for about 80% of new capacity.
Lithium iron phosphate (LFP) has gained a strong position in stationary applications because storage projects value cycle life, safety, cost, and frequent cycling more than the energy density demanded by many electric-vehicle applications. The IEA estimates that LFP represented around 90% of battery storage deployments in 2025, compared with less than half five years earlier.
Project buyers are also placing greater weight on system-level economics. Cell cost remains important, but developers must assess power conversion, thermal management, land use, fire protection, warranties, augmentation, software, maintenance, grid compliance, and service support. CATL's TENER system, for example, combines high-density LFP cells with containerized architecture and a five-year zero-degradation claim, while Tesla integrates battery modules, inverters, thermal systems, and controls within Megapack.
The commercial structure therefore extends beyond battery-cell manufacturing. Cell suppliers, battery-system manufacturers, power-conversion suppliers, software providers, engineering firms, utilities, independent power producers, and system integrators all influence project economics. The value chain is also becoming more regional because tariffs, local-content rules, supply-chain security, grid codes, and national battery strategies affect where systems are manufactured and deployed.
Key Market Indicators
Indicator | Latest Evidence | Commercial Meaning |
|---|---|---|
Global battery storage additions | 108 GW in 2025 | Expanding annual installations increase demand for cells, containers, power systems, controls, and long-term services. |
LFP share of battery storage deployments | Around 90% in 2025 | LFP cost, cycle life, and safety characteristics are shaping current stationary-storage specifications. |
Utility-scale share of new battery capacity | Around 80% in 2025 | Grid projects remain the main commercial channel for battery storage suppliers. |
China share of global additions | Around 60% in 2025 | China has a strong position in both project deployment and battery manufacturing. |
U.S. operational utility-scale battery capacity | Nearly 52 GW by June 2026 | Rapid U.S. project additions are creating a large market for systems, software, services, and replacement capacity. |
China new-type storage capacity | 136 GW / 351 GWh at end-2025 | Large domestic deployment supports scale economies and creates a substantial project base for local suppliers. |
China's scale is particularly relevant to purchasing economics. The National Energy Administration reported that China's new-type energy storage capacity reached 136 GW and 351 GWh at the end of 2025, with average duration rising to 2.58 hours. The U.S. market is also expanding quickly, with EIA data showing nearly 52 GW of utility-scale battery capacity by June 2026.
Market Drivers
Renewable integration is increasing the value of flexible storage
Solar and wind output does not always match electricity demand. Battery systems can move electricity from periods of surplus generation to higher-value periods and can respond rapidly to changes in grid conditions. The IEA identifies battery storage as an important source of short-duration flexibility, including energy shifting, ancillary services, congestion relief, and backup supply.
The commercial effect differs by power system. Markets with high solar penetration can value evening discharge, while systems with transmission constraints may place more value on local capacity and congestion management. Developers therefore increasingly specify duration and power capability around revenue opportunities rather than treating battery capacity as a uniform product.
Grid investment is creating a second demand channel
Battery storage can provide flexibility without waiting for every transmission or distribution upgrade to be completed. The IEA reported that global grid investment was expected to reach USD 400 billion in 2024, while battery-storage investment was expected to exceed USD 50 billion that year.
The commercial opportunity is strongest where network congestion, renewable curtailment, peak demand, or connection delays create a measurable cost. Storage suppliers that can combine battery hardware with power conversion, controls, and long-term service can address these project needs more directly than cell-only manufacturers.
Higher power demand is broadening storage use cases
Electricity demand from data centers, industrial loads, electrification, and cooling is increasing the need for flexible power assets. Wärtsilä reported in 2026 that growing electricity demand, data-center power needs, and renewable generation were supporting demand across its Energy and Energy Storage businesses.
This demand also changes system specifications. Customers may require faster response, longer duration, stronger availability guarantees, or integration with on-site generation. Japan's 2026 Battery and Power Industry Strategy specifically identified advanced power-control needs associated with AI data centers, medical facilities, and disaster prevention as reasons for broader energy-storage solutions.
Battery costs and manufacturing scale support larger projects
The IEA reported that average battery costs had fallen by about 90% since 2010, reflecting advances in chemistry and manufacturing. Lower battery costs have improved project economics, while higher production volumes allow suppliers to standardize containers, racks, thermal systems, and control platforms.
The next commercial gains depend less on cell cost alone. Developers increasingly assess total installed cost, usable energy, degradation, auxiliary consumption, warranty terms, augmentation needs, and expected revenue over the project life. This shifts competition toward integrated system design and lifecycle performance.
Storage policy is moving toward explicit system planning
Governments are creating policies that treat storage as part of electricity-system infrastructure rather than only as a battery product. China's 2025–2027 action plan targets more than 180 GW of new-type energy storage capacity by 2027 and estimates around CNY 250 billion in direct project investment.
Japan has also revised its national battery strategy in 2026, targeting a domestic battery manufacturing base of 150 GWh per year from 2030 toward the mid-2030s. The policy also addresses supply-chain resilience and next-generation battery technologies.
Market Restraints and Challenges
Tariffs and trade rules can change project economics
Battery storage projects depend on globally distributed supply chains. Cells, power electronics, thermal systems, control equipment, and other components may cross several borders before reaching a project site. Wärtsilä reported that its Energy Storage business faced pressure from elevated U.S. tariffs, regulatory changes related to Foreign Entity of Concern rules, and competition in other markets.
These pressures can change supplier selection even when two systems have similar technical specifications. Developers may favor regional production, compliant component sourcing, or suppliers able to provide clearer documentation on origin and eligibility.
Supply-chain concentration remains a structural risk
The IEA has identified concentration across the battery supply chain. China accounts for well over half of global processing for lithium and cobalt and held almost 85% of global battery-cell production capacity in the IEA's 2024 assessment.
This concentration supports low-cost manufacturing but exposes buyers to trade restrictions, shipping disruption, policy changes, and geopolitical risk. National strategies in Japan, China, the United States, and Europe increasingly address local production and supply security, creating opportunities for regional manufacturers while raising the cost of duplication across markets.
Safety requirements increase system engineering costs
Stationary batteries operate for years and can contain large quantities of stored energy at a single site. Developers therefore need thermal management, fire detection and suppression, monitoring, electrical protection, site controls, and compliance with applicable safety standards.
System suppliers are responding through tighter integration. CATL's TENER platform includes dedicated quality management, safety measures, thermal controls, and monitoring, while Tesla integrates thermal systems and controls within Megapack. These features add value, but they also increase engineering and qualification requirements.
Project revenues can depend on local market design
Battery projects can earn revenue from energy arbitrage, capacity, frequency services, reserve products, congestion relief, and other grid functions. The available revenue stack differs by country and electricity market.
A technically strong project can therefore face weak economics if local rules limit participation in several services. The IEA has called for policy frameworks that recognize the different contributions of storage and provide fair market access among technologies.
Major Segment Analysis
Lithium-Ion Batteries
Lithium-ion batteries represent the commercially important chemistry category because their manufacturing scale, established supply chain, operating history, and improving cost structure fit both utility-scale and behind-the-meter projects. Within this category, LFP has gained a clear advantage in stationary storage. The IEA estimates that LFP represented around 90% of battery storage deployments in 2025.
Stationary storage buyers value LFP for characteristics that differ from those prioritized in many vehicle applications. Frequent cycling, thermal stability, usable capacity, service life, and system cost can matter more than maximum gravimetric energy density. CATL's TENER platform illustrates this shift by using LFP cells with 430 Wh/L cell-level energy density and a 6.25 MWh container configuration.
Supplier competition is moving toward complete systems rather than cells alone. Tesla combines battery modules, inverters, thermal systems, and controls in Megapack, while CATL has expanded from cells into containerized storage platforms and flexible rack systems. Buyers therefore compare usable energy, round-trip efficiency, degradation, fire safety, installation time, warranty coverage, service capability, and grid compatibility.
Regional Analysis
North America
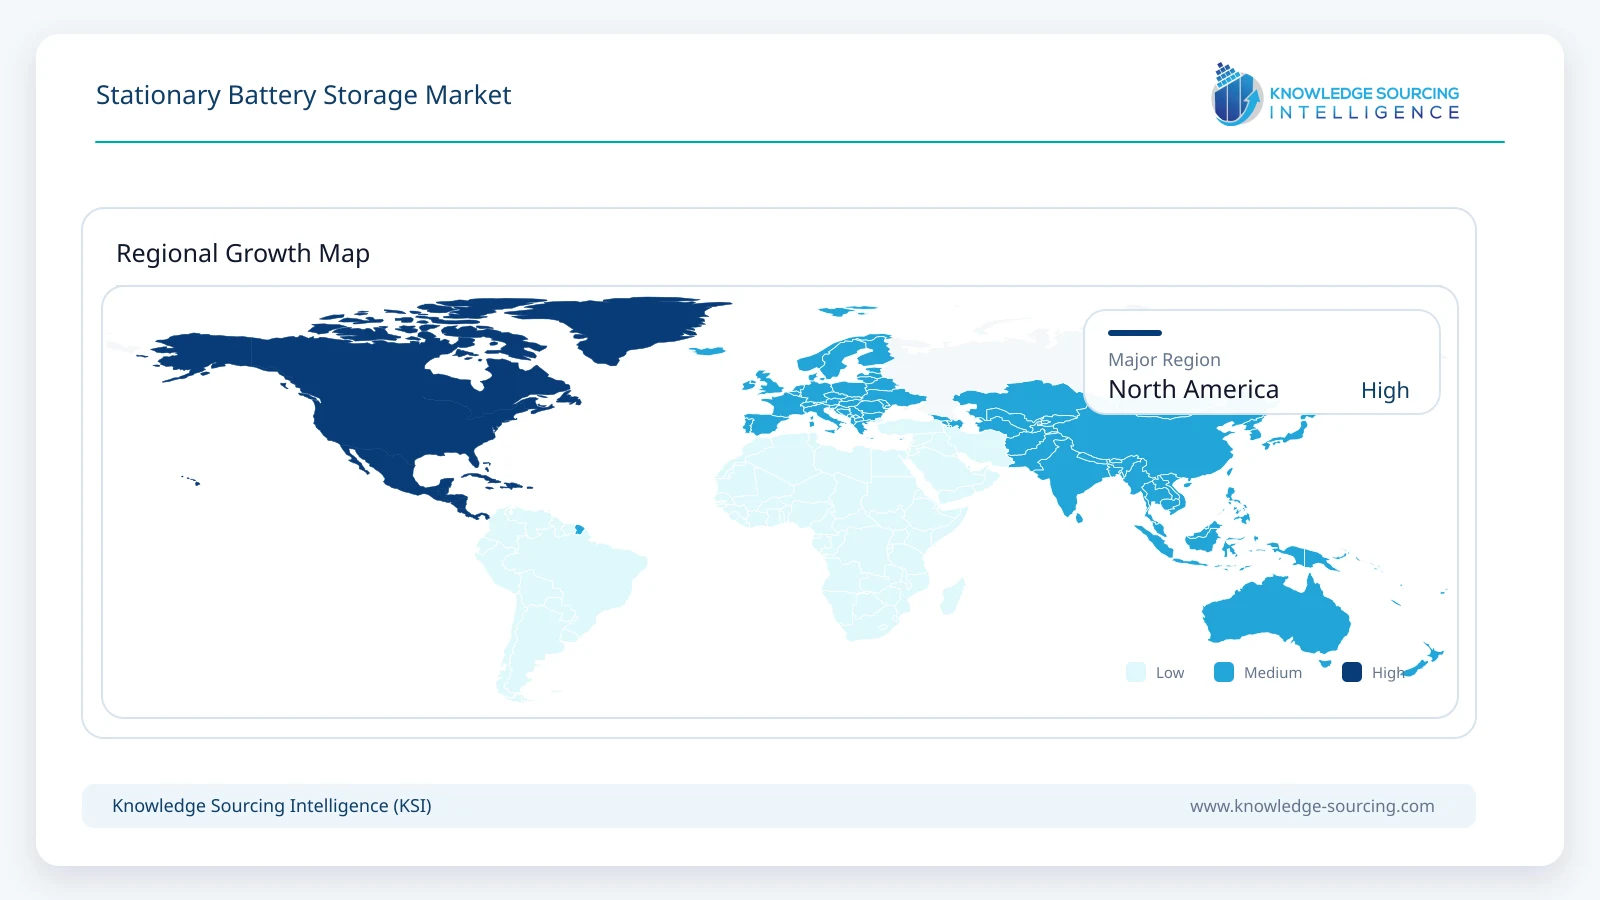
The United States is one of the most commercially developed stationary-storage markets. EIA data shows that U.S. utility-scale battery capacity reached nearly 52 GW by June 2026, after operators added 8.3 GW during the first six months of the year.
The market favors large grid-connected projects, but data-center load growth and industrial demand are adding new requirements for firm and flexible power. Tesla reported 46.7 GWh of energy-storage deployments in 2025 and continued expanding Megapack production, including manufacturing at its Shanghai facility.
Canada and Mexico provide additional opportunities, although project economics depend more heavily on local electricity-market design, renewable deployment, grid needs, and investment rules. Regional competition increasingly depends on domestic manufacturing, tariff exposure, certification, and project execution capability.
Europe
European demand is closely linked to renewable integration, electricity-price volatility, grid flexibility, and energy security. The European Commission states that its 2025 clean-energy competitiveness assessment identified an urgent need for faster deployment of energy storage infrastructure across the European Union. In March 2025, the Commission also launched the European Energy Storage Inventory to provide real-time storage information across European countries.
Germany, the United Kingdom, Italy, Spain, and France provide distinct demand conditions. Utility-scale systems are gaining importance as markets need flexibility around renewable generation, while residential and commercial storage remain relevant in markets with strong distributed solar. Suppliers must also meet differing grid codes, permitting rules, safety requirements, and market-access conditions.
Asia Pacific
Asia Pacific has the largest concentration of battery manufacturing and project deployment. China accounted for around 60% of global battery-storage additions in 2025, according to the IEA, while China's National Energy Administration reported 136 GW of new-type storage capacity by the end of 2025.
China's scale supports local supply chains and lower manufacturing costs, while its policy framework continues to expand storage applications. Japan is placing greater emphasis on domestic manufacturing and system-level power solutions, including applications linked to data centers and disaster resilience. Australia is also becoming an important storage market because batteries now provide a growing share of dispatchable capacity.
South America
Chile is developing a strong utility-scale storage market because batteries can absorb surplus solar generation and discharge during periods of higher demand. The IEA reported that Chile added close to 1 GW of battery capacity in 2025, while battery deployment also expanded across other markets in the region.
Brazil represents another relevant market because of its large power system and growing need to manage renewable generation and grid flexibility. The region remains more dependent on project-specific economics and electricity-market rules than China, the United States, or established European markets.
Middle East and Africa
The Middle East is becoming an important new market for large-scale storage, particularly where solar resources are strong and power-system flexibility is needed. The IEA reported that Saudi Arabia drove much of the region's recent battery deployment, with large projects supporting system flexibility.
The commercial model differs from mature storage markets because large projects can be tied directly to renewable generation, grid reliability, or national infrastructure programs. Suppliers must also address heat exposure, dust, water constraints, remote-site service, and local procurement rules.
Competitive Landscape
Competition is increasingly system-led rather than limited to battery cells. Suppliers are competing on energy density, usable capacity, safety, power-conversion efficiency, software controls, project delivery, warranty terms, service networks, and the ability to meet local grid and regulatory rules.
The supplied competitive set includes Tesla, Contemporary Amperex Technology Co., Limited (CATL), BYD Company Limited, Fluence Energy, LG Energy Solution, Samsung SDI, Sungrow Power Supply, Wärtsilä, Hitachi Energy, ABB, Panasonic Holdings, Toshiba, GS Yuasa, HOPPECKE Batterien, Powin, and Siemens Energy. Their market roles span battery manufacturing, integrated storage systems, power electronics, controls, project delivery, and grid infrastructure.
Tesla's energy-storage disclosures show the increasing importance of integrated systems. Its 2025 results reported 46.7 GWh of energy-storage deployments, while its product architecture combines battery modules, inverters, thermal systems, and controls.
CATL is extending competition at the system level through products such as TENER and TENER Flex. CATL reported that its energy-storage products had been deployed in more than 1,700 projects globally by November 2024, while its TENER platform targets higher energy density and lower site footprint.
BYD is also combining battery technology with integrated energy-storage systems. Its MC Cube platform was used in a 100 MW/400 MWh California project that entered service in 2025, while BYD continues to offer storage systems for residential, commercial, industrial, and grid applications.
Recent supplier actions also show that profitability can diverge from market deployment. Wärtsilä reported weak 2025 Energy Storage order intake, citing U.S. tariffs, regulatory changes, and competition, and later agreed in June 2026 to establish a 50/50 joint venture with RCT Solutions for its global Energy Storage business. This indicates that shipment growth does not automatically translate into attractive margins for every supplier.
Recent Developments
September 2026: LG Energy Solution announced its BESS qualified as NVIDIA DSX Ready BESS, supporting scalable power infrastructure for AI-driven environments through its advanced AC-coupled energy storage solution.
August 2026: Fluence and LEAG Clean Power began construction of the 400 MWh Heinersbrück GridBattery in Germany, deploying Fluence Smartstack technology alongside wind and solar generation assets.
July 2026: CATL and Alfen announced a partnership to deploy 5 GWh of CATL sodium-ion battery energy storage systems across Europe, expanding diversified storage technologies for Europe’s energy transition.
June 2026: CATL officially unveiled the TENER Sodium Energy Storage System, its field-validated sodium-ion BESS, with commercial production readiness and planned global deliveries beginning in June 2027.
May 2026: Ford Energy (a wholly owned subsidiary of Ford Motor Company) signed a five-year framework agreement with EDF power solutions North America to supply up to 20 GWh of DC Block battery energy storage systems (up to 4 GWh annually), with deliveries scheduled to begin in 2028.
Regulatory and Policy Environment
Storage policy is becoming more closely linked to grid planning, domestic manufacturing, safety, and market access. China's 2025 action plan targets more than 180 GW of new-type energy storage by 2027 and calls for broader applications, technology development, and standardization.
Japan revised its Battery and Power Industry Strategy in June 2026 after identifying global oversupply and supply-chain risks. The revised strategy targets 150 GWh per year of domestic battery manufacturing capacity from 2030 toward the mid-2030s and places greater emphasis on complete power-system capability.
Europe is also strengthening its storage policy framework. The European Commission's energy-storage work focuses on flexibility, reliability, and system stability, while its European Energy Storage Inventory provides a common information base for storage deployment across member states.
For suppliers, regulatory compliance now affects more than product certification. Local-content rules, trade restrictions, cybersecurity, fire safety, grid-forming capability, interconnection standards, environmental rules, and supply-chain disclosure can influence eligibility for projects and procurement decisions.
Outlook and Strategic Implications
The market is entering a broad expansion cycle, supported by strong deployment activity across utility-scale and other battery storage applications. Global battery capacity additions reached 108 GW in 2025, with utility-scale projects accounting for about four-fifths of total additions. This expansion reflects rising renewable energy integration, grid flexibility requirements, peak-demand management, and the growing need for reliable energy storage across power systems. The next phase of competition will depend on whether suppliers can reduce the total cost of ownership while meeting tighter safety, grid, and supply-chain rules. LFP is likely to remain commercially important while alternative chemistries compete where duration, material availability, temperature performance, or specific operating requirements justify a different design.
Four strategic issues will shape commercial outcomes through 2031:
System economics: Buyers will compare usable energy, degradation, efficiency, warranty terms, augmentation, service cost, and project revenue rather than cell price alone.
Supply security: Manufacturers and developers will place greater value on regional production, diversified sourcing, and compliance with trade and local-content rules.
Project integration: Suppliers able to combine batteries, power conversion, controls, thermal management, software, and service can address more of the project lifecycle.
Market design: Revenue opportunities will depend on how utilities and regulators value frequency response, capacity, energy shifting, congestion relief, and other storage services.
For investors and manufacturers, the strongest opportunities are likely to remain in markets where storage has several revenue streams and where grid constraints or renewable integration create a measurable need for flexibility. For buyers, supplier selection will increasingly depend on bankability, safety record, local service capability, warranty quality, supply-chain transparency, and proven project execution. The commercial performance of the market will therefore depend not only on battery demand, but on the ability to convert large deployment volumes into durable project returns.
Stationary Battery Storage Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 21.7 billion |
| Total Market Size in 2031 | USD 62.5 billion |
| Forecast Unit | Billion |
| Growth Rate | 23.6% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Battery Chemistry, Power Capacity, Application, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Battery Chemistry
Lithium-Ion Batteries
Lithium Iron Phosphate (LFP)
Nickel Manganese Cobalt (NMC)
Nickel Cobalt Aluminum (NCA)
Sodium-Based Batteries
Sodium-Sulphur
Sodium-Ion
Lead-Acid Batteries
Flow Batteries
Vanadium Flow Batteries
Zinc-Based Flow Batteries
Other Emerging Chemistries
By Power Capacity
Below 100 kWh
100 to 500 kWh
500 to 1,000 kWh
Above 1,000 kWh
By Application
Grid Services
Frequency Regulation
Flexible Ramping
Black Start Services
Energy Shifting and Capacity Deferral
Transmission and Distribution Congestion Relief
Capacity Firming
Others
Behind-the-Meter
Residential
Commercial and Industrial
Microgrids and Mini-Grids
Off-Grid Applications
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Chile
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
United Arab Emirates
South Africa
Others
Asia Pacific
China
Japan
South Korea
India
Australia
Indonesia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. STATIONARY BATTERY STORAGE MARKET BY BATTERY CHEMISTRY
5.1. Introduction
5.2. Lithium-Ion Batteries
5.2.1. Lithium Iron Phosphate (LFP)
5.2.2. Nickel Manganese Cobalt (NMC)
5.2.3. Nickel Cobalt Aluminum (NCA)
5.3. Sodium-Based Batteries
5.3.1. Sodium-Sulphur
5.3.2. Sodium-Ion
5.4. Lead-Acid Batteries
5.5. Flow Batteries
5.5.1. Vanadium Flow Batteries
5.5.2. Zinc-Based Flow Batteries
5.6. Other Emerging Chemistries
6. STATIONARY BATTERY STORAGE MARKET BY POWER CAPACITY
6.1. Introduction
6.2. Below 100 kWh
6.3. 100 to 500 kWh
6.4. 500 to 1,000 kWh
6.5. Above 1,000 kWh
7. STATIONARY BATTERY STORAGE MARKET BY APPLICATION
7.1. Introduction
7.2. Grid Services
7.2.1. Frequency Regulation
7.2.2. Flexible Ramping
7.2.3. Black Start Services
7.2.4. Energy Shifting and Capacity Deferral
7.2.5. Transmission and Distribution Congestion Relief
7.2.6. Capacity Firming
7.2.7. Others
7.3. Behind-the-Meter
7.3.1. Residential
7.3.2. Commercial and Industrial
7.4. Microgrids and Mini-Grids
7.5. Off-Grid Applications
8. STATIONARY BATTERY STORAGE MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. By Battery Chemistry
8.2.2. By Power Capacity
8.2.3. By Application
8.2.4. By Country
8.2.4.1. United States
8.2.4.2. Canada
8.2.4.3. Mexico
8.3. South America
8.3.1. By Battery Chemistry
8.3.2. By Power Capacity
8.3.3. By Application
8.3.4. By Country
8.3.4.1. Brazil
8.3.4.2. Argentina
8.3.4.3. Chile
8.3.4.4. Others
8.4. Europe
8.4.1. By Battery Chemistry
8.4.2. By Power Capacity
8.4.3. By Application
8.4.4. By Country
8.4.4.1. Germany
8.4.4.2. United Kingdom
8.4.4.3. France
8.4.4.4. Italy
8.4.4.5. Spain
8.4.4.6. Others
8.5. Middle East and Africa
8.5.1. By Battery Chemistry
8.5.2. By Power Capacity
8.5.3. By Application
8.5.4. By Country
8.5.4.1. Saudi Arabia
8.5.4.2. United Arab Emirates
8.5.4.3. South Africa
8.5.4.4. Others
8.6. Asia Pacific
8.6.1. By Battery Chemistry
8.6.2. By Power Capacity
8.6.3. By Application
8.6.4. By Country
8.6.4.1. China
8.6.4.2. Japan
8.6.4.3. South Korea
8.6.4.4. India
8.6.4.5. Australia
8.6.4.6. Indonesia
8.6.4.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Tesla, Inc.
10.2. Contemporary Amperex Technology Co., Limited (CATL)
10.3. BYD Company Limited
10.4. Fluence Energy, Inc.
10.5. LG Energy Solution, Ltd.
10.6. Samsung SDI Co., Ltd.
10.7. Sungrow Power Supply Co., Ltd.
10.8. Wärtsilä Corporation
10.9. Hitachi Energy Ltd.
10.10. ABB Ltd.
10.11. Panasonic Holdings Corporation
10.12. Toshiba Corporation
10.13. GS Yuasa International Ltd.
10.14. HOPPECKE Batterien GmbH & Co. KG
10.15. Powin, LLC
10.16. Siemens Energy AG
11. RESEARCH METHODOLOGY
List of Figures
List of Tables





Frequently asked questions
What is the projected market size for stationary battery storage by 2031?
The Stationary Battery Storage Market is projected to reach USD 62.5 billion by 2031.
What is the growth rate (CAGR) for stationary battery storage from 2026 to 2031?
The Stationary Battery Storage Market will grow at a 23.6% CAGR from 2026 to 2031.
Which battery chemistry dominated deployments in 2025 for stationary storage?
LFP batteries represented approximately 90% of global deployments in 2025.
Which application segment leads the Stationary Battery Storage Market?
Utility-scale systems represented about 80% of global additions in 2025.
Which country led global battery storage additions in 2025?
China accounted for around 60% of global battery storage additions in 2025.
What are the primary drivers for Stationary Battery Storage Market growth?
Renewable integration, rising electricity demand, and grid flexibility are key drivers.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Stationary Battery Storage Market - Forecasts from 2026 to 2031. https://www.knowledge-sourcing.com/report/stationary-battery-storage-market