
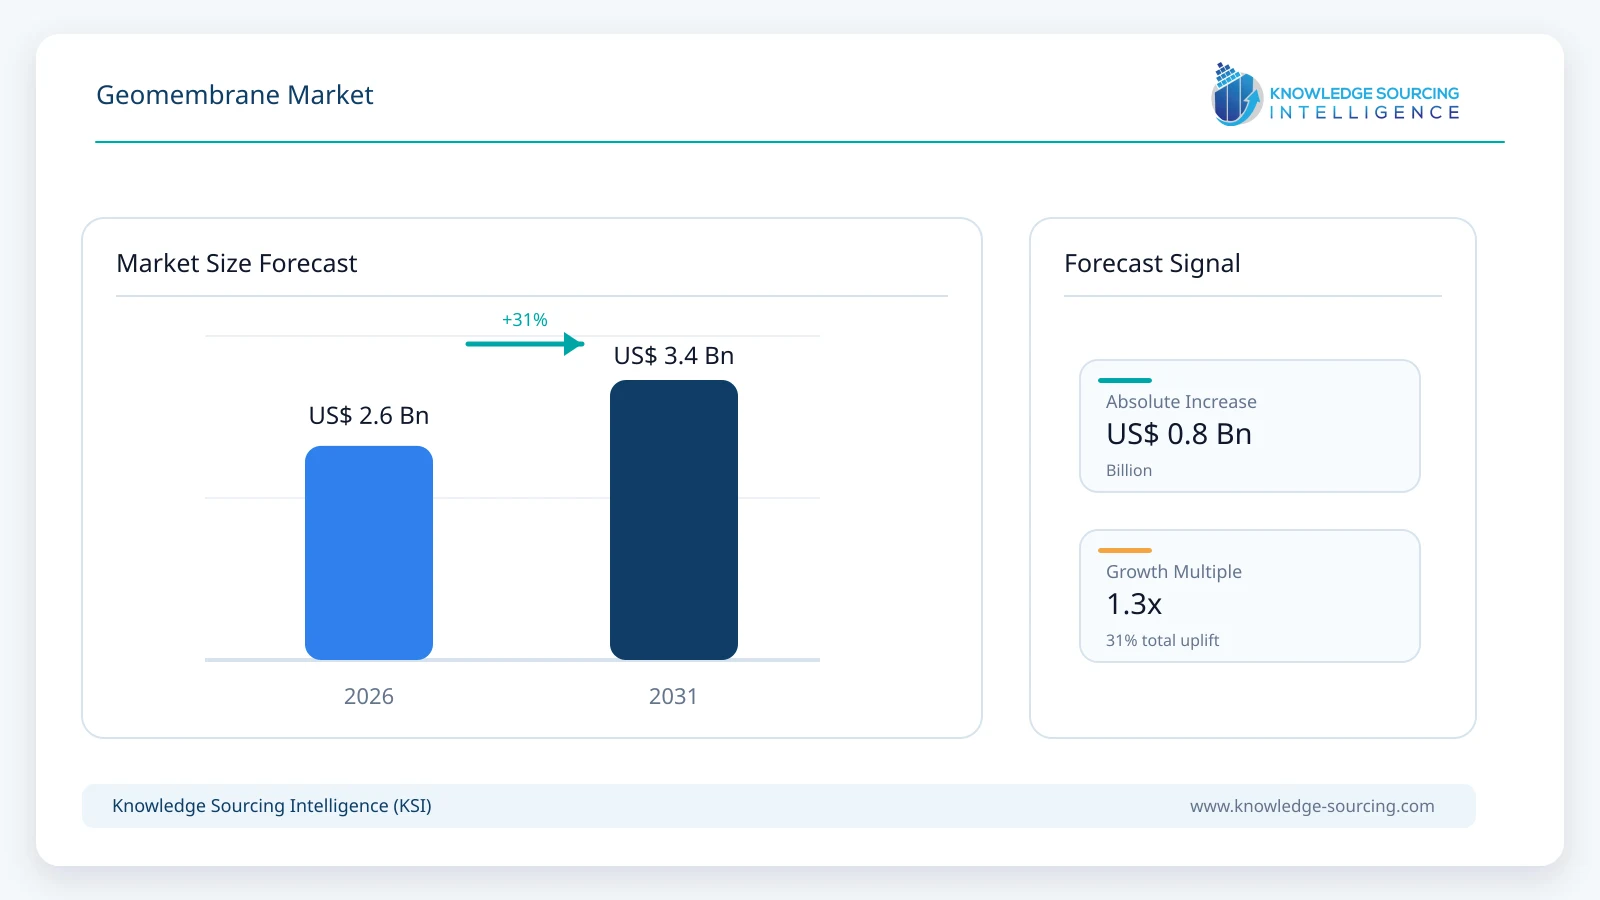
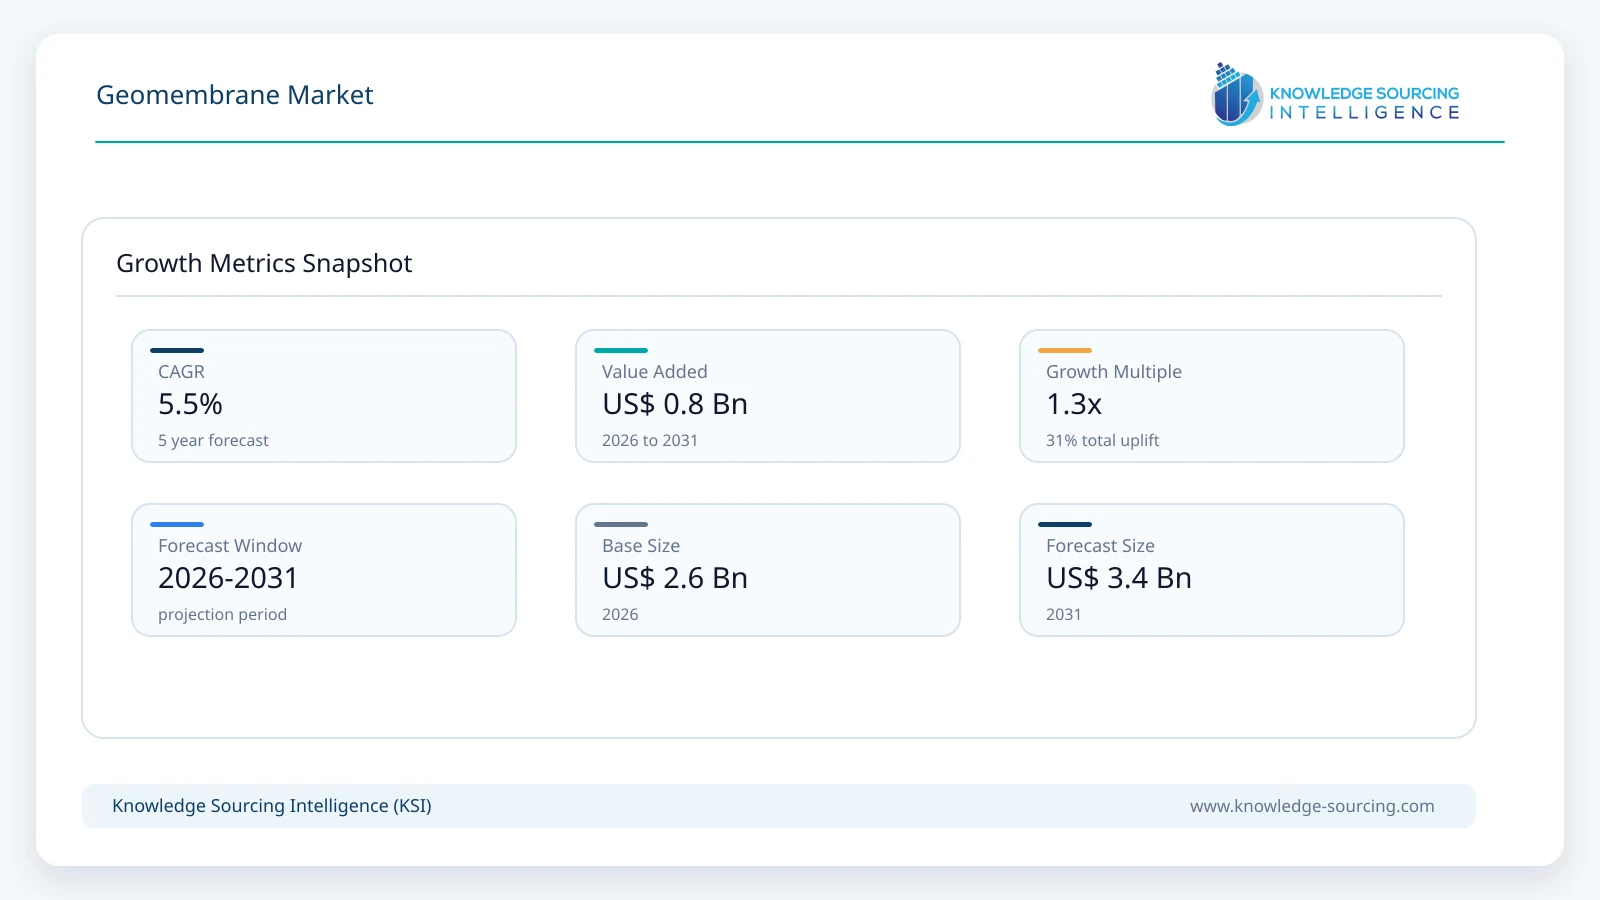
The Global Geomembrane market is forecast to grow at a CAGR of 5.5%, reaching USD 3.4 billion in 2031 from USD 2.6 billion in 2026.
Highlights:
- 1HDPE geomembranes account for approximately 58% of global market value in 2026.
- 2Mining applications are projected to grow at approximately 6.5% annually through 2031.
- 3Water-management end users generate about USD 650 million of market value in 2026.
- 4Asia Pacific represents approximately 39% of global geomembrane revenue in 2026.
- 5Conductive and textured liners are gaining importance in high-consequence containment projects.
- 6Large water, mining, and landfill projects increasingly specify multilayer barrier systems and leak detection.
Market Overview
Geomembranes act as the primary hydraulic barrier in containment systems. Their performance depends on polymer formulation, thickness, seam integrity, interface friction, and resistance to chemical and environmental exposure. Smooth HDPE liners are widely used on flatter surfaces, while textured products improve stability on slopes. Flexible reinforced membranes are preferred in some exposed or prefabricated applications because they can be fabricated into larger panels and tolerate greater deformation. The product selected for a project must therefore match the fluid chemistry, temperature, loading, geometry, and expected service life.
Regulation creates a durable demand base. In the United States, municipal solid-waste landfill requirements under Resource Conservation and Recovery Act Subtitle D use composite liner systems to protect groundwater. The European Union Landfill Directive requires engineered bottom and top barriers to prevent pollution of soil and water. Similar requirements are embedded in landfill, mining and water regulations in many other countries. This creates demand that is linked to environmental compliance rather than discretionary construction alone.
Water infrastructure is becoming another important demand center. Reservoirs, irrigation canals and industrial ponds use geomembranes to reduce seepage and protect water quality. In May 2026, Layfield was awarded a major contract to reline the Garvey Reservoir in California with a double geomembrane system and floating cover. Mining projects also require large liner areas. Solmax documented 900,000 square meters of HDPE geomembrane at the Umm Wu'al phosphate project in Saudi Arabia and more than 3.4 million square meters at large salt-evaporation ponds during 2026.
Demand Themes
Demand Theme | Market Implication |
Landfill and hazardous-waste compliance | Creates recurring demand for certified liners, caps and composite barrier systems. |
Mining and tailings containment | Supports thicker, textured and high-oxidation-resistance HDPE grades. |
Water scarcity and reservoir rehabilitation | Expands demand for potable-water-compliant and flexible liner systems. |
Leak detection and quality assurance | Increases use of conductive geomembranes and electrical leak-location methods. |
Market Trends
Leak detection is becoming part of the liner system rather than a post-installation check
High-consequence projects are placing more emphasis on verifying liner integrity before facilities enter service. Conductive geomembranes allow electrical leak-location surveys to identify defects that may be difficult to find visually. Solmax has expanded the use of conductive and leak-location products in mining and containment applications. This approach is particularly relevant where the liner will be covered by drainage material or process ore after installation. Early defect detection reduces the risk of later repair and supports documented construction quality assurance.
Mining containment is moving toward project-specific durability rather than minimum index compliance
Tailings storage facilities and heap-leach pads expose liners to high loads, aggressive chemistry, and long service periods. Suppliers are therefore emphasizing resin design, oxidation resistance, textured interfaces and project-specific testing. Solmax highlighted this issue in 2026 through updated guidance for mining containment. NAUE also markets enhanced-oxidation-resistant Carbofol grades for heap leach pads and tailings applications. The trend favors suppliers that can provide material testing, slope-stability data and technical support alongside the membrane itself.
Flexible reinforced membranes are expanding in water and exposed-containment projects
HDPE remains dominant, but flexible reinforced membranes have advantages where prefabrication, exposed service or movement tolerance are important. Layfield uses reinforced CSPE and specialty polyethylene systems for large municipal water assets. VIAFLEX supplies reinforced polyethylene, CSPE, EIA and barrier films across water, agriculture and environmental containment. These products broaden the market beyond conventional black HDPE liners and create higher-value niches where installation speed and long-term exposed performance matter.
Market Drivers
Waste-management regulation creates non-discretionary containment demand
Modern landfills require engineered barriers to reduce leachate migration into soil and groundwater. The United States and European Union both maintain detailed requirements for landfill liner and cover systems. New landfill cells, hazardous-waste facilities and closure projects therefore create recurring demand for geomembranes even when broader construction activity is weak. The same principle applies to industrial ash ponds, contaminated-site remediation and wastewater lagoons where regulators require long-term containment performance.
Water scarcity supports reservoir, canal and agricultural pond lining
Water losses through seepage can be material in unlined reservoirs and canals. Geomembranes allow operators to create a low-permeability barrier without relying only on compacted clay. Demand is particularly relevant in arid regions and in municipal systems where potable-water protection is critical. Large relining projects also provide a replacement market as older membranes reach the end of their useful life or assets are upgraded to modern safety requirements.
Mining investment creates large-area demand for engineered liner systems
Heap-leach pads, process ponds and tailings facilities can require hundreds of thousands or millions of square meters of liner material. The value per project is therefore high even though the number of projects is limited. Copper, gold, phosphate, lithium and other mineral developments support demand. The strongest opportunity is in projects that require thick HDPE, textured surfaces, conductive layers or high-oxidation-resistance formulations because these specifications raise both technical barriers and product value.
Market Restraint
Installation quality and polymer-price volatility can delay projects and compress margins
Geomembrane performance depends on both manufacturing quality and field installation. Poor subgrade preparation, welding defects, or damage during cover placement can compromise a technically suitable material. Large projects therefore require trained installers, welding equipment, and detailed quality assurance. Polyethylene and PVC resin prices also influence manufacturing cost. When resin and freight prices rise quickly, suppliers may face margin pressure, or customers may delay lower-priority lining work. These issues are most visible in price-sensitive municipal and agricultural projects.
Segment Analysis
By Raw Material - High-Density Polyethylene (HDPE)
HDPE is the largest raw-material segment because it offers strong chemical resistance, long service life, and broad acceptance in landfill and mining standards. The segment is projected to reach approximately USD 2.0 billion by 2031. Smooth products are widely used on flat containment surfaces, while textured grades improve interface friction on slopes. Higher-performance HDPE grades are also being developed for elevated temperatures and aggressive mining environments.
By Technology - Extrusion
Extrusion is the dominant manufacturing technology because polyethylene geomembranes are commonly produced as continuous sheets using blown-film or flat-die processes. The segment is projected to grow at approximately 5.6% annually through 2031. Extrusion supports large roll widths, controlled thickness, and textured or multilayer constructions. Calendering remains important for PVC, CSPE and other reinforced flexible membranes where fabric reinforcement and multilayer structures are required.
By Application - Mining
Mining is one of the largest high-value applications because heap-leach pads, tailings facilities and process-water ponds require large liner areas and demanding material specifications. The segment is estimated at approximately USD 780 million in 2026. Growth is supported by mineral investment and tighter containment standards. Technical requirements are highest where liners face steep slopes, aggressive process solutions, high temperatures, or long uncovered service periods.
By End User - Water Management
Water management is a major end-user segment across municipal reservoirs, irrigation canals, industrial ponds and potable-water systems. The segment is projected to grow at approximately 5.9% annually through 2031. Demand is driven by water-loss reduction, rehabilitation of aging assets, and the need to isolate stored water from unsuitable ground conditions. Flexible reinforced membranes retain an important position in covered reservoirs and prefabricated water-containment systems.
By Geography - Asia Pacific
Asia Pacific is the largest regional market because it combines extensive mining activity, rapid urbanization, large waste-management needs, and substantial investment in water infrastructure. Regional market value is projected to reach approximately USD 1.37 billion by 2031. China remains the largest manufacturing and demand center, while Australia is important in mining. India and Southeast Asia are expanding landfill, industrial-water, and infrastructure applications as environmental standards become more formalized.
Competitive Environment
Solmax is the largest global geosynthetics supplier and has a broad geomembrane portfolio under the GSE brand. Its products cover HDPE, LLDPE, high-temperature liners, conductive geomembranes, and concrete protection systems. AGRU competes strongly in high-quality polyethylene lining systems and is expanding its U.S. manufacturing footprint. NAUE supplies Carbofol HDPE geomembranes together with complementary geosynthetic clay liners and protection geotextiles.
Atarfil, Plastika Kritis, JUTA and Officine Maccaferri add significant European manufacturing capacity. VIAFLEX is the current owner of the former Raven Engineered Films business and supplies a broad range of reinforced and multilayer geomembranes in the United States. Layfield combines manufacturing, fabrication, and installation across North America and Australia. This vertically integrated model is valuable on reservoir and industrial-containment projects where fabrication and field installation are closely linked.
Seaman Corporation, Plastatech Engineering, Titan Environmental Containment, Aquatan, Megaplast and Poly-America serve specialized regional and material niches. Competition depends on resin formulation, certification, roll width, texture capability, fabrication quality and field technical support. Large projects increasingly favor suppliers that can provide design assistance, welding guidance and documented quality-control systems rather than membrane material alone.
Recent Developments
August 2026: Solmax documented more than 3.4 million m² of GSE HD geomembrane used to line large salt-evaporation ponds under extreme heat and UV exposure.
August 2026: Solmax reported the use of 900,000 m² of double-sided GSE HD FrictionFlex geomembrane at Saudi Arabia's Umm Wu'al phosphate project.
July 2026: Solmax reported a 113,000 m² HDPE geomembrane installation for coal-ash and wastewater containment at a regulated Indonesian power facility.
May 2026: Layfield was awarded the Garvey Reservoir relining and floating-cover contract in California using reinforced CSPE geomembrane systems.
May 2026: Solmax began construction of a new eight-hectare European geosynthetics center in Les Mureaux, France.
April 2026: AGRU America reorganized its executive and lining-systems leadership as it continued expansion across U.S. manufacturing operations.
March 2026: Layfield completed a multilayer geomembrane and geocomposite liner system for a produced-water hub in British Columbia.
February 2026: Solmax documented a geomembrane and geosynthetic-clay-liner system used for comprehensive lining and capping at Thailand's ESBEC landfill.
Geomembrane Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.6 billion |
| Total Market Size in 2031 | USD 3.4 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.5% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Raw Material, Technology, Application, End User |
| Companies |
|
Market Segmentation
By Raw Material
High-Density Polyethylene (HDPE)
Low-Density Polyethylene (LDPE)
Linear Low-Density Polyethylene (LLDPE)
Polyvinyl Chloride (PVC)
Ethylene Propylene Diene Monomer (EPDM)
Polypropylene (PP)
Others
By Technology
Extrusion
Calendering
By Application
Waste Containment
Mining
Water Management
Tunnel Liners and Civil Engineering
Other Applications
By End User
Mining
Water Management
Waste Management
Civil Construction
Agriculture
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Australia
Indonesia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Waste-Management Regulation Creates Non-Discretionary Containment Demand
3.1.2. Water Scarcity Supports Reservoir, Canal and Agricultural Pond Lining
3.1.3. Mining Investment Creates Large-Area Demand for Engineered Liner Systems
3.2. Market Restraint
3.2.1. Installation Quality and Polymer-Price Volatility Can Delay Projects and Compress Margins
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Conductive Geomembranes and Electrical Leak Location
4.2. Textured and High-Friction Surfaces
4.3. High-Oxidation-Resistance Polyethylene
4.4. Reinforced Flexible Geomembranes
4.5. Prefabrication and Multilayer Barrier Systems
5. GEOMEMBRANE MARKET BY RAW MATERIAL
5.1. Introduction
5.2. High-Density Polyethylene (HDPE)
5.3. Low-Density Polyethylene (LDPE)
5.4. Linear Low-Density Polyethylene (LLDPE)
5.5. Polyvinyl Chloride (PVC)
5.6. Ethylene Propylene Diene Monomer (EPDM)
5.7. Polypropylene (PP)
5.8. Others
6. GEOMEMBRANE MARKET BY TECHNOLOGY
6.1. Introduction
6.2. Extrusion
6.3. Calendering
7. GEOMEMBRANE MARKET BY APPLICATION
7.1. Introduction
7.2. Waste Containment
7.3. Mining
7.4. Water Management
7.5. Tunnel Liners and Civil Engineering
7.6. Other Applications
8. GEOMEMBRANE MARKET BY END USER
8.1. Introduction
8.2. Mining
8.3. Water Management
8.4. Waste Management
8.5. Civil Construction
8.6. Agriculture
9. GEOMEMBRANE MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. Germany
9.4.2. France
9.4.3. United Kingdom
9.4.4. Italy
9.4.5. Spain
9.4.6. Others
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. UAE
9.5.3. South Africa
9.5.4. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. Japan
9.6.3. India
9.6.4. South Korea
9.6.5. Australia
9.6.6. Indonesia
9.6.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Product and Technology Positioning
10.4. Mergers, Acquisitions, Agreements and Collaborations
10.5. Competitive Dashboard
11. COMPANY PROFILES
11.1. Solmax International Inc.
11.2. AGRU Kunststofftechnik GmbH
11.3. NAUE GmbH & Co. KG
11.4. Atarfil S.L.
11.5. VIAFLEX
11.6. Layfield Group Ltd.
11.7. Plastika Kritis S.A.
11.8. Officine Maccaferri S.p.A.
11.9. JUTA a.s.
11.10. Seaman Corporation
11.11. Plastatech Engineering Ltd.
11.12. Titan Environmental Containment Ltd.
11.13. Aquatan (Pty) Ltd.
11.14. Megaplast India Pvt. Ltd.
11.15. Poly-America, L.P.
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations
Navigate
Trusted by the world's leading organizations











