
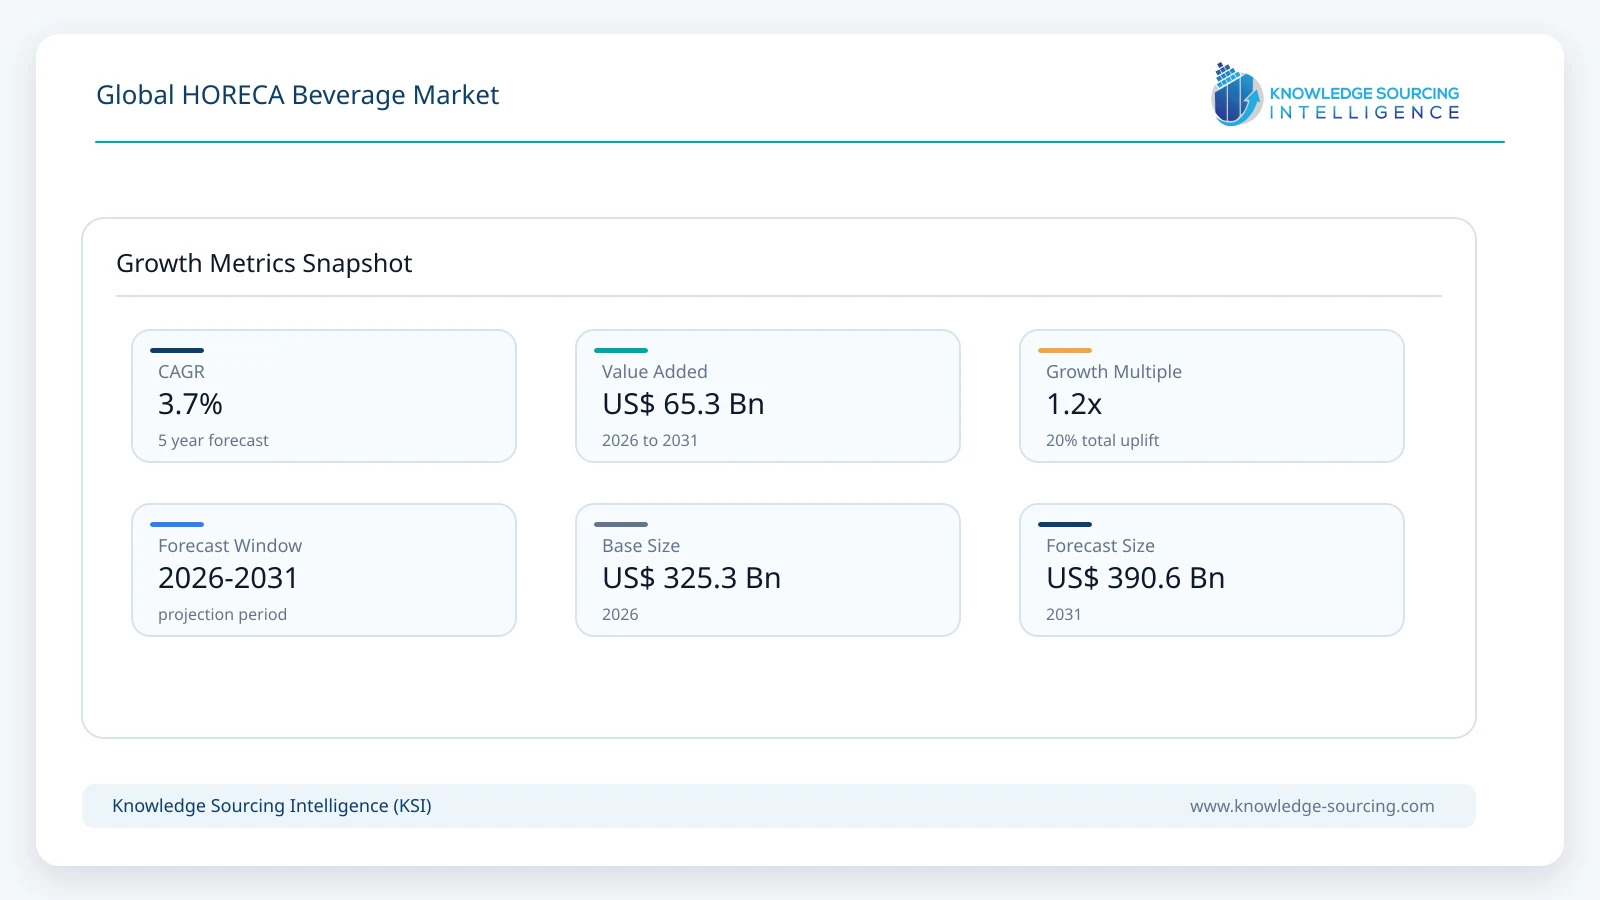
The HORECA Beverage Market is forecast to grow at a CAGR of 3.7%, reaching USD 390.7 billion in 2031 from USD 325.3 billion in 2026.
Highlights:
- 1Restaurants account for approximately 52% of HORECA beverage market value in 2026 and remain the largest end-user segment through 2031.
- 2Non-Alcoholic Beverage represents approximately 57% of market value in 2026 and increases to about 59% by the end of the forecast period.
- 3Bottled Water is estimated at approximately 28% of the non-alcoholic segment in 2026 and gains modest share as hotel, restaurant and event demand expands.
- 4Spirits grow faster than beer/malt within the alcoholic segment as premium pricing and cocktail-led consumption support value growth.
- 5Asia Pacific accounts for approximately 31% of global market value in 2026 and is projected to reach about 33% by 2031.
- 6Hotels increase their share from approximately 28% in 2026 to 29% by 2031, while restaurants remain above half of market value throughout the forecast period.
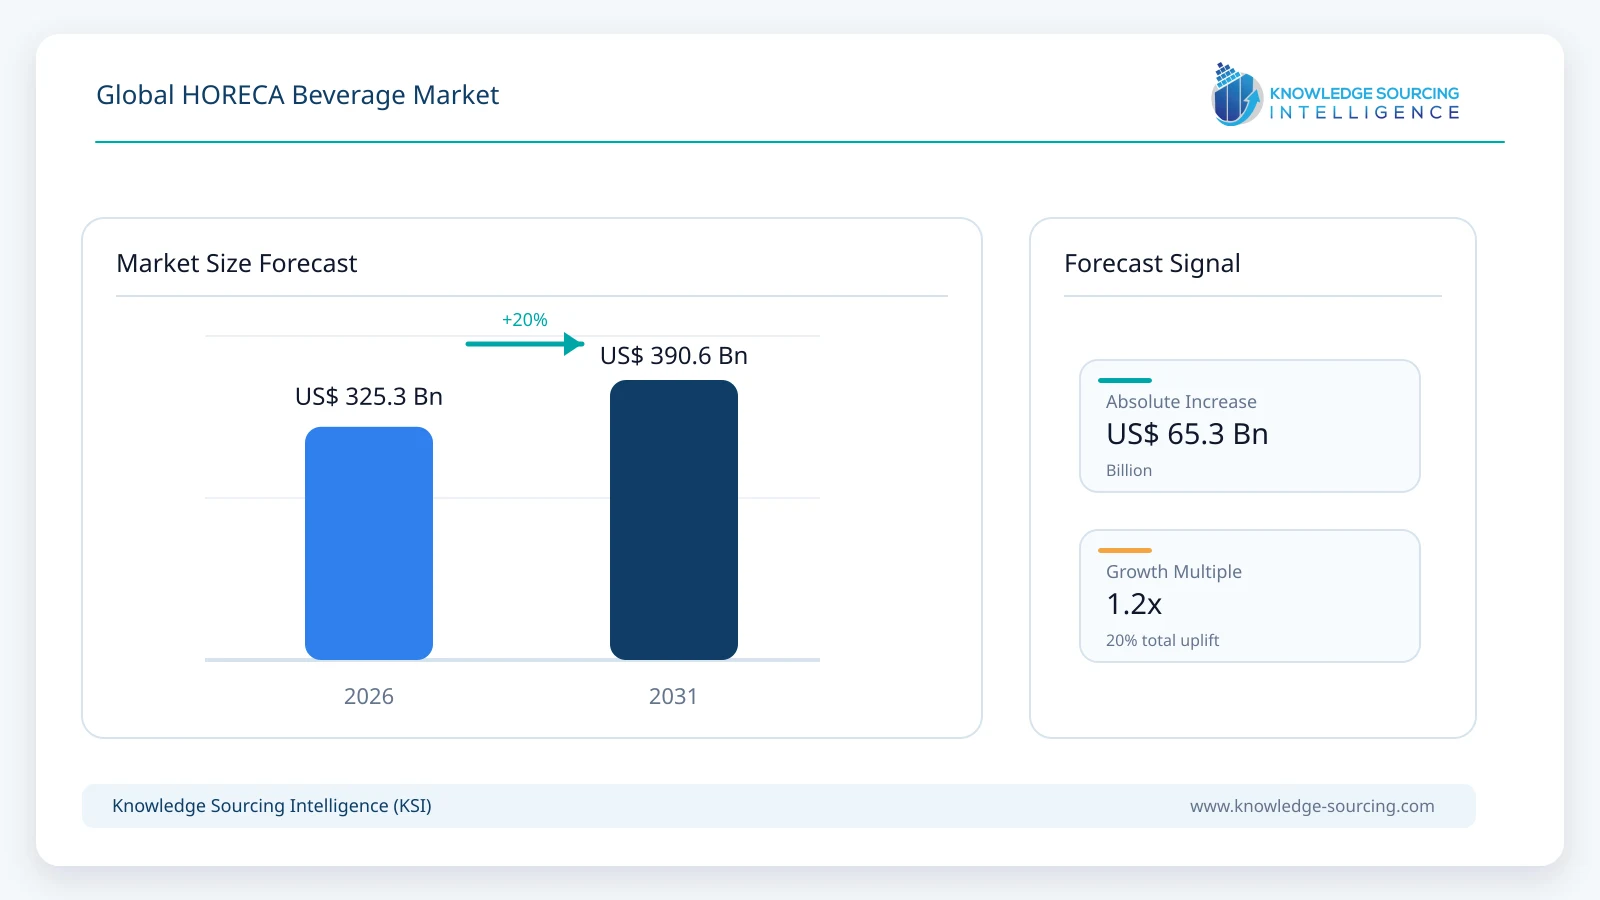
Demand is tied to foodservice transactions, hotel occupancy, tourism, events and the expansion of organized restaurant and café networks, while category growth differs materially by beverage type. Non-alcoholic beverages account for the larger share of spending and are expected to increase from approximately 57% of the market in 2026 to 59% by 2031 as bottled water and milk-based beverages grow faster than beer, fruit juice and conventional carbonated soft drinks.
The market remains operationally different from retail beverage sales because suppliers compete for menu placement, dispensing rights, refrigeration space and recurring outlet contracts rather than shelf position alone. Coca-Cola Europacific Partners reported more than 75,000 cooler placements in Europe during 2025 and continued to prioritize away-from-home execution, while PepsiCo launched its House of Treats platform in 2026 for restaurants, cinemas, stadiums and other high-volume venues. These investments show that distribution capability, equipment and account servicing remain important alongside product portfolio strength.
Restaurants remain the largest end-user segment, accounting for approximately 52% of market value in 2026. Their position reflects the number of transactions handled by the channel and the broad mix of beverages sold across quick-service, casual and full-service formats. Hotels account for approximately 28% of value and gain modest share through 2031 as tourism and premium hospitality recover, while cafés retain approximately one-fifth of market spending under the current KSI segmentation.
Market Growth Drivers and Trends
Expansion of Foodservice and Tourism Activity
HORECA beverage demand rises with restaurant traffic, hotel stays and organized catering activity because these channels generate recurring beverage purchases alongside food and accommodation spending. The existing KSI report identifies restaurant expansion and tourism as central demand factors, while foodservice activity in major markets continues to provide a large underlying transaction base. Growth in international travel, conferences and leisure hospitality is particularly relevant to hotels because beverage sales extend across restaurants, bars, banquets, room service and event facilities. The effect on market value is therefore broader than a simple increase in packaged drink volumes and supports steady expansion through 2031.
Investment in Away-From-Home Distribution and Equipment
Large beverage companies continue to invest in equipment and account coverage because product availability and serving conditions directly affect foodservice sales. Coca-Cola Europacific Partners placed more than 75,000 coolers in Europe during 2025 and reported growth in away-from-home volumes, while its 2026 plan includes further investment in coolers and execution capability. PepsiCo maintains dedicated foodservice operations and launched House of Treats in June 2026 for restaurants, cinemas, stadiums and entertainment locations. These programs increase supplier control over cold availability, dispensing, promotions and account-level execution, which is particularly important for large restaurant and hotel chains.
Dispensing Technology Is Expanding Menu Flexibility
Foodservice dispensing is moving beyond conventional fountain systems as suppliers add software, compact equipment and broader mixing capability. Coca-Cola introduced a new generation of dispensing technology in May 2026, including Freestyle Mini for bars, cafés and compact venues and a non-alcoholic mixology dispenser developed with Micro Matic. PepsiCo's House of Treats follows the same direction by allowing customized beverages to be produced at high-volume venues without materially reducing service speed. The technology gives operators more menu options from a limited equipment footprint and strengthens the role of dispensing systems in supplier selection.
Alcohol-Free Products Are Expanding the Beer Portfolio
Alcohol-free products are growing faster than conventional beer within several major portfolios and are increasingly relevant to on-premise menus. Carlsberg reported 11% organic growth in alcohol-free brews during the first half of 2026 compared with 1% growth in premium beer, while Heineken expanded its 0.0 range with Cold Pressed Lime and Nectarine Juniper in 2026. These products allow hotels and restaurants to serve customers who are moderating alcohol consumption without removing conventional beer from the menu. The category therefore broadens the addressable drinking occasion even as total beer/malt growth remains below the overall HORECA beverage market.
Premiumization Supports Spirits and Higher-Value On-Premise Sales
Spirits retain a strong position in hotels and restaurants because cocktails, premium brands and bartender-led service support higher revenue per serving than standard packaged beverages. Diageo continues to identify cocktail culture, moderation, food occasions and luxury as important demand themes, even as fiscal 2026 performance varied by region. KSI therefore models spirits to increase from approximately 30% of alcoholic HORECA beverage value in 2026 to 32% by 2031, while beer/malt loses modest share. The forecast reflects pricing mix and product positioning rather than an assumption of rapid volume growth.
Market Restraints
Commodity and Packaging Costs
Beverage suppliers remain exposed to movements in sugar, fruit, grains, dairy inputs, aluminium, glass, energy and freight, while foodservice operators remain sensitive to increases in menu prices. Higher input costs can be passed through only to the extent that restaurants and hotels can maintain acceptable beverage price points relative to meals and overall customer spending. The pressure is therefore shared across manufacturers, distributors and outlets and can reduce promotional activity or shift purchasing toward lower-cost brands and formats.
Purchasing Power of Large Foodservice Accounts
Large restaurant and hotel groups have significant negotiating power because a single supply agreement can cover hundreds or thousands of outlets. Contracts can include beverage pricing, fountain equipment, coolers, rebates, promotional support and maintenance, which secures recurring volumes for suppliers but can limit margins. Independent outlets create a different cost problem because smaller orders and higher delivery frequency increase distribution expense. The structure of the customer base therefore constrains both pricing and route-to-market economics.
Packaging and Reuse Requirements
Packaging rules are increasing the operating requirements associated with beverages served through hotels, restaurants and cafés. Reusable glass, returnable containers and dispensing systems can reduce single-use packaging, but they also require storage, collection, cleaning and reverse logistics. Larger beverage groups can spread these costs across established distribution systems, whereas smaller suppliers and outlets face higher implementation burdens. Regulation can therefore change the relative economics of packaging formats even where underlying beverage demand remains unchanged.
Fragmented Distribution
The HORECA customer base is fragmented across multinational chains, independent restaurants, hotels, cafés and local foodservice operators. National accounts can be served through centralized agreements, but smaller outlets frequently depend on wholesalers and regional distributors for replenishment. This increases the number of intermediaries between manufacturer and point of consumption and reduces direct control over inventory, pricing and menu placement. Distribution density remains an important barrier to scale in markets where organized foodservice has a smaller share.
Alcohol Regulation and Taxation
Beer, wine and spirits face licensing, excise, serving-hour and advertising restrictions that vary substantially by market. These rules affect outlet eligibility, end-consumer pricing and promotional flexibility and can reduce the addressable alcoholic beverage market in countries with tighter controls. The effect is particularly relevant to hotel and restaurant operators that serve international customers but must adapt beverage menus to local regulation. Non-alcoholic beverages therefore carry greater strategic importance in markets where alcohol availability is limited.
HORECA Beverage Market Segmentation Analysis
By Type
Alcoholic Beverage
Alcoholic Beverage accounts for approximately USD 139.89 billion, or 43% of total HORECA beverage market value, in 2026. Beer/malt provides the largest volume base within the alcoholic segment, while wine and spirits contribute a larger proportion of premium restaurant and hotel spending. The segment is projected to reach approximately USD 160.17 billion by 2031, although its share declines to around 41% as non-alcoholic beverages grow faster.
Beer/Malt
Beer/Malt is estimated at approximately USD 64.35 billion in 2026, equal to about 46% of alcoholic HORECA beverage value. Restaurants, bars, hotels, sporting venues and events provide the main consumption base, supported by draught systems and established distributor networks. The segment reaches approximately USD 70.47 billion by 2031 but declines to about 44% of alcoholic beverage value as alcohol-free alternatives and higher-value spirits grow faster.
Wine
Wine is estimated at approximately USD 33.57 billion in 2026 and remains concentrated in full-service restaurants, hotels, banquets and premium catering. Demand is closely linked to food pairing, tourism and higher-value dining rather than high-frequency refreshment occasions. The segment is projected to reach approximately USD 38.44 billion by 2031 and maintain about 24% of alcoholic HORECA beverage value.
Spirits
Spirits account for approximately USD 41.97 billion in 2026 and are projected to reach about USD 51.25 billion by 2031. Cocktails, premium brands and higher revenue per serving support stronger value growth than beer/malt, particularly in hotels, bars and full-service restaurants. The segment increases from roughly 30% to 32% of alcoholic HORECA beverage value by the end of the forecast period.
Non-Alcoholic Beverage
Non-Alcoholic Beverage accounts for approximately USD 185.44 billion, or 57% of market value, in 2026 and is projected to reach USD 230.48 billion by 2031. The category serves every major HORECA end-user and is less constrained by licensing than alcohol. Growth is led by bottled water and milk within the current KSI segmentation, while carbonated soft drinks continue to provide a large restaurant volume base and fruit juice remains concentrated in breakfast, hotel and catering occasions.
Bottled Water
Bottled Water is estimated at approximately USD 51.92 billion in 2026, or 28% of the non-alcoholic segment. Demand is broad across hotels, restaurants, meetings, catering and travel-related foodservice, while premium still and sparkling water can support higher pricing in full-service outlets. The segment is projected to reach approximately USD 66.84 billion by 2031 and increase to about 29% of non-alcoholic HORECA beverage value.
Carbonated Soft Drinks
Carbonated Soft Drinks account for approximately USD 66.76 billion in 2026, making them the largest named non-alcoholic segment in the current KSI structure. Fountain systems, meal combinations and national restaurant contracts provide a large recurring volume base. The segment reaches approximately USD 78.36 billion by 2031 but falls from about 36% to 34% of non-alcoholic value as other categories grow faster.
Fruit Juice
Fruit Juice is estimated at approximately USD 29.67 billion in 2026 and is concentrated in breakfast service, hotels, cafés and catering. The category faces competition from bottled water, carbonated drinks and other refreshment formats and therefore records slower growth than the broader non-alcoholic segment. KSI projects market value of approximately USD 32.27 billion by 2031, reducing its share from about 16% to 14% of non-alcoholic HORECA beverages.
Milk
Milk is estimated at approximately USD 37.09 billion in 2026 within the current KSI segmentation. Demand includes direct service as well as beverage preparation across hotels, cafés and restaurant breakfast formats. The segment is projected to reach approximately USD 52.99 billion by 2031 and increase from around 20% to 23% of non-alcoholic value, reflecting its use across multiple prepared beverage and breakfast occasions.
By End-User
Hotels
Hotels account for approximately USD 91.09 billion, or 28% of market value, in 2026. Beverage demand extends across restaurants, bars, banquets, conferences, lounges, room service and other guest facilities, giving hotels a broader consumption profile than a single foodservice outlet. The segment is projected to reach approximately USD 113.29 billion by 2031 and increase to around 29% of market value as tourism and premium hospitality spending expand.
Restaurants
Restaurants account for approximately USD 169.17 billion, or 52% of market value, in 2026 and remain the largest HORECA beverage end-user. The channel combines high transaction frequency with a broad product mix, including carbonated soft drinks, bottled water, beer, wine, spirits, juice and milk-based beverages. National and international chains also support large supply agreements and standardized dispensing programs. Market value is projected to reach approximately USD 199.23 billion by 2031, with share easing only slightly to around 51%.
Cafe
Cafe accounts for approximately USD 65.07 billion, or 20% of market value, in 2026 under the existing KSI segmentation. The channel is driven by beverage-led visits and therefore carries a higher beverage intensity per transaction than many restaurant formats, although the formal KSI type segmentation does not separately quantify coffee and tea. The segment is projected to reach approximately USD 78.13 billion by 2031 and retain around one-fifth of global HORECA beverage value.
Geographical Outlook
Asia Pacific
Asia Pacific accounts for approximately USD 100.85 billion, or 31% of global market value, in 2026 and is projected to reach USD 128.91 billion by 2031. China, India, Japan and South Korea provide large restaurant and hospitality markets, while Southeast Asia adds tourism-led demand across hotels and foodservice. The region increases its global share to approximately 33% as organized foodservice, travel and beverage distribution expand faster than in North America and Europe.
Europe
Europe represents approximately USD 84.59 billion, or 26% of global market value, in 2026. Mature restaurant, hotel, café and alcohol-serving channels provide a broad demand base, while tourism supports seasonal consumption in major destination markets. Growth remains positive but below the global average, reducing regional share to approximately 25% by 2031 as faster expansion occurs in Asia Pacific.
North America
North America accounts for approximately USD 81.33 billion, or 25% of market value, in 2026. The United States provides a large organized restaurant and foodservice base, with extensive fountain, cooler and national-account infrastructure supporting major beverage suppliers. The market reaches approximately USD 93.76 billion by 2031, while its global share moderates to around 24% because the channel is comparatively mature.
Middle East and Africa
Middle East and Africa accounts for approximately USD 32.53 billion, or 10% of market value, in 2026. Gulf hospitality and tourism investment supports premium hotel and restaurant demand, while alcohol restrictions in several markets increase the importance of non-alcoholic beverages. The regional market is projected to reach approximately USD 39.07 billion by 2031 and retain around 10% of global value.
South America
South America accounts for approximately USD 26.03 billion, or 8% of the market, in 2026, with Brazil representing the largest regional demand base. Restaurants, beer, soft drinks and hotel activity support consumption, while macroeconomic and currency volatility can affect pricing and discretionary spending. The market reaches approximately USD 31.25 billion by 2031 and maintains about 8% of global value.
Recent Developments
August 2026 - Carlsberg: Carlsberg reported 11% organic growth in alcohol-free brews and 9% growth in soft drinks during H1 2026, compared with 1% growth in premium beer. The result indicates that portfolio growth is increasingly being generated outside conventional beer and is relevant to hotel, restaurant and event beverage menus.
June 2026 - PepsiCo: PepsiCo launched House of Treats for Away From Home channels, targeting restaurants, cinemas, stadiums and live events. The platform combines customization with high service speed and extends supplier competition beyond standard fountain products.
June 2026 - Starbucks: Starbucks introduced Protein Cold Foam across several Asia Pacific markets, including India and Australia. The development shows that café operators continue to add functional attributes to established beverage formats, although coffee and tea remain outside the formal quantitative subsegments of the current KSI HORECA structure.
May 2026 - The Coca-Cola Company: Coca-Cola introduced its next generation of beverage dispensing technology, including Freestyle Mini and a non-alcoholic mixology dispenser. The equipment is designed for bars, cafés and compact venues and increases the role of connected dispensing in foodservice account strategy.
February 2026 - Heineken: Heineken expanded its 0.0 portfolio with Cold Pressed Lime and Nectarine Juniper. The products are positioned for social occasions including bars and support broader on-premise choice for customers moderating alcohol intake.
2025-2026 - Coca-Cola Europacific Partners: Coca-Cola Europacific Partners reported more than 75,000 cooler placements in Europe during 2025 and continued to prioritize away-from-home execution in 2026. The investment supports cold availability and strengthens account-level competition across foodservice outlets.
Competitive Environment
Competition in the HORECA beverage market is divided across non-alcoholic beverage companies, brewers, spirits groups and diversified food-and-beverage suppliers. Coca-Cola and PepsiCo hold strong positions in fountain systems, equipment and restaurant accounts, while Nestlé, Keurig Dr Pepper and Danone compete across selected non-alcoholic categories. Red Bull and Monster provide additional strength in energy beverages, particularly in entertainment, leisure and convenience-oriented foodservice channels.
Beer competition is led by AB InBev, Heineken, Carlsberg, Molson Coors, Asahi, Kirin and regional brewers, while Diageo, Pernod Ricard, Bacardi, Brown-Forman, Suntory and Constellation Brands compete across spirits and premium on-premise occasions. Supplier scale remains important, but account servicing, route-to-market coverage, equipment support and product breadth determine how effectively that scale converts into HORECA revenue.
The market therefore favors companies that can combine branded beverages with refrigeration, dispensing, maintenance, promotions and national-account management. Smaller brands can gain placement through differentiated products, but they often depend more heavily on wholesalers and specialist distributors to achieve the same outlet coverage.
HORECA Beverage Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 325.3 billion |
| Total Market Size in 2031 | USD 390.7 billion |
| Forecast Unit | Billion |
| Growth Rate | 3.7% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, End-User, Geography |
| Companies |
|
Market Segmentation
By Type
Alcoholic Beverage
Beer/Malt
Wine
Spirits
Non-Alcoholic Beverage
Bottled Water
Carbonated Soft Drinks
Fruit Juice
Milk
By End-User
Hotels
Restaurants
Cafe
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
Japan
India
South Korea
Taiwan
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Expansion of Foodservice and Tourism Activity
3.1.2. Investment in Away-From-Home Distribution and Equipment
3.1.3. Adoption of More Flexible Foodservice Dispensing Systems
3.1.4. Expansion of Alcohol-Free Products in On-Premise Channels
3.1.5. Premiumization of Spirits and Higher-Value Beverage Menus
3.2. Market Restraints
3.2.1. Commodity, Packaging and Energy Cost Pressure
3.2.2. Purchasing Power of Large Foodservice Accounts
3.2.3. Packaging Reuse and Waste-Management Requirements
3.2.4. Fragmented Distribution Across Independent HORECA Outlets
3.2.5. Alcohol Taxation, Licensing and Serving Restrictions
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL ADVANCEMENTS
4.1. Connected Beverage Dispensing Systems
4.2. Compact Foodservice Dispensing Equipment
4.3. Fountain Customization and Mixology Platforms
4.4. Cooler and Refrigeration Monitoring
4.5. Foodservice Equipment Data and Analytics
5. GLOBAL HORECA BEVERAGE MARKET BY TYPE
5.1. Introduction
5.2. Alcoholic Beverage
5.2.1. Beer/Malt
5.2.2. Wine
5.2.3. Spirits
5.3. Non-Alcoholic Beverage
5.3.1. Bottled Water
5.3.2. Carbonated Soft Drinks
5.3.3. Fruit Juice
5.3.4. Milk
6. GLOBAL HORECA BEVERAGE MARKET BY END-USER
6.1. Introduction
6.2. Hotels
6.3. Restaurants
6.4. Cafe
7. GLOBAL HORECA BEVERAGE MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. By Type
7.2.2. By End-User
7.2.3. By Country
7.2.3.1. USA
7.2.3.2. Canada
7.2.3.3. Mexico
7.3. South America
7.3.1. By Type
7.3.2. By End-User
7.3.3. By Country
7.3.3.1. Brazil
7.3.3.2. Argentina
7.3.3.3. Others
7.4. Europe
7.4.1. By Type
7.4.2. By End-User
7.4.3. By Country
7.4.3.1. United Kingdom
7.4.3.2. Germany
7.4.3.3. France
7.4.3.4. Spain
7.4.3.5. Others
7.5. Middle East and Africa
7.5.1. By Type
7.5.2. By End-User
7.5.3. By Country
7.5.3.1. Saudi Arabia
7.5.3.2. UAE
7.5.3.3. Others
7.6. Asia Pacific
7.6.1. By Type
7.6.2. By End-User
7.6.3. By Country
7.6.3.1. China
7.6.3.2. Japan
7.6.3.3. India
7.6.3.4. South Korea
7.6.3.5. Taiwan
7.6.3.6. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. The Coca-Cola Company
9.2. PepsiCo, Inc.
9.3. Nestlé S.A.
9.4. Keurig Dr Pepper Inc.
9.5. Danone S.A.
9.6. Red Bull GmbH
9.7. Monster Beverage Corporation
9.8. Anheuser-Busch InBev SA/NV
9.9. Heineken N.V.
9.10. Carlsberg A/S
9.11. Molson Coors Beverage Company
9.12. Asahi Group Holdings, Ltd.
9.13. Kirin Holdings Company, Limited
9.14. Diageo plc
9.15. Pernod Ricard SA
9.16. Bacardi Limited
9.17. Brown-Forman Corporation
9.18. Suntory Holdings Limited
9.19. Constellation Brands, Inc.
9.20. United Breweries Limited
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key Benefits for Stakeholders
10.5. Research Methodology
10.6. Abbreviations
Navigate
Trusted by the world's leading organizations











