
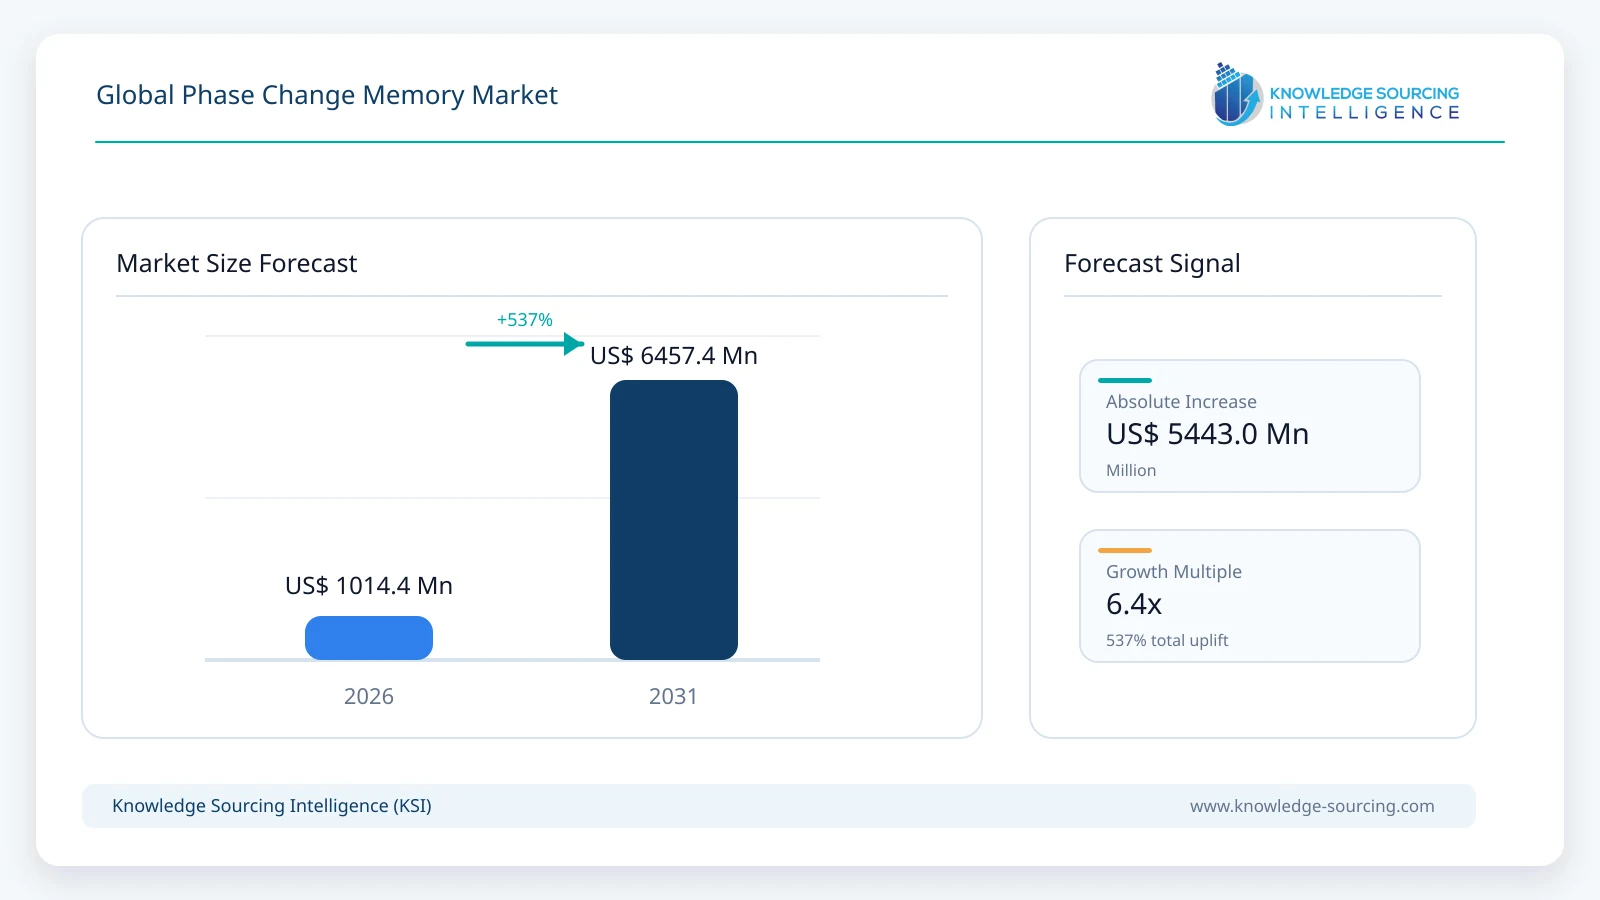
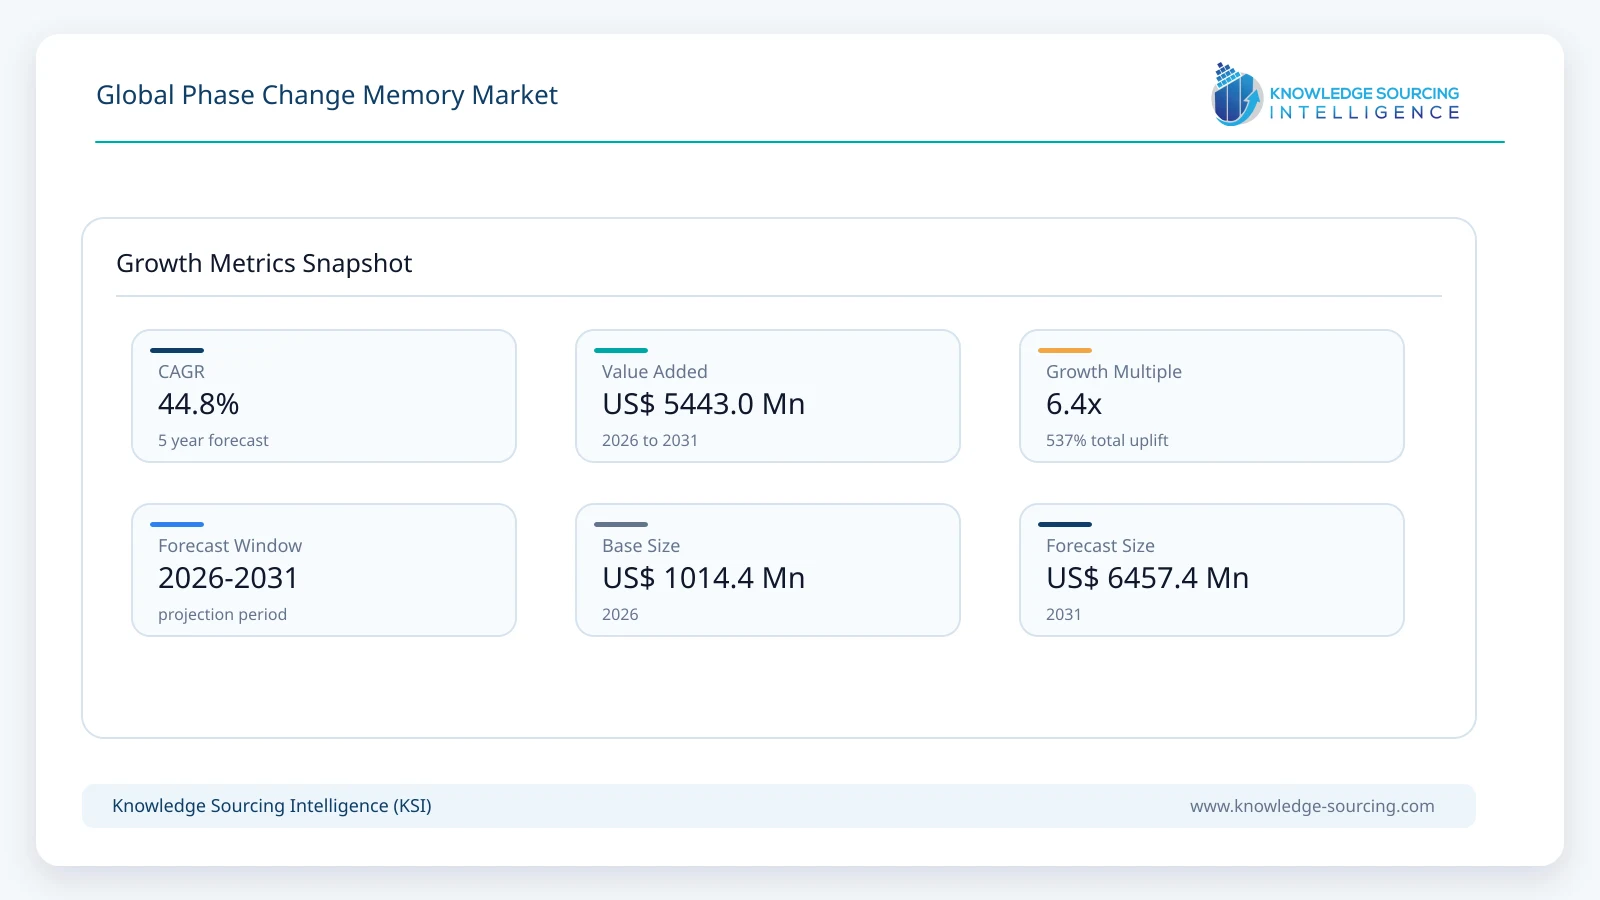
The Phase Change Memory Market is forecast to grow at a CAGR of 44.80%, reaching USD 6,457.35 million in 2031 from USD 1,014.40 million in 2026.
Highlights:
- 1Rising AI computing and high-performance enterprise workloads are strengthening demand for persistent memory technologies.
- 2Enterprise storage and data centre applications represent one of the most commercially attractive application segments.
- 3Asia Pacific remains a major manufacturing and innovation hub owing to its semiconductor ecosystem.
- 4Embedded Phase Change Memory (ePCM) is gaining wider adoption in automotive microcontrollers and industrial electronics.
- 5Government semiconductor manufacturing incentives are encouraging investment in advanced memory technologies.
- 6Competition is increasingly centred on fabrication expertise, intellectual property portfolios, and system integration capabilities.
The Phase Change Memory (PCM) market represents a specialised segment of the non-volatile memory industry focused on memory devices that store information by altering the physical state of chalcogenide materials between amorphous and crystalline phases. Unlike conventional flash memory, PCM offers low latency, high write endurance, non-volatility, and the potential to bridge the performance gap between DRAM and NAND flash. These characteristics have positioned PCM as an attractive technology for applications requiring persistent memory, fast data access, and reliable operation under intensive workloads.
Commercial interest in PCM is driven by industries that demand higher memory bandwidth and lower latency while reducing energy consumption. Enterprise data centres, automotive electronics, industrial automation systems, artificial intelligence (AI) accelerators, edge computing platforms, aerospace electronics, and advanced consumer devices increasingly require memory architectures capable of supporting data-intensive computing. Although flash memory continues to dominate mass storage applications, PCM is attracting attention for specialised workloads where endurance and speed outweigh cost considerations.
Purchasing decisions are strongly influenced by system-level performance rather than component pricing alone. Original equipment manufacturers (OEMs), semiconductor manufacturers, cloud infrastructure providers, automotive suppliers, and industrial equipment developers evaluate PCM based on endurance, retention characteristics, compatibility with existing architectures, manufacturing scalability, and long-term supply availability. Buyers also consider software ecosystem support and controller compatibility before adopting PCM-based solutions.
The industry structure remains relatively concentrated due to the high technical barriers associated with material science, semiconductor fabrication, intellectual property, and process integration. Commercial development requires extensive investment in fabrication facilities, memory controller design, and advanced packaging technologies. Consequently, competition is centred on technological differentiation, manufacturing capability, and strategic partnerships rather than volume production alone.
Growing investments in artificial intelligence infrastructure, autonomous vehicles, industrial automation, and edge computing continue to expand the addressable market for advanced memory technologies. While widespread replacement of NAND flash remains unlikely during the forecast period, PCM is expected to strengthen its position in niche applications where deterministic performance, endurance, and low power consumption provide measurable operational advantages.
Market Drivers
Expansion of AI Infrastructure and High-Performance Computing
Artificial intelligence training and inference workloads require memory solutions capable of handling continuous data transfers with minimal latency. Conventional memory hierarchies often struggle to balance speed, endurance, and persistence, creating opportunities for PCM technologies. Cloud operators, enterprise server manufacturers, and AI hardware developers are investing in advanced memory architectures that reduce bottlenecks between processors and storage devices.
Semiconductor suppliers are responding through improved memory integration, controller optimisation, and closer collaboration with processor manufacturers. These developments support higher-value product offerings while strengthening long-term customer relationships.
Growth of Automotive Electronics
Modern vehicles incorporate increasing numbers of electronic control units supporting advanced driver assistance systems, digital cockpits, battery management systems, and autonomous driving functions. These applications require non-volatile memory capable of maintaining data integrity under wide temperature ranges and demanding operating conditions.
Automotive manufacturers prioritise reliability, endurance, functional safety, and long product lifecycles. Embedded PCM addresses many of these requirements, encouraging semiconductor suppliers to integrate the technology into automotive microcontrollers and system-on-chip devices.
Industrial Automation and Edge Computing Deployment
Industrial digitalisation has increased demand for memory devices that provide dependable operation under continuous workloads. Factory automation, robotics, industrial gateways, and edge computing platforms generate large volumes of operational data requiring persistent, low-latency storage.
Industrial equipment manufacturers increasingly value memory technologies that minimise downtime and extend product lifecycles. PCM's endurance characteristics reduce maintenance requirements while supporting real-time industrial applications.
Increasing Semiconductor R&D Investment
Advanced memory technologies depend on continuous improvements in materials engineering, lithography, process integration, and device architecture. Governments across North America, Europe, and Asia have expanded semiconductor investment programmes to strengthen domestic manufacturing capabilities.
This investment environment supports collaboration between semiconductor manufacturers, research institutions, and equipment suppliers, accelerating commercial development of next-generation PCM products.
Market Restraints and Challenges
High Manufacturing Costs
PCM fabrication requires specialised materials, complex process integration, and advanced manufacturing equipment. Production costs remain considerably higher than mature NAND flash technologies, limiting broader commercial adoption.
System designers frequently reserve PCM for premium applications where performance advantages justify additional expenditure. Manufacturers continue pursuing process optimisation and higher production yields to improve cost competitiveness.
Competition from Alternative Memory Technologies
The market faces competition from MRAM, ReRAM, advanced NAND flash, and evolving DRAM technologies. Buyers often compare multiple emerging memory solutions before selecting a platform.
This competitive landscape increases research expenditure while extending customer qualification cycles. Suppliers differentiate through endurance performance, integration flexibility, and software compatibility.
Software and System Integration Complexity
Introducing new persistent memory technologies frequently requires modifications to firmware, operating systems, storage controllers, and application software. Organisations may delay deployment until compatibility risks are addressed.
Technology vendors increasingly collaborate with software developers and processor manufacturers to simplify deployment and reduce customer implementation costs.
Limited Commercial Scale
Although technical progress continues, PCM production volumes remain relatively limited compared with mainstream memory technologies. Smaller production volumes restrict economies of scale and influence pricing.
Long-term commercial success depends on expanding manufacturing capacity while maintaining consistent quality and supply reliability.
Major Segment Analysis
Enterprise Storage & Data Centres
Enterprise storage and data centre applications represent one of the most commercially significant opportunities for Phase Change Memory. Modern data centres support artificial intelligence, cloud computing, virtualisation, financial services, and large-scale analytics, all of which generate demanding memory workloads requiring rapid data access and high endurance.
Procurement decisions within enterprise infrastructure increasingly prioritise total cost of ownership rather than component cost alone. Data centre operators evaluate energy efficiency, latency reduction, system reliability, and maintenance requirements before selecting memory technologies. PCM's ability to provide persistent storage with near-memory performance supports workload acceleration while reducing recovery times following power interruptions.
Competition within this segment extends beyond semiconductor performance. Suppliers differentiate through ecosystem compatibility, firmware optimisation, enterprise qualification, security features, and long-term product support. Collaboration with processor manufacturers, storage vendors, and cloud infrastructure providers has become increasingly important for commercial success.
Revenue opportunities are strongest in premium enterprise deployments where performance improvements generate measurable operational savings. Although deployment volumes remain below mainstream flash storage, higher average selling prices contribute positively to supplier profitability.
Regional Analysis
North America
North America remains an important centre for PCM research, semiconductor innovation, and enterprise technology adoption. Strong investment in artificial intelligence infrastructure, cloud computing, defence electronics, and advanced semiconductor manufacturing supports commercial demand. Government semiconductor initiatives and substantial private investment encourage continued technology development, although manufacturing costs remain comparatively high.
Europe
European demand is supported by automotive electronics, industrial automation, aerospace, and research-intensive semiconductor programmes. Regional policies promoting semiconductor resilience and technological sovereignty encourage investment in advanced memory capabilities. Automotive suppliers continue evaluating embedded PCM solutions for safety-critical electronic systems.
Asia Pacific
Asia Pacific represents the largest manufacturing base for advanced semiconductor memory technologies. Countries including China, Japan, South Korea, Taiwan, and India continue expanding semiconductor fabrication capacity, research programmes, and electronics manufacturing. Strong consumer electronics production, automotive manufacturing, and government semiconductor incentives reinforce regional demand. Supply chain concentration, however, also exposes manufacturers to geopolitical and trade-related uncertainties.
Middle East & Africa
Demand remains comparatively modest but continues expanding through digital infrastructure projects, industrial diversification, and smart city investments. Procurement is primarily driven by enterprise infrastructure, telecommunications, and government digital initiatives. Limited domestic semiconductor manufacturing constrains regional supply capabilities.
South America
South American adoption remains concentrated in enterprise IT infrastructure, industrial automation, and selected automotive manufacturing activities. Budget limitations and reliance on imported semiconductor products influence purchasing decisions. Nevertheless, ongoing digital infrastructure investment supports gradual adoption of advanced memory technologies.
Competitive Landscape
The Phase Change Memory market is characterised by a concentrated competitive structure where technological capability outweighs manufacturing scale alone. Companies including Micron Technology, Inc., IBM Corporation, Samsung Electronics Co., Ltd., SK hynix Inc., STMicroelectronics N.V., Intel Corporation, Macronix International Co., Ltd., and Renesas Electronics Corporation compete through proprietary material technologies, fabrication expertise, embedded memory integration, patent portfolios, and strategic collaborations.
Competition increasingly focuses on integrating PCM into broader semiconductor platforms rather than offering standalone memory devices. Product differentiation is achieved through endurance improvements, power efficiency, process compatibility, controller optimisation, and application-specific solutions targeting automotive, industrial, and enterprise customers. Geographic manufacturing diversification, long-term customer partnerships, and sustained research investment remain essential competitive strategies.
Recent Developments
February 2026: Micron Technology announced continued investment in advanced memory manufacturing and technology development through its capital expenditure programme. The investment supports future commercialisation of advanced non-volatile memory platforms.
June 2025: Samsung Electronics highlighted continued investment in advanced memory technologies for AI computing and high-performance systems during investor communications. This supports broader development of future memory architectures relevant to enterprise infrastructure.
April 2025: STMicroelectronics expanded its embedded non-volatile memory research programmes supporting next-generation automotive microcontrollers. The initiative strengthens long-term embedded memory development for vehicle electronics.
Regulatory and Policy Environment
Government semiconductor policies are becoming increasingly influential in shaping investment decisions across the PCM industry. Programmes supporting domestic semiconductor manufacturing, research funding, and supply chain resilience encourage expansion of advanced memory development capabilities.
Compliance requirements extend beyond semiconductor manufacturing standards to include automotive functional safety certifications, aerospace quality management systems, environmental regulations governing hazardous materials, and cybersecurity requirements for critical infrastructure applications. International standards covering electronic reliability, quality assurance, and semiconductor manufacturing continue influencing supplier qualification processes.
Export controls affecting advanced semiconductor technologies and manufacturing equipment also influence global supply chain planning. Companies increasingly diversify manufacturing locations and strengthen supplier networks to reduce geopolitical exposure while maintaining customer delivery commitments.
Outlook and Strategic Implications
The commercial outlook for the Phase Change Memory market will depend on its ability to address specialised performance requirements rather than compete directly with established flash memory technologies on cost. Demand is expected to remain strongest in enterprise computing, artificial intelligence infrastructure, automotive electronics, industrial automation, and edge computing environments where endurance, persistence, and low latency generate measurable operational value.
Investment priorities are likely to concentrate on advanced fabrication processes, embedded memory integration, packaging innovation, and software ecosystem compatibility. Procurement strategies among enterprise customers will increasingly emphasise lifecycle economics, system reliability, and infrastructure efficiency rather than initial acquisition costs.
Competitive positioning will depend on sustained research investment, manufacturing scalability, ecosystem partnerships, and intellectual property development. Companies capable of integrating PCM into broader semiconductor platforms while maintaining production efficiency are expected to strengthen their commercial position over the next five years.
Despite ongoing competition from alternative emerging memory technologies and persistent manufacturing cost challenges, PCM remains strategically important within the broader evolution of next-generation memory architectures. Continued advances in semiconductor materials, AI computing infrastructure, and automotive electronics are expected to create commercially attractive opportunities for suppliers capable of delivering highly reliable, application-specific memory solutions.
Phase Change Memory Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1,014.40 million |
| Total Market Size in 2031 | USD 6,457.35 million |
| Forecast Unit | Million |
| Growth Rate | 44.80% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Application, Geography |
| Companies |
|
Market Segmentation
By Type
By Application
By Geography
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. GLOBAL PHASE CHANGE MEMORY MARKET BY TYPE
5.1. Introduction
5.2. Standalone Phase Change Memory (PCM)
5.3. Embedded Phase Change Memory (ePCM)
5.4. Storage-Class Memory (SCM)
5.5. Other Phase Change Memory Technologies
6. GLOBAL PHASE CHANGE MEMORY MARKET BY APPLICATION
6.1. Introduction
6.2. Consumer Electronics
6.3. Automotive
6.4. Enterprise Storage & Data Centers
6.5. Industrial
6.6. Healthcare
6.7. Aerospace & Defence
6.8. Others
7. GLOBAL PHASE CHANGE MEMORY MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. By Type
7.2.2. By Application
7.2.3. By Country
7.2.3.1. United States
7.2.3.2. Canada
7.2.3.3. Mexico
7.3. South America
7.3.1. By Type
7.3.2. By Application
7.3.3. By Country
7.3.3.1. Brazil
7.3.3.2. Argentina
7.3.3.3. Others
7.4. Europe
7.4.1. By Type
7.4.2. By Application
7.4.3. By Country
7.4.3.1. Germany
7.4.3.2. United Kingdom
7.4.3.3. France
7.4.3.4. Italy
7.4.3.5. Spain
7.4.3.6. Others
7.5. Middle East and Africa
7.5.1. By Type
7.5.2. By Application
7.5.3. By Country
7.5.3.1. Saudi Arabia
7.5.3.2. United Arab Emirates
7.5.3.3. South Africa
7.5.3.4. Others
7.6. Asia Pacific
7.6.1. By Type
7.6.2. By Application
7.6.3. By Country
7.6.3.1. China
7.6.3.2. Japan
7.6.3.3. South Korea
7.6.3.4. India
7.6.3.5. Taiwan
7.6.3.6. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Micron Technology, Inc.
9.2. IBM Corporation
9.3. Samsung Electronics Co., Ltd.
9.4. SK hynix Inc.
9.5. STMicroelectronics N.V.
9.6. Intel Corporation
9.7. Macronix International Co., Ltd.
9.8. Renesas Electronics Corporation
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key Benefits for Stakeholders
10.5. Research Methodology
10.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES
Navigate
Trusted by the world's leading organizations











