
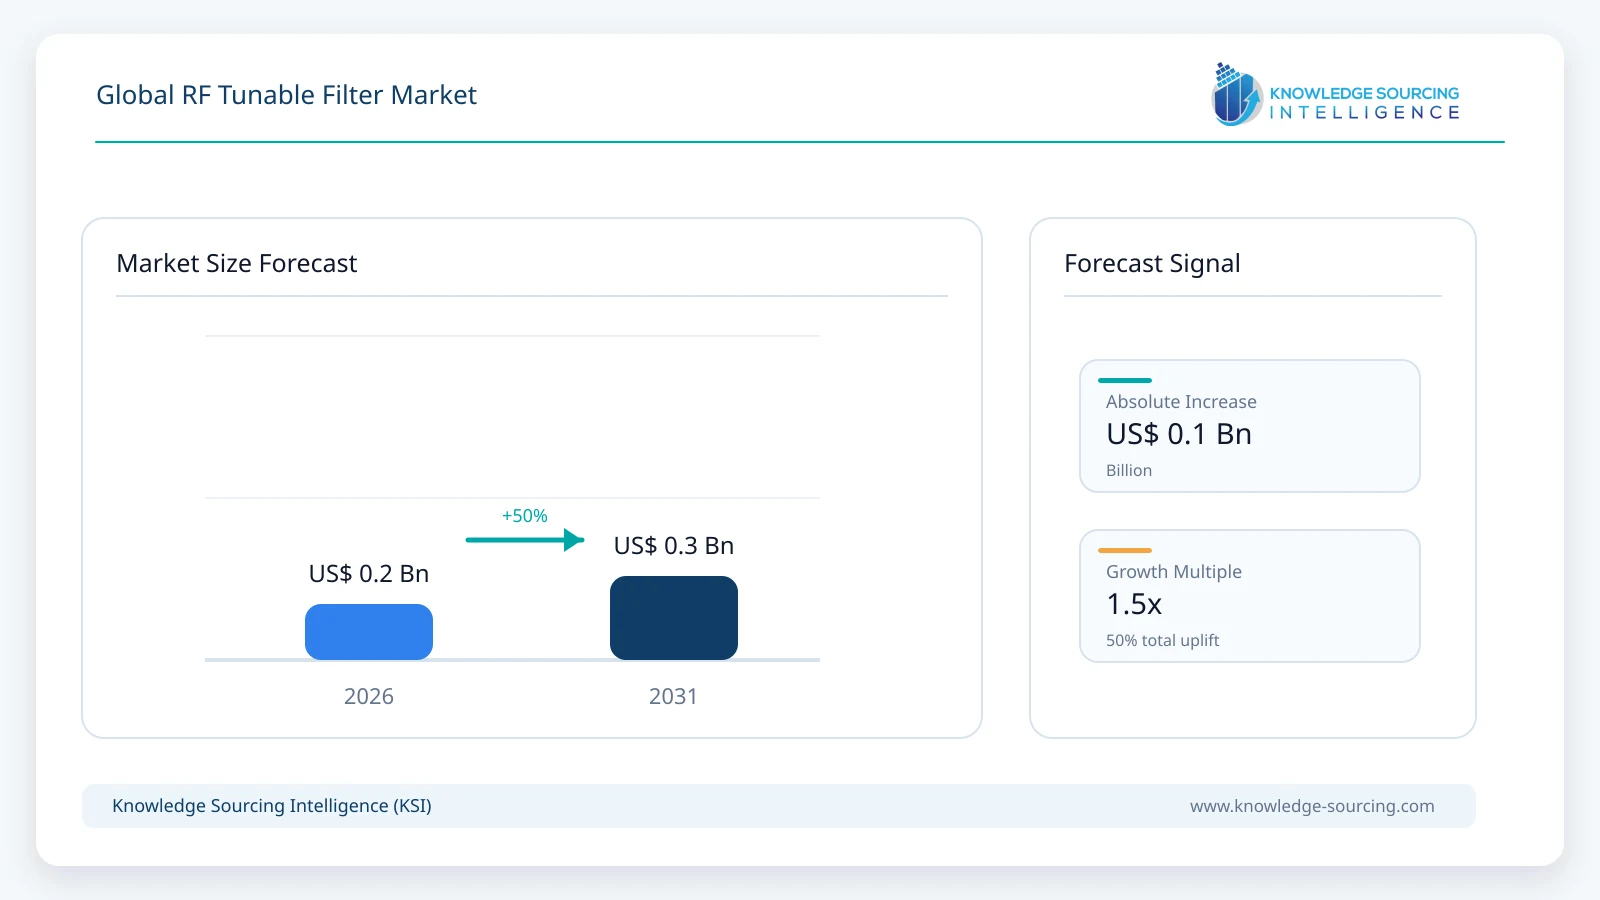
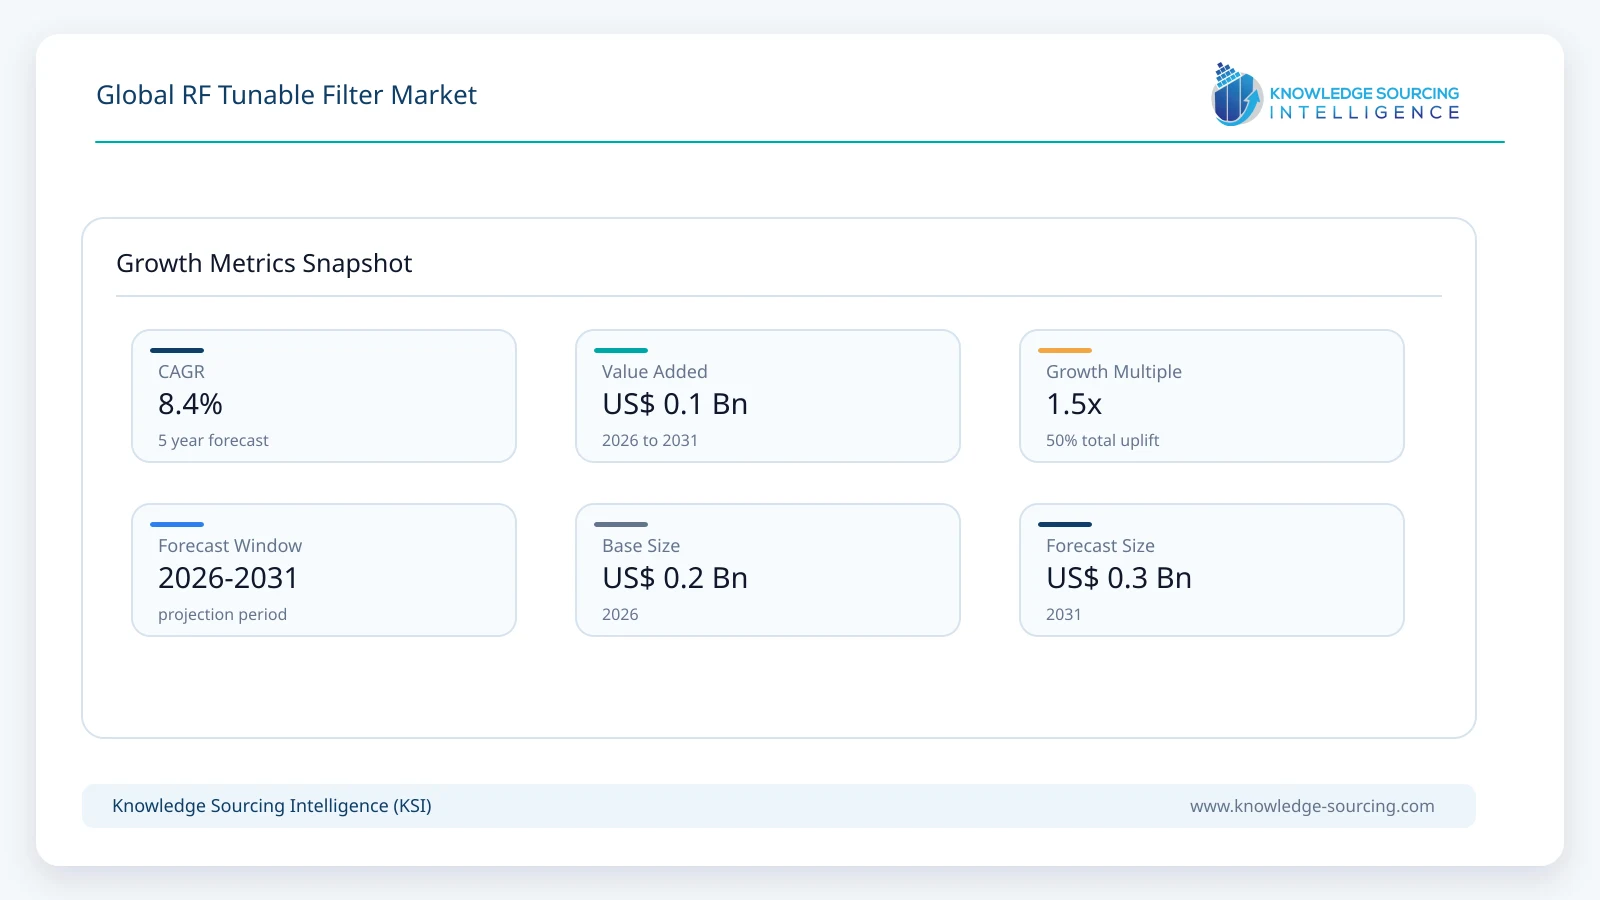
The Global RF Tunable Filter market is forecast to grow at a CAGR of 8.45%, reaching USD 0.3 billion in 2031 from USD 0.2 billion in 2026.
Highlights:
- 1Growing deployment of software-defined radio platforms is strengthening demand for electronically tunable RF filtering solutions.
- 2Wireless communication infrastructure remains one of the most commercially important application segments due to multi-band network deployment.
- 3Asia Pacific represents a major manufacturing and deployment hub supported by telecommunications investment and semiconductor production capacity.
- 4Electronic tuning technologies continue gaining preference because of faster switching speeds and easier system integration.
- 5Government spectrum management policies and defense modernization programs are expanding procurement opportunities for frequency-agile RF components.
- 6Competition increasingly depends on RF performance, integration capability, reliability qualifications, and long-term customer relationships.
The RF tunable filter market represents a specialized segment of the radio frequency (RF) component industry that enables dynamic frequency selection across changing operating bands without requiring hardware replacement. Unlike fixed-frequency filters, tunable filters allow communication equipment, radar platforms, satellite terminals, and test systems to adapt to varying spectrum conditions through adjustable passband characteristics. This capability has become commercially important as wireless networks operate across a wider range of licensed and shared frequency bands while defense and aerospace users require flexible spectrum management in complex electromagnetic environments.
Demand is primarily supported by the expansion of multi-band wireless infrastructure, software-defined radio (SDR) architectures, electronically scanned radar systems, satellite communication terminals, and advanced electronic warfare platforms. Telecommunications equipment manufacturers, defense contractors, aerospace integrators, semiconductor suppliers, and laboratory equipment providers represent the principal buyers. Purchasing decisions increasingly emphasize insertion loss, tuning range, switching speed, linearity, power handling capability, reliability, and compatibility with compact RF front-end architectures rather than simply component cost.
The industry structure combines RF semiconductor manufacturers, passive component specialists, microwave subsystem suppliers, and high-frequency engineering companies. Product development depends heavily on expertise in materials science, microwave circuit design, MEMS technologies, ferroelectric materials, and semiconductor integration. Because RF tunable filters are frequently incorporated into mission-critical communication systems, procurement cycles typically involve extensive qualification, environmental testing, and long-term supply agreements.
Commercial demand is also influenced by the global transition toward spectrum-efficient communications. Network operators continue deploying infrastructure capable of supporting multiple frequency allocations, while governments allocate additional spectrum for commercial broadband, satellite communications, and defense modernization. This creates sustained requirements for RF filtering solutions capable of adapting to changing operating frequencies without increasing system complexity.
Technology adoption varies by application. Defense and aerospace organizations prioritize electronic tuning for radar and secure communication systems requiring rapid frequency agility. Telecommunications infrastructure increasingly adopts tunable filtering to simplify equipment supporting multiple regional frequency bands. Test and measurement equipment manufacturers utilize tunable filters to improve laboratory flexibility, while satellite communication systems benefit from adaptable filtering as operators expand services across diverse frequency allocations.
From a revenue perspective, high-performance filters designed for defense, aerospace, and satellite applications command premium pricing due to demanding technical specifications, stringent certification requirements, and relatively lower production volumes. Consumer electronics and telecommunications generate larger shipment volumes but require cost optimization and manufacturing scalability.
Market Drivers
The expansion of software-defined radio platforms continues to reshape procurement requirements across military, public safety, and commercial communication systems. SDR architectures are designed to support multiple communication standards through software updates rather than hardware replacement. This operating model requires RF front-end components capable of adapting to changing frequency bands while maintaining signal integrity. Equipment manufacturers therefore seek tunable filters that reduce hardware complexity and improve platform flexibility, encouraging suppliers to develop wider tuning ranges with lower insertion losses.
Ongoing investment in advanced radar systems is creating another important source of demand. Modern radar platforms operate across multiple frequencies to improve target detection, electronic countermeasure resistance, and mission adaptability. Defense procurement agencies increasingly specify frequency-agile RF components during system acquisition. Component manufacturers respond by introducing electronically controlled filters capable of supporting rapid frequency transitions under demanding environmental conditions. These technical requirements support higher average selling prices and longer product qualification cycles.
Wireless communication infrastructure is becoming more complex as operators deploy equipment supporting multiple spectrum allocations and evolving network standards. Base station manufacturers seek solutions that minimize the number of dedicated RF chains while maintaining network performance. Tunable filters provide operational flexibility by enabling equipment to support different regional spectrum allocations, reducing inventory complexity and simplifying infrastructure deployment across global markets.
Growth in satellite communication services also contributes to market expansion. Commercial broadband constellations, government satellite programs, and mobile satellite communication providers require RF filtering technologies capable of supporting diverse frequency bands and changing operational conditions. Procurement increasingly favors compact, lightweight, and highly reliable RF components capable of maintaining stable performance throughout extended operational lifecycles.
Market Restraints and Challenges
High engineering complexity remains a primary challenge for manufacturers. Achieving broad tuning ranges while maintaining low insertion loss, high selectivity, and thermal stability requires advanced design capabilities and specialized manufacturing processes. These technical demands increase research expenditure and lengthen product development timelines, creating barriers for new market entrants.
Qualification requirements within aerospace and defense applications extend commercialization schedules. Military communication systems, avionics, and space platforms require extensive environmental, electromagnetic compatibility, and reliability testing before component approval. Suppliers must invest considerable resources in certification activities, delaying revenue realization despite strong long-term demand.
Supply chain concentration for specialized semiconductor materials, microwave substrates, and precision manufacturing equipment also affects production planning. Long procurement lead times and limited qualified suppliers increase inventory costs while exposing manufacturers to disruptions that may delay customer deliveries and project execution.
Price sensitivity within commercial telecommunications and consumer electronics markets presents an additional constraint. Network equipment manufacturers seek high RF performance while simultaneously reducing hardware costs. Suppliers must therefore balance advanced functionality with manufacturing efficiency, making production scale and process optimization increasingly important competitive factors.
Major Segment Analysis
Wireless Communication Infrastructure
Wireless communication infrastructure represents one of the most commercially influential application segments for RF tunable filters because network equipment must support expanding spectrum allocations while maintaining high signal quality and operational efficiency. Base stations, distributed antenna systems, small cells, and private wireless networks increasingly require adaptable RF front-end architectures capable of accommodating multiple frequency bands within compact hardware platforms.
Network equipment manufacturers prioritize filters that combine broad tuning capability with low insertion loss, high power handling, and excellent linearity. These characteristics directly influence network coverage, energy efficiency, and service quality. Procurement decisions also consider long-term reliability because infrastructure equipment is expected to remain operational for many years under continuous service conditions.
Competition within this segment extends beyond RF performance alone. Equipment vendors seek suppliers capable of supporting global product launches through consistent manufacturing quality, application engineering support, and long-term production capacity. Vendors offering integrated RF solutions alongside tunable filtering technologies can strengthen customer relationships by simplifying system-level design and reducing component integration challenges.
Commercially, this segment generates recurring revenue opportunities as mobile operators continue expanding network capacity, modernizing legacy infrastructure, and supporting new spectrum allocations. Continued investment in private wireless networks for industrial facilities, transportation infrastructure, and enterprise campuses further broadens the customer base for tunable RF filtering solutions.
Regional Analysis
North America maintains a strong position due to sustained investment in aerospace, defense electronics, satellite communications, and advanced wireless infrastructure. Government-funded modernization programs support procurement of frequency-agile communication systems, while established semiconductor companies and defense contractors contribute to ongoing technology development. High research expenditure strengthens innovation, although stringent qualification requirements can extend commercialization timelines.
Europe benefits from a diversified industrial base spanning telecommunications equipment, aerospace manufacturing, automotive electronics, and research institutions. Regional regulatory emphasis on efficient spectrum utilization encourages deployment of adaptable RF technologies. Defense collaboration among European countries also supports procurement of advanced communication and radar systems, although budget cycles may influence purchasing patterns.
Asia Pacific represents the largest manufacturing ecosystem for electronic components while simultaneously accounting for substantial telecommunications infrastructure investment. China, Japan, South Korea, Taiwan, and India continue expanding wireless connectivity and semiconductor production capabilities. Regional demand is supported by network equipment manufacturing, consumer electronics production, satellite initiatives, and increasing investment in indigenous defense technologies. Competitive manufacturing costs also encourage production expansion within the region.
The Middle East and Africa generate demand primarily through telecommunications network expansion, defense procurement, and satellite communication investments. Gulf countries continue investing in secure communication infrastructure and advanced radar capabilities, while broader regional adoption remains influenced by infrastructure development priorities and government capital expenditure.
South America presents selective opportunities supported by telecommunications modernization and public-sector communication projects. Demand remains concentrated in larger economies where mobile network investment and industrial communication requirements justify adoption of advanced RF technologies. Budget constraints and dependence on imported high-frequency components continue limiting broader regional expansion.
Competitive Landscape
Competition within the RF tunable filter market is characterized by technological specialization rather than volume manufacturing alone. Analog Devices, Inc., Skyworks Solutions, Inc., Qorvo, Inc., Murata Manufacturing Co., Ltd., Broadcom Inc., TDK Corporation, Smiths Interconnect (Smiths Group plc), and CTS Corporation compete through RF performance, integration capability, manufacturing quality, and application-specific engineering expertise.
Product differentiation centers on tuning range, insertion loss, power handling, switching speed, frequency stability, environmental reliability, and compatibility with highly integrated RF front-end modules. Suppliers increasingly combine tunable filters with amplifiers, switches, and other RF components to simplify customer system integration and reduce overall design complexity.
Strategic partnerships with telecommunications equipment manufacturers, aerospace contractors, semiconductor foundries, and defense system integrators remain important for securing long-term design wins. Geographic manufacturing diversification, investment in advanced packaging technologies, and continued research into miniaturization and material innovations further shape competitive positioning.
Recent Developments
March 2026: Forefront RF announced that its commercial FFM51010 tunable duplexer was entering engagement with device manufacturers through demonstrations supported by detailed technical performance and validation data, accelerating adoption of reconfigurable RF filtering technologies.
February 2026: Murata Manufacturing announced additional investment in advanced electronic component production capacity to address rising global demand for high-frequency communication components. Expanded manufacturing capability supports supply continuity for RF system manufacturers.
September 2025: Qorvo expanded its RF technology portfolio with new infrastructure-focused solutions designed to improve wireless network performance and spectrum efficiency. The development supports equipment manufacturers deploying multi-band communication platforms.
Regulatory and Policy Environment
The RF tunable filter market operates within a regulatory framework shaped by spectrum allocation policies, electromagnetic compatibility requirements, defense procurement standards, and telecommunications certification procedures. National spectrum regulators continue allocating additional frequency resources for commercial broadband, satellite services, and industrial wireless applications, encouraging deployment of adaptable RF technologies capable of operating across multiple bands.
Compliance with electromagnetic compatibility standards remains essential for commercial communication equipment. Aerospace and defense applications require additional qualification under military environmental and reliability specifications, while satellite systems must satisfy stringent space-grade performance requirements. Manufacturers therefore invest extensively in testing, documentation, and quality management systems to support customer certification processes.
Government semiconductor manufacturing initiatives in several regions also influence supply chain investment by encouraging domestic production capacity, advanced packaging, and component manufacturing resilience. These policies may improve long-term component availability while reducing dependence on geographically concentrated supply networks.
Outlook and Strategic Implications
The commercial outlook for RF tunable filters will be shaped by continued investment in flexible communication architectures capable of supporting expanding spectrum utilization across civilian and defense applications. Procurement priorities are expected to favor electronically tunable solutions offering broader operating ranges, lower power consumption, improved integration, and enhanced reliability.
Equipment manufacturers are likely to reduce component counts through greater RF subsystem integration, encouraging suppliers to develop multifunctional solutions that combine filtering, switching, and signal conditioning capabilities. Defense modernization, satellite communication expansion, and wireless infrastructure upgrades should remain stable sources of premium-value demand.
Manufacturers that strengthen semiconductor process technologies, secure resilient supply chains, and expand engineering collaboration with system integrators are expected to improve competitive positioning. Nevertheless, extended qualification cycles, pricing pressure in commercial markets, geopolitical supply chain risks, and evolving spectrum regulations will remain important considerations influencing investment decisions over the next five years.
RF Tunable Filter Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 0.2 billion |
| Total Market Size in 2031 | USD 0.3 billion |
| Forecast Unit | Billion |
| Growth Rate | 8.45% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Tuning Mechanism, Application, End-Use Industry, Geography |
| Companies |
|
Market Segmentation
By Type
- Bandpass Filters
- Band-Stop (Band-Reject) Filters
By Tuning Mechanism
- Mechanical Tuning
- Electronic Tuning
- Magnetic Tuning
By Application
- Software-Defined Radio (SDR)
- Radar Systems
- Wireless Communication Infrastructure
- Mobile Devices
- Avionics and Defense Communication Systems
- Test and Measurement Equipment
- Satellite Communication Systems
By End-Use Industry
- Aerospace and Defense
- Telecommunications
- Consumer Electronics
- Automotive
- Healthcare
- Industrial
- Others
By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- France
- United Kingdom
- Spain
- Rest of Europe
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Israel
- Rest of Middle East and Africa
- Asia Pacific
- China
- Japan
- India
- South Korea
- Indonesia
- Taiwan
- Rest of Asia Pacific
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits for the Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Process
2.3. Data Validation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Analyst View
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter's Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
5. GLOBAL RF TUNABLE FILTER MARKET BY TYPE
5.1. Introduction
5.2. Bandpass Filters
5.3. Band-Stop (Band-Reject) Filters
6. GLOBAL RF TUNABLE FILTER MARKET BY TUNING MECHANISM
6.1. Introduction
6.2. Mechanical Tuning
6.3. Electronic Tuning
6.4. Magnetic Tuning
7. GLOBAL RF TUNABLE FILTER MARKET BY APPLICATION
7.1. Introduction
7.2. Software-Defined Radio (SDR)
7.3. Radar Systems
7.4. Wireless Communication Infrastructure
7.5. Mobile Devices
7.6. Avionics and Defense Communication Systems
7.7. Test and Measurement Equipment
7.8. Satellite Communication Systems
8. GLOBAL RF TUNABLE FILTER MARKET BY END-USE INDUSTRY
8.1. Introduction
8.2. Aerospace and Defense
8.3. Telecommunications
8.4. Consumer Electronics
8.5. Automotive
8.6. Healthcare
8.7. Industrial
8.8. Others
9. GLOBAL RF TUNABLE FILTER MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Rest of South America
9.4. Europe
9.4.1. Germany
9.4.2. France
9.4.3. United Kingdom
9.4.4. Spain
9.4.5. Rest of Europe
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. United Arab Emirates
9.5.3. Israel
9.5.4. Rest of Middle East and Africa
9.6. Asia Pacific
9.6.1. China
9.6.2. Japan
9.6.3. India
9.6.4. South Korea
9.6.5. Indonesia
9.6.6. Taiwan
9.6.7. Rest of Asia Pacific
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Emerging Players and Market Lucrativeness
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Analog Devices, Inc.
11.2. Skyworks Solutions, Inc.
11.3. Qorvo, Inc.
11.4. Murata Manufacturing Co., Ltd.
11.5. Broadcom Inc.
11.6. TDK Corporation
11.7. Smiths Interconnect (Smiths Group plc)
11.8. CTS Corporation
Navigate
Trusted by the world's leading organizations











