
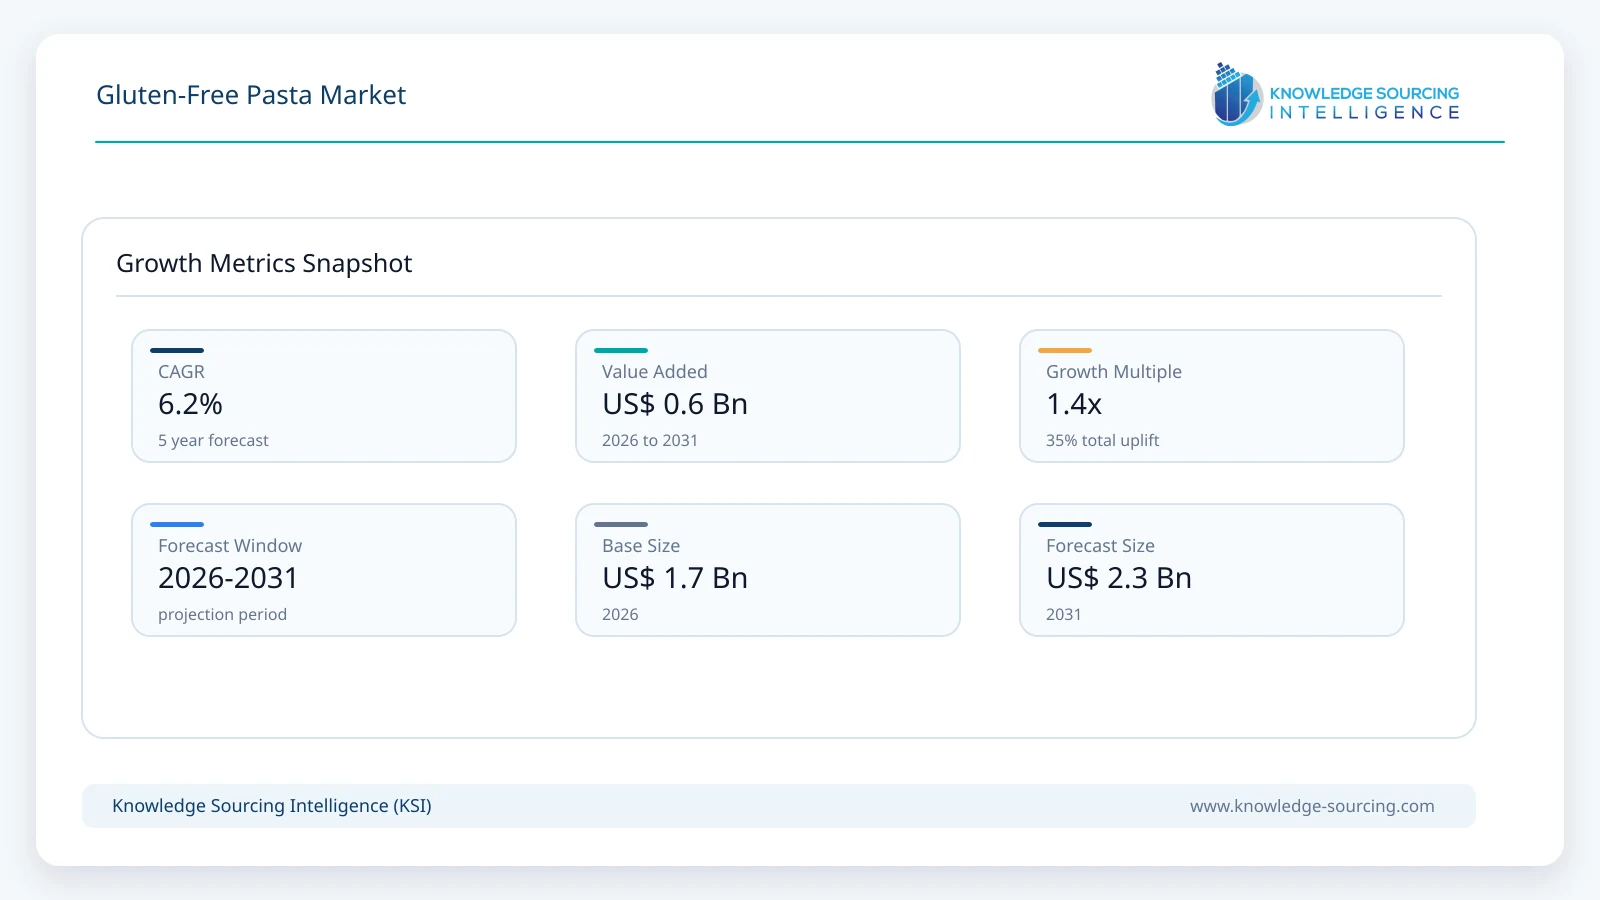
The Global Gluten-Free Pasta market is forecast to grow at a CAGR of 6.2%, reaching USD 2.3 billion in 2031 from USD 1.7 billion in 2026.
Highlights:
- 1Dry pasta accounts for approximately 73% of global gluten-free pasta market value in 2026, reflecting its shelf stability, broad retail availability, and lower distribution complexity.
- 2Rice-based pasta accounts for approximately 39% of market value in 2026, supported by familiar taste, neutral flavor and strong compatibility with established pasta-processing methods.
- 3Online distribution is projected to grow at approximately 9.4% annually through 2031, benefiting from specialty-brand discovery, direct-to-consumer availability, and a wider assortment than many physical stores carry.
- 4Residential consumption accounts for approximately 87% of market value in 2026, as most gluten-free pasta purchases remain centered on household dietary management and everyday meals.
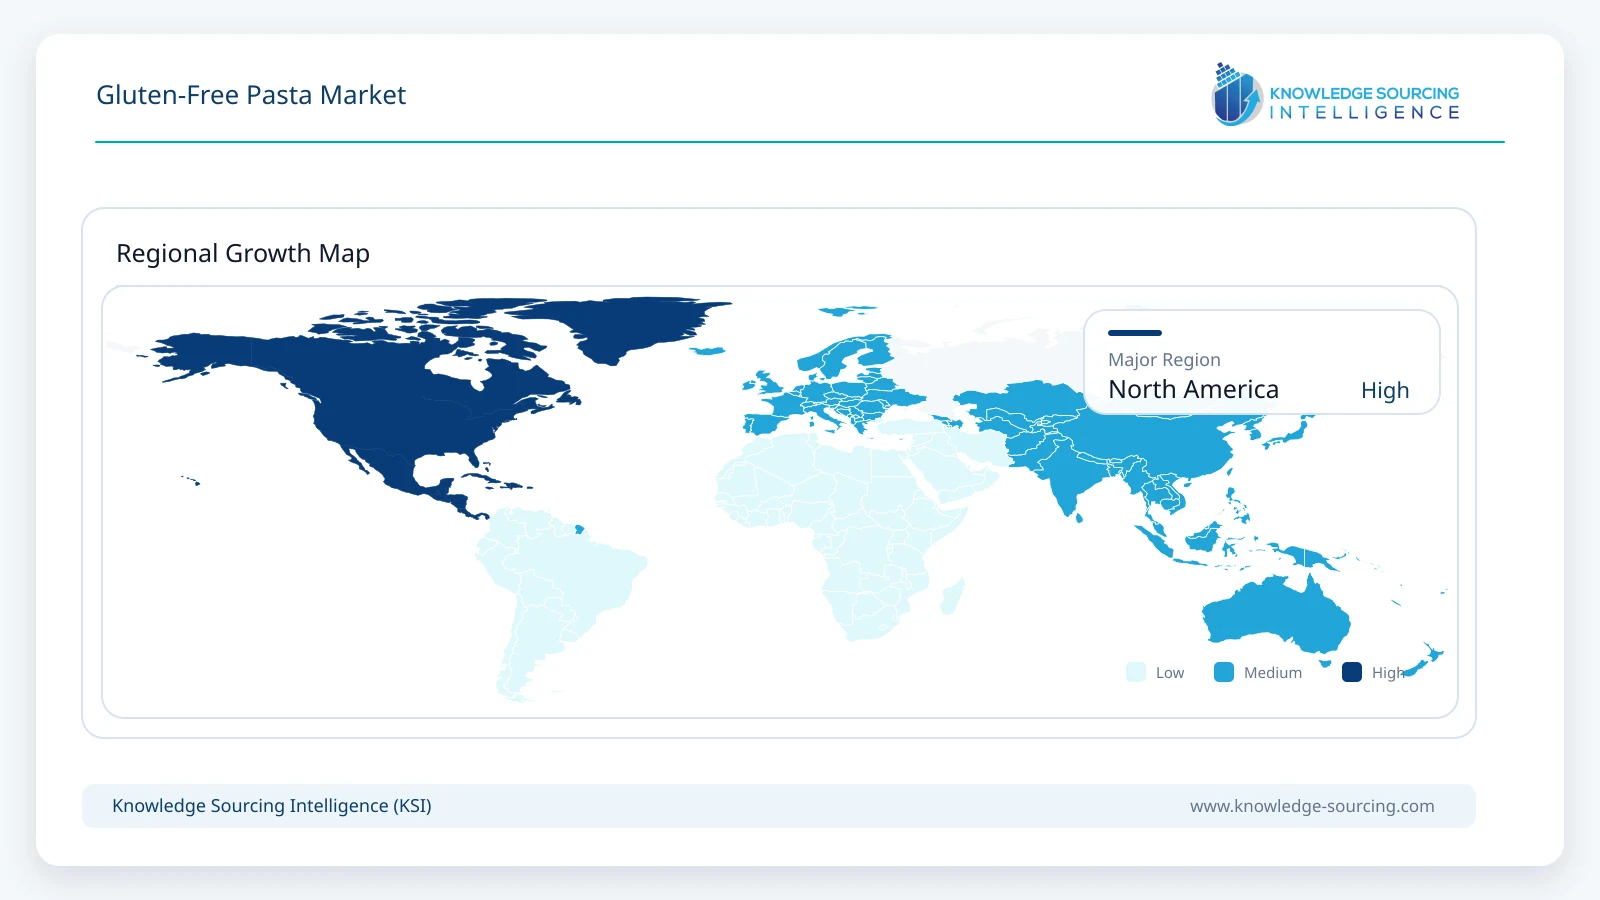
- 5North America accounts for approximately 36% of global market value in 2026, supported by high celiac awareness, established free-from retail channels and broad brand availability.
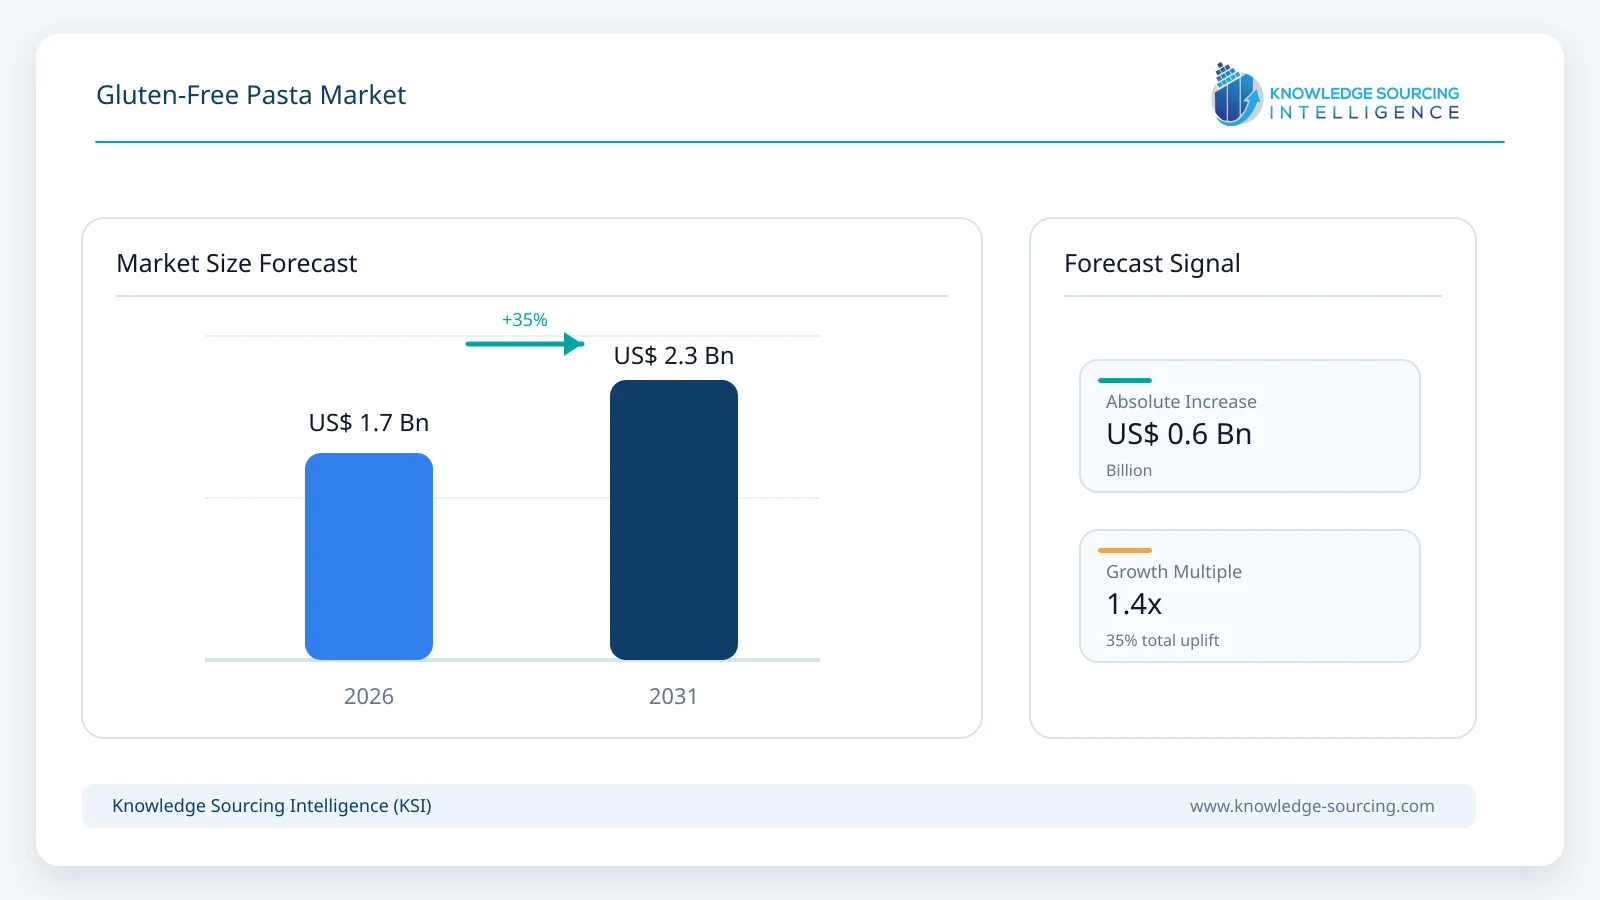
Gluten-free pasta includes pasta products formulated without wheat, barley, rye or other gluten-containing grains and marketed specifically for consumers seeking or requiring gluten-free alternatives. The market includes dry, fresh and frozen products manufactured from rice, corn, millet, legumes, cassava and other gluten-free ingredients, together with blended formulations designed to replicate the structure and cooking performance of conventional wheat pasta.
The category serves consumers with celiac disease and other medically diagnosed gluten-related conditions, but demand has broadened substantially beyond strict medical necessity. Gluten-free pasta is increasingly purchased as part of wider free-from, digestive-wellness and ingredient-diversification trends, while improved availability has made the category more accessible to mixed households where only one family member may require a gluten-free diet.
Product quality has also improved materially. Early gluten-free pasta often suffered from brittleness, poor cooking tolerance and inconsistent texture because conventional pasta depends heavily on gluten for structural integrity. Manufacturers now use combinations of rice, corn, pulses, hydrocolloids and optimized extrusion and drying processes to improve firmness, sauce adhesion and cooking stability. Barilla, for example, currently markets a dedicated gluten-free pasta range based primarily on corn and rice and manufactures it on a dedicated gluten-free line.
Regulatory definitions also reinforce trust in the category. In the United States, the FDA requires foods marketed as “gluten-free” to contain less than 20 parts per million of gluten and prohibits use of the claim where prohibited gluten-containing grains or improperly processed derivatives are present. The FDA estimates that around three million Americans have celiac disease, creating a defined medical consumer base in addition to voluntary gluten-free purchasers.
Market Trends
Ingredient Innovation Is Shifting the Category Beyond Rice and Corn
Rice and corn remain the most established gluten-free pasta bases because they can deliver comparatively familiar flavor, appearance, and cooking performance, but the category is becoming more diverse. Chickpea, lentil, buckwheat, oat, cassava and other alternative ingredients are increasingly used to add protein, fiber, nutritional differentiation or grain-free positioning. Felicia's current portfolio, for example, includes oat, buckwheat, red lentil, chickpea, spirulina and green cauliflower pasta, reflecting the broader move toward ingredient-led differentiation rather than gluten avoidance alone. The company's Organic Oat Penne received a 2026 NEXTY Award in the gluten-free category, while its North American expansion illustrates how alternative formulations are moving into wider mainstream distribution. This trend allows manufacturers to address additional consumer needs such as higher protein, whole-grain positioning and plant-based nutrition, but it also increases formulation complexity because each ingredient behaves differently during extrusion, drying and cooking.
Texture and Cooking Performance Are Becoming Stronger Competitive Differentiators
The commercial challenge in gluten-free pasta is no longer simply removing gluten. Consumers increasingly expect products to behave like conventional pasta during boiling, reheating and sauce preparation. This places greater emphasis on starch selection, protein content, extrusion pressure, drying profiles, and ingredient blending. Jovial positions its brown-rice pasta around bronze dies, slow drying, and dedicated gluten-free production, while Schar uses corn and rice formulations designed to provide conventional pasta texture. Barilla similarly emphasizes traditional taste and texture across its gluten-free range. The improvement in sensory quality is important because repeat purchase depends heavily on eating experience, particularly in households where gluten-free and conventional pasta are consumed side by side. Products that deliver poor texture after cooking or reheating face a significant disadvantage even when certification and ingredient quality are strong.
Fresh and Premium Gluten-Free Pasta Are Expanding the Addressable Market
Gluten-free pasta is increasingly moving beyond the dry grocery aisle into refrigerated and frozen formats positioned around premium taste and restaurant-style eating. Taste Republic operates specifically across fresh and frozen gluten-free pasta and refreshed its packaging in September 2026 to make the product proposition more visible at retail. The development is commercially important because fresh pasta historically represented one of the more difficult parts of the gluten-free category due to texture, shelf-life, and cross-contamination requirements. As processing improves, manufacturers can offer ravioli, tortellini, fettuccine, and other formats that broaden the category beyond standard dried spaghetti and penne. Premium formats also support higher price points and allow manufacturers to compete more directly with conventional gourmet pasta rather than only with other free-from products.
Mainstream Retail Distribution Is Broadening
Gluten-free pasta availability is expanding through supermarkets, online marketplaces, and national specialty chains rather than remaining concentrated in health-food stores. Felicia expanded into more than 800 Canadian retail locations in 2026 and also increased North American access through Amazon, while Giadzy launched its Italian-made gluten-free pasta across 480 Sprouts Farmers Market stores in August 2026. Broader distribution improves category visibility and encourages trial by consumers who may not actively visit specialist free-from retailers. It also raises competitive pressure because shelf space becomes contested by established multinational brands, specialist gluten-free companies, retailer private labels and newer premium entrants. Availability therefore becomes as important as formulation, particularly in markets where consumers expect gluten-free alternatives to be offered alongside conventional pasta rather than in a separate specialty section.
Market Drivers
Diagnosed Celiac Disease Creates a Stable Core Consumer Base
Celiac disease creates a non-discretionary demand base because affected consumers need to avoid gluten over the long term. The FDA estimates that around three million Americans have celiac disease and maintains a formal standard governing use of the gluten-free claim. Products carrying that claim must contain less than 20 ppm of gluten and comply with restrictions concerning wheat, rye, barley, and their derivatives. Pasta is an important substitution category because conventional pasta is heavily wheat-based and is therefore unsuitable for a strict gluten-free diet. Unlike some food categories where naturally gluten-free alternatives are readily available, pasta users often seek a direct replacement that can fit existing recipes and meal habits. This gives certified gluten-free pasta a defined functional role rather than relying solely on general wellness positioning, supporting recurring household demand even when discretionary food trends change.
Broader Free-From Consumption Expands the Addressable Market
The consumer base extends beyond diagnosed celiac disease to people managing non-celiac gluten sensitivity, wheat intolerance, or broader dietary preferences. Some consumers also purchase gluten-free pasta because alternative ingredients such as chickpeas, lentils, brown rice or buckwheat fit protein, fiber or plant-based nutrition goals. This widens the category's relevance but also changes what consumers expect from products. Manufacturers increasingly need to compete on nutritional profile, ingredient simplicity, and taste in addition to gluten-free certification. Felicia's use of oat, buckwheat, and legume-based formulations and Jovial's grain-free cassava range illustrate the expansion into adjacent health-oriented positioning. The result is a market where medically necessary consumption provides a stable base while lifestyle-driven demand creates additional opportunities for premiumization and product innovation.
Improved Availability Supports Routine Rather Than Occasional Consumption
Gluten-free pasta becomes more commercially attractive as consumers can purchase it easily through mainstream supermarkets, e-commerce, and direct-to-consumer channels. Historically, limited availability meant that consumers with celiac disease or gluten intolerance often depended on specialist stores or had access to only a small number of brands and formats. Wider retail penetration allows gluten-free pasta to become a regular pantry item instead of a specialty purchase. Online distribution strengthens this effect by allowing consumers to access niche brands, specialty shapes, and ingredient variants regardless of local physical-store assortment. Felicia's nationwide Amazon expansion and Giadzy's national Sprouts launch demonstrate how brands are using both digital and conventional retail to increase accessibility. Improved distribution also supports category experimentation because consumers can compare rice, corn, legume, and other formulations rather than repeatedly purchasing the only available option.
Market Restraints and Challenges
Gluten-Free Pasta Remains More Expensive Than Conventional Pasta
Gluten-free production generally involves smaller production runs, more expensive alternative ingredients, dedicated manufacturing environments and tighter contamination-control requirements than conventional durum-wheat pasta. These factors raise manufacturing costs and can result in materially higher retail prices. Dedicated production is commercially important because consumers with celiac disease depend on reliable control of cross-contact, and several major brands explicitly promote dedicated gluten-free manufacturing as part of their product assurance. Higher prices can constrain adoption among consumers who do not have a medical requirement to avoid gluten, particularly during periods of food-price inflation. The cost differential is less likely to eliminate demand among diagnosed celiac consumers, but it can encourage price comparison, private-label adoption, or reduced experimentation with premium products.
Cross-Contamination Control Raises Manufacturing Complexity
Manufacturers need to manage raw materials, production equipment, storage, and packaging carefully to ensure that gluten-free products remain within regulatory thresholds. This is particularly challenging for food companies that operate both conventional wheat-based and gluten-free pasta lines. The FDA's definition requires products carrying a gluten-free claim to remain below 20 ppm gluten, making contamination control a regulatory and brand-trust issue rather than only a quality preference. Dedicated lines or facilities can reduce the risk but increase capital and operating requirements, while shared plants require validated cleaning procedures and monitoring. This creates an advantage for specialist gluten-free manufacturers and larger companies capable of maintaining separate production infrastructure. It also raises barriers to entry for small conventional pasta manufacturers attempting to add gluten-free products without investing in appropriate controls.
Sensory Performance Remains Critical to Repeat Purchase
Formulation improvements have narrowed the quality gap, but gluten-free pasta can still differ from wheat pasta in texture, elasticity and cooking tolerance. Rice-based products may become soft if overcooked, while pulse-based formulations can introduce stronger flavors and different mouthfeel. Manufacturers therefore need to balance nutritional value, ingredient simplicity and traditional pasta characteristics. Consumer expectations are rising because leading products increasingly provide good texture and familiar cooking performance, making underperforming formulations less acceptable. The challenge is particularly relevant for premium products, where consumers expect a clear improvement over basic gluten-free alternatives. This places ongoing pressure on extrusion technology, ingredient blending and drying processes and favors manufacturers with established product-development capabilities.
Segment Analysis
By Product Type: Dry Pasta
Dry gluten-free pasta is projected to reach approximately USD 1.61 billion by 2031, remaining the largest product format despite faster development in fresh and frozen alternatives. Its dominance reflects long shelf life, ambient distribution, lower logistics costs and compatibility with conventional supermarket pasta aisles. Dry products also provide manufacturers with the broadest range of shapes and pack sizes while allowing retailers to maintain inventory without cold-chain requirements. Major suppliers including Barilla, Schär, Jovial, Rummo and Garofalo maintain substantial dry gluten-free portfolios, helping normalize the category alongside conventional pasta. Fresh and frozen products gain share gradually as premium consumers seek restaurant-style formats, but dry pasta remains the most scalable route for global distribution and household pantry use. Its role is particularly important in export markets because ambient stability lowers freight and inventory complexity compared with refrigerated alternatives.
By Ingredient: Rice
Rice-based gluten-free pasta is projected to generate approximately USD 0.86 billion by 2031, remaining the largest ingredient segment because of its neutral flavor, established processing characteristics and ability to provide a familiar pasta experience. Brown and white rice are used either independently or in blends with corn and other ingredients. Jovial's brown-rice pasta illustrates the single-ingredient premium end of the segment, while Barilla and Schär use rice together with corn to balance texture and cooking performance. Rice faces increasing competition from legumes, oats, cassava and other functional ingredients, particularly where brands compete on protein or fiber rather than conventional pasta similarity. Even so, the ingredient's mild taste and consumer familiarity support its continued leadership through the forecast period.
By Distribution Channel: Online
Online sales are projected to reach approximately USD 0.64 billion by 2031, making digital retail the fastest-growing distribution channel. E-commerce addresses a structural problem in the gluten-free category: individual supermarkets can carry only a limited number of specialty brands, ingredient types, and pasta shapes, while online platforms can offer a substantially broader assortment. Consumers managing strict diets are also more willing to search for specific certified products rather than substitute whatever is locally available. Felicia's 2026 Amazon expansion demonstrates this strategy, using nationwide digital availability to complement conventional retail growth. Online channels are particularly important for smaller specialist brands because they reduce dependence on national supermarket listings and allow direct communication around ingredients, certification, and allergen controls. Physical retail remains larger in absolute value, but online gains share through 2031 as specialty-food purchasing becomes increasingly omnichannel.
By End User: Residential
Residential consumption is projected to reach approximately USD 1.96 billion by 2031, remaining the dominant end-user segment because gluten-free pasta is primarily purchased for regular household meals. Consumers with celiac disease or medically required gluten avoidance need safe alternatives for routine food preparation, while mixed households increasingly choose one gluten-free product that can be eaten by the entire family. This encourages manufacturers to focus on conventional shapes, familiar taste and reliable cooking behavior rather than treating gluten-free pasta purely as a clinical dietary product. Commercial foodservice demand is also expanding as restaurants and institutional kitchens increase allergen-aware menu options, but contamination control and kitchen procedures make gluten-free service more complicated than packaged retail. Barilla notes that gluten-free options continue expanding across foodservice menus, illustrating an additional growth route without changing residential dominance.
Geographical Outlook
Major Region: North America
North America is projected to reach approximately USD 0.82 billion by 2031, retaining the largest regional market position as awareness of celiac disease, gluten intolerance and free-from diets remains high. The region combines a substantial medically required consumer base with developed supermarket, natural-food and e-commerce channels, allowing both multinational and specialist brands to achieve broad distribution. The FDA's standardized gluten-free definition also gives consumers a consistent regulatory framework for evaluating packaged products. The competitive environment is becoming increasingly diverse: established brands such as Barilla, Jovial and Banza operate alongside newer premium entrants including Felicia and Giadzy, while refrigerated specialist Taste Republic expands the category beyond traditional dry pasta. Recent retail expansion by Felicia in Canada and Giadzy in U.S. Sprouts stores illustrates continuing investment in category distribution.
Major Country: United States
The United States is projected to generate approximately USD 0.63 billion in gluten-free pasta revenue by 2031, remaining the largest individual country market. FDA estimates indicate that around three million Americans have celiac disease, creating a significant medically dependent consumer base before including non-celiac gluten sensitivity or voluntary dietary adoption. The U.S. market also benefits from broad category availability across supermarkets, natural-food retailers, warehouse clubs and e-commerce, making gluten-free pasta increasingly accessible outside specialist dietary stores. Competition spans mainstream brands such as Barilla, specialist producers such as Jovial and Taste Republic, pulse-based brands such as Banza and newer premium entrants such as Giadzy. Retail expansion continues, with Giadzy entering 480 Sprouts stores nationally in August 2026 and Felicia expanding digital availability through Amazon earlier in the year.
Competitive Environment and Analysis
The gluten-free pasta market combines large conventional pasta manufacturers, specialist free-from companies and newer nutrition-led brands. Barilla competes through a dedicated gluten-free line based on corn and rice, while Dr. Schär maintains a broad portfolio targeted specifically at consumers with gluten-related dietary requirements. Jovial differentiates through organic brown-rice and cassava products, while Rummo and Garofalo extend traditional Italian pasta positioning into gluten-free formulations.
Competition is increasingly moving beyond simple certification. Taste, texture, cooking tolerance, protein content, fiber, organic ingredients and sustainability claims are becoming more important as consumers gain wider product choice. Felicia is using oats, buckwheat and legumes to create differentiated nutritional profiles, while Taste Republic focuses on fresh and frozen formats. Banza has established strong recognition around chickpea-based pasta even as it expands into conventional wheat-protein products.
Private-label and retailer competition also increases as the category becomes mainstream. This makes manufacturing scale, certification, dedicated production, distribution access and the ability to maintain consistent sensory performance increasingly important. Brands that combine strong dietary credibility with conventional pasta-like quality are positioned more favorably than products competing only on the absence of gluten.
Recent Developments
September 2026: Taste Republic introduced redesigned packaging across its premium fresh and frozen gluten-free pasta portfolio to strengthen shelf visibility and brand positioning.
August 2026: Giadzy expanded its Italian-made gluten-free pasta into 480 Sprouts Farmers Market stores across the United States.
May 2026: Felicia expanded into more than 800 Canadian retail locations while establishing London, Ontario as its primary North American production base.
March 2026: Felicia's Organic Oat Penne received a NEXTY Award in the gluten-free category, highlighting growing innovation in alternative gluten-free ingredients beyond conventional rice and corn formulations.
February 2026: Felicia expanded nationwide U.S. accessibility through Amazon as part of its broader North American retail expansion.
2026: The FDA continued consultation on gluten-free labeling and prevention of gluten cross-contact in packaged foods, reinforcing regulatory attention to product safety and labeling integrity.
Market Outlook
The global gluten-free pasta market is experiencing sustained growth as medically required demand combines with broader free-from and wellness-oriented consumption. The market's strongest structural advantage is that pasta is a major wheat-based staple, creating a clear need for direct substitutes among consumers who cannot safely consume gluten. This demand is further supported by expanding product availability, improved formulations, and increasing consumer awareness of gluten-free dietary options.
Dry pasta remains the largest product format because of its shelf life, distribution efficiency, and broad availability, while fresh and frozen products broaden premium opportunities. Rice remains the most important ingredient base, although legumes, oats, cassava and other alternatives continue gaining attention as brands compete on nutrition and differentiation. Online distribution grows faster than conventional retail as specialist brands expand direct access, but supermarkets remain central to mainstream category penetration.
North America remains the largest region, led by the United States, where strong celiac awareness, standardized labeling rules, and broad retail infrastructure support category maturity. Competition continues shifting toward improved sensory performance, stronger nutritional positioning and broader mainstream distribution, making quality and availability increasingly important alongside gluten-free certification.
Gluten-Free Pasta Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.7 billion |
| Total Market Size in 2031 | USD 2.3 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.2% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Ingredients, Distribution Channel, End User |
| Companies |
|
Market Segmentation
By Product Type
Dry
Fresh
Frozen
Others
By Ingredients
Rice
Corn
Millet
Others
By Distribution Channel
Online
Offline
By End User
Residential
Commercial
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Italy
Germany
United Kingdom
France
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Australia
Thailand
Indonesia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Gluten-Free Certification and Cross-Contamination Control
3.7. Ingredient and Raw Material Outlook
3.8. Policies and Regulations
3.9. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Gluten-Free Extrusion Technology
4.2. Ingredient Blending and Texture Optimization
4.3. Low-Temperature and Slow-Drying Processes
4.4. Fresh and Frozen Gluten-Free Pasta Processing
4.5. Cross-Contamination Detection and Production Control
5. GLUTEN-FREE PASTA MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Dry
5.3. Fresh
5.4. Frozen
5.5. Others
6. GLUTEN-FREE PASTA MARKET BY INGREDIENTS
6.1. Introduction
6.2. Rice
6.3. Corn
6.4. Millet
6.5. Others
7. GLUTEN-FREE PASTA MARKET BY DISTRIBUTION CHANNEL
7.1. Introduction
7.2. Online
7.3. Offline
7.3.1. Supermarkets/Hypermarkets
7.3.2. Convenience Stores
7.3.3. Specialty Stores
7.3.4. Others
8. GLUTEN-FREE PASTA MARKET BY END USER
8.1. Introduction
8.2. Residential
8.3. Commercial
9. GLUTEN-FREE PASTA MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. By Product Type
9.2.2. By Ingredients
9.2.3. By Distribution Channel
9.2.4. By End User
9.2.5. By Country
9.2.5.1. United States
9.2.5.2. Canada
9.2.5.3. Mexico
9.3. South America
9.3.1. By Product Type
9.3.2. By Ingredients
9.3.3. By Distribution Channel
9.3.4. By End User
9.3.5. By Country
9.3.5.1. Brazil
9.3.5.2. Argentina
9.3.5.3. Others
9.4. Europe
9.4.1. By Product Type
9.4.2. By Ingredients
9.4.3. By Distribution Channel
9.4.4. By End User
9.4.5. By Country
9.4.5.1. Italy
9.4.5.2. Germany
9.4.5.3. United Kingdom
9.4.5.4. France
9.4.5.5. Spain
9.4.5.6. Others
9.5. Middle East and Africa
9.5.1. By Product Type
9.5.2. By Ingredients
9.5.3. By Distribution Channel
9.5.4. By End User
9.5.5. By Country
9.5.5.1. Saudi Arabia
9.5.5.2. UAE
9.5.5.3. Israel
9.5.5.4. South Africa
9.5.5.5. Others
9.6. Asia Pacific
9.6.1. By Product Type
9.6.2. By Ingredients
9.6.3. By Distribution Channel
9.6.4. By End User
9.6.5. By Country
9.6.5.1. China
9.6.5.2. Japan
9.6.5.3. India
9.6.5.4. South Korea
9.6.5.5. Australia
9.6.5.6. Thailand
9.6.5.7. Indonesia
9.6.5.8. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements, and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Dr. Schär AG
11.2. Barilla G. e R. Fratelli S.p.A.
11.3. Jovial Foods, Inc.
11.4. Rummo S.p.A.
11.5. Ebro Foods, S.A.
11.6. Pastificio Lucio Garofalo S.p.A.
11.7. Taste Republic
11.8. Banza LLC
11.9. Andriani S.p.A.
11.10. Food Directions Inc.
11.11. Ancient Harvest
11.12. Saco Foods
11.13. Doves Farm Foods Ltd.
11.14. RP's Pasta Company
11.15. ZENB
12. APPENDIX
12.1. Market Definition and Scope
12.2. Ingredient and Product Inclusion Criteria
12.3. Currency and Conversion Assumptions
12.4. Base Year and Forecast Period
12.5. Market Estimation Approach
12.6. Segment Modelling
12.7. Primary and Secondary Research Framework
12.8. Data Triangulation and Validation
Navigate
Trusted by the world's leading organizations











