
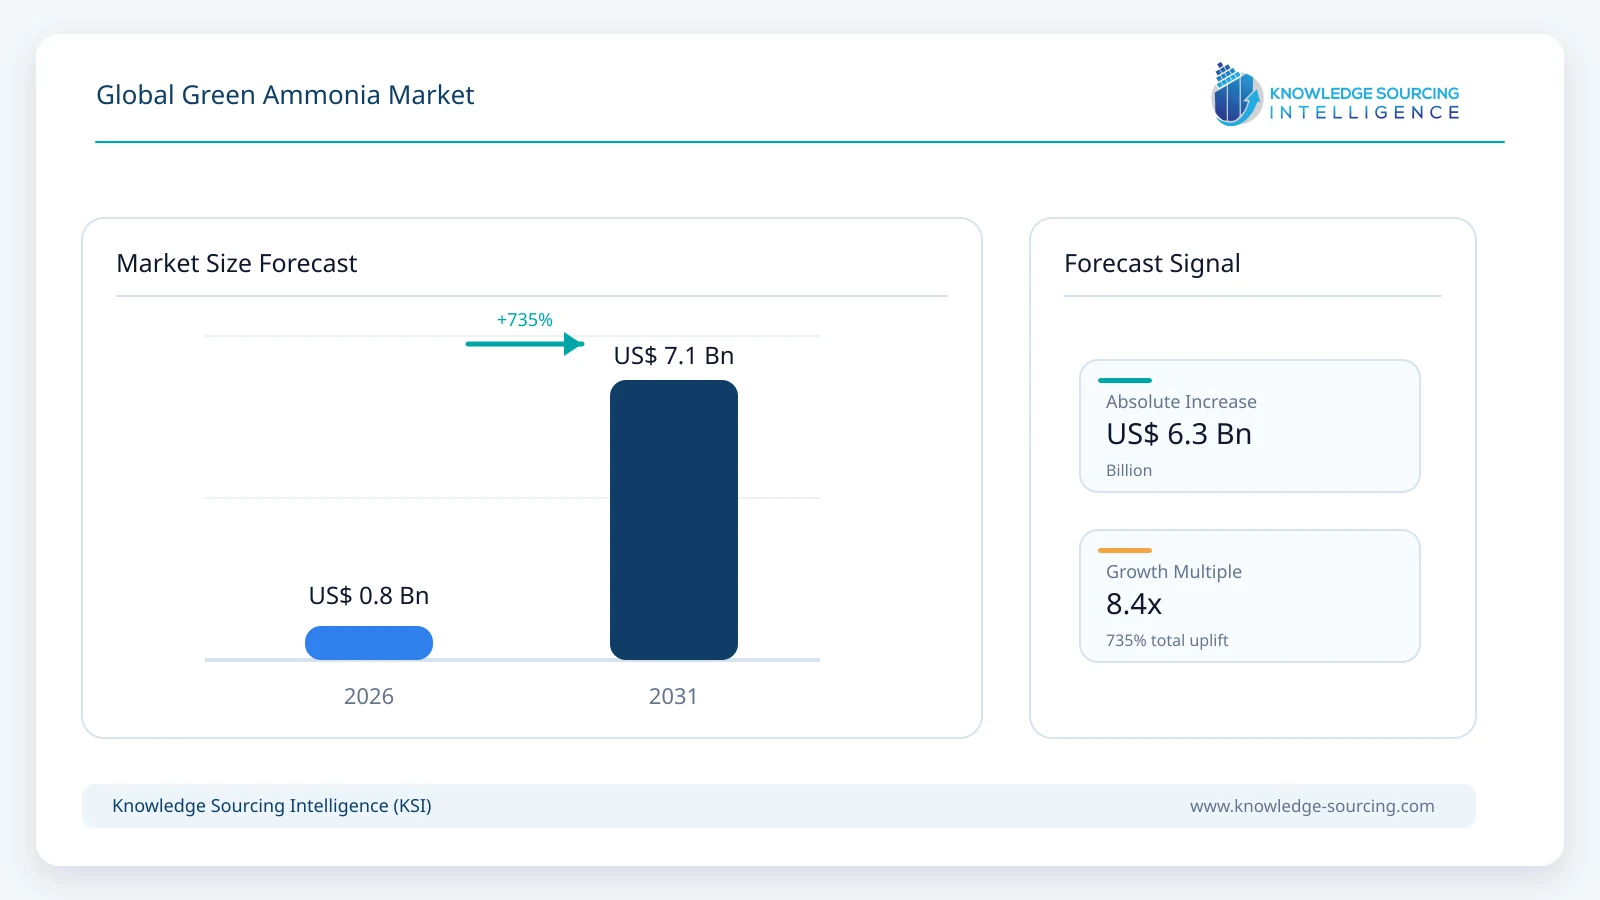
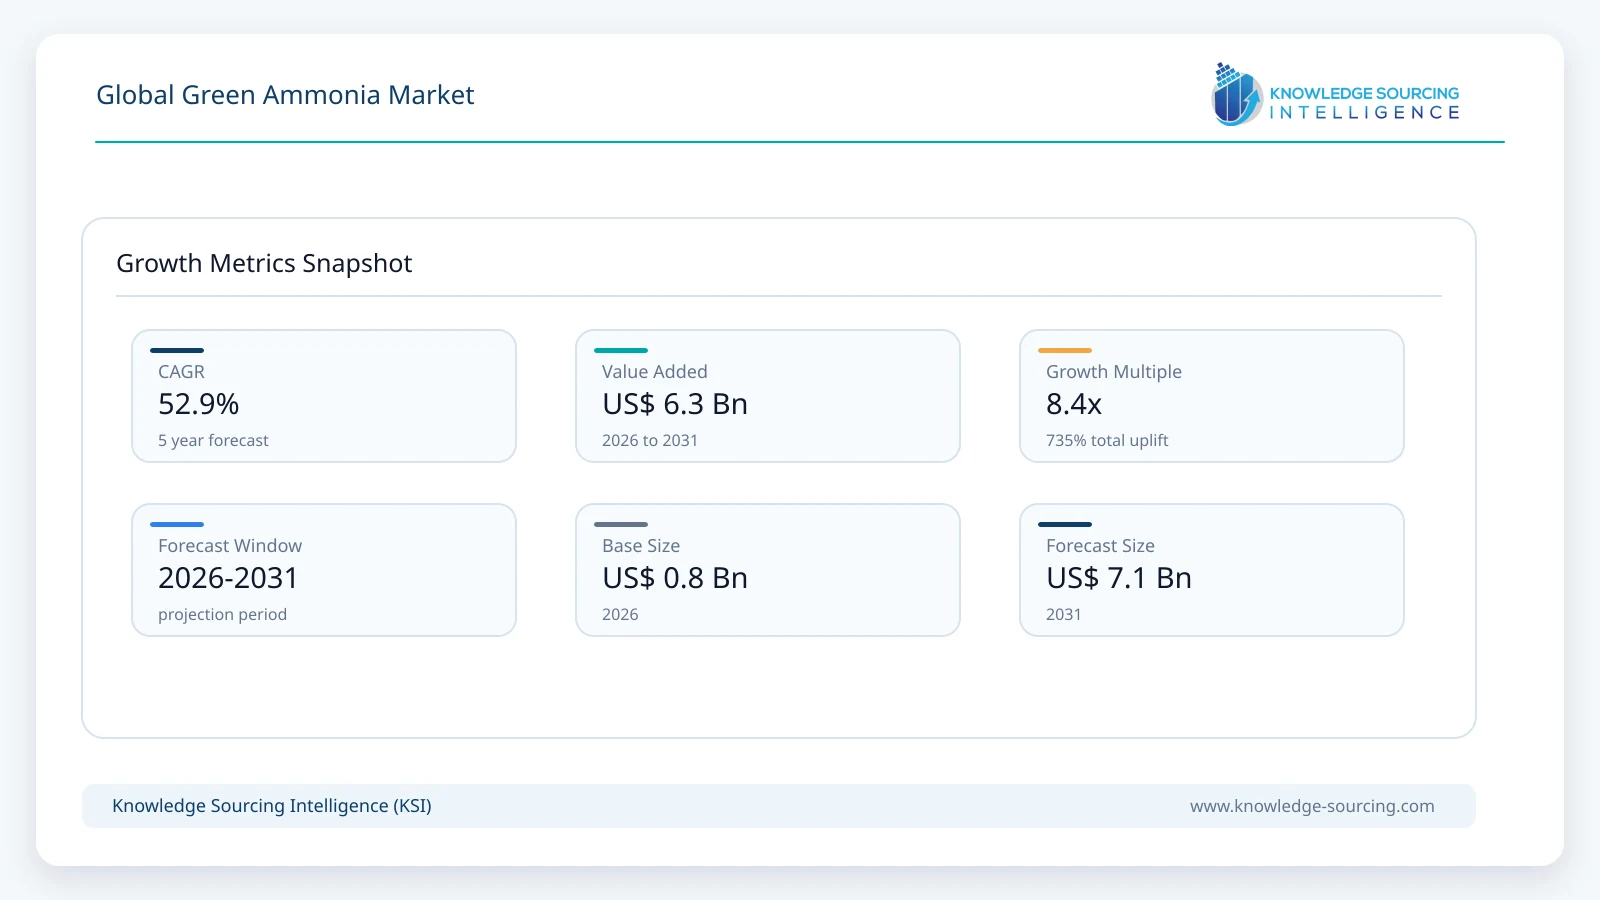
The Global Green Ammonia Market is estimated at USD 0.85 billion in 2026 and is forecast to reach USD 7.10 billion in 2031, representing a CAGR of 52.89% across the forecast period.
Highlights:
- 1The market is estimated at USD 0.85 billion in 2026, reflecting a still-early commercial base.
- 2China has established the first large operating supply base through commercial-scale renewable ammonia production.
- 3Fertilizer remains the anchor use, while maritime fuel develops as the highest-upside new demand segment.
- 4India is converting policy support into contracted fertilizer demand through competitive green-ammonia procurement tenders.
- 5Project-bankability depends increasingly on firm offtake, certification, renewable-power matching, and credible commissioning schedules.
- 6Large announced pipelines are discounted heavily because cancellations, delays, and weak offtake remain structural constraints.
Commercial supply is nevertheless becoming tangible. Envision Energy commissioned a 320,000-tonne-per-year renewable ammonia facility in Chifeng, China, in July 2025 and subsequently supplied green ammonia for marine bunkering and export. Yara’s 24 MW renewable hydrogen plant at Herøya is producing renewable-ammonia-based fertilizer, while larger projects in Saudi Arabia, India, Oman, and Egypt are moving through construction, contracted procurement, or investment-decision stages.
The market therefore has an unusual growth profile: a very small 2026 revenue base, several large projects capable of changing regional supply shares in a single year, and significant realization risk. The forecast to 2031 discounts early-stage capacity, assumes staggered ramp-up rather than immediate nameplate operation, and incorporates declining unit production costs as electrolyzer scale and renewable-power integration improve. It also assumes that premium pricing over conventional ammonia narrows but does not disappear during the forecast period.
Green Ammonia Market Trends
Commercial-Scale Production Replaces Demonstration-Only Supply
The market has moved beyond laboratory and pilot-scale evidence. Envision’s Chifeng project demonstrates that hundreds of thousands of tonnes of renewable ammonia can be produced from an integrated off-grid wind, solar, storage, electrolysis, air-separation, and synthesis system. Yara and other brownfield projects show a second route: replacing a portion of fossil hydrogen at an existing ammonia plant with renewable hydrogen.
This transition changes how the market should be measured. Revenue is increasingly linked to actual tonnes produced and contracted rather than equipment announcements or planned capacity. As a result, operational status, commissioning, utilization, certification, and offtake quality are more important than nominal project pipelines.
Fertilizer Creates the First Bankable Demand Base
Conventional ammonia is already consumed at massive scale in fertilizer production, so replacing fossil-derived hydrogen in existing ammonia supply chains provides a practical first market for renewable ammonia. India’s SIGHT framework is especially important because competitive tenders are creating defined quantities, counterparties, and discovered prices rather than relying only on voluntary green premiums.
SECI’s 2025 green-ammonia auctions awarded supply for multiple fertilizer plants, and a new 54,000-tonne-per-year tranche was launched in September 2026. These procurement mechanisms reduce demand uncertainty and can support project financing if renewable power, electrolyzers, and logistics are delivered on schedule.
Maritime Fuel Moves From Engine Development to Bunkering Trials
Ammonia is attractive for deep-sea shipping because it contains no carbon in the molecule and can be stored and transported using an established global ammonia infrastructure. In July 2025, renewable ammonia from Envision’s Chifeng facility was used in a green-ammonia bunkering operation at Dalian. IMO technical work in 2026 also focused on ammonia-fuel engines, safety, emissions control, bunkering, and infrastructure.
Near-term demand remains uncertain because global maritime regulation is still evolving and ammonia combustion requires strict control of toxicity, NOx, and nitrous oxide. Nevertheless, shipping represents the largest new addressable demand pool outside existing fertilizer and chemical uses.
Certification and Traceability Become Commercial Requirements
Buyers increasingly require evidence that hydrogen and ammonia meet defined lifecycle-emissions and renewable-electricity criteria. Envision obtained Bureau Veritas renewable-ammonia certification for its Chifeng project, while EU RFNBO rules and country-specific procurement frameworks create requirements around power sourcing, emissions accounting, temporal matching, and chain of custody.
This means that two ammonia molecules with identical physical properties can have very different commercial eligibility. Certification systems, metering, renewable-power contracts, emissions accounting, and documented custody therefore become part of the market infrastructure rather than optional sustainability claims.
Project Pipelines Are Being Repriced Around Offtake Quality
The IEA’s 2026 review shows slower investment momentum and a shrinking low-emissions hydrogen pipeline. Developers are therefore placing greater emphasis on long-term offtake, government-backed procurement, brownfield integration, and port-linked projects. Fertiglobe’s Egypt Green project secured a H2Global renewable-ammonia offtake award before its expected 2026 investment decision, while NEOM Green Hydrogen Company has a long-term ammonia offtake arrangement with Air Products.
Projects without credible buyers, competitive renewable power, financing, and export infrastructure face a rising probability of delay beyond 2030. The market is consequently consolidating around fewer, more bankable projects rather than the full volume of announced capacity.
Global Green Ammonia Market Segment Analysis
By Electrolysis Technology
Alkaline Water Electrolysis
Alkaline-electrolyzer-based green ammonia is estimated at approximately USD 0.58 billion in 2026, representing about 68.0% of global market revenue. Alkaline systems benefit from long operating experience, large module sizes, comparatively low capital cost, and strong manufacturing scale in China. They are therefore prevalent in large projects where low-cost renewable electricity and flexible plant design can compensate for slower dynamic response compared with PEM systems.
The share remains high through the forecast period, although PEM gains in projects that place greater value on rapid response to variable renewable power, compact footprints, or specific integration requirements.
By Electrolysis Technology
Proton Exchange Membrane
PEM-linked green ammonia is estimated at approximately USD 0.21 billion in 2026, or about 25.0% of the market. The segment is expected to grow faster than alkaline from a smaller base because PEM electrolysers can respond rapidly to fluctuating wind and solar output and are well suited to highly dynamic renewable-power systems.
PEM adoption remains constrained by higher capital cost and exposure to platinum-group and iridium catalyst supply. The technology is therefore most competitive where flexibility and system integration deliver enough operating value to offset the higher equipment cost.
By End Use
Fertilizer and Agricultural Inputs
Fertilizer and agricultural applications are estimated at approximately USD 0.53 billion in 2026, representing about 62.0% of global green-ammonia revenue. This is the largest segment because ammonia already has an established industrial role in nitrogen fertilizers and can be substituted into existing production and distribution chains without creating an entirely new end-use market.
Demand is driven by decarbonization targets in fertilizer manufacturing, carbon pricing and border measures, food-chain Scope 3 commitments, and government procurement. India’s contracted green-ammonia tenders are particularly important because they connect renewable-ammonia producers directly with named fertilizer plants and discovered supply prices.
By End Use
Maritime Fuel
Maritime fuel represents a relatively small 2026 revenue pool, estimated at about USD 0.09 billion, but is expected to be the fastest-growing end use through 2031. Early bunkering demonstrations, ammonia-capable engines, and port infrastructure are creating the technical basis for adoption in vessels that cannot be economically electrified.
Growth remains sensitive to safety standards, life-cycle emissions rules, fuel-price premiums, engine availability, and the final form of international maritime decarbonization policy. The segment therefore has high upside but greater forecast uncertainty than fertilizer demand.
By Geography
Asia Pacific
Asia Pacific is estimated at approximately USD 0.39 billion in 2026, or about 46.0% of global market revenue. China’s operating renewable-ammonia capacity provides the largest current production base, while India is building a policy-backed demand and project pipeline through SIGHT incentives and SECI procurement. Japan and South Korea provide additional future demand for imported low-emissions ammonia and hydrogen derivatives.
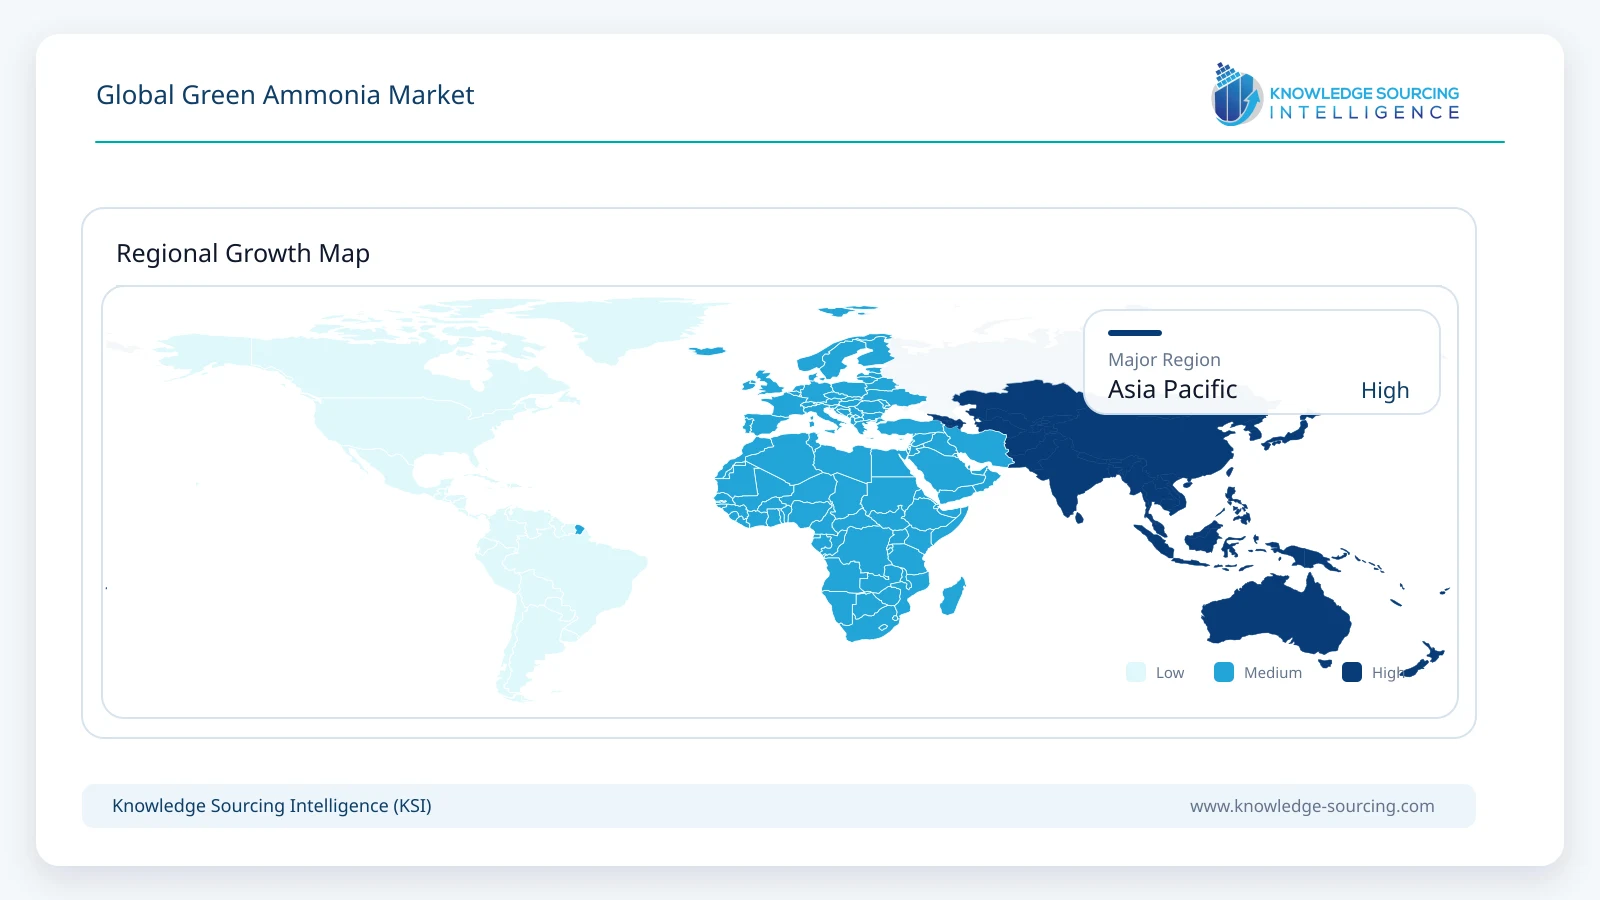
The region should remain the largest market through much of the forecast period because China combines electrolyzer manufacturing scale, low-cost equipment, large renewable projects, and existing chemical demand, while India adds a rapidly expanding portfolio of contracted fertilizer applications.
Middle East and Africa
Middle East and Africa is expected to be the fastest-growing regional market from a smaller 2026 base. The region contains some of the world’s most consequential export-oriented projects, including NEOM Green Hydrogen Company in Saudi Arabia, ACME’s phased development in Oman, and Fertiglobe’s Egypt Green renewable-ammonia project.
Growth depends on project execution and export demand rather than domestic ammonia consumption alone. Large renewable resources, port access, and long-term offtake can support low-cost supply, but financing, infrastructure, and commissioning schedules create substantial year-to-year volatility.
Market Drivers
Decarbonization of Existing Ammonia and Fertilizer Production
Most ammonia today is produced from fossil-derived hydrogen. Replacing that hydrogen with renewable hydrogen can lower lifecycle emissions while using established ammonia plants, storage systems, fertilizer factories, and trade infrastructure.Government Procurement and Industrial Policy
Support mechanisms increasingly move beyond capital grants. India’s green-ammonia tenders create contracted demand, while European RFNBO rules, carbon pricing, and hydrogen support mechanisms improve the economics of certified renewable ammonia.Maritime Decarbonization
Shipping requires energy-dense fuels for long-distance operation. Ammonia can be transported and stored at scale and is being evaluated in engines and bunkering systems, creating a potentially large new demand category.Falling Renewable Power and System-Integration Costs
Electricity is the dominant operating input for renewable hydrogen. Projects with low-cost wind and solar, high utilization, flexible electrolysers, storage, and optimized Haber-Bosch operation can reduce the premium over conventional ammonia.Global Ammonia Logistics Infrastructure
Ammonia already has established refrigerated storage, terminals, vessels, and industrial handling practices. This lowers the infrastructure barrier compared with transporting pure hydrogen over long distances.
Market Restraints
High Production Cost versus Conventional Ammonia
Renewable electricity, electrolyser capital, financing, and lower early-stage utilization keep green ammonia more expensive than unabated fossil-based production in most markets. Premiums must be absorbed by policy support, carbon costs, or buyers willing to pay for lower emissions.Offtake and Bankability Gaps
The IEA continues to identify insufficient firm offtake as a central barrier to low-emissions hydrogen investment. Many announced green-ammonia projects cannot reach final investment decision without long-term buyers or government-backed procurement.Project Delays and Execution Risk
Large integrated projects combine gigawatt-scale renewable generation, electrolysis, water treatment, air separation, ammonia synthesis, storage, and export infrastructure. Delays in any element can shift commercial operation by years.Certification and Renewable-Power Compliance
RFNBO and other low-emissions frameworks can impose additionality, temporal matching, geographic correlation, and emissions-accounting requirements. Projects that cannot document compliance may lose access to premium markets or subsidies.Ammonia Safety and Combustion Emissions
Ammonia is toxic and requires established handling controls. Fuel applications must also manage NOx and nitrous-oxide emissions. These issues add engine, bunkering, monitoring, and regulatory costs, particularly in maritime and power applications.
Competitive Environment
The green ammonia market is not yet a conventional commodity market with stable producer rankings. Competitive position depends on whether a project is operating, under construction, at final investment decision, backed by contracted demand, or still at an early development stage. This report therefore prioritizes companies with operating renewable-ammonia production, formally committed projects, or awarded green-ammonia supply capacity rather than including companies that only supply electrolyzers or announce exploratory concepts.
Envision Energy currently provides one of the clearest operating-scale benchmarks through its Chifeng project. Yara has demonstrated brownfield renewable-ammonia integration at Herøya. AM Green, NEOM Green Hydrogen Company, ACME, and Fertiglobe represent large export-oriented projects at various stages of execution, while Indian developers such as NTPC Renewable Energy, Avaada Green Fuels, Waaree Clean Energy Solutions, Jakson Green, Oriana Power, Onix Renewable, and Reliance Green Hydrogen and Green Chemicals are participating in policy-backed production or supply programs.
Not every company previously associated with green ammonia remains a valid current participant. CF Industries, for example, disclosed in its 2025 annual report that it abandoned its Donaldsonville electrolyzer project after concluding that the incremental investment would not meet return requirements, shifting emphasis toward CCS-based low-carbon ammonia. This illustrates why current project status must be verified before treating announced capacity as green-ammonia supply.
Recent Developments
September 2026: Solar Energy Corporation of India launched a new request for selection covering 54,000 tonnes per year of green-ammonia production and supply under SIGHT Mode 2A Tranche II, extending India’s policy-backed demand pipeline.
September 2026: The International Maritime Organization held a technical seminar focused on ammonia as a marine fuel, covering production, bunkering, infrastructure, engines, emissions control, and safety considerations.
June 2026: Oman announced investment agreements for ACME’s second and third Duqm phases, with the two phases expected to add a combined 800,000 tonnes per year of green-ammonia capacity when completed.
July 2026: Yara stated that it was finalizing a marketing and distribution agreement with Air Products for renewable ammonia from the NEOM Green Hydrogen project, strengthening the project’s future commercial route to market.
2026: Fertiglobe’s 2025 annual report identified Egypt Green as a 74,000-tonne-per-year pre-FID renewable-ammonia project with an expected 2026 investment decision and an H2Global long-term offtake award at a landed price of EUR 1,000 per tonne.
July 2025: Envision Energy commissioned its Chifeng renewable hydrogen and ammonia facility at approximately 320,000 tonnes per year and subsequently supplied green ammonia for marine bunkering and international shipment.
Market Outlook
Green ammonia is expected to remain one of the fastest-growing industrial decarbonization markets through 2031, but growth will be highly uneven. A single million-tonne project can materially alter global supply, while cancellation or delay of the same project can remove a large share of expected revenue. Forecasts therefore require explicit probability weighting rather than straight-line conversion of announced capacity into market size.
Fertilizer and chemical substitution should provide the most dependable demand because ammonia already has an established use and infrastructure base. Maritime fuel creates the largest incremental upside but remains more policy- and technology-sensitive. Power generation demand is likely to remain concentrated in selected Asian markets rather than becoming a globally dominant use by 2031.
Asia Pacific is expected to retain the largest production and consumption share, while the Middle East becomes a major export hub if NEOM and Oman projects execute on schedule. Europe remains a premium demand market because RFNBO rules and carbon policy can support imports, but high production costs and limited domestic renewable resources constrain large-scale local output.
The forecast to USD 7.10 billion by 2031 assumes only a fraction of announced projects become operational, average selling prices decline as scale improves, and utilization ramps over time. A faster build-out of committed projects or stronger maritime mandates would create upside; prolonged weak offtake, permitting delays, or cheaper fossil ammonia would create downside.
Global Green Ammonia Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 0.85 billion |
| Total Market Size in 2031 | USD 7.10 billion |
| Forecast Unit | Billion |
| Growth Rate | 52.89% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Electrolysis Technology, Project Configuration, End Use, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Electrolysis Technology
Alkaline Water Electrolysis
Proton Exchange Membrane (PEM)
Solid Oxide Electrolysis and Other Technologies
By Project Configuration
Greenfield Integrated Renewable-Ammonia Projects
Brownfield Ammonia Decarbonization
Grid-Connected / Certified Renewable Supply Models
By End Use
Fertilizer and Agricultural Inputs
Maritime Fuel
Power Generation
Chemical and Industrial Feedstock
Hydrogen Carrier and Other Uses
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Chile
Others
Europe
Germany
Netherlands
Spain
Norway
Others
Middle East and Africa
Saudi Arabia
Oman
Egypt
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Australia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Validation
2.4. Market Estimation and Forecasting
2.5. Capacity, Utilization and Price Triangulation
2.6. Project Probability and Quality Control
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
3.3. Segment Summary
3.4. Regional Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Decarbonization of Existing Ammonia and Fertilizer Production
4.1.2. Government Procurement and Industrial Policy
4.1.3. Maritime Decarbonization
4.1.4. Falling Renewable Power and System-Integration Costs
4.1.5. Global Ammonia Logistics Infrastructure
4.2. Market Restraints
4.2.1. High Production Cost versus Conventional Ammonia
4.2.2. Offtake and Bankability Gaps
4.2.3. Project Delays and Execution Risk
4.2.4. Certification and Renewable-Power Compliance
4.2.5. Ammonia Safety and Combustion Emissions
5. GREEN AMMONIA MARKET BY ELECTROLYSIS TECHNOLOGY
5.1. Alkaline Water Electrolysis
5.2. Proton Exchange Membrane (PEM)
5.3. Solid Oxide Electrolysis and Other Technologies
6. GREEN AMMONIA MARKET BY PROJECT CONFIGURATION
6.1. Greenfield Integrated Renewable-Ammonia Projects
6.2. Brownfield Ammonia Decarbonization
6.3. Grid-Connected / Certified Renewable Supply Models
7. GREEN AMMONIA MARKET BY END USE
7.1. Fertilizer and Agricultural Inputs
7.2. Maritime Fuel
7.3. Power Generation
7.4. Chemical and Industrial Feedstock
7.5. Hydrogen Carrier and Other Uses
8. GREEN AMMONIA MARKET BY GEOGRAPHY
8.1. North America
8.1.1. United States
8.1.2. Canada
8.1.3. Mexico
8.2. South America
8.2.1. Brazil
8.2.2. Chile
8.2.3. Others
8.3. Europe
8.3.1. Germany
8.3.2. Netherlands
8.3.3. Spain
8.3.4. Norway
8.3.5. Others
8.4. Middle East and Africa
8.4.1. Saudi Arabia
8.4.2. Oman
8.4.3. Egypt
8.4.4. UAE
8.4.5. Others
8.5. Asia Pacific
8.5.1. China
8.5.2. India
8.5.3. Japan
8.5.4. South Korea
8.5.5. Australia
8.5.6. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Producers and Project Developers
9.2. Operating versus Committed Capacity
9.3. Offtake, Certification and Export Positioning
9.4. Technology and Renewable-Power Integration
9.5. Recent Developments
9.6. Competitive Dashboard
10. COMPANY PROFILES
10.1. Envision Energy
10.2. Yara International ASA
10.3. AM Green Ammonia
10.4. ACME Group
10.5. NEOM Green Hydrogen Company
10.6. ACWA Power Company
10.7. Air Products and Chemicals, Inc.
10.8. Fertiglobe plc
10.9. NTPC Renewable Energy Limited
10.10. Avaada Green Fuels Private Limited
10.11. Waaree Clean Energy Solutions Private Limited
10.12. Reliance Green Hydrogen and Green Chemicals Limited
10.13. Jakson Green Limited
10.14. Oriana Power Limited
10.15. Onix Renewable Limited
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Green Ammonia Definition and Exclusions
11.5. Abbreviations





Frequently asked questions
What is the Green Ammonia market size forecast?
Forecast to reach USD 7.10 billion in 2031, from USD 0.85 billion in 2026.
What is the projected CAGR for the Green Ammonia market?
The Global Green Ammonia Market is projected to grow at a CAGR of 52.89% by 2031.
Which country leads in commercial green ammonia supply?
China has established the first large operating supply base.
Which end-use industry is the primary anchor demand?
Fertilizer remains the anchor use for green ammonia.
What is the highest-upside new demand segment?
Maritime fuel is developing as the highest-upside new demand segment.
What are key factors for green ammonia project bankability?
Offtake, certification, renewable power matching, and credible commissioning are critical.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Global Green Ammonia Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/green-ammonia-market