
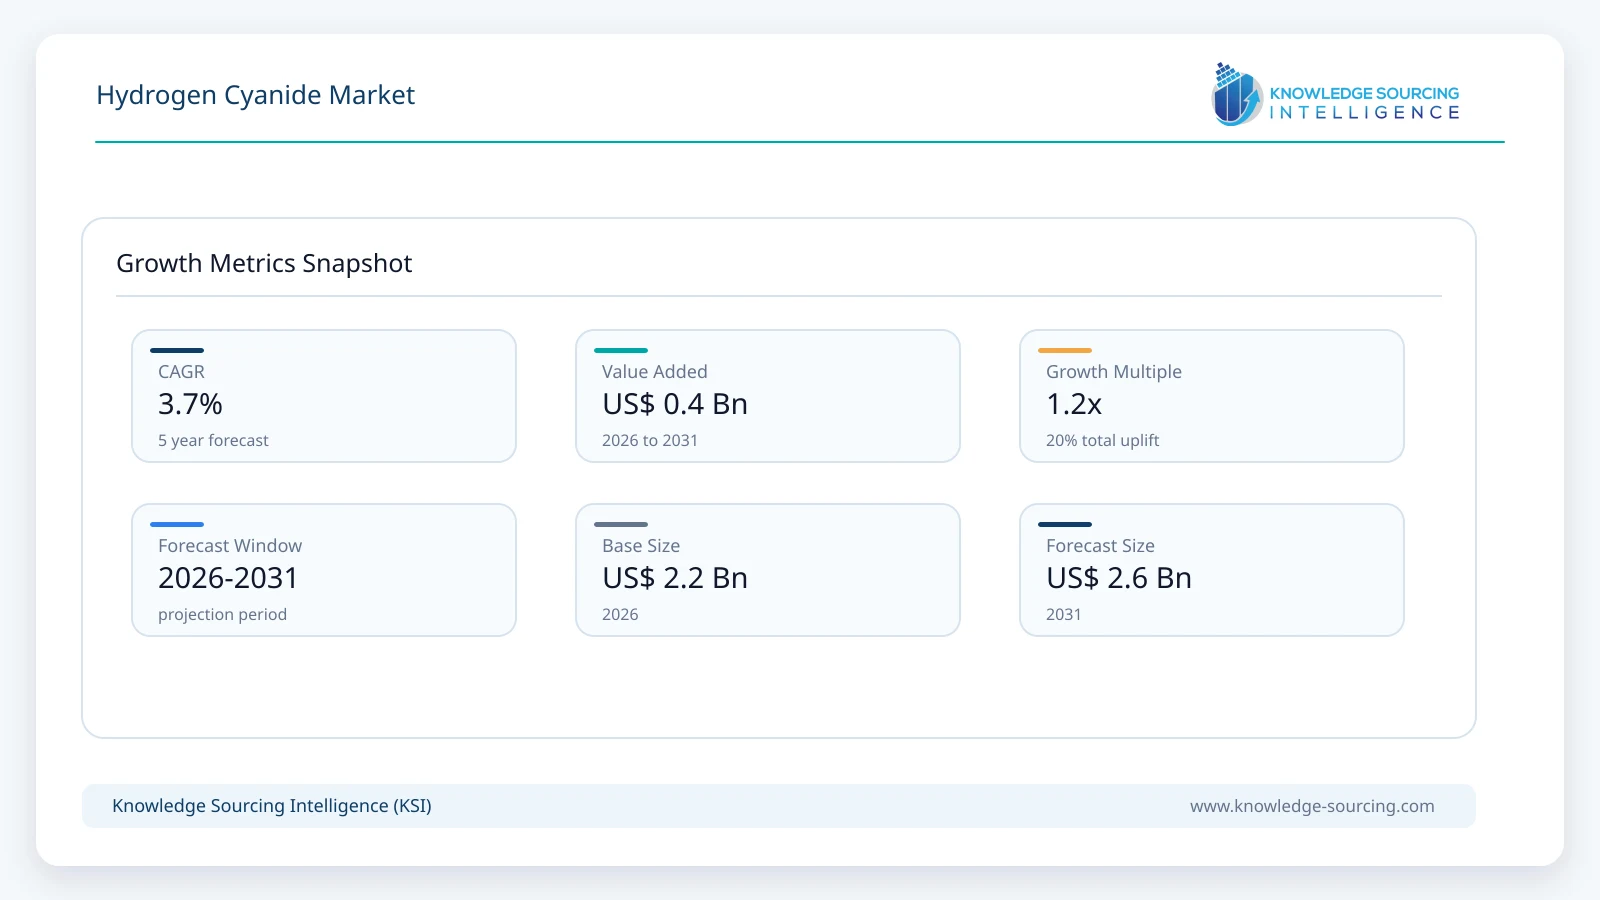
The Hydrogen Cyanide Market is estimated to grow at a CAGR of 3.68%, reaching USD 2.60 billion in 2031 from USD 2.17 billion in 2026.
Highlights:
- 1Sodium Cyanide represents the largest individual downstream application and is estimated at approximately USD 0.67 billion in 2026.
- 2Adiponitrile accounts for roughly one-quarter of market value in 2026, supported by nylon 66 demand across engineering plastics, industrial fibres and automotive applications.
- 3Methionine is one of the faster-growing HCN derivatives through 2031 as commercial poultry and animal-feed production expands.
- 4Integrated/captive production remains structurally important because HCN is highly toxic and difficult to transport, favouring conversion close to the production site.
- 5Asia Pacific accounts for approximately 38% of market value in 2026 and gains share through 2031 as downstream chemical and mining-related capacity expands.
- 6Sodium cyanide capacity additions in Australia and new integrated HCN/NaCN investment in India provide direct evidence of downstream supply-chain expansion during 2026.
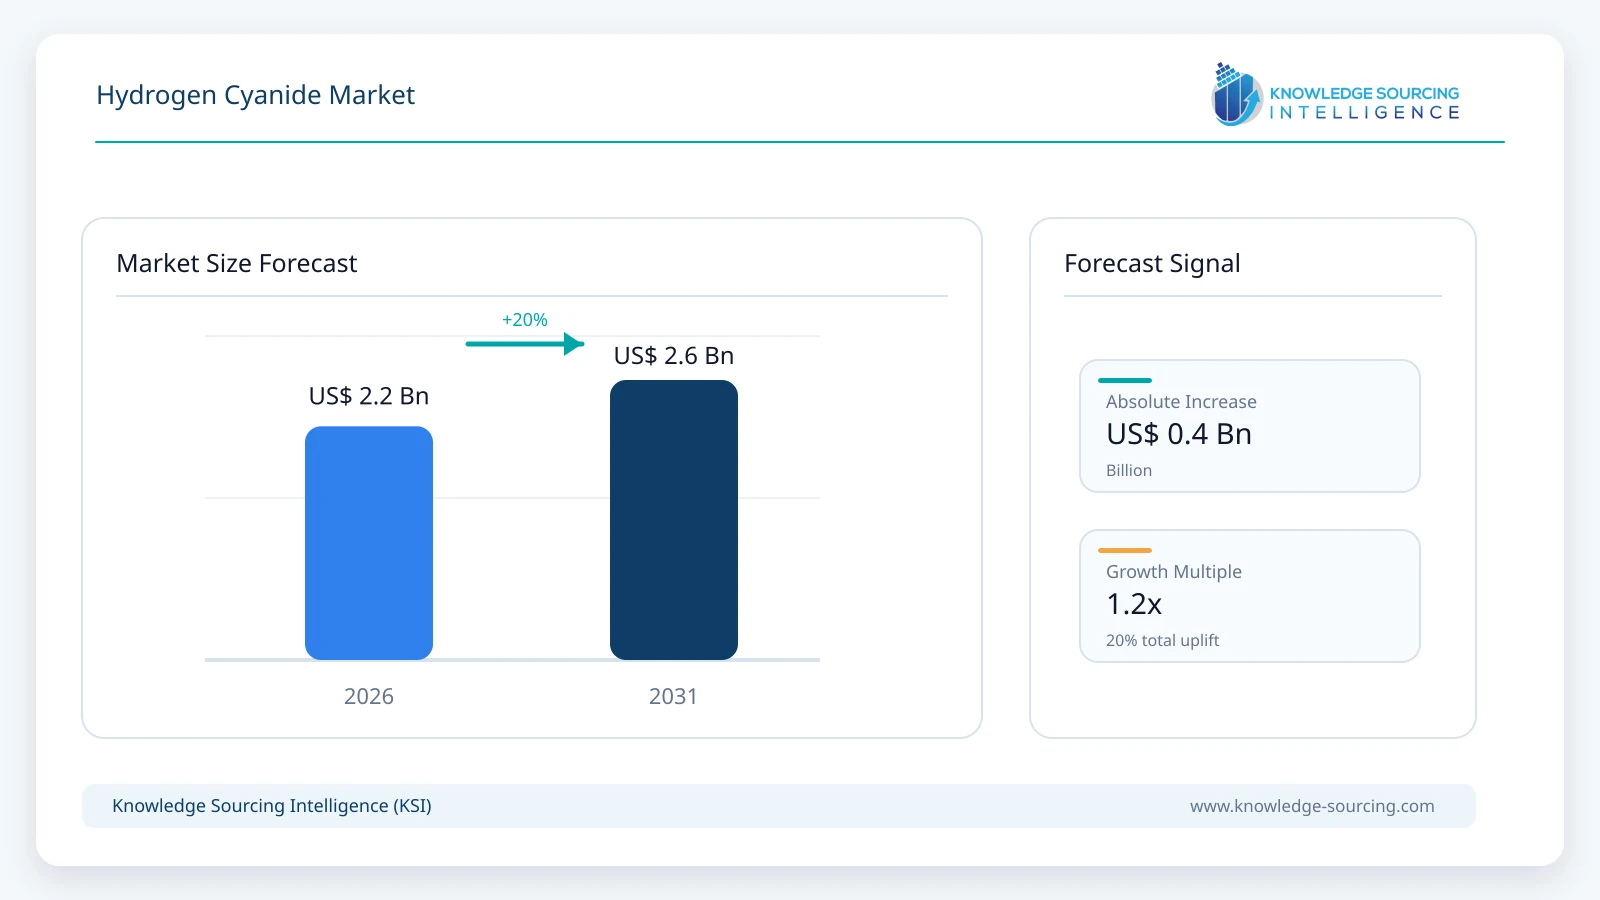
Hydrogen cyanide is primarily an intermediate rather than a final-use chemical, and its commercial value is determined by the downstream products into which it is converted, particularly sodium cyanide, adiponitrile, acetone cyanohydrin, methionine and chelating agents. The market is therefore closely linked to gold mining, nylon 66, acrylic materials, animal nutrition and specialty chemical production. Its high toxicity and volatility also shape the industry's physical structure: a significant share of HCN is produced and consumed within integrated chemical complexes, which reduces long-distance merchant movement and gives producers with downstream conversion capability a structural advantage.
Sodium cyanide represents the strongest source of incremental demand through the forecast period. Gold prices and mine-development activity continue to support cyanide consumption, while declining ore grades at mature deposits increase the amount of material that must be processed to recover each unit of gold. Orica reported strong customer demand for sodium cyanide during the first half of 2026 and completed upgrades at its Winnemucca solids facility, while Wesfarmers reported that the first phase of Australian Gold Reagents' Kwinana expansion increased sodium cyanide capacity by approximately 35,000 tonnes per year to around 130,000 tonnes per year. These additions do not directly measure HCN merchant demand, but they provide strong evidence that one of the largest downstream HCN-consuming value chains is expanding.
Demand from chemical derivatives remains more diversified. Adiponitrile provides a substantial base through nylon 66 production, while acetone cyanohydrin remains an established route into methyl methacrylate and acrylic materials. Methionine adds a separate animal-nutrition demand stream. INEOS identifies sodium cyanide, adiponitrile, chelates, methionine and acetone cyanohydrin among the principal products derived from recovered HCN, while Ascend Performance Materials lists HCN alongside acrylonitrile, adiponitrile and hexamethylene diamine within its intermediate-chemicals portfolio. This combination of mining and chemical demand keeps the market relatively stable even when one downstream sector weakens.
Asia Pacific remains the largest regional market and gains share gradually through 2031 as chemical capacity expands and more downstream cyanide production is localized. Balaji Amines' 2026 annual report identifies a Rs 750 crore expansion at Balaji Speciality Chemicals that includes a new Chincholi unit for hydrogen cyanide, sodium cyanide, EDTA and EDTA-2Na, scheduled to become operational toward the end of FY27. The project is important because it combines HCN production with immediate downstream conversion, which is the model most consistent with the safety, transport and economics of the molecule. North America remains another major market because it combines integrated nitrile production, nylon intermediates, acetone cyanohydrin, and a large gold-mining sodium cyanide supply chain.
Growth Drivers and Trends
Gold Mining Is Supporting Sodium Cyanide Demand
Gold mining provides one of the most visible growth channels for hydrogen cyanide because sodium cyanide remains a standard commercial reagent for recovering gold from ore. The relationship is not simply linked to mine output. Lower ore grades require more rock to be processed for the same quantity of recovered metal, which can increase reagent consumption even when headline gold production grows more slowly. Sodium cyanide demand is therefore influenced by gold prices, mine expansions, greenfield projects, ore characteristics and the economics of processing lower-grade deposits.
The downstream evidence remains strong. Orica's first-half 2026 business update reported continued strong customer demand for sodium cyanide within a robust gold sector and successful completion of upgrades at Winnemucca, allowing optimization across the company's Winnemucca, Yarwun and Alvin network. Wesfarmers' June 2026 strategy briefing reported that the first phase of the Australian Gold Reagents expansion had been delivered, increasing total sodium cyanide capacity by approximately 35,000 tonnes per year to around 130,000 tonnes per year. As a result, sodium cyanide is projected to grow faster than the overall HCN market and increase its share through 2031.
Adiponitrile Maintains a Large Nylon 66 Demand Base
Adiponitrile remains one of the largest HCN-derived intermediates because it is converted into hexamethylene diamine and subsequently nylon 66. The material is used in engineering plastics, automotive components, electrical and electronic parts, industrial fibres and other applications requiring thermal resistance, strength and durability. Ascend Performance Materials operates world-scale adiponitrile capacity in the United States and lists HCN within the same intermediate-chemicals portfolio, illustrating the close integration between nitrile intermediates and downstream polyamide production.
The segment grows more moderately than mining-related sodium cyanide because several major nylon-consuming industries are mature, but it remains commercially significant because of the scale of the installed nylon 66 value chain. The forecast therefore assumes continued absolute growth without a material expansion in market share. Electrification, lightweighting and higher-performance engineering materials support selected end uses, while broader manufacturing cycles continue to influence demand.
Methionine Links HCN Demand to Animal Nutrition
Methionine creates a separate demand stream that is less directly correlated with mining or industrial plastics. Synthetic methionine is widely used to balance poultry and livestock feed formulations and improve nutrient utilization. INEOS identifies methionine as an important HCN derivative, while Evonik produces hydrocyanic acid internally as part of integrated methionine manufacturing at major sites. This integration shows why the HCN market should be evaluated through downstream chemical chains rather than only through merchant product shipments.
The methionine pathway is expected to grow faster than the overall HCN market through 2031 as commercial poultry, aquaculture and feed production continue to expand in Asia and other developing regions. Feed producers increasingly optimize amino-acid profiles to improve conversion efficiency and manage protein costs, supporting demand for synthetic methionine. The application remains smaller than sodium cyanide and adiponitrile but gains modest share over the forecast period.
Acetone Cyanohydrin Continues to Support the Acrylic Value Chain
Acetone cyanohydrin remains an established HCN derivative used in the production of methyl methacrylate and related acrylic materials. INEOS produces acetone cyanohydrin at its Green Lake, Texas acrylonitrile complex by reacting recovered co-product HCN with acetone. The downstream acrylic chain serves construction, signs and displays, automotive components, coatings, lighting, household products and other applications where transparency, weatherability or surface performance are important.
Growth is expected to be slower than sodium cyanide and methionine because the acrylic value chain is comparatively mature and alternative MMA technologies can reduce reliance on the ACH route in some investments. Acetone cyanohydrin nevertheless remains a material part of the installed production base and continues to contribute a significant share of HCN consumption through 2031.
Integrated Production and Localization Are Reshaping Supply
The physical characteristics of HCN encourage production close to downstream consumption. At normal conditions near its boiling point, HCN can exist as either liquid or gas, but the more important commercial distinction is whether the molecule is produced and consumed within an integrated complex or transferred externally. INEOS recovers HCN as a co-product from acrylonitrile manufacturing, Evonik uses HCN internally in methionine production, and Ascend lists HCN alongside its nitrile and nylon intermediates. These examples illustrate why integrated production remains central to market economics.
Localization is becoming more visible in Asia. Balaji Speciality Chemicals' planned Chincholi unit will combine HCN with sodium cyanide and EDTA derivatives, allowing downstream conversion close to the production source. Such projects reduce transport exposure and create domestic supply for mining and specialty chemical customers. Through 2031, new HCN investment is therefore more likely to appear as part of integrated derivative chains than as standalone capacity designed principally for long-distance merchant sales.
Market Restraints
Extreme Toxicity Raises Capital and Operating Requirements
Hydrogen cyanide is a fast-acting systemic toxicant that interferes with the body's ability to use oxygen. NIOSH identifies commercial use in mining, electroplating, chemical synthesis and the production of synthetic fibres, plastics, dyes and pesticides, while also emphasizing that exposure can be rapidly fatal. Industrial plants therefore require containment, continuous monitoring, emergency systems, trained personnel and tightly controlled maintenance procedures. These requirements raise both capital expenditure and operating cost and make HCN production unattractive for companies without established hazardous-chemical capabilities.
Transport Constraints Limit the Merchant Market
HCN's toxicity and volatility make long-distance transportation more complex than movement of many downstream derivatives. Producers frequently convert the molecule immediately into sodium cyanide, acetone cyanohydrin, methionine intermediates or other chemicals rather than shipping large quantities of HCN between unrelated sites. This reduces the effective merchant market and means that total industrial HCN production can be substantially larger than third-party sales. It also gives integrated chemical complexes an advantage because they can capture downstream value while avoiding part of the transport and handling burden.
Regulatory and Community Acceptance Can Slow Capacity Expansion
New HCN and cyanide facilities require extensive environmental, worker-safety and hazardous-material approvals. Developers must address emissions, wastewater, storage, emergency response and occupational exposure before commercial operation. Even when a project is technically viable, permitting and community concerns can lengthen timelines and raise development costs. The effect is particularly important for new locations without an existing hazardous-chemical manufacturing base, which favours brownfield expansions and integrated industrial sites.
Downstream Cycles Influence Plant Utilization
HCN demand is derived from several downstream markets, and weakness in any major value chain can affect plant utilization. Gold-mining investment influences sodium cyanide consumption, automotive and industrial production influence nylon 66, construction and coatings affect acrylic demand, and livestock economics influence methionine. Diversification across these end uses improves resilience at the total-market level, but individual facilities can remain heavily exposed to a single derivative if they are built around one integrated production chain.
Feedstock and Energy Economics Affect Route Competitiveness
The Andrussow and BMA routes both use methane and ammonia and require high-temperature operation, while the BMA process is particularly energy intensive because the reaction is endothermic and heat must be supplied externally. Acrylonitrile co-product recovery follows a different economic logic because the HCN is generated alongside another primary product. Natural gas, ammonia, electricity, catalyst costs and acrylonitrile operating rates therefore influence the relative competitiveness of different HCN sources. Integrated producers with co-product streams or captive feedstocks can maintain a structural advantage during periods of volatile energy pricing.
Segment Analysis
By Production Route
The Andrussow Process remains the largest dedicated production route and accounts for an estimated 47% of market value in 2026. The process reacts methane, ammonia and oxygen over a platinum-group catalyst at high temperature and is widely used where large-scale direct HCN production is required. Its commercial advantage comes from established operating experience and integration with large chemical complexes, although yield and downstream purification requirements influence overall economics.
Acrylonitrile Co-product Recovery represents a substantial part of global supply. INEOS explicitly states that HCN is generated as a co-product during acrylonitrile manufacturing and is recovered and purified for conversion into useful derivatives. This route has a different cost structure from dedicated HCN synthesis because the economics are linked partly to acrylonitrile production rates and the value captured from recovering a stream that would otherwise require treatment.
The BMA Process is projected to record a CAGR of approximately 5.8% through 2031 from a smaller base. It produces HCN from methane and ammonia without oxygen and can achieve high HCN concentration and yield, but requires external heat input and more complex high-temperature equipment. The route remains relevant in integrated facilities where its process characteristics and downstream requirements justify the higher capital and energy intensity.
By Application
Sodium Cyanide represents the largest individual application and is estimated at approximately USD 0.67 billion in 2026. Gold mining provides the principal demand driver, and strong gold-sector economics are supporting capacity additions and plant optimization among major downstream producers. The segment is expected to increase its contribution through 2031 as mine development and lower ore grades support greater reagent consumption.
Adiponitrile accounts for roughly 25% of market value in 2026. Its importance comes from the scale of the nylon 66 chain rather than unusually high forecast growth. Automotive components, industrial fibres, electrical applications and engineering plastics continue to support demand, but the segment grows below the HCN market average and therefore loses limited share by 2031.
Acetone Cyanohydrin is projected to grow at approximately 1.4% annually through 2031. The application remains material because it feeds methyl methacrylate and acrylic materials, but the installed chain is mature and alternative MMA production technologies limit the pace of incremental HCN demand.
Methionine is one of the faster-growing derivative categories, supported by commercial feed production and the continued use of synthetic amino acids to improve feed efficiency. The segment gains modest share through the forecast period, while Chelates and Other Derivatives provide a smaller but diversified demand base across detergents, water treatment, pulp and paper, specialty chemicals and related applications.
By End-User
Chemicals & Petrochemicals remain the largest end-user grouping, with market value of approximately USD 1.02 billion in 2026. The category captures HCN consumed within intermediate chemical chains before the material reaches a final industry, including adiponitrile, acetone cyanohydrin and specialty derivatives. Its share moderates gradually through 2031 because mining and animal-nutrition-related demand grow faster.
Mining accounts for approximately 30% of market value in 2026 and is projected to increase its share over the forecast period. Sodium cyanide demand from gold extraction is the principal mechanism, supported by high gold prices, mine expansions and reagent requirements associated with lower ore grades.
Agriculture & Animal Nutrition is projected to grow at approximately 5.4% annually through 2031, supported principally by methionine and selected agrochemical intermediates. Metallurgy remains a smaller market linked to metal treatment and electroplating applications, while other uses include fumigation, specialty synthesis and niche industrial processes.
Geographical Outlook
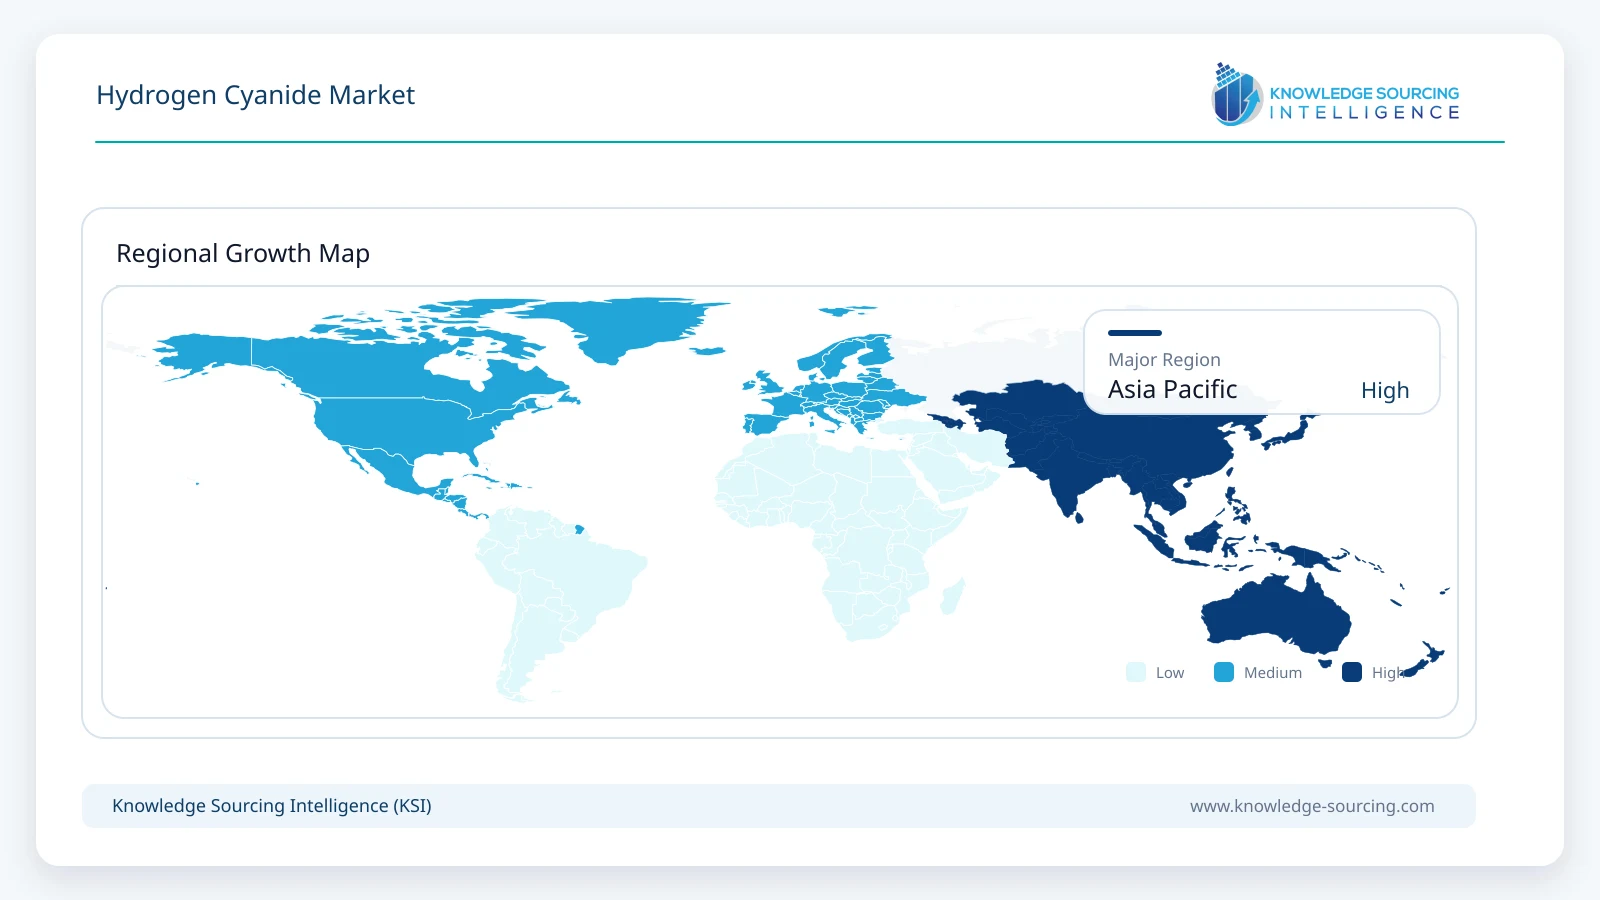
Asia Pacific accounts for approximately 38% of global market value in 2026 and is projected to increase its share through 2031. China remains a major chemical-production base, while India is moving toward greater domestic integration through the planned Balaji Speciality Chemicals HCN and sodium cyanide unit. Regional growth is also supported by mining, animal nutrition and expanding specialty-chemical manufacturing.
North America represents a market of approximately USD 0.59 billion in 2026. The region combines large integrated nitrile and nylon operations with important gold-mining sodium cyanide demand. INEOS, Ascend Performance Materials, Orica/Cyanco and other producers create a deep supply base spanning HCN, adiponitrile, acetone cyanohydrin and cyanide derivatives.
Europe is projected to grow at approximately 1.6% annually through 2031, below the global average. The region retains established chemical infrastructure and integrated methionine and specialty-chemical production, but mature industrial demand and stricter project economics limit the pace of new capacity. Middle East & Africa is expected to record the fastest regional growth, supported by mining investment and a smaller starting base, while South America remains closely linked to gold and other mineral-processing activity.
Recent Developments
In June 2026, Wesfarmers reported that the first phase of Australian Gold Reagents' sodium cyanide expansion had been delivered during the second half of FY26, increasing total production capacity by approximately 35,000 tonnes per year to around 130,000 tonnes per year. Wesfarmers stated that the expansion positions AGR among the larger sodium cyanide producers globally and retains further potential for capacity growth.
During the first half of 2026, Orica reported continued strong customer demand for sodium cyanide within a robust gold sector and confirmed completion of upgrades at the Winnemucca solids plant. The investment enables optimization across Orica's Winnemucca, Yarwun and Alvin production network and supports continued growth in its Specialty Mining Chemicals business.
Balaji Amines' 2026 annual report confirmed progress on the Rs 750 crore Balaji Speciality Chemicals expansion. Unit II at MIDC Chincholi is being developed to produce hydrogen cyanide, sodium cyanide, EDTA and EDTA-2Na and is expected to become operational toward the end of FY27. The project represents a notable move toward localized integrated HCN and cyanide production in India.
Competitive Environment
The Hydrogen Cyanide Market is concentrated around companies with integrated nitrile, nylon, methionine or specialty-chemical operations and the process-safety capability required to manufacture a highly toxic intermediate. INEOS Nitriles is a key participant because it recovers HCN as a co-product of acrylonitrile production and converts it into products including acetone cyanohydrin while identifying sodium cyanide, adiponitrile, chelates and methionine as major downstream derivatives. Ascend Performance Materials is another important integrated participant, listing HCN alongside acrylonitrile, adiponitrile and hexamethylene diamine within its intermediate-chemicals portfolio.
Evonik remains relevant through integrated HCN production associated with methionine manufacturing. Its site information shows HCN production integrated with methionine and related precursor chains, illustrating the captive-production model that characterizes much of the industry. Balaji Speciality Chemicals is emerging as a new participant in India through its planned HCN, sodium cyanide and EDTA complex. In downstream cyanide, Orica/Cyanco and Australian Gold Reagents are important because their capacity expansion directly increases the HCN-equivalent demand required to support gold-mining reagent production.
Competitive advantage depends on feedstock integration, process reliability, safety performance, proximity to downstream conversion and security of supply rather than consumer-facing branding. Producers that control both HCN and derivative capacity can reduce transport risk and capture more value from the molecule. The market therefore favours integrated chemical companies and specialized cyanide producers with long operating histories, established customer relationships and strong hazardous-material management systems.
Analyst View
The Hydrogen Cyanide Market should not be evaluated as a conventional merchant chemical market. A large proportion of HCN is generated and consumed within integrated production chains, and the commercial opportunity is created by the value of downstream conversion rather than by long-distance HCN trade itself.
Sodium cyanide provides the strongest large-scale incremental growth opportunity because gold-sector economics continue to support reagent demand and new downstream capacity. Methionine provides another above-market-growth channel, while adiponitrile maintains a substantial but more mature base and acetone cyanohydrin grows more slowly. This differentiated growth profile means the market gradually shifts toward mining and animal-nutrition-related demand even though chemical intermediates remain the largest overall end-use grouping.
The strongest investment case through 2031 is therefore integrated localization. New projects that combine HCN production with sodium cyanide, methionine, chelates or other derivatives can reduce transport exposure and respond directly to regional demand. Asia Pacific is positioned to capture a growing share of this investment, while North America retains a major installed base and Europe remains important through established specialty-chemical and methionine chains. Producers that combine process technology, downstream integration and strong safety performance are likely to remain the most competitive participants in the market.
Hydrogen Cyanide Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.17 billion |
| Total Market Size in 2031 | USD 2.60 billion |
| Forecast Unit | Billion |
| Growth Rate | 3.68% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Production Route, Application, End-User, Geography |
| Companies |
|
Market Segmentation
By Production Route
Andrussow Process
BMA Process
Acrylonitrile Co-product Recovery & Other Routes
By Application
Sodium Cyanide
Adiponitrile
Acetone Cyanohydrin
Methionine
Chelates and Other Derivatives
By End-User
Mining
Metallurgy
Agriculture & Animal Nutrition
Chemicals & Petrochemicals
Others
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Others
Middle East & Africa
Saudi Arabia
UAE
Israel
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Thailand
Taiwan
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
5. HYDROGEN CYANIDE MARKET BY PRODUCTION ROUTE
5.1. Introduction
5.2. Andrussow Process
5.3. BMA Process
5.4. Acrylonitrile Co-product Recovery & Other Routes
6. HYDROGEN CYANIDE MARKET BY APPLICATION
6.1. Introduction
6.2. Sodium Cyanide
6.3. Adiponitrile
6.4. Acetone Cyanohydrin
6.5. Methionine
6.6. Chelates and Other Derivatives
7. HYDROGEN CYANIDE MARKET BY END-USER
7.1. Introduction
7.2. Mining
7.3. Metallurgy
7.4. Agriculture & Animal Nutrition
7.5. Chemicals & Petrochemicals
7.6. Others
8. HYDROGEN CYANIDE MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. Germany
8.4.2. France
8.4.3. United Kingdom
8.4.4. Spain
8.4.5. Others
8.5. Middle East & Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Israel
8.5.4. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Indonesia
8.6.6. Thailand
8.6.7. Taiwan
8.6.8. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. INEOS Nitriles
10.2. Ascend Performance Materials
10.3. Evonik Industries AG
10.4. Balaji Speciality Chemicals Limited
10.5. Orica Limited
10.6. Australian Gold Reagents
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











