Optical Satellite Communication Market - Strategic Insights and Forecasts (2026-2031)
Optical Satellite Communication Market Size, Growth, Share, Forecasts and Trends Analysis By System Component (Spaceborne Optical Communication Terminals, Optical Ground Stations, Modems and Link Electronics, Pointing, Beam-Control and Adaptive-Optics Systems, Others), Link Type (Inter-Satellite Links, Space-to-Ground and Ground-to-Space Links, Deep-Space and Data-Relay Links), Deployment Type (New Satellite Integration, Hosted Payload and Retrofit Integration), Orbit Type (Low Earth Orbit, Medium Earth Orbit, Geostationary Orbit, Highly Elliptical, Cislunar and Other Orbits), End User (Government and Defense, Commercial Satellite Operators and Service Providers, Civil Space Agencies and Research, Others), and Geography
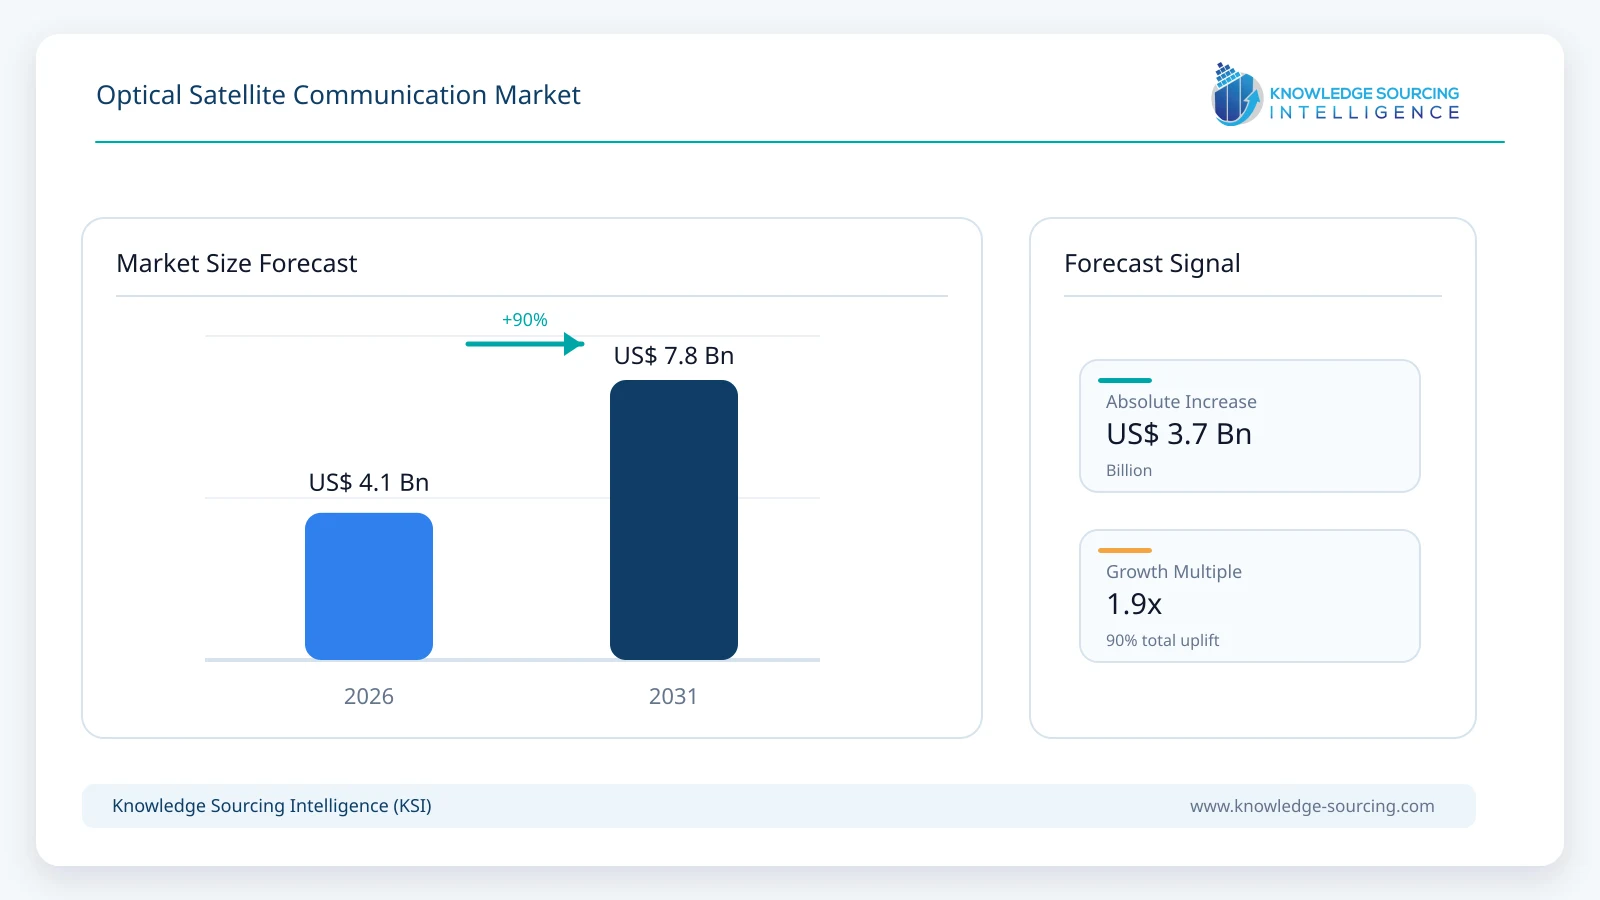
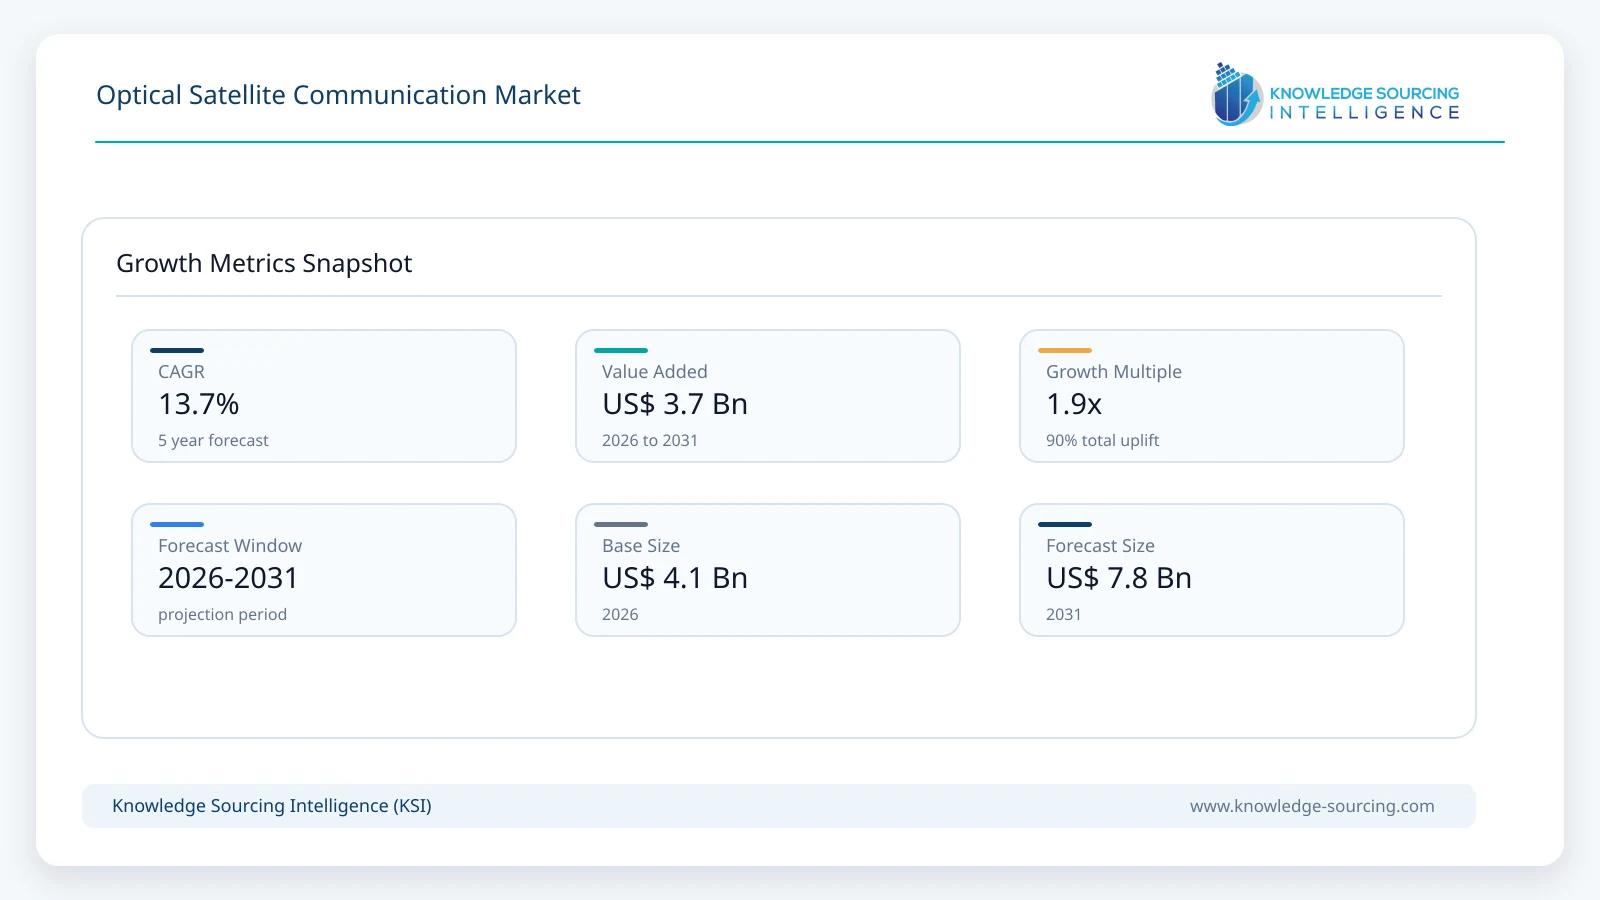
The global optical satellite communication market is estimated at approximately USD 4.1 billion in 2026 and is projected to reach approximately USD 7.8 billion by 2031, representing a CAGR of about 13.7% during the forecast period.
Highlights:
1
Spaceborne optical terminals account for approximately 55% of market value during 2026.
2
New satellite integration represents about 86% of 2026 demand as constellations scale.
3
Inter-satellite links contribute roughly 58% of 2026 spending across optical networks.
4
LEO platforms account for about 68% of 2026 demand, led by proliferated constellations.
5
Government and defense users represent approximately 46% of optical satellite communication spending.
6
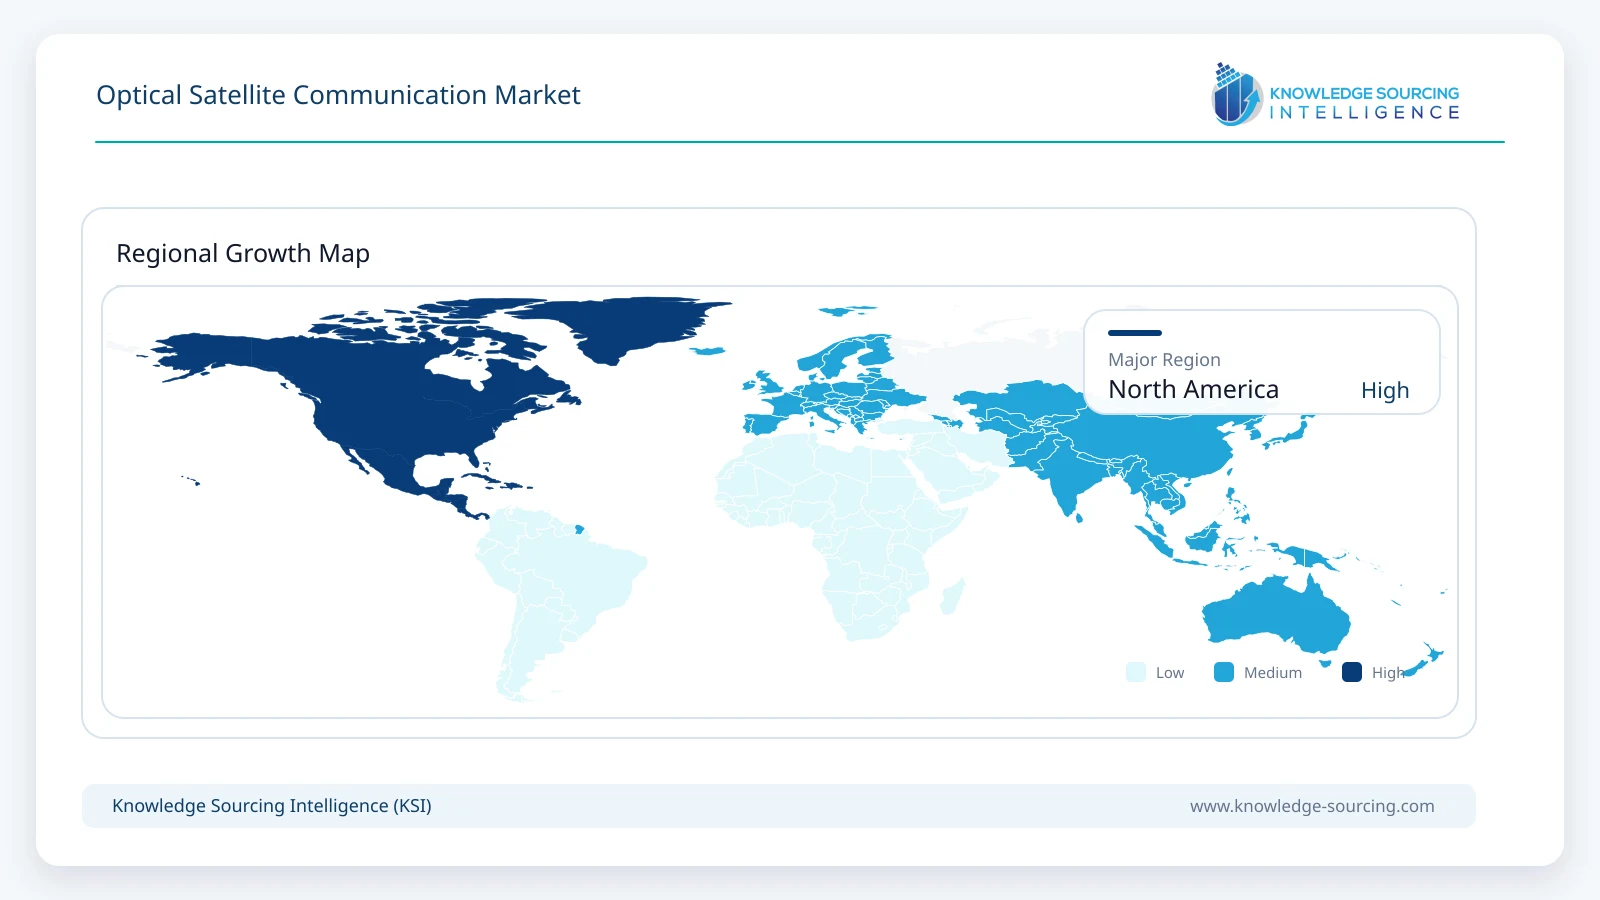
North America contributes about 47% of 2026 revenue through defense and commercial deployments.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Optical satellite communication uses tightly focused laser beams rather than radio-frequency carriers to move large volumes of information through space. The narrow beam supports high data rates and reduces susceptibility to interference or interception, while smaller optical apertures can lower size, weight and power requirements for selected missions. These advantages are increasingly important as Earth-observation satellites generate higher-resolution imagery, defense constellations require resilient crosslinks, and commercial operators seek to move data between satellites without routing every transmission through terrestrial gateways. NASA has demonstrated 200 Gbps direct-to-Earth optical transmission through TBIRD, while its Artemis II optical communications system launched in April 2026 and supported high-definition data transfer from a crewed deep-space mission.
The market is becoming an operational infrastructure layer rather than a collection of isolated technology demonstrations. The U.S. Space Development Agency maintains Optical Communications Terminal standards intended to support interoperability across vendors and domains, while commercial networks are adopting compatible terminal architectures. Kepler Communications launched the first tranche of its optical data-relay constellation in January 2026 and reported commercial service delivery by August. SpaceX operates inter-satellite lasers at constellation scale and is extending the same technology to other missions, including NASA's planned Artemis III optical downlink. ESA is simultaneously advancing HydRON, optical ground-station networks and mass-production programs intended to create a multi-orbit European optical communications ecosystem.
Supply is also consolidating around companies capable of production-scale terminals, precision pointing, ground infrastructure and network integration. Rocket Lab completed the acquisition of Mynaric in April 2026 and is scaling its laser-terminal manufacturing base in Germany. TESAT is expanding from LEO-focused terminals into MEO and GEO applications, while CACI is progressing next-generation terminals for U.S. national-security programs. Cailabs, SSC Space and KSAT are building operational optical ground capacity, and newer relay-network operators are beginning to monetize low-latency optical connectivity as a service.
Market Trends
Interoperability Is Becoming a Core Procurement Requirement
The move from bespoke point-to-point demonstrations toward networked constellations is increasing the value of standardized optical interfaces. SDA has released Optical Communications Terminal standards designed to maintain backward compatibility while supporting future capabilities across space, terrestrial, maritime and airborne platforms. For constellation buyers, interoperability reduces dependence on a single terminal supplier and enables spacecraft procured from different primes to participate in a common mesh network. This is shifting competition toward terminals that can pass cross-vendor testing, support defined acquisition and tracking behavior, and integrate standardized modems and network-management interfaces. CACI, TESAT, Rocket Lab's Mynaric business, Kepler and General Atomics are among the companies aligning products or programs with SDA-compatible architectures, while ESA is also emphasizing interoperability through HydRON and ESTOL-related initiatives.
Terminal Manufacturing Is Moving Toward Constellation-Scale Production
Optical communications economics change substantially when terminals move from low-volume spacecraft programs to hundreds or thousands of repeat units. Suppliers are responding with modular designs, repeatable assembly, automated test processes and higher-volume production lines. Rocket Lab has stated that it intends to use its manufacturing and supply-chain capabilities to increase Mynaric production after completing the acquisition in April 2026. TESAT is broadening its product family from compact LEO terminals to the SCOT135 for MEO and GEO missions, while Skyloom and NEC have been developing 100 Gbps-class optical terminals for multi-orbit networks. These developments support a market where unit costs can fall even as aggregate terminal revenue grows because the number of optical links per satellite and the number of optically networked spacecraft increase.
Optical Ground Stations Are Emerging as Shared Infrastructure
Cloud cover, atmospheric turbulence and the need for geographically distributed access make the ground segment a critical part of commercial optical communications. The industry is increasingly addressing this through networks of optical ground stations rather than single mission-specific sites. Cailabs launched an Optical Ground Station-as-a-Service model in September 2026 and is building manufacturing capacity for substantially higher station output. SSC Space has deployed optical ground stations in Australia and Chile, KSAT is combining optical and RF relay services, and ESA is funding next-generation ground-station programs intended for mass production. Managed networks allow satellite operators to buy optical capacity without building their own global ground infrastructure, improving utilization rates and lowering the entry barrier for Earth-observation, research and sovereign missions.
Optical Links Are Expanding Beyond LEO Crosslinks
LEO remains the center of current demand, but optical communications are expanding into MEO, GEO, lunar and deep-space applications. TESAT delivered its first SCOT135 terminal in March 2026 for links extending to approximately 80,000 kilometers. Thales Alenia Space, Safran, CNES and Hellas Sat are developing an optical communications system for the future Hellas Sat 5 GEO satellite, while NASA continues to build on deep-space laser demonstrations. ESA's HydRON concept is designed around optical data movement across multiple orbital layers rather than a single constellation. This broadening of mission profiles increases demand for higher-power terminals, more capable pointing systems, adaptive optics and ground infrastructure capable of serving different ranges, wavelengths and network protocols.
Defense and government programs are major early adopters because optical crosslinks combine high capacity with narrow beams that are difficult to intercept or jam compared with broad radio-frequency transmissions. The Space Development Agency's proliferated architecture requires standardized optical links across large numbers of satellites, creating repeat demand for terminals and interoperability testing. CACI advanced to Phase 3 of the U.S. Space Force Enterprise Space Terminal program in May 2026, while General Atomics continues to integrate SDA-compatible optical terminals into resilient satellite platforms. Similar requirements are emerging among allied defense and sovereign connectivity programs, supporting demand for space-to-space and transportable space-to-ground optical systems.
Earth Observation and On-Orbit Computing Increase Data-Movement Requirements
Higher-resolution imaging, hyperspectral sensing, synthetic-aperture radar and onboard artificial-intelligence processing are increasing the amount of useful data generated in orbit. Optical links allow satellites to move that data across a constellation or toward suitable ground locations without waiting for the next direct RF ground-station pass. Kepler's operational optical relay network combines inter-satellite links with onboard computing, enabling missions to process and route information closer to where it is generated. As sensor capability and onboard compute increase, communications capacity becomes a system constraint, strengthening the commercial case for optical crosslinks and data-relay services.
Spectrum Constraints and Spacecraft SWaP Favor Optical Architectures
Radio-frequency satellite networks face spectrum-coordination requirements, interference risks and antenna-size constraints as constellations scale. Optical links use much narrower beams and can deliver high throughput with smaller apertures for many mission profiles. This can improve size, weight and power efficiency while reducing pressure on congested RF spectrum. The advantage is particularly relevant to small satellites and high-density constellations. AAC Clyde Space's CubeCAT illustrates the small-satellite opportunity with a compact optical terminal designed for gigabit-class direct-to-Earth links, while Sony Space Communications is pursuing miniaturized optical equipment intended for small spacecraft and relay networks.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Market Restraints
Atmospheric Availability, Precision Pointing and Qualification Remain Major Barriers
Optical communication offers substantial bandwidth advantages but requires accurate pointing, acquisition and tracking because the transmitted beam is extremely narrow. Space-to-ground links also remain vulnerable to clouds, turbulence, scintillation and local weather conditions, which makes geographic diversity and hybrid RF-optical architectures important for reliable service. Hardware must survive launch loads, radiation and thermal cycling while maintaining optical alignment, and multi-vendor networks require rigorous interoperability testing. These factors raise engineering and qualification costs, particularly for new suppliers, while shortages of space-qualified photonics, precision mechanisms and specialist manufacturing capacity can constrain rapid production scaling.
Optical Satellite Communication Market Segment Analysis
By System Component
Spaceborne Optical Communication Terminals
Spaceborne optical communication terminals form the largest system component because every optical crosslink or direct optical downlink requires flight-qualified transmit, receive, beam-steering, pointing and control hardware. The segment is projected to approach approximately USD 4.5 billion by 2031 as commercial and defense constellations increase terminal counts per satellite and as higher-capacity terminals move into MEO and GEO missions. Optical ground stations remain strategically important and grow rapidly as commercial managed networks expand, while modems, adaptive optics and network-control systems provide additional value around the terminal hardware.
By Link Type
Inter-Satellite Links
Inter-satellite links remain the largest link type because proliferated constellations use optical crosslinks to route data across orbital planes, reduce dependence on continuous ground visibility and create low-latency mesh networks. The segment is projected to reach approximately USD 4.9 billion by 2031. Space-to-ground and ground-to-space links also expand rapidly as Earth-observation operators seek higher downlink capacity and optical ground-station networks become more accessible. Deep-space optical links remain smaller in commercial value but continue to advance through NASA and international space-agency programs.
By Deployment
New Satellite Integration
New-build satellite integration dominates deployment because optical terminals are most efficiently incorporated during spacecraft design, when power, thermal, structural and pointing requirements can be optimized around the terminal. Revenue associated with new satellite integration is projected to reach approximately USD 6.8 billion by 2031. Hosted payloads and retrofit-type deployments remain important for technology demonstrations, relay services and selected larger satellites, but modifying an existing spacecraft architecture generally carries higher integration constraints than designing optical connectivity into a new platform.
By Orbit Type
Low Earth Orbit
Low Earth orbit is the largest orbit segment and is projected to generate approximately USD 5.6 billion by 2031. LEO contains the highest concentration of broadband, Earth-observation and defense constellations, and its shorter link distances support compact terminals and high-capacity optical crosslinks. MEO and GEO applications grow from a smaller base as suppliers introduce higher-power multi-orbit terminals and operators evaluate optical data relay and direct-to-Earth services. Cislunar and deep-space applications remain strategically important but represent a comparatively small commercial revenue pool during the forecast period.
Government and defense remain the largest end-user segment, supported by secure communications, missile warning, intelligence, surveillance and reconnaissance requirements and sovereign space-network investment. The segment is projected to exceed approximately USD 3.3 billion by 2031. Commercial operators grow at a faster rate as optical crosslinks become standard in large constellations and commercial relay services mature, narrowing the gap with government spending. Civil space agencies and research organizations continue to support deep-space, science and interoperability programs that create important technology spillovers for the broader market.
By Geography
North America
North America remains the largest regional market and is projected to generate approximately USD 3.4 billion by 2031. The United States combines SDA and Space Force procurement, NASA technology adoption, SpaceX's constellation-scale laser deployment, Amazon Leo optical-network development and a dense supplier base spanning terminals, spacecraft and ground infrastructure.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Europe is the second major technology cluster through ESA ScyLight, HydRON, TESAT, Cailabs, Thales Alenia Space, Safran and emerging relay networks. Asia Pacific expands through Japanese optical-terminal development, national space programs, commercial constellations and new optical ground infrastructure in countries including South Korea and Australia.
Competitive Environment
Competition is moving from technology demonstration toward repeatable manufacturing, interoperability and service delivery. Rocket Lab now owns Mynaric following completion of the acquisition in April 2026 and is positioning the business as a scaled laser-terminal supplier. TESAT has one of the broadest optical-terminal portfolios across LEO, MEO and GEO applications. CACI competes strongly in U.S. national-security optical terminals, while General Atomics integrates SDA-compatible optical capabilities into satellite platforms. SpaceX remains the most visible vertically integrated operator because inter-satellite lasers are deployed at constellation scale and are being offered for partner integration through Starshield.
The ground and network layers are also becoming more competitive, with players like Cailabs scaling optical ground-station manufacturing and managed services, while KSAT and SSC Space developing hybrid RF-optical ground networks. Kepler Communications is operating a commercial optical relay constellation, and Airbus with Space Compass is developing space-based optical connectivity services. Thales Alenia Space and Safran are advancing GEO optical links, NEC and Skyloom are developing high-rate terminals, and AAC Clyde Space targets compact optical terminals for small satellites. Sony Space Communications continues to develop miniaturized optical networking technology. Ball Corporation is not treated as a standalone competitor because Ball Aerospace was acquired by BAE Systems in 2024; relevant space capabilities now sit within BAE Systems Space & Mission Systems.
Recent Developments
September 2026: NTT and Cailabs signed an agreement to explore direct optical connectivity between satellite networks, optical ground stations and terrestrial all-photonic infrastructure.
September 2026: Cailabs began demonstrating its first transportable optical ground station with Gilat DataPath and outlined an initial production series for 2027.
September 2026: Kepler secured launch capacity for ten additional Tranche-2 optical relay satellites as it prepared to expand its operational data-relay network.
August 2026: ESA selected a Lumino Technologies-led consortium to develop mass-production-ready optical and quantum ground stations under the NG-OGS Accelerator project.
August 2026: Kepler reported that its first optical data-relay tranche had entered commercial service for government and commercial customers.
July 2026: NASA selected SpaceX Starlink mini laser terminals to support high-bandwidth imagery and video downlinks for the Artemis III mission.
May 2026: CACI advanced to Phase 3 of the U.S. Space Force Enterprise Space Terminal program for next-generation optical communications terminals.
April 2026: Rocket Lab completed its acquisition of Mynaric and announced plans to scale laser optical communication terminal production.
March 2026: TESAT delivered its first SCOT135 optical communication terminal for MEO and GEO missions with link distances up to 80,000 kilometers.
February 2026: Thales Alenia Space, Safran, CNES and Hellas Sat agreed to develop a next-generation GEO optical communications system for Hellas Sat 5.
Optical Satellite Communication Market Scope:
Report Metric
Details
Total Market Size in 2026
USD 4.1 billion
Total Market Size in 2031
USD 7.8 billion
Forecast Unit
Billion
Growth Rate
13.7%
Study Period
2021 to 2031
Historical Data
2021 to 2024
Base Year
2025
Forecast Period
2026 – 2031
Segmentation
System Component, Link Type, Deployment, Orbit Type, End User, Geography