
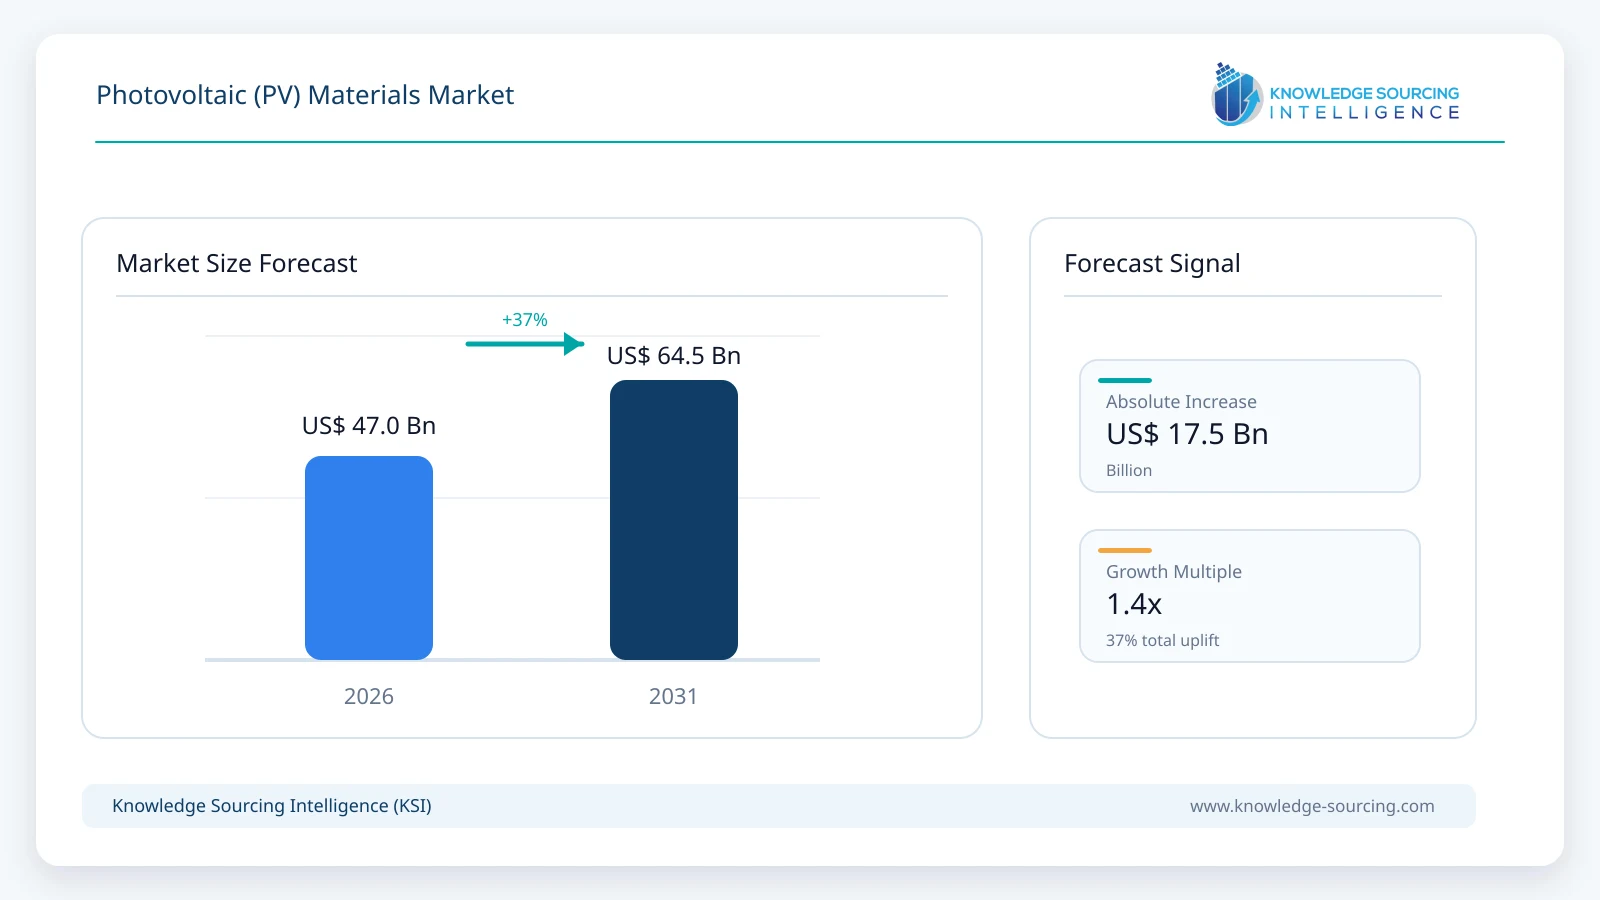
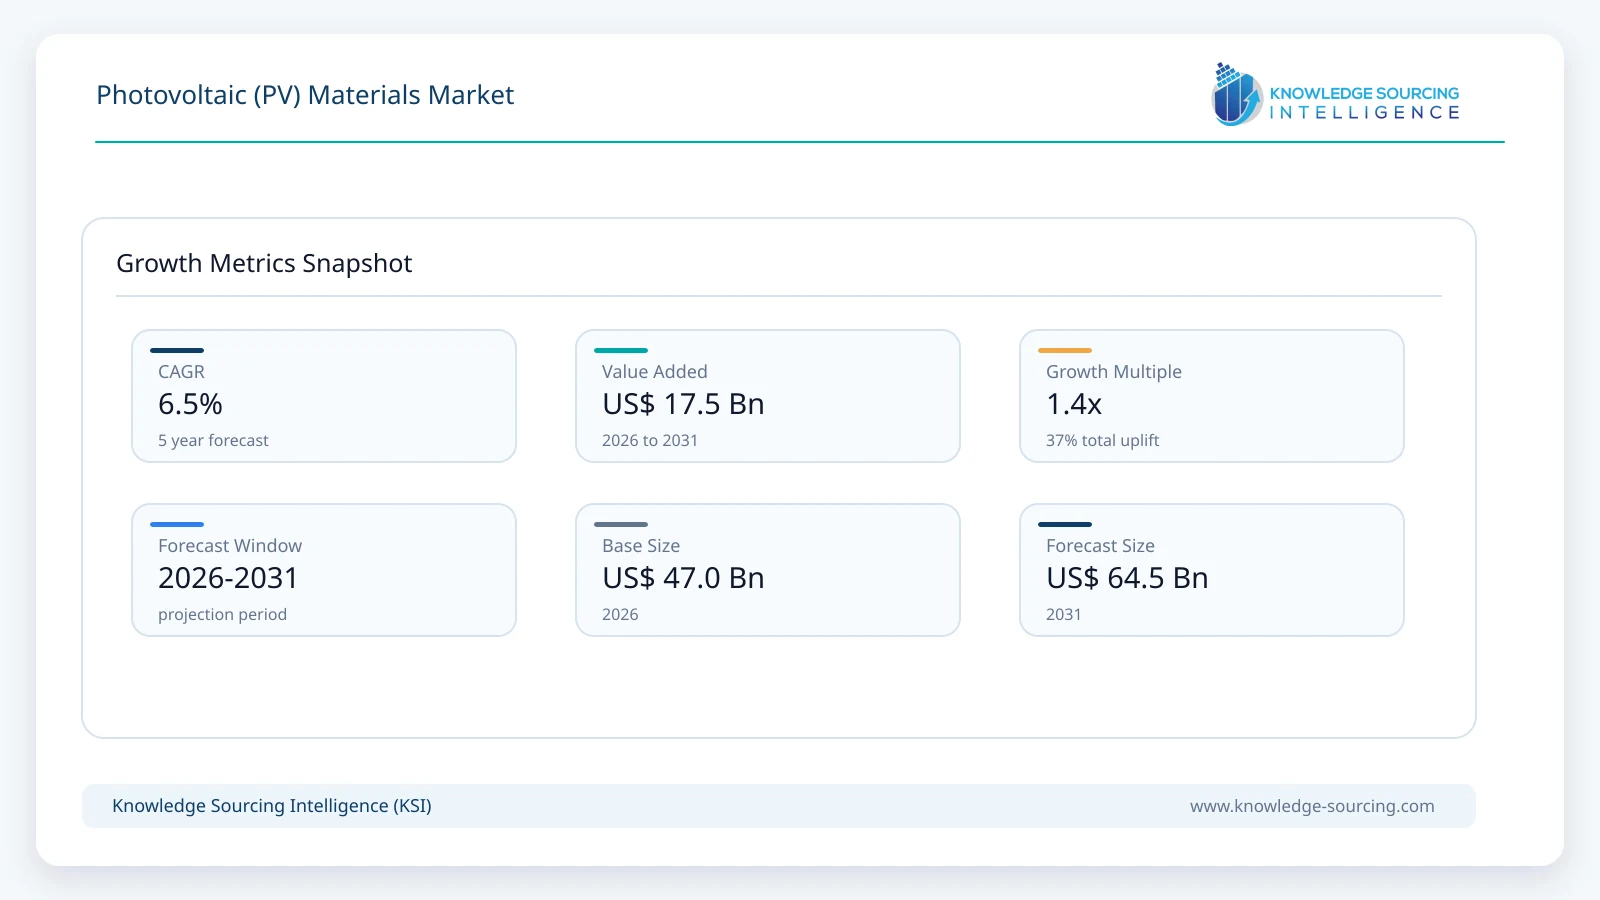
The global photovoltaic (PV) materials market is forecast to grow from USD 47.0 billion in 2026 to USD 64.5 billion in 2031, representing a CAGR of 6.5% during the forecast period.
Highlights:
- 1Silicon and semiconductor materials account for approximately 24.0% of global PV materials revenue in 2026.
- 2Utility-scale solar applications represent approximately 61.0% of global PV materials demand by value in 2026.
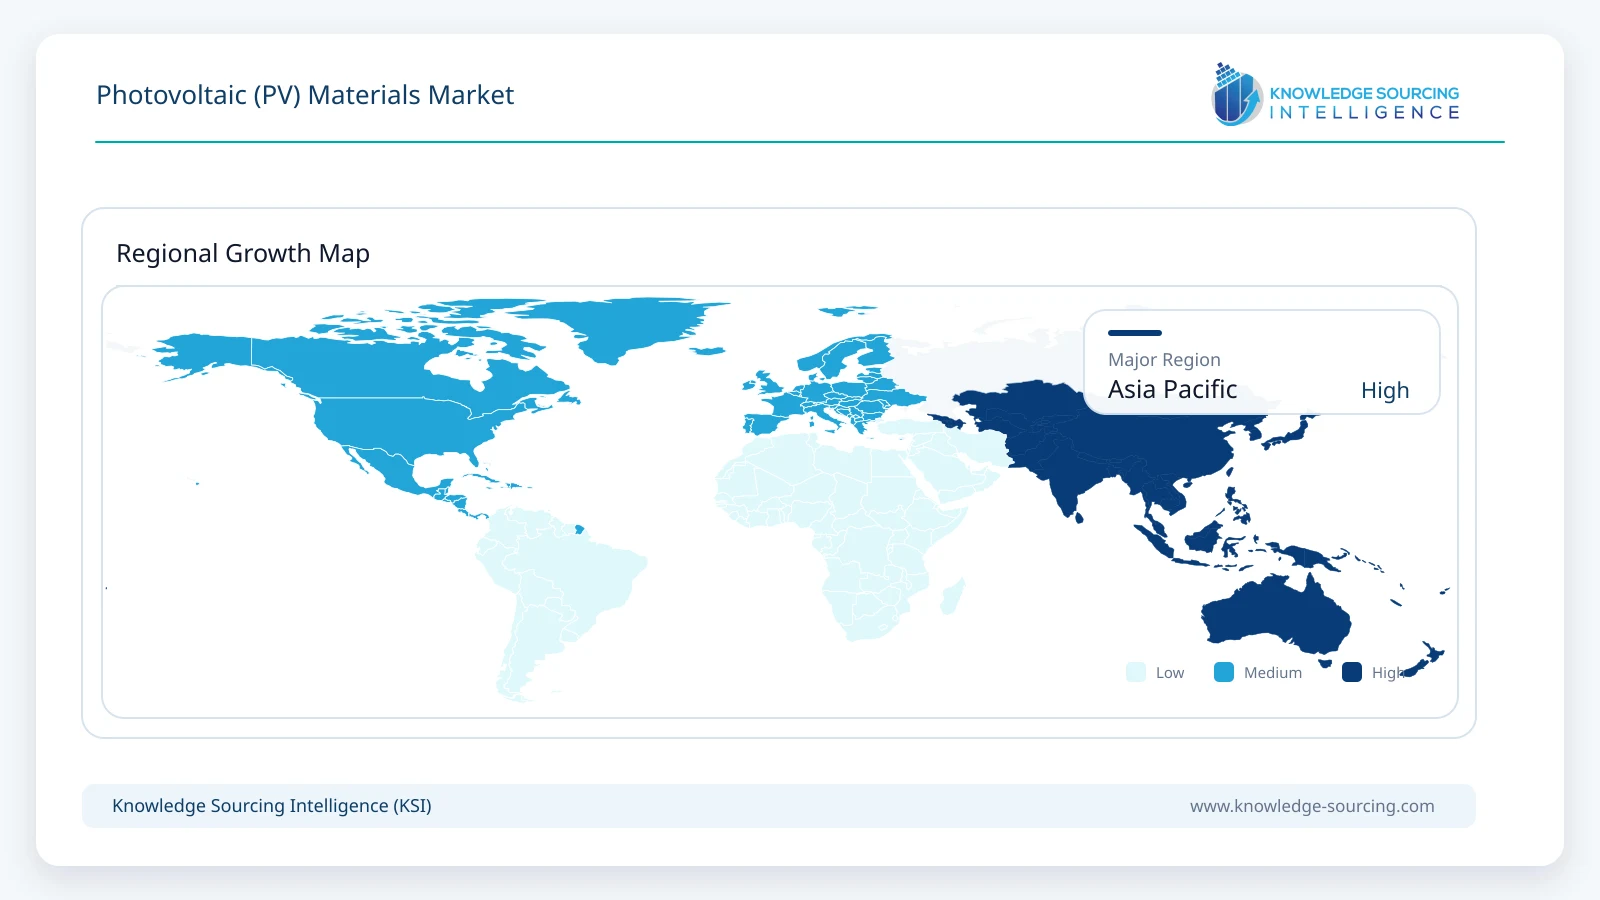
- 3Asia Pacific accounts for approximately 76.0% of global PV materials revenue in 2026, reflecting the concentration of cell and module manufacturing.
- 4Global PV installations reached about 690 GW in 2025, increasing material consumption even as per-watt material intensity and prices continued to decline.
- 5PV glass, encapsulants, metallization materials, backsheets and aluminum framing now represent material pools comparable in strategic importance to silicon feedstock.
- 6Material innovation is increasingly focused on silver reduction, copper substitution, POE/EPE encapsulation, dual-glass architectures, lower-carbon silicon and higher recyclability.
Market Overview
The photovoltaic materials market covers raw and semi-processed materials consumed directly in the manufacture of photovoltaic cells and modules. The scope includes solar-grade polysilicon and other semiconductor absorber materials, photovoltaic glass, encapsulants such as EVA, POE and EPE, backsheets and protective films, metallization pastes and interconnect metals, aluminum frame materials, adhesives, sealants and other module-level materials. Finished wafers, cells, modules, inverters, trackers, mounting systems, batteries and installation services are excluded to avoid double counting component and system value.
Global PV deployment reached another record scale in 2025. IEA PVPS reports approximately 690 GW of new PV capacity installed during the year, taking cumulative global capacity to about 2.96 TW. This deployment base creates very large recurring demand for material inputs even though module prices and material intensity per watt continue to decline. The market therefore grows more slowly in value than PV installation volumes.
The material mix has also changed. Crystalline silicon remains the dominant technology, but the economic value of the module stack is spread across several categories. Xinyi Solar reported RMB 17.83 billion of solar-glass revenue in 2025, while WACKER's Polysilicon division generated EUR 882.9 million and GCL Technology reported RMB 14.43 billion of group revenue with granular silicon remaining its core business. Hangzhou First Applied Material, RenewSys, DuPont, Dow and Arkema supply encapsulation and protective materials, while Heraeus remains a major supplier of photovoltaic metallization pastes.
The existing market is under significant price pressure. WACKER reported lower solar-grade polysilicon prices and volumes in 2025, while Xinyi Solar also reported lower average selling prices for solar glass despite volume growth. Similar dynamics affect encapsulants and other high-volume materials. For that reason, the 2026-2031 forecast is based on rising PV manufacturing volumes offset by continued material efficiency, substitution and competitive pricing rather than on an extension of historical double-digit material-value growth.
Technology choices will increasingly influence future material demand. IEA PVPS' 2026 material-flow assessment highlights silver and indium as particularly sensitive to technology pathways, with copper substitution potentially reducing silver demand materially. Meanwhile, dual-glass modules, n-type cells and higher-efficiency designs are shifting demand among glass, encapsulants, metallization pastes and backsheet materials. Recycling will also become a more meaningful secondary source over time, particularly for silver and aluminum.
Photovoltaic Materials Market Trends
Silver Thrifting and Copper Substitution Reshape Metallization
Silver remains one of the most valuable materials in crystalline-silicon cell production, but manufacturers continue to reduce silver consumption per watt through finer metallization, multi-busbar and zero-busbar designs and alternative conductor systems. IEA PVPS identifies silver substitution with copper-based metallization as an important pathway for reducing future resource pressure. This creates a market in which installed PV volumes grow rapidly while silver paste consumption per watt can decline.
POE and EPE Gain Share in Encapsulation
EVA remains widely used, but POE and co-extruded EPE structures are gaining importance in n-type and glass-glass modules because of improved resistance to potential-induced degradation, moisture and acid formation. Dow continues to commercialize ENGAGE PV POE, while FIRST and RenewSys offer broad POE/EPE portfolios. Encapsulation is therefore becoming a higher-specification material category rather than a commodity film market alone.
Dual-Glass Designs Increase Solar-Glass Intensity
Bifacial and utility-scale modules increasingly use glass-glass construction, raising glass area per module compared with conventional glass-backsheet designs. Xinyi Solar's 22,600-tonne-per-day operating capacity as of June 2026 illustrates the scale of the global PV glass market. This shift supports glass demand even as module thickness reduction and lightweighting lower kilograms of glass per watt.
Low-Carbon Materials Become a Procurement Criterion
Module buyers and regulators are paying greater attention to embodied carbon and traceability. GCL Technology reports a verified low carbon footprint for granular silicon, while OCI TerraSus uses hydroelectric power for Malaysian polysilicon production. Similar differentiation is emerging in glass, encapsulants and backsheets as customers increasingly evaluate lifecycle emissions alongside price and performance.
Recycling Moves from Waste Management to Material Recovery
IEA PVPS' 2026 recycling and material-flow work shows that retired modules can become an increasingly relevant secondary source of silver, aluminum, glass and silicon. Recycling is not yet large enough to displace primary materials materially, but improving purity and recovery economics are beginning to influence material design and end-of-life requirements.
Segment Analysis
By Material Type - Silicon and Semiconductor Materials
Silicon and semiconductor materials are estimated at approximately USD 11.28 billion in 2026. The segment includes solar-grade polysilicon and other photovoltaic absorber materials consumed in cell manufacturing, including cadmium telluride and smaller volumes of other compound-semiconductor inputs. Crystalline silicon remains the dominant global PV technology, and n-type cell architectures are increasing purity requirements even as grams of silicon per watt continue to fall. Large suppliers such as GCL Technology, WACKER, Daqo, OCI TerraSus and Xinte Energy operate at substantial scale, but persistent overcapacity and lower selling prices constrain value growth. Through 2031, rising cell output should offset continuing reductions in material intensity, keeping silicon and semiconductor materials the largest individual material category by revenue.
By Application - Utility-Scale Solar
Utility-scale solar applications are estimated at approximately USD 28.67 billion in 2026. The segment consumes the largest volume of PV materials because ground-mounted projects account for the majority of annual PV capacity additions and typically use large-format modules in very high quantities. Utility modules increasingly employ bifacial n-type cells, dual-glass construction, POE or EPE encapsulation, high-performance metallization and aluminum framing designed for long operating lives. The scale of projects in China, India, the United States, the Middle East and Latin America drives bulk demand across the entire material stack. Utility procurement also accelerates material optimization because small reductions in silver, silicon, glass thickness or frame weight create significant cost savings when multiplied across gigawatt-scale orders.
By Geography - Asia Pacific
Asia Pacific is estimated at approximately USD 35.72 billion in 2026. The region dominates the PV materials market because China and neighboring Asian economies contain the majority of global wafer, cell and module manufacturing capacity as well as major upstream suppliers of polysilicon, solar glass, encapsulants, backsheets and metallization materials. China installed 415 GW of PV in 2025 and remains the largest manufacturing hub, while India is rapidly expanding domestic cell and module capacity and related material supply. Xinyi Solar, GCL Technology, Daqo, Xinte Energy, FIRST, Cybrid, RenewSys and several other leading material suppliers operate large Asian production footprints. Regional dominance is expected to persist through 2031 despite growing manufacturing localization in the United States, Europe and the Middle East.
Market Drivers
Record Global PV Deployment
IEA PVPS reports approximately 690 GW of PV additions in 2025, providing a very large and growing volume base for cell and module materials. Even moderate future installation growth translates into substantial incremental demand for glass, encapsulants, silicon, metals and protective materials.
Transition to N-Type and Higher-Efficiency Cells
TOPCon, heterojunction and back-contact architectures require changes in metallization, encapsulation and cell materials. N-type growth supports higher-specification POE/EPE films, new silver-paste formulations and alternative interconnect technologies.
Growth of Bifacial and Glass-Glass Modules
Bifacial modules and long-life utility designs are increasing use of dual-glass structures. This supports photovoltaic glass demand and changes encapsulant requirements, particularly for moisture and PID resistance.
Manufacturing Localization
The United States, India and other markets are expanding domestic PV manufacturing through incentives, tariffs and procurement rules. New module and cell capacity creates regional demand for encapsulants, glass, backsheets, metallization pastes and silicon feedstock.
Material Innovation and Reliability Requirements
Manufacturers are seeking lower degradation, higher power retention and longer warranties. Material suppliers can therefore capture value through improved barrier films, lower-acid encapsulants, advanced coatings and optimized metallization systems.
Market Restraints
Severe Price Pressure Across the PV Supply Chain
Overcapacity in polysilicon, glass and modules has compressed selling prices. Material volume can therefore rise substantially without producing equivalent revenue growth.
Continuing Material Thrifting
Cell and module manufacturers systematically reduce grams of silicon, silver, aluminum and other materials per watt. Efficiency improvements lower cost but reduce material intensity.
Commodity Input Volatility
Silver, aluminum, copper, soda ash, energy and polymer feedstocks can experience significant price swings. These movements affect supplier margins and can create short-term volatility in market value.
Technology Substitution
Copper metallization, thinner glass, frameless module designs and alternative encapsulation structures can displace established materials. Suppliers must continually adapt portfolios to changing cell and module architectures.
Trade and Supply-Chain Restrictions
Tariffs, traceability requirements and local-content rules can alter material flows and increase qualification costs, particularly for polysilicon and other upstream materials linked to geographically concentrated supply chains.
Competitive Landscape
The PV materials market is fragmented across distinct material categories rather than dominated by one integrated supplier group. GCL Technology, WACKER, Daqo, OCI TerraSus and Xinte Energy are important polysilicon suppliers; Xinyi Solar and Flat Glass Group lead photovoltaic glass; FIRST, Cybrid and RenewSys compete in encapsulation and backsheet materials; DuPont, Dow and Arkema provide specialized polymers and protective materials; and Heraeus is a major supplier of metallization pastes.
Scale, process efficiency and qualification with major cell or module manufacturers are critical competitive factors. Material suppliers must meet tight specifications for optical transmission, adhesion, purity, electrical performance, thermal behavior and long-term reliability. Because module warranties often extend 25 to 30 years, suppliers with field-proven materials and strong qualification records can maintain strategic positions even in highly price-competitive markets.
Competition is increasingly shaped by technology transitions. N-type and zero-busbar architectures alter silver-paste and interconnect requirements, while glass-glass modules change backsheet demand and increase the role of POE/EPE encapsulation. Low-carbon production and traceability are also becoming differentiators, particularly for suppliers serving Europe and the United States.
Recent Developments
September 2026: IEA PVPS published a new material-flow assessment for silicon-based PV, highlighting silver substitution, indium constraints and the future role of recovered materials in terawatt-scale deployment.
July 2026: Xinyi Solar reported 22,600 tonnes per day of photovoltaic-glass melting capacity in operation, including capacity in Malaysia and Indonesia, as it continued geographic diversification of production.
July 2026: RenewSys hosted its second Anusandhan PV Encapsulants & Backsheets Technology Conclave, focusing on next-generation module materials, reliability and manufacturing technologies.
February 2026: DuPont announced that its Tedlar PVF film manufacturing operations in the United States were being matched with 100% renewable electricity through renewable-energy certificates.
January 2026: RenewSys launched CONSERV AUGMENSHEET, an encapsulant sheet designed specifically for insulation and sealing around solar-module busbar and junction-box areas.
2026: GCL Technology reported further progress in low-carbon granular silicon, with its product receiving third-party lifecycle verification and being positioned for high-efficiency n-type PV applications.
Market Outlook
The photovoltaic materials market is expected to expand steadily through 2031 as global PV manufacturing remains at very high volumes. Market value growth will remain slower than installation growth because material intensity per watt continues to decline and competitive pressure limits selling prices.
Silicon and semiconductor materials will remain the largest individual category, but solar glass, encapsulants and metallization materials will capture a growing share of technology attention as module architectures evolve. Silver reduction, copper substitution, thinner glass, POE/EPE encapsulation and recyclable module design will materially change the mix of demand even if total PV capacity continues to rise.
Asia Pacific will remain the center of production and consumption, although manufacturing localization will gradually increase material demand in India, the United States, Europe and the Middle East. Suppliers with low-cost production, technology-specific formulations, strong qualification records and credible low-carbon supply chains are best positioned to gain share.
Photovoltaic (PV) Materials Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 47.0 billion |
| Total Market Size in 2031 | USD 64.5 billion |
| Forecast Unit | Billion |
| Growth Rate | 6.5% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Material Type, Application, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Material Type
Silicon and Semiconductor Materials
Photovoltaic Glass
Encapsulants
Backsheets and Protective Films
Metallization and Interconnect Materials
Aluminum Frame Materials
Adhesives, Sealants and Other Materials
By Application
Utility-Scale Solar
Commercial and Industrial Solar
Residential Solar
Other and Specialty PV Applications
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Chile
Others
Europe
Germany
Spain
Italy
France
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Southeast Asia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Validation
2.4. Market Estimation and Forecasting
2.5. Data Triangulation and Quality Control
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
3.3. Material and Application Summary
3.4. Regional Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Record Global PV Deployment
4.1.2. Transition to N-Type and Higher-Efficiency Cells
4.1.3. Growth of Bifacial and Glass-Glass Modules
4.1.4. Manufacturing Localization
4.1.5. Material Innovation and Reliability Requirements
4.2. Market Restraints
4.2.1. Severe Price Pressure Across the PV Supply Chain
4.2.2. Continuing Material Thrifting
4.2.3. Commodity Input Volatility
4.2.4. Technology Substitution
4.2.5. Trade and Supply-Chain Restrictions
5. PHOTOVOLTAIC MATERIALS MARKET BY MATERIAL TYPE
5.1. Silicon and Semiconductor Materials
5.2. Photovoltaic Glass
5.3. Encapsulants
5.4. Backsheets and Protective Films
5.5. Metallization and Interconnect Materials
5.6. Aluminum Frame Materials
5.7. Adhesives, Sealants and Other Materials
6. PHOTOVOLTAIC MATERIALS MARKET BY APPLICATION
6.1. Utility-Scale Solar
6.2. Commercial and Industrial Solar
6.3. Residential Solar
6.4. Other and Specialty PV Applications
7. PHOTOVOLTAIC MATERIALS MARKET BY GEOGRAPHY
7.1. North America
7.1.1. United States
7.1.2. Canada
7.1.3. Mexico
7.2. South America
7.2.1. Brazil
7.2.2. Chile
7.2.3. Others
7.3. Europe
7.3.1. Germany
7.3.2. Spain
7.3.3. Italy
7.3.4. France
7.3.5. Others
7.4. Middle East and Africa
7.4.1. Saudi Arabia
7.4.2. UAE
7.4.3. South Africa
7.4.4. Others
7.5. Asia Pacific
7.5.1. China
7.5.2. India
7.5.3. Japan
7.5.4. South Korea
7.5.5. Southeast Asia
7.5.6. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Material Category Positioning
8.3. Technology and Qualification Requirements
8.4. Manufacturing Footprint and Supply-Chain Strategy
8.5. Recent Developments
8.6. Competitive Dashboard
9. COMPANY PROFILES
9.1. GCL Technology Holdings Limited
9.2. Wacker Chemie AG
9.3. Daqo New Energy Corp.
9.4. OCI Holdings / OCI TerraSus
9.5. Xinte Energy Co., Ltd.
9.6. Xinyi Solar Holdings Limited
9.7. Flat Glass Group Co., Ltd.
9.8. Hangzhou First Applied Material Co., Ltd.
9.9. Cybrid Technologies Inc.
9.10. RenewSys India Pvt. Ltd.
9.11. DuPont
9.12. Dow Inc.
9.13. Arkema S.A.
9.14. Heraeus Photovoltaics
9.15. Targray
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Abbreviations





Frequently asked questions
What is the projected market size for PV materials by 2031?
The Photovoltaic (PV) Materials Market is forecast to reach USD 64.5 billion by 2031.
What is the CAGR for the global PV materials market?
The Photovoltaic (PV) Materials Market is projected to grow at a 6.5% CAGR from 2026-2031.
Which region dominates global PV materials market revenue?
Asia Pacific accounts for 76.0% of global PV materials revenue.
Which PV material segment accounts for the largest revenue share in 2026?
Silicon and semiconductor materials account for 24.0% of revenue.
What is the dominant application for global PV materials demand by value?
Utility-scale solar applications represent 61.0% of demand.
What are key material innovation trends in the PV market?
Innovations focus on silver reduction, POE/EPE, dual-glass, and recyclability.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Photovoltaic (PV) Materials Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/photovoltaic-pv-materials-market