
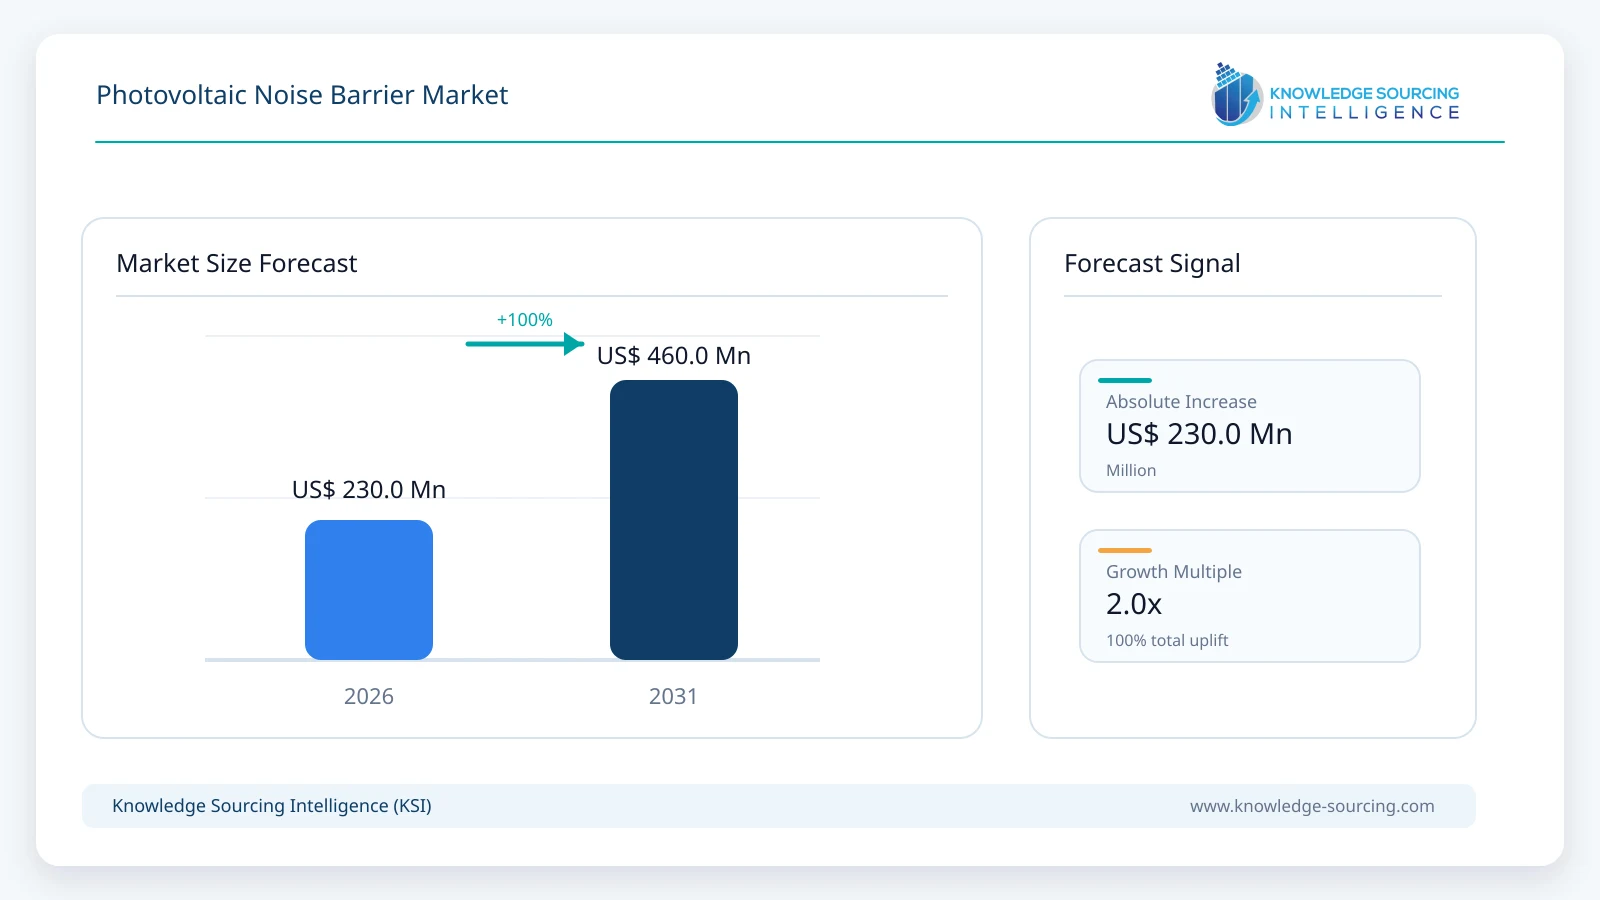
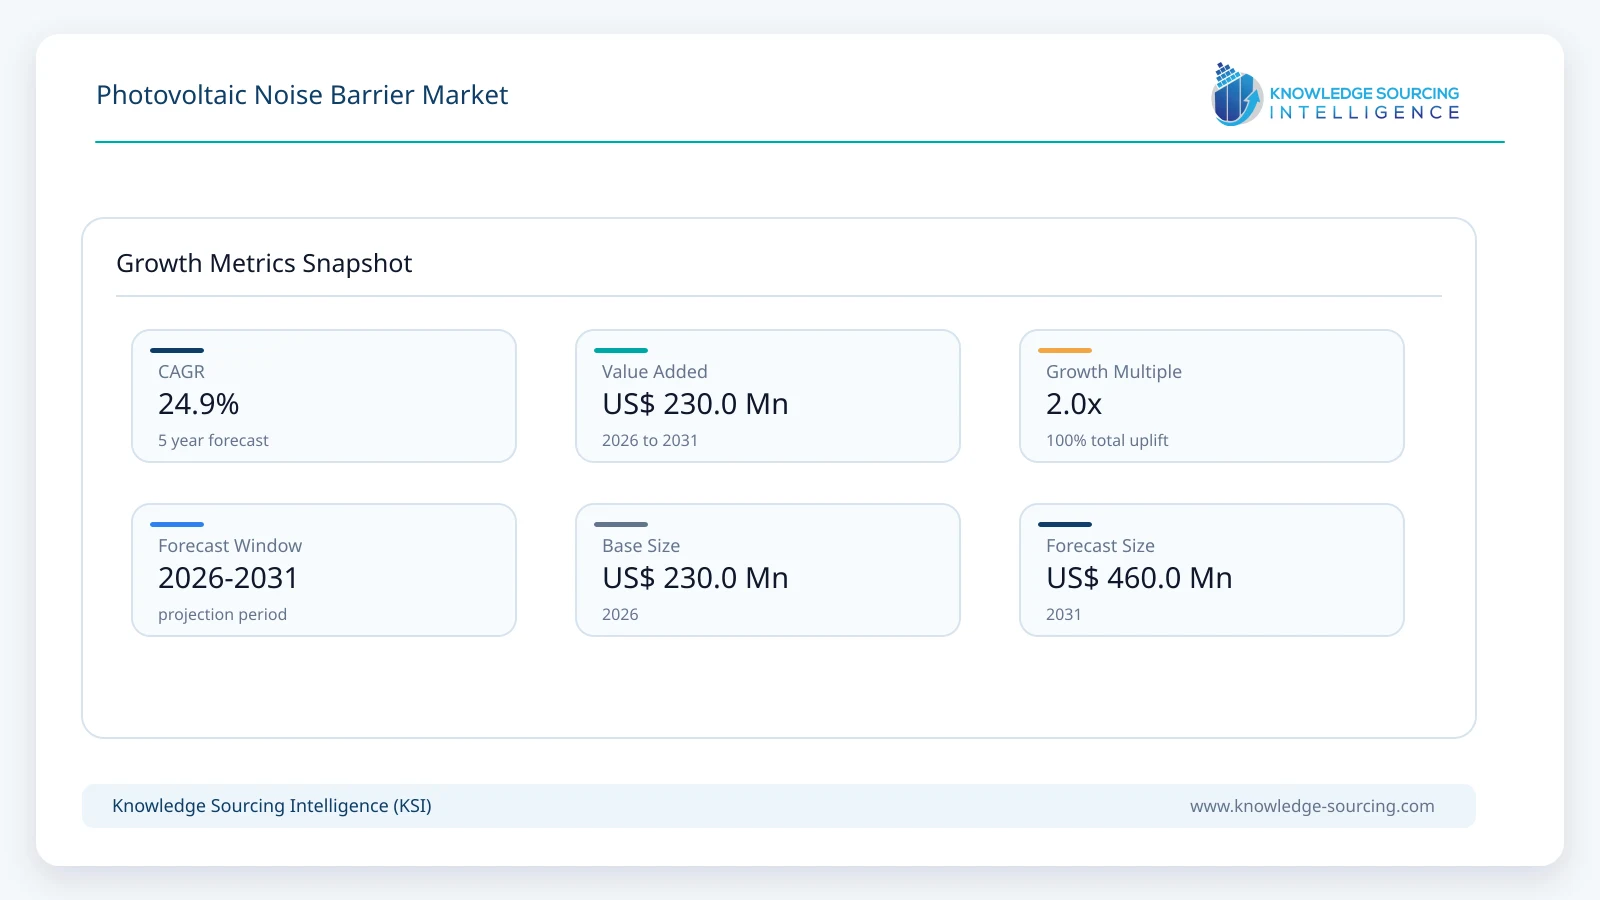
The photovoltaic noise barrier market is forecast to grow at a CAGR of approximately 14.9%, reaching USD 460 million in 2031 from USD 230 million in 2026.
Highlights:
- 1More than 100 photovoltaic noise barriers had been installed across at least 14 countries by 2023, demonstrating commercial experience beyond a small group of experimental sites.
- 2Germany has approximately 5 GW of estimated technical photovoltaic noise-barrier potential along roads and railways.
- 3The United States had accumulated approximately 300.1 million square feet and 3,866 miles of highway noise barriers by the end of 2022, creating a large potential retrofit base.
- 4China’s mapped roadside noise-barrier estate across surveyed cities totals approximately 2,667 km, providing substantial physical infrastructure for future PV integration.
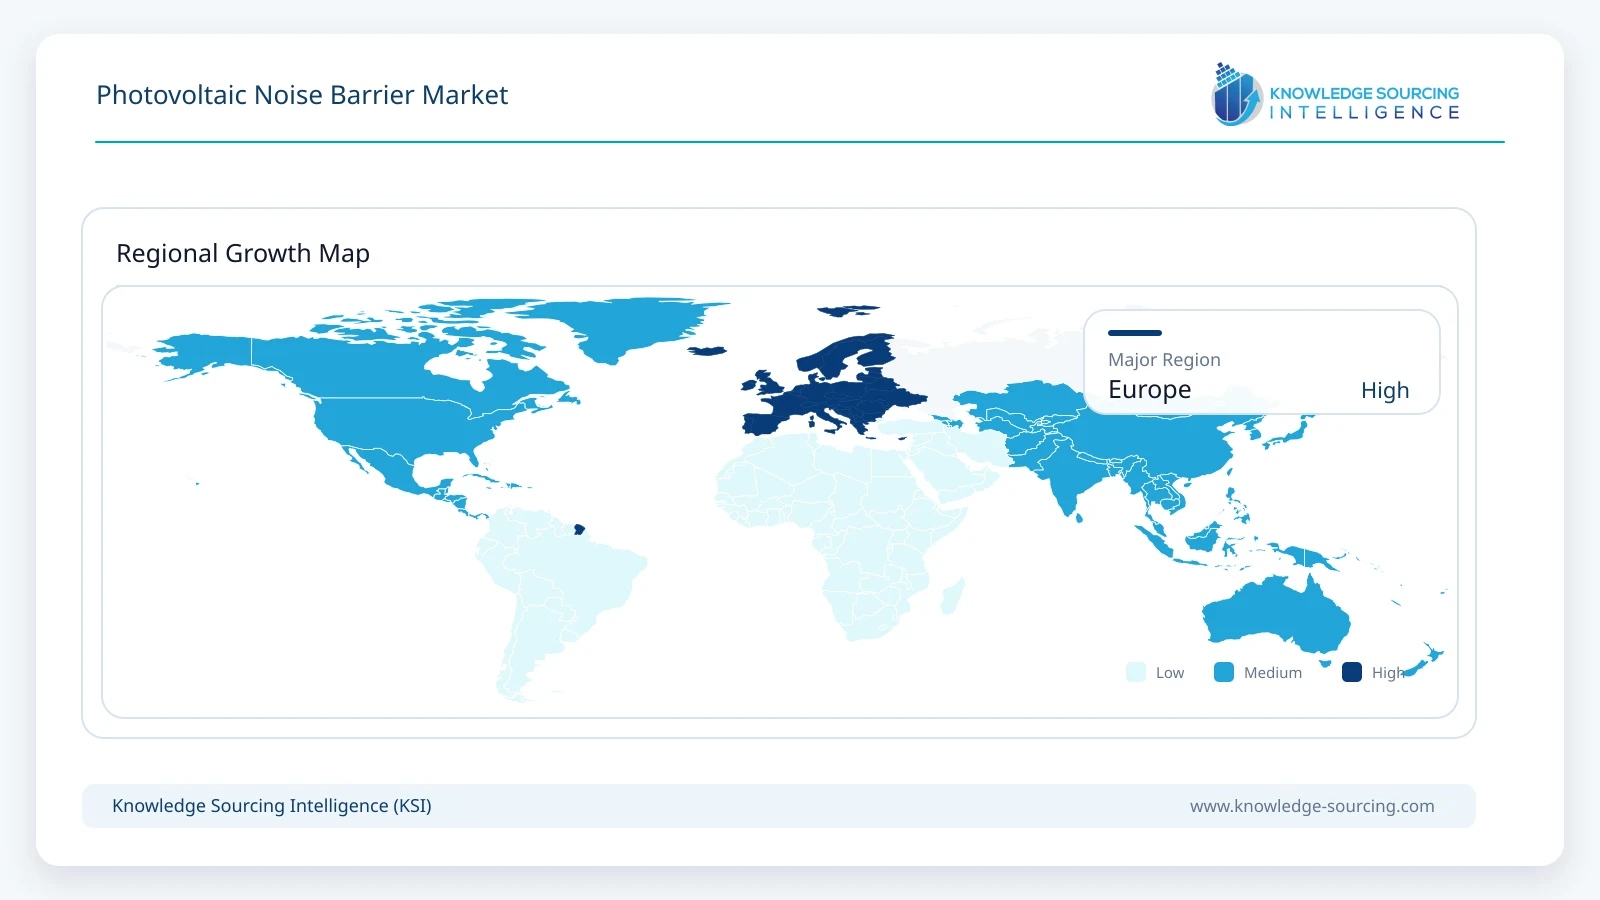
- 5Europe accounts for slightly more than half of current market value, while Asia Pacific and North America are expected to grow faster from lower commercial penetration.
- 6The market is forecast to expand aided by retrofit deployment, bifacial modules, standardization and broader infrastructure procurement.
Market Overview
Photovoltaic noise barriers are acoustic structures that incorporate photovoltaic modules so that the same infrastructure reduces traffic or industrial noise while generating electricity. Systems can be designed as fully integrated photovoltaic acoustic panels, vertically mounted bifacial barriers, PV cassettes, photovoltaic elements mounted on top of existing barriers, or retrofit systems attached to an existing sound wall.
The market includes photovoltaic modules, specialized acoustic barrier elements, mounting structures, electrical components and engineering directly associated with photovoltaic integration. Conventional noise barriers without photovoltaic functionality are excluded.
The scale of existing acoustic infrastructure provides a substantial foundation for future deployment. U.S. state transportation departments constructed approximately USD 925 million of highway noise barriers between 2020 and 2022, equivalent to roughly USD 308 million annually, covering 222 linear miles. Since 1963, U.S. highway barrier expenditure has totaled approximately USD 10.8 billion in 2022 dollars.
Germany provides another significant infrastructure base. Deutsche Bahn used approximately EUR 201 million in federal funds for existing-network noise remediation in 2025 and completed 39.6 km of barriers, while another 61.5 km of barriers were completed on new and expanded railway lines. In the first half of 2026, approximately EUR 52 million was used within the remediation program while around 7.5 km of barriers were completed.
Austria had around 1,400 km of noise-protection measures along motorways and expressways by the end of 2021 and indicated annual expenditure of around EUR 20-30 million for noise abatement on the existing network. ASFINAG has also tested seven photovoltaic systems on noise barriers and selected four concepts for broader deployment.
Photovoltaic penetration remains comparatively low within this installed acoustic infrastructure, leaving significant room for deployment as retrofit economics improve and transport authorities establish repeatable technical standards.
Market Trends
Bifacial Photovoltaic Modules Are Becoming Central to Vertical Barrier Design
Noise barriers cannot generally be oriented according to ideal solar geometry because their location is determined by the road or railway. Bifacial modules mitigate part of this constraint by producing electricity from irradiation reaching both sides of a vertically mounted system.
The Netherlands’ Solar Highways installation on the A50 uses a 400-meter-long and five-meter-high barrier containing 136 double-sided photovoltaic panels with approximately 238 kWp of capacity.
SoliTek is similarly using bifacial glass-glass modules in current projects. Its portfolio includes approximately 19 kW in Italy, 20.7 kW in Lithuania and 402 kW in Austria. South Korea’s Hansol EnergyON also offers bifacial photovoltaic sound-wall products certified against Korea Expressway Corporation requirements and reports commercial references of 167.7 kW in Wonju and 265.3 kW at Wonju Seogokri.
Bifacial technology is therefore becoming increasingly relevant for barriers with vertical or near-vertical module orientation and where generation from both faces can improve the overall yield profile.
Retrofit Deployment Is Expanding the Addressable Opportunity
Existing road and railway walls provide a substantially larger infrastructure base than annual new barrier construction. Retrofit systems allow suitable sections of this installed stock to be converted into distributed solar-generation assets without replacing the entire acoustic structure.
Fraunhofer ISE’s PVwins program estimates approximately 5 GW of technical potential in Germany and evaluates new-build, barrier-extension and retrofit concepts. Academic analysis of existing U.S. noise barriers has estimated approximately 7-9 GW of photovoltaic capacity under technically suitable large-scale deployment scenarios.
The commercial opportunity is expected to expand as structural assessment, mounting systems, electrical connections and maintenance requirements become increasingly standardized across transport agencies.
Project Economics Are Becoming Easier to Benchmark
Several completed projects provide increasingly useful references for the cost of combining photovoltaic generation with acoustic infrastructure. A 234-meter photovoltaic noise barrier constructed in Neuötting, Germany, with approximately 65.4 kWp of capacity had total project costs of about EUR 450,000, including approximately EUR 76,000 associated with the photovoltaic installation.
A 700-meter barrier retrofit along Germany’s A8 in Wendlingen involved approximately EUR 900,000 of total investment, including around EUR 300,000 of photovoltaic-related expenditure.
Cost structures differ materially according to whether PV is integrated into a newly constructed barrier or added to an existing structure. Structural reinforcement, foundations, grid connection, module configuration and road-access requirements can therefore have a significant effect on project economics.
Photovoltaic Noise Barriers Are Becoming More Productized
Commercial offerings are moving beyond project-specific engineering. Mitrex and Healthy Infrastructure have introduced dedicated North American solar noise-barrier systems, while Ko-Solar develops photovoltaic systems specifically for highway, railway and airport rights-of-way.
EtWay offers its Sound Solar Panel as a dedicated photovoltaic acoustic product, and reports completed installations across road, railway, industrial and private infrastructure. Solar Innova similarly supplies semitransparent photovoltaic noise-barrier systems and lists project references in the Netherlands, China and Hong Kong.
Greater product standardization can reduce engineering complexity and make photovoltaic integration easier to incorporate into routine transport-infrastructure procurement.
Segment Analysis
By System Architecture: Integrated Systems
Integrated PV noise barriers represent the largest current system category. The photovoltaic modules form part of the acoustic enclosure rather than operating as an independent array mounted near it.
Integrated construction can reduce duplication of structural materials and provide a more unified infrastructure design. These systems must nevertheless satisfy acoustic, mechanical, fire, impact, glare and electrical requirements simultaneously.
Fraunhofer’s PVwins program developed five configurations with R. Kohlhauer, IGRA Power and Megasol Energie, including fully integrated structures, retrofit designs and add-on solutions.
Retrofit and top-mounted systems represent a smaller current market but are expected to grow faster because they address the substantially larger installed base of existing sound barriers.
By PV Technology: Crystalline Silicon
Crystalline-silicon technology dominates current commercial installations. Standard monocrystalline modules provide supply-chain scale and cost advantages, while bifacial glass-glass designs are gaining share because of their suitability for vertical installation.
Thin-film and customized semitransparent photovoltaic technologies remain relevant where lower weight, architectural transparency or non-standard module dimensions are required. Companies such as Megasol Energie, ertex solar and Solar Innova provide customized photovoltaic glazing and module architectures suited to infrastructure integration.
By Application: Roads and Highways
Roads and highways form the largest commercial application. Government agencies already manage extensive noise-barrier estates, and roadside structures offer long linear surfaces without requiring additional land acquisition.
U.S. transportation departments had constructed 3,866 linear miles of barriers by 2022, while Austria reports approximately 1,400 km of motorway and expressway noise protection.
Railways represent the second major application. Germany’s large rail-noise-remediation program and Lithuania’s photovoltaic railway barrier demonstrate the opportunity. SoliTek and Stalcorp’s Lithuanian railway installation uses around 60 bifacial modules across a 70-meter barrier.
Industrial and power infrastructure provides a smaller but increasingly visible opportunity. China Energy Engineering’s East China Electric Power Design Institute began a 538-meter, 107 kWp integrated photovoltaic sound-barrier demonstration at power infrastructure in late 2025.
Market Drivers
Large Existing Noise-Barrier Networks Create a Retrofit Base
The market can expand without requiring construction of entirely new transport corridors. Large acoustic-barrier estates already exist across North America, Europe and Asia.
The United States alone had approximately 300 million square feet of highway barriers by the end of 2022. China’s roadside-noise-barrier dataset identifies approximately 2,667 km of barriers across surveyed cities.
Only a portion of these structures will have suitable orientation, structural strength, solar irradiation and grid access, but the installed base provides a significant platform for future retrofit activity.
Integrated Solar Uses Infrastructure Without Additional Land Consumption
Photovoltaic noise barriers generate electricity from a surface that already exists for another infrastructure purpose. This is particularly attractive in densely populated European and Asian markets where competing land uses can restrict conventional ground-mounted solar development.
Germany’s approximately 5 GW technical potential illustrates the scale available from the dual use of road and railway infrastructure.
Public Infrastructure Owners Are Progressing From Pilots Toward Wider Deployment
ASFINAG’s Austrian program has progressed from seven tested systems to four concepts selected for broader implementation. Italy’s ANAS Smart Road program is monitoring a 100-meter, 19.575 kW installation near Rome to assess energy production, maintenance requirements and wider deployment potential.
South Korea already has commercially deployed photovoltaic sound walls certified for highway applications, while China is developing integrated systems for transport and power infrastructure.
These programs indicate that procurement is gradually shifting from isolated proof-of-concept installations toward repeatable applications.
Market Restraints
Project Economics Remain Site-Specific
Photovoltaic noise barriers generally cost more per installed watt than conventional utility-scale or rooftop solar because structural and acoustic requirements add engineering and construction complexity.
Historical and current projects show considerable variation in economics. Neuötting’s 65.4 kWp wall cost around EUR 450,000 in total, while the photovoltaic component accounted for approximately EUR 76,000. A larger German A10 proposal involving up to 10 MW of photovoltaic capacity and nine kilometres of noise infrastructure was eventually abandoned after the economic case weakened following changes in solar remuneration.
Site selection, structural condition, grid proximity and expected electricity output therefore remain central to project viability.
Not All Existing Barriers Are Suitable for Photovoltaic Integration
Orientation, shading, structural loading, grid access, vegetation, maintenance access and road-safety requirements can materially reduce the proportion of existing noise barriers suitable for PV deployment.
North-facing sections, heavily shaded corridors or barriers requiring extensive structural reinforcement may not provide competitive economics even where sufficient physical surface is available.
Road Safety and Acoustic Performance Remain Primary Requirements
The acoustic barrier must continue to satisfy its primary infrastructure function. Photovoltaic integration must comply with noise attenuation, structural loading, electrical safety, glare, fire, impact and maintenance requirements.
Fraunhofer’s PVwins program evaluates acoustic properties, mechanical construction, electrical safety and economic operation together, reflecting the multidisciplinary nature of photovoltaic noise-barrier design.
Regional Outlook
Europe
Europe accounts for slightly more than half of global market value in 2026. The region has the longest history of PVNB deployment and contains the highest concentration of active projects, public programs and specialist suppliers.
Germany is the largest individual opportunity because of its road and railway barrier estate, historical multi-megawatt installations and approximately 5 GW of estimated technical potential. Historical German systems include installations of approximately 3 MW at Mühlsdorf, 2.65 MW at Goldbach/Hösbach and around 1 MW at both Wallersdorf and Bollberg.
Austria is increasingly important as ASFINAG progresses from pilot testing toward wider implementation. Domestic suppliers such as ertex solar also provide specialized infrastructure-integrated photovoltaic capabilities.
The Netherlands remains an important reference market through Solar Highways, while Italy has a growing commercial project base involving EtWay, SoliTek, GSM Continental and ANAS. Switzerland remains strategically important because it hosted one of the world’s earliest PV noise barriers and retains long-standing engineering expertise through TNC.
Lithuania, France, Belgium, the United Kingdom, Denmark and Sweden should also remain within the European country analysis because photovoltaic noise-barrier installations or development activity have been documented in these markets.
Asia Pacific
Asia Pacific represents the second-largest regional opportunity and is expected to gain share through 2031.
China combines an extensive roadside noise-barrier estate with the world’s largest photovoltaic manufacturing base and emerging domestic PVNB development. Approximately 2,667 km of roadside noise barriers have been mapped across surveyed Chinese cities, while active suppliers and engineering groups include Harmony Fab, Yukings and China Energy Engineering.
South Korea is an important commercial market because Hansol EnergyON reports certified photovoltaic sound-wall products and multiple operating highway installations.
Japan and Australia should remain explicit country markets because both possess mature transport-noise regulation, extensive road infrastructure and documented historical photovoltaic noise-barrier activity.
North America
North America has substantial physical potential but remains commercially less mature than Europe.
The United States has a large existing noise-barrier estate and continuing annual construction activity. Commercial product availability is also improving. Mitrex and Healthy Infrastructure market a dedicated North American photovoltaic noise-barrier system, while Ko-Solar specializes in solar energy systems integrated into transportation infrastructure.
The region’s growth through 2031 is expected to depend on the development of repeatable specifications, standardized permitting processes and viable ownership or electricity-offtake structures for public transport agencies.
South America, Middle East and Africa
Commercial PV-noise-barrier activity remains limited compared with Europe, Asia Pacific and North America. Brazil represents the most relevant South American market because of its large highway system and established solar industry.
The UAE and Saudi Arabia provide potential longer-term opportunities through solar-resource availability and major road-infrastructure investment, although documented PVNB deployment remains limited. These regions therefore account for a relatively small portion of 2026 market value.
Competitive Landscape
The competitive environment differs from the mainstream photovoltaic module market because successful project delivery requires acoustic engineering, structural design, photovoltaic integration and infrastructure construction capabilities.
SoliTek is one of the most visible current module suppliers with documented PVNB projects in Italy, Lithuania and Austria.
R. Kohlhauer is an established acoustic-barrier specialist and worked with Fraunhofer ISE, IGRA Power and Megasol Energie on the PVwins program.
EtWay has developed a dedicated Sound Solar Panel and reports Italian road, railway and industrial installations. Hansol EnergyON has established a strong South Korean position through highway-certified bifacial photovoltaic sound-wall systems.
Mitrex and Healthy Infrastructure have developed an integrated North American solar acoustic wall, while Ko-Solar specializes in transportation-integrated solar and solar sound barriers.
Solar Innova, ertex solar, Megasol Energie, Shenzhen Yukings and Harmony Fab provide customized photovoltaic modules or integrated structures suited to infrastructure installations.
Project contractors and infrastructure specialists including Heijmans, GSM Continental, Stalcorp and China Energy Engineering also play important roles because PVNB systems are generally delivered through partnerships rather than by module manufacturers alone.
Recent Developments
In 2026, Fraunhofer ISE continued commercial-development and technical work following the PVwins project, which developed five photovoltaic noise-barrier concepts and identified approximately 5 GW of technical potential in Germany.
In 2026, South Korean supplier Hansol EnergyON continued marketing Korea Expressway Corporation-certified bifacial photovoltaic sound walls supported by operating projects in Yeoju and Wonju.
In late 2025, China Energy Engineering’s East China Electric Power Design Institute began construction of a 538-meter, 107 kWp integrated photovoltaic sound-barrier demonstration.
In December 2025, SPHINX partners Fraunhofer ISE, EtWay and M10 installed three photovoltaic noise-barrier concepts at Merdingen, Germany, for performance monitoring.
In November 2025, ANAS, GSM Continental and SoliTek completed a 100-meter, 19.575 kW bifacial PV noise barrier near Rome.
In November 2025, photovoltaic modules were commissioned on approximately 700 meters of renovated motorway noise barrier in Wendlingen, Germany, with total project investment around EUR 900,000.
Lithuania continues to monitor photovoltaic noise barriers developed by SoliTek, Stalcorp and transport-infrastructure partners along railway and highway corridors.
Market Outlook
Europe remains the largest region through 2031, but its share gradually moderates as deployment expands in China, South Korea and North America. Asia Pacific is expected to record faster growth as domestic suppliers develop dedicated products and transport authorities increase adoption. North America expands from a comparatively low commercial base.
Road and highway barriers remain the largest application, while railway installations provide a substantial secondary opportunity, particularly in Germany and other densely populated European markets. Industrial and power infrastructure remains smaller but broadens the potential application base beyond conventional transportation corridors.
Bifacial crystalline-silicon systems are expected to gain share because vertical and near-vertical barriers can benefit from generation on both module surfaces. Retrofit solutions are also expected to grow faster than new-build systems as infrastructure operators begin evaluating existing sound walls as renewable-energy assets.
Long-term development depends on the conversion of proven technical concepts into standardized infrastructure specifications. Greater project repeatability, easier structural assessment, simplified grid connection and clearer ownership models would allow a larger proportion of the installed barrier estate to become commercially suitable for photovoltaic integration.
Photovoltaic Noise Barrier Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 230 million |
| Total Market Size in 2031 | USD 460 million |
| Forecast Unit | Million |
| Growth Rate | 24.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | System Architecture, PV Technology, Application, Geography |
| Companies |
|
Market Segmentation
By System Architecture
Integrated / New-Build PV Noise Barriers
Retrofit and Add-On Systems
By PV Technology
Monofacial Crystalline Silicon
Bifacial Crystalline Silicon
Thin-Film PV
Other and Custom PV Technologies
By Application
Roads and Highways
Railways and Urban Transit
Industrial and Power Infrastructure
Other Infrastructure Applications
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Others
Europe
Germany
Netherlands
Austria
Switzerland
Italy
France
Belgium
United Kingdom
Lithuania
Denmark
Sweden
Others
Middle East and Africa
UAE
Saudi Arabia
Others
Asia Pacific
China
South Korea
Japan
Australia
India
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Revenue Inclusion and Exclusion Criteria
1.4. Scope of the Study
1.5. Market Segmentation
1.6. Currency
1.7. Assumptions
1.8. Base and Forecast Years
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Research
2.4. Global Noise-Barrier Infrastructure Mapping
2.5. Documented PVNB Project Mapping
2.6. Project Cost and Installed-Capacity Analysis
2.7. Regional Commercial-Penetration Analysis
2.8. Forecast Methodology
2.9. Data Triangulation and Validation
3. EXECUTIVE SUMMARY
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Existing Noise-Barrier Retrofit Base
4.1.2. Renewable Generation Without Additional Land Consumption
4.1.3. Public-Infrastructure Pilot and Rollout Programs
4.1.4. Improving Bifacial Photovoltaic Performance
4.2. Market Restraints
4.2.1. Site-Specific Project Economics
4.2.2. Structural and Acoustic Integration Requirements
4.2.3. Orientation, Shading and Grid-Connection Constraints
4.2.4. Public Procurement and Approval Cycles
4.3. Market Opportunities
4.4. Industry Value Chain Analysis
4.5. Project Cost and Lifecycle Economics
4.6. Retrofit versus New-Build Economics
4.7. Ownership, PPA and Concession Models
4.8. Acoustic, Electrical and Road-Safety Standards
5. TECHNOLOGY OUTLOOK
5.1. Vertical Bifacial PV Noise Barriers
5.2. Integrated Photovoltaic Acoustic Panels
5.3. Cassette Systems
5.4. Top-Mounted and Tilted PV Systems
5.5. Shingled and Custom Module Designs
5.6. Transparent and Semi-Transparent PV
5.7. Retrofit Systems for Existing Barriers
5.8. Antiglare, Anti-Soiling and Monitoring Technologies
6. PHOTOVOLTAIC NOISE BARRIER MARKET BY SYSTEM ARCHITECTURE
6.1. Integrated / New-Build PV Noise Barriers
6.2. Retrofit and Add-On Systems
7. PHOTOVOLTAIC NOISE BARRIER MARKET BY PV TECHNOLOGY
7.1. Monofacial Crystalline Silicon
7.2. Bifacial Crystalline Silicon
7.3. Thin-Film PV
7.4. Other and Custom PV Technologies
8. PHOTOVOLTAIC NOISE BARRIER MARKET BY APPLICATION
8.1. Roads and Highways
8.2. Railways and Urban Transit
8.3. Industrial and Power Infrastructure
8.4. Other Infrastructure Applications
9. PHOTOVOLTAIC NOISE BARRIER MARKET BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Others
9.3. Europe
9.3.1. Germany
9.3.2. Netherlands
9.3.3. Austria
9.3.4. Switzerland
9.3.5. Italy
9.3.6. France
9.3.7. Belgium
9.3.8. United Kingdom
9.3.9. Lithuania
9.3.10. Denmark
9.3.11. Sweden
9.3.12. Others
9.4. Middle East and Africa
9.4.1. UAE
9.4.2. Saudi Arabia
9.4.3. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. South Korea
9.5.3. Japan
9.5.4. Australia
9.5.5. India
9.5.6. Others
10. COUNTRY-LEVEL DEPLOYMENT AND PROJECT PIPELINE
10.1. Germany
10.2. Austria
10.3. Netherlands
10.4. Italy
10.5. Switzerland
10.6. Lithuania
10.7. China
10.8. South Korea
10.9. United States
10.10. Other Emerging Country Programs
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Major Players and Strategy Analysis
11.2. Market Share Analysis
11.3. Strategies of Key Players
11.4. Recent Developments
11.5. Competitive Dashboard
12. COMPANY PROFILES
12.1. SoliTek
12.2. R. Kohlhauer GmbH
12.3. Mitrex
12.4. Healthy Infrastructure
12.5. Ko-Solar
12.6. Solar Innova
12.7. EtWay
12.8. Megasol Energie AG
12.9. IGRA Power GmbH
12.10. Heijmans N.V.
12.11. Hansol EnergyON
12.12. GSM Continental
12.13. Stalcorp
12.14. TNC Engineering AG
12.15. SolSystems Energy Trade & Construct GmbH
12.16. ertex solar
12.17. Shenzhen Yukings Industrial Co., Ltd.
12.18. Harmony Fab (Jiangsu) Solar Tech Co., Ltd.
12.19. China Energy Engineering
Navigate
Trusted by the world's leading organizations











