
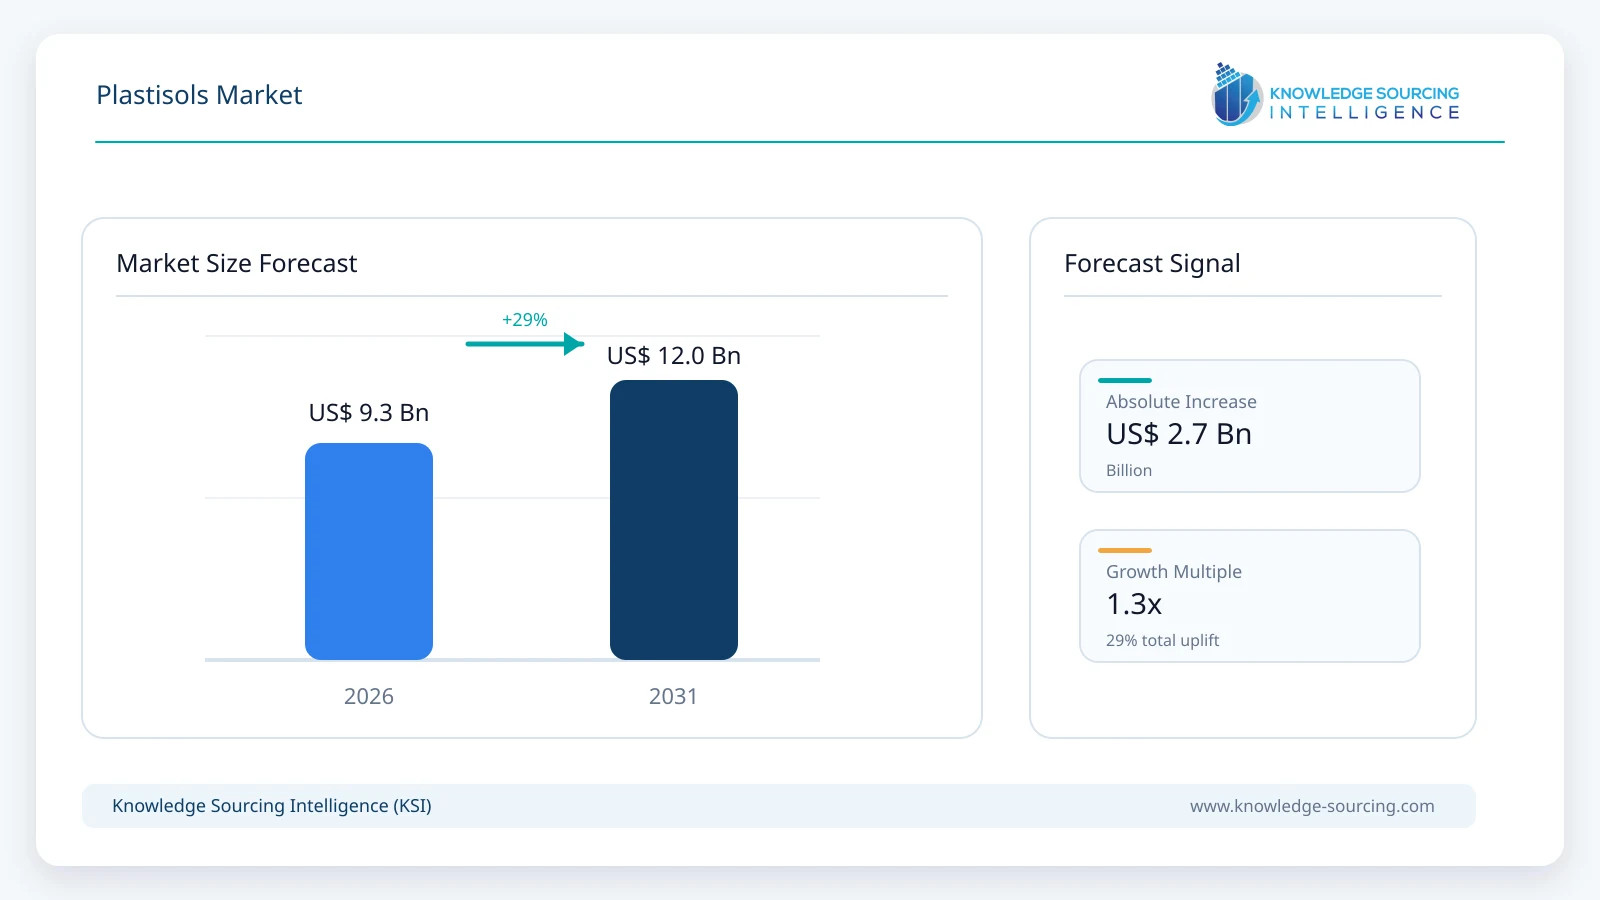
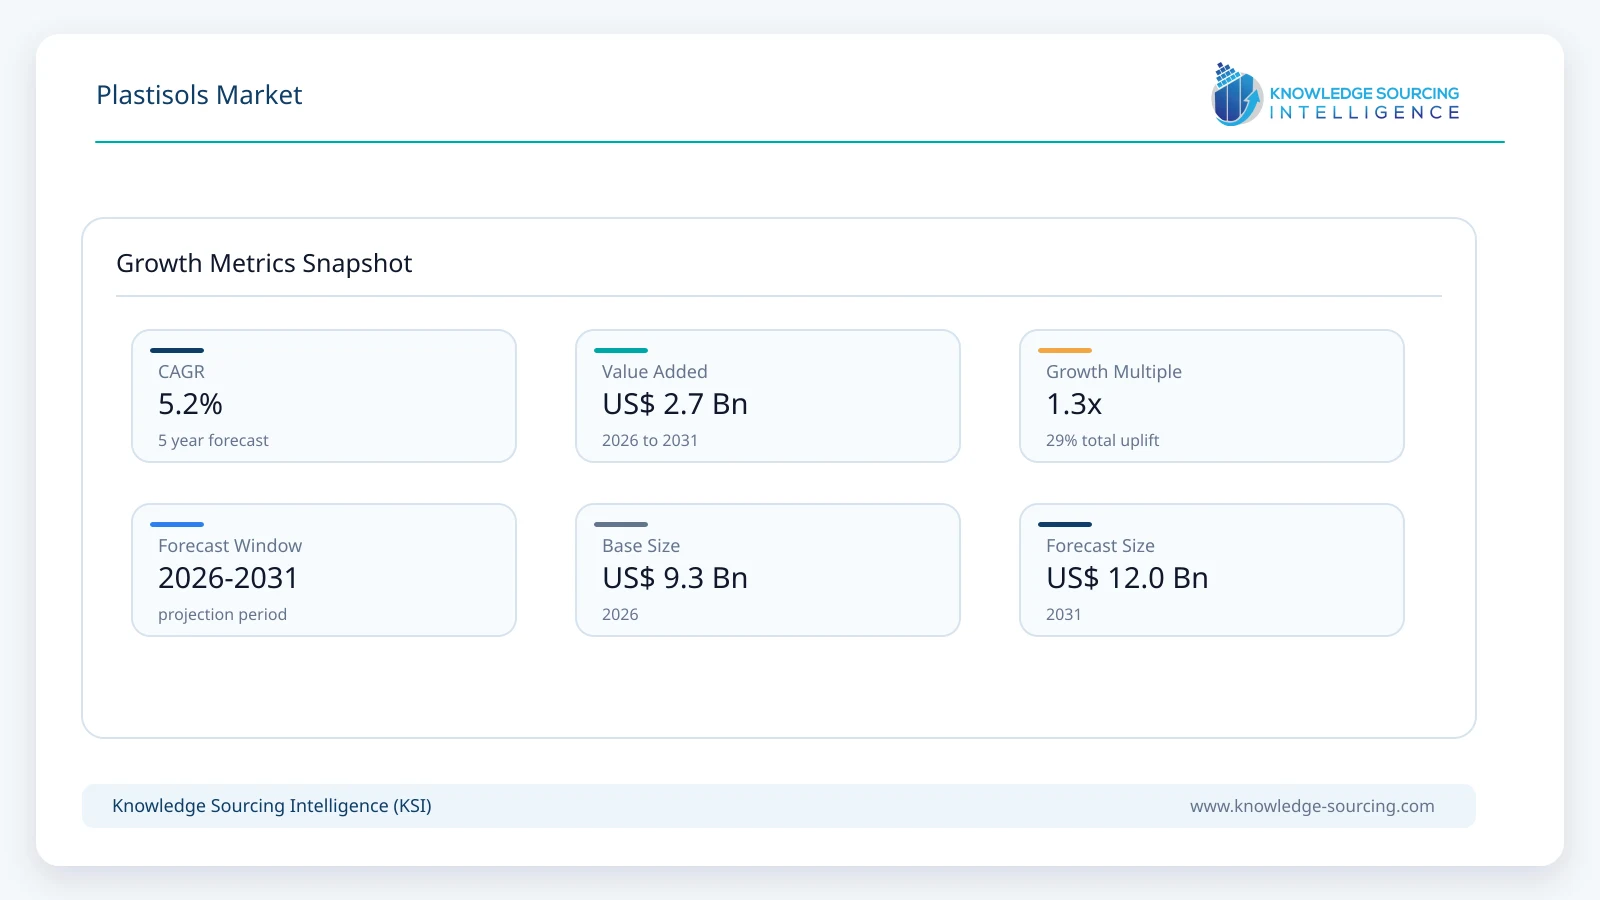
The global plastisols market is estimated at USD 9.30 billion in 2026 and is projected to reach USD 12.00 billion by 2031, representing a CAGR of 5.2% during the forecast period.
Highlights:
- 1The market is estimated at USD 9.30 billion in 2026 and is projected to reach USD 12.00 billion by 2031, growing at a 5.2% CAGR.
- 2Coatings are estimated to hold about 34% of 2026 market revenue, reflecting broad use in industrial dip coating, flooring, wallcoverings, coated fabrics and automotive protection.
- 3Printing inks are expected to be the fastest-growing major application, with an estimated 6.1% CAGR through 2031, supported by garment decoration and continued demand for low-cure and phthalate-free systems.
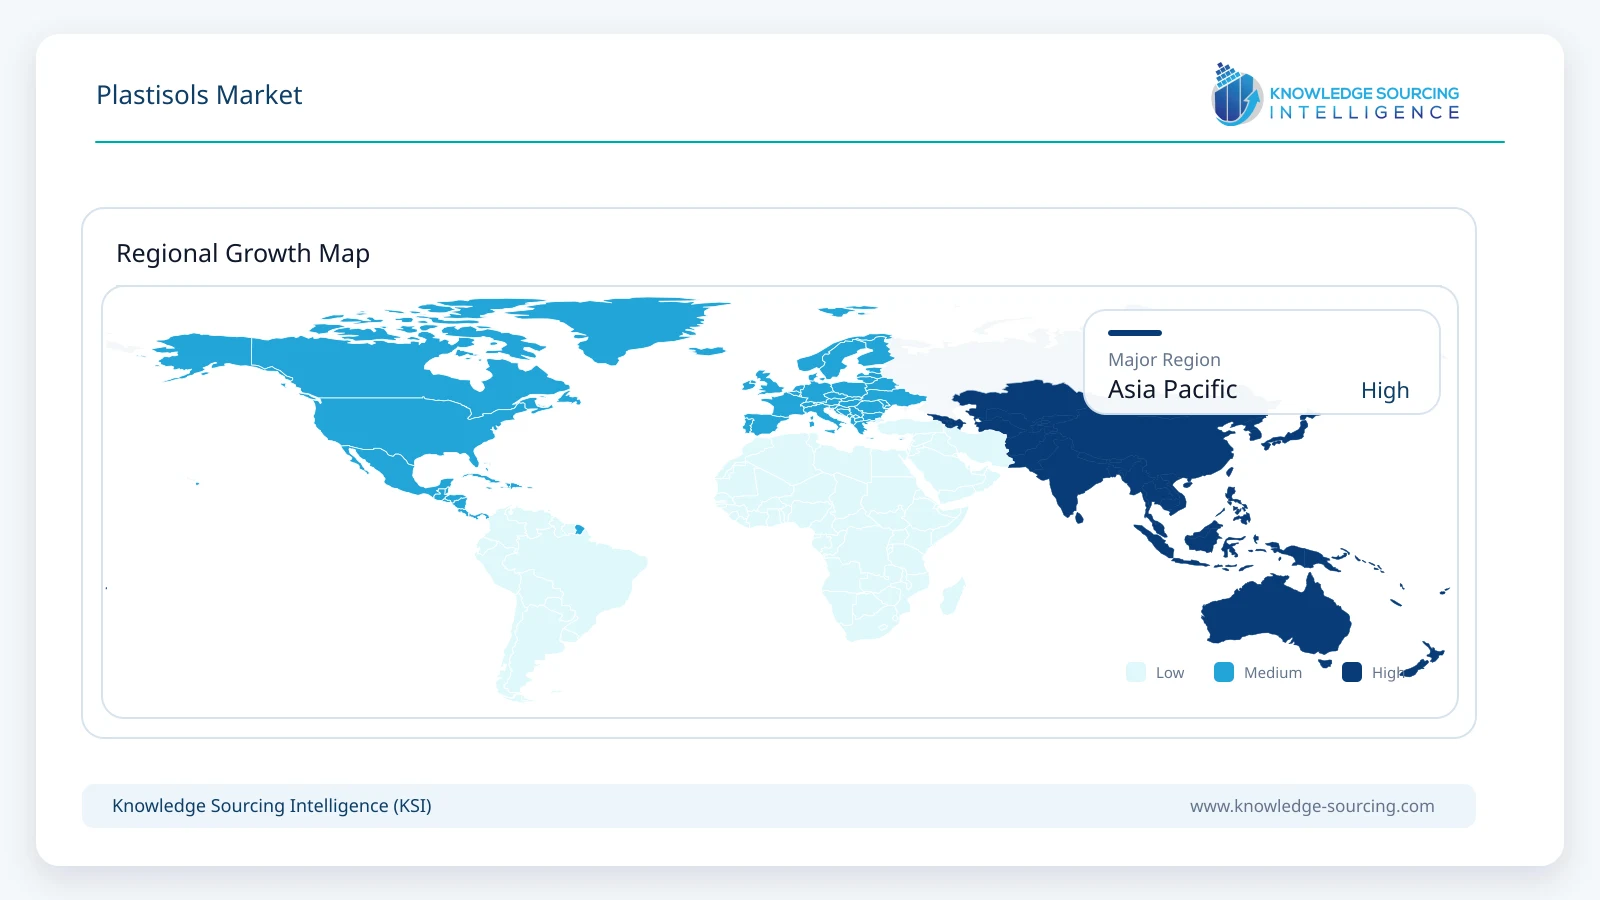
- 4Asia Pacific is estimated to account for approximately 47% of global revenue in 2026 due to the concentration of textile manufacturing, PVC conversion, automotive production and construction activity.
- 5Competition is shifting toward compliant, lower-impact formulations, including non-phthalate and bio-derived plasticizer systems, while consolidation is occurring among custom compounders and screen-printing ink suppliers.
PVC remains one of the world's most widely used polymers, with global resin consumption exceeding 40 million tonnes annually. The European Council of Vinyl Manufacturers states that worldwide PVC use grows by roughly 3% per year, with faster growth in developing economies. Plastisol demand represents a specialized subset of this broader PVC chain. Westlake's industry presentation identified roughly 4.2 million tonnes of global specialty PVC capacity in 2021, including major producers such as Orbia/Vestolit, Westlake/Vinnolit, INOVYN, Formosa, Kaneka, Kem One and Asian suppliers. Paste and dispersion PVC grades form the key resin base used in plastisol formulations.
A typical plastisol formulation can contain 40-100 parts plasticizer per 100 parts PVC resin, with additional fillers, stabilizers, pigments and functional additives depending on the application. Kaneka's published formulation examples show plasticizer loadings ranging from about 45 to 120 phr across wallpaper, flooring, gloves and automotive body-sealer applications. This formulation structure means the commercial value of plastisols is materially larger than the underlying paste-PVC resin value. Market sizing reflects specialty/paste-PVC availability, formulation ratios, end-use conversion activity and prevailing mix across industrial coatings, automotive, textiles and construction applications.
The market remains technically mature but formulation-intensive. Suppliers differentiate on viscosity, gelation temperature, hardness, chemical resistance, dielectric performance, adhesion, low-temperature flexibility, flame retardancy, color and regulatory compliance. The migration away from regulated phthalates has already changed product portfolios across North America and Europe, while bio-derived plasticizer systems are now being commercialized in selected applications. At the same time, plastisols retain advantages where thick-film build, screen stability, abrasion resistance, corrosion protection and flexible molding are more important than ultra-low-temperature processing.
Market Drivers
Automotive sealing, coating and NVH applications
Automotive manufacturing remains a major source of high-value plastisol demand. PVC plastisols are used in body seam sealers, underbody protection, sound-deadening layers, interior slush molding and selected adhesives because the material can be applied as a liquid, tolerate complex geometries and cure into a flexible protective layer. Kaneka continues to publish dedicated paste-PVC grades for body sealers and underbody coatings, while Avient offers customized vinyl plastisol systems for coating and molding. Vehicle electrification does not eliminate these requirements; instead, OEM attention to corrosion protection, sealing, cabin acoustics and durable lightweight interior surfaces sustains demand, although some EV platforms may adopt competing non-PVC materials in specific components.
Textile screen printing and specialty inks
Plastisol remains a workhorse chemistry for textile screen printing because it does not dry in the screen, provides high opacity on dark garments and can be formulated for low-cure, stretch, metallic, puff and bleed-resistant effects. Avient continues to market multiple plastisol ink families and highlighted its Rutland Evolve Bio Plastisol inks at Impressions Expo 2025. International Coatings, Lancer Group, Total Ink Solutions, Thanet Coatings, Beautyflex and other manufacturers also maintain active plastisol ink portfolios. Demand is strongest in garment-printing hubs, although water-based, silicone and PVC-free ink systems are increasingly competitive where fashion brands prioritize softer hand feel or restricted-substance compliance.
Industrial coating and dip-molding versatility
Plastisols remain difficult to replace in many dip-coating, dip-molding and casting applications because they combine process simplicity with strong control over hardness, color, texture and thickness. Chemionics, PolySol, Lakeside Plastics and StockCap all continue to offer custom plastisol formulations for applications such as tool grips, electrical insulation, filters, industrial fabrics, medical products, protective caps and specialty molded parts. The ability to formulate for FDA, NSF, UL, military, RoHS and REACH requirements supports continued use in specialized industrial markets.
Market Restraints
Substitution by water-based, silicone and non-PVC systems: textile printing and selected coatings face increasing competition from alternatives that can offer softer hand feel, lower PVC content or different sustainability profiles.
Plasticizer regulation and customer restricted-substance lists: suppliers must reformulate around phthalate restrictions and changing brand requirements, increasing development and qualification costs.
Weak European PVC economics: European PVC producers face high energy costs, imports and plant rationalization. VinylPlus reported increased import dependence in 2025, while Vynova announced plans to cease PVC production at its 225,000-tonne Beek plant.
Cure-energy requirements: plastisols generally require thermal fusion, which can raise energy use relative to ambient- or lower-temperature systems and can be a disadvantage in some printing and coating operations.
Global Plastisols Market Segment Analysis
By Application
Coatings are estimated to account for approximately 34% of global plastisol revenue in 2026, making them the largest application. The segment includes industrial dip and spray coatings, coated fabrics, flooring and wallcovering layers, automotive protective coatings and other thick-film applications. Its scale reflects the broad technical range of paste-PVC grades and the ability of formulators to tailor hardness, foamability, adhesion and rheology.
Printing inks are expected to record the fastest growth among major applications, at approximately 6.1% CAGR from 2026 to 2031. Growth is supported by garment customization, sportswear and promotional apparel, particularly in Asia, while innovation around low-cure, non-phthalate and partially bio-derived systems helps defend plastisol against water-based and silicone alternatives.
By End-Use Industry
Textile and apparel remain a major demand center due to screen printing and coated-fabric applications. Automotive and transportation represent another high-value segment through seam sealing, underbody coating, sound damping and interior applications. Construction and flooring demand includes vinyl floor structures, wallcoverings, roofing-related products, sealants and coated architectural materials. Industrial and consumer applications span tool grips, electrical insulation, wire products, caps, toys, fishing lures, filters and molded protective components.
Geographic Analysis
Asia Pacific
Asia Pacific is estimated to represent approximately 47% of global plastisol revenue in 2026. The region combines large textile-printing clusters, high PVC conversion volumes, significant automotive output and continued construction demand. China remains the largest manufacturing base, while India, Bangladesh, Vietnam and other South and Southeast Asian markets support printing-ink and coated-fabric demand. Japan and South Korea remain important suppliers of specialty paste PVC and high-performance formulations.
North America
North America has a strong base of custom plastisol compounders, dip molders and screen-printing ink manufacturers. The region benefits from automotive, industrial, medical and specialty textile applications. Competitive activity is also consolidating: in September 2025, Protech Group acquired Loes Enterprises, a custom PVC plastisol compounder, and integrated the business into its Chemionics specialty-materials division.
Europe
Europe remains technologically important in specialty PVC, flooring, wallcoverings, coated fabrics and industrial applications, but the upstream PVC chain is under pressure. VinylPlus reported that PVC resin imports, including primary PVC and compounds, accounted for 19% of the European market in 2025. Formulators are simultaneously responding to stricter chemical requirements and customer demand for non-phthalate systems, creating opportunities for higher-value compliant formulations even as commodity PVC production rationalizes.
Other Regions
Latin America, the Middle East and Africa represent smaller but growing markets led by textile printing, construction materials, automotive assembly and industrial coating applications. Local demand is often served by regional formulators and imported specialty compounds, with growth linked to manufacturing investment and the gradual localization of apparel, footwear and automotive supply chains.
Competitive Environment
The plastisols market is fragmented across large specialty-material companies, regional custom compounders and textile-ink specialists. Competitive advantage depends less on commodity PVC scale than on formulation know-how, consistency, compliance documentation, color matching, application support and the ability to customize rheology and cure behavior. Large suppliers such as Avient compete across multiple vinyl-formulation applications, while focused companies such as Chemionics, PolySol, Lakeside Plastics and StockCap specialize in industrial plastisol compounding. Textile printing is served by Avient's ink brands alongside International Coatings, Lancer Group, Total Ink Solutions, FUJIFILM Sericol India, Thanet Coatings, Grafco, Radiant Inks and regional manufacturers.
Recent consolidation reinforces the importance of technical service and distribution reach. Protech's acquisition of Loes expanded its PVC plastisol coatings portfolio, while Nazdar acquired FUJIFILM's U.S., Canada and Latin America screen and flexographic ink business in June 2026. These moves increase the scale of specialist suppliers without eliminating the role of smaller formulators serving custom industrial requirements.
Recent Developments
June 2026: Nazdar acquired FUJIFILM North America's U.S., Canada and Latin America screen and flexographic ink business, expanding its analog-ink customer base and technical-service footprint.
September 2025: Protech Group acquired Loes Enterprises, a custom compounder of PVC plastisol and related products, and announced integration of Loes manufacturing into its Chemionics specialty-materials operation.
January 2025: Avient showcased Rutland Evolve Bio Plastisol inks containing 56-59% bio-derived content at Impressions Expo 2025, highlighting the move toward lower fossil-derived content within conventional plastisol processing.
July 2025: Vynova announced its intention to cease PVC production at its 225,000-tonne-per-year Beek site by November 2025, reflecting the cost and import pressures facing European PVC production.
Market Outlook
The plastisols market is expected to expand at a moderate pace through 2031 rather than experience a step-change in demand. Core applications in automotive protection, industrial coating, flooring, wallcoverings, dip molding and textile printing remain durable, while growth is increasingly tied to formulation upgrades rather than entirely new end uses. Asia Pacific should continue to gain share due to manufacturing concentration and faster underlying PVC demand growth.
The central competitive challenge is substitution. Suppliers that simply offer conventional phthalate-based formulations are likely to face increasing pressure from water-based, silicone and non-PVC alternatives. By contrast, formulators that combine low-cure processing, non-phthalate plasticizers, partial bio-derived content, compliance support and application-specific performance should preserve pricing power. As a result, market value growth is expected to modestly exceed underlying volume growth over the forecast period.
Global Plastisols Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 9.30 billion |
| Total Market Size in 2031 | USD 12.00 billion |
| Forecast Unit | Billion |
| Growth Rate | 5.2% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Application, End-Use Industry, Geography |
| Companies |
|
Market Segmentation
By Application
Coatings
Printing Inks
Sealants and Adhesives
Molding and Casting Compounds
Other Applications
By End-Use Industry
Textile and Apparel
Automotive and Transportation
Construction, Flooring and Wallcoverings
Industrial and Consumer Goods
Medical and Other End Uses
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Other South American Markets
Europe
Germany
United Kingdom
France
Italy
Other European Markets
Middle East and Africa
Saudi Arabia
UAE
South Africa
Other Middle East and African Markets
Asia Pacific
China
India
Japan
South Korea
Southeast Asia
Other Asia Pacific Markets
Table of Contents
1. INTRODUCTION
1.1 Market Definition and Scope
1.2 Market Segmentation
1.3 Currency and Units
1.4 Base Year and Forecast Period
2. RESEARCH METHODOLOGY
3. EXECUTIVE SUMMARY
3.1 Key Research Highlights
4. MARKET DYNAMICS
4.1 Market Drivers
4.1.1 Automotive Sealing, Coating and NVH Applications
4.1.2 Textile Screen Printing and Specialty Inks
4.1.3 Industrial Coating and Dip-Molding Versatility
4.1.4 Construction, Flooring and Wallcovering Demand
4.2 Market Restraints
4.2.1 Substitution by Water-Based, Silicone and Non-PVC Systems
4.2.2 Plasticizer Regulation and Restricted-Substance Requirements
4.2.3 European PVC Cost and Supply Pressures
4.2.4 Thermal Cure Energy Requirements
4.3 Market Opportunities
4.3.1 Non-Phthalate and Bio-Derived Plastisol Formulations
4.3.2 Low-Cure Textile Printing Systems
4.3.3 Custom Medical and Industrial Formulations
4.4 Industry Value Chain Analysis
5. PLASTISOLS MARKET, BY APPLICATION
5.1 Introduction
5.2 Coatings
5.3 Printing Inks
5.4 Sealants and Adhesives
5.5 Molding and Casting Compounds
5.6 Other Applications
6. PLASTISOLS MARKET, BY END-USE INDUSTRY
6.1 Introduction
6.2 Textile and Apparel
6.3 Automotive and Transportation
6.4 Construction, Flooring and Wallcoverings
6.5 Industrial and Consumer Goods
6.6 Medical and Other End Uses
7. PLASTISOLS MARKET, BY GEOGRAPHY
7.1 North America
7.1.1 United States
7.1.2 Canada
7.1.3 Mexico
7.2 South America
7.2.1 Brazil
7.2.2 Argentina
7.2.3 Other South American Markets
7.3 Europe
7.3.1 Germany
7.3.2 United Kingdom
7.3.3 France
7.3.4 Italy
7.3.5 Other European Markets
7.4 Middle East and Africa
7.4.1 Saudi Arabia
7.4.2 UAE
7.4.3 South Africa
7.4.4 Other Middle East and African Markets
7.5 Asia Pacific
7.5.1 China
7.5.2 India
7.5.3 Japan
7.5.4 South Korea
7.5.5 Southeast Asia
7.5.6 Other Asia Pacific Markets
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1 Competitive Positioning
8.2 Product and Formulation Strategy
8.3 Mergers, Acquisitions and Partnerships
8.4 Competitive Dashboard
9. COMPANY PROFILES
9.1 Avient Corporation
9.2 The Protech Group / Chemionics
9.3 PolySol LLC
9.4 Lakeside Plastics, Inc.
9.5 Sinclair & Rush, Inc. (StockCap)
9.6 International Coatings Company
9.7 Lancer Group International
9.8 Total Ink Solutions
9.9 FUJIFILM Sericol India Pvt. Ltd.
9.10 Nazdar Ink Technologies
9.11 Thanet Coatings Ltd.
9.12 Grafco S.r.l.
9.13 Radiant Inks
9.14 Beautyflex Textile Printing Inks
9.15 Shiva Plastochem Industries
9.16 Hong Rui Sheng
10. RECENT DEVELOPMENTS
11. MARKET OUTLOOK
12. APPENDIX
Navigate
Trusted by the world's leading organizations











