
The residential proxy server market is forecast to grow from USD 1.92 billion in 2026 to USD 3.05 billion by 2031, representing a CAGR of approximately 9.7% during the forecast period.
Highlights:
- 1Rotating residential proxies account for approximately 77% of global market value in 2026, supported by large-scale data collection and automated location switching.
- 2HTTP/HTTPS connectivity accounts for approximately 72% of global revenue in 2026, reflecting its compatibility with browser-based and web-data applications.
- 3Web scraping and data collection account for approximately 42% of market value in 2026, supported by e-commerce monitoring, AI data pipelines and competitive intelligence.
- 4North America accounts for approximately 36% of the residential proxy server market in 2026, supported by extensive enterprise use of public web data.
- 5The United States accounts for approximately 27% of global revenue in 2026, remaining the largest individual national market.

Residential proxies route internet traffic through IP addresses assigned by internet service providers to consumer households and other genuine residential connections. Commercial services allow customers to select geographic locations, rotate IP addresses between requests or maintain persistent sessions depending on the application. Static ISP proxies are included if the address is commercially presented as a residential or ISP-backed connection. However, this does not apply to mobile proxies, conventional data-center proxies, or public free-proxy networks.
Large providers now operate networks spanning most major internet markets. Oxylabs advertises more than 175 million residential IPs across 195 countries, Decodo provides access to more than 115 million ethically sourced addresses, and SOAX reports a pool exceeding 155 million residential IPs. These figures represent provider-reported available pools rather than simultaneously active connections, but they illustrate the scale required to support city-, region-, ZIP-, ASN- and ISP-level targeting for international customers.
The commercial proposition is also changing. Providers increasingly sell residential connectivity alongside scraping APIs, automated browsers and structured-data services so customers can collect information without managing IP rotation, retries and anti-bot responses independently. Decodo's transition from Smartproxy in 2025 reflected this broader positioning, while Bright Data and Oxylabs have increasingly described themselves as web-data or AI-data infrastructure businesses rather than proxy vendors alone.
Market Trends
Residential Proxies Are Becoming Part of Broader Web-Data Platforms
Proxy access is increasingly being embedded within complete data-collection systems rather than sold only as an infrastructure endpoint. Customers can now purchase scraping APIs and browser-based services in which the provider automatically chooses IP addresses, handles retries, manages CAPTCHAs and returns the requested information in a usable form.
This development reduces the engineering resources required to maintain large scraping systems, particularly when websites change frequently or use sophisticated anti-automation controls. Decodo's rebranding from Smartproxy accompanied the expansion of its platform into web scraping APIs and AI-oriented data tools, while Bright Data and Oxylabs have followed similar strategies around structured web information and AI-ready datasets. The service provider therefore competes increasingly on the complete reliability of the data pipeline rather than the number of proxy IPs alone.
AI Applications Are Increasing Demand for Continuously Updated Web Data
Generative AI and agentic software are creating new requirements for information that reflects current conditions rather than static training datasets. Businesses use public web information to support retrieval systems, market intelligence, product discovery and automated agents that need to react to changes in prices, inventories, news and online content.
Residential networks provide one of several access methods used within this infrastructure because they allow requests to originate from geographically diverse consumer internet connections. Bright Data reported annualized revenue above USD 300 million as demand for live web data accelerated, while Oxylabs reported approximately USD 350 million in annual recurring revenue across its wider data platform in July 2026. Neither figure represents residential proxy revenue alone, but both demonstrate the commercial expansion of the broader web-data ecosystem serving these workloads.
Geographic Targeting Is Becoming More Granular
Country-level proxy targeting is increasingly insufficient for applications such as local price monitoring, advertising verification and search-result analysis. Providers are therefore expanding location controls to regions, cities, ZIP codes, internet service providers and autonomous system numbers.
This precision allows a retailer to observe how a competitor's website appears in individual markets or enables an advertising company to confirm whether campaigns are delivered correctly in selected locations. It also gives search and travel-data businesses greater control over regional data collection. The capability has consequently become a mainstream feature among large enterprise networks rather than a premium add-on available from only a small number of providers.
IP Sourcing Has Become a Core Competitive Issue
Enterprise customers are paying greater attention to how residential IP addresses enter commercial proxy networks. These connections can be sourced through opt-in bandwidth-sharing applications, software development kits, direct partnerships or other arrangements, creating substantial differences in transparency and user consent between networks.
Events during 2026 intensified scrutiny of this issue. Google disrupted the IPIDEA residential proxy infrastructure in January after finding that millions of devices were being enrolled through software and SDKs without sufficiently clear disclosure in many cases. Its research also showed significant overlap between apparently independent proxy brands, highlighting the importance of understanding the underlying network rather than relying only on a provider's marketed IP count.
Established providers increasingly respond by emphasizing consent, ethical sourcing and customer verification. These capabilities are becoming particularly important when serving large companies whose procurement teams require evidence that data infrastructure meets internal governance and security requirements.
Market Drivers
E-Commerce Price and Product Monitoring Require Localized Data
Online retailers, brands and analytics companies continuously monitor prices, product availability, customer reviews and promotional activity across digital marketplaces. Residential proxy networks help them access regional versions of these websites and distribute requests across genuine consumer IP ranges.
The requirement becomes more complex as retailers personalize content according to country, city or user location. A business monitoring thousands of products across several markets needs infrastructure capable of collecting information repeatedly without depending on a small number of easily identified addresses.
Residential networks are therefore used alongside scraping software to provide geographic diversity and request continuity. Price monitoring remains one of the most established commercial use cases, with providers increasingly integrating location targeting directly into automated data-collection products.
Increasing Anti-Bot Sophistication Supports Higher-Quality Proxy Demand
Websites are using more advanced techniques to identify automated activity, including behavioral signals, browser fingerprints, traffic patterns and network reputation. Residential IPs can reduce dependence on easily identifiable data-center ranges, but the address alone no longer guarantees successful access.
Cloudflare has introduced specific detection capabilities for traffic associated with commercial residential proxy networks, demonstrating how defenses continue to evolve beyond simple IP-blocking approaches. This increases the importance of session management, request behavior, browser technology and IP quality alongside network size.
As a result, customers increasingly evaluate providers according to successful request delivery rather than advertised IP pools alone. Networks capable of combining clean addresses with appropriate rotation and reliable infrastructure can command stronger positions in enterprise applications.
Advertising Verification Creates Recurring Enterprise Demand
Digital advertisers need to confirm that campaigns appear in the intended location, format and context, especially when advertising platforms automatically adapt content according to geography or user characteristics. Residential proxies enable verification systems to view advertisements from different locations without maintaining physical infrastructure in each market.
The same approach can help identify unauthorized placements, incorrect localization and competitive advertisements. Because campaigns run continuously, these activities generate recurring rather than one-time proxy usage, making advertising verification an attractive enterprise application.
Geographic precision becomes particularly important where campaigns differ between individual cities or regions. Providers offering city-, ZIP- and ISP-level targeting can therefore support more granular verification services than networks limited to country selection.

Market Restraints and Challenges
Network Sourcing Creates Significant Compliance and Security Risk
Residential networks can expose enterprises to substantial reputational and operational risk when IP addresses are acquired without clear user consent. The issue became especially visible in 2026 when Google and its partners disrupted IPIDEA, describing it as one of the world's largest residential proxy networks and linking its infrastructure to extensive malicious activity.
In September 2026, Google announced further coordinated action involving the NetNut residential proxy network, continuing its campaign against malicious residential proxy infrastructure. These events do not make legitimate residential proxy services inherently unsafe, but they raise the importance of supplier due diligence and demonstrate why enterprise customers increasingly examine sourcing practices before purchasing network access.
Providers with documented consent mechanisms, transparent sourcing and customer-verification procedures are consequently better positioned to serve compliance-sensitive organizations.
Pricing Remains Higher Than Data-Center Proxy Services
Residential connectivity generally costs more than conventional data-center proxy traffic because suppliers must acquire and maintain access to distributed consumer connections. Pricing has declined as competition increases, yet the difference remains meaningful for workloads requiring large amounts of bandwidth.
Current residential plans from major suppliers span a wide range according to traffic commitments and service level. Decodo lists standard packages from approximately USD 2-4 per GB depending on volume, while SOAX offers declining rates as subscriptions increase. Oxylabs and Bright Data similarly provide volume-based commercial structures.
Companies therefore often combine proxy types, reserving residential addresses for targets where their higher trust characteristics justify the additional cost and using less expensive infrastructure for simpler data collection.
Segment Analysis
By Type: Rotating Residential Proxies
Rotating residential proxies are projected to generate approximately USD 2.39 billion by 2031, remaining the largest service type. These products automatically change the exit IP between requests or according to configurable session rules, enabling large workloads to draw from extensive residential pools without manually assigning individual addresses.
The model is particularly suitable for e-commerce monitoring, search analysis and public web-data collection because those activities require repeated access to many pages across different locations. Sticky-session functionality can preserve the same address for a defined period when continuity is necessary, after which it returns to the broader rotating pool.
Static residential or ISP proxies remain valuable for applications that require a persistent identity, but their narrower use case means rotating services continue to account for the larger revenue pool.
By Protocol: HTTP/HTTPS
HTTP/HTTPS connectivity is projected to generate approximately USD 2.16 billion by 2031, remaining the largest protocol category because most commercial residential-proxy demand is associated with web-based applications.
The protocols integrate readily with browsers, scraping frameworks and standard HTTP request libraries, making them suitable for pricing intelligence, search monitoring, advertising verification and public website collection. Providers increasingly expose the same residential network through several protocols, allowing customers to choose the interface best suited to each workflow.
SOCKS5 remains important because it can handle a wider range of traffic and applications. However, the market's concentration around web data allows HTTP and HTTPS to retain the largest commercial position throughout the forecast period.
By Application: Web Scraping and Data Collection
Web scraping and data collection are projected to generate approximately USD 1.35 billion in residential proxy revenue by 2031, remaining the largest application. Businesses use these services to collect product information, prices, reviews, search results, travel data and other publicly accessible information across large numbers of websites.
The segment is changing as providers move from raw connectivity toward managed extraction. Rather than requiring customers to integrate proxies, browsers and parsing systems separately, newer platforms can manage the entire request and return structured information.
Artificial intelligence increases the relevance of this model because applications increasingly require continuously refreshed external information. Residential proxy infrastructure consequently becomes part of a broader web-data pipeline rather than an isolated networking product.
Regional Analysis
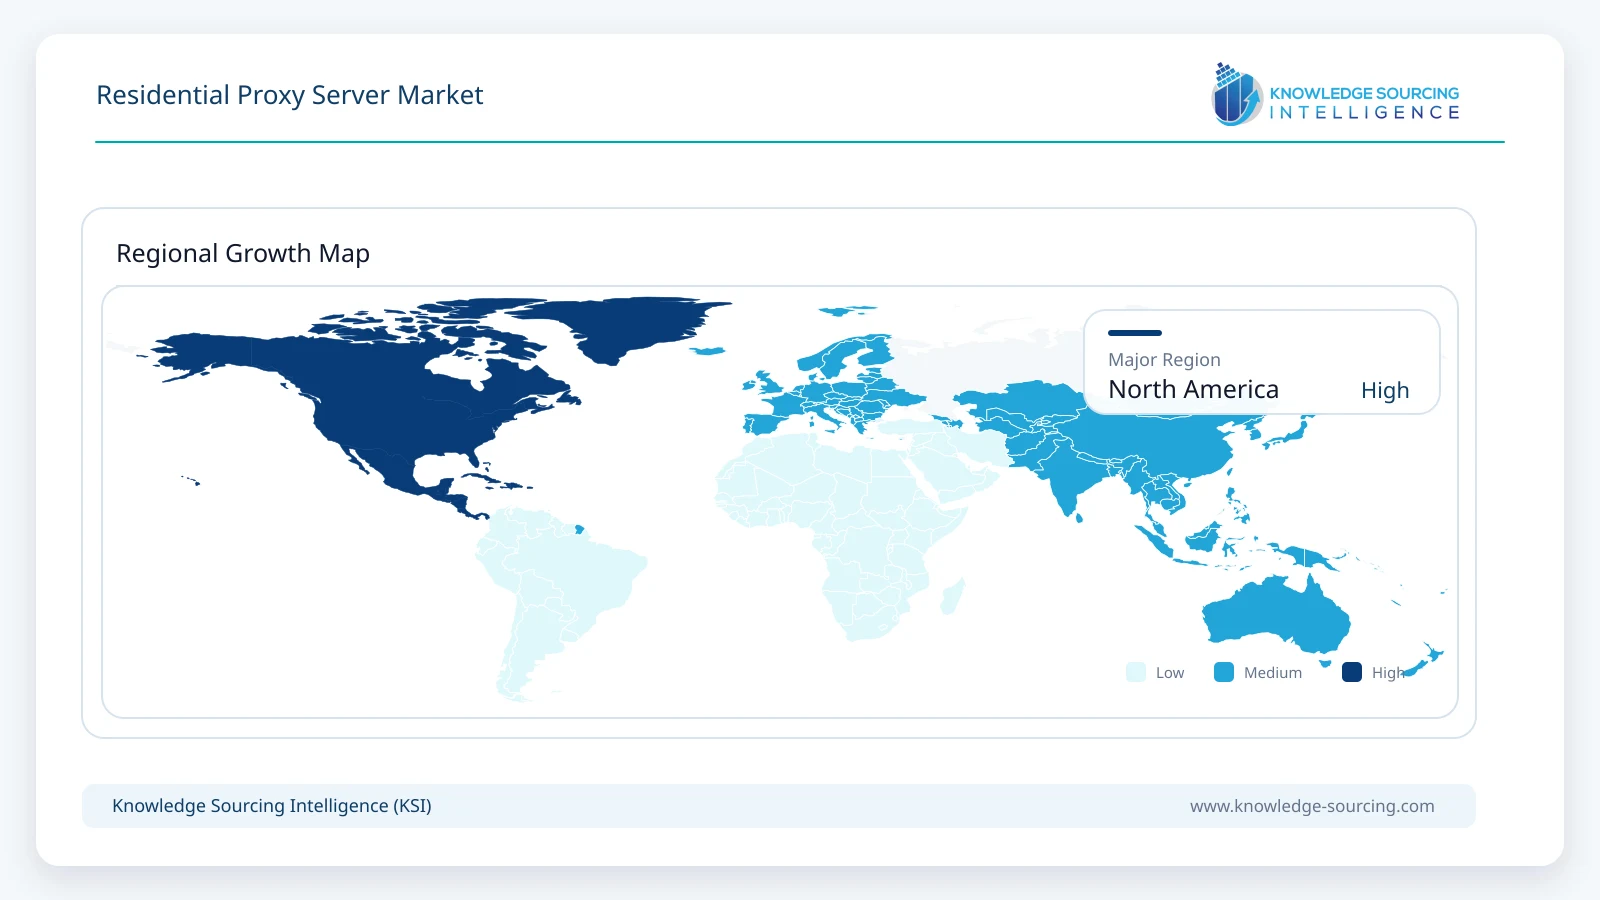
Major Region: North America
North America is projected to generate approximately USD 1.08 billion in residential proxy server revenue by 2031, remaining the largest regional market. The region combines extensive e-commerce activity, digital advertising, AI development and enterprise analytics with a high concentration of companies purchasing public web-data services.
Its businesses use residential networks for competitive pricing, search intelligence, advertisement auditing, travel information and AI-related data collection. Large international proxy providers also maintain extensive North American address coverage because the United States and Canada are high-value target locations for global data projects.
Growth remains supported by these commercial applications even as procurement teams apply greater scrutiny to sourcing, privacy and cybersecurity practices.
Major Country: United States
The United States is projected to generate approximately USD 810 million in residential proxy server revenue by 2031, remaining the largest individual national market.
The country's scale in e-commerce, advertising technology and artificial intelligence creates substantial demand for real-time public web information. US websites are also common targets for international data collection, increasing demand for American residential IP addresses among customers located outside the country.
Large providers consequently maintain sizeable US pools and offer targeting below the country level. This combination of domestic enterprise consumption and international demand for localized access keeps the United States central to market development through 2031.
Competitive Environment and Analysis
The residential proxy server market includes large web-data infrastructure providers, specialist proxy companies and lower-cost self-service suppliers. Bright Data and Oxylabs occupy prominent enterprise positions, while Decodo, SOAX, IPRoyal, Webshare, Infatica, Rayobyte and other companies compete through different combinations of pricing, location coverage, network scale and ease of use.
Network size remains visible in competitive positioning, but it does not determine performance on its own. Oxylabs reports more than 175 million residential IPs, SOAX advertises more than 155 million and Decodo provides over 115 million, while Bright Data markets an even larger available residential pool. Buyers increasingly evaluate these figures together with successful request rates, targeting granularity, network sourcing and integration capabilities.
Competition is also extending beyond proxy traffic. Bright Data and Oxylabs generate substantial revenue from broader web-data infrastructure, while Decodo's product strategy now includes scraping APIs and AI-oriented data collection. This transition makes software capability increasingly important because customers can choose between building their own collection system or purchasing a managed solution.
Ethical sourcing provides another point of differentiation following the disruption of problematic residential networks during 2026. Providers able to document how users join their networks and demonstrate stronger governance have a clearer proposition for enterprise procurement teams.
Price nevertheless remains important, particularly among developers and smaller companies. Self-service providers have reduced per-gigabyte rates significantly, making residential networks accessible to users that previously depended on data-center proxies. The market therefore supports both premium enterprise platforms and lower-cost traffic-oriented services.
Recent Developments
September 2026: Google continued coordinated action against malicious residential proxy infrastructure, including the NetNut network, following its earlier disruption of IPIDEA.
July 2026: Oxylabs received a USD 130 million investment from Warburg Pincus, valuing the group at approximately USD 3.6 billion as it expands its web-data and AI infrastructure business.
January 2026: Google Threat Intelligence Group and its partners disrupted the IPIDEA residential proxy network, reducing its available device pool by millions and increasing industry attention on consent-based IP sourcing.
2026: Decodo expanded its residential proxy pool to more than 115 million IPs across over 195 locations, alongside continued development of scraping and public web-data tools.
April 2025: Smartproxy rebranded as Decodo, reflecting its expansion from proxy connectivity into a broader public web-data platform.
Market Outlook
The global residential proxy server market is forecast to increase from USD 1.92 billion in 2026 to USD 3.05 billion by 2031, representing a CAGR of approximately 9.7%. Its growth is increasingly connected with the broader expansion of public web-data infrastructure.
Rotating networks remain the principal service model because they support high-volume collection across many locations, while HTTP/HTTPS connectivity retains the largest protocol position due to the market's concentration around web applications. Price intelligence, AI data pipelines and e-commerce monitoring continue to expand the addressable commercial base.
The competitive environment becomes more demanding as anti-bot technologies improve and residential-network sourcing receives greater scrutiny. Simply offering a large IP pool is therefore becoming less sufficient; customers increasingly require reliable request performance, granular targeting, transparent sourcing and software that simplifies complex collection workflows.
Residential proxies consequently evolve from a specialist networking product into one component of a broader data-access infrastructure used by enterprises to observe and analyze the continuously changing public internet.
Residential Proxy Server Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 1.92 billion |
| Total Market Size in 2031 | USD 3.05 billion |
| Forecast Unit | Billion |
| Growth Rate | 9.7% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Protocol, Application, Geography |
| Companies |
|
Market Segmentation
By Type
Static Residential / ISP Proxy
Rotating Residential Proxy
By Protocol
HTTP/HTTPS
SOCKS5
By Application
Web Scraping and Data Collection
SEO and SERP Monitoring
Advertising Verification
Price Intelligence and Market Research
Brand Protection
Application and Localization Testing
Social Media Management
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Spain
Lithuania
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Indonesia
Singapore
Australia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Residential IP Sourcing and Network Architecture
3.7. Rotation and Session Management
3.8. Anti-Bot and Web Access Environment
3.9. Ethical Sourcing and Enterprise Compliance
3.10. Pricing and Bandwidth Economics
3.11. AI and Public Web Data Infrastructure
3.12. Strategic Recommendations
4. RESIDENTIAL PROXY SERVER MARKET BY TYPE
4.1. Introduction
4.2. Static Residential / ISP Proxy
4.3. Rotating Residential Proxy
5. RESIDENTIAL PROXY SERVER MARKET BY PROTOCOL
5.1. Introduction
5.2. HTTP/HTTPS
5.3. SOCKS5
6. RESIDENTIAL PROXY SERVER MARKET BY APPLICATION
6.1. Introduction
6.2. Web Scraping and Data Collection
6.3. SEO and SERP Monitoring
6.4. Advertising Verification
6.5. Price Intelligence and Market Research
6.6. Brand Protection
6.7. Application and Localization Testing
6.8. Social Media Management
6.9. Others
7. RESIDENTIAL PROXY SERVER MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. By Type
7.2.2. By Protocol
7.2.3. By Application
7.2.4. By Country
7.2.4.1. United States
7.2.4.2. Canada
7.2.4.3. Mexico
7.3. South America
7.3.1. By Type
7.3.2. By Protocol
7.3.3. By Application
7.3.4. By Country
7.3.4.1. Brazil
7.3.4.2. Argentina
7.3.4.3. Others
7.4. Europe
7.4.1. By Type
7.4.2. By Protocol
7.4.3. By Application
7.4.4. By Country
7.4.4.1. United Kingdom
7.4.4.2. Germany
7.4.4.3. France
7.4.4.4. Spain
7.4.4.5. Lithuania
7.4.4.6. Others
7.5. Middle East and Africa
7.5.1. By Type
7.5.2. By Protocol
7.5.3. By Application
7.5.4. By Country
7.5.4.1. Saudi Arabia
7.5.4.2. UAE
7.5.4.3. Israel
7.5.4.4. South Africa
7.5.4.5. Others
7.6. Asia Pacific
7.6.1. By Type
7.6.2. By Protocol
7.6.3. By Application
7.6.4. By Country
7.6.4.1. China
7.6.4.2. India
7.6.4.3. Japan
7.6.4.4. South Korea
7.6.4.5. Indonesia
7.6.4.6. Singapore
7.6.4.7. Australia
7.6.4.8. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Residential IP Pool and Geographic Coverage
8.3. Pricing and Service Positioning
8.4. Network Sourcing and Compliance
8.5. Web Data Platform Integration
8.6. Mergers, Investments, Agreements, and Collaborations
8.7. Competitive Dashboard
9. COMPANY PROFILES
9.1. Bright Data Ltd.
9.2. Oxylabs
9.3. Decodo
9.4. SOAX
9.5. IPRoyal Services FZE LLC
9.6. Webshare Software Inc.
9.7. Infatica
9.8. Rayobyte
9.9. ProxyEmpire
9.10. DataImpulse
9.11. Massive
9.12. Evomi
9.13. Shifter
9.14. PacketStream
9.15. NodeMaven
10. APPENDIX
10.1. Market Definition and Scope
10.2. Currency
10.3. Assumptions
10.4. Base and Forecast Years
10.5. Research Methodology
10.6. Segment Modelling
10.7. Data Triangulation and Validation
10.8. Abbreviations
Navigate
Trusted by the world's leading organizations











