
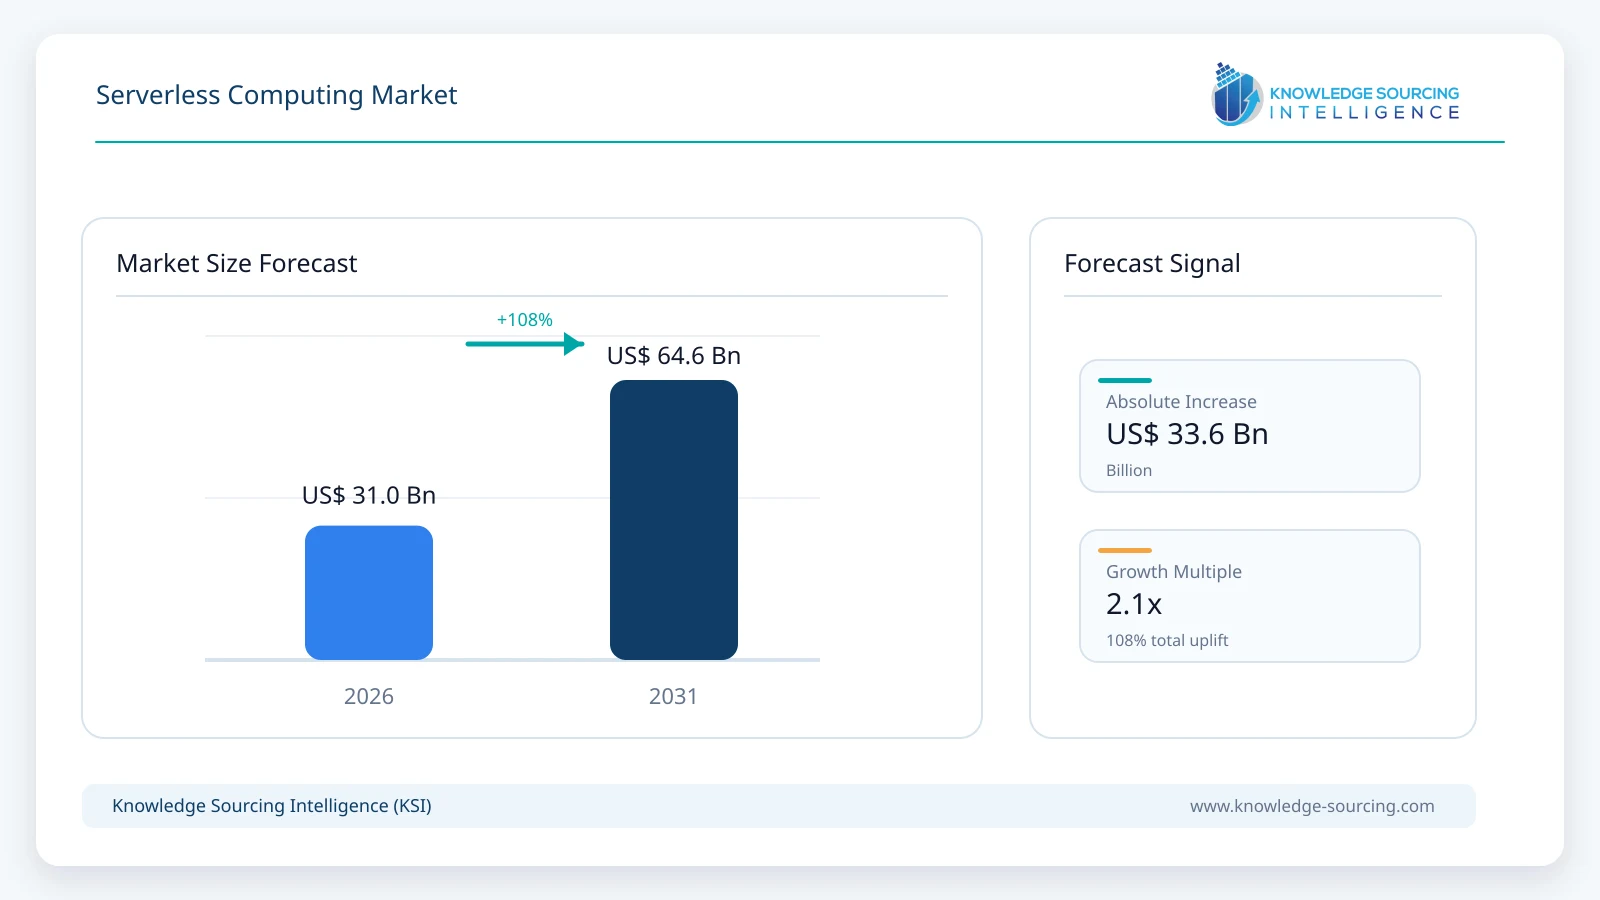
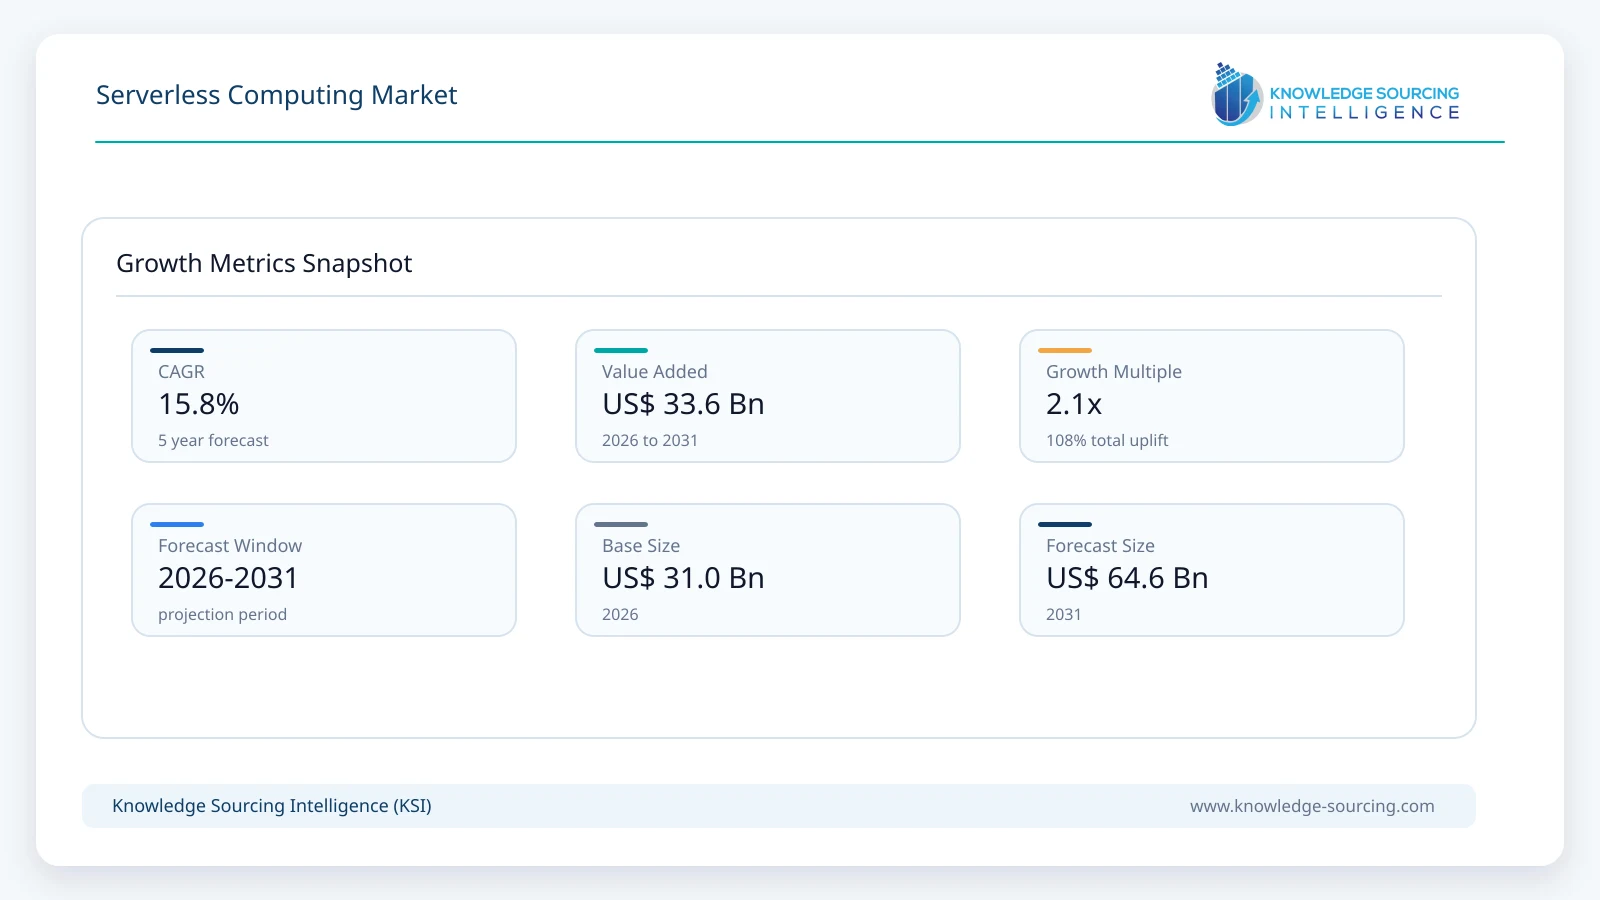
The serverless computing market is estimated at USD 31.0 billion in 2026 and is projected to reach USD 64.6 billion by 2031, expanding at a CAGR of 15.8% during the forecast period.
Highlights:
- 1Serverless compute and Function-as-a-Service account for approximately USD 14.0 billion of 2026 market value.
- 2API, microservice and event-driven application workloads contribute approximately USD 9.6 billion in 2026.
- 3Large enterprises account for approximately USD 19.2 billion of global serverless spending in 2026.
- 4IT and telecom users represent approximately USD 7.1 billion of 2026 demand.
- 5North America accounts for approximately USD 12.4 billion of the global market in 2026.
The market includes fully managed cloud services that abstract server provisioning and scale compute or application resources automatically in response to requests, events, scheduled jobs or application demand. Revenue is measured across serverless compute, serverless application platforms and containers, managed backend and data services, and event-driven workflow or integration services where infrastructure operation is materially abstracted from the customer.
The market has moved beyond the original Function-as-a-Service model. Enterprises now use serverless platforms for APIs, microservices, asynchronous data processing, web backends, automation, AI-agent execution, coding sandboxes and event-driven integration. The commercial boundary is increasingly defined by operating model rather than product label: automatic scaling, usage-based charging, limited infrastructure administration and the ability to scale toward zero remain the core characteristics.
Serverless economics are also becoming more sophisticated. Enterprises no longer evaluate only invocation price. Concurrency, memory allocation, CPU time, network egress, minimum instances, always-ready capacity, cold-start latency and downstream database limits increasingly determine the real cost per transaction. This shifts vendor competition toward workload efficiency and predictable performance rather than headline request pricing alone.
Growth is supported by a widening serverless workload envelope rather than simple migration of short-lived functions. Managed containers, event buses, durable workflows, serverless databases, AI-agent runtimes and isolated execution environments are increasing revenue per application while keeping the operational model serverless. The market also benefits from continued migration away from fixed-capacity infrastructure for bursty and event-driven workloads.
Serverless Computing Market Trends
Usage-Based Pricing is Shifting Toward Workload-Level Cost Engineering
The original serverless value proposition was simple: do not pay for idle servers. In production, however, execution economics depend on several meters at once. Google Cloud Run currently prices active CPU at about USD 0.000024 per vCPU-second, memory at about USD 0.0000025 per GiB-second and requests at USD 0.40 per million before discounts and free allowances. Cloudflare Workers charges USD 0.30 per additional million requests on its paid plan and separately meters CPU time, while Fastly Compute combines request and vCPU-millisecond pricing. At scale, execution duration, concurrency and data transfer can therefore matter more than invocation count.
This changes procurement behavior. A platform that appears cheaper per million requests can be more expensive for CPU-heavy or low-concurrency workloads, while high concurrency can spread CPU and memory cost across more requests. Engineering teams are increasingly benchmarking cost per transaction, cost per workflow and cost per active user rather than comparing only list prices. Observability and FinOps tooling consequently become part of the serverless buying decision.
Cold-Start Mitigation is Creating a Hybrid Between Pure Consumption and Reserved Readiness
Enterprise adoption has forced providers to address the latency trade-off created when workloads scale to zero. Azure Functions Flex Consumption now supports always-ready instances, private networking, per-function scaling and up to 1,000 scale-out instances. Google Cloud Run allows minimum instances, while other platforms use similar prewarming or provisioned-capacity mechanisms. The result is commercially important: serverless no longer means zero standing capacity in every deployment. Buyers can purchase a small always-on baseline for latency-sensitive functions while retaining burst elasticity above that floor.
This model broadens serverless into workloads previously considered too latency-sensitive for scale-to-zero platforms, including customer-facing APIs, payment flows and interactive enterprise applications. It also means cost optimization requires balancing standby capacity against cold-start exposure rather than maximizing scale-to-zero.
AI Workloads are Expanding Serverless From Functions Into Isolated Execution Environments
AI coding assistants, agents and user-generated applications are creating a new serverless workload: running untrusted or dynamically generated code in isolated environments for short periods. AWS introduced Lambda MicroVMs in June 2026 with VM-level isolation, near-instant launch and state preservation. AWS states that the underlying Lambda platform now handles more than 15 trillion monthly invocations. These workloads require stronger isolation and sometimes state retention, extending serverless design beyond stateless request handlers.
The same expansion is visible elsewhere. Google reported in April 2026 that external active developers and applications on Cloud Run doubled during 2025, with more new customers and applications joining during that year than in its first six years combined. Cloud Run is also being positioned for AI models and agents. This makes AI a revenue-expansion mechanism for serverless platforms because the workload can consume materially more CPU, memory and accelerator capacity than traditional lightweight functions.
Serverless Functions and Containers are Converging
The practical distinction between FaaS and serverless containers is narrowing. Google deploys source-based functions onto Cloud Run infrastructure, Microsoft supports Functions alongside Azure Container Apps, and AWS continues extending Lambda toward more flexible execution models. Developers increasingly choose between a function, container or managed application runtime based on packaging, concurrency, execution duration, networking and language requirements rather than on separate architectural philosophies.
This convergence expands addressable workloads but also changes competitive positioning. Function platforms must support larger payloads, longer execution, private networking and richer runtimes, while serverless container platforms must preserve scale-to-zero and fine-grained billing. Providers that cover both patterns can retain workloads as applications become more complex.
Edge Serverless is Competing on Latency and Data Locality
Edge serverless platforms shift execution closer to users and data. Cloudflare Workers deploys by default across more than 335 cities and markets no-cold-start execution, while Fastly Compute uses usage-based request and CPU pricing across its edge network. The commercial value is strongest for request transformation, personalization, security logic, low-latency APIs and globally distributed applications where sending every request back to a central cloud region adds avoidable latency or data-transfer cost.
Segment Analysis
By Service Category - Serverless Compute / Function-as-a-Service
Serverless compute and Function-as-a-Service are estimated at approximately USD 14.0 billion in 2026, making this the largest service category. AWS Lambda, Azure Functions, Google Cloud Run functions, IBM Code Engine and comparable services handle event-triggered code execution without customers provisioning hosts. The category remains the most recognizable serverless model because it directly converts application activity into compute consumption.
Commercial differentiation is increasingly driven by what happens beyond the invocation. Concurrency determines how efficiently each instance handles traffic; memory and CPU configuration change the cost curve; private-network support controls enterprise suitability; and always-ready capacity affects latency. AWS's move into isolated MicroVMs and Azure's Flex Consumption model show that the category is expanding upward into workloads that once required dedicated containers or VMs. This raises average revenue per workload while preserving the managed scaling model.
The principal constraint is that function-level billing can become less economical for continuously busy workloads. Once utilization remains high for long periods, serverless buyers compare consumption pricing against reserved containers or VMs. Platform providers therefore compete by improving concurrency, execution efficiency and committed-use discounts so that customers do not automatically graduate away from serverless as traffic grows.
By Application - APIs, Microservices and Event-Driven Applications
APIs, microservices and event-driven applications account for approximately USD 9.6 billion in 2026 and form the largest application group. These workloads map naturally to serverless because traffic is variable, execution units are independently scalable and events can trigger processing without a permanently running application server. Typical patterns include API backends, webhooks, order events, file processing, notifications and service-to-service automation.
The buying decision increasingly extends beyond compute to the event and orchestration layer. API gateways, event buses, queues, workflow engines and managed identity frequently generate additional platform revenue around the serverless function itself. AWS Step Functions, EventBridge, Azure Durable Functions and Google Eventarc illustrate how providers monetize an event-driven application as a collection of managed services rather than a single compute meter.
This architecture also creates switching friction. Function code may be portable, but triggers, identity models, workflow definitions, observability and data services are often provider-specific. Consequently, enterprise serverless adoption can deepen cloud-platform commitment even when the execution layer uses open runtimes.
By Enterprise Size - Large Enterprises
Large enterprises are estimated to account for approximately USD 19.2 billion of serverless spending in 2026. Their share is driven less by the number of applications than by integration complexity, multi-region requirements, security controls, private networking, observability and higher aggregate transaction volumes. Serverless adoption has moved from isolated developer experiments into production APIs, data pipelines and event-processing systems.
Enterprise requirements are also changing provider product design. Azure Flex Consumption adds virtual-network integration and always-ready capacity; AWS continues increasing payload and execution flexibility; and Google Cloud Run combines managed scaling with container packaging. These features address the gap between developer convenience and enterprise requirements for predictable networking, controlled rollout, security boundaries and performance.
The main commercial friction is governance. Rapid function creation can fragment observability, permissions and cost ownership across hundreds or thousands of deployed services. Enterprises therefore increasingly standardize runtime templates, centralized logging, policy-as-code and FinOps controls before expanding serverless across business units.
By End User - IT and Telecommunications
IT and telecommunications users contribute approximately USD 7.1 billion of the market in 2026. The sector combines high API volumes, event streams, digital customer channels, network automation and software-development workloads that benefit from elastic execution. Serverless is particularly attractive for irregular control-plane tasks, event-driven data processing and digital services whose demand varies sharply over time.
Telecommunications workloads also demonstrate why serverless economics are not limited to scale-to-zero. High-volume services can remain continuously active but still benefit from automatic scaling and reduced infrastructure operations. For these workloads, concurrency, regional presence, networking charges and integration with streaming or messaging services influence platform economics more than the availability of a free invocation tier.
By Geography - North America
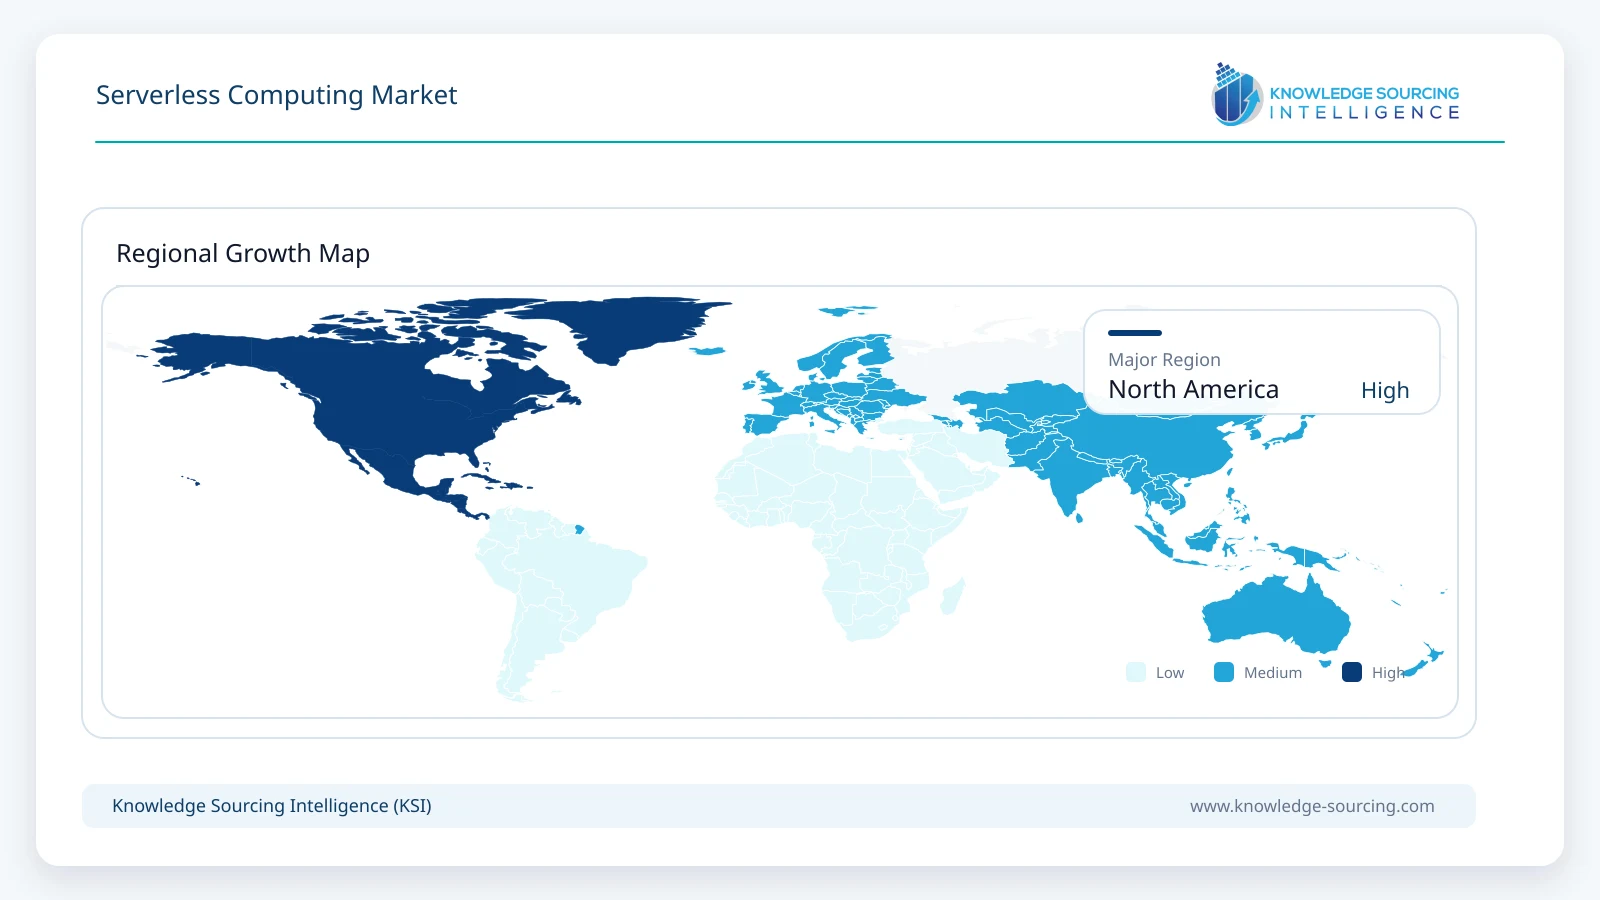
North America is estimated at approximately USD 12.4 billion in 2026, making it the largest regional market. The region contains the headquarters and largest customer ecosystems of AWS, Microsoft, Google Cloud, Cloudflare, Fastly, Vercel and several other serverless-platform providers. High public-cloud penetration, mature DevOps practices and large software, financial-services, retail and media sectors support broad production adoption.
The region is also where serverless product boundaries are changing fastest. Providers are adding stateful execution, serverless containers, AI-agent hosting, edge compute and always-ready capacity. This increases the addressable spend per customer but also brings serverless into more direct competition with Kubernetes, managed container services and reserved cloud compute.
Market Drivers
Event-driven applications and microservices are increasing demand for automatically scaling execution and orchestration.
AI agents and user-generated code are expanding demand for secure, short-duration isolated compute environments.
Serverless containers are extending the operating model to applications that do not fit traditional function limits.
Edge execution is increasing adoption for latency-sensitive APIs, personalization and security logic.
Enterprise demand for reduced infrastructure administration is supporting managed compute even where scale-to-zero is not the primary benefit.
Market Restraints
High and steady utilization can make consumption-based serverless more expensive than reserved containers or virtual machines.
Cold-start latency remains relevant for selected languages and interactive workloads unless customers pay for warm capacity.
Provider-specific event, identity, workflow and observability services can increase architectural lock-in.
Downstream databases and APIs may not scale as quickly as functions, forcing customers to limit serverless concurrency.
Execution, networking and observability charges can make production cost harder to predict than simple request pricing suggests.
Competitive Environment
Competition is concentrated around hyperscale cloud providers but increasingly differentiated by execution model. AWS Lambda remains the most established FaaS platform; Microsoft Azure Functions is shifting new Linux deployments toward Flex Consumption; and Google Cloud is converging functions with Cloud Run. Cloudflare, Fastly and Akamai compete from the edge, while Vercel and Netlify package serverless execution into application-development platforms. IBM, Oracle, Alibaba Cloud, Tencent Cloud, Huawei Cloud, DigitalOcean and Red Hat provide additional enterprise and regional alternatives.
The competitive metric is no longer only function count or supported languages. Providers increasingly compete on cold-start behavior, scale-out speed, concurrency, state handling, private networking, GPU availability, edge presence, developer experience, observability and the economics of running large workloads continuously. The market is therefore moving from a narrowly defined FaaS category toward a broader managed application-execution layer.
Recent Developments
September 2026: AWS Step Functions added automatic integration with new AWS services, beginning with Lambda MicroVMs and Lambda Core, extending serverless orchestration for agentic workloads.
August 2026: AWS Lambda introduced public-preview runtimes, beginning with Node.js 26 and Python 3.15, allowing pre-GA runtime testing before production release.
June 2026: AWS introduced Lambda MicroVMs for isolated, stateful execution of user- and AI-generated code with VM-level isolation and near-instant startup.
April 2026: Google reported that external active developers and applications on Cloud Run doubled during 2025 and expanded Cloud Run for AI models and agents.
2026: Microsoft continued migration toward Azure Functions Flex Consumption, combining pay-per-use execution with private networking, per-function scaling and optional always-ready instances.
2026: Cloudflare expanded Dynamic Workers billing for platforms that create and execute customer-specific Workers while retaining request- and CPU-based usage pricing.
Market Outlook
Serverless computing is likely to remain one of the fastest-growing cloud execution models through 2031, but the category will look progressively less like its original short-function definition. Functions, serverless containers, isolated MicroVMs, edge runtimes and AI-agent platforms are converging around a common operating principle: customers specify code or workload requirements while the provider controls placement, scaling and infrastructure lifecycle.
The commercial outcome is a larger addressable market but a more complex cost model. Providers that can make burst workloads inexpensive while also supporting low-latency, high-concurrency and continuously active applications can retain customers across a wider portion of the application lifecycle. Buyers, meanwhile, will increasingly benchmark complete application cost including networking, orchestration, observability and always-ready capacity rather than treating serverless as an invocation-price comparison.
Serverless Computing Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 31.0 billion |
| Total Market Size in 2031 | USD 64.6 billion |
| Forecast Unit | Billion |
| Growth Rate | 15.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Service Category, Application, Enterprise Size, End User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Service Category
Serverless Compute / Function-as-a-Service
Serverless Application Platforms and Containers
Serverless Backend and Data Services
Serverless Workflow and Integration Services
By Application
APIs, Microservices and Event-Driven Applications
Data Processing and Streaming
Web and Mobile Backends
AI, Agents and Isolated Code Execution
Automation and Integration
By Enterprise Size
Large Enterprises
Small and Medium Enterprises
By End User
IT and Telecommunications
BFSI
Retail and E-Commerce
Media and Entertainment
Healthcare and Life Sciences
Manufacturing
Government and Other Industries
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Spain
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Singapore
Australia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition and Scope
1.3. Revenue Reference Point
1.4. Currency and Assumptions
2. RESEARCH METHODOLOGY
2.1. Secondary Research
2.2. Provider and Product Validation
2.3. Market Estimation and Forecasting
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Global Market Size, 2026-2031
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Consumption Pricing and FinOps
4.4. Cold Starts, Concurrency and Always-Ready Capacity
4.5. AI and Agentic Workloads
4.6. Vendor Lock-In and Portability
5. SERVERLESS COMPUTING MARKET BY SERVICE CATEGORY
5.1. Serverless Compute / Function-as-a-Service
5.2. Serverless Application Platforms and Containers
5.3. Serverless Backend and Data Services
5.4. Serverless Workflow and Integration Services
6. SERVERLESS COMPUTING MARKET BY APPLICATION
6.1. APIs, Microservices and Event-Driven Applications
6.2. Data Processing and Streaming
6.3. Web and Mobile Backends
6.4. AI, Agents and Isolated Code Execution
6.5. Automation and Integration
7. SERVERLESS COMPUTING MARKET BY ENTERPRISE SIZE
7.1. Large Enterprises
7.2. Small and Medium Enterprises
8. SERVERLESS COMPUTING MARKET BY END USER
8.1. IT and Telecommunications
8.2. BFSI
8.3. Retail and E-Commerce
8.4. Media and Entertainment
8.5. Healthcare and Life Sciences
8.6. Manufacturing
8.7. Government and Other Industries
9. SERVERLESS COMPUTING MARKET BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. Germany
9.3.2. United Kingdom
9.3.3. France
9.3.4. Spain
9.3.5. Italy
9.3.6. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. UAE
9.4.3. South Africa
9.4.4. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. India
9.5.3. Japan
9.5.4. South Korea
9.5.5. Singapore
9.5.6. Australia
9.5.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Hyperscale Cloud Platforms
10.2. Edge Serverless Platforms
10.3. Application Development Platforms
10.4. Pricing and Performance Benchmarking
10.5. Strategic Developments
11. COMPANY PROFILES
11.1. Amazon Web Services, Inc.
11.2. Microsoft Corporation
11.3. Google LLC
11.4. Cloudflare, Inc.
11.5. IBM Corporation
11.6. Oracle Corporation
11.7. Alibaba Cloud
11.8. Tencent Cloud
11.9. Huawei Technologies Co., Ltd.
11.10. DigitalOcean Holdings, Inc.
11.11. Fastly, Inc.
11.12. Akamai Technologies, Inc.
11.13. Vercel Inc.
11.14. Netlify, Inc.
11.15. Red Hat, Inc.
12. APPENDIX
12.1. Market Definition and Exclusions
12.2. Assumptions
12.3. Abbreviations





Frequently asked questions
What is the projected market value of serverless computing by 2031?
The Serverless Computing Market is projected to reach USD 64.6 billion by 2031.
What is the CAGR for the Serverless Computing Market (2026-2031)?
The Serverless Computing Market is expanding at a 15.8% CAGR during the forecast period.
Which region holds the largest share in the 2026 serverless market?
North America accounts for approximately USD 12.4 billion in 2026.
What is the market value of Function-as-a-Service in 2026?
Serverless compute and FaaS account for approximately USD 14.0 billion in 2026.
Which enterprise segment leads serverless spending in 2026?
Large enterprises account for approximately USD 19.2 billion of global spending.
What is a key evolving trend in serverless computing economics?
Usage-based pricing is shifting toward workload-level cost engineering.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Serverless Computing Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/serverless-computing-market