
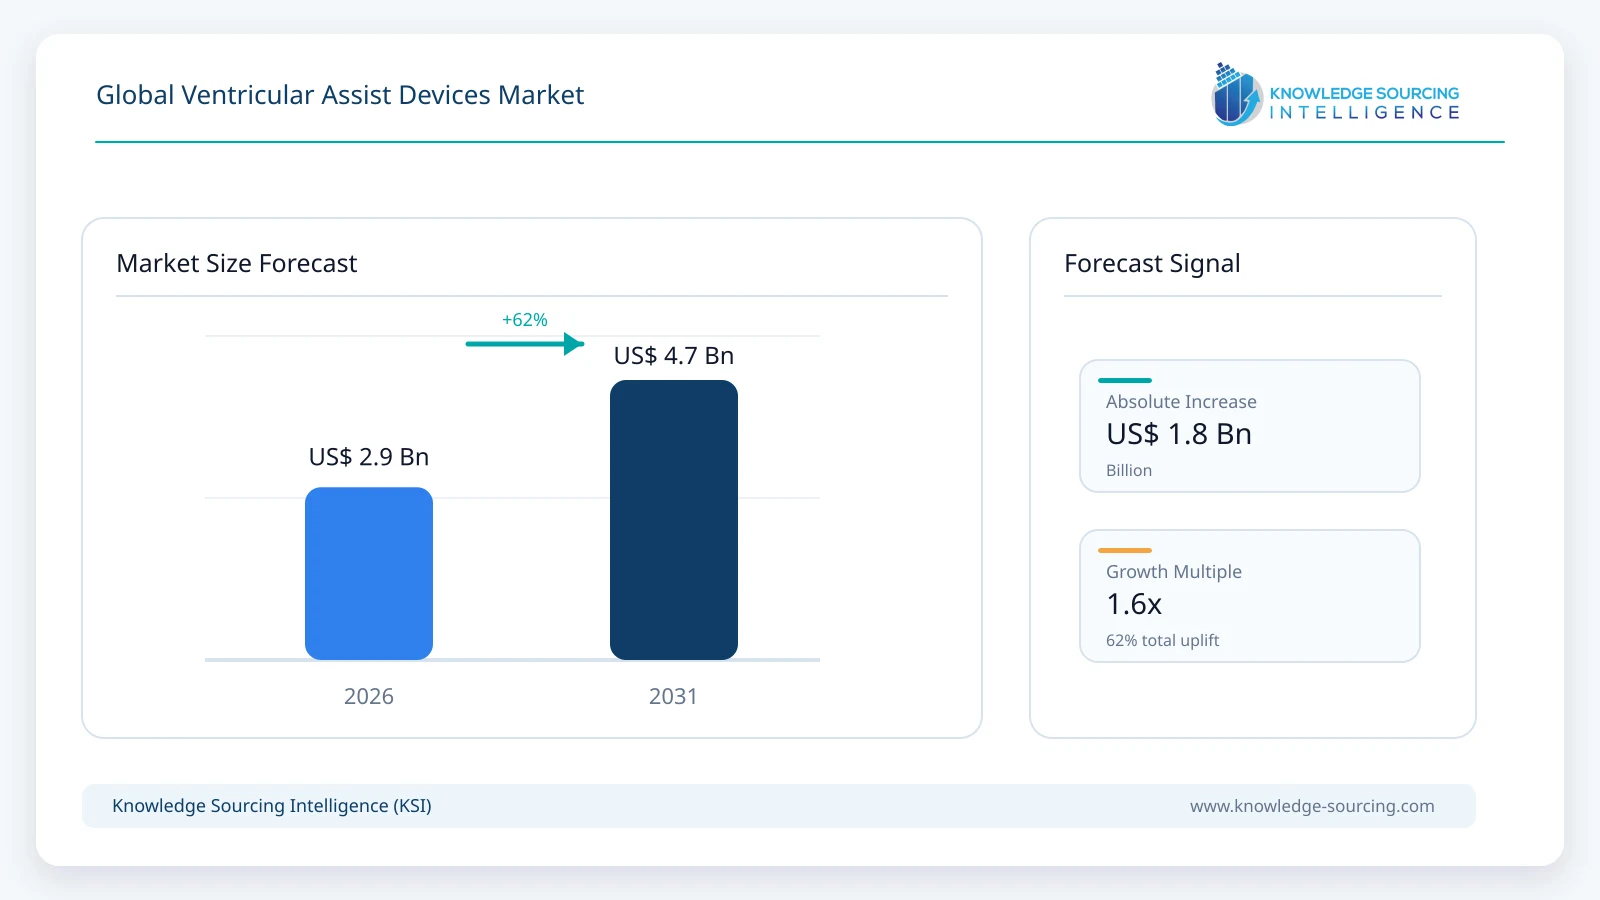
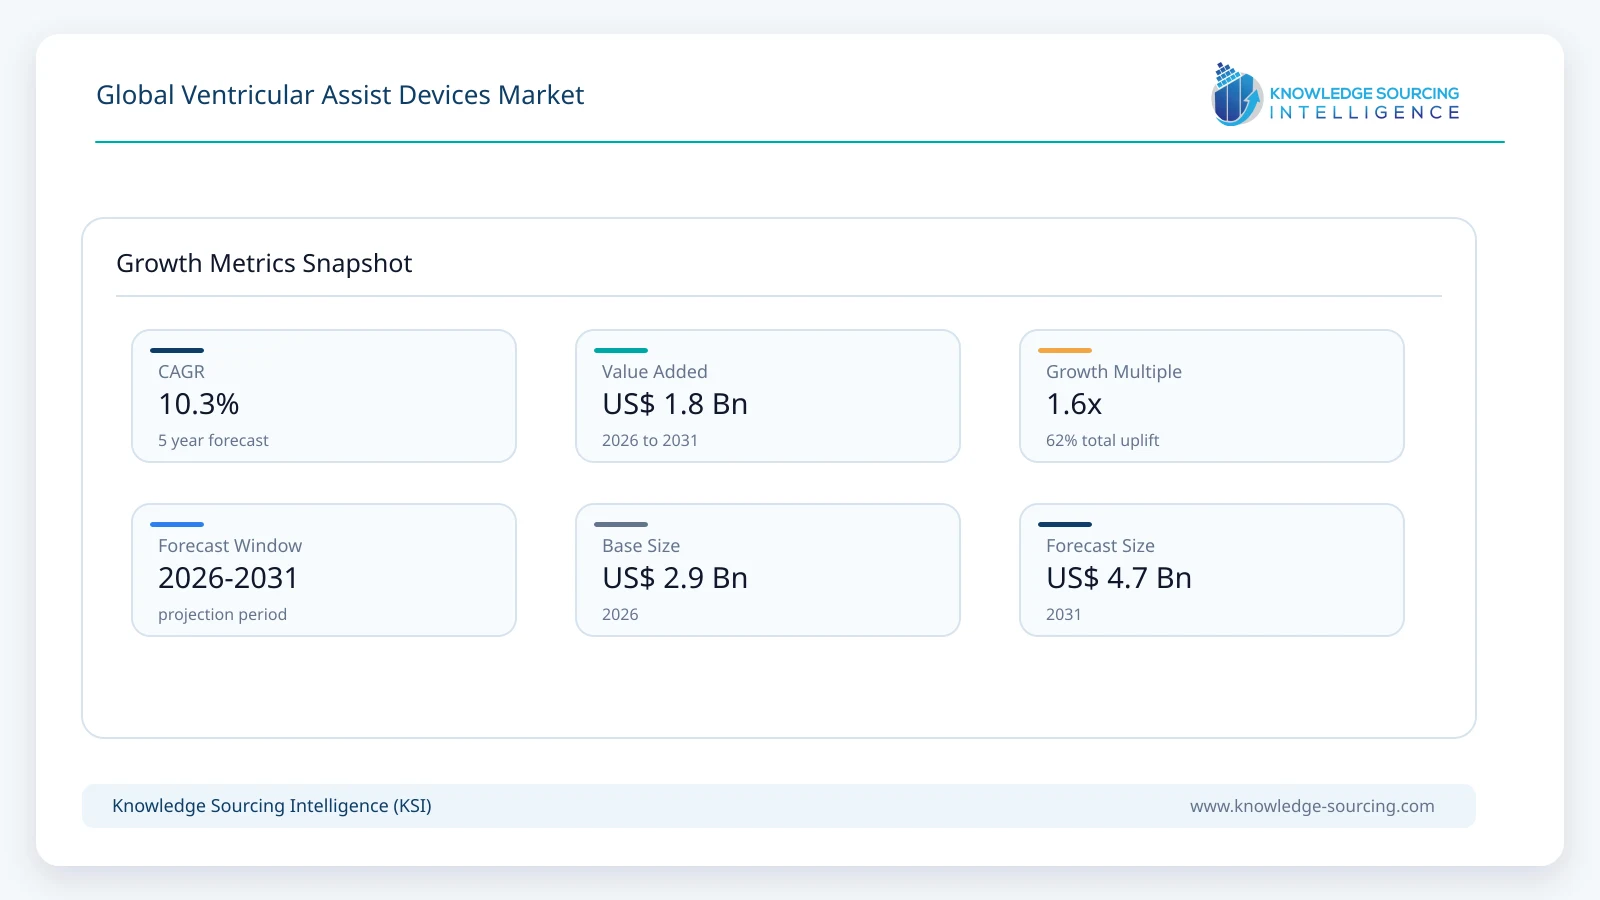
The global ventricular assist devices market is forecast to grow at a CAGR of 10.3%, reaching USD 4.7 billion in 2031 from USD 2.9 billion in 2026.
Highlights:
- 1Advanced heart failure and limited donor-organ availability are sustaining demand for durable mechanical circulatory support.
- 2LVADs remain the commercially important segment because of their broader established use in advanced left-sided heart failure.
- 3North America remains strategically important due to specialized implant centers, established reimbursement pathways, and extensive clinical infrastructure.
- 4Technology development is targeting smaller systems, improved hemocompatibility, reduced external hardware, and more physiologic circulatory support.
- 5Regulatory requirements remain a major competitive filter, with ventricular assist devices regulated as high-risk Class III devices in the United States.
- 6Competition is extending beyond established LVAD suppliers as emerging companies pursue differentiated pumps, temporary support systems, pediatric devices, and total circulatory support technologies.
The ventricular assist devices market comprises implantable, extracorporeal, and other mechanical circulatory support systems designed to assist or replace the pumping function of one or both ventricles in patients with severe cardiac failure. The market includes left ventricular assist devices (LVADs), right ventricular assist devices (RVADs), and biventricular assist devices (BiVADs), deployed across bridge-to-transplant, bridge-to-myocardial-recovery, and destination therapy applications.
Demand is concentrated in a relatively small number of specialized cardiac centers, but the commercial value per treated patient is high. A ventricular assist device purchase is not a conventional capital-equipment transaction. It involves the pump, controller, power system, accessories, surgical procedure, postoperative management, long-term patient monitoring, clinical training, and replacement or support components. Consequently, suppliers compete not only for initial implantation volume but also for recurring revenue associated with patient support and the installed device base.
The principal demand environment is shaped by advanced heart failure, limited donor-heart availability, and the clinical need to maintain circulation when pharmacological and conventional cardiac interventions are no longer sufficient. Heart transplantation remains an important treatment option for eligible patients, but the availability of donor organs does not match the potential clinical need. Mechanical circulatory support therefore occupies a strategic position between medical management and transplantation, while destination therapy expands the addressable patient population to individuals who are not suitable transplant candidates.
Buyer priorities differ according to the clinical setting. Transplant centers emphasize survival outcomes, adverse-event profiles, surgical familiarity, reliability, and compatibility with established clinical pathways. Hospital administrators also assess total episode-of-care costs, reimbursement, inventory requirements, and the resource intensity of long-term follow-up. Procurement decisions are therefore influenced by multidisciplinary teams rather than a single purchasing department.
The industry has a concentrated commercial structure in established implantable LVADs, while newer companies are attempting to differentiate through alternative pump architectures, reduced thrombogenicity, miniaturization, physiologic flow characteristics, fully implantable systems, or new approaches to biventricular and total circulatory support. This creates two distinct competitive arenas. Incumbents benefit from clinical experience, installed infrastructure, physician familiarity, and regulatory approvals. Development-stage companies compete by addressing unresolved clinical and operational limitations of current systems.
LVADs represent the most commercially established part of the market because left-sided heart failure is the principal indication for durable mechanical circulatory support. Abbott's HeartMate 3 system is indicated for short- and long-term mechanical circulatory support, including bridge to transplant, myocardial recovery, and destination therapy, illustrating the broad application profile available within the LVAD category.
RVAD and BiVAD demand follows a different purchasing pattern. These devices are generally associated with more complex hemodynamic conditions, acute right-heart dysfunction, postoperative complications, congenital or pediatric cases, and patients requiring support of both ventricles. Volumes are smaller, but clinical complexity is higher. Suppliers serving these categories must therefore compete on flexibility, patient-size suitability, ease of implantation, and compatibility with highly specialized treatment environments.
Revenue growth during 2026–2031 will depend less on broad-based hospital purchasing and more on expansion in eligible patient populations, referral networks, implanting-center capacity, reimbursement coverage, and successful commercialization of next-generation systems. The market's economics favor companies capable of supporting clinicians throughout the patient journey. Device performance alone is insufficient when a supplier cannot provide dependable clinical training, technical support, inventory management, and post-implantation infrastructure.
Technology adoption is also shifting toward systems that seek to reduce complications associated with mechanical circulatory support. Bleeding, infection, stroke, thrombosis, right-heart failure, device malfunction, and power-system dependence remain material clinical and economic considerations. Current device labeling for HeartMate 3, for example, identifies a broad range of potential adverse events, including bleeding, infection, neurological events, right-heart failure, renal dysfunction, and pump thrombosis. These risks influence hospital protocols, patient selection, monitoring intensity, and total treatment costs.
Supply-chain management has become another commercial consideration. Ventricular assist devices contain highly engineered pumps, electronics, controllers, batteries, cables, graft components, and sterile materials. FDA records show continued post-approval manufacturing and supplier modifications involving Abbott's HeartMate systems, including changes related to alternate suppliers, manufacturing processes, cables, batteries, and other components. Such activity demonstrates the importance of qualified supply continuity and component control in this high-risk device category.
Overall, the ventricular assist devices market is defined by high clinical specialization, concentrated purchasing, demanding regulatory requirements, and substantial barriers to entry. Commercial success depends on evidence generation, regulatory execution, physician adoption, hospital infrastructure, and long-term device support. These characteristics make the market attractive for companies with differentiated technology, but they also extend development timelines and increase the capital required to reach meaningful commercial scale.
Market Drivers
Growing Advanced Heart Failure Treatment Needs
The primary demand driver for ventricular assist devices is the need to support patients whose cardiac function cannot be adequately maintained through medical therapy or conventional interventions. Advanced heart failure creates a clinically urgent requirement for therapies capable of sustaining circulation while patients await transplantation, recover cardiac function, or receive long-term mechanical support.
The commercial mechanism is straightforward but highly specialized. As heart-failure patients progress into advanced disease stages, treatment options narrow. Hospitals and physicians require access to therapies that can stabilize hemodynamics and extend survival in appropriately selected patients. Ventricular assist devices address this requirement by providing mechanical circulatory support when ventricular function is severely compromised.
Buyers are principally transplant centers, tertiary hospitals, academic medical institutions, and advanced heart-failure programs. Their purchasing decisions depend on the number of eligible patients, surgeon experience, intensive-care capabilities, and the institution's capacity to manage long-term device recipients. As a result, patient referrals and center accreditation can influence market demand as strongly as general hospital spending.
Suppliers respond through clinical evidence, physician education, patient-management programs, and expansion of implanting-center capabilities. The commercial implication is that market development requires investment in clinical infrastructure. A device manufacturer can increase addressable demand by helping qualified centers develop the expertise required to identify, implant, and manage suitable patients.
Persistent Gap Between Heart Transplant Demand and Donor Availability
Heart transplantation remains dependent on donor availability and patient eligibility. This structural limitation supports demand for ventricular assist devices as bridge-to-transplant therapy and, in selected cases, longer-term support.
The value proposition differs according to the patient pathway. A bridge-to-transplant device must provide reliable support while preserving the patient's suitability for transplantation. Hospitals therefore assess durability, adverse events, infection risk, anticoagulation requirements, and the operational burden of managing patients before transplant.
This application also creates recurring demand because the duration of support can vary substantially. Longer waiting periods increase the importance of device reliability and follow-up infrastructure. Hospitals may therefore place greater value on suppliers with established clinical service networks and dependable component availability.
For manufacturers, the commercial opportunity lies in securing long-term relationships with transplant centers rather than pursuing isolated procedural sales. Once a center establishes clinical protocols around a particular system, switching costs can become meaningful because surgeons, nurses, coordinators, and patients are trained around established workflows.
Expansion of Destination Therapy
Destination therapy broadens the market beyond patients waiting for a transplant. It addresses individuals with advanced heart failure who are not appropriate transplant candidates but may still benefit from long-term mechanical circulatory support.
This application changes buyer behavior because treatment planning extends beyond the surgical procedure. Hospitals must evaluate whether patients can manage external components, comply with anticoagulation and monitoring requirements, and maintain adequate caregiver support. Patient selection therefore has a direct effect on clinical outcomes and healthcare costs.
Abbott's current HeartMate 3 indication includes destination therapy, alongside bridge-to-transplant and bridge-to-myocardial-recovery applications, underlining the commercial importance of systems capable of serving multiple advanced heart-failure pathways.
The expansion of destination therapy increases the importance of outpatient management. Suppliers that reduce the burden associated with power systems, driveline care, monitoring, and patient training may improve the economic proposition for hospitals and healthcare systems. This is one reason why fully implantable and wireless energy-transfer concepts continue to attract development investment.
Improvements in Pump Design and Hemocompatibility
Technology development remains a major driver because clinical complications directly affect adoption and lifetime treatment costs. Improvements in pump design are directed toward maintaining stable blood flow while reducing blood damage, thrombosis, and other device-related complications.
Established systems have demonstrated the commercial value of advanced pump engineering, while emerging companies are pursuing different approaches to circulatory support. CorWave, for example, is associated with a wave-membrane approach, while BiVACOR is developing an alternative architecture for complete circulatory support. Other companies are targeting miniaturized pumps, temporary mechanical support, or specialized pediatric applications.
The buyer response to new technology is likely to remain evidence-driven. Advanced heart-failure centers will not replace established treatment pathways solely because a device introduces a novel engineering concept. Manufacturers must demonstrate safety, reliability, clinical utility, and operational advantages.
Commercially, this favors companies capable of financing lengthy development and clinical programs. It also creates opportunities for differentiated suppliers if they can demonstrate meaningful reductions in complications, hospital resource use, or patient-management burden.
Expansion of Specialized Cardiac Care Infrastructure
The availability of ventricular assist devices depends on specialized infrastructure. Implantation requires trained surgeons, perfusion and cardiac teams, intensive-care resources, imaging capabilities, anticoagulation management, and long-term outpatient follow-up.
Expansion of advanced cardiac programs can therefore create incremental device demand. This is particularly relevant in emerging healthcare markets where cardiovascular disease treatment capacity is improving but advanced mechanical circulatory support remains concentrated in a limited number of institutions.
Manufacturers can influence this driver through training, clinical partnerships, technical support, and physician education. However, infrastructure development is capital intensive and dependent on national healthcare priorities. The pace of market expansion outside established treatment centers will consequently remain uneven.
Market Restraints and Challenges
High Treatment and Infrastructure Costs
Ventricular assist device therapy is expensive because the device is only one component of the total treatment pathway. Costs include surgery, hospitalization, intensive care, diagnostic monitoring, anticoagulation management, device accessories, and long-term follow-up.
The burden is particularly significant in healthcare systems with limited reimbursement for advanced mechanical circulatory support. Hospitals may have clinical interest in adopting a technology but remain constrained by budget impact and uncertainty regarding payment.
This affects manufacturers through longer sales cycles and restricted access to new centers. Suppliers can mitigate the challenge by supporting health-economic evidence, working with reimbursement stakeholders, improving service efficiency, and reducing avoidable device-related complications.
Clinical Complications and Patient Management Burden
Complications remain one of the most important barriers to wider adoption. Device recipients may face bleeding, infection, stroke, right-heart failure, thrombosis, and other adverse events. These risks increase the complexity of patient selection and can raise lifetime treatment costs.
The affected stakeholders include patients, hospitals, clinicians, payers, and manufacturers. Hospitals must allocate resources for monitoring and emergency management, while suppliers face the need for ongoing post-market surveillance and product improvement.
Current HeartMate 3 safety information illustrates the broad range of adverse events that must be considered during therapy selection and management.
Mitigation depends on better patient selection, clinical protocols, infection prevention, anticoagulation management, and improved device design. Companies pursuing technologies that reduce external hardware or improve blood compatibility are attempting to address this commercial barrier.
Stringent Regulatory and Clinical Evidence Requirements
Ventricular assist devices are high-risk systems. In the United States, ventricular bypass assist devices are regulated under the Class III framework, and the FDA recognizes standards specifically covering ventricular assist devices, including left and right heart support, BiVADs, total artificial hearts, percutaneous assist devices, and pediatric systems.
The regulatory burden creates a substantial entry barrier. Manufacturers must invest in engineering validation, biocompatibility, reliability testing, clinical evidence, quality systems, and post-market obligations.
For emerging companies, the result is a long period between prototype development and commercial revenue. Investors must therefore finance regulatory and clinical programs without immediate sales returns. Established manufacturers benefit from experience with regulatory submissions and mature quality-management infrastructure.
Concentrated Implanting-Center Capacity
Demand cannot expand simply through product availability. Many hospitals lack the multidisciplinary capabilities required to implant and manage durable ventricular assist devices. Procedures remain concentrated in specialized centers.
This limits geographic expansion and creates dependency on referral networks. Patients in regions without advanced heart-failure programs may face delayed access or require treatment at distant institutions.
Manufacturers can reduce this constraint through training and center-development initiatives, but supplier involvement cannot substitute for hospital investment. Consequently, market penetration in developing healthcare systems may remain slower than the underlying cardiovascular disease burden would suggest.
Manufacturing and Component-Supply Complexity
Mechanical circulatory support systems depend on specialized components and tightly controlled manufacturing processes. Changes involving batteries, cables, connectors, graft components, sterilization, or suppliers require extensive quality and regulatory oversight.
Recent FDA PMA supplements involving Abbott and Medtronic systems demonstrate that post-approval product maintenance can involve manufacturing, component, and supplier modifications.
Supply disruption can have disproportionate consequences because device availability affects life-sustaining treatment pathways. Manufacturers must therefore qualify alternative suppliers, maintain inventory resilience, and manage product changes without compromising regulatory compliance or clinical reliability.
Major Segment Analysis:
Left Ventricular Assist Devices
The LVAD segment is the most commercially important segment within the ventricular assist devices market because durable left-sided mechanical support has the broadest established application base in advanced refractory heart failure.
LVAD demand is supported by three distinct treatment pathways: bridge to transplant, bridge to myocardial recovery, and destination therapy. This range gives the segment greater commercial depth than narrower applications focused on acute right-heart support or highly complex biventricular conditions.
Buyer requirements are demanding. Advanced heart-failure and transplant programs assess long-term reliability, survival evidence, adverse-event performance, surgical handling, patient quality of life, outpatient management, and service availability. A favorable pump specification alone is insufficient because clinicians must manage the entire support system over extended periods.
The installed clinical ecosystem also provides incumbents with an important competitive advantage. Surgeons and multidisciplinary care teams develop protocols around specific devices. Hospitals invest in training, inventory, emergency procedures, and patient education. This creates practical switching barriers and gives suppliers with established systems a durable commercial position.
Abbott's HeartMate 3 remains a central reference point in the durable LVAD category. The system is indicated for short- and long-term support across bridge-to-transplant, myocardial-recovery, and destination-therapy applications.
However, the segment still contains important unmet needs. External drivelines and power systems create infection and lifestyle-management challenges. Anticoagulation requirements can limit patient eligibility, while adverse events continue to affect healthcare utilization.
These gaps provide an opportunity for companies developing alternative LVAD designs. CorWave's technology program and Calon Cardio's development activities reflect continued interest in improving the mechanical and physiologic characteristics of circulatory support. Emerging suppliers must nevertheless establish clinical evidence strong enough to justify adoption in a segment where hospitals already possess established treatment pathways.
Revenue implications extend beyond the implant procedure. A durable LVAD generates demand for controllers, batteries, cables, accessories, service, and patient support. As the number of patients living with implanted systems increases, the installed base can become an important source of recurring commercial activity.
The segment will remain strategically relevant through 2031 because it combines an established clinical market with ongoing technology-development opportunities. Future competition is likely to focus on reducing treatment burden rather than simply increasing pump capacity.
Regional Analysis
North America
North America represents the most mature commercial environment for ventricular assist devices. The United States has a large network of advanced heart-failure and transplant centers, established medical-device regulation, and reimbursement mechanisms supporting highly specialized cardiovascular care.
Demand is concentrated in hospitals with dedicated cardiac surgery and mechanical circulatory support programs. Procurement decisions are heavily evidence-based and influenced by clinical outcomes, reimbursement, existing physician experience, and total treatment costs.
The U.S. regulatory framework remains particularly important because FDA approval can influence global commercialization strategies. The FDA classifies ventricular assist devices within a high-risk regulatory category and recognizes technical standards covering a wide range of mechanical circulatory support systems.
Canada offers demand through advanced academic and tertiary care institutions, although population size and procurement structures limit overall volume relative to the United States. Mexico represents a longer-term opportunity, but access depends on specialized treatment infrastructure, healthcare funding, and the availability of advanced cardiac programs.
North American competition will continue to favor suppliers with strong clinical evidence, reliable service capabilities, and established relationships with implanting centers.
Europe
Europe combines established cardiac-care infrastructure with diverse national reimbursement systems. Germany, France, and the United Kingdom are important markets because of their specialist hospitals, advanced cardiovascular care, and established medical-device procurement systems.
The transition toward the European Union's Medical Device Regulation has increased the importance of regulatory planning, clinical evidence, quality documentation, and post-market surveillance. For manufacturers, compliance costs can be substantial, particularly for smaller companies without extensive regulatory resources.
Buyer behavior varies by country. Public healthcare systems may emphasize cost-effectiveness and national procurement structures, while leading university hospitals place strong weight on clinical performance and specialist familiarity.
Europe is also important as a base for several companies involved in mechanical circulatory support development. Berlin Heart has an established position in pediatric mechanical circulatory support, while CorWave represents continuing European investment in alternative circulatory support technology.
The principal growth constraint is not the absence of clinical need but the complexity of reimbursement, regulatory compliance, and uneven access across healthcare systems.
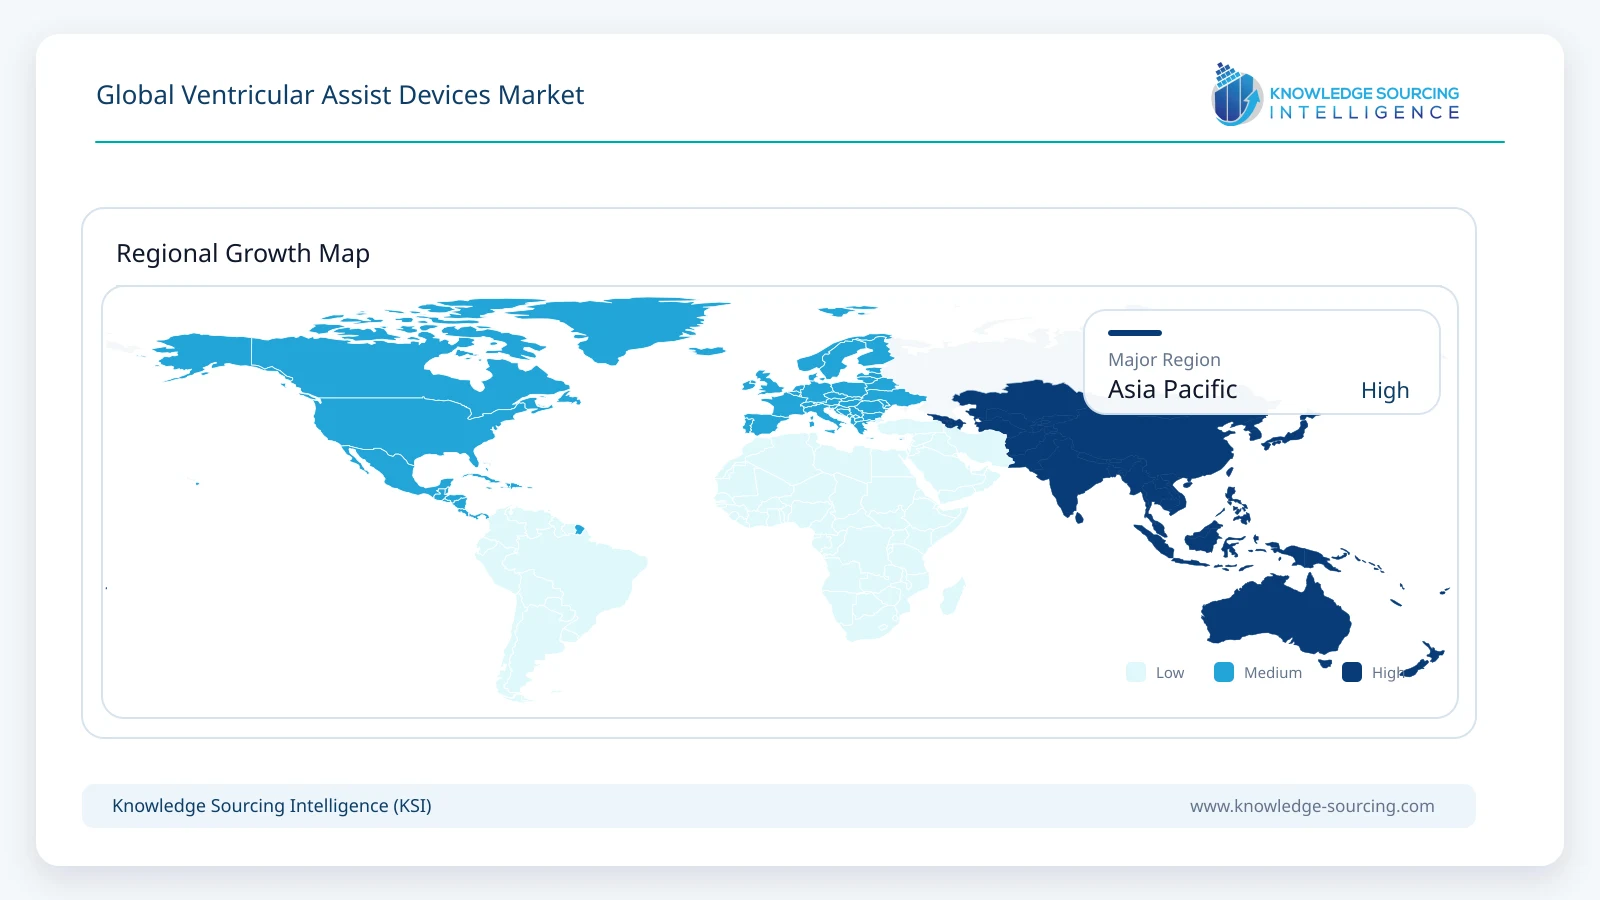
Asia Pacific
Asia Pacific offers a large long-term patient base but remains heterogeneous in its capacity to adopt ventricular assist devices. Japan, China, South Korea, Taiwan, India, Thailand, and Indonesia differ substantially in healthcare expenditure, cardiac-surgery capacity, reimbursement, and availability of transplant programs.
Japan has a highly developed medical infrastructure and a regulated market for advanced cardiovascular technologies. China is expanding its domestic medical-device capabilities and specialist cardiac infrastructure, creating potential for both imported and locally developed circulatory support technologies.
India presents substantial clinical need because of its large cardiovascular disease burden, but high device costs, uneven reimbursement, and limited availability of specialized implant centers restrict broad adoption. Demand is therefore likely to remain concentrated in major metropolitan and tertiary-care institutions during the forecast period.
South Korea and Taiwan offer stronger infrastructure for advanced medical technology adoption, while Thailand and Indonesia represent emerging opportunities dependent on healthcare investment and specialist capacity.
The region's strategic importance lies in the gap between potential clinical demand and current treatment penetration. Companies entering Asia Pacific must adapt commercial strategies to local reimbursement conditions, physician training requirements, regulatory processes, and hospital purchasing structures.
Middle East and Africa
The Middle East and Africa market is characterized by concentration rather than broad-based demand. Saudi Arabia and Israel are the most relevant markets within the provided geographic scope because of comparatively advanced medical infrastructure and investment in specialist healthcare services.
Saudi Arabia's healthcare investment can support the development of advanced cardiac treatment capacity, although adoption of ventricular assist devices depends on specialist training, transplant and heart-failure programs, and reimbursement arrangements.
Israel has a sophisticated medical technology ecosystem and advanced clinical capabilities, supporting demand for highly specialized cardiovascular treatments and creating opportunities for technology development and clinical collaboration.
Across much of Africa, adoption remains limited by infrastructure constraints, procedure costs, specialist shortages, and restricted access to long-term device management. Suppliers will generally prioritize major referral centers rather than broad geographic distribution.
South America
Brazil represents the largest commercial opportunity in South America because of its population, established tertiary hospitals, and relatively developed medical-device market. Demand remains concentrated in specialist institutions capable of providing cardiac surgery and long-term follow-up.
Argentina also has relevant cardiac-care capabilities but faces economic and procurement volatility that can affect capital-intensive medical technologies. Currency pressures, reimbursement uncertainty, and import dependence can influence device purchasing decisions.
For suppliers, South American expansion requires close attention to pricing, distributor capability, regulatory approvals, and hospital funding. Clinical demand alone will not determine adoption where the economic burden of advanced mechanical circulatory support remains high.
Competitive Landscape
The competitive landscape includes established medical-device companies, specialized mechanical circulatory support manufacturers, and development-stage technology companies. The market structure is differentiated by clinical maturity, regulatory status, target patient population, and technology approach.
Abbott Laboratories holds a strong position in durable LVADs through the HeartMate franchise. Its competitive advantage is supported by an established clinical footprint, broad treatment indications, regulatory experience, and a large installed base. FDA records continue to show post-approval product and manufacturing updates associated with HeartMate systems, reflecting the ongoing lifecycle management required for a mature Class III device platform.
Medtronic plc remains relevant through its mechanical circulatory support portfolio and legacy HeartWare system activities. FDA records show continued regulatory management involving design, component, and power-system changes associated with the HeartWare Ventricular Assist System.
Berlin Heart GmbH occupies a differentiated position through its focus on mechanical circulatory support for pediatric and small-patient populations. This specialization addresses a market where patient size and physiology limit the direct applicability of adult-oriented devices.
Jarvik Heart, Inc. also competes through specialized circulatory support technologies, including systems relevant to pediatric applications. Pediatric mechanical support represents a technically demanding niche with high clinical barriers and relatively limited patient volumes.
Abiomed, now part of Johnson & Johnson's broader corporate structure but included in this market's competitive universe as provided, is associated with temporary mechanical circulatory support. Its market relevance differs from that of durable LVAD suppliers because temporary support follows distinct clinical pathways and purchasing patterns.
Magenta Medical is pursuing miniaturized circulatory support technology, while Calon Cardio and CorWave are developing differentiated approaches to long-term mechanical support. Their competitive challenge is to demonstrate advantages sufficient to overcome the clinical familiarity and installed infrastructure of established systems.
BiVACOR Inc. is pursuing an alternative model of complete circulatory support, creating strategic differentiation from conventional single-ventricle assist systems. SynCardia Systems, LLC operates in the total artificial heart field, while the broader competitive environment also includes companies addressing acute, durable, pediatric, and biventricular support needs.
Competition is therefore not based solely on device price. Clinical evidence, reliability, regulatory status, surgical workflow, patient management, service infrastructure, and the ability to reduce complications are more important determinants of supplier positioning. Partnerships with transplant centers, cardiac hospitals, universities, and clinical investigators are also critical because they support evidence generation and physician adoption.
Recent Developments
July 2026: The U.S. FDA approved an Abbott HeartMate 3 supplement allowing an alternate supplier for components used in the outflow graft assembly. Commercial relevance: the approval highlights the industry's focus on qualified supply redundancy and manufacturing continuity for life-sustaining devices.
April 2026: The U.S. FDA approved a Medtronic HeartWare Ventricular Assist System supplement covering a new battery charger, revised power-cord packaging, and labeling updates. Commercial relevance: the decision demonstrates continued regulatory and service obligations for existing mechanical circulatory support populations.
November 2025: The U.S. FDA approved a HeartMate 3 Left Ventricular Assist System manufacturing material change involving the modular and percutaneous cable resin. Commercial relevance: the approval supported continued lifecycle and supply-chain management for an established durable LVAD platform.
Regulatory and Policy Environment
The ventricular assist devices market operates under stringent regulatory oversight because device malfunction or inadequate clinical performance can create immediate life-threatening risks. Regulatory compliance therefore influences product design, clinical development, manufacturing, supplier qualification, and post-market surveillance.
In the United States, ventricular bypass assist devices fall within the FDA's Class III medical-device framework. The agency's recognized consensus standards include coverage for LVADs, RVADs, BiVADs, total artificial hearts, percutaneous assist devices, and pediatric assist devices.
For manufacturers, this means regulatory strategy must be incorporated early in product development. Engineering decisions relating to blood-contacting materials, electromagnetic compatibility, reliability, software, battery systems, and manufacturing processes can affect premarket and post-approval requirements.
Post-market obligations are particularly important because ventricular assist devices may remain implanted for extended periods. Manufacturers must monitor adverse events, investigate device failures, manage product changes, and maintain quality systems.
Recent FDA PMA records involving both Abbott and Medtronic demonstrate the breadth of lifecycle modifications that can require regulatory review, including changes to manufacturing materials, component suppliers, battery-related elements, cables, and power systems.
In Europe, manufacturers must comply with the Medical Device Regulation framework, including clinical evaluation, technical documentation, quality-system requirements, post-market surveillance, and ongoing safety reporting. The regulatory burden may be especially challenging for smaller companies developing novel mechanical circulatory support technologies.
Reimbursement policy is equally important. Regulatory approval creates market access but does not guarantee adoption. Hospitals require sustainable payment mechanisms for implantation, inpatient care, and long-term follow-up. National healthcare authorities and payers therefore influence the pace at which new systems enter routine clinical practice.
Outlook and Strategic Implications
The ventricular assist devices market through 2031 will be shaped by the interaction of advanced heart-failure demand, transplant limitations, clinical infrastructure, and technology development. Durable LVADs are expected to remain the commercial center of the market, but competitive pressure will increase from companies seeking to reduce the complications and operational burdens associated with current systems.
Investment priorities will favor technologies that improve hemocompatibility, reduce infection risk, simplify power management, and support longer-term outpatient use. Fully implantable concepts, wireless energy transfer, alternative pumping mechanisms, and improved physiologic flow characteristics could influence the next generation of mechanical circulatory support.
Procurement behavior is likely to remain conservative. Hospitals will require clinical evidence before replacing established treatment systems. Suppliers introducing new devices will need to demonstrate not only safety and efficacy but also a credible advantage in adverse-event reduction, patient management, surgical workflow, or healthcare economics.
Manufacturing resilience will become more important. The regulatory history of established systems shows that even relatively focused changes to components or suppliers can require formal review. Companies should therefore invest in qualified secondary sourcing, lifecycle planning, component traceability, and regulatory change-control capabilities.
Competitive evolution will depend on whether emerging companies can convert engineering differentiation into clinical and commercial evidence. Established suppliers benefit from physician familiarity and installed infrastructure, while smaller companies may create opportunities by addressing unresolved limitations rather than directly competing on conventional product specifications.
Geographic expansion will also require differentiated strategies. North America and selected European markets offer the strongest near-term infrastructure for advanced mechanical circulatory support. Asia Pacific provides a substantial longer-term opportunity, particularly as specialist cardiac programs expand, but affordability and reimbursement will remain decisive constraints. The Middle East offers concentrated opportunities in advanced healthcare hubs, while South American demand will depend heavily on economic conditions and institutional purchasing capacity.
The principal risks include long regulatory timelines, expensive clinical trials, device-related complications, reimbursement pressure, supply-chain dependence, and limited availability of specialized implanting centers. These risks favor companies with strong capital resources, experienced regulatory teams, and the ability to support customers beyond the initial procedure.
The strongest strategic opportunities will emerge where technology, clinical evidence, and healthcare economics align. Suppliers that can reduce the lifetime burden of mechanical circulatory support, improve patient management, and maintain dependable manufacturing and service capabilities will be better positioned to expand adoption. Over the next five years, the ventricular assist devices market will remain a highly specialized cardiovascular technology segment in which clinical credibility and execution capability carry greater commercial weight than broad product portfolios or price competition alone.
Ventricular Assist Devices Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.9 billion |
| Total Market Size in 2031 | USD 4.7 billion |
| Forecast Unit | Billion |
| Growth Rate | 10.3% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Application, Geography |
| Companies |
|
Market Segmentation
By Type
- Left Ventricular Assist Device (LVAD)
- Right Ventricular Assist Device (RVAD)
- Biventricular Assist Device (BiVAD)
By Application
- Bridge to Transplant
- Bridge to Myocardial Recovery
- Destination Therapy
By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Others
- Europe
- Germany
- France
- United Kingdom
- Others
- Middle East and Africa
- Saudi Arabia
- Israel
- Others
- Asia Pacific
- China
- India
- Japan
- South Korea
- Taiwan
- Thailand
- Indonesia
- Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base Year and Forecast Period
1.8. Key Benefits to Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Process
3. EXECUTIVE SUMMARY
3.1. Key Findings
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter's Five Forces Analysis
4.3.1. Bargaining Power of Suppliers
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry
4.4. Industry Value Chain Analysis
4.5. Analyst View
5. VENTRICULAR ASSIST DEVICE MARKET BY TYPE
5.1. Introduction
5.2. Left Ventricular Assist Device (LVAD)
5.2.1. Market Trends and Opportunities
5.2.2. Growth Prospects
5.2.3. Geographic Lucrativeness
5.3. Right Ventricular Assist Device (RVAD)
5.3.1. Market Trends and Opportunities
5.3.2. Growth Prospects
5.3.3. Geographic Lucrativeness
5.4. Biventricular Assist Device (BiVAD)
5.4.1. Market Trends and Opportunities
5.4.2. Growth Prospects
5.4.3. Geographic Lucrativeness
6. VENTRICULAR ASSIST DEVICE MARKET BY APPLICATION
6.1. Introduction
6.2. Bridge to Transplant
6.2.1. Market Trends and Opportunities
6.2.2. Growth Prospects
6.2.3. Geographic Lucrativeness
6.3. Bridge to Myocardial Recovery
6.3.1. Market Trends and Opportunities
6.3.2. Growth Prospects
6.3.3. Geographic Lucrativeness
6.4. Destination Therapy
6.4.1. Market Trends and Opportunities
6.4.2. Growth Prospects
6.4.3. Geographic Lucrativeness
7. VENTRICULAR ASSIST DEVICE MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. By Type
7.2.2. By Application
7.2.3. By Country
7.2.3.1. United States
7.2.3.1.1. Market Trends and Opportunities
7.2.3.1.2. Growth Prospects
7.2.3.2. Canada
7.2.3.2.1. Market Trends and Opportunities
7.2.3.2.2. Growth Prospects
7.2.3.3. Mexico
7.2.3.3.1. Market Trends and Opportunities
7.2.3.3.2. Growth Prospects
7.3. South America
7.3.1. By Type
7.3.2. By Application
7.3.3. By Country
7.3.3.1. Brazil
7.3.3.1.1. Market Trends and Opportunities
7.3.3.1.2. Growth Prospects
7.3.3.2. Argentina
7.3.3.2.1. Market Trends and Opportunities
7.3.3.2.2. Growth Prospects
7.3.3.3. Others
7.3.3.3.1. Market Trends and Opportunities
7.3.3.3.2. Growth Prospects
7.4. Europe
7.4.1. By Type
7.4.2. By Application
7.4.3. By Country
7.4.3.1. Germany
7.4.3.1.1. Market Trends and Opportunities
7.4.3.1.2. Growth Prospects
7.4.3.2. France
7.4.3.2.1. Market Trends and Opportunities
7.4.3.2.2. Growth Prospects
7.4.3.3. United Kingdom
7.4.3.3.1. Market Trends and Opportunities
7.4.3.3.2. Growth Prospects
7.4.3.4. Others
7.4.3.4.1. Market Trends and Opportunities
7.4.3.4.2. Growth Prospects
7.5. Middle East and Africa
7.5.1. By Type
7.5.2. By Application
7.5.3. By Country
7.5.3.1. Saudi Arabia
7.5.3.1.1. Market Trends and Opportunities
7.5.3.1.2. Growth Prospects
7.5.3.2. Israel
7.5.3.2.1. Market Trends and Opportunities
7.5.3.2.2. Growth Prospects
7.5.3.3. Others
7.5.3.3.1. Market Trends and Opportunities
7.5.3.3.2. Growth Prospects
7.6. Asia Pacific
7.6.1. By Type
7.6.2. By Application
7.6.3. By Country
7.6.3.1. China
7.6.3.1.1. Market Trends and Opportunities
7.6.3.1.2. Growth Prospects
7.6.3.2. India
7.6.3.2.1. Market Trends and Opportunities
7.6.3.2.2. Growth Prospects
7.6.3.3. Japan
7.6.3.3.1. Market Trends and Opportunities
7.6.3.3.2. Growth Prospects
7.6.3.4. South Korea
7.6.3.4.1. Market Trends and Opportunities
7.6.3.4.2. Growth Prospects
7.6.3.5. Taiwan
7.6.3.5.1. Market Trends and Opportunities
7.6.3.5.2. Growth Prospects
7.6.3.6. Thailand
7.6.3.6.1. Market Trends and Opportunities
7.6.3.6.2. Growth Prospects
7.6.3.7. Indonesia
7.6.3.7.1. Market Trends and Opportunities
7.6.3.7.2. Growth Prospects
7.6.3.8. Others
7.6.3.8.1. Market Trends and Opportunities
7.6.3.8.2. Growth Prospects
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Calon Cardio
9.2. Jarvik Heart, Inc.
9.3. Magenta Medical
9.4. Medtronic plc
9.5. SynCardia Systems, LLC
9.6. CorWave
9.7. Abiomed
9.8. BiVACOR Inc.
9.9. Abbott Laboratories
9.10. Berlin Heart GmbH
Navigate
Trusted by the world's leading organizations











