
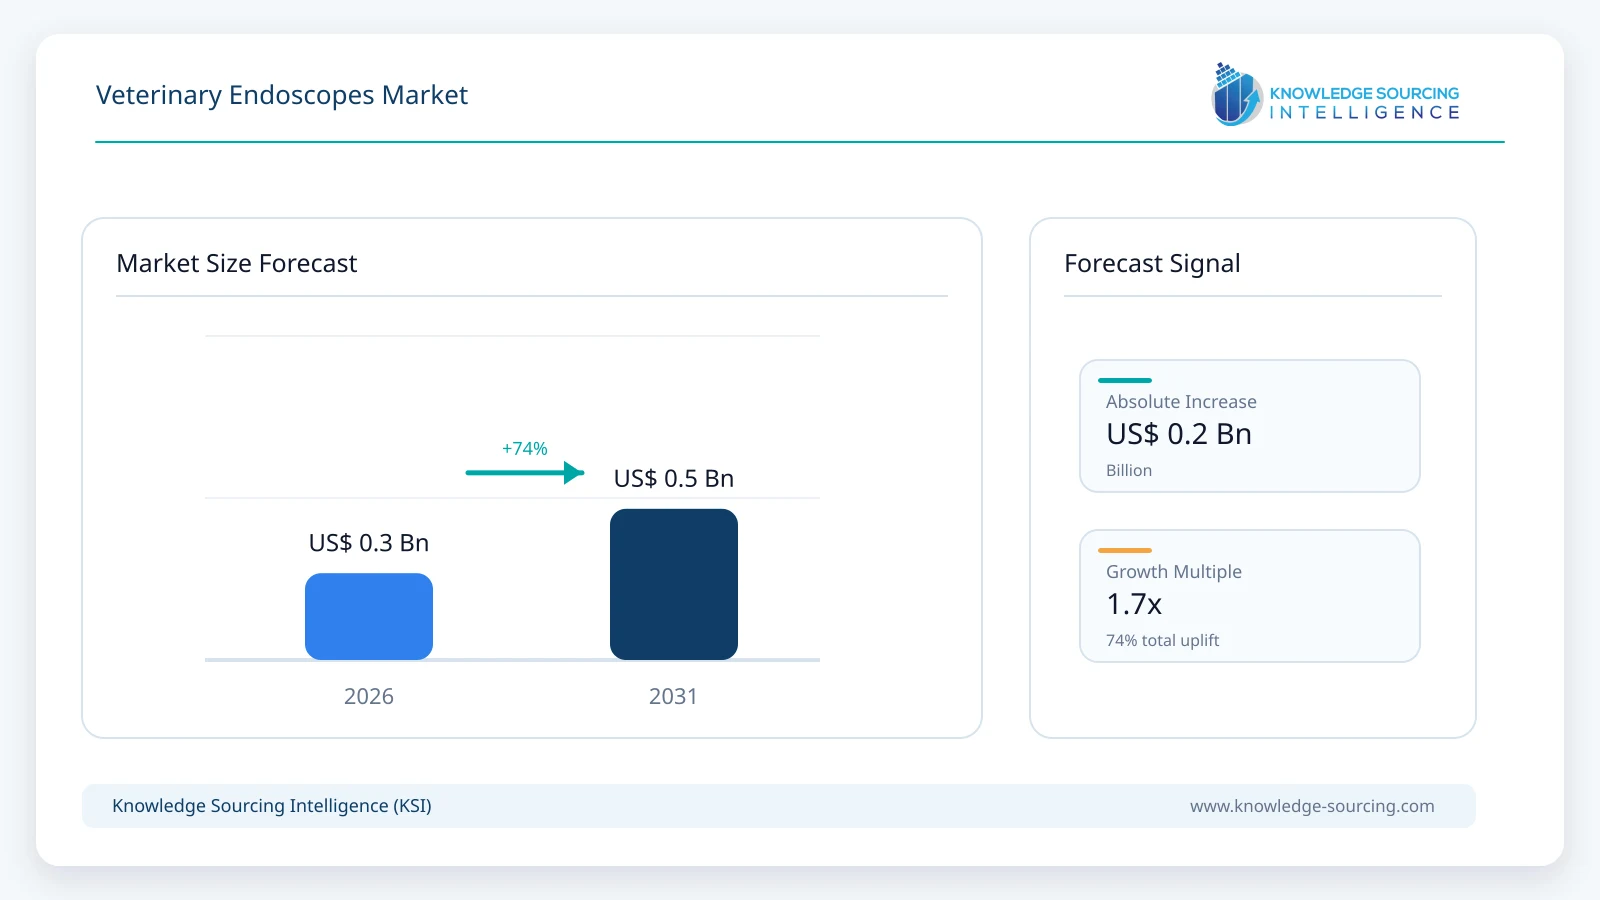
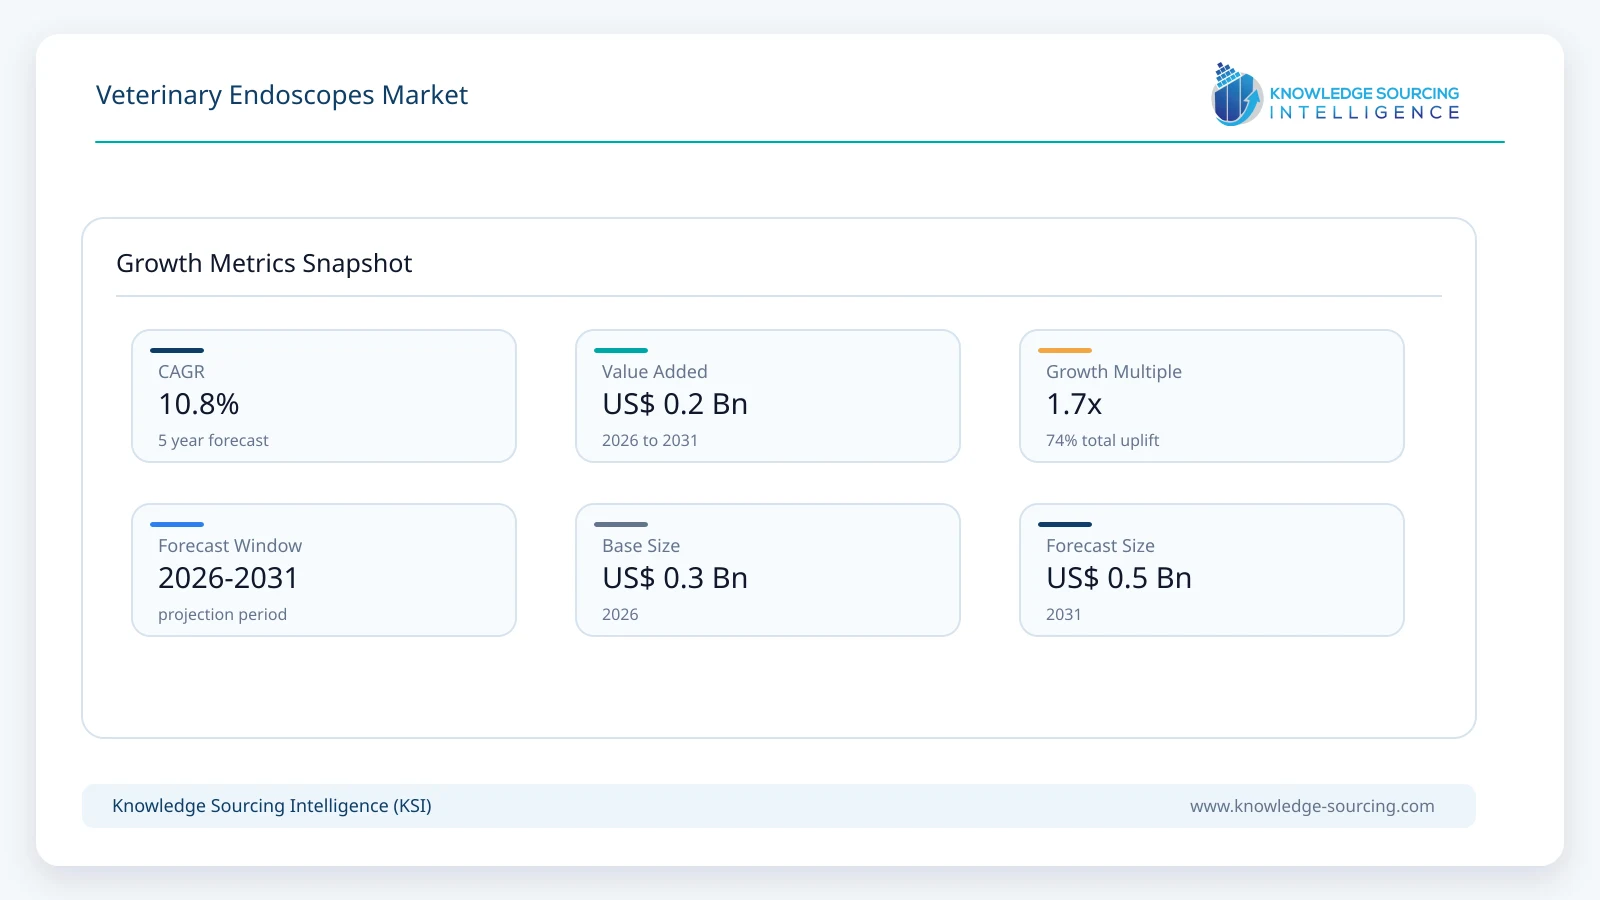
The Veterinary Endoscopes market is forecast to expand at a CAGR of 10.8%, reaching USD 0.54 billion in 2031 from USD 0.31 billion in 2026.
Highlights:
- 1Transition Toward Integrated Digital PlatformsVeterinary endoscope manufacturers are increasingly aligning hardware, imaging software, and workflow tools into unified digital ecosystems to support diagnostic efficiency and data management within veterinary practices.
- 2Rising Adoption of Minimally Invasive ProceduresDemand for flexible and rigid endoscopes is growing as minimally invasive diagnostic and surgical techniques become more common in companion animal care, particularly within referral hospitals and specialty clinics.
- 3Advances in Instrument MiniaturizationOngoing miniaturization of endoscopic instruments has expanded procedural access to smaller anatomical structures and a wider range of animal species, including small companion animals and exotics.
- 4Expansion of Veterinary-Specific Product PortfoliosGlobal medical device companies are increasingly developing veterinary-dedicated endoscopic systems rather than adapting human devices, reflecting the anatomical and procedural needs of animal healthcare.
The veterinary endoscopes market supports diagnostic and minimally invasive surgical procedures across companion animals, livestock, and equine medicine. Endoscopic systems enable visualization and intervention within internal anatomical structures while reducing surgical trauma, recovery time, and procedural risk. Historically, veterinary endoscopy relied on modified human medical devices; however, the market has evolved toward equipment designed specifically for veterinary anatomy and practice workflows.
Current market development is influenced by advances in digital imaging, fiber-optic technology, and procedural standardization within veterinary medicine. As veterinary practices increasingly emphasize advanced diagnostics, specialization, and continuing professional development, demand for endoscopic systems and supporting equipment continues to expand across developed and emerging markets.
Market Dynamics
Market Drivers
Escalating Demand for Minimally Invasive Surgery: The primary driver for market growth is the shift toward procedures that reduce surgical trauma and recovery time. Endoscopy allows for the immediate visualization of internal issues, enabling interventions that were previously reliant on invasive open surgeries.
Automated Clinical Workflows and Data Integration: Modern veterinary practices demand efficiency. Veterinary endoscopes now feature software that automates image capture and integrates with Practice Management Systems (PMS), making clinical documentation more efficient and defensible for insurance claims.
Rising Pet Ownership and Humanization: As pet owners increasingly view animals as family members, the willingness to invest in advanced diagnostics like bronchoscopy or cystoscopy has surged. This cultural shift acts as a bridge connecting basic care to advanced, technology-dependent medical services.
Expansion of Pet Insurance: The proliferation of comprehensive pet insurance plans has lowered the financial barrier for high-cost endoscopic procedures, encouraging practitioners to invest in premium equipment with the assurance of steady procedural volume.
Market Restraints & Opportunities
Veterinary Endoscope optimization faces challenges such as high upfront acquisition costs for imaging towers, integration hurdles with existing clinic infrastructure, and a shortage of specialized training for general practitioners. Smaller clinics often struggle with the operational burden of maintenance and sterilization protocols. However, significant opportunities exist as vendors transition to modular and portable "as-a-service" or flexible leasing models. Growing investments in specialized equine medicine and the expansion of exotic animal practices increase the need for versatile identity-management platforms for clinical data. As veterinary ecosystems become more decentralized, endoscopy can emerge as the core digital layer connecting diagnostic imaging with surgical outcomes.
Raw Material and Pricing Analysis
Veterinary endoscope manufacturing depends on high-grade materials including surgical stainless steel, optical fibers, CMOS imaging sensors, and biocompatible polymers. Pricing is influenced by fluctuations in electronic component supply, particularly semiconductors and high-intensity LED components used in modern imaging systems.
The transition from fiber-optic to digital video endoscopes has increased system complexity and average unit pricing. Integrated 4K imaging platforms require advanced processors and enhanced thermal management, contributing to higher costs. At the same time, manufacturers based in Asia have introduced competitively priced alternatives, increasing price segmentation within the market. Established suppliers justify premium pricing through durability, image quality, and extended product lifecycles.
Supply Chain Analysis
The veterinary endoscopes supply chain is characterized by specialized manufacturing and limited supplier redundancy. Core production hubs are located in Europe, Japan, and the United States, where expertise in precision optics and medical instrumentation is concentrated. Key components such as miniature cameras and flexible cabling often overlap with supply chains serving human healthcare and consumer electronics.
To reduce supply chain risk and improve service responsiveness, manufacturers are expanding regional assembly, distribution, and repair capabilities. Localized service centers are particularly important in veterinary medicine, where equipment downtime directly affects clinical operations. This regionalization strategy also supports faster adoption in emerging markets by improving post-sales support.
Government Regulations
Jurisdiction | Key Regulation / Agency | Market Impact Analysis |
United States | FDA Center for Veterinary Medicine (CVM) | Provides oversight related to manufacturing standards and labeling for veterinary medical devices, influencing compliance requirements. |
European Union | Veterinary regulatory framework and animal welfare directives | Indirectly influence equipment standards by emphasizing animal safety, hygiene, and procedural quality. |
China | National Medical Products Administration (NMPA) | Streamlined registration pathways for domestic manufacturers have increased local competition in veterinary endoscopy. |
United Kingdom | RCVS Practice Standards Scheme | Establishes voluntary benchmarks that encourage adoption of advanced diagnostic equipment in accredited practices. |
Market Segmentation
By Type: Flexible Endoscopes
Flexible endoscopes represent a key technology segment due to their essential role in gastrointestinal and respiratory diagnostics. Their maneuverability enables access to complex internal pathways, supporting procedures such as gastroscopy, bronchoscopy, and rhinoscopy. In companion animal practice, flexible endoscopy is commonly used for foreign body retrieval and biopsy, reducing the need for invasive surgery.
Technological advancements have shifted the segment from fiber-optic to fully digital video systems, improving image quality and diagnostic precision. Integration of enhanced imaging modalities is an emerging trend, particularly in referral settings. Replacement demand is driven by the need to upgrade aging equipment and improve workflow efficiency.
By End-User: Hospitals and Clinics
Veterinary hospitals and specialty clinics are the primary end-users of endoscopic systems. Their procurement decisions are influenced by case complexity, referral volume, and the range of services offered. Large referral centers typically maintain multiple endoscopes and integrated imaging towers to support different specialties.
General clinics increasingly seek compact and modular systems that can be used across multiple procedures. Connectivity and digital image management are becoming more important, enabling consultation, documentation, and client communication. Corporate ownership structures further support standardized purchasing and long-term service agreements.
Regional Analysis
North America Market Analysis
North America has become one of the most mature regions in the world for Veterinary Endoscopes due to high levels of pet insurance penetration and advanced clinical infrastructure. In the United States, the focus on specialized veterinary medicine and strict procedural standards is driving the adoption of high-definition digital systems. Organizations in the U.S. are prioritizing analytics-integrated endoscopy to manage complex caseloads and meet the expectations of a highly demanding pet-owner demographic. Canada shows similar trends in digital modernization and the adoption of portable endoscopic solutions for field-based equine medicine.
South America Market Analysis
The governments and enterprises of South America have begun to ramp up their focus on animal health standards and surgical modernization; as a result, they are beginning to implement Veterinary Endoscopy at a steady pace. Brazil, for example, is investing in veterinary infrastructure as part of its growing companion animal market. Large clinics are experimenting with digital endoscopy systems to manage increasing patient loads and improve surgical success rates. While infrastructure development is ongoing, a growing number of regional animal welfare policies will provide additional motivation for organizations to implement advanced diagnostic software.
Europe Market Analysis
The implementation of Veterinary Endoscopes has been largely accelerated in Europe primarily due to stringent animal welfare directives and a high concentration of market-leading manufacturers. The European strategy promotes the use of advanced diagnostics to ensure that invasive procedures are minimized. Countries like Germany and the United Kingdom have large-scale operations utilizing rigid and flexible endoscopy to stabilize their clinical systems and protect animal health assets. Furthermore, the emphasis on specialized equine medicine in Western Europe is creating vast opportunities for high-end arthroscopic and laparoscopic equipment.
Middle East and Africa Market Analysis
The Middle East and Africa region is in the early stage of adoption but shows significant growth potential, particularly in the UAE and Saudi Arabia. These nations are investing heavily in world-class veterinary facilities for falconry, equine sports, and high-end companion animal care. Large-scale digital transformation in the region is increasing the need for integrated diagnostic tools. In Saudi Arabia, government-led modernization programs are encouraging the adoption of advanced medical tools within the public and private veterinary sectors to support national biodiversity and animal health goals.
Asia Pacific Market Analysis
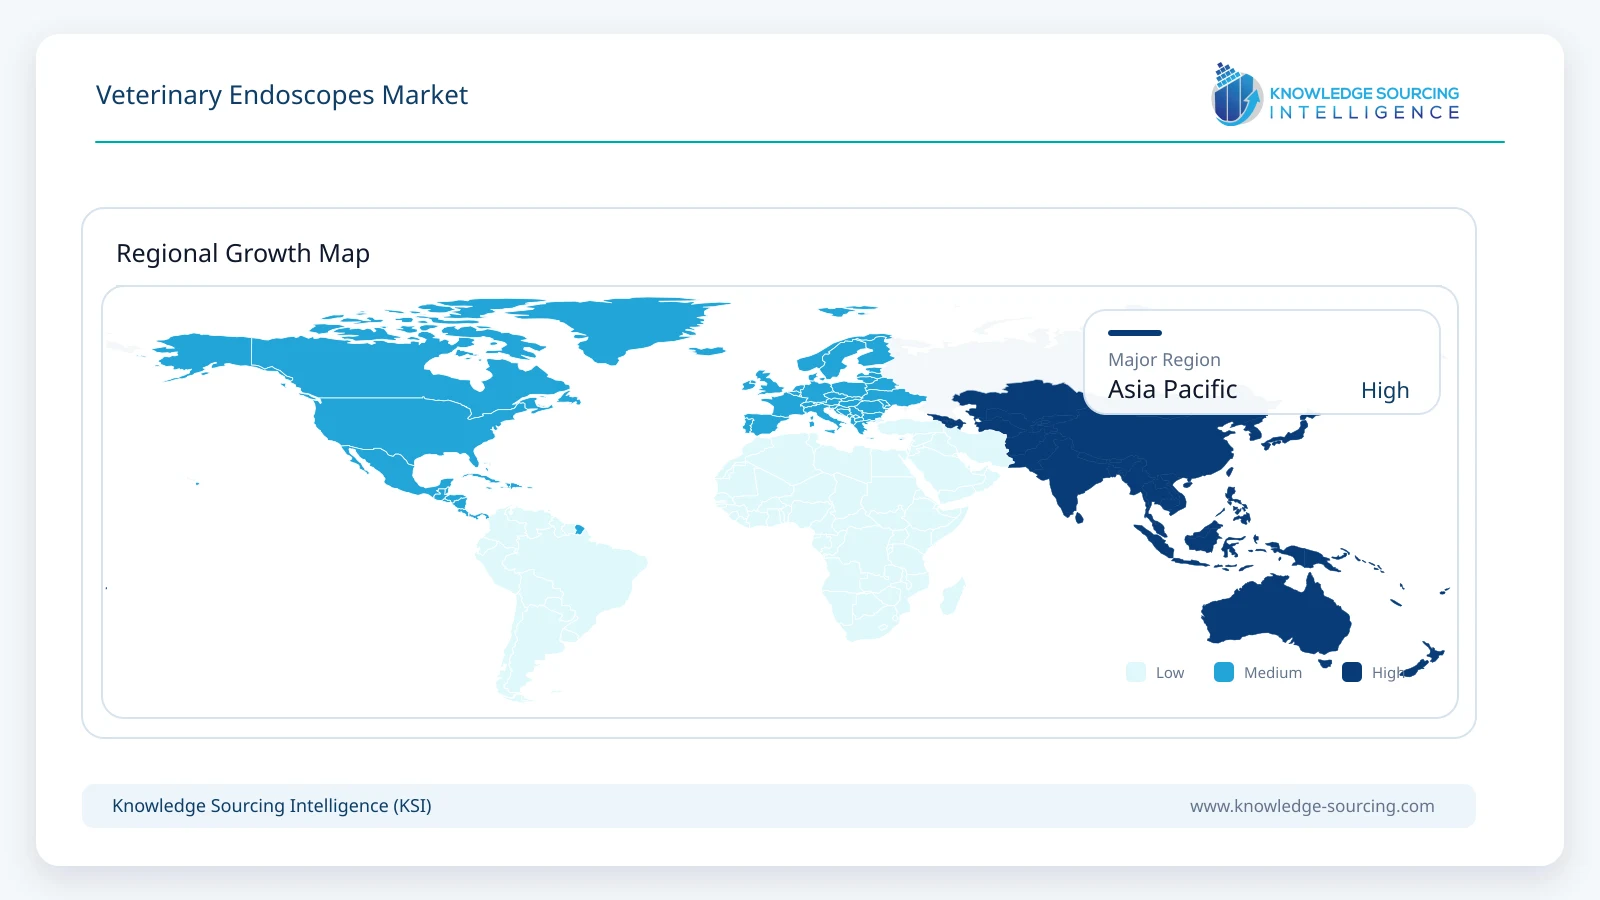
The rapidly evolving market in the Asia-Pacific region is attributed to strong digital adoption targets and the increasing deployment of veterinary clinics in urban centers. Japan has taken a lead in developing standards for high-precision veterinary optics. In China, the integration of domestic manufacturing with digital imaging is enabling the management of massive amounts of clinical data at competitive price points. India, Australia, and South Korea are also investing heavily in veterinary infrastructure. The rapid rise of the middle class in India has created high demand for modern clinics that can optimize surgical safety in real-time.
List of Companies
KARL STORZ
Biovision Veterinary Endoscopy, LLC
Advanced Monitors Corporation
MDS Incorporated
Aohua Endoscopy Co., Ltd
Dr. Fritz Endoscopes GmbH
Vetel Diagnostics
Eickemeyer Veterinary Equipment Limited
Steris Animal Health (Steris Corporation)
eKuore
KARL STORZ
KARL STORZ is recognized globally as an authority on veterinary endoscopy and integrated operating room technology. Their platforms enable the continuous movement of diagnostic data between the surgical suite and hospital management systems. The KARL STORZ system gathers capacity from various rigid and flexible scopes to create a single, unified view of the patient’s internal health. This allows veterinary surgeons to utilize high-definition video to balance surgical precision and reduce the risk of tissue trauma. The company has deployed its software across multiple countries within academic and corporate programs to support the modernization of veterinary digital grids.
Aohua Endoscopy
Aohua Endoscopy focuses on providing digital imaging and endoscopic services using AI-enhanced software technologies. Aohua specializes in providing flexibility to the veterinary market through its portable and integrated 4K towers. By using these tools, the company provides distributed diagnostic resources, including real-time image enhancement and automated workflow management, to improve the stability of clinical operations. Aohua has established a strong presence in the Asia-Pacific and European markets, developing pilot programs that help customers meet modern diagnostic goals and develop the infrastructure necessary for smart, secure veterinary ecosystems.
Biovision Veterinary Endoscopy
Biovision provides specialized, miniaturized endoscopy software and hardware that orchestrates diagnostics for even the smallest animal patients. Its software enables organizations to forecast procedural needs, optimize instrument usage, and dispatch clinical resources in real-time. In the context of Identity Analytics for clinical data, Biovision’s software can coordinate diagnostic flows for niche applications like needle arthroscopy. The company participates in global veterinary modernization initiatives where advanced miniaturization tools support the integration of office-based diagnostics and smarter, portable imaging systems.
Key Developments
August 2026: IMV Technologies launched Vet Solutions, uniting regional veterinary businesses under one global brand to strengthen its integrated veterinary equipment and service offering.
May 2026: Reescope showcased its latest small-animal flexible and rigid endoscopic systems at the 18th Eastern-Western Small Animal Veterinary Symposium (WESAVS) in Tianjin, highlighting advanced diagnostic visualization.
November 2025: Aohua Endoscopy featured its VET-OR1800 advanced tower system and the AQ-150 series integrated 4K ultra-high-definition endoscopy system at the London Vet Show, targeting the European demand for space-efficient, high-resolution diagnostic platforms.
July 2025: KARL STORZ announced the unification of its Canada, United States, and Veterinary organizations into a single North America region. This restructuring is designed to streamline the delivery of integrated endoscopic solutions to veterinary hospitals.
Veterinary Endoscopes Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | US$ 0.31 billion |
| Total Market Size in 2031 | US$ 0.54 billion |
| Forecast Unit | Billion |
| Growth Rate | 10.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Animal Type, End-User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Flexible Endoscope
Rigid Endoscope
Other Endoscopes
By Animal Type
Companion
Livestock
By End-User
Hospitals and Clinics
Academic and Research Institutes
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
UK
Others
Middle East and Africa
Saudi Arabia
UAE
Others
Asia Pacific
China
India
Japan
South Korea
Taiwan
Thailand
Indonesia
Others
Table of Contents
1. INTRODUCTION
1.1. Market Definition
1.2. Market Segmentation
2. RESEARCH METHODOLOGY
2.1. Research Data
2.2. Assumptions
3. EXECUTIVE SUMMARY
3.1. Research Highlights
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Porter's Five Forces Analysis
4.3.1. Bargaining Power of End-Users
4.3.2. Bargaining Power of Buyers
4.3.3. Threat of New Entrants
4.3.4. Threat of Substitutes
4.3.5. Competitive Rivalry in the Industry
4.4. Industry Value Chain Analysis
5. VETERINARY ENDOSCOPE MARKET ANALYSIS, BY TYPE
5.1. Introduction
5.2. Flexible Endoscope
5.3. Rigid Endoscope
5.4. Other Endoscopes
6. VETERINARY ENDOSCOPE MARKET ANALYSIS, BY ANIMAL TYPE
6.1. Introduction
6.2. Companion
6.3. Livestock
7. VETERINARY ENDOSCOPE MARKET ANALYSIS, BY END-USER
7.1. Introduction
7.2. Hospitals and Clinics
7.3. Academic and Research Institutes
8. VETERINARY ENDOSCOPE MARKET ANALYSIS, BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. Germany
8.4.2. France
8.4.3. UK
8.4.4. Others
8.5. Middle East and Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Japan
8.6.4. South Korea
8.6.5. Taiwan
8.6.6. Thailand
8.6.7. Indonesia
8.6.8. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Emerging Players and Market Lucrativeness
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Vendor Competitiveness Matrix
10. COMPANY PROFILES
10.1. KARL STORZ
10.2. Biovision Veterinary Endoscopy, LLC
10.3. Advanced Monitors Corporation
10.4. MDS Incorporated
10.5. Aohua Endoscopy Co., Ltd
10.6. Dr. Fritz Endoscopes GmbH
10.7. Vetel Diagnostics
10.8. Eickemeyer Veterinary Equipment Limited
10.9. Steris Animal Health (Steris Corporation)
10.10. eKuore
List of Figures
List of Tables





Frequently asked questions
What is the projected market size for veterinary endoscopes by 2031?
The Veterinary Endoscopes Market is forecast to reach USD 0.54 billion by 2031.
What is the Compound Annual Growth Rate (CAGR) for this market?
The Veterinary Endoscopes Market is forecast to expand at a 10.8% CAGR.
What are the primary growth drivers for veterinary endoscopes?
Minimally invasive surgery, workflow automation, and pet humanization are key drivers.
What key trends are shaping the Veterinary Endoscopes Market?
Digital platforms, miniaturization, and veterinary-specific products are key trends.
Which animal segments does the Veterinary Endoscopes Market serve?
The Veterinary Endoscopes Market serves companion animals, livestock, and equine medicine.
How has the Veterinary Endoscopes Market recently evolved?
The Veterinary Endoscopes Market evolved from human devices to veterinary-specific systems and digital integration.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Veterinary Endoscopes Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/veterinary-endoscopes-market