
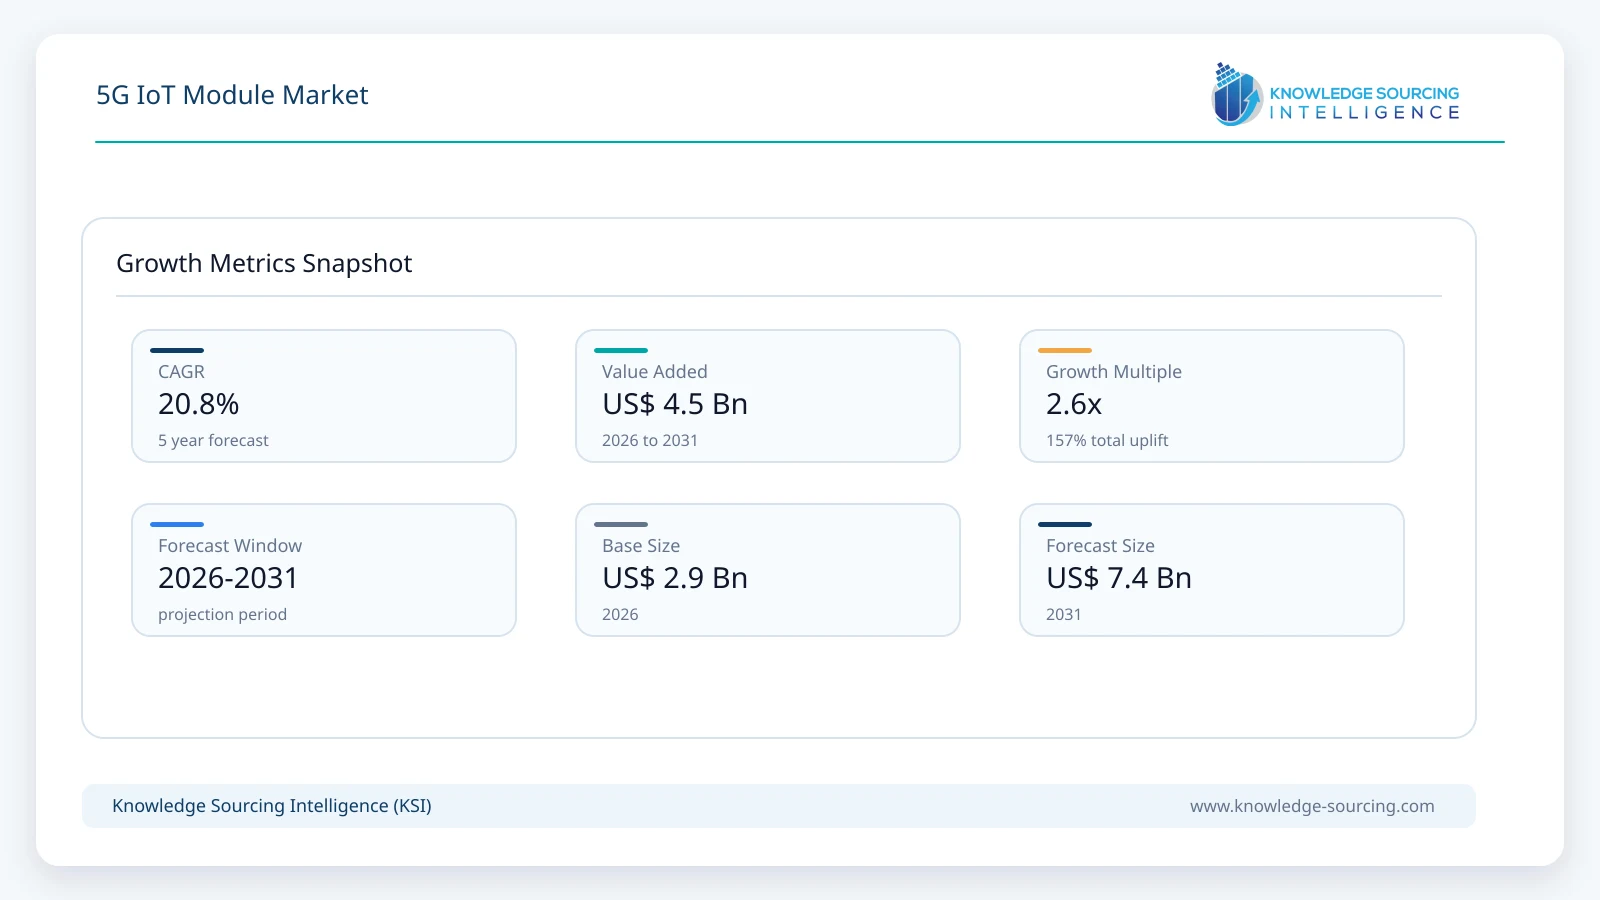
The Global 5G IoT Module market is forecast to grow at a CAGR of 20.8%, reaching USD 7.36 billion in 2031 from USD 2.86 billion in 2026.
Highlights:
- 1Full-capability 5G NR modules account for an estimated 66.0% of market revenue in 2026, reflecting their established position in gateways, CPE, routers and other high-bandwidth devices.
- 25G RedCap and eRedCap modules represent approximately 17.0% of revenue in 2026 but are projected to increase to 36.0% by 2031, making them the fastest-growing module category.
- 3LGA modules account for approximately 53.0% of market revenue in 2026, supported by embedded industrial, automotive and compact IoT designs.
- 4FWA, routers and gateways represent approximately 32.0% of module demand in 2026, but industrial, automotive and lower-power IoT applications gain a larger share through the forecast period.
- 5Asia Pacific accounts for an estimated 46.0% of global revenue in 2026, supported by China’s module manufacturing ecosystem and large electronics, automotive and industrial-device markets.
- 6RMB 24.33 billionQuectel reported 2025 company revenue of approximately , while Fibocom reported approximately USD 945 million, illustrating the scale of the broader cellular-module supplier ecosystem from which 5G products are expanding.
- 7RedCap becomes the most important structural growth driver because it allows products historically designed around LTE Cat 4 and similar technologies to migrate to 5G without adopting the cost and power profile of a full-capability 5G modem.
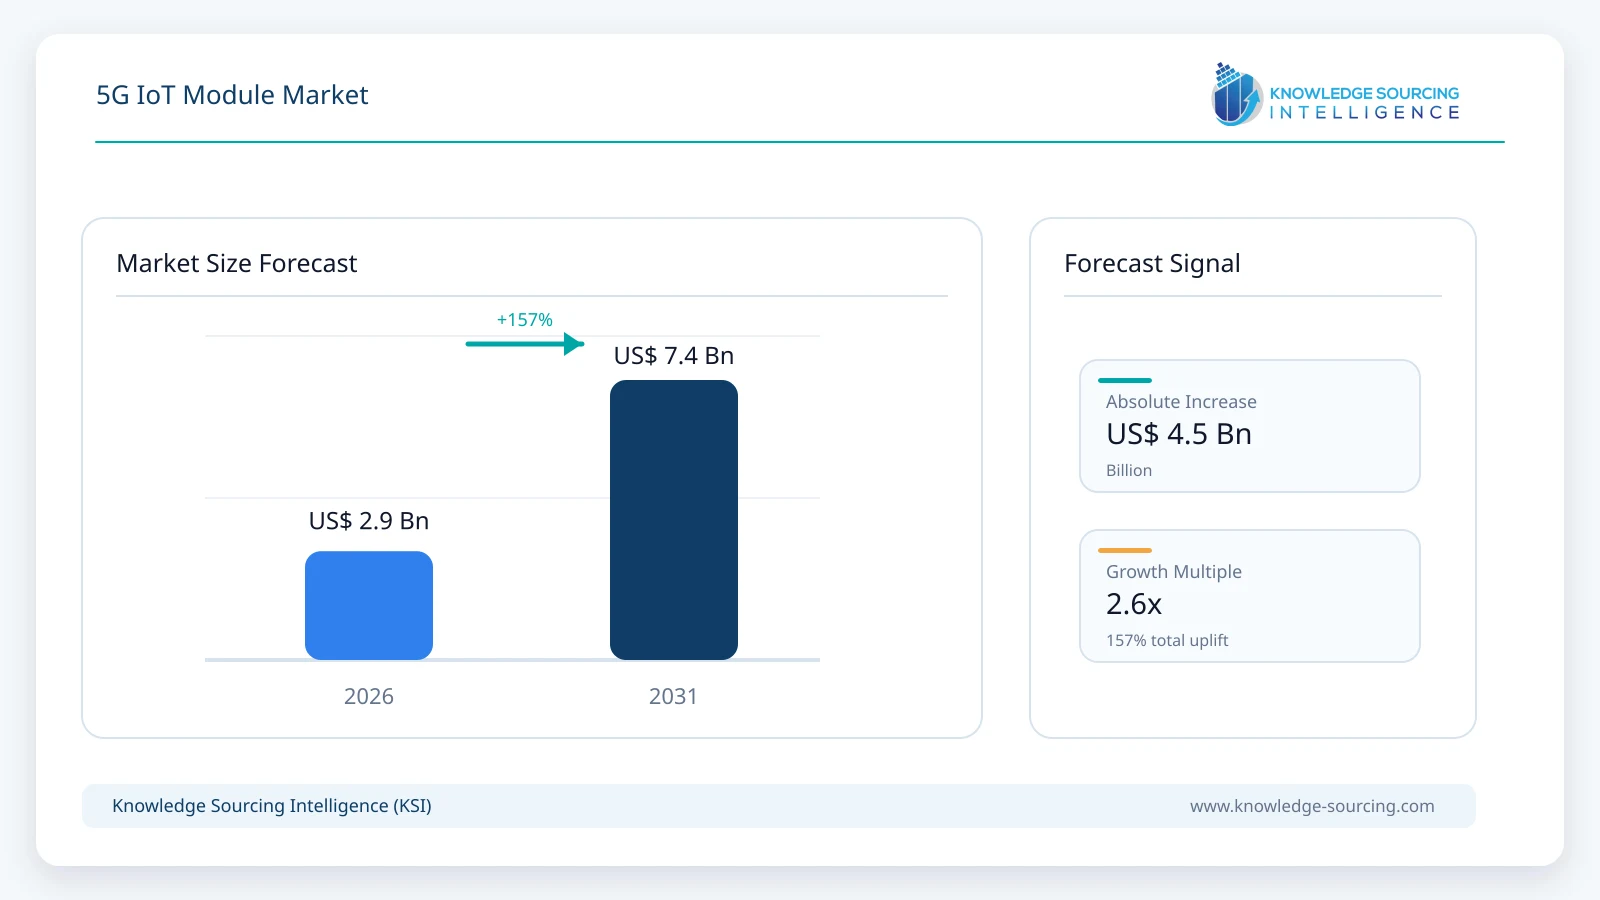
Growth is being supported by commercialization of 5G RedCap, migration of industrial equipment from LTE to 5G, expansion of private 5G networks, wider use of cellular connectivity in edge-computing devices, connected transportation and increasing integration of AI processing directly within communication modules.
5G IoT modules are embedded communication components that allow industrial equipment, routers, gateways, vehicles, cameras, terminals, medical devices and other connected products to access 5G networks. The market includes full-capability 5G NR data modules, Reduced Capability modules based on 3GPP RedCap/eRedCap specifications and smart modules that integrate cellular connectivity with application processors and operating systems.
The scope covers modules sold for incorporation into third-party devices and systems. Complete routers, CPEs, smartphones, standalone modem chipsets and connectivity-service revenue are excluded. Automotive-grade modules are included where the communication module is sold as a distinct embedded component, while complete telematics control units are excluded.
The commercial structure is changing rapidly. Full-capability 5G modules were initially designed primarily for applications requiring multi-gigabit connectivity, including enterprise routers, CPE and high-performance industrial systems. RedCap creates a lower-cost and lower-power 5G tier for devices that do not require full eMBB performance. Fibocom’s RU311, Quectel’s RG255 series and Semtech’s EM8695 illustrate the increasingly broad commercial ecosystem around this intermediate device class.
Market Overview
Cellular IoT module demand has historically been divided between very low-bandwidth technologies such as NB-IoT and LTE-M, mid-range LTE technologies such as Cat 1 and Cat 4, and high-performance LTE Advanced modules. Early 5G modules entered primarily at the highest end of this spectrum because first-generation 5G modem platforms were optimized for multi-gigabit broadband performance.
That structure limited early adoption outside CPE, industrial routers, and data-intensive edge equipment. Many IoT devices do not require gigabit throughput, four receive antennas, or the processing capability of a flagship 5G platform. Cost, power consumption, physical size, and product lifetime can be more important than peak speed.
RedCap directly addresses this gap. Quectel’s RG255C supports 3GPP Release 17 RedCap with theoretical speeds of approximately 223 Mbps downlink and 123 Mbps uplink, while Fibocom’s RU311 provides approximately 226 Mbps downlink and 120 Mbps uplink with LTE Cat 4 fallback. Both are positioned for applications such as industrial gateways, surveillance, energy equipment, and mid-speed broadband devices.
This makes RedCap commercially important not because it increases maximum speed, but because it lowers the minimum economic threshold for adopting 5G. A device OEM can move from LTE toward a long-lived 5G SA architecture without paying for capabilities that the application will never use.
The high-performance segment is evolving simultaneously. Telit Cinterion introduced Release 18 FE990D50 and FE990D60 modules in March 2026 with enhanced carrier aggregation and up to 8RX MIMO for industrial, enterprise and networking equipment. Fibocom continues optimizing conventional 5G modules for cost and power as the technology enters larger-volume applications.
The result is a market developing in three directions: lower-cost RedCap for mainstream IoT, increasingly powerful full-capability modules for broadband devices, and smart modules that combine cellular connectivity with local computing and AI functionality.
Market Drivers
RedCap creates a realistic migration path from LTE to 5G for mid-tier IoT
The strongest market driver is not simply increasing 5G coverage. It is the availability of a 5G device class whose economics are appropriate for applications previously served by LTE Cat 4 and similar technologies.
Full-capability 5G NR modules can provide several gigabits per second of throughput but require more complex RF designs, memory, antennas, and power management. This is unnecessary for applications such as surveillance terminals, industrial gateways, telemetry equipment, and many transportation systems.
Fibocom formally expanded this category with the RU311 series in August 2026. The product supports RedCap and LTE Cat 4 and is offered in LGA, M.2, and Mini PCIe configurations. Its pin-layout strategy is designed to reduce redesign requirements for customers migrating existing 4G products.
Quectel follows a similar strategy with RG255C products offered in LGA, M.2 and Mini PCIe formats. Semtech’s module portfolio now includes the EM8695 RedCap module alongside full-bandwidth 5G devices.
The RedCap/eRedCap category is projected to increase from approximately USD 486 million in 2026 to USD 2.65 billion in 2031, representing growth of about 40.4% annually.
Migration from 4G devices supports replacement demand beyond greenfield IoT
A substantial proportion of the future 5G module opportunity comes from replacing existing LTE designs rather than creating entirely new connected-device categories.
Industrial routers, surveillance systems, mobile broadband equipment and gateways frequently remain in service for many years. OEMs therefore need communication platforms that can continue operating as spectrum and operator investment increasingly shift toward 5G SA.
Backward compatibility is consequently central to current module design. Fibocom’s RU311 supports both RedCap and LTE Cat 4, while Quectel’s RG255C is designed to operate with LTE fallback and shares compatibility characteristics with earlier module families. Telit Cinterion similarly positions its RedCap modules as migration platforms from LTE.
This reduces redesign cost and allows manufacturers to maintain common device platforms across regions where the pace of 5G SA deployment differs.
Industrial edge computing is increasing the value of integrated connectivity and processing
Industrial IoT increasingly requires local processing alongside connectivity. Video analytics, machine vision, robotics and predictive-maintenance applications can generate more data than should economically be transported continuously to a remote cloud.
Module suppliers are therefore integrating greater processing capability and AI functionality directly into connected-device platforms. Telit Cinterion announced an Edge AI SDK on September 8, 2026 that enables machine-learning models to run within selected 4G, RedCap and full 5G cellular modules using LiteRT. The architecture allows inference to occur on the module’s application processor without requiring a separate accelerator.
Quectel’s SG520B provides another example of this convergence. The module combines 5G, Wi-Fi 6E, Bluetooth, GNSS and an Android-capable octa-core processor within one embedded platform.
This shift supports above-market growth for smart modules because OEMs can reduce component count and integrate cellular connectivity, application processing, positioning, and multimedia capability within a common package.
Private 5G expands the industrial addressable market
Private 5G changes cellular connectivity from a service consumed primarily through a national public operator into infrastructure that can be deployed within a factory, mine, port or logistics facility.
Industrial gateways, cameras, robots, rugged terminals and computing systems need compatible modules to connect directly to these networks. RedCap is particularly relevant because many industrial endpoints require deterministic connectivity and long product lifetimes but not multi-gigabit throughput.
Telit Cinterion’s collaboration with Nokia, announced on January 7, 2026, provides a current example. Nokia’s Cognitive Digital Mine platform incorporates Telit Cinterion cellular, satellite, and Wi-Fi communication modules within equipment designed for mining and other heavy industrial operations.
Private 5G therefore supports demand across both full-capability and RedCap modules, with the appropriate technology determined by individual device bandwidth and latency requirements.
Automotive connectivity is increasing module value per vehicle
Vehicles are becoming another important embedded 5G platform. Automotive modules require extended temperature ranges, long product support cycles, carrier aggregation, precise positioning and, in some configurations, C-V2X support.
Quectel’s current automotive portfolio includes AG55xQ and AG57xQ modules supporting 5G NR, LTE fallback, automotive-qualified chipsets and optional C-V2X.
The automotive and transportation application segment is projected to expand from approximately USD 515 million in 2026 to USD 1.62 billion in 2031, representing a CAGR of about 25.8%.
Growth is supported not only by passenger vehicles but also by fleet systems, commercial vehicles, rail, public safety and connected mobility equipment.
Falling module cost expands the range of commercially viable devices
Cost remains one of the most important differences between LTE and full-capability 5G. Module suppliers are increasingly reducing bill-of-material requirements as volumes increase.
Fibocom announced on June 29, 2026 a memory-optimized FG550-EAU configuration that reduces LPDDR4x RAM from 8 Gb to 4 Gb while retaining key 5G capabilities. The company explicitly linked the redesign to lower terminal BOM cost and improved supply resilience.
RedCap amplifies this trend by reducing modem complexity itself. Falling module cost therefore expands adoption into applications that previously could not justify 5G.
Market Restraints and Challenges
LTE remains economically sufficient for many IoT applications
5G does not automatically create value for every connected device. Smart meters, simple asset trackers and low-frequency sensors often require very little bandwidth and can remain economically better suited to NB-IoT, LTE-M or LTE Cat 1bis.
This places a natural limit on the addressable market. The strongest migration opportunity lies in applications requiring more performance than LPWA but less than conventional high-end 5G.
RedCap improves this position substantially, but LTE will continue operating throughout much of the forecast period. Device OEMs therefore need to justify migration through network longevity, private 5G capability, power performance or product consolidation rather than technology branding alone.
Certification requirements increase development cost
A cellular module needs regulatory and often operator certification across the markets where it will be deployed. The challenge increases when manufacturers support many 5G bands, carrier combinations, SA/NSA architectures and regional variations.
Module vendors can absorb much of this burden through pre-certified products, but end-device OEMs still need integration and final product testing.
This particularly affects smaller IoT manufacturers, for which the engineering expense of moving from an established LTE platform can exceed the near-term connectivity benefit.
Full-capability 5G remains power intensive
High-performance 5G modules use additional receive chains, broader carrier aggregation and more sophisticated processing than simpler LTE or RedCap devices.
This limits their suitability for battery-operated equipment. Even when a full-capability module technically supports the application, RedCap or LTE can provide a better system-level design.
The increasing divergence between high-performance and reduced-capability modules therefore becomes structural rather than temporary.
Module price compression can restrain revenue growth
Unit shipments can increase substantially while average selling prices decline as platforms mature and competition intensifies. Quectel, Fibocom, SIMCom, MeiG and other suppliers compete aggressively in high-volume markets, particularly in Asia.
RedCap modules are also specifically designed to reduce hardware cost relative to conventional 5G.
Market revenue consequently grows more slowly than 5G module unit shipments, which is why shipment-growth assumptions should not be applied mechanically to market-value forecasts.
Geopolitical and supply-chain requirements are influencing vendor selection
Cellular modules contain modem chipsets, memory, secure elements and RF components sourced through global supply chains. Government and enterprise customers increasingly scrutinize product origin, cybersecurity and manufacturing location.
Telit Cinterion announced in September 2026 that it would expand trusted manufacturing in the United States, reflecting the growing commercial importance of regional production and supply-chain transparency.
These requirements can fragment product portfolios and increase certification and manufacturing costs for suppliers serving multiple geopolitical markets.
Major Segment Analysis
By Module Class
Full-capability 5G NR modules remain the largest category in 2026 at approximately 66.0% of market revenue. These products serve CPE, gateways, routers, industrial PCs, video systems and other applications requiring high throughput.
The category is projected to reach approximately USD 3.24 billion by 2031, but its share falls to around 44% because RedCap opens 5G to a much broader device base. Full-capability module revenue grows at approximately 11.4% annually, substantially below overall market growth.
RedCap and eRedCap represent the strongest expansion opportunity. Revenue increases from approximately USD 486 million to USD 2.65 billion, with adoption moving from early industrial devices into surveillance, wearables, energy equipment, routers, telematics and enterprise endpoints.
5G smart modules account for approximately 17% of 2026 revenue and are projected to reach USD 1.47 billion by 2031. Integration of Android or Linux processing, graphics, camera interfaces and AI functionality increases their use in smart retail, robotics, terminals and visual edge applications.
By Form Factor
LGA is the largest form factor, representing approximately 53.0% of 2026 revenue and increasing to approximately 58% by 2031. Its compact physical design and direct board integration make it particularly suitable for embedded industrial, automotive and RedCap applications.
LGA module revenue is projected to reach approximately USD 4.27 billion in 2031, representing annual growth of about 23.0%.
M.2 modules remain important in routers, CPE, industrial computers and upgradeable equipment. They account for approximately 29% of the market in 2026 but lose share as integrated embedded designs grow.
Mini PCIe and other form factors remain relevant where OEMs prioritize replaceability and compatibility with existing industrial hardware.
By Application
FWA, routers and gateways account for approximately 32.0% of market revenue in 2026, making them the largest initial application. Full-capability modules are well suited to these products because they need high throughput and can generally tolerate higher power consumption.
The segment reaches approximately USD 1.77 billion by 2031, but its share declines as 5G spreads into other IoT applications.
Industrial and enterprise equipment increases from approximately USD 715 million in 2026 to USD 2.06 billion in 2031, representing approximately 23.6% annual growth. Private 5G, edge computing, industrial gateways and machine connectivity support the expansion.
Automotive and transportation grows faster at approximately 25.8% annually, reaching around USD 1.62 billion.
Energy, utilities and smart-city applications expand through connected infrastructure and RedCap migration, while healthcare and wearable devices represent the fastest-growing smaller application category as lower-power 5G architectures become commercially practical.
Regional Analysis
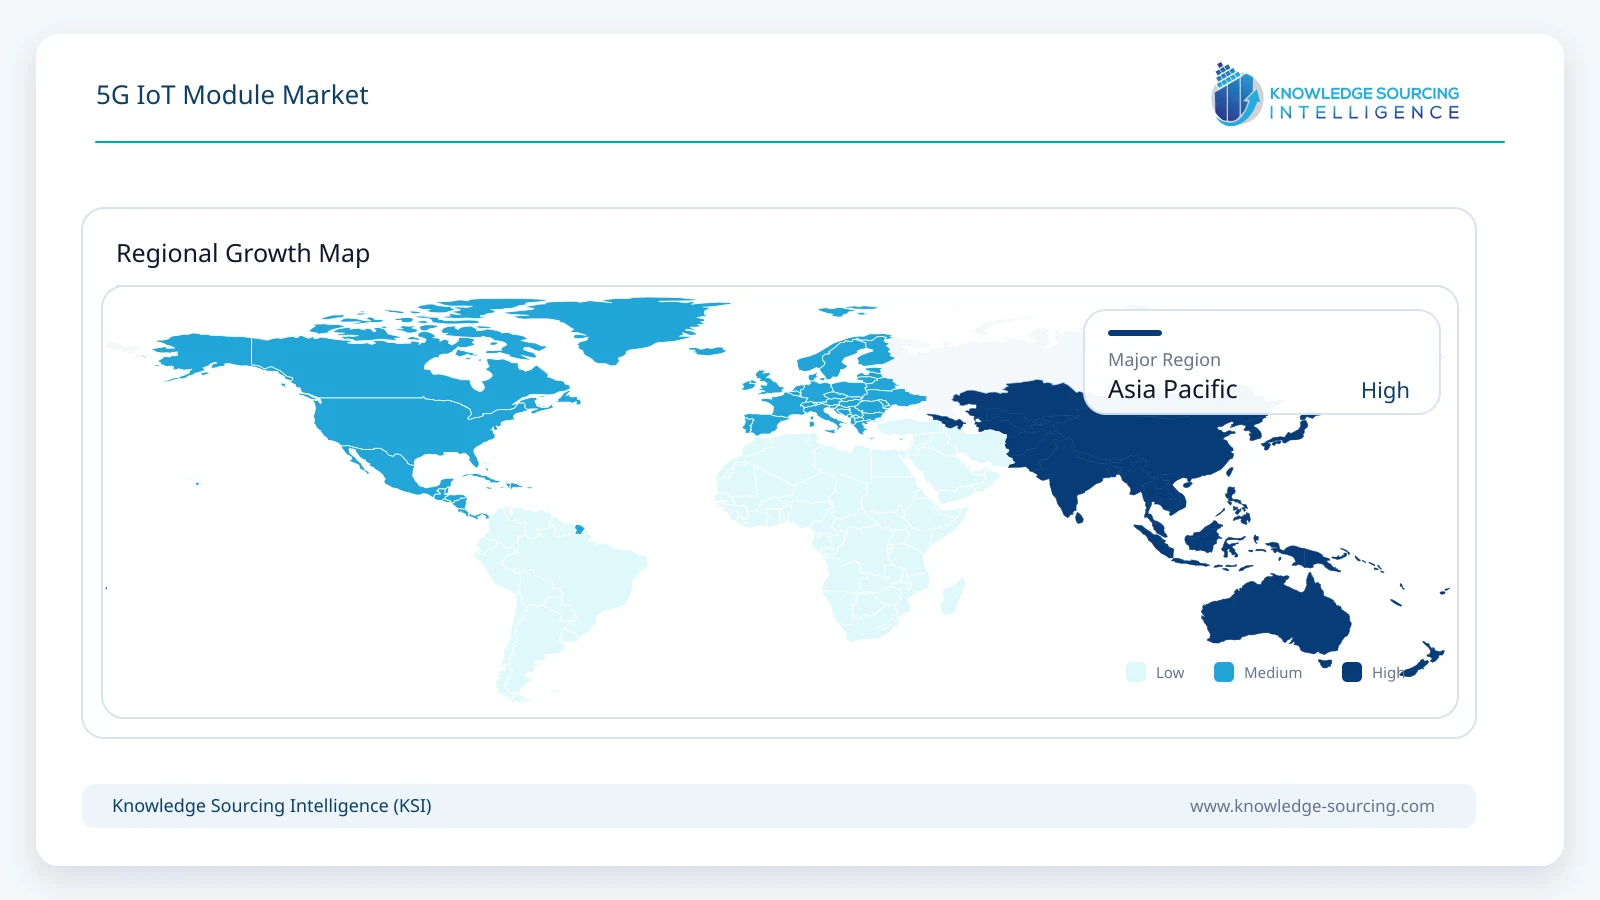
Asia Pacific is the largest 5G IoT module market, accounting for approximately 46.0% of global revenue in 2026. China contains the largest concentration of global module manufacturers, including Quectel, Fibocom, SIMCom, MeiG Smart, Neoway and GosuncnWelink, while the wider region contains major electronics, automotive and industrial-device manufacturing ecosystems.
Asia Pacific revenue is projected to reach approximately USD 3.61 billion by 2031, with the region’s share increasing to around 49%.
China remains central to supply as well as demand. Quectel’s total 2025 company revenue increased by more than 30% to RMB 24.33 billion, while the company reported continuing expansion across LTE, automotive, 5G, smart and short-range module products.
North America accounts for approximately 25% of the market in 2026. The region has a large enterprise router, FWA, industrial and connected-vehicle ecosystem and comparatively strong demand for globally certified modules.
Europe represents approximately 19% of revenue and has significant demand across industrial automation, automotive, rail, energy and private networks. Telit Cinterion’s Release 18 portfolio includes an FRMCS-ready module supporting n100 and n101 bands, directly addressing future railway connectivity.
Middle East and Africa and South America remain smaller but expand alongside private networks, industrial connectivity and broader 5G SA availability.
Technology Outlook
RedCap and eRedCap
RedCap represents the most important technology transition in the market because it fills the performance and cost gap between high-end 5G and LPWA/LTE IoT.
Current commercial RedCap products already support applications requiring hundreds of megabits per second while using simpler RF architectures than conventional 5G. Future eRedCap further reduces complexity for applications that need less bandwidth.
The result is a broader performance ladder within 5G rather than a single module architecture attempting to serve every IoT requirement.
Edge AI Within Cellular Modules
Processing capability is increasingly moving into the communication module itself. Smart modules already integrate CPUs, GPUs, multimedia interfaces and operating systems, while newer platforms increasingly add dedicated AI capability.
Telit Cinterion’s September 2026 Edge AI SDK illustrates this direction by allowing machine-learning inference directly on selected cellular modules.
The commercial benefit is reduced system complexity and lower latency for applications such as visual inspection, robotics, surveillance and smart retail.
5G-Advanced, NTN and Multi-Access Connectivity
Release 18 adds improved radio performance, carrier aggregation and functionality relevant to industrial and mobility devices. Telit Cinterion’s FE990D50 and FE990D60 are already based on Release 18 platforms.
Module roadmaps are also beginning to combine terrestrial 5G with satellite connectivity, positioning and Wi-Fi. The longer-term module becomes a multi-access connectivity platform rather than a cellular modem alone.
Recent Developments
September 2026: Telit Cinterion announced an Edge AI SDK for selected 4G, 5G RedCap and high-performance 5G modules. The software embeds LiteRT within module firmware, allowing machine-learning models to execute on the module’s own application processor without a separate AI accelerator.
August 28, 2026: Fibocom formally launched the RU311 5G RedCap module series, based on the UNISOC V527 platform. The modules support RedCap and LTE Cat 4 and are offered in LGA, M.2 and Mini PCIe formats for industrial gateways, surveillance, telematics, energy equipment and mobile broadband devices.
June 2026: Fibocom introduced the FG550-EAU 5G module with an optimized 4 Gb LPDDR4x memory configuration, reducing RAM capacity by 50% relative to the previous configuration while retaining major product functions. The redesign targets lower BOM cost, improved power efficiency and supply-chain stability for commercial 5G devices.
March 2026: Telit Cinterion launched its FE990D50 and FE990D60 Release 18 5G module series, incorporating enhanced carrier aggregation, up to 8RX MIMO and an FRMCS-ready variant for future railway communications.
January 2026: Telit Cinterion and Nokia announced a collaboration integrating 5G, Wi-Fi and NTN communication modules into Nokia’s Cognitive Digital Mine platform, targeting mining, oil and gas, logistics and other mission-critical industrial environments.
Competitive Landscape
Quectel remains one of the largest global cellular-module suppliers and has a broad 5G portfolio spanning full-capability NR modules, RedCap, automotive modules and Android-based smart modules. Its product architecture covers LGA, M.2 and Mini PCIe designs and increasingly integrates GNSS, Wi-Fi and edge processing.
Fibocom is another major global supplier with approximately USD 945 million of total 2025 revenue. Its portfolio includes conventional 5G modules, RedCap, automotive-grade products and smart modules. The company’s 2026 activity shows a strong emphasis on reducing module cost, expanding RedCap and integrating connectivity with AI-oriented edge devices.
Telit Cinterion competes strongly in industrial and enterprise IoT. Its portfolio combines full-capability 5G, RedCap, smart-device connectivity, positioning and cloud/device-management services. Release 18 products and embedded AI software are increasing the amount of functionality incorporated directly into the module.
Semtech continues the Sierra Wireless cellular-module business and currently offers full 5G and RedCap products, including EM9293 and EM8695. Its wider industrial IoT portfolio combines embedded modules, finished gateways, connectivity and device-management services.
SIMCom, MeiG Smart, Rolling Wireless, Neoway and GosuncnWelink provide additional competition across conventional 5G, automotive, RedCap and smart-module categories. Their presence contributes to pricing pressure, particularly in high-volume Asian device markets.
Cavli Wireless differentiates through bundled cellular modules, embedded eSIM, and its Hubble connectivity platform. The company is expanding its high-performance portfolio with CQM211 alongside its existing CQM220 RedCap products.
Trasna should now be treated as the owner of the former u-blox cellular-module business. u-blox completed the divestment on June 6, 2025, transferring cellular-module technology, employees, and product assets to Trasna. u-blox should therefore not be listed as an independent current cellular-module competitor.
Sequans remains relevant primarily as a 5G IoT semiconductor and technology supplier rather than as a major finished-module vendor. Qualcomm acquired its 4G IoT technology in 2024, while Sequans retained ownership of its 5G technology.
Competition is shifting from peak modem performance toward cost-performance fit, global certification, power consumption, migration compatibility, edge processing, integrated eSIM, and lifecycle management.
Analyst View
The most important change in the 5G IoT module market is the development of a genuine middle tier. Early 5G products were technically impressive but economically excessive for much of IoT. RedCap creates a module class that can replace widely deployed LTE technologies without forcing an OEM to adopt smartphone-class RF complexity and power consumption.
This changes where incremental revenue will come from. FWA and routers remain important, but the larger long-term opportunity lies in industrial endpoints, transportation, energy equipment, surveillance, wearables, and other devices that historically remained on LTE because conventional 5G offered limited economic benefit.
RedCap’s growth should not be interpreted as the disappearance of full-capability modules. Multi-gigabit products remain necessary for gateways, CPE, video systems and high-performance edge computing. Instead, the market becomes more segmented, with device designers selecting among full NR, RedCap, eRedCap and LPWA according to actual application requirements.
Module architecture is also becoming more integrated. Cellular connectivity is increasingly packaged with GNSS, eSIM, Wi-Fi, device management and local AI processing. This raises the strategic value of the module within the device while reducing the need for separate components.
The competitive advantage will therefore increasingly come from reducing an OEM’s total development burden rather than simply offering a faster modem. Pin-compatible migration, operator approvals, regional certifications, software tools, edge processing and integrated lifecycle management become as important as radio performance.
Asia Pacific remains structurally important because it combines device manufacturing, module manufacturing and growing domestic demand. North America and Europe remain higher-value destinations for globally certified industrial, automotive and enterprise modules.
The strongest incremental opportunities through 2031 are concentrated in RedCap/eRedCap, embedded industrial systems, automotive connectivity, edge-AI smart modules and platforms that combine connectivity with positioning, eSIM and device management.
5G IoT Module Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 2.86 billion |
| Total Market Size in 2031 | USD 7.36 billion |
| Forecast Unit | Billion |
| Growth Rate | 20.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Module Class, Form Factor, Application, Geography |
| Companies |
|
Market Segmentation
By Module Class
Full-Capability 5G NR Modules
5G RedCap & eRedCap Modules
5G Smart Modules
By Form Factor
LGA
M.2
Mini PCIe & Other Form Factors
By Application
FWA, Routers & Gateways
Industrial & Enterprise Equipment
Automotive & Transportation
Energy, Utilities & Smart Infrastructure
Healthcare & Wearable Devices
Other Applications
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
India
Japan
South Korea
Taiwan
Australia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition and Scope
2.3. Scope Exclusions
2.4. Market Segmentation
2.5. Key Market Indicators
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints and Challenges
3.3. Market Opportunities
3.4. Cellular IoT Technology Migration
3.5. 5G Standalone and RedCap Network Readiness
3.6. Module Pricing and BOM Economics
3.7. Device Certification and Operator Approval
3.8. Private 5G and Industrial IoT Opportunity
3.9. Porter’s Five Forces Analysis
3.10. Strategic Recommendations
4. TECHNOLOGY OUTLOOK
4.1. RedCap and eRedCap
4.2. Edge AI Within Cellular Modules
4.3. 5G-Advanced, NTN and Multi-Access Connectivity
5. 5G IOT MODULE MARKET BY MODULE CLASS
5.1. Introduction
5.2. Full-Capability 5G NR Modules
5.3. 5G RedCap & eRedCap Modules
5.4. 5G Smart Modules
6. 5G IOT MODULE MARKET BY FORM FACTOR
6.1. Introduction
6.2. LGA
6.3. M.2
6.4. Mini PCIe & Other Form Factors
7. 5G IOT MODULE MARKET BY APPLICATION
7.1. Introduction
7.2. FWA, Routers & Gateways
7.3. Industrial & Enterprise Equipment
7.4. Automotive & Transportation
7.5. Energy, Utilities & Smart Infrastructure
7.6. Healthcare & Wearable Devices
7.7. Other Applications
8. 5G IOT MODULE MARKET BY GEOGRAPHY
8.1. North America
8.1.1. United States
8.1.2. Canada
8.1.3. Mexico
8.2. South America
8.2.1. Brazil
8.2.2. Argentina
8.2.3. Others
8.3. Europe
8.3.1. Germany
8.3.2. United Kingdom
8.3.3. France
8.3.4. Italy
8.3.5. Spain
8.3.6. Others
8.4. Middle East and Africa
8.4.1. Saudi Arabia
8.4.2. UAE
8.4.3. South Africa
8.4.4. Others
8.5. Asia Pacific
8.5.1. China
8.5.2. India
8.5.3. Japan
8.5.4. South Korea
8.5.5. Taiwan
8.5.6. Australia
8.5.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Competitive Positioning
9.2. Full-Capability 5G Module Benchmarking
9.3. RedCap & eRedCap Portfolio Analysis
9.4. Form-Factor and Migration Compatibility
9.5. Automotive and Industrial Certification
9.6. Edge AI and Smart-Module Capability
9.7. eSIM, GNSS and Device-Management Integration
9.8. Strategic Developments
9.9. Competitive Dashboard
10. COMPANY PROFILES
10.1. Quectel Wireless Solutions Co., Ltd.
10.2. Fibocom Wireless Inc.
10.3. Telit Cinterion
10.4. Semtech Corporation / Sierra Wireless
10.5. SIMCom Wireless Solutions Limited
10.6. MeiG Smart Technology Co., Ltd.
10.7. Rolling Wireless S.à r.l.
10.8. Cavli Wireless
10.9. Neoway Technology Co., Ltd.
10.10. GosuncnWelink Technology Co., Ltd.
10.11. China Mobile IoT / OneMO
10.12. Trasna
11. ANALYST VIEW
12. APPENDIX
12.1. Research Methodology
12.2. Market Estimation and Assumptions
12.3. Scope and Double-Counting Controls
12.4. Definitions and Abbreviations
Navigate
Trusted by the world's leading organizations











