
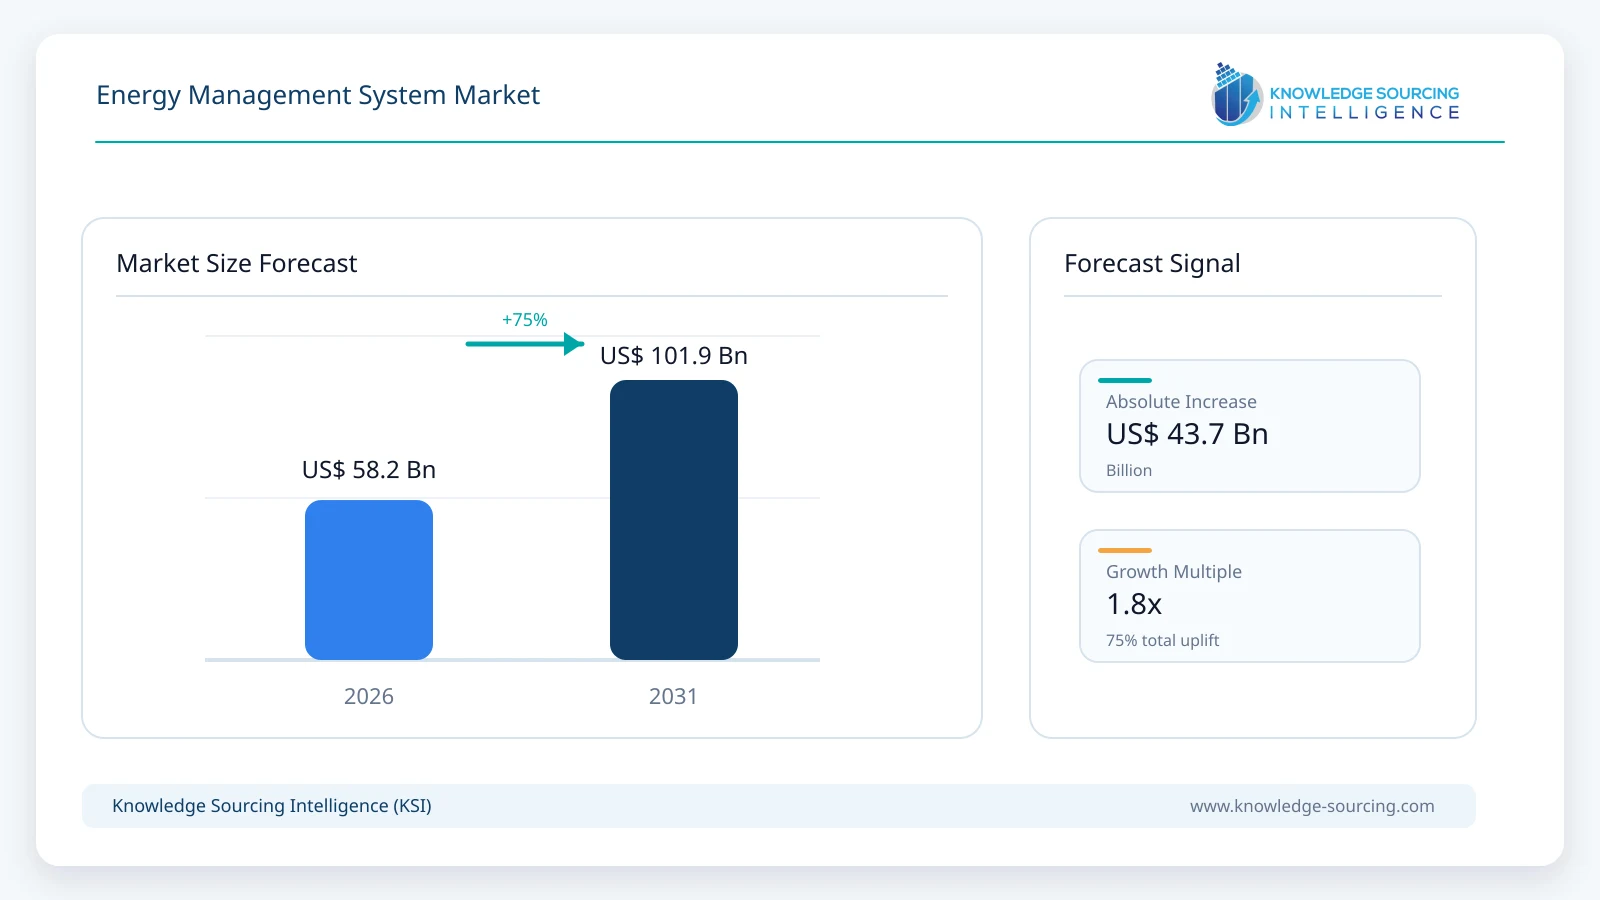
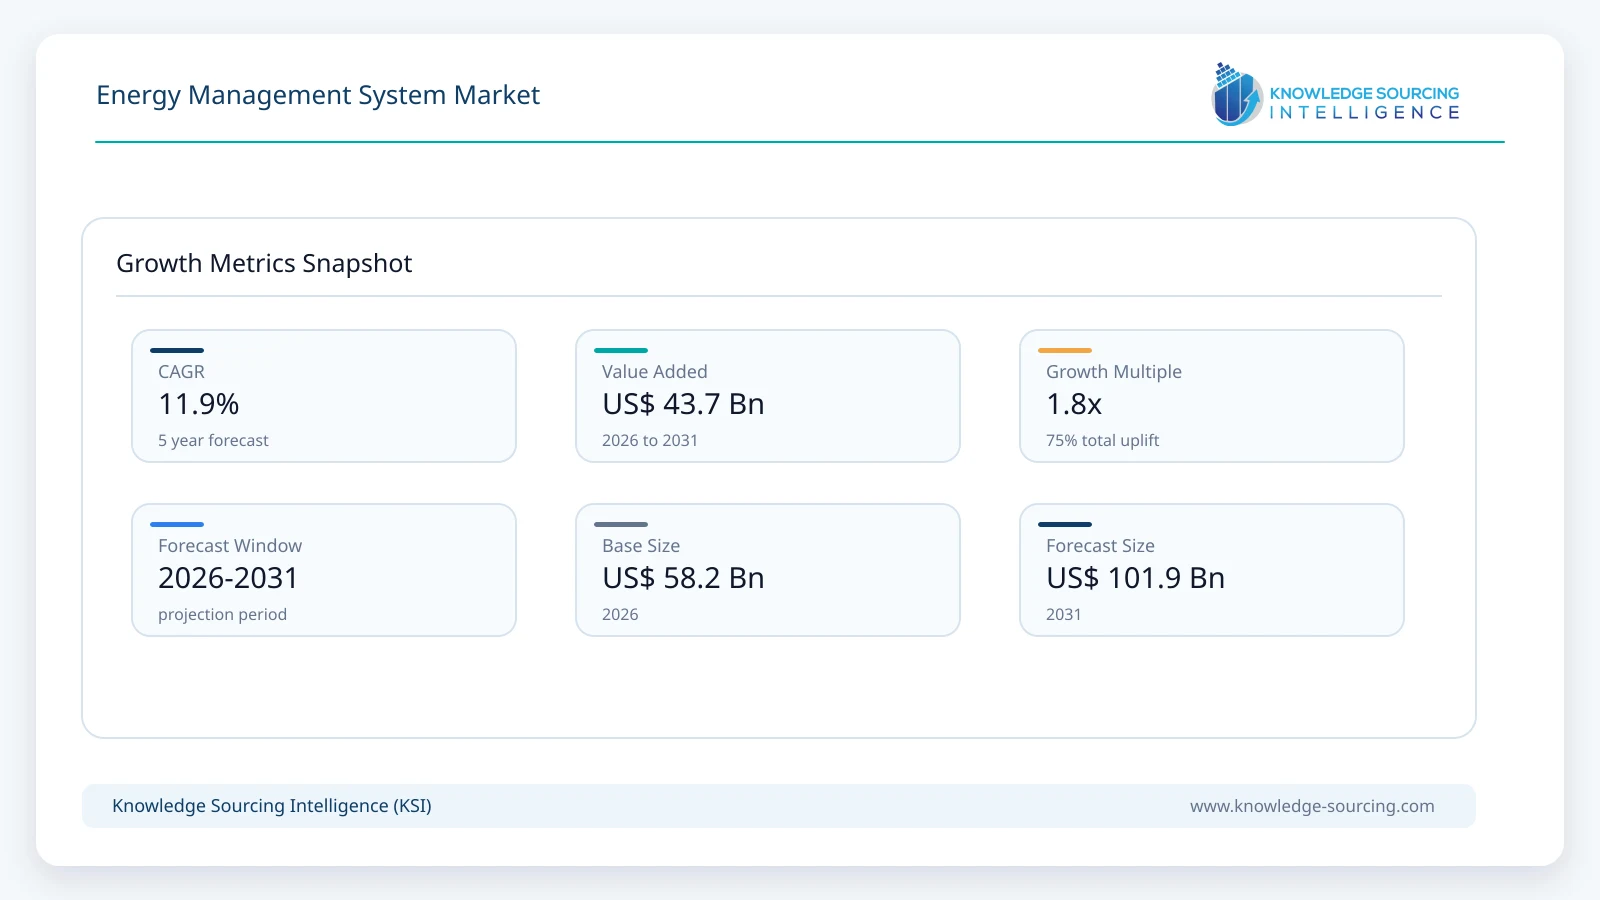
The global energy management system market is projected to increase from USD 58.2 billion in 2026 to USD 101.9 billion in 2031, representing a CAGR of 11.9% throughout the forecast period.
Highlights:
- 1Industrial Energy Management Systems account for an estimated 43.6% of 2026 market revenue.
- 2Cloud deployment represents about 56.8% of 2026 demand as multi-site monitoring and analytics expand.
- 3Software is the largest component, with an estimated 2026 market size of approximately USD 25.5 billion.
- 4North America represents about USD 20.5 billion of 2026 revenue, supported by industrial and commercial adoption.
- 5Artificial intelligence is moving from energy reporting toward automated optimization, forecasting and operator assistance.
Energy management has become a recurring operating requirement across industrial plants, data centers, hospitals, campuses, commercial portfolios and other energy-intensive facilities. The International Energy Agency (IEA) estimates that industry accounts for nearly 40% of global final energy consumption and identifies process optimization and energy management as important measures for improving industrial efficiency. The economics are particularly strong where energy forms a material share of operating costs or where facilities contain large motors, heating systems, compressed air, refrigeration, process heat and other continuously operated loads. Energy management systems give operators a common data layer for measuring consumption, identifying abnormal loads, benchmarking assets and verifying whether efficiency projects produce the expected savings.
The regulatory case is also becoming more direct. The European Union Energy Efficiency Directive requires enterprises with average annual energy consumption above 85 terajoules over the previous three years to implement a certified energy management system by October 11, 2027. Enterprises above 10 terajoules that do not implement an energy management system are subject to energy audits. ISO 50001:2018 remains the principal international framework for establishing and improving energy management systems and was confirmed as current in 2024. In the United States, the Department of Energy continues to support ISO 50001-aligned implementation through the 50001 Ready program, which provides a structured route for facilities to formalize continuous energy improvement.
Selected Segment Estimates
Segment | Subsegment | 2026 Contribution to Total Revenues | Analysis |
Offering | System | 72.5% share | Integrated software and hardware remain the core procurement package, while services support implementation and optimization. |
Component | Software | USD 25.5 billion | Largest component as analytics, visualization, forecasting and enterprise integration capture more value. |
Type | Industrial Energy Management System | 43.6% share | Largest type due to energy intensity, complex process loads and formal efficiency programs. |
Deployment | Cloud | 56.8% share | Multi-site access, lower infrastructure requirements and faster software updates support adoption. |
Application | Manufacturing | 30.8% share | Production facilities use energy management to control utility costs and process-related energy intensity. |
End User | Industrial | 45.6% share | Largest end-user group because energy savings directly affect operating margins in energy-intensive facilities. |
Geography | North America | USD 20.5 billion | Large installed base of digital facilities and industrial energy-management programs supports demand. |
Market Dynamics
Energy cost control and industrial efficiency support recurring investment
Energy management systems address a recurring operating expense rather than a one-time compliance requirement. Industrial facilities continuously face changes in production schedules, equipment condition, tariffs and load profiles, which means that efficiency losses can reappear even after individual retrofit projects are completed. A formal energy management system allows facilities to establish baselines, monitor significant energy users and verify whether process changes reduce energy intensity. The U.S. Department of Energy states that sites participating in structured energy-management programs typically achieve continuing annual energy savings over extended periods. This supports recurring spending on metering, analytics, controls, software licenses and professional services instead of limiting demand to initial hardware installation.
Mandatory energy-management requirements increase enterprise adoption
Regulation is moving energy management from a voluntary sustainability initiative toward an operating requirement for large energy users. The European Union Energy Efficiency Directive is particularly important because its Article 11 sets consumption-based thresholds for energy management systems and audits rather than relying only on company size. Enterprises consuming more than 85 terajoules annually must have a certified energy management system in place by October 2027. This creates a measurable compliance-driven opportunity across manufacturing, logistics, data infrastructure and large commercial sites. ISO 50001 provides a widely recognized framework for these systems and supports integration with existing environmental and quality-management processes.
Artificial intelligence increases the value of software and analytics
Energy management software is moving beyond dashboards and historical reporting. The next phase of adoption combines forecasting, anomaly detection, natural-language interaction and automated control. ABB integrated generative artificial intelligence capabilities into its industrial Energy Management System in April 2026, enabling users to query energy-performance data through natural language. Siemens added ISO 50001-certified energy management and artificial intelligence-enabled sustainability workflows to Building X during 2026. Johnson Controls expanded OpenBlue with artificial intelligence-based energy optimization and agentic capabilities, while Schneider Electric published 2026 research indicating that artificial intelligence-enabled building controls can materially reduce energy consumption in modeled commercial-building applications. These developments increase the software share of system value and strengthen demand for connected sensors, clean data and integration services.
Legacy integration and data quality remain important restraints
The main implementation constraint is rarely the availability of energy data alone. Large facilities often operate equipment from multiple generations and vendors, with inconsistent communications protocols, incomplete submetering and limited contextual information about production, occupancy or weather. A technically capable energy platform cannot optimize a process reliably if the underlying measurement architecture is incomplete or if operational data cannot be linked to energy consumption. Integration therefore adds engineering cost and can lengthen deployment schedules, particularly for older plants and complex campuses. Cybersecurity requirements become more important as operational technology is connected to cloud analytics and enterprise systems, which can slow adoption in critical infrastructure and highly regulated facilities.
Return on investment varies by facility and limits smaller deployments
The economic case for energy management is strongest where facilities have high energy bills, complex loads or large portfolios. Smaller sites with limited controllable loads may find that advanced analytics, submetering and integration costs produce longer payback periods. Organizations can also delay system investment when electricity prices are stable or when capital budgets prioritize production expansion over efficiency projects. This creates a two-speed market: large industrial and commercial users increasingly adopt advanced platforms, while smaller users often begin with basic monitoring, utility-data software or managed services before moving to more sophisticated automation.
Energy Management System Market Segment Analysis
By Offering
System
System offerings account for an estimated 72.5% of 2026 market revenue, equivalent to approximately USD 42.2 billion. This category combines the core software and hardware required to meter, collect, analyze and control energy use. Its scale reflects the fact that most enterprise deployments require a connected stack rather than a stand-alone application. The system share is expected to remain dominant through 2031, although services grow alongside it as users require integration, baseline development, commissioning, optimization and ongoing support. The boundary between systems and services is also becoming less rigid as software subscriptions increasingly bundle analytics and remote advisory capabilities.
By Component
Software
Software represents an estimated USD 25.5 billion in 2026 and is the largest component of the market. Its value is increasing because the competitive differentiation of an energy management system increasingly depends on analytics, workflow integration and the ability to convert meter data into operational decisions. Enterprise platforms now combine energy dashboards with tariff analysis, carbon accounting, anomaly detection, asset performance and forecasting. Cloud-native software also allows suppliers to add artificial intelligence capabilities and update algorithms without replacing field hardware. Hardware remains essential for metering and connectivity, but the recurring revenue opportunity is increasingly concentrated in software licenses, subscriptions and digital services.
By Type
Industrial Energy Management System
Industrial Energy Management Systems (IEMS) account for an estimated 43.6% of 2026 revenue, making them the largest type. Industrial sites have concentrated energy loads, measurable production outputs and significant opportunities to improve energy intensity through process optimization. Manufacturing plants can link consumption to production lines, shifts, batches and specific equipment, allowing energy performance to be managed alongside throughput, quality and maintenance. IEMS adoption is also supported by the greater use of industrial automation and connected sensors, which reduces the cost of collecting granular operating data. Energy-intensive industries such as metals, chemicals, food processing, automotive, pulp and paper and cement provide particularly strong use cases.
By Deployment
Cloud
Cloud deployment represents an estimated 56.8% of the 2026 market. The model is particularly attractive to organizations operating multiple facilities because it centralizes data, simplifies software updates and allows specialists to compare sites without maintaining separate infrastructure at each location. Cloud deployment also supports artificial intelligence models that require large data sets and frequent model updates. On-premise systems remain important in facilities with strict cybersecurity, latency or data-sovereignty requirements, and hybrid architectures are common where real-time control stays at the edge while analytics and reporting move to the cloud.
By Application
Manufacturing
Manufacturing accounts for an estimated 30.8% of 2026 market revenue, equivalent to approximately USD 17.9 billion. Energy management is commercially attractive in manufacturing because consumption can be linked directly to production performance. Plants use energy data to identify equipment operating outside expected ranges, avoid unnecessary peak demand, optimize compressed air and motor loads, and verify the savings generated by capital projects. The value proposition is strongest when energy data is integrated with manufacturing execution, maintenance and process-control systems rather than reviewed as a separate utility report.
By End User
Industrial
Industrial users represent an estimated 45.6% of 2026 market revenue, or approximately USD 26.5 billion. Their leading position reflects both scale and operating economics. A small percentage improvement in energy intensity can create substantial savings across large continuous-process facilities, while energy-management data also supports emissions reporting and internal investment decisions. Commercial buildings remain a large second demand pool, particularly across offices, hospitals, campuses, hotels and retail portfolios. Residential adoption is growing through smart-home energy management, distributed solar, battery storage and electric-vehicle charging, but average system values remain lower than in industrial and commercial deployments.
Technology and Market Impact
Solutions and Regulations | Latest Development | Market Impact |
ABB industrial EMS | Generative AI capabilities added to ABB Ability Energy Management System in April 2026 | Natural-language interaction moves energy analytics closer to operational users. |
Siemens Building X | Energy Manager achieved ISO 50001 certification in the June 2026 release | Formal standards alignment strengthens enterprise and compliance-led use cases. |
Johnson Controls OpenBlue | AI-native platform expansion announced in August 2026 | Autonomous optimization is moving into day-to-day building operations. |
Schneider Electric AI study | September 2026 research modeled up to 22% whole-building energy reduction with AI-enabled controls | Supports the business case for software-led optimization in commercial buildings. |
EU Energy Efficiency Directive | Enterprises above 85 TJ annual energy consumption must implement an energy management system by October 2027 | Creates a defined compliance deadline for large European energy users. |
ISO 50001 | ISO 50001:2018 remained current after review and confirmation in 2024 | Provides the principal international framework for systematic energy management. |
North America Market Analysis
North America is estimated to account for approximately USD 20.5 billion of energy management system revenue in 2026, representing about 35.2% of the global market. The region combines a large installed base of commercial building controls, energy-intensive manufacturing, data centers, healthcare facilities and multi-site enterprise portfolios.
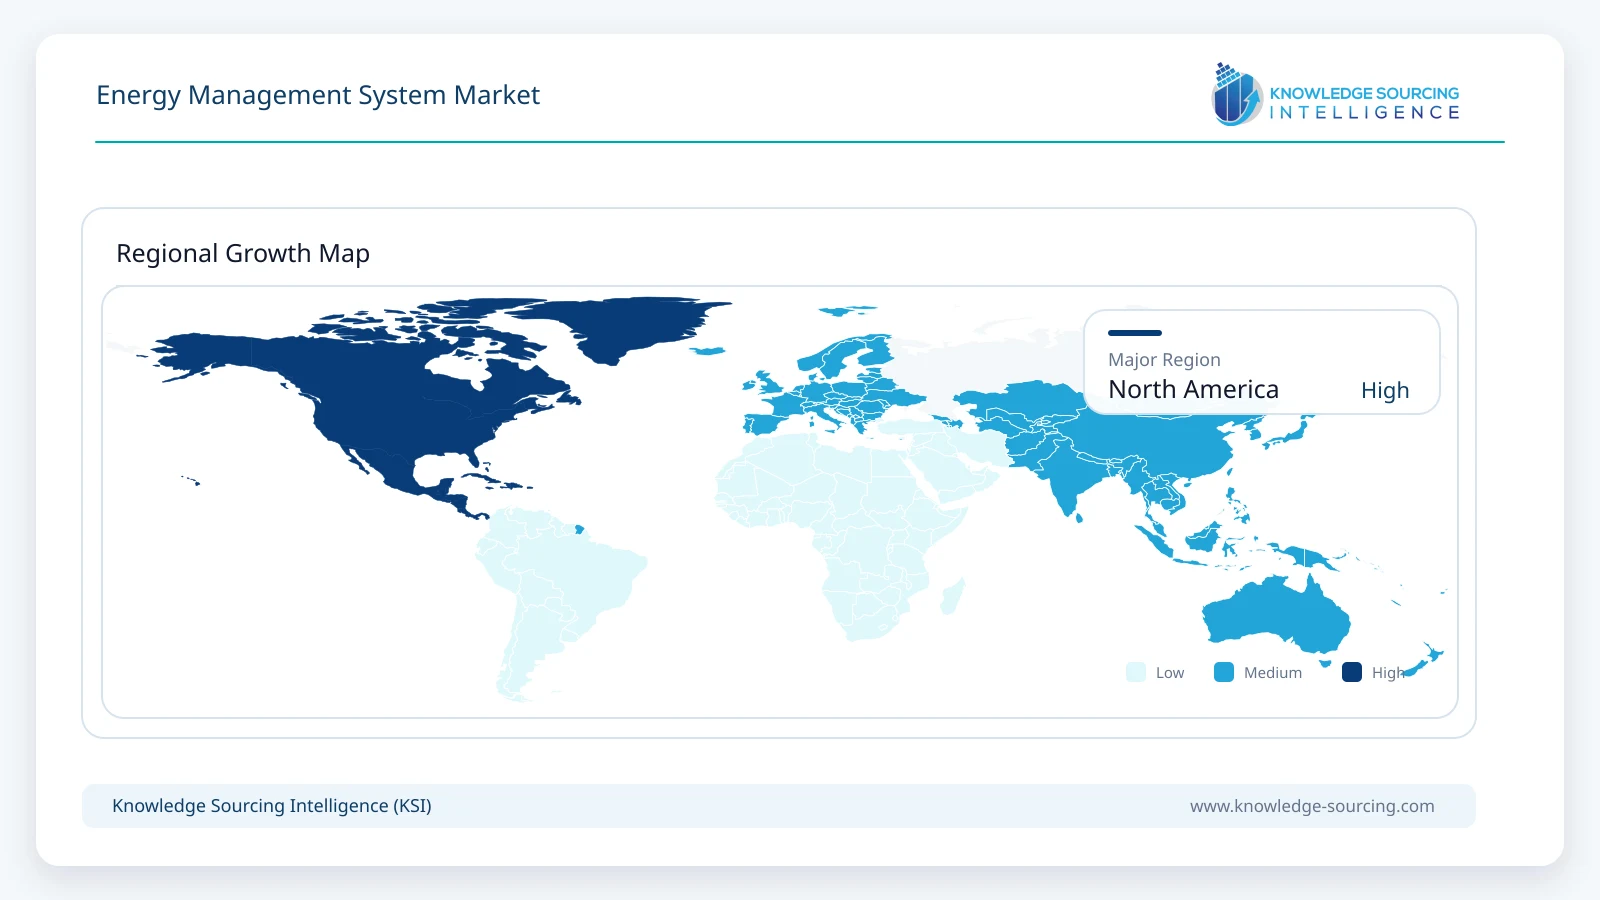
Demand is supported by relatively mature automation infrastructure, widespread use of cloud software and a strong market for performance contracting, energy services and building modernization. The United States is the principal contributor because its industrial and commercial customers have broad access to smart metering, digital controls and energy-management software.
The U.S. Department of Energy continues to support systematic energy management through the 50001 Ready program, while private-sector suppliers are expanding software and automated control capabilities. Honeywell was selected in January 2026 to modernize building automation and energy-management systems at Fort Benning, with the project expected to reduce power demand and energy waste. Johnson Controls expanded OpenBlue during 2026 with artificial intelligence-enabled control, and Schneider Electric continues to invest in energy and industrial intelligence across commercial and industrial applications. Canada provides additional demand through commercial buildings, industrial facilities and decarbonization programs. North America is expected to remain one of the largest regional revenue pools through 2031, although Asia Pacific records faster expansion from a lower installed base.
Competitive Landscape
Competition spans industrial automation, building controls, electrical distribution, enterprise software and specialist energy-management platforms. Schneider Electric, Siemens, ABB and Honeywell compete with broad portfolios that connect electrical infrastructure, automation and software. Johnson Controls has strong exposure to building automation and energy optimization, while Rockwell Automation and Emerson participate through industrial control and digital manufacturing environments. Eaton combines electrical distribution with intelligent power management, and IBM and other software providers participate through analytics, asset management and enterprise data integration. Competitive advantage increasingly depends on interoperability, installed-base connectivity, cybersecurity, software usability and the ability to demonstrate measurable energy savings across multi-site portfolios.
· Schneider Electric SE
· Siemens AG
· ABB Ltd.
· Honeywell International Inc.
· Johnson Controls International plc
· Eaton Corporation plc
· Rockwell Automation, Inc.
· Emerson Electric Co.
· IBM Corporation
· General Electric Company
· Delta Electronics, Inc.
· Legrand SA
· Azbil Corporation
· Yokogawa Electric Corporation
· Mitsubishi Electric Corporation
· Cisco Systems, Inc.
· GridPoint, Inc.
· DEXMA by Spacewell
Recent Developments
September 21, 2026: Schneider Electric published research indicating that artificial intelligence-enabled building controls can reduce whole-building energy use by up to 22% compared with traditional controls in the modeled scenarios used in the study.
August 5, 2026: Johnson Controls announced an AI-native expansion of its OpenBlue platform, including Energy & Comfort Intelligence and agentic artificial intelligence capabilities for building operations.
June 2026: Siemens reported that Building X Energy Manager achieved ISO 50001 certification as part of the platform's June 2026 release, alongside new artificial intelligence-enabled sustainability workflows.
April 27, 2026: Johnson Controls acquired Nantum AI to add advanced energy-optimization and control algorithms to the OpenBlue digital ecosystem.
April 1, 2026: ABB integrated its Industrial Knowledge Vault generative artificial intelligence capabilities with ABB Ability Energy Management System for natural-language access to energy-performance data.
January 7, 2026: Honeywell announced its selection by the U.S. Army to modernize building automation and energy-management systems at Fort Benning, Georgia.
Energy Management System Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 58.2 billion |
| Total Market Size in 2031 | USD 101.9 billion |
| Forecast Unit | Billion |
| Growth Rate | 11.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Offering, Component, Type, Development, Application, End User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
BY OFFERING
System
Services
BY COMPONENT
Software
Hardware
Services
BY TYPE
Industrial Energy Management System (IEMS)
Building Energy Management System (BEMS)
Home Energy Management System (HEMS)
BY DEPLOYMENT
On-Premise
Cloud
BY APPLICATION
Power & Energy
Telecom & IT
Manufacturing
Enterprise
Healthcare
Others
BY END USER
Residential
Commercial
Industrial
BY GEOGRAPHY
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Australia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Energy cost control and industrial efficiency
3.1.2. Mandatory energy-management requirements
3.1.3. Artificial intelligence and advanced analytics
3.2. Market Restraints
3.2.1. Legacy integration and data-quality limitations
3.2.2. Return-on-investment constraints for smaller facilities
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Regulatory and Standards Landscape
4. ENERGY MANAGEMENT SYSTEM MARKET BY OFFERING
4.1. System
4.2. Services
5. ENERGY MANAGEMENT SYSTEM MARKET BY COMPONENT
5.1. Software
5.2. Hardware
5.3. Services
6. ENERGY MANAGEMENT SYSTEM MARKET BY TYPE
6.1. Industrial Energy Management System (IEMS)
6.2. Building Energy Management System (BEMS)
6.3. Home Energy Management System (HEMS)
7. ENERGY MANAGEMENT SYSTEM MARKET BY DEPLOYMENT
7.1. On-Premise
7.2. Cloud
8. ENERGY MANAGEMENT SYSTEM MARKET BY APPLICATION
8.1. Power & Energy
8.2. Telecom & IT
8.3. Manufacturing
8.4. Enterprise
8.5. Healthcare
8.6. Others
9. ENERGY MANAGEMENT SYSTEM MARKET BY END USER
9.1. Residential
9.2. Commercial
9.3. Industrial
10. ENERGY MANAGEMENT SYSTEM MARKET BY GEOGRAPHY
10.1. North America
10.1.1. United States
10.1.2. Canada
10.1.3. Mexico
10.2. South America
10.2.1. Brazil
10.2.2. Argentina
10.2.3. Others
10.3. Europe
10.3.1. Germany
10.3.2. France
10.3.3. United Kingdom
10.3.4. Italy
10.3.5. Others
10.4. Middle East and Africa
10.4.1. Saudi Arabia
10.4.2. UAE
10.4.3. South Africa
10.4.4. Others
10.5. Asia Pacific
10.5.1. China
10.5.2. Japan
10.5.3. India
10.5.4. South Korea
10.5.5. Australia
10.5.6. Others
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Major Players and Strategy Analysis
11.2. Market Share Analysis
11.3. Mergers, Acquisitions, Agreements and Collaborations
11.4. Competitive Dashboard
12. COMPANY PROFILES
12.1. Schneider Electric SE
12.2. Siemens AG
12.3. ABB Ltd.
12.4. Honeywell International Inc.
12.5. Johnson Controls International plc
12.6. Eaton Corporation plc
12.7. Rockwell Automation, Inc.
12.8. Emerson Electric Co.
12.9. IBM Corporation
12.10. General Electric Company
12.11. Delta Electronics, Inc.
12.12. Legrand SA
12.13. Azbil Corporation
12.14. Yokogawa Electric Corporation
12.15. Mitsubishi Electric Corporation
12.16. Cisco Systems, Inc.
12.17. GridPoint, Inc.
12.18. DEXMA by Spacewell
13. RECENT DEVELOPMENTS
14. APPENDIX
14.1. Currency
14.2. Assumptions
14.3. Base and Forecast Years Timeline
14.4. Research Methodology
14.5. Abbreviations





Frequently asked questions
What is the projected growth rate of the EMS market?
The Energy Management System Market is projected to grow at an 11.9% CAGR from 2026-2031.
What is the estimated market value for EMS by 2031?
The Energy Management System Market is estimated to reach $101.9 billion by 2031.
Which industry segment holds the largest EMS market share?
Industrial Energy Management Systems account for 43.6% of 2026 revenue.
What is the dominant deployment type for Energy Management Systems?
Cloud deployment represents 56.8% of 2026 demand.
Which component is the largest in the EMS market?
Software is the largest component, valued at $25.5 billion in 2026.
What are key drivers influencing Energy Management System adoption?
Regulatory mandates and AI for optimization are significant drivers.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Energy Management System Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/energy-management-system-market