
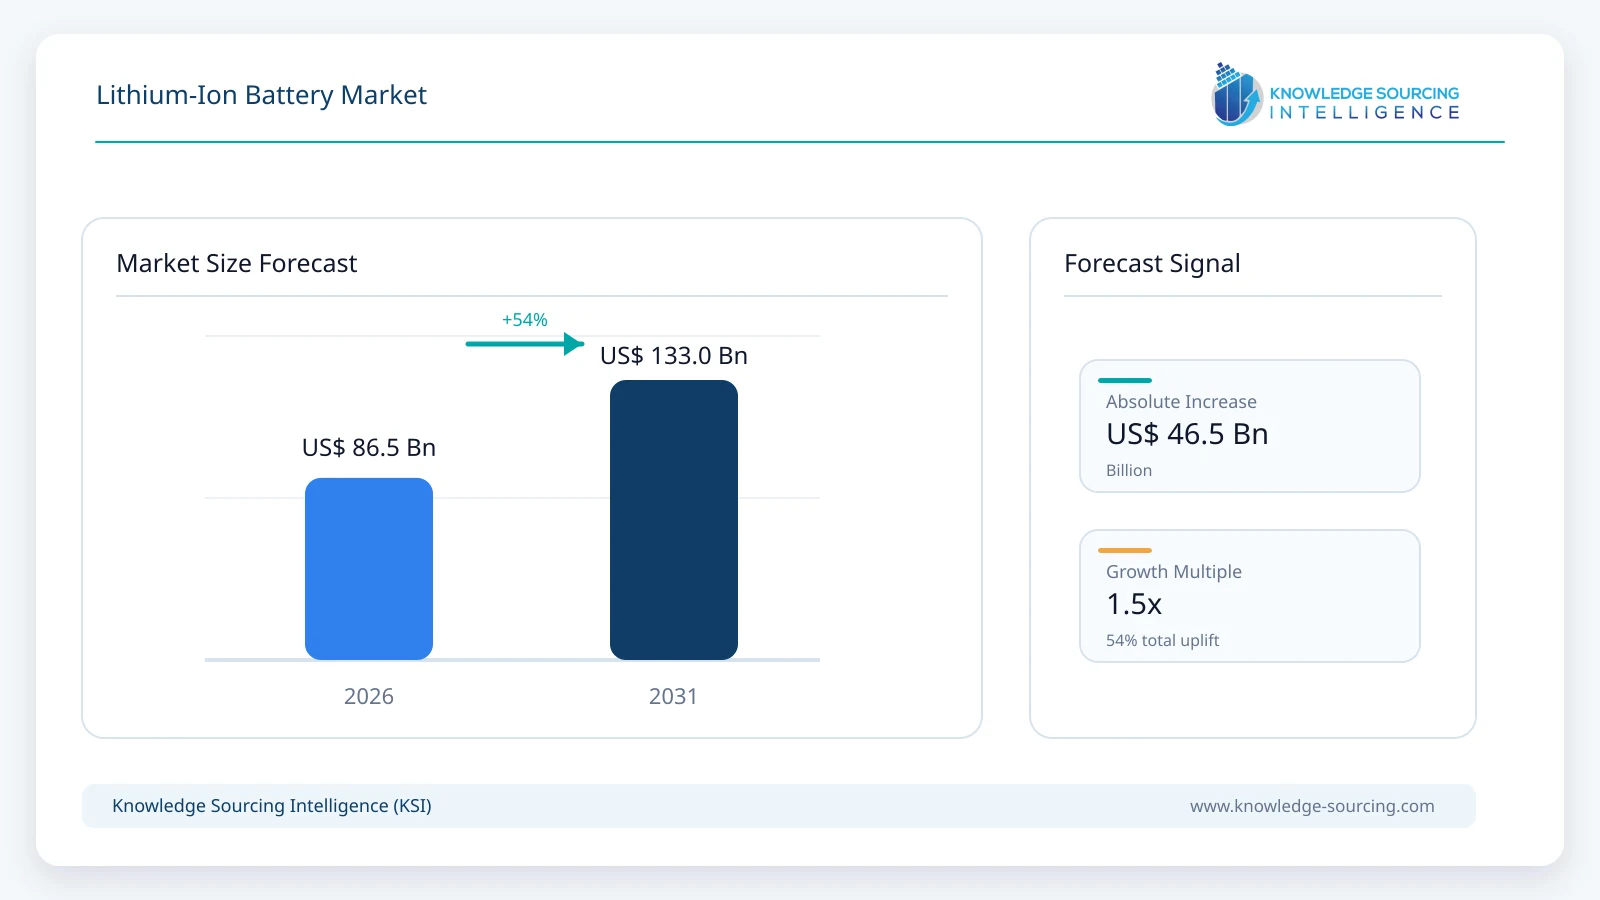
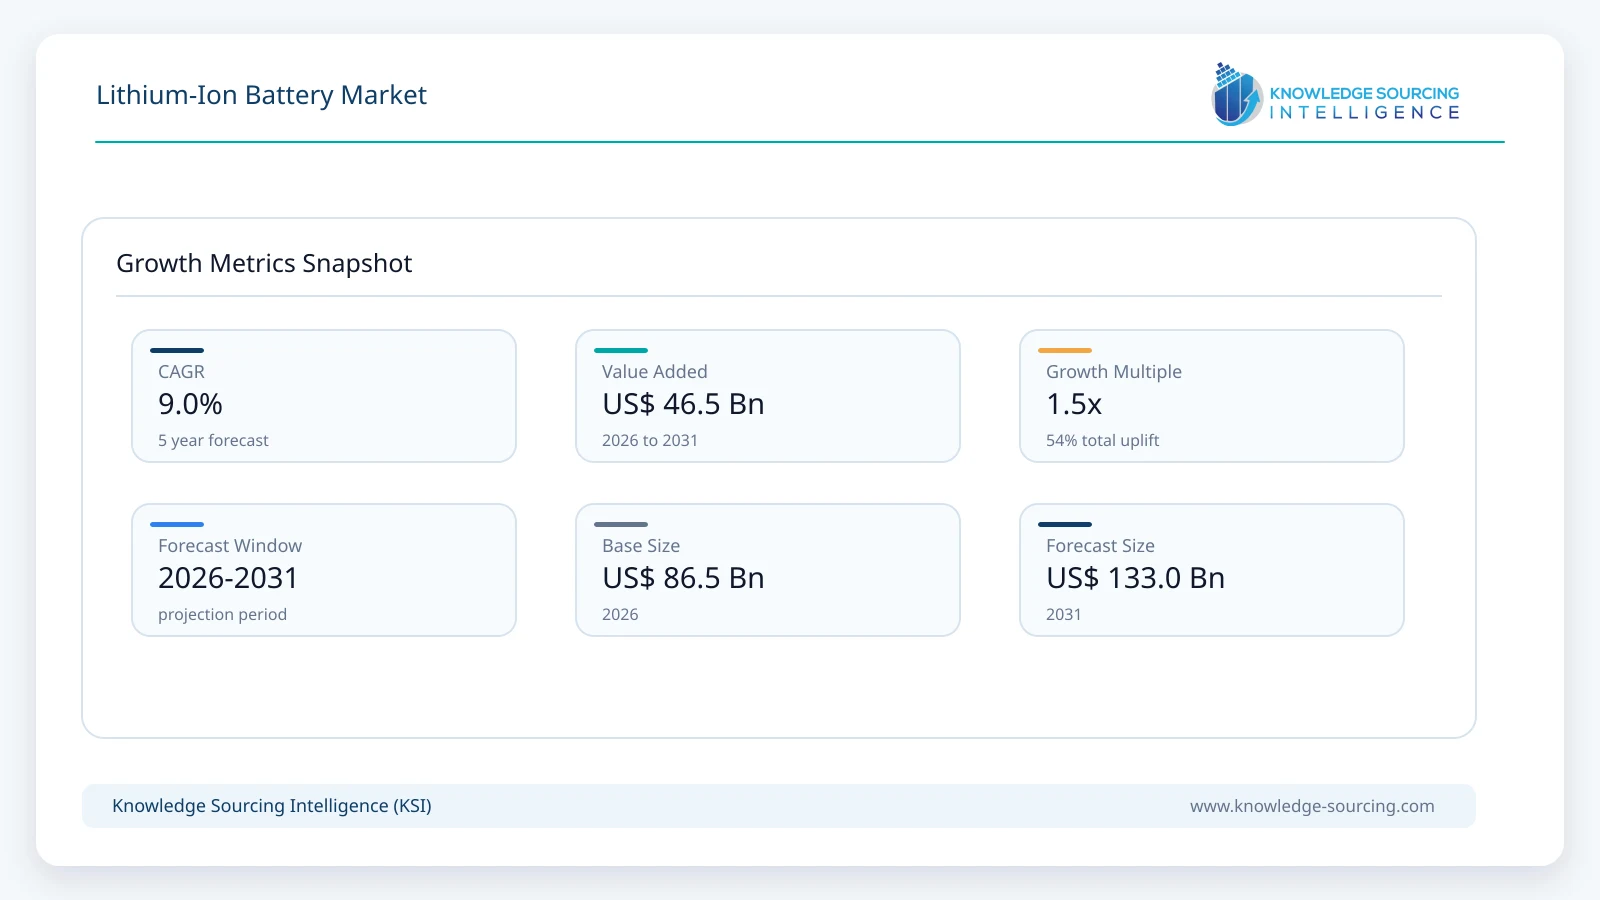
The global lithium-ion battery market is forecast to increase from USD 86.5 billion in 2026 to USD 133.0 billion in 2031, representing a CAGR of 9.0% during the forecast period.
Highlights:
- 1Batteries above 60,000 mAh account for approximately 65% of global lithium-ion battery market value in 2026, supported by automotive traction batteries and stationary energy storage.
- 2Automotive applications account for approximately 66% of global market value in 2026, reflecting the scale of battery-electric and plug-in hybrid vehicle deployment.
- 3Energy storage systems are projected to grow at approximately 17.9% annually through 2031, supported by grid storage, renewable integration and distributed energy applications.
- 4Asia Pacific accounts for approximately 73% of global market value in 2026, supported by China, South Korea and Japan's battery manufacturing and EV ecosystems.
- 5China accounts for more than 80% of global battery-cell production in 2025, retaining a dominant manufacturing position even as localization accelerates elsewhere.
The lithium-ion industry is expanding as cell costs continue to decline over time. The International Energy Agency reports that deployment of lithium-ion batteries across all applications increased more than sixfold between 2020 and 2025, with electric vehicles and battery storage representing around 90% of the current market by deployed capacity. This creates a market in which GWh volumes can grow rapidly even as technology improvements, competition and manufacturing scale reduce average cost per unit of storage.
China remains central to both demand and production. The IEA estimates that the country accounted for more than 80% of global battery cell production in 2025 and remains the largest source of EV battery demand, although manufacturing capacity is expanding in North America, Europe and other Asian markets.
Market Trends
LFP Is Expanding Beyond Its Original Cost-Oriented Positioning
Lithium iron phosphate batteries are increasing their role across electric mobility and stationary storage because they combine comparatively low material cost, strong thermal stability and long cycle life. LFP avoids nickel and cobalt, reducing exposure to some higher-cost battery metals, while improvements in cell-to-pack architecture help compensate for its lower gravimetric energy density. LG Energy Solution describes LFP as particularly suitable for applications where safety, longevity and cost efficiency are central and is expanding LFP production for energy storage systems in the United States. The chemistry is particularly attractive in stationary storage, where weight and volume constraints are less severe than in passenger vehicles, while EV manufacturers increasingly use LFP in standard-range models. Nickel-rich chemistries remain important for applications prioritizing maximum energy density, so the market is evolving toward a chemistry mix aligned with individual use cases rather than one universal cell architecture.
Stationary Storage Is Becoming a Second Major Demand Center
Lithium-ion battery demand was initially transformed by portable electronics and subsequently by electric vehicles, but stationary energy storage is now creating another major source of deployment. Renewable electricity systems require storage to balance variable generation, manage peak demand and improve grid flexibility, while commercial and industrial customers use batteries for backup power and energy management. LG Energy Solution entered 2026 targeting more than 90 GWh of new ESS battery orders and over 60 GWh of ESS production capacity, with more than 80% located in North America. The company began production at its Lansing facility in August 2026, with the plant designed for more than 35 GWh of annual battery capacity across ESS and EV applications. These investments illustrate how stationary storage is becoming sufficiently large to influence battery chemistry, manufacturing localization and supplier strategy independently of vehicle demand.
Battery Manufacturing Is Localizing but Remains Highly Concentrated
Governments and battery manufacturers are developing new factories in the United States, Europe, India and Southeast Asia to reduce dependence on imported cells and satisfy local-content requirements. However, the global production base remains strongly concentrated in Asia. The IEA reports that China produced more than 80% of battery cells in 2025 and that nearly all cells worldwide are supplied by companies headquartered in China, South Korea or Japan. The IEA's committed project pipeline for 2030 remains broadly sufficient to meet anticipated global battery deployment, but significant overcapacity may persist in some regions if announced projects operate close to nominal capacity. The industry therefore faces a dual trend: manufacturing becomes geographically more diversified for strategic reasons while supplier concentration and intense price competition continue to place pressure on margins.
Cylindrical Cell Platforms Are Moving Toward Larger Formats
Battery manufacturers are developing larger cylindrical cell formats to improve manufacturing efficiency, energy capacity and pack integration. Panasonic Energy is expanding advanced cylindrical battery production in Japan and North America, while LG Energy Solution began producing 46-Series cylindrical cells in Korea and reported an order backlog exceeding 440 GWh by April 2026. Larger cylindrical cells allow manufacturers to reduce the number of individual cells within a battery pack while potentially improving structural efficiency and production economics. The format competes with pouch and prismatic cells rather than replacing them universally because vehicle architecture, thermal management and manufacturer preferences differ. The broader trend demonstrates that lithium-ion innovation is increasingly occurring not only in chemistry but also in cell dimensions, electrode design, pack integration and manufacturing productivity.
Market Drivers
Electric Vehicle Deployment Remains the Largest Source of Battery Demand
Electric vehicles remain the principal application for lithium-ion batteries because passenger cars require battery packs that are orders of magnitude larger than those used in portable electronics. The IEA reports that EV battery deployment reached 1.2 TWh in 2025 and is expected to approach 3 TWh by 2030 under current and stated policy scenarios. Battery demand expands through both higher EV sales and increasing electrification of trucks, buses and other transport categories. The market's revenue growth is lower than its growth in GWh because manufacturing scale, chemistry shifts and improved production efficiency continue to reduce cost per unit of storage. Nevertheless, the amount of physical manufacturing infrastructure required remains substantial, supporting investment in cells, active materials, separators, electrolytes and recycling. EV demand also accelerates product innovation because automakers simultaneously seek longer range, faster charging, lower cost, improved safety and greater cycle life.
Renewable Energy Deployment Is Increasing Storage Requirements
Solar and wind capacity additions create greater need for electricity storage because generation varies according to weather and time of day. Lithium-ion batteries are currently the dominant technology for short-duration electrochemical storage because of their high round-trip efficiency, modular deployment and established manufacturing base. Grid-scale projects can be installed comparatively quickly and scaled from individual commercial systems to multi-hundred-megawatt facilities. ESS growth is influencing chemistry strategy as suppliers prioritize LFP for applications where cycle life, cost and thermal stability are more important than achieving the highest possible energy density. LG Energy Solution expects global ESS installations to grow by more than 40% during 2026 and is allocating substantial production capacity to the segment. Panasonic is similarly adapting selected lithium-ion production capability for data-center storage applications as AI infrastructure increases electricity and backup-power requirements.
Manufacturing Scale Continues to Reduce Battery Costs
Lithium-ion battery manufacturing has moved from relatively specialized production to very large-scale industrial facilities measured in tens of gigawatt-hours annually. CATL reported global production capacity of 772 GWh at the end of 2025, with a further 321 GWh under construction, while annual lithium-ion battery sales reached 661 GWh. Larger factories allow manufacturers to spread fixed costs across greater output, automate production and strengthen purchasing power across battery materials. Chemistry development also reduces cost, particularly through LFP and lower-cobalt formulations. Falling battery costs make EVs and storage systems more economically competitive, reinforcing demand and creating a feedback loop between manufacturing scale and deployment. However, rapid capacity expansion also increases the risk of oversupply and weak margins if utilization falls below planned levels.
Market Restraints and Challenges
Manufacturing Overcapacity Is Pressuring Battery Economics
Battery manufacturing capacity is expanding ahead of near-term demand in several regions. The IEA reports that committed global manufacturing capacity for 2030 remains sufficient to meet expected deployment and highlights potential short-term overcapacity in China and the United States. Overcapacity benefits battery buyers through stronger price competition but creates financial pressure for manufacturers because large factories need high utilization to generate attractive returns. Companies may delay projects, repurpose EV capacity toward ESS or consolidate production if demand develops more slowly than expected. The market therefore faces an unusual situation in which physical battery deployment can grow rapidly while producer profitability remains constrained. Scale, technology differentiation, customer contracts and supply-chain efficiency become increasingly important competitive advantages when capacity is abundant.
Critical Mineral and Supply Chain Exposure Remains Significant
Lithium-ion cells depend on lithium, graphite and, for many chemistries, nickel, cobalt and manganese. Supply diversification is improving, but refining and active-material production remain geographically concentrated. Battery manufacturers therefore seek long-term raw-material agreements and localized supply chains to reduce exposure to commodity volatility and policy restrictions. LG Energy Solution's August 2026 agreement with Smackover Lithium provides for 8,000 metric tonnes of U.S.-produced lithium carbonate annually over ten years, supporting a more localized North American LFP supply chain. Chemistry shifts can reduce exposure to individual materials, as LFP removes nickel and cobalt, but lithium and graphite remain fundamental. Material prices can therefore alter battery manufacturing economics even when factory productivity improves.
Safety Requirements Remain Critical Across High-Energy Applications
Lithium-ion batteries store substantial energy within compact cells, making thermal management, cell quality and battery management systems critical. Manufacturing defects, mechanical damage, internal short circuits or uncontrolled heating can result in thermal runaway, creating heightened regulatory and engineering requirements for EVs, aircraft, consumer devices and stationary storage. LFP offers stronger thermal stability than several nickel-rich chemistries, contributing to its growth in stationary applications, but battery-system safety depends on pack design and operating controls as well as chemistry. Manufacturers therefore continue investing in separators, monitoring, thermal management, pack architecture and battery-management software. Safety requirements can increase testing and certification costs and create significant financial exposure if quality problems lead to large recalls.
Lithium-Ion Battery Market Segment Analysis
By Power Capacity
More Than 60,000 mAh
Lithium-ion batteries above 60,000 mAh are projected to generate approximately USD 90.4 billion in market revenue by 2031, remaining the largest capacity segment because automotive traction batteries and stationary energy storage dominate physical battery deployment. A single EV battery pack can contain tens of kilowatt-hours of capacity, while grid-scale storage projects operate at megawatt-hour or gigawatt-hour scale, making these applications substantially larger than portable-electronics batteries on an energy basis. Deployment is increasing as electric cars gain share and renewable electricity systems add storage. The segment also benefits from growing electrification of trucks, buses, industrial equipment and data-center backup systems. Lower-capacity batteries remain important for smartphones, laptops, wearables and power tools, but their smaller energy requirement limits their contribution to overall battery demand relative to mobility and stationary storage. This keeps the highest-capacity segment dominant through 2031 even as cell prices continue declining.
By End-User Industry
Automotive
Automotive applications are projected to generate approximately USD 81.1 billion by 2031, remaining the largest end-user segment. Electric cars continue to account for the majority of lithium-ion battery deployment, while electric trucks, buses and other commercial vehicles add incremental demand. The IEA's 2026 outlook indicates EV battery deployment approaching 3 TWh by 2030, compared with 1.2 TWh in 2025. Automotive battery competition increasingly focuses on cost per kWh, charging speed, safety, cycle life, low-temperature performance and pack integration. Manufacturers are using several chemistry and form-factor strategies, including LFP for cost-sensitive vehicles, nickel-rich cells for longer-range models and larger cylindrical cells to improve manufacturing and pack efficiency. Energy storage systems grow more quickly from a smaller base, but the physical size and continued expansion of global EV deployment keep automotive applications dominant throughout the forecast period.
Fastest-Growing End User
Energy Storage Systems
Energy storage systems are projected to reach approximately USD 25.8 billion by 2031, supported by renewable integration, grid balancing, commercial energy management and data-center power requirements. Lithium-ion has become the principal technology for short-duration battery storage because it benefits from the same large-scale manufacturing ecosystem developed for electric vehicles. LFP is particularly important because stationary storage prioritizes cost, safety and cycle life over minimum weight. LG Energy Solution is expanding North American LFP production and entered 2026 targeting more than 90 GWh of new ESS orders, while Panasonic is adapting lithium-ion manufacturing capability for data-center storage demand. ESS therefore provides battery manufacturers with an increasingly significant alternative demand pool, particularly when EV production growth varies by region.
Major Region
Asia Pacific
Asia Pacific is projected to generate approximately USD 92.4 billion in lithium-ion battery revenue by 2031, retaining its dominant position because China, South Korea and Japan contain the world's largest battery manufacturers and electric-vehicle supply chains.
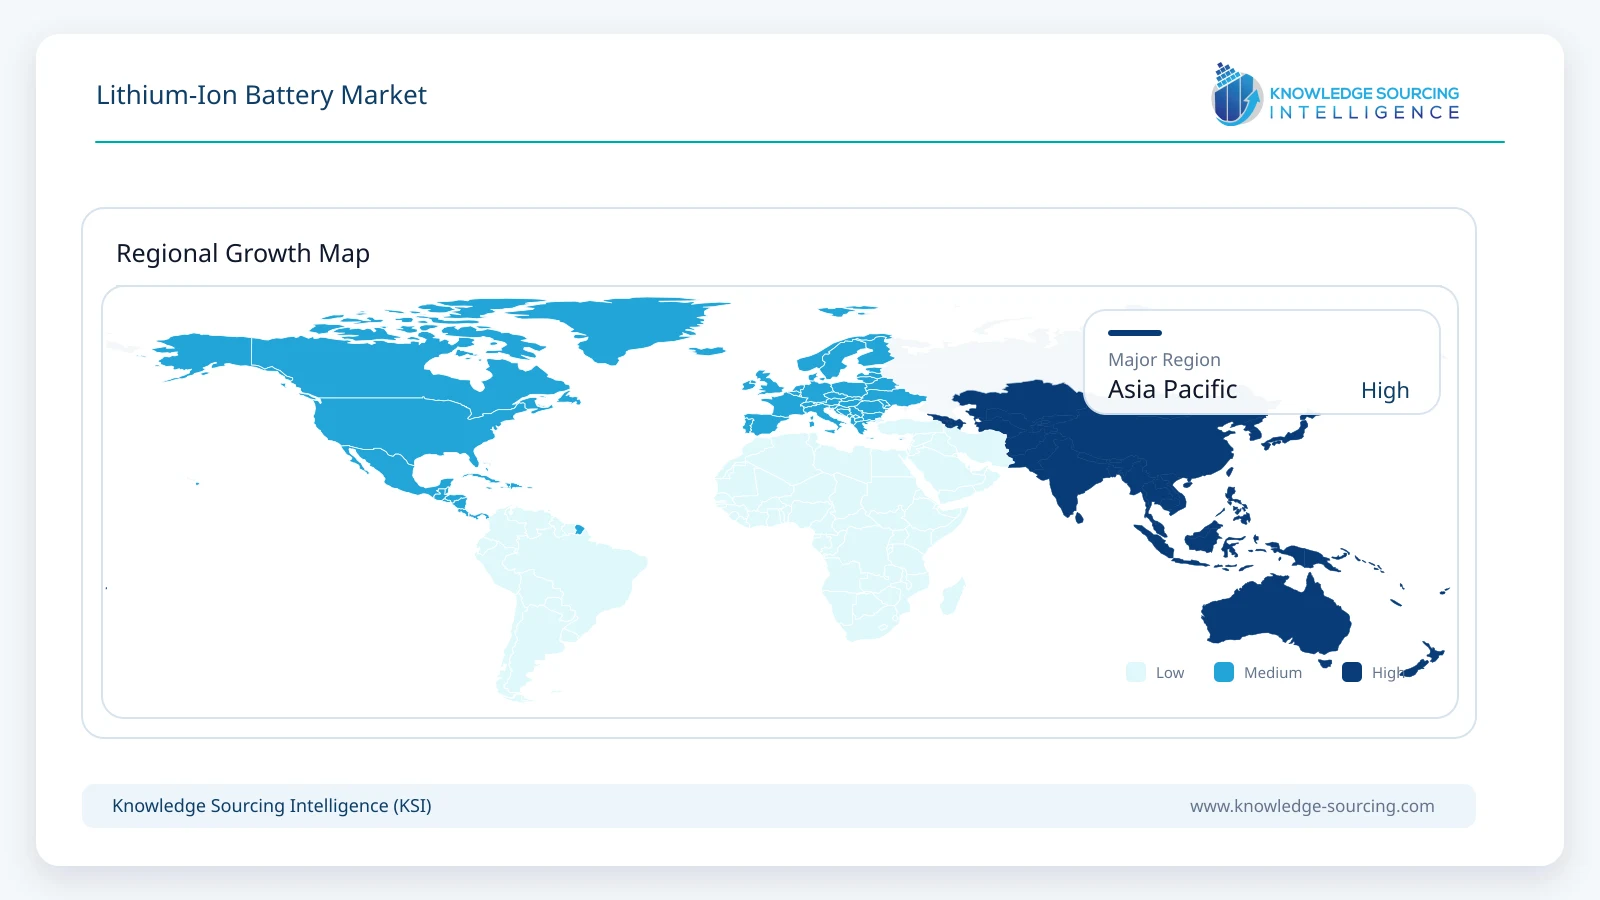
The region's importance extends across the full value chain from active materials and cell production to EV manufacturing and stationary storage. China alone accounted for more than 80% of global battery cell production in 2025, while Chinese, Korean and Japanese companies collectively supply almost all cells worldwide. CATL, BYD, LG Energy Solution, Samsung SDI, SK On and Panasonic Energy give the region an unusually concentrated manufacturing ecosystem with large investments in research, automation and production scale. North America and Europe are increasing local cell manufacturing, but the announced project pipeline does not remove Asia Pacific's cost and supply-chain advantages during the forecast period.
Major Country
China
China remains the most important individual lithium-ion battery market because it combines the world's largest cell-manufacturing capacity, EV market, battery-material supply chain and rapidly expanding energy-storage sector. The IEA estimates that the country accounted for more than 80% of global cell production in 2025 and around 60% of global EV battery demand in 2024. China's demand share is expected to decline gradually as EV adoption accelerates elsewhere, but it remains the largest individual market through 2031. Domestic manufacturers have also achieved enormous scale. CATL sold 661 GWh of lithium-ion batteries in 2025 and reported 772 GWh of global production capacity, while BYD remains another major vertically integrated battery and EV producer. This scale creates strong manufacturing economics and reinforces China's influence over global battery pricing and technology competition.
Competitive Environment and Analysis
The lithium-ion battery industry is highly concentrated among Asian manufacturers but is becoming more geographically diversified as production expands in North America and Europe. CATL remains the world's largest power-battery supplier and reported lithium-ion sales of 661 GWh in 2025. BYD combines battery manufacturing with vertically integrated vehicle production, while LG Energy Solution, Samsung SDI and SK On maintain substantial Korean production and international joint ventures. Panasonic Energy remains an important cylindrical-cell supplier and continues expanding automotive battery capability in Japan and North America. EVE Energy, CALB and Gotion High-Tech add further Chinese capacity, while Envision AESC expands internationally.
Competition increasingly depends on more than scale. Suppliers differentiate through chemistry, manufacturing yield, fast charging, cell format, lifecycle, safety, local-content qualification and long-term customer agreements. ESS is also creating a second competitive arena, particularly around LFP, where lower cost and long cycle life are often more important than maximum energy density.
Recent Developments
September 2026: Panasonic Energy launched Energy Innovation Square in Osaka as a global R&D hub for next-generation lithium-ion batteries serving automotive and data-center applications.
August 2026: LG Energy Solution began production at its new Lansing, Michigan facility, targeting more than 35 GWh of annual capacity for ESS and EV batteries at full scale.
August 2026: LG Energy Solution signed a ten-year agreement to source 8,000 tonnes of U.S.-produced battery-grade lithium carbonate annually from Smackover Lithium.
April 2026: LG Energy Solution reported more than 440 GWh of 46-Series cylindrical battery order backlog and targeted more than 50 GWh of North American ESS production capacity by year-end.
March 2026: CATL reported lithium-ion battery sales of 661 GWh for 2025, up 39%, and global production capacity of 772 GWh.
Market Outlook
The lithium-ion battery market is forecast to increase from USD 86.5 billion in 2026 to USD 133.0 billion by 2031 as electric mobility and stationary storage increase global battery deployment. Automotive applications remain the largest source of revenue, while ESS provides the strongest incremental growth opportunity as renewable-power systems and data centers require additional storage.
Battery manufacturing becomes more geographically diversified, but Asia Pacific remains dominant through the forecast period and China continues to lead both production and demand. LFP gains market share as cost, safety and cycle life become increasingly important, while high-energy nickel chemistries remain important for premium and long-range vehicles.
The market's physical growth in GWh is likely to remain considerably faster than its growth in dollar value because manufacturing scale and competition continue reducing battery costs. Suppliers therefore increasingly compete through manufacturing productivity, technology differentiation, localization and long-term customer relationships rather than relying solely on market-volume expansion.
Lithium-ion Battery Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 86.5 billion |
| Total Market Size in 2031 | USD 133.0 billion |
| Forecast Unit | Billion |
| Growth Rate | 9.0% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Power Capacity, End-User Industry, Geography |
| Companies |
|
Market Segmentation
By Power Capacity
0 to 3,000 mAh
3,000 mAh to 10,000 mAh
10,000 mAh to 60,000 mAh
More Than 60,000 mAh
By End-User Industry
Automotive
Consumer Electronics
Energy Storage Systems
Aerospace and Defense
Others
By Geography
North America
By Power Capacity
By End-User Industry
By Country
United States
Canada
Mexico
South America
By Power Capacity
By End-User Industry
By Country
Brazil
Argentina
Others
Europe
By Power Capacity
By End-User Industry
By Country
Germany
France
United Kingdom
Italy
Spain
Sweden
Hungary
Poland
Others
Middle East and Africa
By Power Capacity
By End-User Industry
By Country
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
By Power Capacity
By End-User Industry
By Country
China
South Korea
Japan
India
Indonesia
Thailand
Australia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Battery Manufacturing Capacity Outlook
3.7. Battery Chemistry and Raw Material Outlook
3.8. Battery Recycling and Circularity
3.9. Policies and Regulations
3.10. Strategic Recommendations
4. TECHNOLOGY OUTLOOK
4.1. Lithium Iron Phosphate
4.2. Nickel-Rich NCM/NCA
4.3. Larger Cylindrical Cells
4.4. Pouch and Prismatic Cell Technologies
4.5. Silicon-Enhanced Anodes
4.6. Fast-Charging Technology
4.7. Battery Management Systems
4.8. Battery Safety and Thermal Management
5. LITHIUM-ION BATTERY MARKET BY POWER CAPACITY
5.1. Introduction
5.2. 0 to 3,000 mAh
5.3. 3,000 mAh to 10,000 mAh
5.4. 10,000 mAh to 60,000 mAh
5.5. More Than 60,000 mAh
6. LITHIUM-ION BATTERY MARKET BY END-USER INDUSTRY
6.1. Introduction
6.2. Automotive
6.3. Consumer Electronics
6.4. Energy Storage Systems
6.5. Aerospace and Defense
6.6. Others
7. LITHIUM-ION BATTERY MARKET BY GEOGRAPHY
7.1. Introduction
7.2. North America
7.2.1. By Power Capacity
7.2.2. By End-User Industry
7.2.3. By Country
7.2.3.1. United States
7.2.3.2. Canada
7.2.3.3. Mexico
7.3. South America
7.3.1. By Power Capacity
7.3.2. By End-User Industry
7.3.3. By Country
7.3.3.1. Brazil
7.3.3.2. Argentina
7.3.3.3. Others
7.4. Europe
7.4.1. By Power Capacity
7.4.2. By End-User Industry
7.4.3. By Country
7.4.3.1. Germany
7.4.3.2. France
7.4.3.3. United Kingdom
7.4.3.4. Italy
7.4.3.5. Spain
7.4.3.6. Sweden
7.4.3.7. Hungary
7.4.3.8. Poland
7.4.3.9. Others
7.5. Middle East and Africa
7.5.1. By Power Capacity
7.5.2. By End-User Industry
7.5.3. By Country
7.5.3.1. Saudi Arabia
7.5.3.2. UAE
7.5.3.3. South Africa
7.5.3.4. Others
7.6. Asia Pacific
7.6.1. By Power Capacity
7.6.2. By End-User Industry
7.6.3. By Country
7.6.3.1. China
7.6.3.2. South Korea
7.6.3.3. Japan
7.6.3.4. India
7.6.3.5. Indonesia
7.6.3.6. Thailand
7.6.3.7. Australia
7.6.3.8. Others
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements, and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. CATL
9.2. BYD Company Limited
9.3. LG Energy Solution Ltd.
9.4. Panasonic Energy Co., Ltd.
9.5. Samsung SDI Co., Ltd.
9.6. SK On Co., Ltd.
9.7. EVE Energy Co., Ltd.
9.8. CALB Group Co., Ltd.
9.9. Gotion High-Tech Co., Ltd.
9.10. Envision AESC
9.11. Sunwoda Electronic Co., Ltd.
9.12. Farasis Energy
9.13. GS Yuasa Corporation
9.14. Toshiba Corporation
9.15. Murata Manufacturing Co., Ltd.
10. APPENDIX
10.1. Market Definition and Scope
10.2. Currency
10.3. Assumptions
10.4. Base and Forecast Years
10.5. Research Methodology
10.6. Data Triangulation and Validation
10.7. Abbreviations
Navigate
Trusted by the world's leading organizations











