
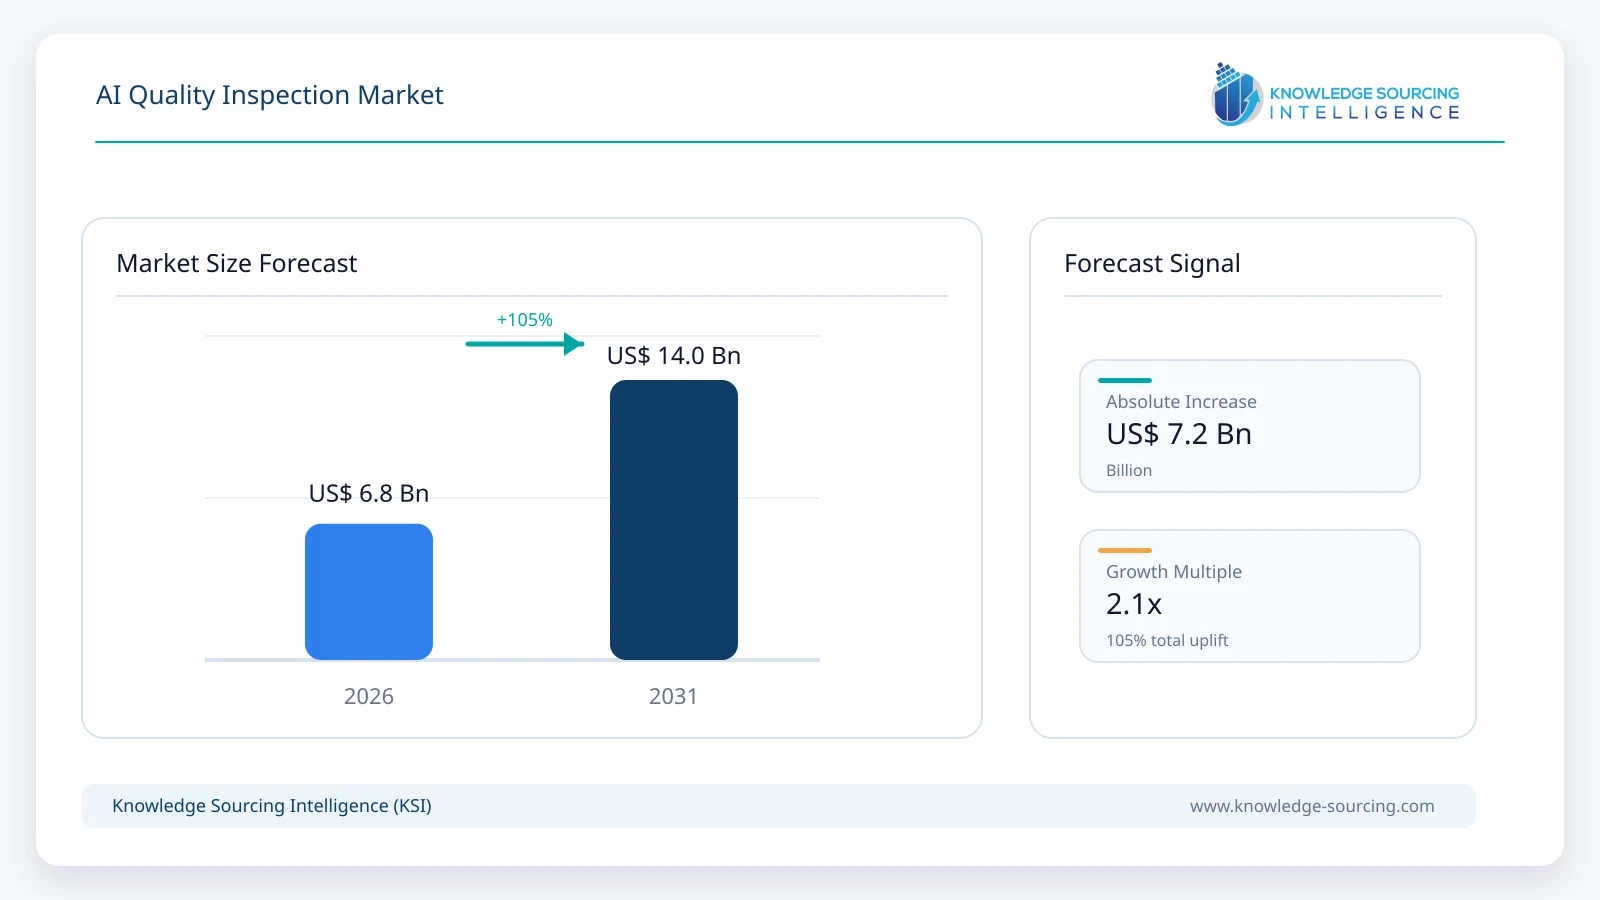
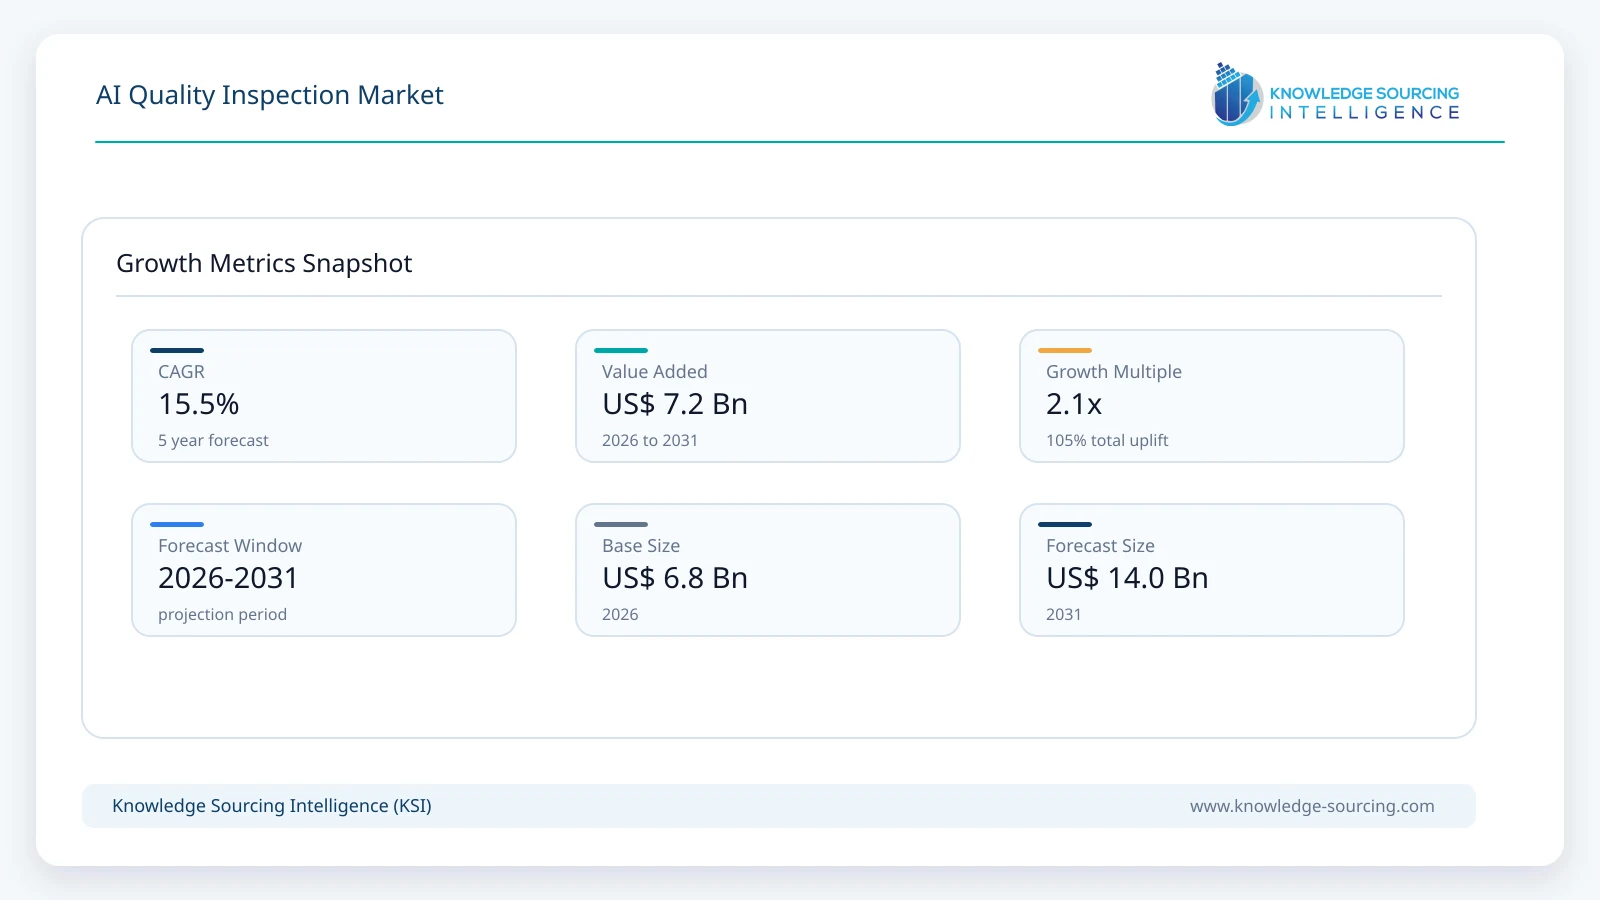
The AI quality inspection market is forecast to grow from USD 6.80 billion in 2026 to USD 13.97 billion by 2031, representing a CAGR of 15.5% during the forecast period.
Highlights:
- 1Software accounts for approximately 43% of AI quality inspection revenue globally in 2026.
- 2Defect and surface detection represents approximately 44% of application revenue in 2026.
- 3Electronics and semiconductors account for approximately 27% of market revenue in 2026.
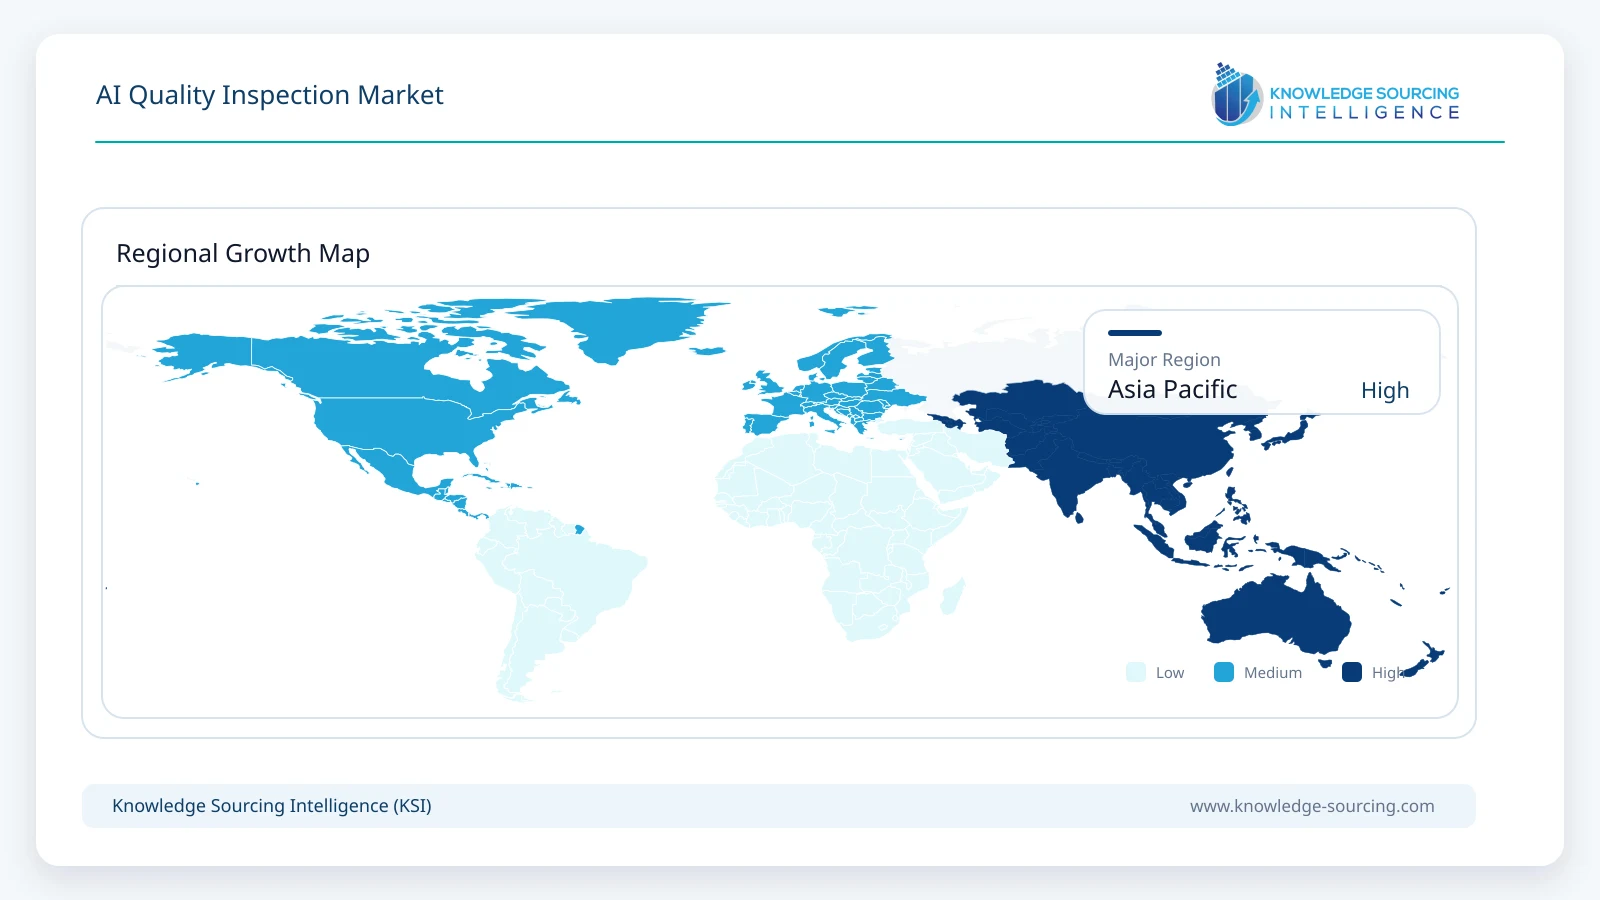
- 4Asia Pacific rises from 29% of market revenue in 2026 to 35% by 2031.
- 5About 57% of surveyed manufacturers already use AI within machine vision operations.
The AI quality inspection market is moving from isolated machine-vision projects toward integrated quality-control platforms deployed across production lines and multiple facilities. These systems combine industrial cameras, optics, lighting, computing hardware and AI software to detect surface defects, verify assembly, measure dimensions, inspect packaging and identify quality deviations that are difficult to capture consistently through manual inspection or traditional rules-based vision.
The market structure remains useful across components, applications and industries. Software is becoming a larger part of total market value as vendors shift differentiation toward model training, defect classification, image management, inference, analytics and centralized deployment. Hardware remains essential because cameras, optics, illumination and industrial processors determine the quality and speed of image acquisition, while integration and lifecycle services are required to adapt AI systems to individual production environments. Procurement is increasingly based on total inspection performance and integration capability rather than camera specifications alone.
Adoption has already moved beyond early experimentation. Cognex reported on March 23, 2026 that 57% of more than 500 surveyed manufacturers, integrators and OEMs were already using AI in machine vision operations, while another 30% planned near-term deployment. The same market is becoming easier to deploy as embedded processing improves and fewer training images are required for some inspection tasks. Cognex’s April 2026 In-Sight 6900, for example, introduced transformer-based classification designed to operate with as few as 10-20 training images for applicable tasks.
Major Market Drivers
Shift from Rules-Based Inspection to AI for Variable Defects
Traditional machine vision performs well when manufacturers can define stable visual rules around dimensions, edges, contrast or geometry. It becomes less effective when defects vary significantly between products, surfaces, batches or lighting conditions. Deep learning and AI-based inspection systems address this gap by learning acceptable and defective visual patterns rather than depending exclusively on manually programmed thresholds.
This capability is particularly important in electronics, semiconductors, automotive components, textiles and complex surface inspection. Manufacturers increasingly combine conventional vision with AI instead of replacing established inspection logic completely. Siemens’ Visual Inspection Cockpit, for example, combines AI-driven semantic segmentation with classical vision logic, while Cognex’s latest platforms provide rule-based, edge-AI and advanced-AI tools within the same environment. This hybrid architecture allows manufacturers to retain deterministic inspection where appropriate while applying AI to defects that are difficult to specify using fixed rules.
Edge AI Is Removing Latency and Deployment Barriers
Production inspection frequently requires decisions within milliseconds, making continuous cloud inference impractical for high-speed manufacturing lines. Edge AI allows models to run directly on industrial vision systems or local computing hardware, reducing latency, protecting production data and maintaining inspection even when network connectivity is unavailable.
Hardware improvement is rapidly expanding what can be executed locally. Cognex launched its In-Sight 6900 Vision Controller on April 28, 2026 with NVIDIA Jetson processing delivering up to 157 TOPS of AI performance, while its In-Sight 3900 introduced embedded AI inspection capable of operating at full production speed without an external PC. Siemens is similarly expanding Industrial Edge as an execution environment for AI models and visual inspection. Edge deployment therefore increases the addressable market for AI inspection across high-throughput production environments where cloud-dependent systems would create operational risk.
Semiconductor and Electronics Manufacturing Investment
Electronics and semiconductor manufacturing is becoming one of the most important demand pools because inspection requirements intensify as components become smaller, manufacturing tolerances tighten and production processes become more complex. Semiconductor manufacturing uses automated inspection throughout wafer processing, assembly, test and packaging, while electronics manufacturing relies heavily on automated optical inspection for solder joints, components and printed circuit boards.
The investment environment remains supportive. On July 14, 2026, SEMI forecast total semiconductor manufacturing equipment sales of USD 165.9 billion in 2026, up 23.2% year over year, while semiconductor test equipment sales were projected to increase 31.0% to USD 15.3 billion. Continued expansion of advanced logic, memory, packaging and testing capacity increases the installed base of production equipment requiring high-accuracy automated inspection.
Major Market Restraints
Training Data, Model Maintenance and Production Variability
AI inspection models need sufficiently representative production images covering acceptable products, known defect classes and normal process variation. This requirement becomes difficult when defects are rare, new products are introduced frequently or environmental conditions change between facilities.
A model trained on one production line can lose accuracy when transferred to another line with different cameras, lighting, tooling or product variation. Manufacturers therefore need processes for image collection, labeling, model validation, retraining and version control throughout the system lifecycle. Cloud-to-edge platforms such as Cognex OneVision are emerging specifically to address this problem by centralizing model development while maintaining local inference, but this introduces additional software governance requirements.
Legacy Integration and Initial Implementation Cost
AI inspection rarely operates independently from production equipment. Systems need to communicate with programmable logic controllers, robots, manufacturing execution systems, quality-management platforms and production databases while meeting line-speed requirements. Retrofitting older factories can therefore require cameras, lighting, computing hardware, software integration and engineering work in addition to the AI model itself.
These costs can be justified quickly in high-value manufacturing where a missed defect causes substantial scrap, warranty or recall exposure. The economics are less straightforward for smaller manufacturers or lower-value production, particularly when several lines require separate engineering. Vendors are responding with embedded AI, no-code configuration and standardized edge deployment, but implementation complexity remains a material barrier to broader adoption.
AI Quality Inspection Market Trends
AI Vision Is Moving from Individual Lines to Enterprise Deployment
Manufacturers increasingly want inspection models that can be developed centrally and deployed consistently across facilities. Cognex made OneVision generally available on May 13, 2026, reporting that more than 100 customers had used the platform since its beta launch and that some users were progressing from individual lines to multi-site deployments. The platform separates centralized AI lifecycle management from real-time local inference.
This transition changes the economics of machine vision. Inspection applications that previously required separate engineering projects at each plant can increasingly share datasets, models and updates, improving standardization across multinational production networks.
Few-Shot Training Is Reducing Data Requirements
Training-image requirements have historically constrained industrial AI because manufacturers may have thousands of examples of normal production but relatively few defective parts. Newer classification and anomaly-detection tools increasingly work with smaller datasets.
Cognex’s In-Sight 6900 includes few-sample classification models designed for some applications using only 10-20 training images. LandingAI has also continued simplifying labeling workflows, including a March 31, 2026 update integrating Meta’s SAM 2 into LandingLens Smart Labeling to improve segmentation accuracy.
3D Inspection Is Expanding Beyond Conventional 2D Vision
Two-dimensional imaging remains the largest inspection modality, but 3D vision is gaining importance where height, depth, volume, shape or surface topology cannot be assessed reliably from conventional images. Applications include electronics assemblies, automotive components, welds, precision machining and robotic inspection.
3D inspection becomes particularly valuable when geometric variation and surface defects must be evaluated together. Continued improvements in stereo imaging, structured light, laser profiling and AI-based 3D analysis support stronger growth for this segment through 2031.
Synthetic Data and Simulation Are Entering Inspection Development
Manufacturers often lack enough real defective products to train and validate AI inspection systems. Simulation and synthetic images can expand available datasets before a line reaches full production.
Basler introduced Vision Simulation in June 2026 to improve machine-vision system planning, while OMRON announced on July 16, 2026 that it was integrating its VT-X board inspection technology with NVIDIA Omniverse and Metropolis for physically accurate visualization of board warpage and AI-driven diagnosis. These developments indicate growing convergence between digital twins, simulation and production inspection.
AI Quality Inspection Market by Inspection Modality
2D AI vision accounts for approximately 60% of market value in 2026, making it the largest inspection modality. Conventional industrial cameras can be combined with deep-learning classification, object detection, segmentation and anomaly-detection models without requiring more complex depth-sensing hardware.
The technology is widely used for scratches, contamination, component presence, assembly errors, printing defects, packaging inspection and other visual quality problems. Its market share is expected to decline modestly through 2031 as 3D and multisensor systems expand faster, but 2D remains the core inspection architecture because of its lower hardware cost and broad application coverage.
AI Quality Inspection Market Segmentation Analysis
By Component
Software
Software accounts for approximately 43% of market value in 2026 and is projected to increase to roughly 46% by 2031. The segment includes AI model-development platforms, inference software, image-management systems, defect-classification tools, analytics, model governance and integrations with manufacturing software.
Software gains share because competitive advantage increasingly depends on how quickly manufacturers can train models, adapt inspection to new products, deploy changes across plants and extract process intelligence from inspection data. Centralized AI lifecycle management also creates recurring software and subscription revenue beyond the initial inspection-hardware installation.
By Application
Defect and Surface Detection
Defect and surface detection represents approximately 44% of market revenue in 2026, making it the largest application group. AI is particularly effective where defects vary in size, shape, position or appearance, making fixed rules difficult to maintain.
Applications include scratches, dents, cracks, contamination, coating defects, textile irregularities, semiconductor defects and cosmetic imperfections. The segment is projected to retain the largest share through 2031 as AI expands the range of visual deviations that can be inspected automatically.
By Industry
Electronics and Semiconductors
Electronics and semiconductors account for approximately 27% of AI quality inspection revenue in 2026 and are projected to approach 30% by 2031. Inspection intensity is high because microscopic defects can materially affect yield and product reliability, while production volumes justify automated inspection at multiple stages.
SEMI’s July 2026 equipment forecast illustrates the scale of investment supporting this demand. Total semiconductor equipment sales are expected to reach USD 165.9 billion in 2026, while continued expansion of advanced logic, memory, test and packaging creates additional inspection points throughout semiconductor production.
AI Quality Inspection Market by Geography
Asia Pacific
Asia Pacific represents approximately 29% of global market value in 2026 and is projected to reach around 35% by 2031, making it the fastest-growing major region. China, Japan, South Korea and Taiwan have extensive electronics and semiconductor manufacturing bases, while India and Southeast Asia continue attracting industrial investment.
The regional outlook is strengthened by semiconductor and electronics capacity expansion. SEMI’s Q2 2026 World Fab Forecast tracks more than 1,600 semiconductor facilities and production lines globally and identifies China as the largest equipment-spending market in 2026. High production density across Asian electronics, automotive and precision-manufacturing clusters creates strong economics for automated inspection systems.
Competitive Landscape
The AI quality inspection market includes established machine-vision companies, industrial automation suppliers, AI software developers and precision-measurement companies. Cognex and Keyence maintain strong positions in integrated industrial vision, while Siemens and OMRON combine inspection with broader factory automation and edge-computing portfolios. MVTec supplies machine-vision software platforms, LandingAI focuses on enterprise visual AI, and companies such as Basler, Teledyne and Pleora provide imaging, connectivity and processing technologies used within inspection architectures.
Competition is shifting toward easier AI deployment, centralized model management, embedded processing and interoperability with existing industrial systems. Vendors are increasingly expected to support hybrid environments where conventional vision, AI inference and industrial automation work together rather than selling isolated AI applications.
The ability to scale inspection across factories is becoming an important competitive differentiator. Product architecture increasingly combines local edge inference with centralized model training and governance, allowing manufacturers to standardize quality inspection without sacrificing production-line response times.
Recent Developments
July 2026: OMRON announced integration of its VT-X board inspection technology with NVIDIA Omniverse and Metropolis to support physically accurate visualization and AI-driven diagnostic inspection.
May 2026: MVTec released HALCON 26.05 with improvements across classical and deep-learning machine-vision workflows, including next-generation AI object detection.
May 2026: Cognex announced general availability of OneVision, its cloud-to-edge AI vision development and deployment environment.
May 2026: Cognex launched the In-Sight 3900 embedded AI vision system with processing up to four times faster than its previous-generation systems.
April 2026: Cognex launched the NVIDIA Jetson-powered In-Sight 6900 Vision Controller with up to 157 TOPS of AI performance.
April 2026: Siemens announced general availability of its Industrial AI Suite and new Industrial Edge partner solutions for machine vision and quality inspection.
Market Outlook
The AI quality inspection market is expected to more than double between 2026 and 2031 as automated manufacturing systems increasingly require inspection intelligence that can match production speed and product complexity. Adoption is moving beyond experimental AI models toward production platforms that combine industrial imaging, embedded inference, cloud-based model management and manufacturing-system integration.
Software, electronics and semiconductor applications, 3D inspection and Asia Pacific are expected to gain market share during the forecast period. Hardware remains essential, but value increasingly shifts toward AI model development, analytics, centralized deployment and lifecycle management.
The strongest suppliers will be those capable of combining inspection accuracy with practical industrial deployment. Manufacturers increasingly require systems that can be installed without large AI teams, integrated with existing automation infrastructure and updated consistently across plants.
AI Quality Inspection Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 6.80 billion |
| Total Market Size in 2031 | USD 13.97 billion |
| Forecast Unit | Billion |
| Growth Rate | 15.5% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Inspection Modality, Component, Application, Industry, Geography |
| Companies |
|
Market Segmentation
By Inspection Modality
2D AI Vision
3D AI Vision
X-Ray, Thermal and Multispectral AI Inspection
Other Sensor-Fusion Inspection
By Component
Hardware
Software
Services
By Application
Defect and Surface Detection
Dimensional Measurement
Assembly Verification
Packaging and Label Inspection
Others
By Industry
Automotive
Electronics and Semiconductors
General Manufacturing
Healthcare and Pharmaceuticals
Food and Beverage
Aerospace and Defense
Textiles and Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
United Kingdom
France
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
Others
Asia Pacific
China
Japan
South Korea
Taiwan
India
Singapore
Australia
Others
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Key Findings
1.2. AI Quality Inspection Market Size, 2026-2031
1.3. Inspection Modality Outlook
1.4. Component Outlook
1.5. Application Outlook
1.6. Industry Outlook
1.7. Regional Opportunity Summary
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
2.5. Historical and Forecast Period
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Shift from Rules-Based Vision to AI for Variable and Complex Defects
3.1.2. Edge AI Processing Reducing Inspection Latency and Cloud Dependence
3.1.3. Semiconductor, Electronics and Advanced Manufacturing Capacity Expansion
3.1.4. Enterprise Standardization of AI Inspection Across Multiple Production Sites
3.2. Market Restraints
3.2.1. Training Data Availability, Model Drift and Continuous Retraining Requirements
3.2.2. Legacy Automation Integration and High Initial Implementation Cost
3.2.3. False Positives, Validation Requirements and Explainability in Regulated Manufacturing
3.2.4. Industrial Cybersecurity and Production Data Governance Requirements
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Computer Vision
4.2. Deep Learning and Machine Learning
4.3. Edge AI Inference
4.4. 3D Machine Vision
4.5. Anomaly Detection
4.6. Few-Shot and Low-Data Model Training
4.7. Synthetic Data and Digital-Twin-Based Inspection Development
4.8. Explainable AI for Industrial Quality Control
4.9. Cloud-to-Edge Model Lifecycle Management
5. AI QUALITY INSPECTION MARKET BY INSPECTION MODALITY
5.1. Introduction
5.2. 2D AI Vision
5.3. 3D AI Vision
5.4. X-Ray, Thermal and Multispectral AI Inspection
5.5. Other Sensor-Fusion Inspection
6. AI QUALITY INSPECTION MARKET BY COMPONENT
6.1. Introduction
6.2. Hardware
6.3. Software
6.4. Services
7. AI QUALITY INSPECTION MARKET BY APPLICATION
7.1. Introduction
7.2. Defect and Surface Detection
7.3. Dimensional Measurement
7.4. Assembly Verification
7.5. Packaging and Label Inspection
7.6. Others
8. AI QUALITY INSPECTION MARKET BY INDUSTRY
8.1. Introduction
8.2. Automotive
8.3. Electronics and Semiconductors
8.4. General Manufacturing
8.5. Healthcare and Pharmaceuticals
8.6. Food and Beverage
8.7. Aerospace and Defense
8.8. Textiles and Others
9. AI QUALITY INSPECTION MARKET BY GEOGRAPHY
9.1. North America
9.1.1. United States
9.1.2. Canada
9.1.3. Mexico
9.2. South America
9.2.1. Brazil
9.2.2. Argentina
9.2.3. Others
9.3. Europe
9.3.1. Germany
9.3.2. United Kingdom
9.3.3. France
9.3.4. Italy
9.3.5. Spain
9.3.6. Others
9.4. Middle East and Africa
9.4.1. Saudi Arabia
9.4.2. UAE
9.4.3. Israel
9.4.4. Others
9.5. Asia Pacific
9.5.1. China
9.5.2. Japan
9.5.3. South Korea
9.5.4. Taiwan
9.5.5. India
9.5.6. Singapore
9.5.7. Australia
9.5.8. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Cognex Corporation
11.2. Keyence Corporation
11.3. Siemens AG
11.4. OMRON Corporation
11.5. Teledyne Technologies Incorporated
11.6. Basler AG
11.7. MVTec Software GmbH
11.8. LandingAI
11.9. Pleora Technologies Inc.
11.10. NEC Corporation
11.11. ABB Ltd.
11.12. Mitutoyo Corporation
12. APPENDIX
Navigate
Trusted by the world's leading organizations











