
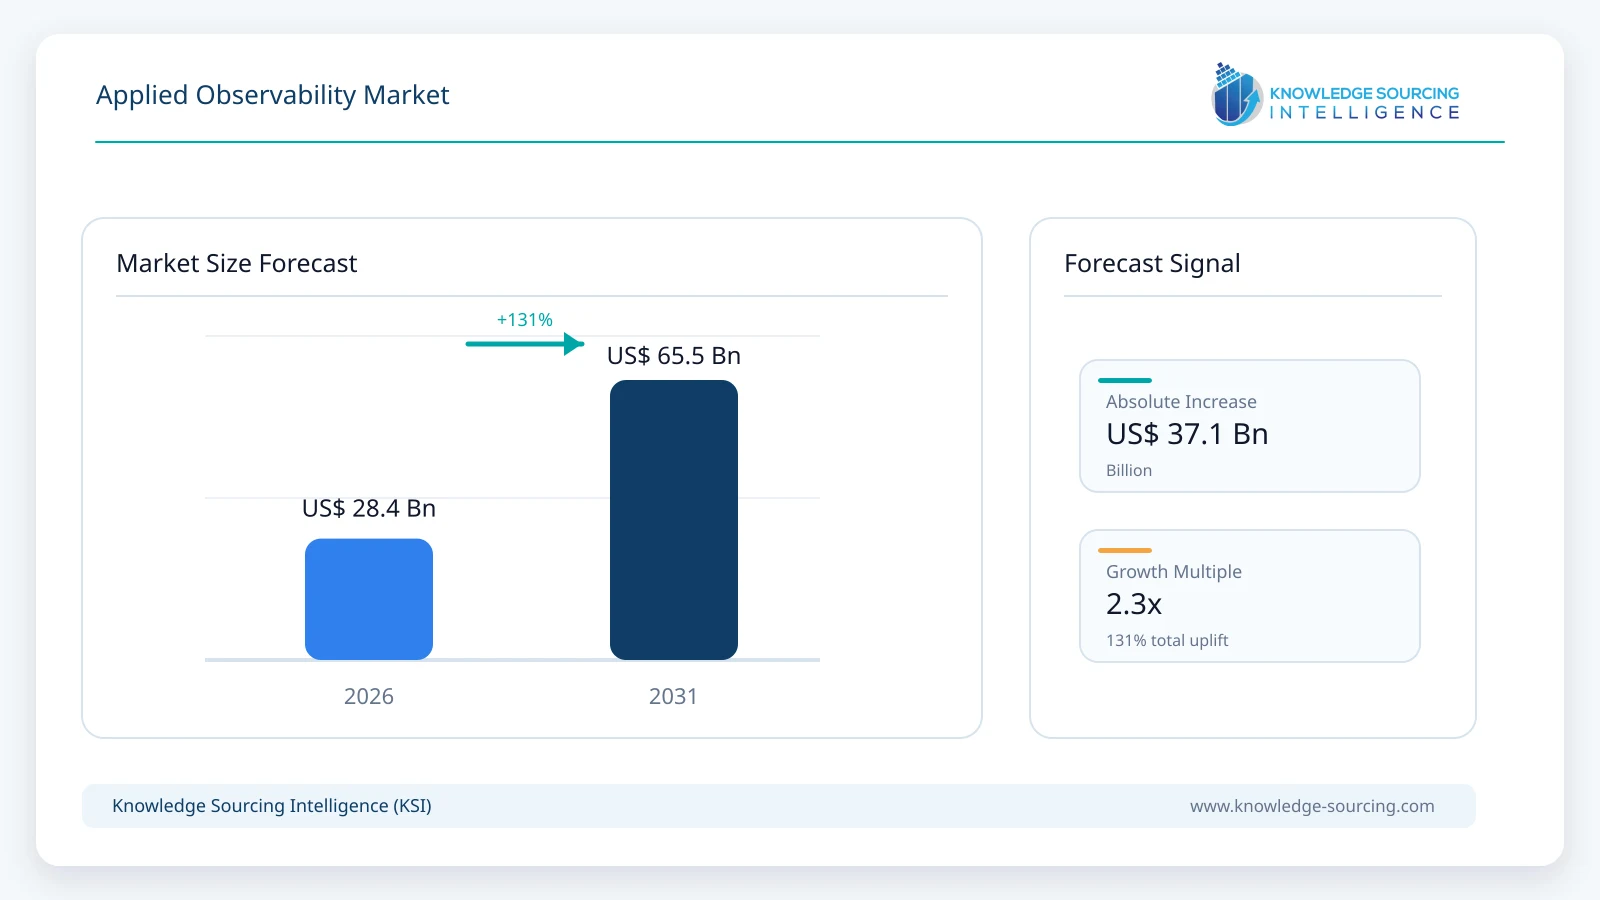
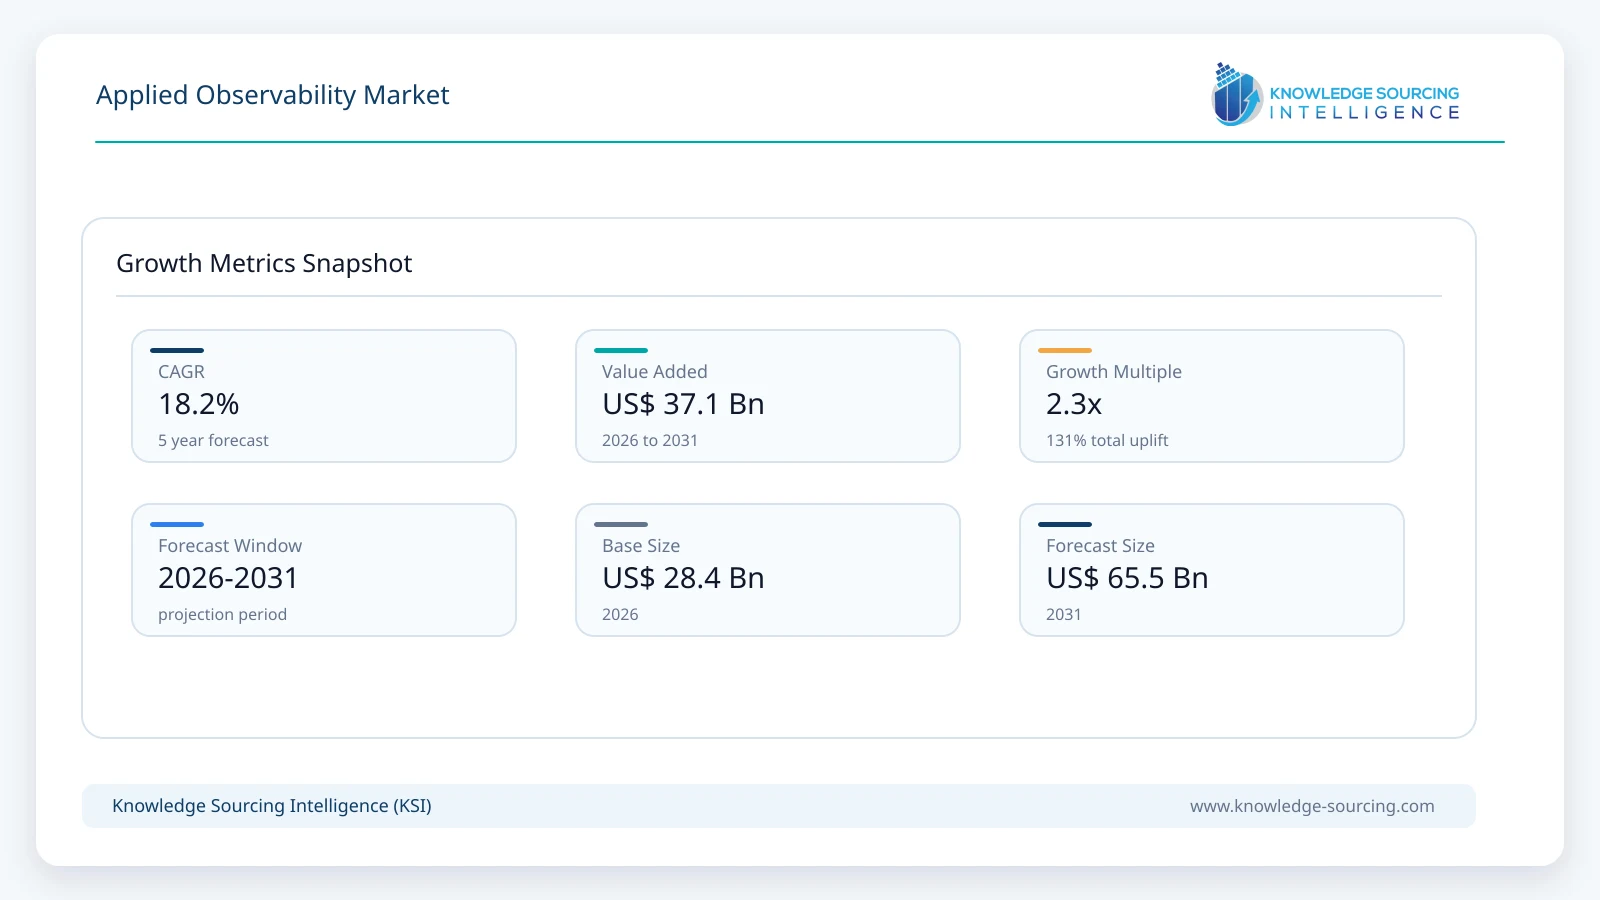
The applied observability market is forecast to grow at a CAGR of 18.2%, reaching USD 65.5 billion in 2031 from USD 28.4 billion in 2026.
Highlights:
- 1Observability platforms and software account for approximately 74% of market value in 2026, with services accounting for the remaining implementation, optimization and managed-service demand.
- 2Cloud/SaaS deployment accounts for approximately 72% of market value in 2026, supported by consumption-based observability platforms and cloud-native applications.
- 3Application and service observability represents approximately 32% of market demand in 2026, remaining the largest functional domain.
- 4IT and telecommunications account for approximately 30% of end-user demand in 2026, reflecting high software complexity and continuous digital-service requirements.
- 5North America accounts for approximately 45% of global market value in 2026, supported by the concentration of cloud software, digital businesses and major observability vendors.
Applied observability refers to the use of telemetry, analytics and operational context to understand how applications, infrastructure, networks, cloud services and increasingly AI systems behave in production. The market includes observability platforms, application performance monitoring, infrastructure and cloud monitoring, log and telemetry management, distributed tracing, digital experience monitoring, network observability, AI/LLM observability and related implementation and optimization services. General cybersecurity, broad cloud infrastructure spending and generic IT consulting are excluded unless the expenditure is directly attributable to observability.
The market is considerably smaller than the previous KSI estimate suggested. The largest dedicated vendors provide a useful scale check. Datadog generated USD 3.43 billion in 2025 revenue, up 28%, while Dynatrace generated USD 2.02 billion in FY2026, up 19%. Grafana Labs surpassed USD 600 million in annual recurring revenue in August 2026, while LogicMonitor exceeded USD 400 million ARR. Elastic generated USD 1.74 billion in FY2026 across Search & AI, Observability and Security, so only the attributable observability portion belongs inside this market. These disclosures do not support a 2026 market above USD 140 billion.
The technology base is nevertheless expanding rapidly. OpenTelemetry achieved CNCF graduated-project status in May 2026. CNCF reported that the project had attracted more than 12,000 contributors from over 2,800 companies, reflecting the move toward vendor-neutral collection of metrics, logs and traces. This is changing observability economics by separating telemetry generation and collection from the analytical backend, making it easier for enterprises to consolidate, replace or combine observability vendors.
Market Trends
• AI Observability Is Becoming a New Product Layer
Enterprise AI creates new observability requirements around model latency, token consumption, prompt and response traces, agent execution, retrieval quality, hallucination, cost and business outcomes. Traditional infrastructure monitoring does not provide enough context to understand why an AI application produced a particular result.
Dynatrace announced plans in August 2026 to acquire Arize, bringing AI evaluation and observability into its broader enterprise platform. Cisco’s September 2026 Splunk announcements similarly introduced Agent Observability capabilities that monitor AI-agent activity and track token economics. The category is therefore expanding from observing servers and applications toward observing probabilistic AI systems and autonomous agents.
• OpenTelemetry Is Reducing Instrumentation Lock-In
Historically, observability vendors used proprietary agents and instrumentation libraries, making platform changes expensive. OpenTelemetry provides a common framework for collecting and exporting metrics, traces and logs and has become the principal open standard for cloud-native observability.
Its graduation within CNCF in 2026 indicates that the framework has moved beyond experimental adoption. OpenTelemetry also began expanding profiling support in 2026, extending standardized telemetry beyond the traditional metrics-logs-traces model. Vendors increasingly compete on storage economics, analytics, correlation, AI and remediation rather than ownership of the instrumentation layer.
• Observability Is Moving From Detection Toward Automated Action
The competitive focus is shifting from displaying telemetry to deciding what matters and automating the response. LogicMonitor reported in May 2026 that its Edwin AI platform was already contributing one-third of company bookings and that associated recurring revenue was growing approximately 200% year over year. Its platform is increasingly linking anomaly detection, topology and telemetry with automated remediation.
Dynatrace is pursuing a similar direction through domain-specific agents and autonomous operations, while Splunk is extending AI across security and observability workflows. Applied observability therefore increasingly overlaps with AIOps, but the scope remains anchored to systems where operational decisions are driven by telemetry and system context rather than generic enterprise automation.
• Telemetry Economics Are Becoming a Buying Criterion
Observability platforms can become expensive as log, metric and trace volumes increase. AI workloads intensify this problem because they generate additional application, model and agent telemetry. Customers are therefore paying greater attention to sampling, telemetry pipelines, tiered storage and cost control.
Dynatrace agreed in April 2026 to acquire Bindplane to strengthen telemetry-pipeline capabilities. Elastic continues emphasizing unified storage and search across logs, metrics and traces, while Grafana’s open stack allows organizations to combine different telemetry backends. Observability architecture is increasingly being evaluated not only by detection quality but by cost per ingested and retained unit of telemetry.
Market Drivers
• Cloud-Native and Distributed Architectures Generate More Operational Complexity
Modern applications are increasingly built around containers, microservices, APIs, serverless functions and multiple cloud environments. A single customer transaction can cross numerous application services and infrastructure layers, making conventional device-centric monitoring insufficient.
Dynatrace’s FY2026 subscription revenue increased 19% to USD 1.93 billion, while Datadog revenue increased 28% to USD 3.43 billion in 2025. These growth rates at two of the largest dedicated observability vendors provide direct evidence that organizations continue allocating more spending toward unified visibility across complex digital environments.
• OpenTelemetry Is Expanding the Addressable Platform Ecosystem
OpenTelemetry reduces the cost of instrumenting distributed applications and creates a standardized flow of telemetry into commercial observability platforms. CNCF’s decision to graduate the project in May 2026 followed broad production adoption and participation from thousands of organizations and contributors.
Standardized telemetry does not remove the need for commercial observability. Instead, it moves competition toward data storage, analytics, AI, correlation and workflow automation. This can expand adoption among organizations that previously avoided deeper observability because of vendor lock-in or instrumentation complexity.
• AI Workloads Create New Reliability and Governance Requirements
Generative AI and autonomous agents introduce failure modes that conventional application monitoring cannot fully explain. Organizations need visibility into prompts, model calls, retrieval steps, tool invocation, token use and downstream business outcomes.
The strategic value is visible in vendor investment. Dynatrace’s planned Arize acquisition extends observability into AI evaluation, while Splunk is introducing agent-specific observability and cost monitoring. Grafana, Elastic, Datadog and New Relic are also building AI-focused capabilities within their platforms. AI therefore creates both additional telemetry and an entirely new class of systems requiring observation.
Market Restraints
• Telemetry Growth Can Produce High and Unpredictable Costs
Observability platforms often charge according to hosts, usage, data volume, retention or combinations of these variables. As organizations collect more logs and traces, observability expenditure can increase faster than the underlying infrastructure footprint.
This encourages sampling, telemetry routing and storage-tier optimization and also increases demand for open-source alternatives. The result is a market in which telemetry volume supports revenue growth but simultaneously creates pressure on per-unit pricing.
• Platform Consolidation Creates Competitive Pressure
Organizations often operate separate tools for application performance, logs, infrastructure, networks and digital experience. LogicMonitor’s 2026 survey of observability decision-makers found 84% were pursuing or considering tool consolidation, while 67% indicated they were likely to switch observability platforms within one to two years.
Consolidation increases the opportunity for broad platforms but makes it harder for smaller single-function products to defend spending. It also means growth in unified observability platforms can partly reflect replacement of existing monitoring tools rather than entirely incremental expenditure.
Segment Analysis
• By Component: Platforms and Solutions
Observability platforms and software account for approximately 74% of global market value in 2026 and form the largest component. The segment includes application and infrastructure observability, log management, distributed tracing, digital experience monitoring, network visibility, telemetry management and AI-assisted operational analytics.
Dedicated vendors demonstrate the scale of recurring software revenue. Datadog generated USD 3.43 billion in 2025, Dynatrace ended March 2026 with USD 2.05 billion ARR, Grafana surpassed USD 600 million ARR and LogicMonitor surpassed USD 400 million ARR. Services represent a smaller but still substantial market because enterprises require architecture design, telemetry migration, implementation, platform engineering and managed observability.
• By Deployment: Cloud/SaaS
Cloud/SaaS deployment accounts for approximately 72% of market value in 2026. Usage-based SaaS is particularly suited to observability because workloads, telemetry volume and infrastructure scale change continuously. Datadog operates primarily as a SaaS platform, while Dynatrace reported increasing cloud-hosting expenses as use of its SaaS platform expanded. Elastic generated USD 837.3 million in Elastic Cloud revenue in FY2026, up 22% year over year.
Self-managed deployments remain important in government, financial services and other regulated environments. The segmentation is therefore better represented as Cloud/SaaS versus Self-Managed/On-Premises rather than the existing Public Cloud versus Private Cloud structure.
• By Observability Domain: Application and Service Observability
Application and service observability accounts for approximately 32% of market value in 2026 and remains the largest functional domain. Revenue includes application performance monitoring, distributed tracing, service-level analysis, transaction monitoring and increasingly AI-assisted root-cause analysis.
Infrastructure and cloud observability represent another major value pool, followed by log and telemetry management, digital experience and network observability. AI/LLM observability remains comparatively small in 2026 but is expected to record the fastest growth as enterprises move AI agents and generative-AI applications into production.
• By Industry: IT and Telecommunications
IT and telecommunications account for approximately 30% of global market value in 2026 because digital services require continuous visibility across applications, networks, APIs, databases, cloud infrastructure and customer experience. Software companies also tend to adopt newer observability practices earlier because system reliability directly affects the product being sold.
BFSI represents another large market because payment, trading and banking platforms have stringent availability requirements. Manufacturing, retail, healthcare and public-sector organizations are increasing observability spending as more customer and operational processes become software-dependent.
Regional Outlook
• North America
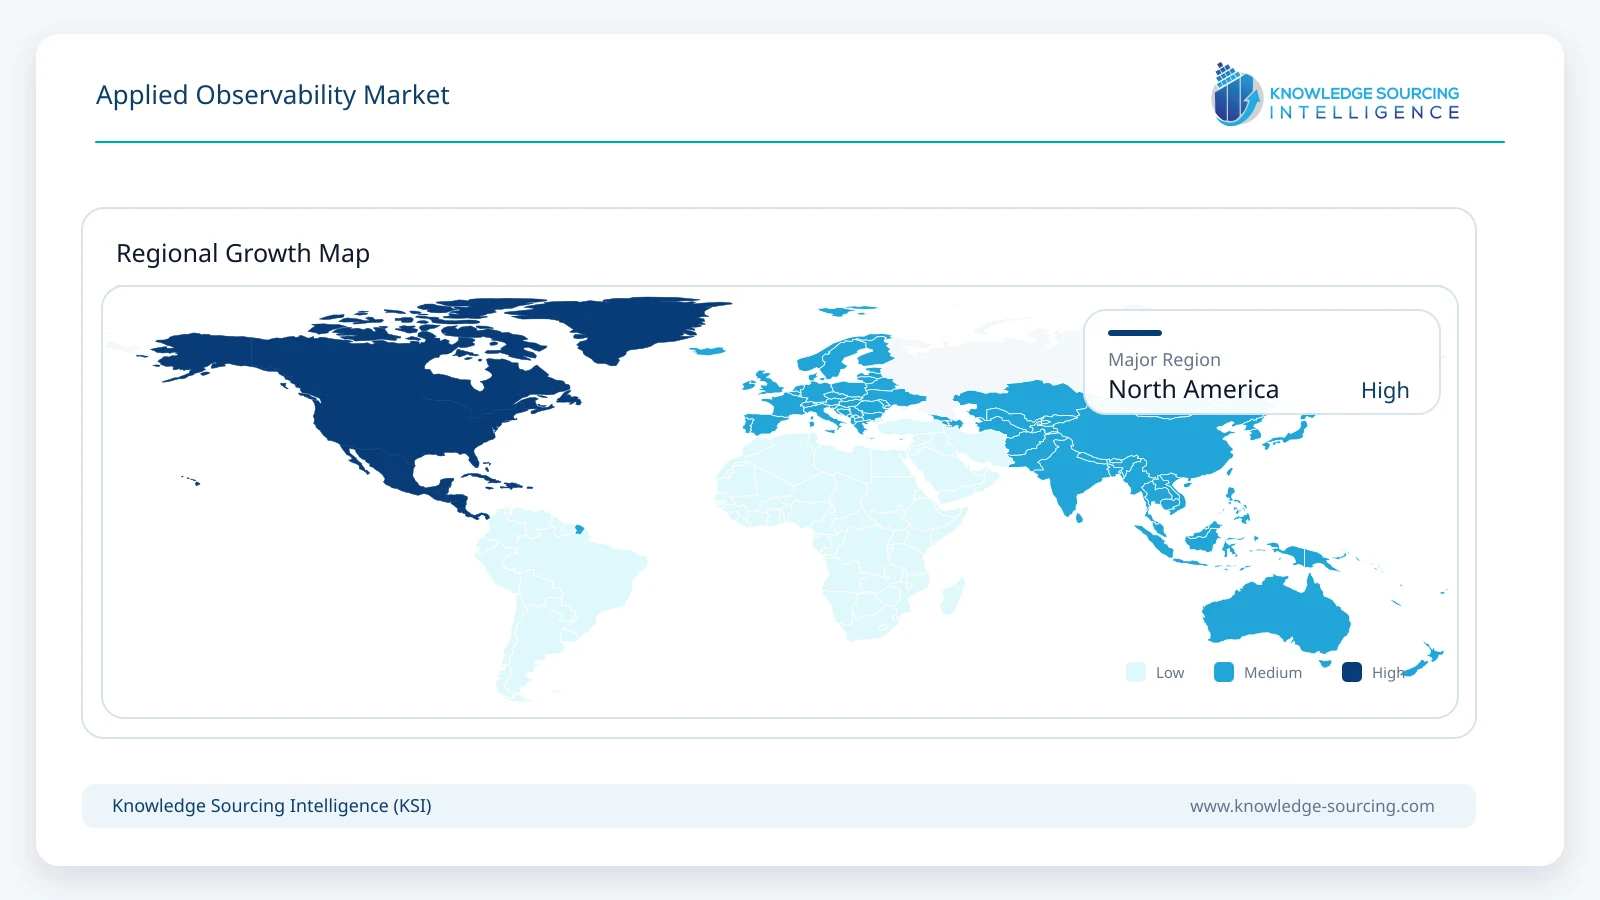
North America accounts for approximately 45% of global applied observability market value in 2026. The region combines a large base of cloud-native enterprises, software companies and financial institutions with the headquarters of major vendors including Datadog, Cisco/Splunk, New Relic, Grafana Labs, LogicMonitor and Honeycomb.
The region’s share is materially higher than its proportion of global IT users because observability expenditure per workload is higher among cloud-intensive and software-led organizations. Europe represents the second-largest regional market, supported by financial services, telecommunications and large enterprise digitalization. Asia Pacific is expected to grow faster through 2031 as cloud adoption, digital services and regional software infrastructure expand.
Competitive Landscape
The competitive environment is concentrated around several large observability platforms but remains fragmented at the specialist level.
Datadog is one of the largest dedicated observability vendors, generating USD 3.43 billion of revenue in 2025. Dynatrace generated USD 2.02 billion in FY2026 and continues expanding from application monitoring into logs, cloud operations and AI observability. Cisco/Splunk combines machine-data analytics, security and observability and is increasingly positioning the platform around AI-agent operations.
New Relic remains a major full-stack observability platform. Grafana Labs has grown rapidly through its open-observability ecosystem and surpassed USD 600 million ARR in August 2026 with more than 10,000 customers. Elastic provides Observability alongside Search & AI and Security and generated USD 1.74 billion of total company revenue in FY2026. LogicMonitor exceeded USD 400 million ARR in 2026 and is extending its platform toward autonomous IT operations.
IBM Instana, ScienceLogic, Honeycomb, SolarWinds and other specialist providers contribute additional competition. The existing KSI company set should therefore remove unrelated entities such as Ansell and research organizations such as Gartner from the vendor profile section.
Recent Developments
September 2026: Cisco introduced additional Splunk AI capabilities, including Agent Observability and Tokenomics for tracking agent performance and AI consumption.
August 2026: Grafana Labs announced that it had surpassed 10,000 customers and USD 600 million in ARR.
August 2026: Dynatrace announced plans to acquire Arize to combine AI evaluation with production observability across AI applications and agents.
May 2026: LogicMonitor reported that ARR had surpassed USD 400 million, while Edwin AI represented one-third of bookings.
May 2026: OpenTelemetry became a CNCF graduated project, reflecting broad production adoption of the vendor-neutral telemetry framework.
April 2026: Dynatrace announced an agreement to acquire Bindplane to strengthen telemetry-pipeline capabilities for cloud-native and AI observability.
Market Outlook
The applied observability market reflects the continued expansion of core observability platforms together with faster growth in AI observability, telemetry management, autonomous remediation and managed observability services.
Cloud/SaaS remains the dominant deployment model as organizations expand distributed applications and consumption-based technology stacks. Application and service observability remains the largest functional segment, but its relative share gradually declines as AI/LLM observability, telemetry pipelines and digital-experience monitoring expand more rapidly.
The market is also becoming more open at the instrumentation layer. OpenTelemetry reduces dependence on proprietary collection agents, pushing vendors to differentiate through analytics, data economics, AI, cross-domain correlation and automated action. This makes observability platforms increasingly important to enterprise operations while preventing instrumentation ownership alone from becoming a durable competitive advantage.
Applied Observability Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 28.4 billion |
| Total Market Size in 2031 | USD 65.5 billion |
| Forecast Unit | Billion |
| Growth Rate | 18.2% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Component, Deployment, Observability Domain, Industry Vertical, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Component
Platforms and Solutions
Services
By Deployment
Cloud / SaaS
Self-Managed / On-Premises
By Observability Domain
Application and Service Observability
Infrastructure and Cloud Observability
Log and Telemetry Management
Digital Experience and Network Observability
AI / LLM Observability
By Industry Vertical
IT and Telecommunications
BFSI
Retail and E-Commerce
Manufacturing
Healthcare
Government and Public Sector
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
United Kingdom
Germany
France
Spain
Italy
Others
Middle East and Africa
Saudi Arabia
UAE
Israel
Others
Asia Pacific
China
India
Japan
South Korea
Australia
Singapore
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition and Revenue Boundary
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Secondary Research
2.3. Primary Research
2.4. Vendor Revenue and ARR Analysis
2.5. Observability Revenue Attribution
2.6. Segment Modelling
2.7. Data Triangulation and Validation
3. EXECUTIVE SUMMARY
3.1. Key Findings
3.2. Applied Observability Market Size, 2026-2031
3.3. Component Outlook
3.4. Deployment Outlook
3.5. Observability Domain Outlook
3.6. Industry Outlook
3.7. Regional Opportunity Summary
4. MARKET DYNAMICS
4.1. Market Drivers
4.1.1. Cloud-Native and Distributed Application Complexity
4.1.2. OpenTelemetry and Vendor-Neutral Instrumentation
4.1.3. AI Workloads and Agent Observability
4.2. Market Restraints
4.2.1. Telemetry Cost and Data-Volume Growth
4.2.2. Platform Consolidation and Pricing Pressure
4.3. Market Opportunities
4.4. Porter’s Five Forces Analysis
4.5. Industry Value Chain Analysis
4.6. Observability Pricing and Telemetry Economics
4.7. Regulatory, Data Residency and Governance Considerations
5. TECHNOLOGY OUTLOOK
5.1. OpenTelemetry and OTLP
5.2. AIOps and Automated Root-Cause Analysis
5.3. AI and LLM Observability
5.4. Telemetry Pipelines
5.5. eBPF and Continuous Profiling
5.6. Autonomous Remediation and Agentic Operations
6. APPLIED OBSERVABILITY MARKET BY COMPONENT
6.1. Introduction
6.2. Platforms and Solutions
6.3. Services
7. APPLIED OBSERVABILITY MARKET BY DEPLOYMENT
7.1. Introduction
7.2. Cloud / SaaS
7.3. Self-Managed / On-Premises
8. APPLIED OBSERVABILITY MARKET BY OBSERVABILITY DOMAIN
8.1. Introduction
8.2. Application and Service Observability
8.3. Infrastructure and Cloud Observability
8.4. Log and Telemetry Management
8.5. Digital Experience and Network Observability
8.6. AI / LLM Observability
9. APPLIED OBSERVABILITY MARKET BY INDUSTRY VERTICAL
9.1. IT and Telecommunications
9.2. BFSI
9.3. Retail and E-Commerce
9.4. Manufacturing
9.5. Healthcare
9.6. Government and Public Sector
9.7. Others
10. APPLIED OBSERVABILITY MARKET BY GEOGRAPHY
10.1. North America
10.1.1. United States
10.1.2. Canada
10.1.3. Mexico
10.2. South America
10.2.1. Brazil
10.2.2. Argentina
10.2.3. Others
10.3. Europe
10.3.1. United Kingdom
10.3.2. Germany
10.3.3. France
10.3.4. Spain
10.3.5. Italy
10.3.6. Others
10.4. Middle East and Africa
10.4.1. Saudi Arabia
10.4.2. UAE
10.4.3. Israel
10.4.4. Others
10.5. Asia Pacific
10.5.1. China
10.5.2. India
10.5.3. Japan
10.5.4. South Korea
10.5.5. Australia
10.5.6. Singapore
10.5.7. Others
11. COMPETITIVE ENVIRONMENT AND ANALYSIS
11.1. Major Players and Strategy Analysis
11.2. Full-Stack Observability Platform Positioning
11.3. Open Observability and OpenTelemetry Positioning
11.4. AI / LLM Observability Capabilities
11.5. Telemetry Management and Data Economics
11.6. Cloud versus Self-Managed Deployment Capabilities
11.7. Mergers, Acquisitions and Partnerships
11.8. Competitive Dashboard
12. COMPANY PROFILES
12.1. Datadog, Inc.
12.2. Dynatrace, Inc.
12.3. Cisco Systems, Inc.
12.4. New Relic, Inc.
12.5. Grafana Labs
12.6. Elastic N.V.
12.7. LogicMonitor, Inc.
12.8. IBM
12.9. ScienceLogic, Inc.
12.10. Honeycomb.io
13. APPENDIX
13.1. Market Definition and Scope
13.2. Revenue Inclusion and Exclusion Criteria
13.3. Currency and Conversion Assumptions
13.4. Base Year and Forecast Period
13.5. Market Estimation Approach
13.6. Primary and Secondary Research Framework
13.7. Data Triangulation and Validation
13.8. Abbreviations





Frequently asked questions
What is the projected growth trajectory and market size for the Applied Observability market between 2026 and 2031?
The Applied Observability market is forecast to expand significantly, growing from USD 28.4 billion in 2026 to USD 65.5 billion by 2031. This represents a robust Compound Annual Growth Rate (CAGR) of 18.2% over the forecast period, reflecting substantial market expansion.
Which deployment models and product segments are leading the Applied Observability market in 2026?
In 2026, observability platforms and software account for approximately 74% of the market value, with services making up the remaining demand for implementation, optimization, and managed services. Cloud/SaaS deployment is dominant, capturing about 72% of the market value, driven by consumption-based observability platforms and cloud-native applications.
Which functional domains and end-user industries are the primary drivers of demand in the Applied Observability market?
Application and service observability represents the largest functional domain, accounting for approximately 32% of market demand in 2026. From an end-user perspective, the IT and telecommunications sector is the leading driver, consuming about 30% of the market demand due to its high software complexity and continuous digital-service requirements.
Which geographic region holds the largest share of the Applied Observability market in 2026, and why?
North America is the dominant region in the Applied Observability market, accounting for approximately 45% of the global market value in 2026. This leadership is supported by a significant concentration of cloud software, digital businesses, and major observability vendors within the region.
Who are some of the prominent dedicated vendors highlighted in the Applied Observability market report, and what is their scale?
The report highlights major dedicated vendors such as Datadog, which generated USD 3.43 billion in 2025 revenue, and Dynatrace, with USD 2.02 billion in FY2026. Other significant players include Grafana Labs, which surpassed USD 600 million in annual recurring revenue in August 2026, and LogicMonitor, exceeding USD 400 million ARR.
What emerging technologies and trends are influencing the evolution of the Applied Observability market?
The Applied Observability Market's technology base is rapidly expanding, notably with OpenTelemetry achieving CNCF graduated-project status in May 2026, attracting over 12,000 contributors. This reflects a significant move toward vendor-neutral collection of metrics, logs, and traces. The market is also increasingly focusing on understanding the behavior of AI/LLM systems in production.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Applied Observability Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/applied-observability-market