Argentina Road Transportation Vehicle Market - Strategic Insights and Forecasts (2026-2031)
Argentina Road Transportation Vehicle Market Size, Share, Forecasts and Trends Analysis By Vehicle Type (Oil Fuel Based (Gasoline Vehicle, Diesel Vehicle), Biofuel Based (Biodiesel Vehicle, Ethanol Vehicle, Other Biofuel Vehicle), Natural Gas Based, E Fuel Based, Hydrogen Based, Electric Vehicle (Battery Electric Vehicle, Plug-in Hybrid Electric Vehicle, Hybrid Electric Vehicle)), and Province
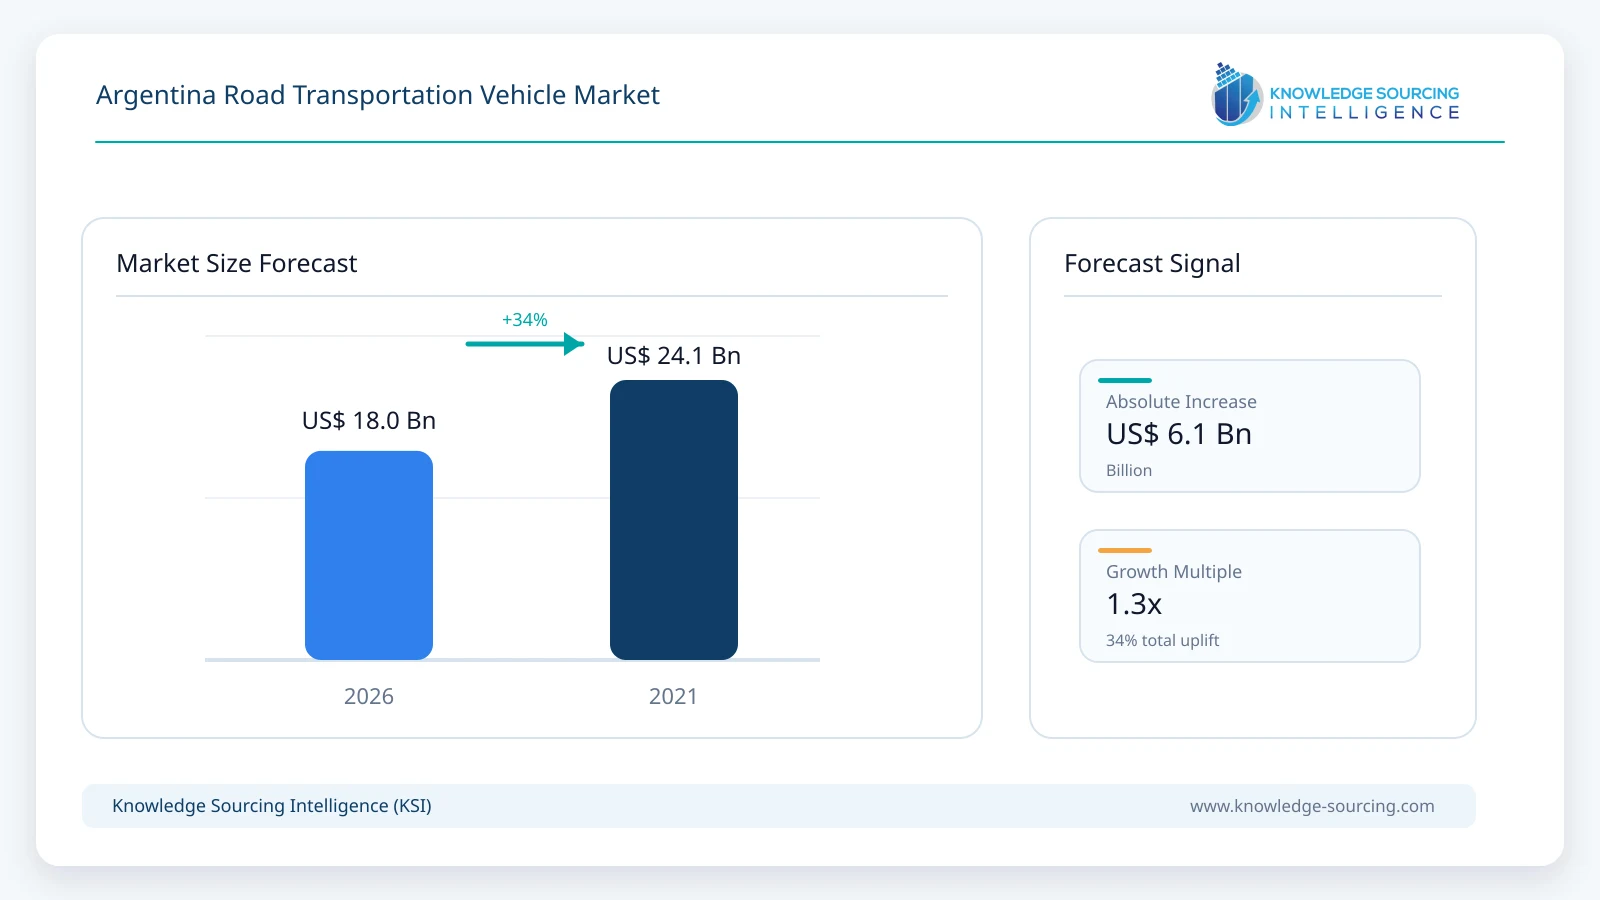
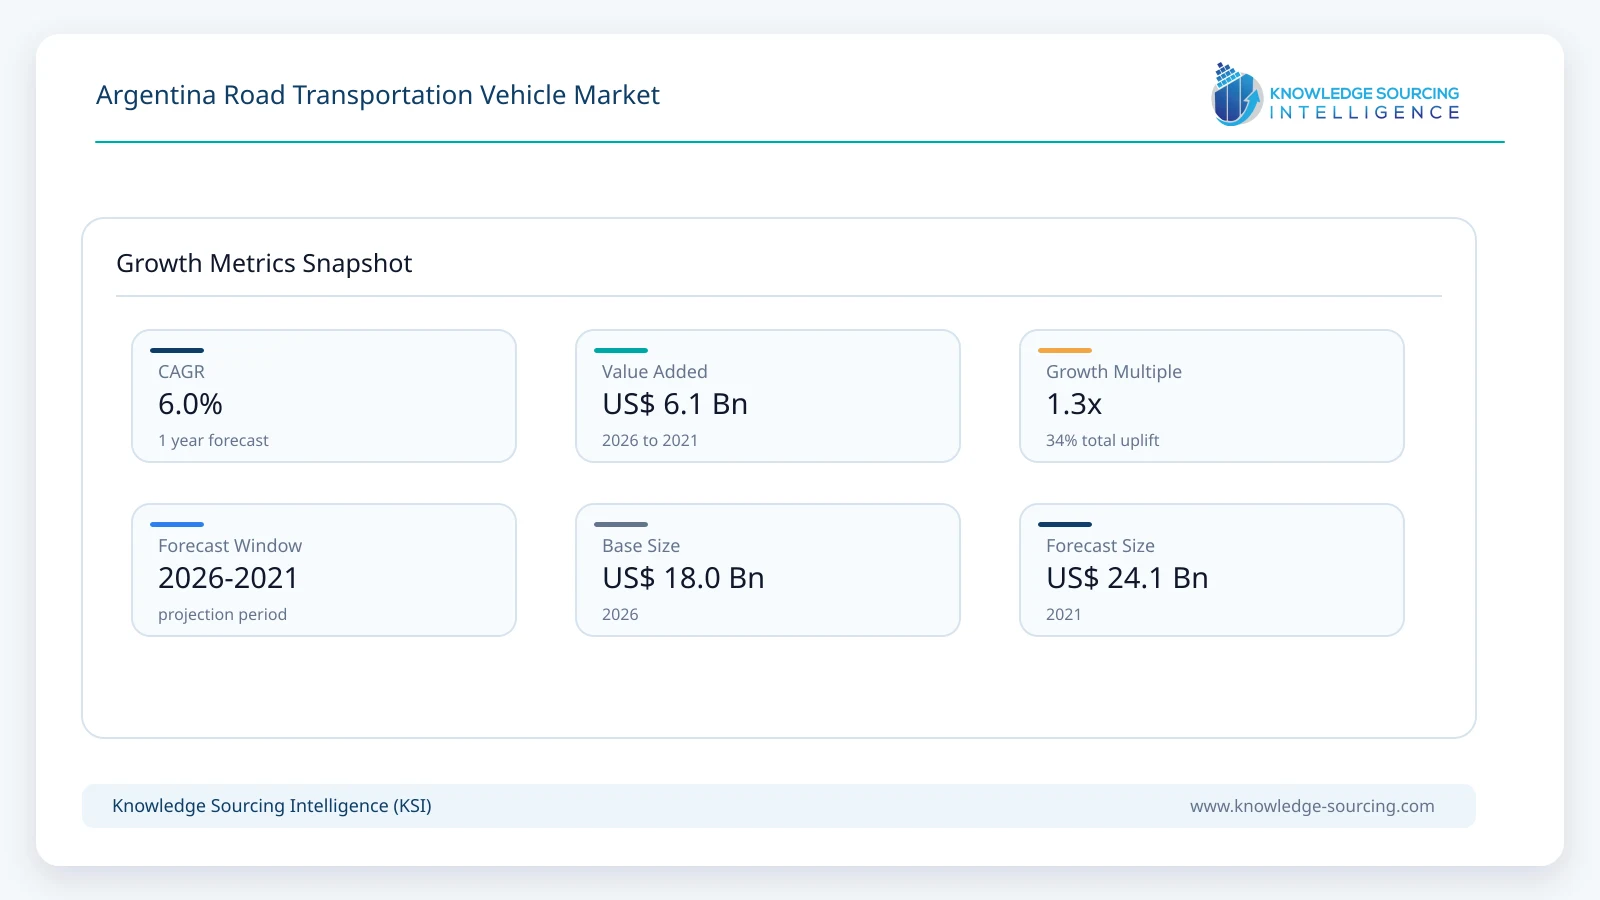
The Argentina Road Transportation Vehicle Market is projected to grow at a CAGR of 6.01%, reaching approximately USD 24.1 billion in 2031 from USD 18.0 billion in 2026.
Highlights:
1
Conventional petrol and diesel models dominate new-vehicle value across private and commercial users.
2
Pickup production underpins a substantial share of domestic automotive manufacturing and exports.
3
Hybrids and battery-electric models broaden passenger-car choice through dealership and import channels.
4
Light commercial vehicles remain sensitive to fleet utilization, service support and financing.
5
Córdoba is projected to outpace other named provinces as investment and fleet replacement recover.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Argentina's road transportation vehicle market covers new registered passenger cars, sport utility vehicles, pickups, vans, trucks and buses sold to domestic users. The revenue measure is the finished-vehicle transaction value attributable to Argentine first sales. It excludes motorcycles, used-vehicle transfers, parts sold separately, fleet operating expenditure and vehicles manufactured locally but exported rather than registered in Argentina. Distinguishing these transactions from factory output is material because pickup manufacturing is strongly export oriented.
ACARA recorded 435,493 registrations in the first nine months of 2026, while ADEFA reported 314,975 units manufactured and 203,072 units exported during the same period. The series measure different activities, but together indicate a market in which import availability, industrial capacity and local demand cannot be used interchangeably. Vehicle manufacturers compete through retail price, availability, model mix, financing, warranty support and the ability to supply work vehicles to commercial buyers.
Market Overview
Commercial pickups occupy a central position in Argentina's automotive manufacturing economy. Toyota's Zárate operation produces Hilux, SW4 and Hiace; Ford builds Ranger at Pacheco; Volkswagen manufactures Amarok; and Stellantis has extended its Córdoba operation from the Fiat Cronos into additional pickups. These operations support domestic model availability, supplier networks and export earnings, but production announcements alone do not establish near-term retail-market gains. In 2025, Toyota manufactured 180,352 vehicles in Argentina and exported 140,768, illustrating the substantial separation between local assembly and domestic purchases.
Household vehicle purchases face a different set of constraints from business fleet procurement. Entry and mid-range passenger cars compete principally on acquisition price, installment terms, fuel use and maintenance, whereas operators of vans, buses and heavy vehicles attach greater value to uptime, payload, service-network reach and resale support. The manufacturer price list for Fiat models in April 2026 spans compact passenger vehicles, Strada pickups, Toro and the larger Titano, reinforcing the importance of a differentiated average selling price rather than one price assigned to all registrations.
Motorization is changing gradually. Conventional gasoline and diesel vehicles account for most established model lines, while fully electric and hybrid vehicles are widening the range offered through import channels and selected domestic programs. Argentina allocated 50,000 vehicles to the 2026 duty-free electric and hybrid import regime, but quota allocations are not retail sales. Charging access, cost of ownership, electricity supply, vehicle suitability and financing determine which of these cars reaches an operator or household. Commercial adoption is likely to remain uneven across vehicle class and province.
Market Trends
Imported Models Are Reshaping Price and Specification Competition
The domestic vehicle market is becoming less tightly linked to the output of Argentina's assembly plants. ACARA's September 2026 statement described a rising share of imported models in registrations as dealerships expanded their product portfolios. Import competition can put pressure on established vehicle prices and equipment levels, especially in compact cars and crossovers, but it also increases dependence on exchange-rate conditions, customs clearance and spare-parts availability.
Local producers have different defenses against this pressure. Pickup platforms supported by broad service networks and commercial users benefit from established brand relationships, while volume passenger-car manufacturers must protect affordability and financeability. Growth in the value of new vehicles should therefore be understood as a combination of registrations, vehicle mix and realized prices, not as a direct consequence of a greater number of available badges.
Pickup Manufacturing Is Broadening Beyond Established Platforms
Toyota, Ford and Volkswagen anchor Argentina's medium-pickup manufacturing cluster, with model programs requiring tooling, powertrain sourcing and extensive aftersales coverage. Stellantis began producing the Fiat Titano at Córdoba in 2025 and has since included the Ram Dakota in the plant's expanded portfolio. Its October 2026 production update describes a further engine investment intended to improve the industrial position of the complex.
These investments matter to the domestic market chiefly through vehicle choice, model supply and competitive pressure in business-oriented segments. Export orders remain a separate demand stream: a pickup produced in Argentina for a neighboring country does not become part of Argentine retail vehicle revenue. The industry's future mix will depend on whether factories can maintain profitable export programs while serving domestic fleets across price and payload bands.
Electrification Is Expanding Through Import-led Model Availability
Argentina's import framework for electrified passenger cars has increased the number of models that dealers can offer. The allocation for 2026 covers battery-electric, plug-in hybrid and conventional hybrid vehicles, as well as specified mild-hybrid vehicles. Yet a quota describes eligibility for entry, not evidence that all units have been delivered to buyers or that every hybrid can operate electrically for meaningful distances.
For vehicle suppliers, success depends on making the operating economics credible at the point of sale. Hybrids can reduce exposure to charging limitations, while pure electric cars appeal to users with suitable charging access and predictable routes. The faster-growing electric category is still materially smaller in value than conventional motorization and should not be interpreted as replacing diesel pickups, long-haul trucks or intercity buses on the same schedule.
Financing Terms Are Influencing the Timing of Purchases
Argentine vehicle makers are using model-specific finance programs to support registrations in a market where buyers frequently compare total monthly expenditure rather than sticker prices alone. Stellantis' October 2026 commercial offer combined zero-rate programs, different credit maturities and special terms for selected passenger cars and vans. Such programs may bring forward purchases, but financing cost, inflation expectations and access to qualifying credit limit their effectiveness.
Fleet buyers typically operate with longer replacement horizons than private households. A logistics operator may defer van purchases until contracted utilization supports the additional debt burden, while a taxi fleet may value downtime protection more than a short promotional rate. A measured recovery in unit demand is more plausible than extending one strong monthly registration figure through 2031.
Fleet Renewal Is Increasing the Importance of Commercial Service Networks
Light commercial vans and pickups serve parcel distribution, agricultural businesses, construction and service technicians, while heavy trucks and buses underpin freight and passenger mobility. Stellantis used ExpoTransporte 2026 to present Citroën and Peugeot utility-vehicle ranges and preview the Partner Rapid, showing that manufacturers are marketing configurations tailored to commercial users rather than relying solely on passenger-car dealership traffic.
Operating economics differ sharply across these categories. Load capacity, maintenance intervals, route geography and dealer support influence commercial purchase decisions; for buses and heavy trucks, financing and vehicle uptime often dominate engine technology alone. Suppliers with strong parts distribution and fleet relationships can retain customers even as new entrants make the passenger-car market more price competitive.
Segment Analysis
By Vehicle Type: Oil Fuel Based Vehicles
Petrol- and diesel-powered vehicles account for an estimated 91.3% of Argentine new road-vehicle sales value in 2026. Their position reflects the installed fuel-distribution network, established pickup and commercial-vehicle models, and the availability of conventional passenger cars across price points. The group includes vehicles using routine legally blended petrol or diesel; such blends do not make them a second, independently counted dedicated-biofuel vehicle sale.
Toyota Hilux, Ford Ranger, Volkswagen Amarok and Stellantis' Cronos, Titano and Dakota demonstrate the breadth of conventional powertrains across family and work applications. By 2031, the category is forecast to remain the largest source of revenue at approximately USD 20.78 billion, although its proportion of the market moderates as electrified registrations grow. The rate of displacement will be shaped by price, vehicle availability, fuel economics and whether customers can obtain equivalent utility and servicing from alternative propulsion.
Market Drivers
Replacement Demand for Passenger and Family Vehicles
Argentina's established passenger-car population creates recurring replacement demand even when consumers postpone purchases during weak economic periods. Older vehicles eventually face rising maintenance expense, reduced resale appeal and changing safety expectations, giving dealers a potential pipeline of buyers as financing and income conditions permit. ACARA's registration figures nevertheless point to a softer first nine months of 2026, so replacement demand is not equivalent to an immediate sales rebound.
Manufacturers offering competitive entry prices and stable parts availability are best placed to convert this deferred demand. Some deferred replacement purchases should return over the next five years, although household affordability is likely to prevent a one-year catch-up surge.
Commercial Pickup Demand from Productive Sectors
Agricultural, energy, construction and field-service operators use pickups as mobile working assets, creating demand different from private commuter replacement. Domestic programs at Toyota, Ford, Volkswagen and Stellantis provide several competing payload, drivetrain and equipment configurations. The continuation of these platforms also helps sustain dealership service capability in interior provinces where vehicle availability is an important purchase consideration.
Higher-trim pickups can lift market value even without an equivalent increase in registrations, but that mix benefit depends on financing and business profitability. Fleets may instead extend asset lives when financing costs or export-linked revenues move against them. Pickup growth therefore reflects both user demand and the pricing power of locally established manufacturers.
New Vehicle Choice Through Import Channels
Wider access to imported brands and model variants gives Argentine buyers more options in compact cars, SUVs and alternative-propulsion vehicles. In September 2026, ACARA described a marked change in the supply mix toward imports. Model competition can stimulate registrations by offering additional price-equipment combinations and shorter delivery times where domestic plants do not produce the desired body style.
A broader supply base does not guarantee sustained unit growth. Buyers still compare warranties, repair networks, financing and exchange-rate exposure. Producers with local parts logistics and dependable dealers may preserve share even against lower advertised prices, while poorly supported newcomers could struggle to turn initial imports into repeat vehicle sales.
Electrified Vehicle Import Programs and Product Variety
The Argentine government's 2026 import allocation for electric and hybrid vehicles permits a defined number of qualifying models to enter without the usual extra-zone tariff. This can lower entry costs for some products and widen consumer choice beyond established conventional powertrains. Conventional hybrids may be more immediately practical where home or public charging is limited, while battery-electric models require a stronger match between route length and charging access.
The effect on overall market value depends on the number actually registered and their realized transaction prices. A larger electrified mix can raise equipment spending, although competition may also reduce average prices. Electrified vehicles therefore remain a faster-growing but still minority contributor to finished-vehicle revenue.
Renewal of Vans, Heavy Trucks and Passenger Fleets
Freight distribution, construction supply chains and passenger transport rely on vehicle availability and uptime. Van and heavy-vehicle purchases are commonly evaluated against contract utilization, operating hours and the cost of retaining older equipment. Stellantis' 2026 utility-vehicle campaign indicates that major producers are actively targeting small-business and professional fleet buyers with product-specific offers.
Commercial fleets can generate durable demand when replacement economics improve, but new purchases are not driven solely by freight growth. Operators must be able to finance vehicles and secure servicing beyond major urban centers. This favors manufacturers with established dealer infrastructure and predictable parts supply.
Full historical and forecast dataset available in Excel and dashboard formats.Download Sample Data →
Market Restraints
Purchasing Power and Vehicle Financing Costs
Household budgets and the cost of credit directly affect new-vehicle registrations. Even when a manufacturer advertises a low promotional rate, eligibility, down-payment requirements and the financed share of the transaction can materially change affordability. Purchasers comparing a used vehicle with a new model may delay replacement when monthly payments remain high relative to income.
This creates a gap between demand for mobility and the addressable market for new vehicles. Manufacturers can use finance programs to support selected models, but a broad-based recovery requires stable purchasing power, not short-term dealership promotions alone.
Exposure to Imported Vehicle and Component Supply
Growing imports broaden choice but leave the Argentine market exposed to external vehicle pricing, currency movement, freight expense and customs processes. Local assemblers face related pressures because engines, electronics and other content can be sourced internationally. A disruption can affect showroom availability even when underlying customer demand is unchanged.
These conditions are especially consequential for manufacturers managing inventories across many variants. Excess inventory ties up working capital, while an undersupplied dealership loses price-sensitive buyers. Supplier resilience and model planning are therefore as important as advertised vehicle specifications.
Weakness in Domestic Assembly and Export Cycles
ADEFA recorded lower production in January–September 2026 than in the corresponding 2025 period, even though export volumes were slightly higher. The mismatch reflects changes in plant utilization, domestic wholesale demand and the allocation of models between Argentine and overseas customers. Higher factory production cannot automatically be translated into a larger domestic market.
Local plants must also balance fixed costs and tooling requirements against volumes that depend on both Argentina and neighboring markets. A prolonged slowdown in either destination may constrain supplier investment, limit locally produced model options or shift the economics of future production programs.
Uneven Charging Access for Electric Road Vehicles
Battery-electric cars and commercial vehicles remain dependent on reliable charging, while diesel and petrol models can draw on much broader refueling infrastructure. This difference is particularly important for long-distance transport and rural operations, where downtime or route deviations affect work schedules. Public charging expansion does not automatically provide heavy-vehicle-capable power or depot access.
For operators with predictable daily routes and private chargers, electric models may become economical sooner. Other buyers will favor hybrids or conventional vehicles until charging, maintenance and residual-value expectations become more dependable. This slows the transition of the larger commercial revenue pools.
Price Competition and Margin Pressure on Manufacturers
New imported variants intensify competition in a market where retailers already negotiate discounts, trade-ins and credit terms. Manufacturers must protect profitability while supporting dealer networks and technical training. Offers that stimulate registrations can be costly if demand shifts mainly between brands rather than increasing total new-vehicle purchases.
For domestic plants, the challenge is sharper when production and local sourcing costs cannot adjust as rapidly as imported vehicle prices. Price pressure may benefit consumers, but it can also delay new investment or compress dealer earnings, particularly for lower-volume models with specialized components.
Geographical Outlook
Buenos Aires Province
Buenos Aires Province represents an estimated 34.5% of Argentina's new road-vehicle market value in 2026, the largest share among Argentina's individual provinces. Its industrial corridors, dense population, pickup and passenger-car dealerships and proximity to Zárate and General Pacheco make it important to both demand and supply. The province is not interchangeable with the City of Buenos Aires, which is retained within the KSI report's residual geographical category rather than silently added to the province.
The province's value is projected to reach approximately USD 8.19 billion in 2031. Its share eases slightly as other productive provinces add commercial vehicle demand, but replacement purchases and work-vehicle registrations maintain a substantial base. Manufacturing output at local plants is not counted as provincial spending unless the finished vehicles are first sold to buyers in the province.
Córdoba
Córdoba's vehicle market is projected to expand at approximately 8.0% annually from 2026 to 2031, making it the fastest-growing province among those separately identified in the report. The expansion reflects its manufacturing and services economy, freight links and presence of Renault's Santa Isabel facility and Stellantis' Ferreyra complex. New pickup investments and ongoing passenger-car production strengthen local industry visibility but do not, by themselves, determine registrations within Córdoba.
From an estimated USD 2.16 billion in 2026, the province approaches USD 3.18 billion by 2031 as commercial fleet replacement and household demand recover. Distribution reach, financing, and import availability remain important determinants of this trajectory. The forecast assumes sustained business investment rather than assigning every locally assembled vehicle to a Córdoba buyer.
Competitive Landscape
Toyota, Ford and Volkswagen compete with differentiated but well-established Argentine pickup manufacturing positions, while Stellantis operates a broader portfolio of local passenger and commercial vehicles across Fiat, Peugeot, Citroën and Ram. Renault's Córdoba operation adds local production capability in vans and pickups. These producers compete not only through vehicles, but also through service reach, financing channels, parts reliability and their capacity to support high-mileage business users.
General Motors, Nissan, Hyundai, Mercedes-Benz, Iveco, Scania, Volvo and other vehicle manufacturers address overlapping customer segments through imported models, locally assembled products where applicable, and specialized distribution networks. The relevant comparison is finished vehicles offered to Argentine customers. A truck supplier and a compact-car producer should not be assigned a common price or treated as identical competitors merely because both operate in road transportation.
Factory platforms and dealer networks also differ in resilience to price competition. Local pickup programs gain some support from regional exports, whereas import-led models can respond quickly to changes in body style and propulsion demand. Long-run supplier advantage is likely to depend on product refresh cycles and affordability together with service support; headline plant capacity does not establish a share of domestic vehicle sales.
Recent Developments
19 October 2026: Stellantis reported that its Córdoba manufacturing complex had reached 1.5 million cumulative vehicles and described investment in a new engine line alongside Cronos, Titano and Dakota programs. This is an industrial milestone, not a domestic sales count.
5 October 2026: Stellantis detailed October financing programs for its vehicle brands, including passenger and commercial models. The offers demonstrate active retail support but do not establish completed registrations.
11 August 2026: Stellantis presented Citroën and Peugeot light commercial vehicles at ExpoTransporte, including a preview of Partner Rapid before its intended commercial launch. The event targets fleet and small-business buyers.
9 February 2026: Stellantis announced production of the 500,000th Fiat Cronos at Ferreyra in Córdoba, demonstrating the continued scale of an established locally built passenger-car platform.
14 January 2026: Ford confirmed plans to manufacture Ranger Tremor at General Pacheco from late 2026. The notice describes a future program, not vehicles already delivered.
1 January 2026: Toyota Argentina reported its 2025 result, including 180,352 vehicles built at Zárate and 140,768 exported. The disclosure illustrates Argentina’s export-oriented pickup manufacturing base.
Market Outlook
Argentina's road-vehicle market should develop through a combination of replacement sales, commercial fleet investment and gradual changes in propulsion. The underlying forecast does not require an abrupt switch to electric drivetrains: conventional passenger cars, pickups and commercial vehicles continue to account for most transaction value even as hybrid and battery-electric offerings become more accessible. The most important swing factors are registrations and vehicle mix rather than headline announcements of model launches or factory output.
Manufacturers with durable fleet relationships, competitive financing and reliable parts networks will be better placed to defend margins. Imported products may increase the pressure to improve equipment content and reduce entry prices; local producers will need productive export programs to justify some of their capital investments. Córdoba gains relative share in domestic vehicle demand, while Buenos Aires remains the largest individual province. The pace of investment and buyer access to finance will determine whether the modeled recovery is sustained.
Argentina Road Transportation Vehicle Market Scope: