
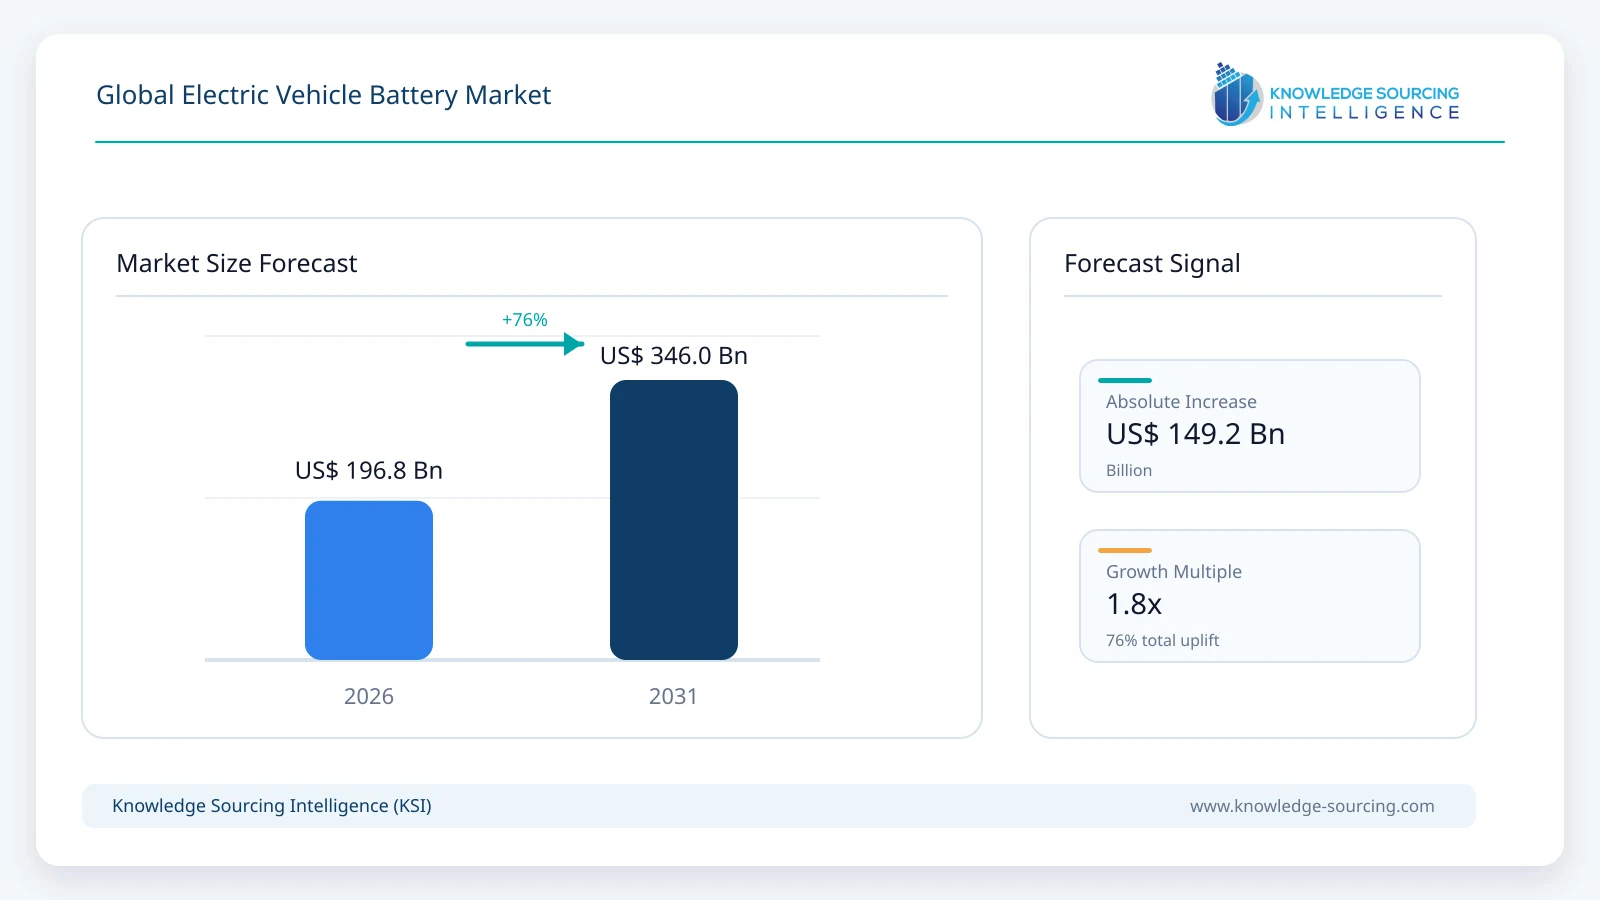
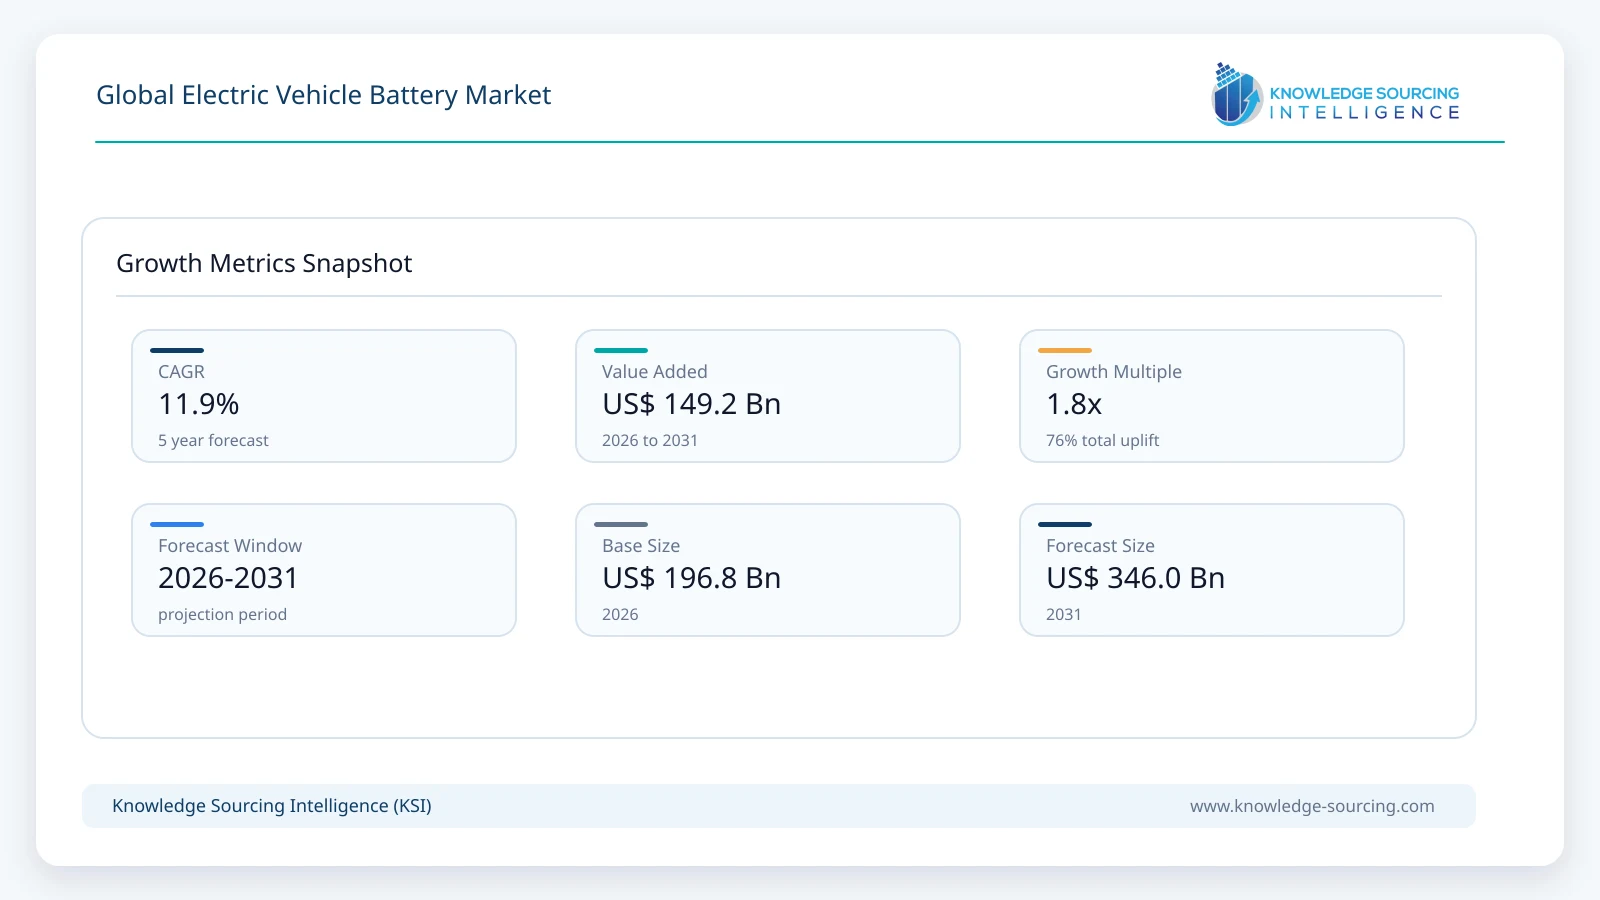
The Electric Vehicle Battery Market is forecast to grow at a CAGR of 11.9%, reaching USD 346.0 billion in 2031 from USD 196.8 billion in 2026.
Highlights:
- 1LFP-based batteries account for approximately 51% of global EV battery market value in 2026.
- 2Battery electric vehicles generate roughly 86% of 2026 EV battery revenue.
- 3Asia Pacific accounts for approximately 68% of 2026 market value, led by China.
- 4Global EV battery deployment reached 1.2 TWh in 2025, rising almost 30% year over year.
- 5China represented more than 80% of global battery cell production in 2025.
- 6CATL plans full-scale sodium-ion battery production by the end of 2026.
Market Overview
EV batteries remain the largest source of lithium-ion battery demand globally. The International Energy Agency estimates that EVs accounted for more than 70% of total battery deployment in 2025, with EV battery deployment reaching 1.2 TWh. China represented around 60% of global EV battery deployment, the European Union almost 15% and the United States about 10%. Global nameplate lithium-ion manufacturing capacity exceeded 4 TWh by the end of 2025, but the industry remains highly concentrated: China accounted for over 80% of both global battery cell production and manufacturing capacity, while Chinese producers supplied nearly three-quarters of electric-car battery deployment.
Chemistry economics increasingly determine competitive positioning. LFP has expanded rapidly in cost-sensitive vehicles because it avoids nickel and cobalt, offers strong cycle life and supports increasingly fast charging. NMC and NCA remain important where higher energy density is required, particularly in larger and premium vehicles. The IEA notes that LFP accounted for more than 10% of EV battery demand in the European Union in 2025, while the United States remained much more dependent on nickel-rich chemistries because of sourcing rules and tariffs. China, by contrast, has a highly developed LFP ecosystem and most of the world's LFP cathode and precursor capacity.
Technology competition is now extending beyond chemistry into charging speed and pack architecture. CATL's third-generation Shenxing battery, introduced in April 2026, emphasizes extreme fast charging, while its Naxtra sodium-ion battery is scheduled for full-scale mass production by the end of 2026. BYD launched its second-generation Blade Battery and flash-charging technology in March 2026, positioning faster replenishment as a core vehicle attribute. At the same time, Samsung SDI continues to target all-solid-state mass production in 2027, although IEA analysis indicates that solid-state batteries still require large-scale commercial demonstration before they can materially affect global EV battery volumes.
Market Trends
LFP Is Moving from Low-Cost Chemistry to Mainstream Global Platform
LFP's commercial proposition has broadened beyond entry-level vehicles. Improvements in cell-to-pack design, thermal management and charging capability are allowing LFP to serve mainstream passenger cars while retaining cost and durability advantages. The chemistry is especially dominant in China, where battery manufacturers, cathode suppliers and automakers operate within a tightly integrated value chain. Europe and North America are trying to localize LFP production, but the IEA notes that cathode and precursor capacity remains heavily concentrated in China. This creates a structural difference between local cell assembly and genuine supply-chain independence.
Fast Charging Is Becoming a Battery-Level Competitive Metric
Charging speed is shifting from a vehicle-system feature to a battery technology differentiator. CATL and BYD are both using new cell chemistries, electrode design and thermal systems to reduce charging time, while high-power public charging networks are being designed around these capabilities. BYD's second-generation Blade Battery and flash-charging system targets very short charging intervals, and CATL's third-generation Shenxing platform follows the same direction. Faster charging can reduce the amount of battery capacity consumers believe they need, potentially moderating pack-size growth even as EV sales expand.
Supply-Chain Localization Is Replacing Capacity Expansion as the Main Industrial Policy Issue
Battery manufacturing capacity is no longer the only constraint. The IEA estimates global nameplate manufacturing capacity above 4 TWh in 2025, well ahead of actual EV battery deployment, but critical upstream materials remain much more concentrated. China produces around 85% of cathode active material and more than 90% of anode active material used in electric-car batteries. The United States and Europe are adding cell plants, yet many facilities still depend on imported cathode, anode and precursor materials. Future competitiveness therefore depends on the localization of the entire chain rather than cell assembly alone.
Sodium-Ion and Solid-State Batteries Are Moving Closer to Commercialization
Alternative chemistries are becoming more credible but remain limited in near-term market share. CATL's Naxtra sodium-ion battery is scheduled for full-scale production by the end of 2026, creating a commercial pathway for sodium-ion in applications where cost, cold-weather performance and mineral availability matter more than maximum energy density. Solid-state batteries target a different segment. Samsung SDI plans mass production in 2027, while other developers continue pilot and customer-validation programs. IEA analysis, however, cautions that solid-state performance advantages have not yet been proven at large-scale commercial deployment.
Market Drivers
Electric Vehicle Sales Continue to Expand Global Battery Deployment
Vehicle electrification remains the primary demand driver. IEA data show global EV battery deployment rose almost 30% in 2025 to 1.2 TWh, with electric vehicles accounting for more than 70% of all battery deployment. Battery electric cars remain the dominant end use, while electric trucks are becoming more important: truck battery demand more than doubled in 2025 and reached about 8% of EV battery deployment. By 2030, IEA scenarios place EV battery demand near 3 TWh, supporting sustained growth in cell, pack and battery-management revenue even as battery cost per kWh declines.
Lower Battery Cost Is Expanding the Addressable EV Market
Battery cost remains the largest determinant of EV affordability. Greater manufacturing scale, lower lithium prices, higher LFP penetration and better pack integration are reducing cost per usable kilowatt-hour. Lower battery cost enables manufacturers to offer more affordable electric vehicles without sacrificing margin or range, while high-density batteries reduce the physical pack size required for longer-range models. This creates a reinforcing cycle in which cost reduction supports EV adoption and higher EV production supports further manufacturing scale.
Commercial Vehicles Are Becoming a Larger Source of Battery Demand
Electric trucks, buses and vans require significantly larger packs than passenger cars and therefore contribute disproportionate battery demand per vehicle. The IEA reported that electric-truck battery deployment more than doubled in 2025, driven largely by China. Commercial fleets also have a clearer total-cost-of-ownership case where vehicles operate high annual mileage and return to predictable depots. As charging infrastructure and heavy-duty battery systems improve, commercial transport provides an additional growth engine beyond passenger EV sales.
Market Restraints
Manufacturing Overcapacity, Margin Pressure and Supply Concentration Increase Industry Risk
Global battery manufacturing capacity is expanding faster than current demand, creating low utilization and pricing pressure in several regions. The IEA reports more than 4 TWh of nameplate lithium-ion capacity at the end of 2025 against 1.2 TWh of EV battery deployment, although stationary storage also absorbs output. Producers face additional pressure from low margins in cathode materials, changing policy support and automakers revising battery-supply agreements. At the same time, upstream concentration in China leaves Europe and North America exposed even when local cell capacity exists. These conditions can delay projects, reduce returns on new factories and intensify consolidation.
Segment Analysis
By Battery Chemistry - Lithium Iron Phosphate (LFP)
LFP batteries are estimated to account for approximately USD 100.4 billion in 2026 and represent the largest chemistry segment by market value. Their cost advantage, long cycle life, thermal stability and growing fast-charging capability make them increasingly suitable for mainstream passenger EVs as well as commercial vehicles. NMC and NCA batteries retain a strong position in premium and long-range models because of higher energy density. Sodium-ion and solid-state batteries remain small but represent the most important emerging chemistry pathways over the forecast period.
By Vehicle Type - Battery Electric Vehicle
Battery electric vehicles are estimated to generate approximately USD 169.2 billion of EV battery revenue in 2026. BEVs require significantly larger battery packs than plug-in hybrids or conventional hybrids, making them the dominant battery revenue source even where their vehicle share is lower. Plug-in hybrid batteries are expanding as average electric range increases, especially in China and Europe. Hybrid electric vehicles remain relevant but contribute a much smaller battery value per vehicle because their packs are designed primarily for power support rather than long electric-only range.
By Battery Form - Prismatic
Prismatic cells are estimated to represent the largest battery-form segment in 2026 because of their dominance among Chinese manufacturers and widespread use in LFP packs. They integrate efficiently into cell-to-pack and structural pack architectures and can reduce module-level complexity. Cylindrical cells remain important for Tesla, Panasonic and several premium EV platforms, while pouch cells retain a meaningful position among Korean and European supply chains. The market is unlikely to converge on one cell format because pack architecture, chemistry, vehicle platform and manufacturing strategy remain closely linked.
By Geography - Asia Pacific
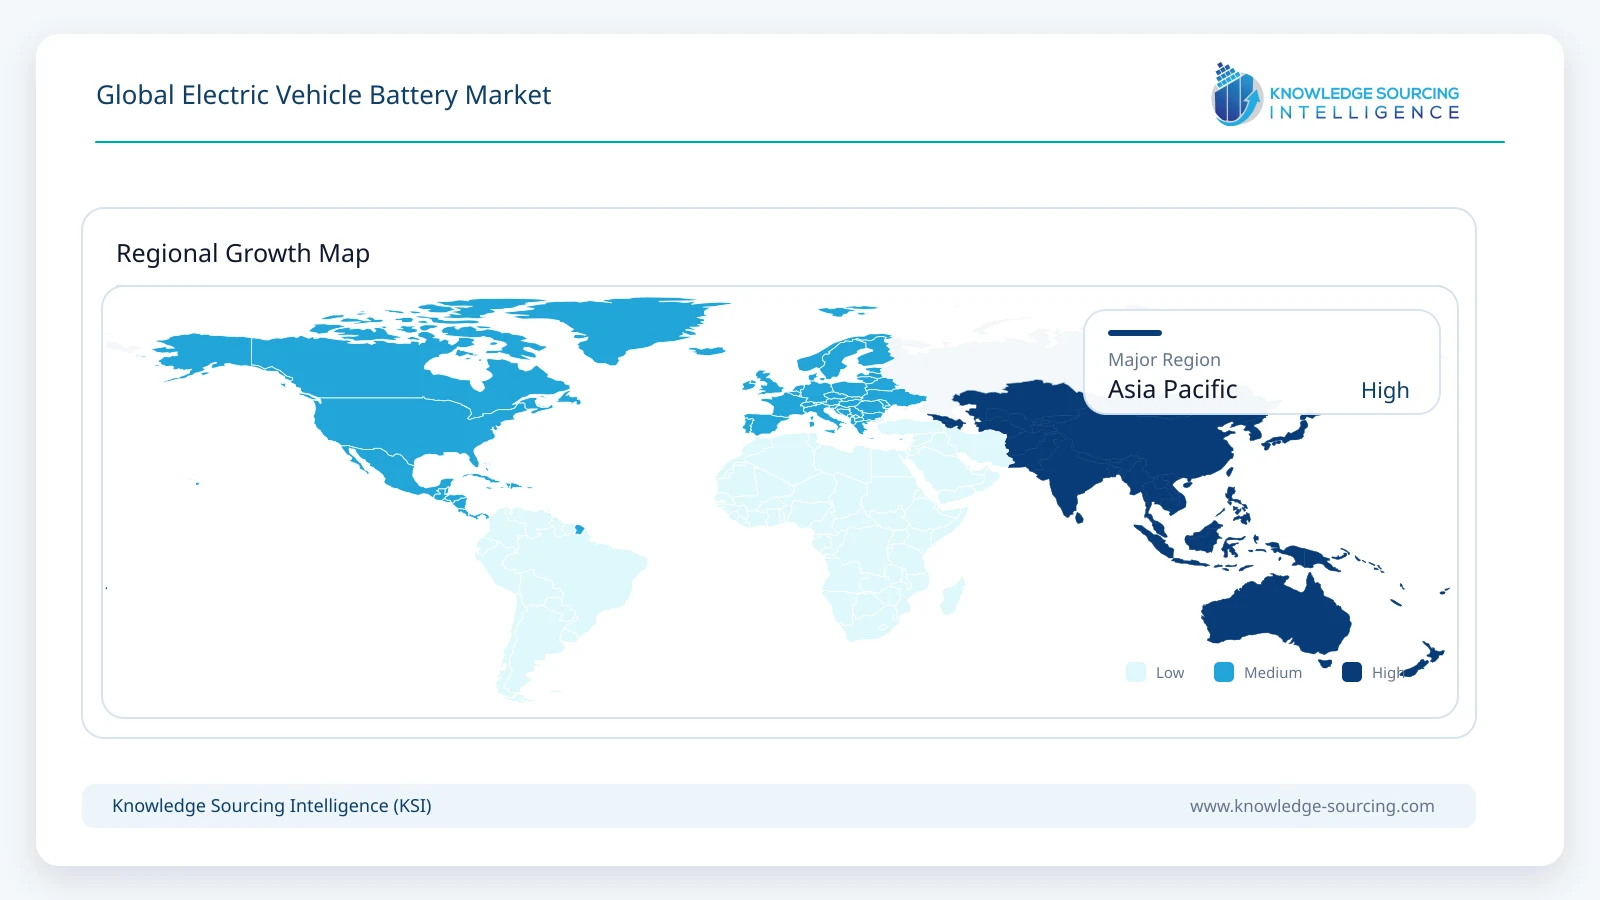
Asia Pacific is estimated at approximately USD 133.8 billion in 2026 and remains the largest regional market. China alone accounted for about 60% of global EV battery deployment in 2025 and more than 80% of battery cell production. The region also includes major battery producers in South Korea and Japan, while India, Indonesia and Southeast Asia are building new cell and material capacity. Europe is the second-largest demand region and is attracting Chinese and Korean investment, while North America has expanded manufacturing capacity but faces softer EV demand expectations and continuing dependence on imported upstream materials.
Competitive Environment
The EV battery market is led by companies headquartered in China, South Korea and Japan. CATL, BYD, LG Energy Solution, Panasonic Energy and Samsung SDI are among the most important global suppliers, while CALB, Gotion High-Tech, EVE Energy and Sunwoda strengthen China's second tier. Competition increasingly spans chemistry, fast charging, pack integration, manufacturing yield, raw-material access and automaker relationships rather than cell capacity alone. CATL and BYD benefit from integrated domestic supply chains, while Korean and Japanese suppliers retain strong relationships with European and North American automakers.
The market is also becoming more vertically integrated. BYD combines battery manufacturing with vehicle production, CATL is expanding into charging and swapping ecosystems, and automakers are forming joint ventures or direct supply agreements to secure local capacity. Panasonic Energy began mass production at its Kansas plant in 2025 with planned annual capacity of approximately 32 GWh, increasing its North American footprint. The strategic challenge for all suppliers is to balance localization and customer-specific investments against the risk of underutilized capacity if vehicle programs are delayed or revised.
Recent Developments
April 2026: CATL unveiled third-generation Shenxing, third-generation Qilin and Naxtra sodium-ion batteries, with Naxtra scheduled for full-scale production by year-end.
March 2026: BYD launched its second-generation Blade Battery and flash-charging technology, emphasizing faster charging and improved low-temperature performance.
2026: Samsung SDI continued preparations for all-solid-state battery mass production targeted for 2027.
July 2025: Panasonic Energy began mass production at its Kansas factory, targeting approximately 32 GWh of annual capacity.
2025: Global EV battery deployment reached 1.2 TWh, up almost 30% year over year according to the IEA.
2025: Global lithium-ion battery manufacturing capacity exceeded 4 TWh, with China accounting for over 80% of the total.
Electric Vehicle Battery Market Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 196.8 billion |
| Total Market Size in 2031 | USD 346.0 billion |
| Forecast Unit | Billion |
| Growth Rate | 11.9% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Battery Chemistry, Vehicle Type, Battery Form, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Battery Chemistry
Lithium Iron Phosphate (LFP)
Nickel Manganese Cobalt / Nickel-Rich Lithium-Ion
Nickel Metal Hydride
Sodium-Ion and Other Emerging Chemistries
By Vehicle Type
Battery Electric Vehicle
Plug-In Hybrid Electric Vehicle
Hybrid Electric Vehicle
By Battery Form
Prismatic
Cylindrical
Pouch
By Geography
North America
USA
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Spain
Italy
Others
Middle East & Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
South Korea
India
Indonesia
Thailand
Australia
Others
Geographical Segmentation
- Middle East and Africa
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Electric Vehicle Sales Continue to Expand Global Battery Deployment
3.1.2. Lower Battery Cost Is Expanding the Addressable EV Market
3.1.3. Commercial Vehicles Are Becoming a Larger Source of Battery Demand
3.2. Market Restraints
3.2.1. Manufacturing Overcapacity, Margin Pressure and Supply Concentration Increase Industry Risk
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Lithium Iron Phosphate (LFP)
4.2. Nickel Manganese Cobalt (NMC) and Nickel-Rich Chemistries
4.3. Sodium-Ion Batteries
4.4. Solid-State Batteries
4.5. Cell-to-Pack and Structural Battery Architecture
4.6. Fast-Charging Battery Technology
4.7. Battery Management Systems and Thermal Management
5. GLOBAL ELECTRIC VEHICLE BATTERY MARKET BY BATTERY CHEMISTRY
5.1. Introduction
5.2. Lithium Iron Phosphate (LFP)
5.3. Nickel Manganese Cobalt / Nickel-Rich Lithium-Ion
5.4. Nickel Metal Hydride
5.5. Sodium-Ion and Other Emerging Chemistries
6. GLOBAL ELECTRIC VEHICLE BATTERY MARKET BY VEHICLE TYPE
6.1. Introduction
6.2. Battery Electric Vehicle
6.3. Plug-In Hybrid Electric Vehicle
6.4. Hybrid Electric Vehicle
7. GLOBAL ELECTRIC VEHICLE BATTERY MARKET BY BATTERY FORM
7.1. Introduction
7.2. Prismatic
7.3. Cylindrical
7.4. Pouch
8. GLOBAL ELECTRIC VEHICLE BATTERY MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. USA
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. Germany
8.4.2. France
8.4.3. United Kingdom
8.4.4. Spain
8.4.5. Italy
8.4.6. Others
8.5. Middle East & Africa
8.5.1. Saudi Arabia
8.5.2. UAE
8.5.3. South Africa
8.5.4. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. Japan
8.6.3. South Korea
8.6.4. India
8.6.5. Indonesia
8.6.6. Thailand
8.6.7. Australia
8.6.8. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Chemistry and Cell-Format Positioning
9.3. Capacity Expansion and Localization
9.4. Partnerships, Joint Ventures and Supply Agreements
9.5. Competitive Dashboard
10. COMPANY PROFILES
10.1. Contemporary Amperex Technology Co., Limited (CATL)
10.2. BYD Company Limited
10.3. LG Energy Solution Ltd.
10.4. Panasonic Energy Co., Ltd.
10.5. Samsung SDI Co., Ltd.
10.6. CALB Group Co., Ltd.
10.7. Gotion High-Tech Co., Ltd.
10.8. EVE Energy Co., Ltd.
10.9. Sunwoda Electronic Co., Ltd.
10.10. SK On Co., Ltd.
10.11. Envision AESC Group Ltd.
10.12. Farasis Energy
10.13. SVOLT Energy Technology Co., Ltd.
10.14. Prime Planet Energy & Solutions, Inc.
10.15. Automotive Cells Company SE
10.16. QuantumScape Corporation
10.17. Solid Power, Inc.
10.18. ProLogium Technology Co., Ltd.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations
LIST OF FIGURES
LIST OF TABLES





Frequently asked questions
What is the forecasted market size for EV batteries by 2031?
The Global Electric Vehicle Battery Market is projected to reach USD 346.0 billion by 2031.
What is the forecasted CAGR for the EV battery market (2026-2031)?
The Global Electric Vehicle Battery Market is forecast to grow at an 11.9% CAGR.
Which region dominates the global EV battery market and supply chain?
Asia Pacific is the largest regional market and supply chain center.
What is the leading EV battery chemistry by deployed capacity?
Lithium iron phosphate (LFP) is the leading chemistry.
Which EV battery form factor is currently dominant?
Prismatic cells are the dominant form factor, over 60%.
What new battery technologies are emerging?
Sodium-ion and solid-state batteries are entering commercial production.
Cite this report
Knowledge Sourcing Intelligence. (Sep 2026). Global Electric Vehicle Battery Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/global-electric-vehicle-battery-market