Asia Pacific (APAC) Colocation Market - Strategic Insights and Forecasts (2026-2031)
Asia Pacific (APAC) Colocation Market Share, Growth, Forecasts and Industry Trends By Colocation Model (Retail Colocation, Wholesale Colocation), Enterprise Size (Small Enterprises, Medium Enterprises, Large Enterprises), Industry Vertical (Banking, Financial Services, and Insurance (BFSI), Manufacturing, IT and Telecommunications, Healthcare, Energy and Utilities, Education, Government, Media and Entertainment, Others), and Country
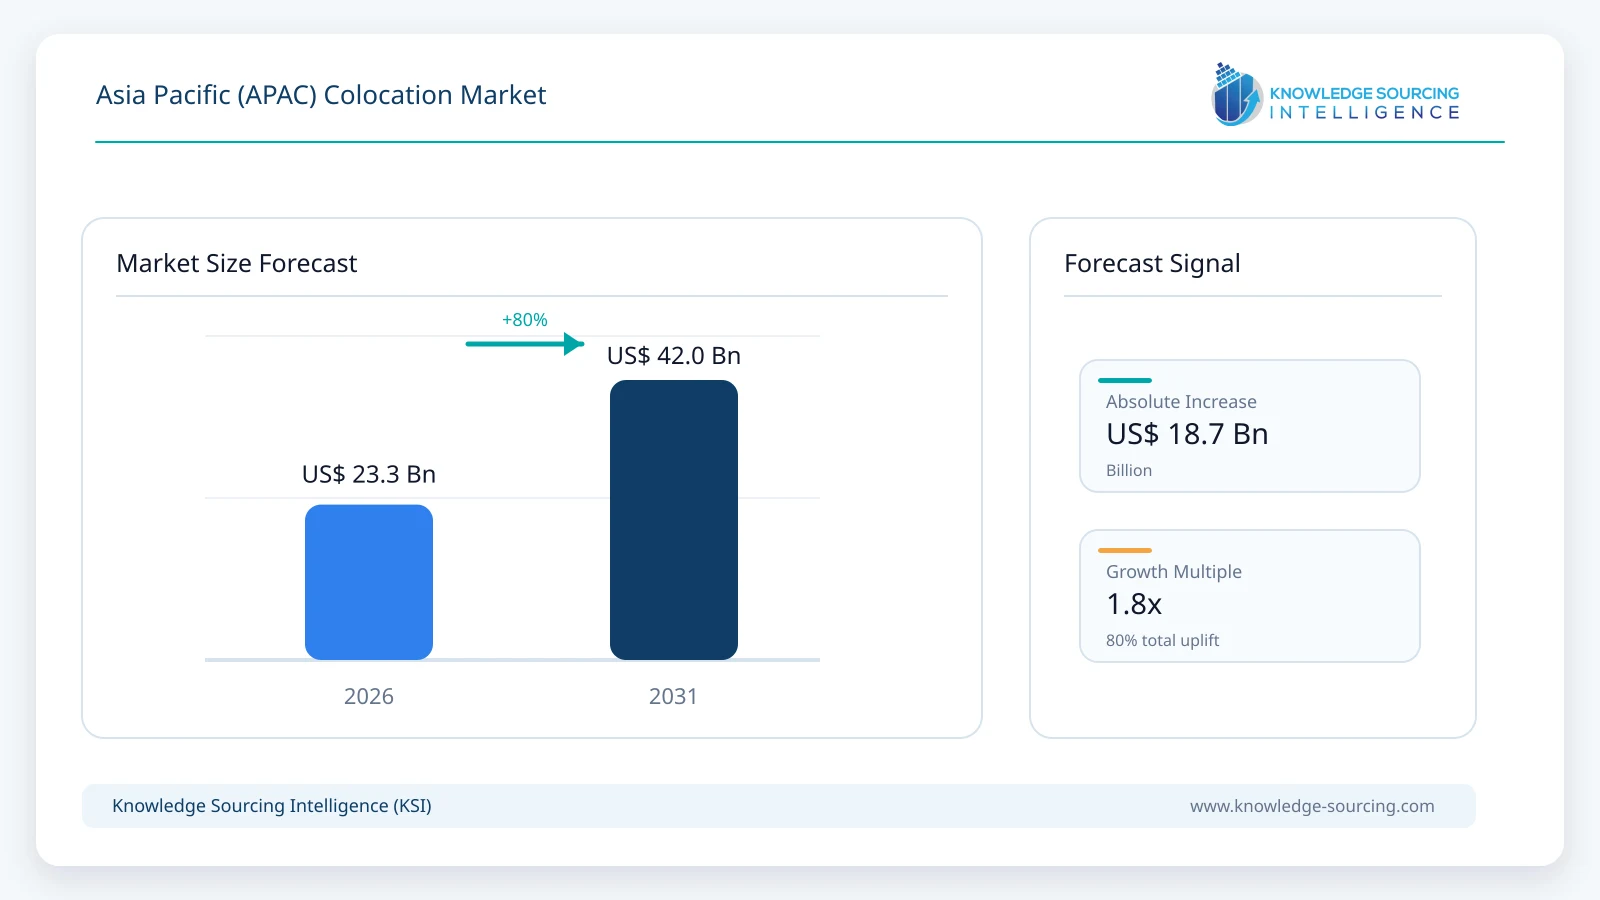
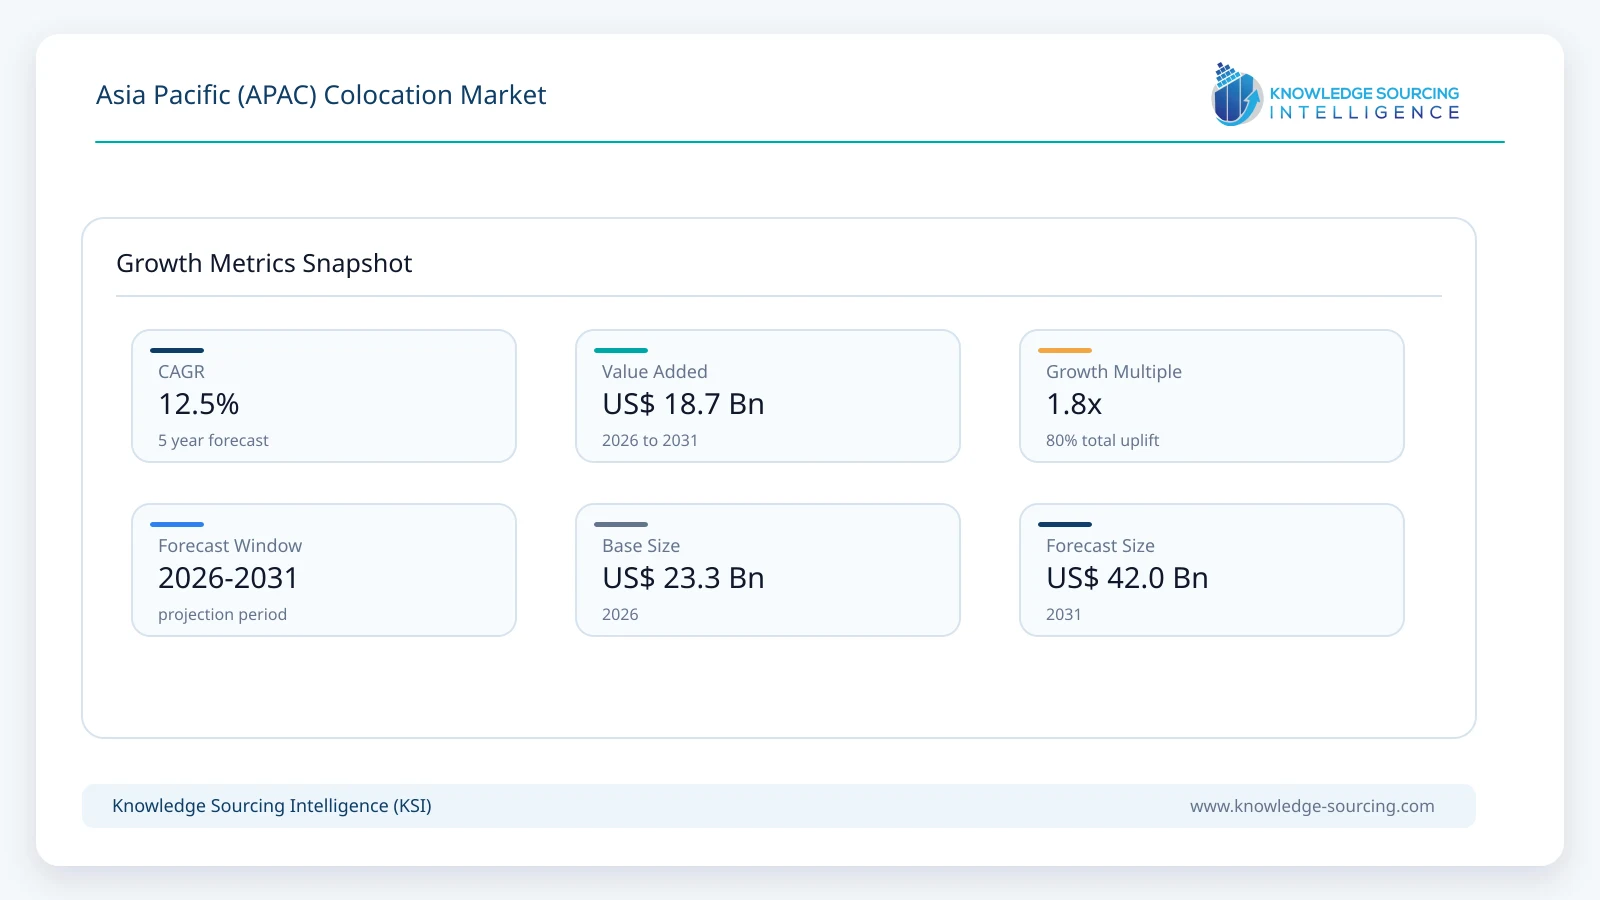
The Asia Pacific (APAC) colocation market is projected to grow at a CAGR of 12.7%, from USD 23.32 billion in 2026 to USD 42.37 billion in 2031.
Highlights:
1
Wholesale colocation accounts for an estimated 53.2% of APAC market revenue in 2026
, supported by hyperscale cloud deployments, AI infrastructure and large dedicated capacity requirements.
2
Communication and technology account for an estimated 35.7% of market demand in 2026
, reflecting infrastructure requirements from cloud providers, telecommunications operators, internet platforms and AI-related computing.
3
Large enterprises remain the largest direct customer category, although medium-sized enterprises are increasing their use of colocation through managed infrastructure and hybrid-cloud services.
4
more than 70 cloud, enterprise and colocation data centers with total capacity exceeding 1.4 GW
Singapore currently has , while additional capacity is being released through a controlled sustainability-led framework.
5
India is moving from a primarily enterprise-colocation market toward large-scale hyperscale and AI infrastructure, led by Mumbai and Chennai with further geographic expansion expected.
6
Japan is increasingly coordinating electricity, telecommunications and data center development as AI workloads increase infrastructure requirements outside established Tokyo clusters.
7
Indonesia is emerging as a significant hyperscale market, with operators securing sites capable of supporting several hundred megawatts of new capacity.
8
Liquid cooling, high-density electrical infrastructure, direct cloud connectivity and access to reliable electricity are becoming more important competitive differentiators than conventional rack capacity alone.
The market covers retail and wholesale third-party data center infrastructure providing customers with computing space, electrical capacity, cooling, physical security, network connectivity and related infrastructure across major Asia Pacific markets.
Market Overview
The Asia Pacific colocation market combines mature interconnected infrastructure hubs with some of the world’s fastest-growing data center development markets. Singapore, Tokyo, Sydney, Hong Kong and Seoul maintain established enterprise, financial-services, cloud and telecommunications ecosystems, while Mumbai, Chennai, Jakarta and other locations are attracting progressively larger hyperscale developments. This produces a market in which interconnected retail colocation remains commercially important at the same time that large dedicated data halls and multi-megawatt wholesale deployments are absorbing a growing share of new infrastructure investment.
The market’s development is increasingly shaped by computing intensity rather than only growth in data volumes. Cloud migration, digital platforms and enterprise modernization continue to support conventional demand, but artificial intelligence is increasing electrical and thermal requirements per unit of computing space. Facilities that were designed for traditional enterprise servers may have available floor area without sufficient power distribution or cooling capability to support current GPU deployments. New construction is consequently being designed around higher rack densities, direct liquid cooling and larger utility connections, while established operators selectively retrofit existing facilities where the economics justify the investment.
Current operator activity supports the revised market trajectory. Equinix reported continued Asia Pacific revenue growth in 2025 and substantial regional property, plant and equipment, while Digital Realty reported 24 Asia Pacific facilities with approximately 218 MW of white-space IT load in the first quarter of 2026. Princeton Digital Group states that its portfolio exceeds 1.8 GW across seven Asian markets, while major facilities are being added by NTT DATA, Equinix and other regional operators. These capacity pipelines support continued double-digit market growth without requiring the assumption that every APAC country expands at the same rate.
The regional structure is becoming more distributed. Singapore remains a strategically important interconnection hub but controls incremental capacity because of electricity and resource constraints. Japan is encouraging greater coordination between digital and power infrastructure. India is attracting larger international and domestic developments, while Indonesia and Malaysia provide additional land and power for Southeast Asian hyperscale demand. The market therefore increasingly operates through interconnected groups of metropolitan and hyperscale locations rather than through a small number of dominant regional hubs.
Market Drivers
AI deployment is increasing demand for high-density colocation infrastructure
Artificial intelligence is changing data center requirements throughout Asia Pacific. GPU-based infrastructure concentrates substantially greater electrical and thermal loads than conventional enterprise computing, while many organizations do not possess internal facilities capable of accommodating these deployments. Colocation providers can offer pre-engineered high-density power, direct liquid cooling, redundant electrical systems and network connectivity without requiring customers to redesign existing corporate facilities. Digital Realty’s NRT14 facility in Japan illustrates the transition, supporting hybrid liquid and air cooling and high-density deployments of up to 150 kW per rack. AI therefore expands the colocation opportunity through both higher computing demand and migration from technically unsuitable enterprise facilities.
Hyperscale customers are increasing wholesale capacity requirements
Cloud platforms and large digital businesses increasingly require dedicated infrastructure measured in megawatts rather than conventional rack counts. This changes development economics because operators must secure larger sites, utility connections and expansion rights before customer deployment. Princeton Digital Group’s April 2026 acquisition of a powered Greater Jakarta site for a planned 240 MW campus increased its Indonesian planned portfolio to approximately 400 MW. Similar large-scale development strategies are being pursued across India, Japan, Australia and Southeast Asia. Wholesale operators able to deliver multiple phases of capacity within the same campus therefore benefit from customers seeking predictable expansion without repeatedly relocating infrastructure.
India’s cloud and digital economy are supporting larger domestic infrastructure requirements
India is becoming one of the most important incremental markets within APAC. The country combines a large digital-user base, cloud-region development, growing AI adoption, financial-services digitization, e-commerce and data-residency requirements. Equinix opened its MB3 facility in Mumbai in April 2026 with more than 1,370 cabinets initially and design capacity exceeding 5,475 cabinets. Mumbai remains the principal interconnection market, while Chennai is becoming increasingly important because of cloud deployments, submarine connectivity and available development land. Domestic operators are simultaneously increasing investment, creating a competitive environment that includes both international colocation platforms and Indian infrastructure specialists.
Singapore’s constrained supply supports continued value in interconnected capacity
Singapore remains strategically significant despite deliberate controls on physical expansion. The government reported in February 2026 that the country had more than 70 cloud, enterprise and colocation data centers with aggregate capacity exceeding 1.4 GW. The Green Data Centre Roadmap provides for at least another 300 MW of capacity in the near term, with future development linked to energy efficiency and access to green energy. This controlled expansion increases the importance of existing interconnected facilities and favors operators capable of demonstrating efficient use of scarce electricity. Singapore therefore remains an important APAC market even as large-scale hyperscale development expands into neighboring countries.
Indonesia is progressing from a developing market toward hyperscale-scale infrastructure
Indonesia’s large population, increasing cloud adoption and rapidly developing digital economy are encouraging larger infrastructure commitments around Greater Jakarta. New projects increasingly resemble hyperscale campuses rather than conventional enterprise colocation facilities. Princeton Digital Group’s JC4 site has power allocated for 240 MW across four planned buildings and is positioned close to its existing JC3 campus, allowing shared power and connectivity infrastructure. This development pattern provides evidence that Jakarta is becoming a standalone regional infrastructure hub rather than merely an extension of Singapore-based deployments.
Hybrid cloud continues to support network-dense metropolitan colocation
Public-cloud adoption does not eliminate the need for physical infrastructure because large organizations continue to operate regulated databases, private applications, legacy systems and latency-sensitive workloads outside public-cloud environments. Carrier-neutral colocation allows enterprises to connect these systems directly to several cloud and telecommunications providers. This supports demand for established metropolitan facilities even as newer hyperscale campuses provide greater power availability outside central locations. The commercial value of these facilities increasingly lies in their network ecosystems rather than simply the amount of floor space available.
Market Restraints and Challenges
Electricity availability is becoming a primary constraint on development
High-density cloud and AI facilities require very large electrical connections, and utility infrastructure cannot always expand at the same speed as computing demand. Japan has established policy initiatives aimed at better coordinating electricity and telecommunications infrastructure because data center and AI requirements are increasing. Singapore similarly limits expansion according to resource availability and efficiency. Developers that secure land without corresponding power commitments can therefore experience extended deployment delays. Access to energized capacity is increasingly becoming a prerequisite for commercially credible project pipelines.
Cooling requirements are increasing development and operating costs
Asia Pacific contains several warm and humid markets where cooling already accounts for a substantial part of facility energy use. Higher-density AI equipment compounds this issue by producing significantly greater heat loads within individual racks. Singapore’s Tropical Data Centre Standard specifically addresses operation in tropical conditions and estimates that cooling-energy savings can be achieved by safely increasing operating temperatures within appropriate technical parameters. Direct liquid cooling can further improve high-density performance, but retrofitting older facilities requires additional capital, pipework, heat-rejection systems and operational changes.
APAC market conditions differ substantially between countries
Regional growth does not translate uniformly across Asia Pacific. Singapore provides mature connectivity but constrained land and electricity. Japan offers large enterprise and cloud demand but faces power and geographic-concentration issues. India provides stronger growth potential but requires substantial new supporting infrastructure. Indonesia and Malaysia offer larger development sites but have less mature interconnection ecosystems than Singapore. China operates within a distinct regulatory and competitive structure, while Australia faces different power and geographic economics. Providers consequently need country-specific development, pricing and energy strategies rather than treating APAC as one uniform infrastructure environment.
Large hyperscale campuses increase capital and execution risk
The increasing size of data center campuses means operators commit substantial capital before all customer capacity becomes operational. Land acquisition, substations, power connections, cooling systems and building shells can require investment several years before a campus reaches full utilization. Large anchor customers can provide development visibility, but they can also create customer-concentration risk and request customized technical specifications. Phased construction therefore becomes increasingly important so that providers can align capital expenditure with contracted demand.
Sustainability requirements can restrict development in constrained markets
Governments increasingly need to balance data center expansion against electricity-system capacity and decarbonization objectives. Singapore’s Digital Infrastructure Bill, introduced in September 2026, establishes licensing frameworks covering security, resilience and environmental sustainability. Major colocation and cloud facilities with critical IT loads of at least 10 MW fall within the proposed infrastructure regime. Similar policy pressure is likely to influence other constrained markets as AI increases electricity demand. Higher sustainability standards can improve industry efficiency but may also require upgrades to older facilities and increase the investment threshold for new developments.
Major Segment Analysis
By Colocation Type
Wholesale colocation is projected to grow at approximately 14.6% annually between 2026 and 2031, above overall market growth. Large cloud platforms, AI infrastructure providers and digital-service companies increasingly require dedicated data halls and multi-megawatt deployments, allowing wholesale infrastructure to increase its contribution to APAC revenue.
Retail colocation remains an important market because financial institutions, multinational enterprises and other customers continue to require racks, private cages, direct cloud connectivity and carrier-neutral interconnection. Established facilities in Singapore, Tokyo, Hong Kong, Sydney and other major metropolitan markets retain strong network advantages even where new hyperscale construction shifts toward locations with greater land and electricity availability.
By Enterprise Size
Large enterprises account for an estimated 60.5% of direct APAC colocation revenue in 2026. Their leadership reflects greater requirements for disaster recovery, regulatory compliance, geographically distributed infrastructure and direct connectivity between private systems and multiple public-cloud environments.
Medium-sized enterprise adoption is expected to expand faster as managed infrastructure and cloud connectivity simplify colocation use. Small companies remain less significant as direct customers because much of their infrastructure is consumed indirectly through software, cloud and managed-service providers.
By End User
Communication and technology are projected to generate approximately USD 16.01 billion of APAC colocation revenue by 2031. Cloud platforms, telecommunications companies, internet businesses, digital-content providers and AI infrastructure customers require both substantial electrical capacity and dense network connectivity, keeping the segment in the leading position.
Banking and financial services remain important in Singapore, Hong Kong, Tokyo, Sydney and Mumbai, where institutions require resilient, low-latency and regulated infrastructure. Manufacturing also contributes significant demand through industrial digitization, particularly in China, Japan, South Korea and Southeast Asia.
Country Analysis
China remains one of the largest individual APAC colocation markets because of the scale of its cloud, internet and enterprise technology sectors. Domestic providers play a particularly significant role, while regulation and market structure differentiate China from other regional countries. Growth remains substantial but is expected to be slower than in India and selected Southeast Asian markets, gradually reducing China’s share of incremental APAC revenue.
Japan remains a major mature market built around Tokyo and Osaka, with expansion increasingly extending toward additional locations where electricity and land can be secured. NTT DATA opened its 30 MW OSK11 data center in the Osaka-Kyoto corridor in April 2026, while Digital Realty opened NRT14 at its Greater Tokyo campus with liquid-cooling capability for high-density AI infrastructure. Japan’s market should increasingly combine mature enterprise demand with new AI-oriented capacity.
India is expected to record an estimated 18.5% CAGR between 2026 and 2031, making it one of the fastest-growing major markets in the regional model. Mumbai retains the strongest connectivity and financial-services ecosystem, while Chennai is developing as a second major location supported by submarine connectivity, cloud infrastructure and available development land. Hyderabad, Delhi-NCR and other locations should gradually increase their contribution as national cloud and enterprise demand expands.
South Korea benefits from highly developed telecommunications infrastructure, large technology companies and growing AI demand. Seoul and surrounding areas remain the principal infrastructure center, although future high-density development may become more geographically distributed according to electricity availability.
Indonesia records strong forecast growth as new hyperscale campuses move into operation. Greater Jakarta remains the primary market and benefits from a very large domestic digital economy. The shift toward projects measured in hundreds of megawatts indicates that the country is beginning to compete for regional hyperscale deployments alongside more established locations.
Thailand remains smaller in absolute market size but benefits from increasing cloud investment, digital-service demand and its position within mainland Southeast Asia. Continued infrastructure investment should support above-average growth, although the country remains below China, Japan, India, South Korea and Indonesia in total revenue.
Technology Outlook
High-Density Power and Liquid Cooling
Liquid cooling is moving from a specialized capability toward an increasingly standard requirement for AI-ready APAC facilities. Digital Realty’s NRT14 in Japan can support high-density colocation of up to 150 kW per rack using a hybrid liquid- and air-cooling environment. Operators designing new hyperscale facilities are increasingly incorporating cooling flexibility during construction rather than relying on later retrofits.
Energy-Efficient Tropical Data Center Design
Thermal-management efficiency is particularly important in Singapore, India, Malaysia and Indonesia. Singapore’s Tropical Data Centre Standard encourages higher operating temperatures where technically appropriate and provides guidance for reducing cooling energy without undermining equipment reliability. More efficient cooling can effectively increase the share of available electrical capacity used for computing, making thermal design directly relevant to facility economics.
Software-Defined and Multi-Cloud Interconnection
Colocation operators increasingly supplement physical cross-connects with software-defined connectivity that allows customers to establish connections to cloud platforms and other facilities more rapidly. This strengthens the role of carrier-neutral colocation as an exchange point between private infrastructure and public cloud environments and provides mature metropolitan facilities with an additional competitive advantage beyond physical space and electricity.
Recent Developments
April 2026: Princeton Digital Group acquired powered land in Greater Jakarta for its planned 240 MW JC4 campus, increasing its planned Indonesian portfolio to approximately 400 MW. Construction commenced with four planned 60 MW buildings.
April 2026: Equinix opened MB3 in Mumbai, adding more than 1,370 cabinets initially with the facility designed to scale beyond 5,475 cabinets. The project expands the company’s Indian capacity for AI, cloud and hybrid infrastructure.
April 2026: NTT DATA opened the 30 MW OSK11 facility in Keihanna, Japan, adding AI-ready capacity in the Osaka-Kyoto corridor and expanding infrastructure outside Greater Tokyo.
April 2026: Digital Realty opened NRT14 in Japan, increasing its NRT campus toward 100 MW of total IT power and introducing hybrid liquid and air cooling capable of supporting high-density GPU workloads.
September 2026: Singapore introduced the Digital Infrastructure Bill, establishing proposed licensing regimes for major data centers and cloud providers and a separate framework covering environmental sustainability of data center operations.
Competitive Landscape
The APAC colocation market contains a combination of global interconnection platforms, regional hyperscale specialists and country-focused operators. Equinix maintains strong carrier-neutral and enterprise positions across major regional metros, while Digital Realty combines interconnected facilities with larger hyperscale campuses. NTT Global Data Centers has a substantial regional footprint, particularly in Japan and other mature enterprise markets.
Asia-headquartered operators have developed increasingly large infrastructure platforms. Princeton Digital Group operates across seven markets and has expanded rapidly in Indonesia, India and other locations. AirTrunk has established a significant hyperscale presence across Australia and Asia, while ST Telemedia Global Data Centres participates across Singapore, India and other regional markets. Keppel Data Centres maintains an important position in Singapore and selected international markets.
India contains one of the region’s broadest domestic operator groups. Nxtra by Airtel, CtrlS Datacenters, Sify Technologies, Yotta Data Services and AdaniConneX compete alongside international providers across Mumbai, Chennai, Hyderabad and other developing locations. China remains structurally distinct, with GDS Holdings and VNET among its major domestic operators, while NEXTDC has a significant position in Australia and DCI Indonesia is an established domestic participant in Indonesia.
Competition through 2031 is expected to be increasingly determined by deliverable electrical capacity, high-density cooling capability, access to cloud and carrier ecosystems and the ability to support customers across several APAC markets. Facility count alone becomes a less useful measure as individual new campuses increase substantially in scale.
Analyst View
The APAC colocation market is developing into a multi-hub infrastructure system rather than a market dominated by a small number of established locations. Singapore, Tokyo, Sydney and other mature markets retain strategic value because of their connectivity, financial-services demand and cloud ecosystems, while India, Indonesia and other growth markets provide larger capacity pipelines. Customers increasingly use both types of locations, placing interconnected enterprise infrastructure in mature hubs while deploying larger compute requirements in markets where additional power can be secured.
AI accelerates this transition because electricity and cooling requirements are increasing faster than traditional rack density. A facility with unused floor space is not necessarily capable of supporting modern high-density computing. New buildings designed around liquid cooling and larger power allocations should therefore capture a disproportionate share of AI demand, while older facilities remain valuable for conventional enterprise and network infrastructure.
India represents the most important change in the regional country mix. Its forecast growth is supported not simply by internet adoption but by large-scale investment in cloud infrastructure, AI computing, financial services, enterprise digitalization and local capacity. Mumbai remains the primary hub, but a broader multi-city ecosystem should emerge through 2031.
Southeast Asia is similarly becoming more distributed. Singapore continues to control growth according to resource availability, preserving the value of efficient interconnected capacity while creating an economic incentive for larger campuses in Indonesia, Malaysia and other neighboring markets. Greater Jakarta’s transition toward campuses measured in hundreds of megawatts illustrates this evolution.
Asia Pacific (APAC) Colocation Market Scope
Report Metric
Details
Total Market Size in 2026
USD 23.32 billion
Total Market Size in 2031
USD 42.37 billion
Forecast Unit
Billion
Growth Rate
12.7%
Study Period
2021 to 2031
Historical Data
2021 to 2024
Base Year
2025
Forecast Period
2026 – 2031
Segmentation
Colocation Model, Enterprise Size, Industry Vertical, Country
Companies
Equinix
Inc.
Digital Realty
NTT Global Data Centers
AirTrunk
ST Telemedia Global Data Centres
Princeton Digital Group
Keppel Data Centres
Market Segmentation
By Colocation Type
·Retail Colocation
·Wholesale Colocation
By Enterprise Size
·Small Enterprises
·Medium Enterprises
·Large Enterprises
By End User
·Banking and Financial Services
·Communication & Technology
·Manufacturing
·Healthcare
·Energy
·Education
·Government
·Media & Entertainment
·Others
By Country
·China
·Japan
·India
·South Korea
·Indonesia
·Thailand
·Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
2.5. Key Market Indicators
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.2. Market Restraints and Challenges
3.3. Market Opportunities
3.4. Power Availability and Data Center Infrastructure Analysis
3.5. Regulatory and Sustainability Environment
3.6. Porter’s Five Forces Analysis
3.7. Industry Value Chain Analysis
3.8. Strategic Recommendations
4. TECHNOLOGY OUTLOOK
4.1. High-Density Power and Liquid Cooling
4.2. Energy-Efficient Tropical Data Center Design
4.3. Software-Defined and Multi-Cloud Interconnection
5. ASIA PACIFIC COLOCATION MARKET BY COLOCATION TYPE
5.1. Introduction
5.2. Retail Colocation
5.3. Wholesale Colocation
6. ASIA PACIFIC COLOCATION MARKET BY ENTERPRISE SIZE
6.1. Introduction
6.2. Small Enterprises
6.3. Medium Enterprises
6.4. Large Enterprises
7. ASIA PACIFIC COLOCATION MARKET BY END USER
7.1. Introduction
7.2. Banking and Financial Services
7.3. Communication & Technology
7.4. Manufacturing
7.5. Healthcare
7.6. Energy
7.7. Education
7.8. Government
7.9. Media & Entertainment
7.10. Others
8. ASIA PACIFIC COLOCATION MARKET BY COUNTRY
8.1. Introduction
8.2. China
8.3. Japan
8.4. India
8.5. South Korea
8.6. Indonesia
8.7. Thailand
8.8. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Competitive Positioning
9.2. Data Center Capacity and Geographic Footprint
9.3. AI-Ready Infrastructure and Interconnection Benchmarking
The APAC colocation market is forecasted to grow at a robust CAGR of 12.7%. This significant expansion will see the market's value increase from USD 23.32 billion in 2026 to an estimated USD 42.37 billion by 2031, driven by substantial infrastructure investment and demand across the region.
Wholesale colocation is the primary revenue driver, accounting for an estimated 53.2% of APAC market revenue in 2026, largely supported by hyperscale cloud deployments, AI infrastructure, and large dedicated capacity requirements. Additionally, the communication and technology sector represents an estimated 35.7% of market demand, reflecting infrastructure needs from cloud providers, telecommunications operators, internet platforms, and AI-related computing.
India is transitioning from a primarily enterprise-colocation market towards large-scale hyperscale and AI infrastructure, led by Mumbai and Chennai with expected further geographic expansion. Japan is increasingly coordinating electricity, telecommunications, and data center development as AI workloads elevate infrastructure requirements outside established Tokyo clusters. Indonesia is emerging as a significant hyperscale market, with operators securing sites capable of supporting several hundred megawatts of new capacity.
Beyond conventional rack capacity, key competitive differentiators now include liquid cooling, high-density electrical infrastructure, direct cloud connectivity, and access to reliable electricity. The market's development is increasingly shaped by computing intensity rather than only growth in data volumes, with AI workloads escalating electrical and thermal requirements per unit of computing space.
Large enterprises remain the largest direct customer category for colocation services in the APAC market. However, medium-sized enterprises are increasing their use of colocation through managed infrastructure and hybrid-cloud services, indicating a broader adoption across various business scales.
The market's development is increasingly shaped by computing intensity, rather than solely data volumes, with artificial intelligence significantly increasing electrical and thermal requirements per unit of computing space. This trend necessitates facilities designed for high-density electrical infrastructure and advanced cooling solutions, such as liquid cooling, to remain competitive and meet future demands.