
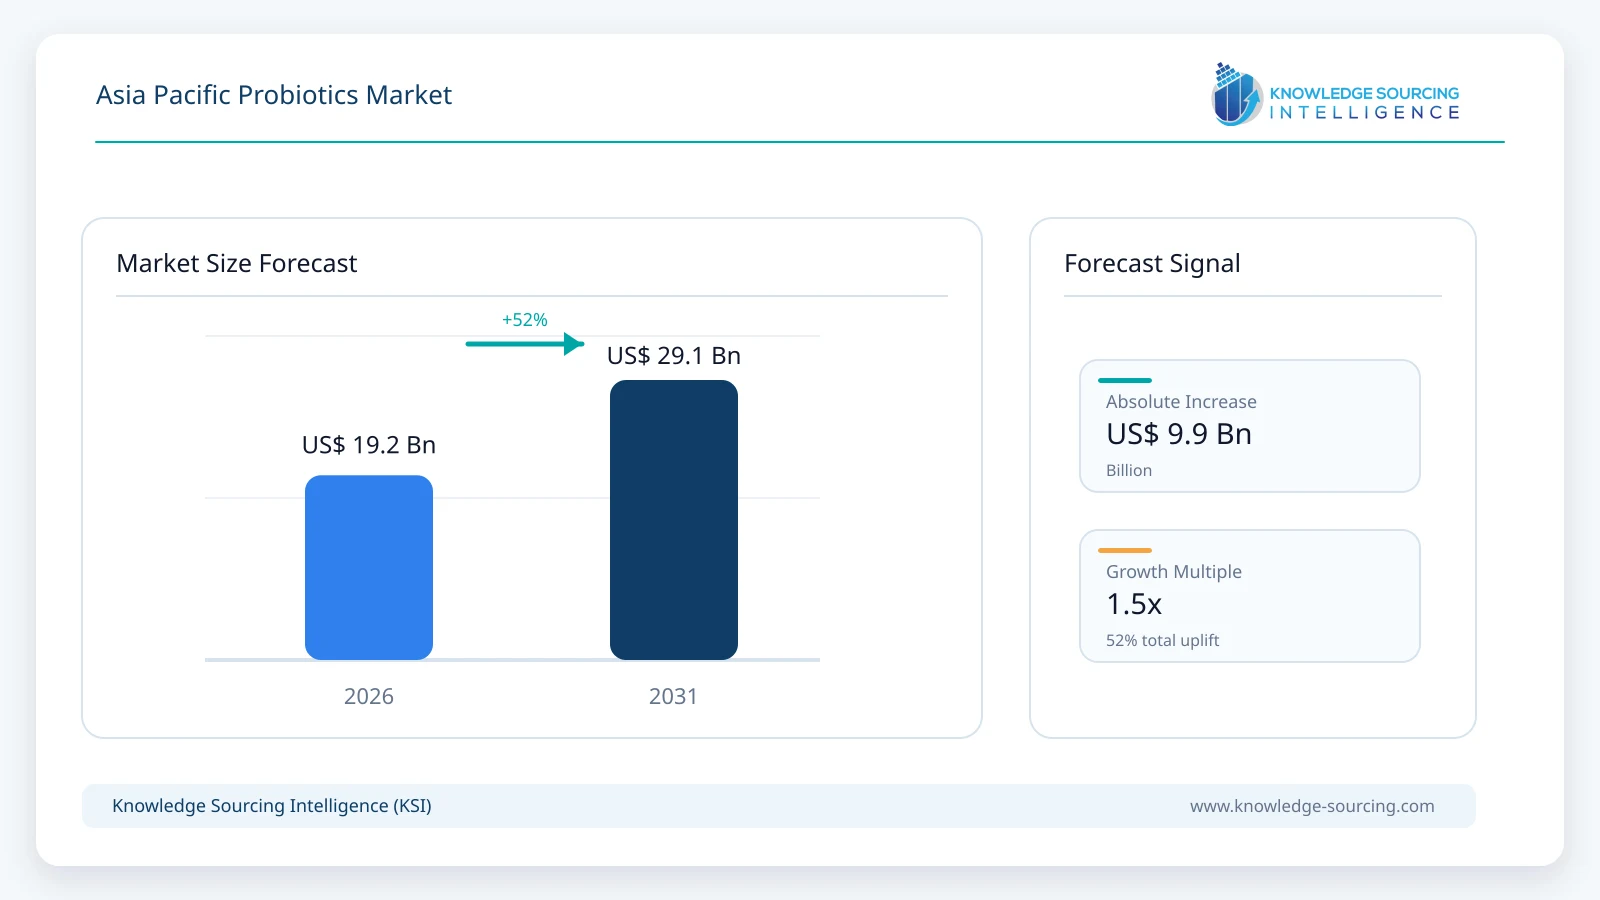
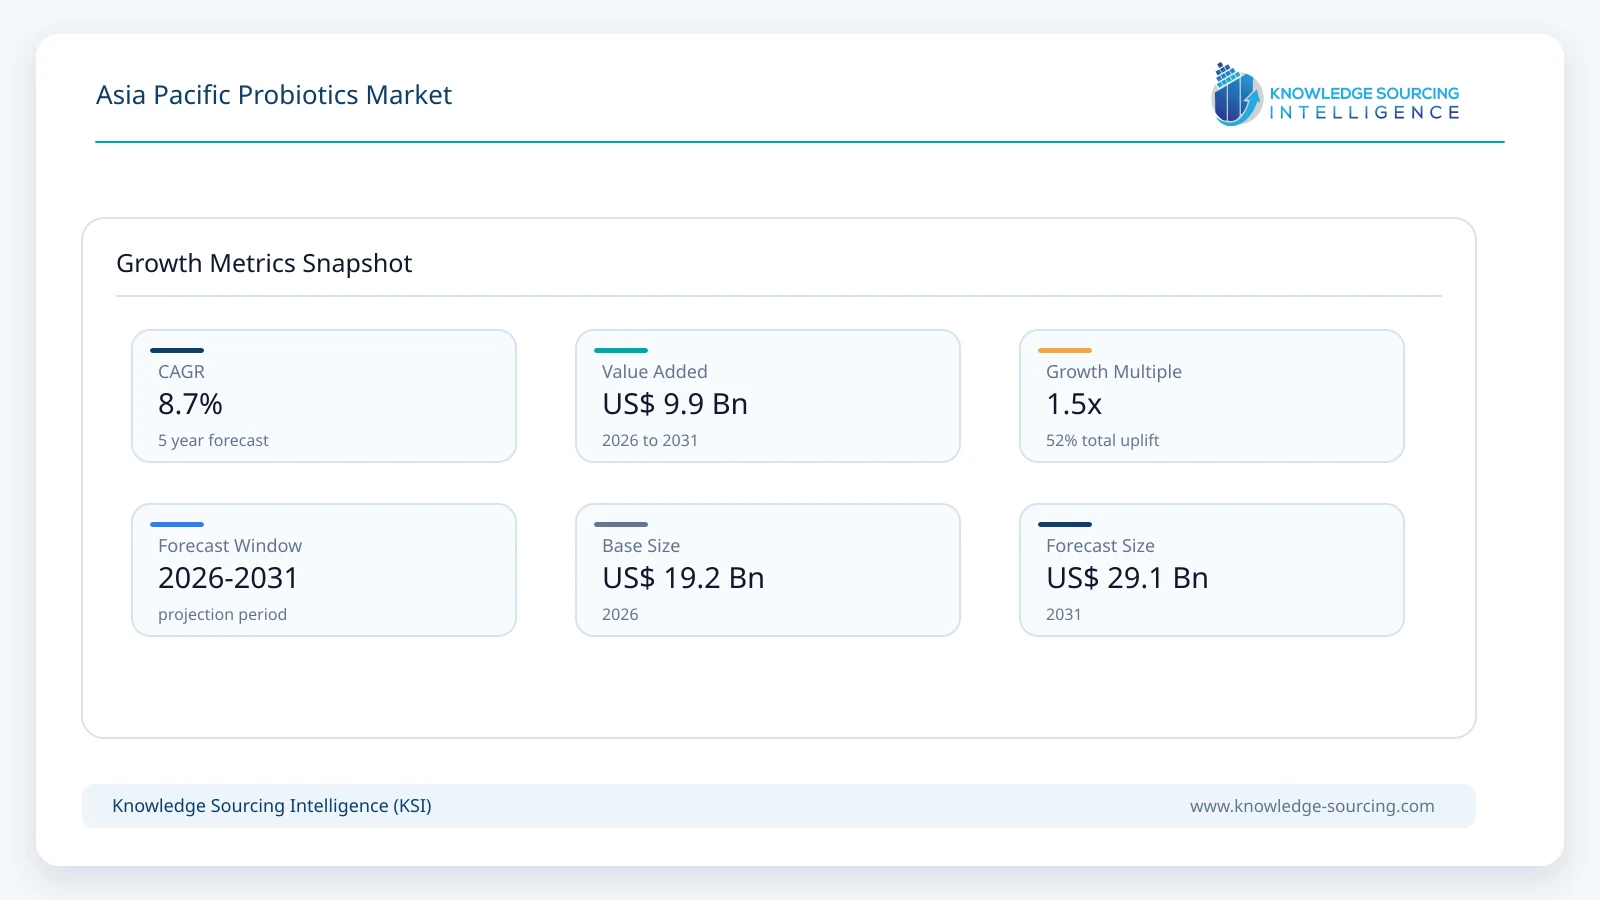
The Asia Pacific Probiotics Market is projected to expand at a CAGR of 8.67%, reaching USD 29.1 billion in 2031 from USD 19.2 billion in 2026.
Highlights:
- 1Lactobacillus remains the largest culture group, representing approximately 51% of 2026 market value.
- 2Liquid formats hold roughly 65% of 2026 sales through established beverages and dairy products.
- 3Functional foods and beverages contribute approximately 72% of 2026 value across Asia Pacific.
- 4Dry supplements gain distribution through pharmacies, specialist retail and digital marketplaces.
- 5Human-oriented probiotic products represent approximately 94.7% of 2026 market value.
The Asia-Pacific probiotics market encompasses finished products containing live microorganisms sold for a defined functional purpose, together with probiotic culture ingredients where the underlying finished product is not counted in the same revenue channel. Its principal outlets are probiotic beverages and foods, dietary supplements and microbial additives used in animal nutrition. Commercial performance depends on strain viability, product shelf life, consumer acceptance, distribution temperature and the regulatory treatment of product claims.
A regional network of beverage and dairy manufacturers competes alongside specialist culture developers and supplement brands. Yakult, Danone, Morinaga Milk and domestic dairy groups provide consumer products, while Novonesis, Probi and Lallemand supply characterized strains to brand owners. Multiple sales models coexist, but established retail beverages compete on repeat consumption and visibility, whereas supplement manufacturers increasingly rely on clinical dossiers, capsule stability and professional recommendation. Plant-based foods and livestock feed formulations widen the range of addressable customers without making all fermented products eligible for inclusion.
Market Overview
Yakult’s fiscal 2025 disclosures recorded JPY 136.2 billion in food-and-beverage sales in Asia and Oceania outside Japan, while its Japanese business reported JPY 229.6 billion. The company had previously disclosed average Asian and Oceanian sales of 21.93 million bottles a day in fiscal 2024. Those figures demonstrate the scale of a single specialized beverage producer, although the region’s wider probiotic market also contains cultured dairy, capsules, powders and supplier-developed strains. Established consumption is concentrated in countries with convenient cold distribution and familiar fermented-food categories; newer demand is being developed through consumer education, local tastes and smaller retail pack sizes.
Strain selection increasingly determines whether products can move into higher-value nutrition categories. Morinaga Milk markets Bifidobacterium strains for specific applications and announced an expansion of freeze-dried culture production in October 2026. Probi and Nomura Dairy Products introduced an LP299V-containing fermented carrot beverage in Japan in May 2025, showing that new formulations need not be dairy-based. An increasing proportion of innovation therefore comes from matching a documented microbial strain with a feasible product matrix, storage requirement and permitted product claim.
The commercial framework differs across the region. Indian probiotic foods are covered by FSSAI’s specialized food regulations, while Australian listed probiotic medicines operate under TGA requirements involving organism identity, quantity and quality. Producers serving several markets must adapt labels, claims and technical documentation without assuming that a strain approved in one jurisdiction is automatically eligible in another. Producers with local manufacturing, validated culture supplies and established routes to market can reduce execution risk, although rising trial and documentation costs may favor larger companies.
Market Trends
Strain-Specific Science Is Influencing Product Selection
Probiotic brands increasingly identify the organism and strain used in their formulation rather than relying on an undifferentiated digestive-health label. Morinaga Milk’s BB536 and B-3 work, Probi’s LP299V research and Yakult’s Lacticaseibacillus paracasei strain Shirota illustrate how manufacturers build recognizable strain portfolios. The distinction matters commercially: clinical data, manufacturing consistency, and intellectual property can support differentiation in a crowded supplement category.
Clinical studies do not establish identical benefits for every formulation or consumer group. Claims require evaluation at the actual dose, population, and endpoint studied. Suppliers capable of linking product specifications to strain-level evidence can provide brand owners with more credible formulations, while companies offering only generic blends face greater comparison on price and capsule count.
Flavor Innovation Is Extending Mature Beverage Franchises
Yakult has used localized flavors to defend and develop markets with established fermented-milk consumption. In 2025, the company discussed new mango-flavored product performance in Indonesia and a recovery in Chinese sales volumes. Its 2026 news archive also records mango, peach and strawberry variants for China, Vietnam and Indonesia, reflecting adaptation of taste and pack preferences rather than a change in underlying probiotic technology.
For beverage producers, flavor extensions can refresh repeat purchasing through existing distribution networks at lower cost than building a completely new product category. However, sugar content, shelf life and affordability still influence repeat demand, and premium variants are not assured of displacing inexpensive everyday drinks. Country-level forecast assumptions therefore reflect different maturity and consumption conditions.
Dry Formats Are Widening Use Beyond Chilled Dairy
Freeze-dried probiotics can be formulated into capsules, sachets and powdered nutrition products that travel through retail and e-commerce channels without the same distribution model as refrigerated drinks. Morinaga Milk’s planned production expansion for bifidobacteria and other cultures illustrates investment in upstream capacity for these applications. Product development still requires stable viable counts during processing and at the end of shelf life.
Ingredient suppliers earn a different type of revenue from consumer brand owners, typically based on culture identity, formulation support and manufacturing supply contracts. The value of a culture sold to a beverage producer should not be added again to the full retail value of the beverage. Growth in dry formats is consequently evaluated through finished supplement demand and direct ingredient sales in channels where there is no overlapping finished product.
Market Access Is Shaped by Local Regulatory Definitions
India’s FSSAI framework treats probiotic foods as a defined category, while Australia’s TGA guidance addresses strain characterization, viable-organism measurement and quality of listed probiotic medicines. Requirements differ between conventional foods and therapeutic goods, so the same package design and promotional statement cannot automatically be used in both.
Stronger documentation may improve trust but can also delay product adaptation. Manufacturers that develop validated assays, stability data and jurisdiction-specific labels at the formulation stage can shorten later registration work. Retailers and consumers may benefit from clearer identification of cultures, provided health claims remain tied to appropriate evidence rather than speculative microbiome outcomes.
Animal Nutrition Is Establishing a Distinct Probiotic Channel
Livestock and aquaculture feed formulators are assessing microbial additives for gut health and feed performance. These products differ substantially from consumer probiotic drinks: the buyers are commercial feed producers and farms, dose delivery occurs through feed or water, and performance must be evaluated under practical husbandry conditions.
The supplier opportunity is linked to standardized concentrated cultures, manufacturing tolerance and documented performance in target species. Antibiotic-use policy and farm economics may strengthen interest, but probiotic additives should not be treated as direct replacements for veterinary medicines without an applicable evidence base. Producers must also account for feed-processing temperatures and the compatibility of strains with other ingredients.
Segment Analysis
By Type: Lactobacillus
Lactobacillus-derived products contribute an estimated USD 9.80 billion in 2026, making them the largest type group in the region. The category includes products based on established lactic-acid bacteria used in probiotic drinks, functional dairy and supplements. Yakult and Probi illustrate two different commercial routes: the former operates finished beverage brands, while the latter provides characterized strains used by other producers. Many species formerly classified under Lactobacillus have been reassigned to new genera; commercial taxonomy must therefore be reconciled to a consistent classification.
The type group is expected to reach approximately USD 14.45 billion in 2031. That expansion is linked to wider distribution and greater product variety rather than uniform growth across strains. A producer with a robust stability process and a distinguishable strain can maintain pricing more effectively than a commodity culture supplier, particularly when labels and permitted claims require detailed organism identification.
By Form: Liquid
Liquid probiotic products remain the largest format because regular beverage purchases support high transaction frequency and established supermarket and delivery distribution. Yakult’s daily bottle sales show the persistence of this business model, particularly in Japan and Southeast Asia. Refrigeration requirements, distribution density and the price per serving shape where the format can scale.
Liquid products are projected to reach USD 17.40 billion by 2031, although their share moderates as dry supplement formats expand more quickly. Dairy-based drinks remain commercially important, but producers are also adapting sugar levels and exploring alternative matrices. The volume advantage of liquids is balanced by transport weight, spoilage risk and consumer willingness to purchase a product repeatedly.
By Application: Functional Food & Beverages
Functional food and beverages are projected to reach USD 19.55 billion in 2031, continuing to generate the largest proportion of probiotic-product sales in the region. They combine habitual food consumption with a recognizable strain or active-culture positioning, including fermented-milk drinks and selected cultured foods. The category deliberately excludes generic fermented products sold without qualifying probiotic positioning, preventing the inclusion of unrelated dairy turnover.
Product innovation is increasingly specific to local eating and drinking habits. Probi’s partnership with Nomura Dairy on an LP299V fermented carrot drink shows how a culture can be introduced into a nontraditional beverage. Manufacturers must nevertheless balance flavor, acidity, and processing treatment against organism survival, because a formulation that loses viability may not deliver the product described on its label.
By End-User: Human
Human consumption dominates regional demand. Consumer products cover drinks, cultured foods and supplements intended for different age groups and health interests, with higher-volume beverage consumption offset by more expensive supplement purchases. The dominant buying decisions are influenced by brand familiarity, taste, price, confidence in safety and distribution accessibility.
By 2031, human-oriented products are estimated to reach USD 27.24 billion. Growth is expected to be supported by evidence-backed ingredients and emerging demand in India, Vietnam and Indonesia, but producers will still have to justify premium prices against conventional foods. Claims around complex conditions require particular discipline: demonstrated digestive or immune-related outcomes for a specific strain do not automatically establish effectiveness for obesity or chronic disease treatment.
Market Drivers
Established Consumption of Probiotic Beverages
Japan, China and several Southeast Asian markets have a long history of cultured-milk purchasing, which provides a large distribution base for probiotic brands. Yakult’s substantial Japanese and Asia-Oceania sales show how high purchase frequency can support scale even when growth in individual countries slows. Repeat consumption and retailer visibility give manufacturers a basis for introducing new flavors or package sizes without rebuilding consumer familiarity.
Growth depends on retaining shoppers in mature markets while extending affordable availability in underpenetrated urban and secondary locations. High transport costs and pressure from substitutes can reduce the benefit of incremental volumes.
Higher Investment in Characterized Cultures
Strain identity, viable counts and formulation stability are increasingly central to product development. Morinaga Milk’s October 2026 expansion decision and Probi’s work with documented strains are examples of producer investment in this capability. Ingredient suppliers offering reproducible production and technical formulation support can address multiple brand customers across national markets.
The resulting commercial advantage lies in reducing formulation failure and supporting defensible consumer information. Higher R&D expense also makes efficient production and long-term customers important.
Broader Distribution for Supplement Formats
Capsules, tablets and sachets allow probiotic products to be sold in pharmacies, organized retail and digital commerce without the logistics required for short-shelf-life fermented drinks. India and South Korea are commercially relevant because consumers already purchase a wide range of nutritional supplements, creating natural points of distribution for probiotic products.
The expansion is not equivalent to automatic use: purchase conversion depends on clarity of strain information, product pricing, shelf-life assurance and the evidence behind particular claims.
Localized Product Development in Southeast Asia
Consumer preferences differ substantially between Indonesia, Vietnam, China and Japan. Yakult’s regional product and flavor initiatives show that local adaptation can increase sales through the same production and distribution architecture. Suppliers also adjust sweetness, serving size and formats to fit income levels and consumption occasions.
Localized launches can increase trial and repeat purchases, although manufacturers must manage inventory complexity and ensure that formulation changes do not compromise viable culture levels.
Animal Feed Producers Seeking Targeted Additives
Probiotic inputs can enter animal nutrition as concentrated microbial additives selected for resilience and species-specific performance. Asian aquaculture and livestock industries provide large potential feed-processing bases, while suppliers have opportunities to improve handling stability and provide technical support.
Commercial adoption remains tied to documented feed outcomes and price-per-tonne economics, rather than an assumption that all producers will replace other feed additives.
Market Restraints
Difficulties Maintaining Viability Through Shelf Life
Processing temperature, acidity, oxygen exposure and distribution conditions can lower the number of viable organisms delivered to consumers. Manufacturers must validate stability under the intended packaging and storage conditions, and an initially high microbial count does not eliminate end-of-life testing.
Where the cold chain is inconsistent, wastage and returns can materially erode margins on liquid products.
Restrictions on Health Claims and Strain-Level Evidence
National regulators do not treat all probiotic foods and supplements as identical. Australian guidance emphasizes organism characterization and quality, while Indian rules establish a specific regulatory category for probiotic foods. Claims involving the treatment or prevention of disease need an appropriate regulatory basis and evidence.
Brands therefore incur added costs for label revision, dossier preparation and market-specific approvals.
Consumer Price Sensitivity and Functional-Food Substitutes
Probiotic products compete with standard yogurt, fermented foods, ordinary supplements and other beverages. Rising household costs can shift purchasing toward lower-priced alternatives, especially if consumers cannot distinguish the documented value of a proprietary strain.
Premium pricing is more sustainable where product information is clear and repeated consumption has an established place in the household budget.
Manufacturing and Quality-Control Complexity
Multistrain products require testing for identity, contamination, and potency throughout manufacturing. Production-scale fermentation and freeze-drying can introduce variability, particularly when formulations are adapted to local ingredients and processing environments.
Quality failures can lead to rejected batches, disrupted retailer supplies, and reputational damage even before regulatory penalties are considered.
Uneven Clinical Evidence Across Applications
Research findings for a single strain and study population cannot be extended automatically to all probiotic products. Some applications have limited or inconsistent evidence, and claims related to weight management or broad immune enhancement may be particularly vulnerable to overstatement.
Poorly substantiated positioning can weaken consumer trust and increase regulatory scrutiny, raising the need for conservative communication and continued product testing.
Regional Outlook
China: Largest Country Market
China accounts for an estimated USD 5.75 billion of Asia-Pacific probiotics sales in 2026, supported by a wide market for cultured drinks, functional dairy and nutritional supplements. Yakult operates local production and sales networks, while Chinese dairy groups serve consumers through extensive refrigerated distribution. A mature beverage base does not guarantee strong near-term growth: Yakult previously reported restructuring its Shanghai business after a period of weaker consumption, showing that brand positioning and retail economics require continued attention.
The Chinese market is expected to reach USD 8.10 billion by 2031, with future value increasingly influenced by clinically positioned supplements and differentiated drinks. Competition for shelf space, changing product claims and consumer interest in lower-sugar options will affect product mix. Producers with local culture manufacturing and stable distribution can respond faster to price and flavor preferences, but international brands must continue to adapt to domestic rivals and evolving oversight.
India: Fastest-Growing Country Market
India is projected to expand at approximately 15.74% annually through 2031, as probiotic products widen beyond established urban dairy and pharmacy channels. Yakult’s local operations and domestic dairy brands provide the consumer infrastructure for drinks and cultured foods, while dry formats can reach a broader geographic market through pharmacies and online retailers. FSSAI’s distinct probiotic food category requires manufacturers to define product composition and communicate claims appropriately, increasing the value of regulatory and formulation expertise.
The modeled market approaches USD 4.05 billion in 2031, supported by rising packaged-product availability and more diverse consumption occasions. Sales remain constrained by price sensitivity, heat exposure during distribution and differences in awareness between major cities and smaller towns. Companies able to provide affordable pack sizes, reliable viable counts and locally relevant formulations will be better placed to convert initial trial into routine demand.
Competitive Landscape
The competitive structure combines consumer-product manufacturers, specialist probiotic ingredient producers and companies serving feed formulators. Yakult and Danone bring branded consumer distribution and established fermentation expertise. Morinaga Milk and Meiji connect culture science to dairy and nutrition products, while Chinese dairy groups including Yili and Mengniu have extensive domestic retail reach. Brand owners typically control packaging, consumer claims and channel relationships; their supplier agreements determine where culture-development companies participate in the value chain.
Novonesis, Probi and Lallemand compete through strain selection, technical support, production quality and documented clinical use. Probi’s 2025 collaboration with Nomura Dairy illustrates how ingredient producers can enter a local consumer category without manufacturing every finished item themselves. BioGaia operates branded probiotic solutions with differentiated strains, while larger nutrition groups including Nestlé distribute probiotic-containing products within broader portfolios. Company participation should not be interpreted as a ranking of probiotic-specific market shares, because disclosed corporate turnover generally includes substantial non-probiotic revenue.
Product competition is likely to intensify around distinct evidence packages, manufacturing stability, permitted health claims and distribution costs. New entrants can formulate products from external cultures but still face substantial technical and marketing costs to establish repeat purchase. The most durable positions are therefore expected among companies able to combine credible strain characteristics with an affordable consumer proposition and consistent shelf availability.
Recent Developments
1 October 2026: Morinaga Milk Industry approved an investment to expand bifidobacteria and lactic-acid bacteria production at its Fukui facility, with planned group capacity of approximately 250 tonnes annually when the new capacity becomes operational in 2029.
28 July 2026: Morinaga Milk reported that Bifidobacterium breve B-3 received an individual-recognition registration for cognitive-health positioning in South Korea, extending its strain-specific commercial options.
1 July 2026: Probi, now part of Symrise, highlighted its expanded health-positioning portfolio and the published research supporting its LP299V strain, marking continued investment in differentiated probiotic ingredients.
18 June 2026: Morinaga Milk published new findings on Bifidobacterium longum BB536 in yogurt, reporting exploratory results when consumption was combined with lifestyle changes; this was research evidence, not a new medical approval.
7 May 2025: Probi and Nomura Dairy Products introduced a fermented carrot beverage containing LP299V in Japan, demonstrating an additional nontraditional food matrix for a characterized strain.
Market Outlook
The regional market is expected to remain predominantly consumer-oriented, with beverages and cultured foods providing the principal revenue base. Further growth will depend less on awareness campaigns alone and more on product propositions supported by viable-count assurance, recognizable strains and convenient distribution. India and parts of Southeast Asia can expand through consumption frequency and broader retail reach, while Japanese and Chinese producers are likely to rely more heavily on formulation improvements, channel efficiency and higher-value products.
Dry supplement formats should gain share as producers offer more stable, targeted formulations through specialist retail and digital channels. Culture suppliers will seek long-term manufacturing relationships with brand owners, although contract prices and the degree of ingredient differentiation will vary substantially. Animal nutrition remains a smaller but faster-growing outlet, subject to evidence of performance under real feed-processing and farming conditions. Across all uses, the companies best positioned for sustained growth are those that manage cost, product stability, and country-specific compliance alongside clinically responsible marketing.
Asia Pacific Probiotics Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 19.2 billion |
| Total Market Size in 2031 | USD 29.1 billion |
| Forecast Unit | Billion |
| Growth Rate | 8.67% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Type, Form, Application, End-user |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Type
Lactobacillus
Streptococcus
Bifidobacterium
Spore Formers
Others
By Form
Liquid
Dry
By Application
Functional Food & Beverages
Dietary Supplement
Animal Feed
By End-user
Human
Animal
By Geography
China
Japan
South Korea
India
Australia
Indonesia
Vietnam
Others
Table of Contents
1. EXECUTIVE SUMMARY
1.1. Key Findings
1.2. Market Size and Forecast, 2026–2031
1.3. Segment and Country Outlook
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Established Consumption of Probiotic Beverages
3.1.2. Higher Investment in Characterized Cultures
3.1.3. Broader Distribution for Supplement Formats
3.1.4. Localized Product Development in Southeast Asia
3.1.5. Animal Feed Producers Seeking Targeted Additives
3.2. Market Restraints
3.2.1. Difficulties Maintaining Viability Through Shelf Life
3.2.2. Restrictions on Health Claims and Strain-Level Evidence
3.2.3. Consumer Price Sensitivity and Functional-Food Substitutes
3.2.4. Manufacturing and Quality-Control Complexity
3.2.5. Uneven Clinical Evidence Across Applications
3.3. Market Opportunities
3.4. Porter’s Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Strain Characterization and Clinical Documentation
4.2. Fermentation, Freeze Drying and Viability
4.3. Product Stability and Functional Food Formulation
4.4. Quality Control, Labelling and Regulatory Compliance
5. ASIA PACIFIC PROBIOTICS MARKET BY TYPE
5.1. Introduction
5.2. Lactobacillus
5.2.1. Market Trends and Opportunities
5.2.2. Growth Prospects
5.3. Streptococcus
5.3.1. Market Trends and Opportunities
5.3.2. Growth Prospects
5.4. Bifidobacterium
5.4.1. Market Trends and Opportunities
5.4.2. Growth Prospects
5.5. Spore Formers
5.5.1. Market Trends and Opportunities
5.5.2. Growth Prospects
5.6. Others
5.6.1. Market Trends and Opportunities
5.6.2. Growth Prospects
6. ASIA PACIFIC PROBIOTICS MARKET BY FORM
6.1. Introduction
6.2. Liquid
6.2.1. Market Trends and Opportunities
6.2.2. Growth Prospects
6.3. Dry
6.3.1. Market Trends and Opportunities
6.3.2. Growth Prospects
7. ASIA PACIFIC PROBIOTICS MARKET BY APPLICATION
7.1. Introduction
7.2. Functional Food & Beverages
7.2.1. Market Trends and Opportunities
7.2.2. Growth Prospects
7.3. Dietary Supplement
7.3.1. Market Trends and Opportunities
7.3.2. Growth Prospects
7.4. Animal Feed
7.4.1. Market Trends and Opportunities
7.4.2. Growth Prospects
8. ASIA PACIFIC PROBIOTICS MARKET BY END-USER
8.1. Introduction
8.2. Human
8.2.1. Market Trends and Opportunities
8.2.2. Growth Prospects
8.3. Animal
8.3.1. Market Trends and Opportunities
8.3.2. Growth Prospects
9. ASIA PACIFIC PROBIOTICS MARKET BY GEOGRAPHY
9.1. Introduction
9.2. China
9.2.1. Market Trends and Opportunities
9.2.2. Growth Prospects
9.3. Japan
9.3.1. Market Trends and Opportunities
9.3.2. Growth Prospects
9.4. South Korea
9.4.1. Market Trends and Opportunities
9.4.2. Growth Prospects
9.5. India
9.5.1. Market Trends and Opportunities
9.5.2. Growth Prospects
9.6. Australia
9.6.1. Market Trends and Opportunities
9.6.2. Growth Prospects
9.7. Indonesia
9.7.1. Market Trends and Opportunities
9.7.2. Growth Prospects
9.8. Vietnam
9.8.1. Market Trends and Opportunities
9.8.2. Growth Prospects
9.9. Others
9.9.1. Market Trends and Opportunities
9.9.2. Growth Prospects
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Mergers, Acquisitions, Agreements and Collaborations
10.4. Competitive Dashboard
11. COMPANY PROFILES
11.1. Yakult Honsha Co., Ltd.
11.2. Danone S.A.
11.3. Nestlé S.A.
11.4. Morinaga Milk Industry Co., Ltd.
11.5. Meiji Holdings Co., Ltd.
11.6. Novonesis A/S
11.7. Probi AB
11.8. BioGaia AB
11.9. Lallemand Inc.
11.10. International Flavors & Fragrances Inc.
11.11. Inner Mongolia Yili Industrial Group Co., Ltd.
11.12. China Mengniu Dairy Company Limited
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations





Frequently asked questions
What is the projected growth of the Asia Pacific Probiotics Market?
The Asia Pacific Probiotics Market is projected to reach USD 29.1 billion by 2031 at an 8.67% CAGR.
Which product format holds the largest market share?
Liquid formats hold approximately 65% of 2026 sales.
Which probiotic culture group dominates the market?
Lactobacillus remains the largest culture group, representing 51% of 2026 value.
What is the primary application area for probiotics in Asia Pacific?
Functional foods and beverages contribute approximately 72% of 2026 value.
What factors influence commercial performance in the market?
Strain viability, shelf life, consumer acceptance, and regulation are key.
What was the Asia Pacific Probiotics Market value in 2026?
The Asia Pacific Probiotics Market was valued at USD 19.2 billion in 2026.
Cite this report
Knowledge Sourcing Intelligence. (Oct 2026). Asia Pacific Probiotics Market - Strategic Insights and Forecasts (2026–2031). https://www.knowledge-sourcing.com/report/asia-pacific-probiotics-market