
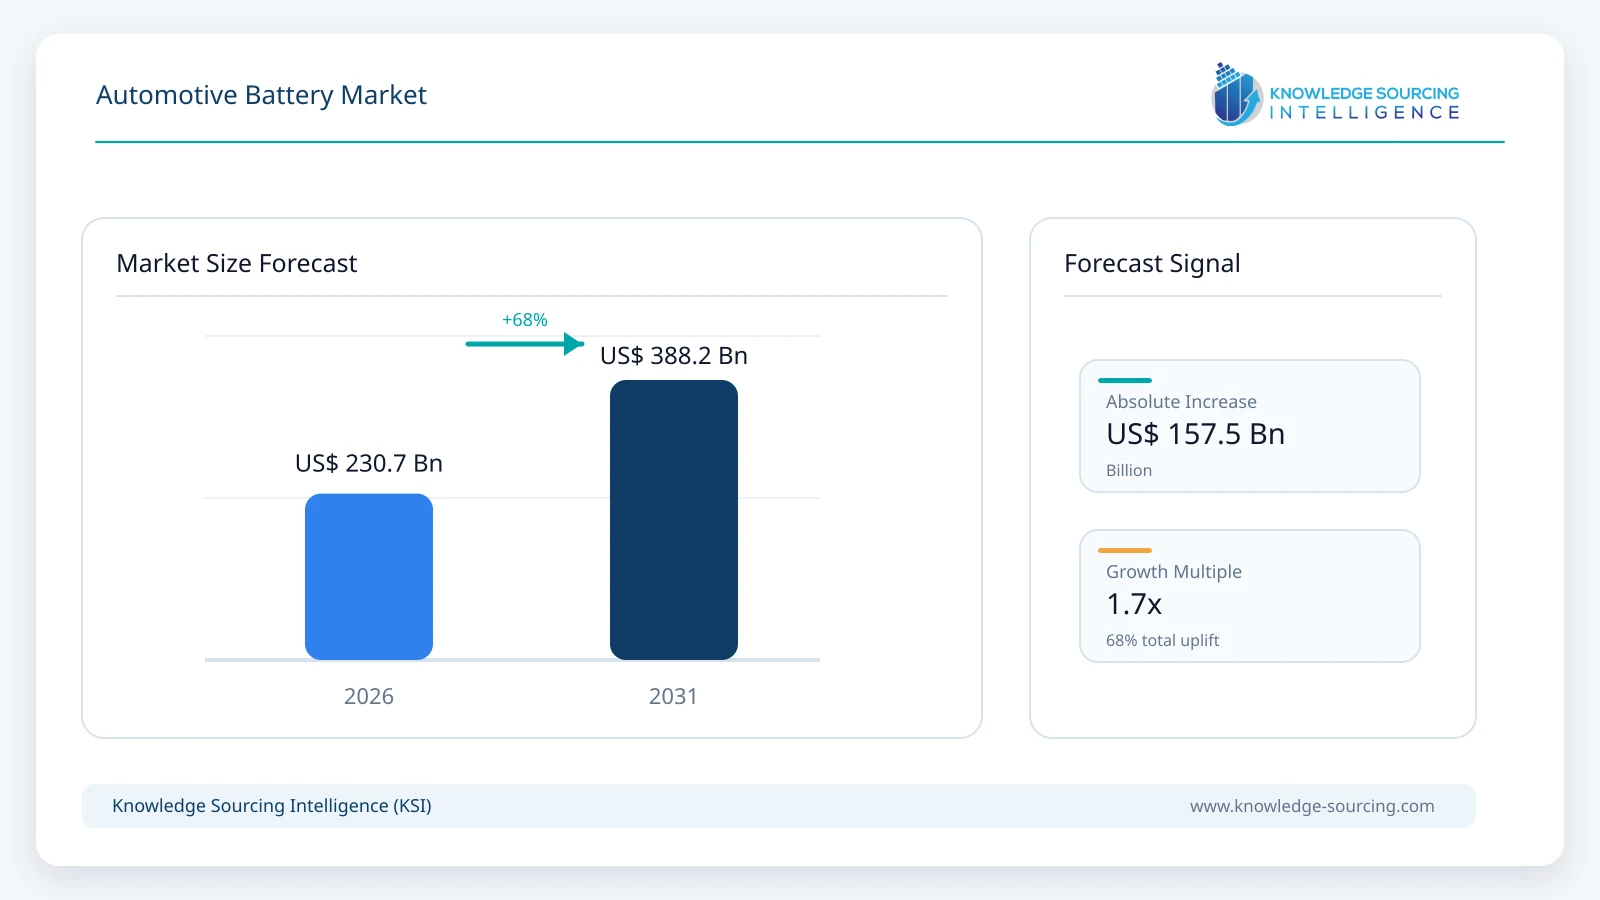
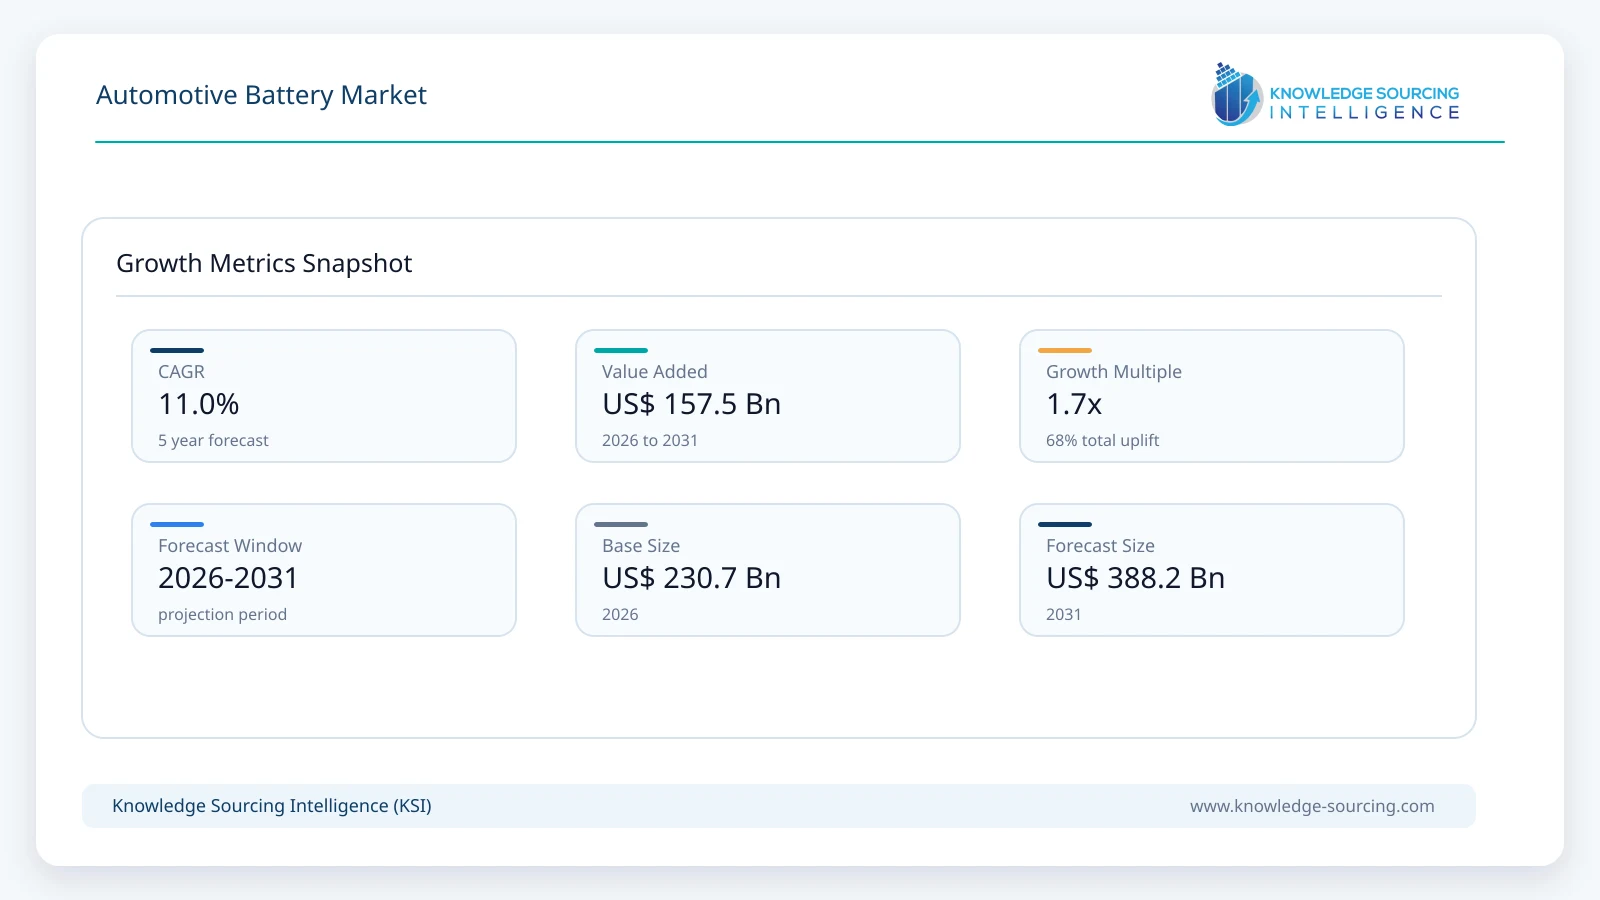
The automotive battery market is anticipated to grow at a CAGR of 11%, from USD 230.7 billion in 2026 to USD 388.2 billion by 2031.
Highlights:
- 1Lithium-ion batteries account for approximately 85% of global automotive battery value in 2026.
- 2Passenger cars generate approximately USD 180 billion of automotive battery demand in 2026.
- 3Battery electric vehicle applications are projected to grow at about 13.2% annually through 2031.
- 4Original equipment manufacturers account for approximately 84% of global market value in 2026.
- 5Asia Pacific generates approximately USD 138 billion of automotive battery revenue in 2026.
- 6Sodium-ion and solid-state technologies are moving from development into early automotive deployment.
Automotive batteries perform different functions depending on vehicle architecture. A conventional internal combustion vehicle mainly uses a low-voltage battery for engine starting and electrical support. Hybrid vehicles add higher-voltage energy storage for regenerative braking and electric assistance. Plug-in hybrids require larger traction batteries that support meaningful electric-only driving. Battery electric vehicles rely on the traction battery as their primary energy source and also use a separate low-voltage battery for control systems, safety functions and accessories.
The high-voltage side of the market is expanding rapidly. The International Energy Agency reported that electric vehicle battery deployment reached 1.2 TWh in 2025, up almost 30% from 2024. Light-duty vehicles represented more than 85% of deployment. The agency expects EV battery demand to approach 3 TWh by 2030 under current and stated policy scenarios. Battery prices continued to decline in 2025, although regional differences widened and lithium and cobalt prices moved higher again at the beginning of 2026.
Low-voltage automotive batteries remain commercially important despite electrification. Clarios reported about USD 10.6 billion of revenue in fiscal 2025 and sold more than 150 million batteries, with roughly 80% of revenue coming from the aftermarket. GS Yuasa reported more than JPY 372 billion of automotive lead-acid battery sales in the year ended March 2026. The company expects automotive lead-acid demand to remain close to current levels well into the next decade because nearly every vehicle still requires a low-voltage electrical system.
Battery Technology Snapshot
Technology | Current Role | Market Direction |
Lithium-ion | Primary traction battery for BEVs and PHEVs | Fast growth with LFP, NCM and new pack architectures |
Lead-acid / AGM / EFB | Low-voltage starting and auxiliary systems | Stable replacement demand with higher cycling requirements |
Nickel-metal hydride | Selected hybrid-electric platforms | Mature niche supported by proven hybrid applications |
Sodium-ion / solid-state | Early commercial and development-stage automotive use | Emerging route for cost, safety, cold-weather and energy-density gains |
Market Trends
Lithium iron phosphate is becoming the default chemistry for a larger share of mass-market electric vehicles
Lithium iron phosphate is gaining share because it avoids nickel and cobalt, offers strong cycle life and has reached sufficient energy density for many mainstream vehicles. The International Energy Agency reported that LFP accounted for more than 55% of global EV battery deployment in 2025. Chinese manufacturers remain the technology leaders, but localization is expanding in North America and Europe. The change is increasing competition on charging speed, pack integration and manufacturing efficiency rather than chemistry alone.
Fast charging is becoming a major competitive target across battery chemistries
Battery suppliers are reducing charging time through cell chemistry, thermal control and higher-voltage vehicle architectures. CATL introduced its third-generation Shenxing battery in April 2026 and stated that the system can move from 10% to 80% state of charge in less than four minutes under specified conditions. Automakers are also moving toward 800-volt and 1,000-volt platforms. Faster charging improves vehicle usability but increases the importance of heat management, charger capability and long-term cell durability.
Multi-chemistry portfolios are replacing the idea of one battery chemistry for every vehicle
Battery suppliers are widening chemistry portfolios to match cost, range, climate and performance requirements. CATL is developing LFP, high-nickel, sodium-ion and hybrid chemistry systems in parallel. Samsung SDI is using high-nickel NCM for performance-oriented electric vehicles while adding LFP capability. LG Energy Solution is expanding both NCM and LFP capacity. This approach allows manufacturers to optimize batteries by vehicle class rather than forcing one technology across all platforms.
Market Drivers
Electric vehicle sales are creating a much larger high-voltage battery demand base
Global electric car sales exceeded 20 million units in 2025 and represented one-quarter of new car sales, according to the International Energy Agency. Europe strengthened further in 2026. Battery-electric cars reached 20.7% of European Union registrations during the first half of the year, while plug-in hybrids reached 9.8%. Each additional electric vehicle adds a traction battery that is far more valuable than the low-voltage battery used in a conventional vehicle. This changes the value mix of the automotive battery market even when total vehicle production grows slowly.
The installed vehicle fleet sustains low-voltage replacement demand
Low-voltage batteries remain a recurring maintenance item. They are replaced several times during the life of a vehicle and are required in internal combustion, hybrid and battery electric vehicles. Europe had 256 million passenger cars, 31.1 million vans and 6.2 million trucks on the road in 2024. Similar replacement demand exists across North America, China, India and other large vehicle markets. Advanced driver assistance, connectivity and start-stop systems are also increasing electrical loads, supporting higher-value low-voltage battery formats.
Regional battery manufacturing and supply-chain localization support new investment
Automakers are seeking battery production closer to vehicle assembly to reduce logistics risk and satisfy local-content rules. LG Energy Solution began production at its Lansing, Michigan plant in August 2026 and plans more than 35 GWh of annual capacity at full scale. Panasonic Energy continues to expand North American automotive battery manufacturing, while CATL, Samsung SDI, SK On and other suppliers are building regional production networks. Localization also extends upstream to lithium, cathode materials and recycling.
Market Restraint
Price pressure, overcapacity and raw-material volatility can weaken returns on new battery investment
The battery industry is adding manufacturing capacity faster than demand in some regions. This creates lower utilization and strong price competition. The International Energy Agency reported more than 4 TWh of global lithium-ion nameplate capacity by the end of 2025, compared with 1.2 TWh of EV battery deployment during the year. Lithium and cobalt prices also increased again in early 2026 after earlier declines. Producers therefore face a difficult balance between lowering prices, maintaining margins and funding new technology and regional manufacturing.
Segment Analysis
By Technology - Lithium-Ion
Lithium-ion batteries form the largest technology segment because they are the dominant traction technology for battery electric and plug-in hybrid vehicles. The segment is projected to reach approximately USD 345 billion by 2031. LFP provides a lower-cost route for mainstream vehicles, while high-nickel chemistries remain important where maximum energy density is required. Cylindrical, prismatic and pouch formats continue to coexist because automakers use different vehicle architectures and manufacturing strategies.
By Vehicle Type - Passenger Cars
Passenger cars are the largest vehicle-type segment because they account for most electric vehicle sales and the largest share of the global vehicle parc. The segment is projected to grow at approximately 10.6% annually through 2031. Demand is being supported by battery electric cars, plug-in hybrids and the continuing replacement of low-voltage batteries in conventional vehicles. Higher battery capacity in sport utility vehicles also raises average battery value per vehicle.
By Application - Battery Electric Vehicles
Battery electric vehicles are the largest application by market value because the traction battery is one of the highest-value components in the vehicle. The segment accounts for approximately 62% of global automotive battery value in 2026. Battery size varies by region and vehicle class, with larger packs common in North America and smaller average packs in China. Continued cost reduction and faster charging are making battery electric models more competitive across a wider range of passenger and commercial vehicles.
By End User - Original Equipment Manufacturer
Original equipment manufacturers form the largest end-user segment because traction batteries are installed during vehicle production and are typically supplied through long-term automotive qualification programs. The segment is projected to reach approximately USD 326 billion by 2031. The aftermarket remains important for low-voltage battery replacement and will gradually develop for traction-battery repair, remanufacturing and replacement as the electric vehicle fleet ages.
By Geography - Asia Pacific
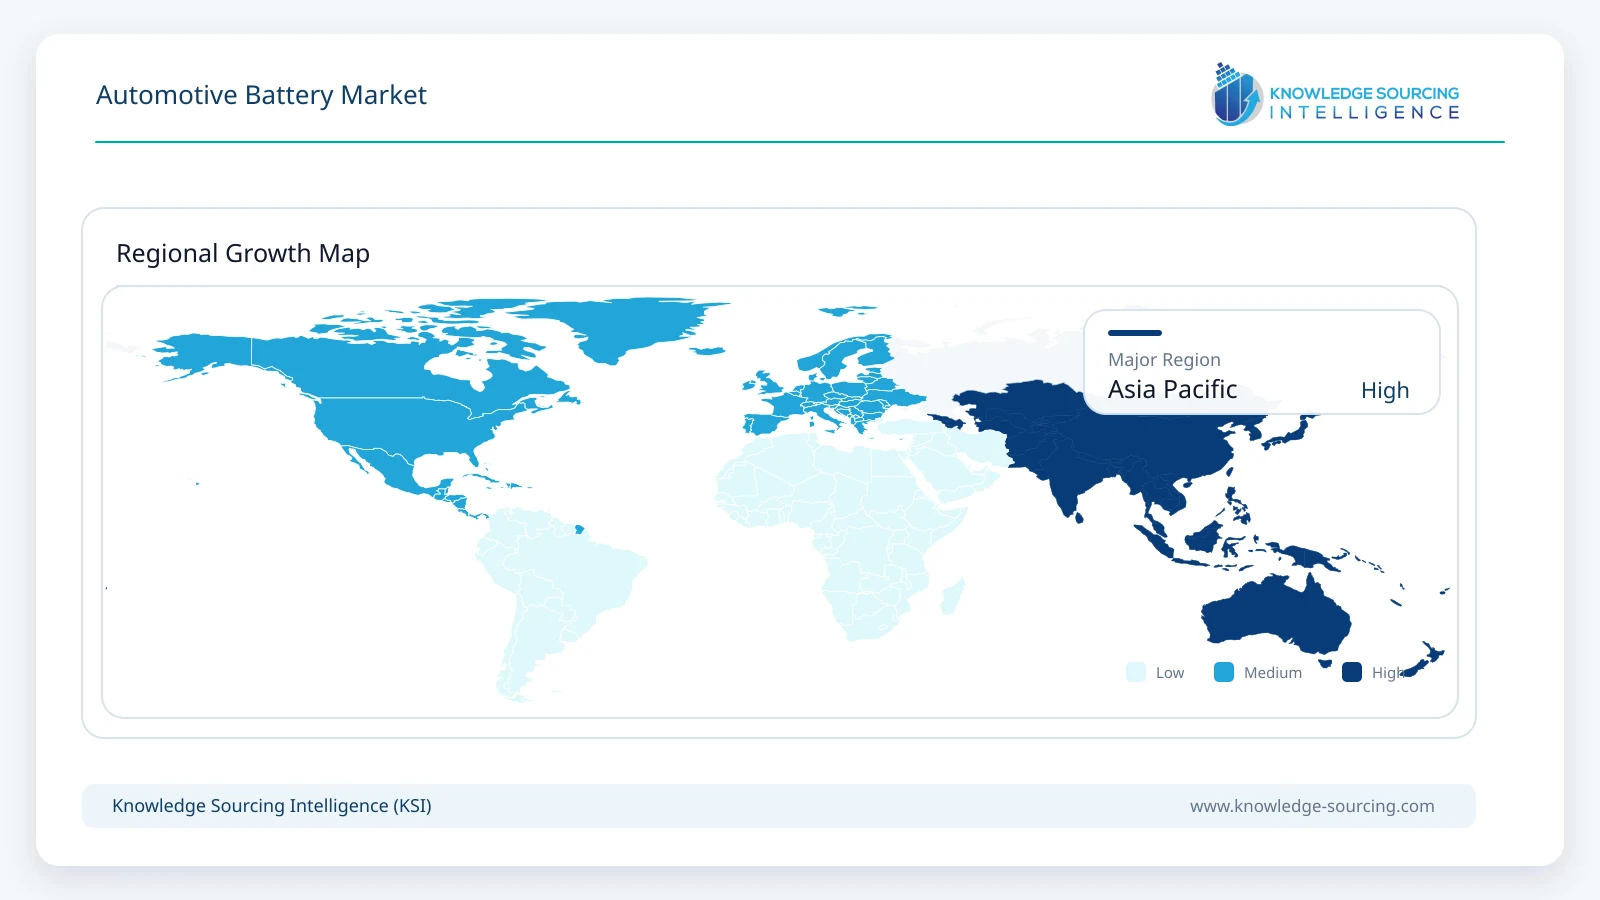
Asia Pacific is the largest regional market because China is the largest source of electric vehicle battery demand and the center of global cell manufacturing. The region is projected to grow at approximately 11.5% annually through 2031. China accounted for around 60% of global EV battery deployment in 2025, while Japan and South Korea remain major battery technology and manufacturing centers. India and Southeast Asia are becoming more important as electric two-wheelers, passenger vehicles and local battery manufacturing expand.
Competitive Environment
CATL and BYD are the largest Chinese battery competitors and benefit from strong domestic electric vehicle demand and vertically integrated supply chains. CATL supplies a wide range of global automakers and is expanding across LFP, high-nickel, sodium-ion and battery-swapping systems. BYD combines battery manufacturing with vehicle production and uses Blade Battery technology across its own models and external supply relationships.
LG Energy Solution, Panasonic Energy and Samsung SDI are major global suppliers to passenger vehicle manufacturers. LG Energy Solution operates a broad pouch and cylindrical portfolio and is expanding North American production. Panasonic Energy remains strong in cylindrical automotive cells and is increasing research and production capability. Samsung SDI focuses heavily on premium prismatic and cylindrical batteries while expanding LFP and next-generation chemistries.
SK On, CALB, Gotion High-Tech, EVE Energy, AESC and Sunwoda add substantial traction-battery capacity across China, Korea, Europe and North America. Clarios and GS Yuasa remain important in low-voltage automotive batteries, where distribution, replacement coverage and recycling networks are major competitive advantages. Exide Industries and Amara Raja Energy & Mobility hold strong positions in India and are expanding toward lithium-ion systems.
Recent Developments
September 2026: Panasonic Energy opened a new global battery R&D hub in Osaka for automotive and data-center applications.
September 2026: LG Energy Solution signed a ten-year agreement for U.S.-produced battery-grade lithium carbonate.
August 2026: LG Energy Solution started production at its Lansing, Michigan battery plant with more than 35 GWh of planned annual capacity.
August 2026: Samsung SDI and General Motors signed a new agreement to develop next-generation prismatic EV battery cells.
June 2026: Stellantis and Factorial began road testing a Dodge Charger Daytona development vehicle using solid-state battery cells.
April 2026: CATL introduced six battery and charging innovations, including new Shenxing, Qilin and sodium-ion products.
April 2026: Samsung SDI signed its first electric vehicle battery supply agreement with Mercedes-Benz.
February 2026: CATL and Changan unveiled a mass-production passenger vehicle using sodium-ion battery technology.
Automotive Battery Market Scope
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 230.7 billion |
| Total Market Size in 2031 | USD 388.2 billion |
| Forecast Unit | Billion |
| Growth Rate | 11% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Technology, Vehicle Type, Application, End User, Geography |
| Companies |
|
| Customization Scope | 15% Free Customization included with purchase — Request Custom Breakdown → |
| Sample & Data Access | PDF Sample, Excel Databook & Analyst Briefing — Download Free Sample → |
Market Segmentation
By Technology
Lead-Acid
Lithium-Ion
Nickel-Metal Hydride
Other Technologies
By Vehicle Type
Passenger Cars
Commercial Vehicles
Two-Wheelers
Three-Wheelers
By Application
Internal Combustion Engine Vehicles
Hybrid Electric Vehicles
Plug-In Hybrid Electric Vehicles
Battery Electric Vehicles
By End User
Original Equipment Manufacturer
Aftermarket
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Germany
France
United Kingdom
Italy
Spain
Others
Middle East and Africa
Saudi Arabia
UAE
South Africa
Others
Asia Pacific
China
Japan
India
South Korea
Australia
Indonesia
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Electric Vehicle Sales Are Creating a Much Larger High-Voltage Battery Demand Base
3.1.2. The Installed Vehicle Fleet Sustains Low-Voltage Replacement Demand
3.1.3. Regional Battery Manufacturing and Supply-Chain Localization Support New Investment
3.2. Market Restraint
3.2.1. Price Pressure, Overcapacity and Raw-Material Volatility Can Weaken Returns on New Battery Investment
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Lithium Iron Phosphate and High-Nickel Chemistries
4.2. Sodium-Ion Batteries
4.3. Solid-State Batteries
4.4. Fast Charging and High-Voltage Architectures
4.5. Battery Management Systems and Pack Integration
5. AUTOMOTIVE BATTERY MARKET BY TECHNOLOGY
5.1. Introduction
5.2. Lead-Acid
5.3. Lithium-Ion
5.4. Nickel-Metal Hydride
5.5. Other Technologies
6. AUTOMOTIVE BATTERY MARKET BY VEHICLE TYPE
6.1. Introduction
6.2. Passenger Cars
6.3. Commercial Vehicles
6.4. Two-Wheelers
6.5. Three-Wheelers
7. AUTOMOTIVE BATTERY MARKET BY APPLICATION
7.1. Introduction
7.2. Internal Combustion Engine Vehicles
7.3. Hybrid Electric Vehicles
7.4. Plug-In Hybrid Electric Vehicles
7.5. Battery Electric Vehicles
8. AUTOMOTIVE BATTERY MARKET BY END USER
8.1. Introduction
8.2. Original Equipment Manufacturer
8.3. Aftermarket
9. AUTOMOTIVE BATTERY MARKET BY GEOGRAPHY
9.1. Introduction
9.2. North America
9.2.1. United States
9.2.2. Canada
9.2.3. Mexico
9.3. South America
9.3.1. Brazil
9.3.2. Argentina
9.3.3. Others
9.4. Europe
9.4.1. Germany
9.4.2. France
9.4.3. United Kingdom
9.4.4. Italy
9.4.5. Spain
9.4.6. Others
9.5. Middle East and Africa
9.5.1. Saudi Arabia
9.5.2. UAE
9.5.3. South Africa
9.5.4. Others
9.6. Asia Pacific
9.6.1. China
9.6.2. Japan
9.6.3. India
9.6.4. South Korea
9.6.5. Australia
9.6.6. Indonesia
9.6.7. Others
10. COMPETITIVE ENVIRONMENT AND ANALYSIS
10.1. Major Players and Strategy Analysis
10.2. Market Share Analysis
10.3. Technology and Chemistry Positioning
10.4. Mergers, Acquisitions, Agreements and Collaborations
10.5. Competitive Dashboard
11. COMPANY PROFILES
11.1. Contemporary Amperex Technology Co., Limited (CATL)
11.2. BYD Company Limited
11.3. LG Energy Solution Ltd.
11.4. Panasonic Energy Co., Ltd.
11.5. Samsung SDI Co., Ltd.
11.6. SK On Co., Ltd.
11.7. CALB Group Co., Ltd.
11.8. Gotion High-tech Co., Ltd.
11.9. EVE Energy Co., Ltd.
11.10. AESC Group Ltd.
11.11. Sunwoda Electronic Co., Ltd.
11.12. Farasis Energy, Inc.
11.13. Clarios
11.14. GS Yuasa Corporation
11.15. Exide Industries Limited
11.16. Amara Raja Energy & Mobility Limited
11.17. East Penn Manufacturing Co.
11.18. Tianneng Battery Group Co., Ltd.
12. APPENDIX
12.1. Currency
12.2. Assumptions
12.3. Base and Forecast Years Timeline
12.4. Key Benefits for Stakeholders
12.5. Research Methodology
12.6. Abbreviations





Frequently asked questions
What is the projected growth for the Automotive Battery Market?
Market grows 11% CAGR, reaching $388.2 billion by 2031.
Which battery technology holds the largest market share?
Lithium-ion batteries account for 85% of global market value in 2026.
What vehicle segment drives automotive battery demand?
Passenger cars generate approximately $180 billion in 2026 demand.
What emerging battery technologies are developing for automotive use?
Sodium-ion and solid-state are moving into early automotive deployment.
Who accounts for the majority of Automotive Battery Market value?
Original equipment manufacturers account for 84% of global market value.
Cite this report
Knowledge Sourcing Intelligence. (Nov 2026). Automotive Battery Market - Strategic Insights and Forecasts (2026-2031). https://www.knowledge-sourcing.com/report/automotive-battery-market