
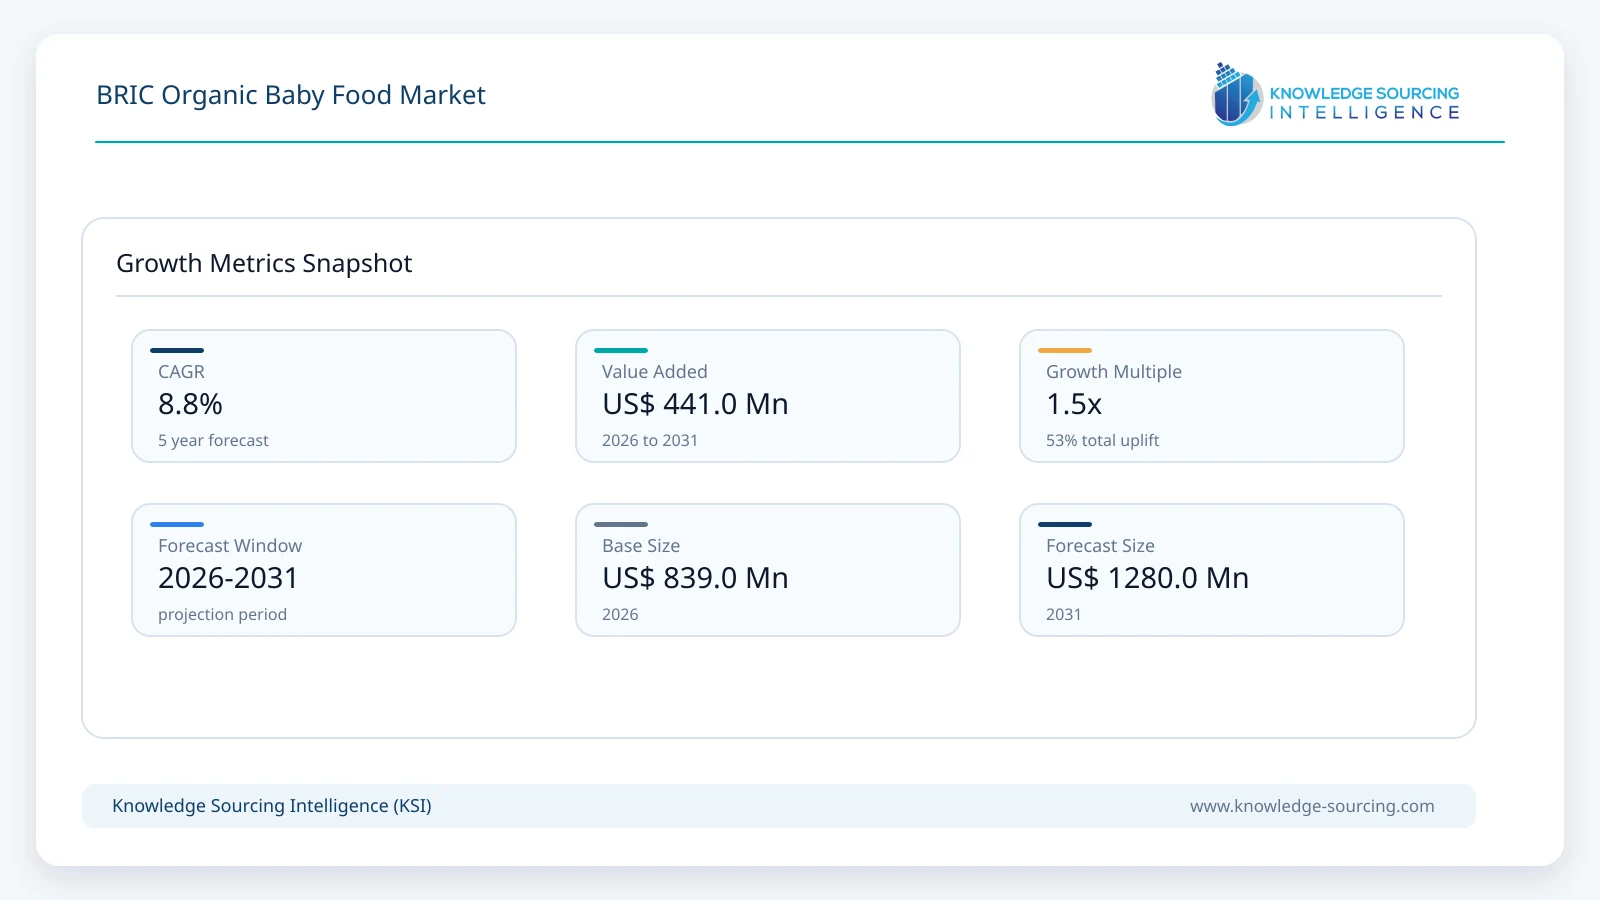
The BRIC Organic Baby Food Market is projected to grow at a CAGR of 8.8%, increasing from USD 839 million in 2026 to USD 1,280 million by 2031.
Highlights:
- 1Milk Formula accounts for around 42% of market value in 2026, supported by high unit values and premium positioning.
- 2Ready-to-Eat Purees and Pouches are projected to grow at approximately 11% annually through 2031, making them one of the fastest-growing product categories.
- 3Supermarkets remain the largest distribution channel, while Online sales record substantially faster growth as specialized products become easier to discover and purchase.
- 4China remains the largest BRIC country market in 2026, while India is projected to record the strongest growth through 2031.
- 5India’s certified organic farm production exceeded 4.39 million metric tons in 2024-25, improving the domestic supply base for organic cereals, fruits and processed ingredients.
- 6China’s infant-food market is moving toward tighter quality control and production oversight, with SAMR launching a nationwide infant complementary-food safety improvement programme in 2026.
- 7Demographic pressure remains materialChina recorded 7.92 million births in 2025, making premiumization and expenditure per child increasingly important to market growth.
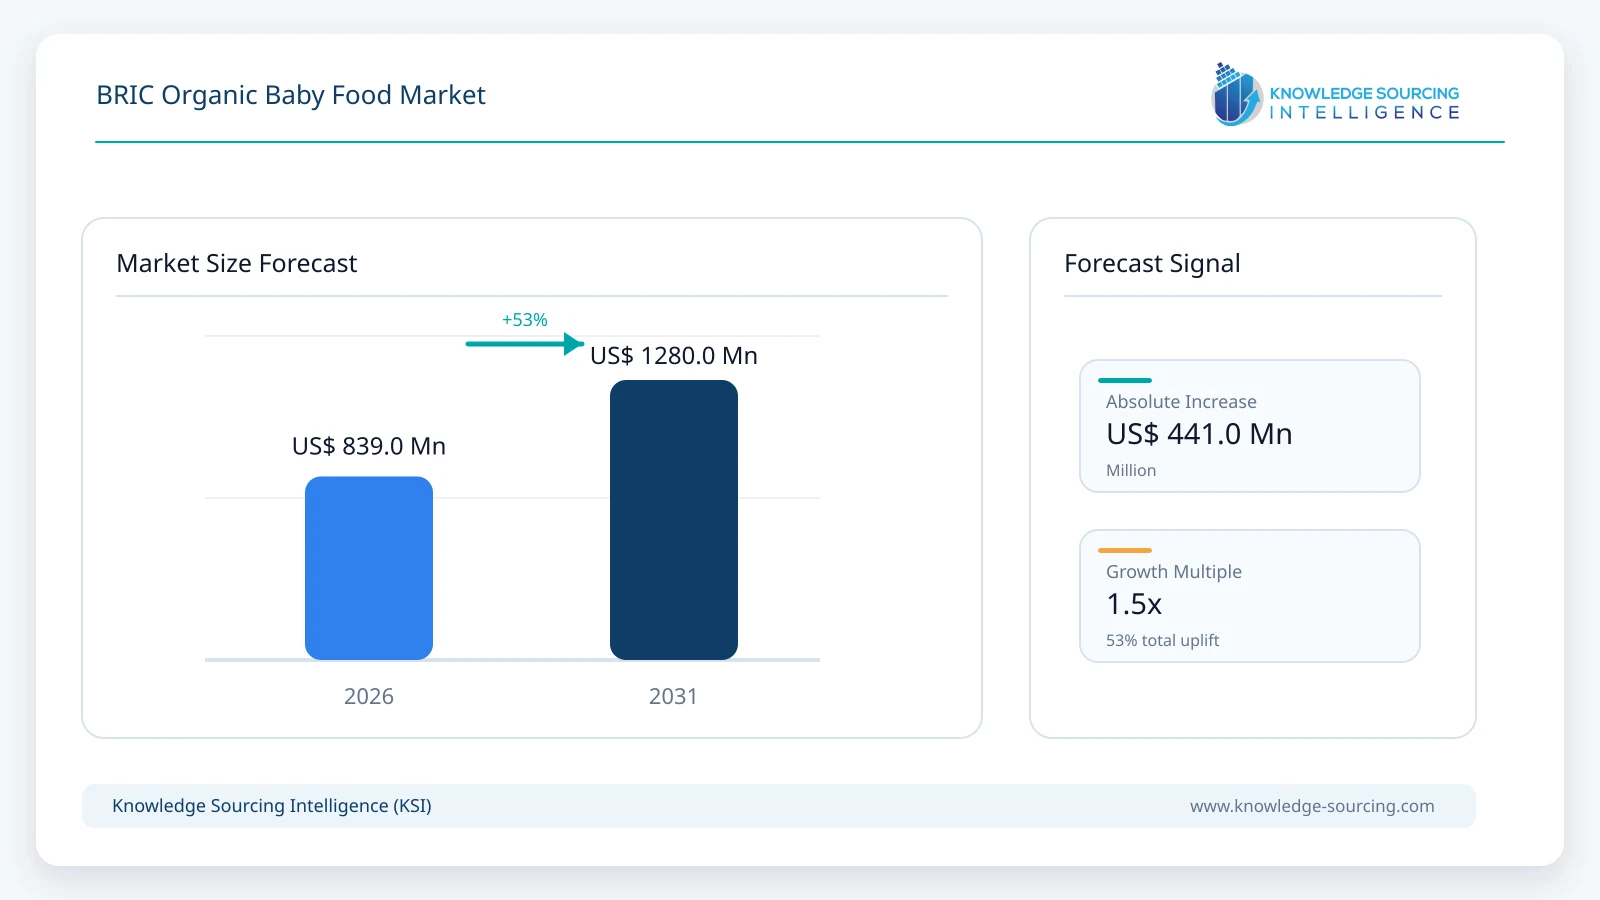
Organic baby food remains a premium subset of the wider infant nutrition market, covering products made from certified organic ingredients and sold as infant formula, prepared meals, purees, cereals, dried foods, and other complementary nutrition products. Demand is supported by growing parental focus on ingredient provenance, expanding certified-organic food supply, stronger premium retail and e-commerce distribution, and greater availability of products positioned around simple ingredient lists, no added sugar, and traceable sourcing across Brazil, Russia, India, and China.
The addressable market remains large despite slowing birth rates in several BRIC economies. China recorded 7.92 million births in 2025, while India continues to have a substantially higher birth rate, with the official Sample Registration System estimating 18.4 births per thousand population in 2023. Brazil registered approximately 2.38 million live births in 2024, and Russia recorded 104,954 births in January 2025 alone. The demographic picture is therefore mixed: China, Brazil and Russia face structural birth-rate pressure, while India continues to provide a much larger new-child cohort. Market growth consequently depends increasingly on expenditure per child, premium product penetration and wider access to certified products rather than simply on growth in the number of infants.
Milk Formula remains the largest product category and accounts for approximately 42% of market value in 2026. Organic formula carries high value per unit and benefits from the willingness of affluent parents to pay for certified milk sourcing, ingredient traceability and specialized formulations where formula feeding is required. China is particularly important because premium infant formula is highly developed and brands such as Bellamy’s Organic, Feihe, Yili and Junlebao offer organic or premium-certified formula products. Bellamy’s Chinese portfolio includes certified organic infant formula, organic cereals, purees and complementary foods, while Junlebao markets an organic infant formula line built around certified supply-chain sourcing.
India provides the strongest incremental growth opportunity within BRIC. The country combines a large infant population with rapid expansion of organized retail, e-commerce and domestic organic-food supply. APEDA reports that India had more than 2.25 million hectares of certified organic cultivated land in 2024-25 and approximately 4.39 million metric tons of certified organic farm production, providing a growing domestic ingredient base for cereals, millets, fruits and processed foods. Companies such as Happa already sell organic fruit and vegetable purees, cereals and complementary feeding products for infants from six months onward. This supports a market in which locally sourced cereals, millets, fruit and vegetable formulations can expand alongside imported and multinational infant-nutrition brands.
Market Growth Drivers and Trends
Parental Preference for Certified and Traceable Ingredients Is Increasing
Parents purchasing baby food generally apply higher safety and quality expectations than they do to conventional adult packaged foods because infants have narrower nutritional tolerances and greater vulnerability to contaminants. Organic certification provides one way of communicating agricultural and sourcing standards by restricting specified synthetic pesticides, fertilizers and genetically modified inputs according to the applicable national or international certification system. Premium baby food companies increasingly combine this certification with no-added-sugar formulations, short ingredient lists and detailed sourcing information, turning organic status into part of a wider trust proposition rather than presenting it as a guarantee of inherently superior nutrition.
HiPP has built much of its baby-food positioning around certified organic agriculture and controls extending from soil and crop selection to finished-product testing. Bellamy’s Organic similarly offers certified organic formula and complementary foods in China, while Happa sells organic purees and cereal-based foods in India using formulations that emphasize fruit, vegetables, grains and limited additives. FrutoNyanya also maintains experience with certified organic purees in Russia. These portfolios demonstrate that organic baby food is developing across milk, cereals and prepared complementary foods rather than remaining confined to one niche product form.
This trend increases value per child because certified products typically occupy premium price bands and often compete on formulation, packaging and supply-chain transparency in addition to basic nutrition. The strongest impact is therefore in higher-income urban households and online channels where parents can compare ingredients and certification claims more easily.
India’s Infant Base and Organic Supply Chain Are Expanding the Addressable Market
India provides a different growth profile from China, Russia and Brazil because its infant population remains large and its birth rate remains materially higher. The official Sample Registration System reported a national crude birth rate of 18.4 per thousand in 2023, including 20.3 in rural areas and 14.9 in urban areas. Even as fertility declines over the longer term, the absolute number of infants entering the complementary-feeding age group remains substantial.
The domestic ingredient environment is becoming more supportive at the same time. Certified organic cultivated area under India’s National Programme for Organic Production reached 2.25 million hectares in 2024-25, while certified farm production reached 4.39 million metric tons. Cereals and millets are particularly relevant to baby foods because ragi, rice, oats and millet-based formulations already form an important part of Indian complementary feeding. Processed organic foods also represented approximately USD 154 million of India’s organic exports during 2024-25, demonstrating increasing manufacturing capability around certified ingredients.
The resulting opportunity is not simply imported organic formula. Domestic companies can build products around local grains, fruit and vegetable ingredients while international companies compete in premium formula and packaged complementary nutrition. India is therefore projected to record a low-double-digit CAGR through 2031, materially above the BRIC average.
Premiumization Is Offsetting Birth-Rate Pressure in China
China remains the largest BRIC organic baby food market despite a declining birth cohort. The country’s 7.92 million births in 2025 were below previous years, but household expenditure on infant products has increasingly concentrated on premium nutrition, specialized formula, traceable dairy supply and products positioned around digestive health, immunity and advanced nutrient combinations.
Organic infant formula is well established within this premium segment. Bellamy’s Organic offers China-compliant certified organic formula, organic A2 products, cereals, fruit purees and other complementary foods. Feihe currently lists dedicated organic infant formula ranges, while Junlebao markets its Youcui organic infant formula as a fully organic supply-chain product. Yili’s infant-nutrition portfolio also includes formula using organic A2 milk and advanced nutritional ingredients.
The commercial effect is that declining births reduce the available customer base but increase competitive focus on share of wallet per child. Organic products benefit where parents treat certified ingredient sourcing as part of a broader premium nutrition purchase, although category growth remains slower than in India because demographic pressure becomes increasingly difficult to offset entirely through higher prices.
E-Commerce Is Expanding Access to Specialized Organic Products
Organic baby food assortments are generally narrower than conventional baby-food ranges in physical stores, particularly outside the largest metropolitan areas. E-commerce reduces this limitation by allowing parents to search by product age, ingredient, certification, dietary characteristic and brand without depending on the shelf space available in a local supermarket or pharmacy.
This is particularly important in India and China, where digital commerce can connect specialized brands with consumers beyond premium urban supermarkets. Happa sells organic purees, cereals and snacks directly through its online channel, while Chinese organic formula and complementary-food brands maintain strong direct and marketplace availability. Online retail also supports recurring purchases of formula and cereals because parents can reorder known products without visiting specialized outlets.
Online sales account for roughly one-fifth of BRIC organic baby food value in 2026 but are projected to grow at around 15% annually through 2031, substantially faster than offline retail. Supermarkets and pharmacies remain important because many parents continue to value physical product inspection and professional recommendation, but digital channels are increasingly important for assortment depth and premium brand discovery.
Regulation Is Encouraging Greater Investment in Quality Assurance
Infant nutrition is one of the most tightly regulated parts of the food industry, and regulatory requirements are becoming more detailed across the BRIC markets. China launched a nationwide infant complementary-food safety improvement programme in May 2026 covering cereal-based complementary foods, canned foods and nutritional supplements for children aged six to 36 months. The programme strengthens licensing, inspections, digital supervision and enforcement, while a revised production licensing framework was issued for consultation in July.
China also introduced detailed licensing requirements for liquid infant formula in January 2026 following product-registration requirements introduced at the end of 2025. India regulates infant formula, cereal-based complementary foods and traditional packaged infant foods through dedicated FSSAI infant-nutrition standards, while Brazil requires market authorization for infant formulas and applies strict marketing controls under NBCAL.
These rules increase compliance costs, but they also raise barriers against poorly controlled products and support established manufacturers capable of providing traceability, laboratory testing and verified certification. Within organic baby food, regulatory oversight makes certification and quality-management systems central parts of the value proposition.
Market Restraints
Organic Certification and Premium Ingredients Increase Retail Prices
Organic products require certified agricultural inputs, controlled supply chains and segregation from conventional ingredients. These costs are amplified in baby food because manufacturers also need strict microbiological, contaminant and nutritional controls. Organic infant formula can require certified milk production and imported specialty ingredients, while small-volume purees or cereals can face higher unit packaging and testing expenses.
The resulting retail premium limits penetration among price-sensitive consumers. This is especially important in India, Brazil and Russia, where a large proportion of households continue to rely on home-prepared complementary foods or conventional packaged products. Organic baby food therefore remains a premium market rather than becoming the default feeding category during the forecast period.
Declining Birth Cohorts Reduce Volume Growth in Several BRIC Markets
Demographics create a structural restraint in China, Brazil and Russia. China recorded 7.92 million births in 2025 and continued to experience population decline. Brazil registered approximately 2.38 million births in 2024, while Russia’s birth trajectory remains under long-term pressure despite month-to-month fluctuations.
A smaller birth cohort means manufacturers need to gain greater expenditure per child or increase the organic share of total baby food merely to maintain high category growth. Premiumization can compensate partly, but it cannot indefinitely offset large demographic declines. India therefore becomes increasingly important to the overall BRIC growth profile.
Breastfeeding Policy Restricts Promotion of Formula-Based Products
Public-health policy appropriately prioritizes breastfeeding, which limits commercial promotion of infant formula in several BRIC countries. Brazil’s NBCAL framework regulates promotion and labelling of products intended for infants and young children and prohibits commercial promotion of infant formula for children under 12 months. India’s infant nutrition rules similarly operate alongside restrictions designed to protect breastfeeding and govern how infant milk substitutes and foods can be marketed.
These restrictions do not eliminate legitimate demand for infant formula, but they reduce the promotional tools available to manufacturers. Organic formula producers consequently rely more heavily on healthcare channels, brand reputation, compliant product information and later-stage toddler nutrition than conventional FMCG-style advertising.
Certification and Raw-Material Availability Can Limit Product Scaling
A product marketed as organic requires certified raw materials rather than simply ingredients perceived as natural. This creates a narrower supplier pool for milk, fruit, cereals, vegetables and specialty ingredients and can expose manufacturers to crop variability, certification delays and higher procurement costs.
India has substantially expanded certified production, but individual categories can still have limited year-round availability. Brazil similarly requires organic products to be certified through approved conformity-assessment systems before they can be marketed as organic.
Supply constraints become more significant as manufacturers attempt to scale national distribution because ingredient specifications need to remain consistent across production batches. The requirement particularly affects smaller companies that do not have long-term contracts or vertically integrated agricultural supply.
Home-Prepared Foods Remain a Strong Substitute
Packaged organic baby food competes not only with conventional branded baby food but also with food prepared at home. Rice, cereals, fruit, vegetables, pulses and dairy products can be prepared for infants at comparatively low cost, and home feeding remains culturally established across all four BRIC markets.
This is particularly important after six months, when complementary feeding becomes more diverse. Packaged foods gain advantages in portability, consistency, convenience and shelf life, but they need to demonstrate sufficient value to justify higher prices. The strongest commercial opportunities therefore occur among working households, travellers, urban consumers and parents seeking specific certified ingredients or convenient portion-controlled formats.
BRIC Organic Baby Food Market Segmentation Analysis
By Product Type
Organic Milk Formula accounts for approximately 42% of BRIC market value in 2026 and remains the largest product category. Formula has a substantially higher average selling value than purees or cereals, while certified organic dairy sourcing provides a clear premium differentiation. China provides the largest addressable market for organic formula, with Bellamy’s Organic, Feihe, Junlebao and Yili all participating in premium or organic infant nutrition. The segment continues growing in absolute terms through 2031 but gradually loses share as prepared foods and convenient complementary products expand faster.
Ready-to-Eat Purees & Pouches are projected to grow at approximately 11% annually through 2031. The segment benefits from convenience, portion control and the ability to combine fruits, vegetables and grains in portable formats. Happa’s Indian portfolio includes certified organic fruit, vegetable and grain purees for infants from six months, while Bellamy’s Organic sells fruit purees and complementary foods in China.
Prepared Baby Meals represent an estimated USD 190 million market in 2026. The category includes prepared jarred or packaged meals intended for later-stage complementary feeding and benefits particularly from urban households seeking time-saving products. Growth remains above the overall baby-food market but below the fastest-growing pouch formats.
Dried Baby Food remains an important category across India, China and Russia because cereals and powdered complementary foods have long shelf lives, comparatively low logistics costs and strong compatibility with local feeding practices. Organic rice, millet, oat and mixed-grain cereals are particularly relevant in India and China, while FrutoNyanya maintains a broad cereal portfolio in Russia. Other products include organic snacks, dissolvable foods, toddler foods and specialized complementary nutrition.
By Distribution Channel
Supermarkets account for approximately 36% of market value in 2026 and remain the largest distribution channel. Their position reflects broad brand availability, trusted packaged-food environments and the ability of parents to compare products physically. The channel is particularly important for prepared meals, cereals and established premium brands in China, Brazil and Russia.
Online sales are projected to record a CAGR of approximately 15% through 2031, significantly above the total market. Digital retail provides access to wider product ranges and allows smaller organic specialists to compete without obtaining national supermarket shelf space. Direct-to-consumer brands in India are particularly well suited to this model, while China’s mature e-commerce ecosystem supports online purchase of premium formula and complementary foods.
Chemists, Pharmacies and Drug Stores represent an estimated USD 150 million market in 2026. The channel remains important for infant formula and specialized nutrition because parents frequently associate pharmacies with healthcare advice and product authenticity. Specialty Outlets maintain a smaller but attractive position in metropolitan areas where premium, imported and organic foods are concentrated.
Other channels include baby stores, convenience retail and direct institutional or healthcare-linked distribution. Their combined share remains limited but varies significantly by country.
Geographical Outlook
China accounts for approximately 42% of the BRIC Organic Baby Food Market in 2026 and remains the largest country through 2031. The country’s premium infant-nutrition ecosystem, developed formula market and wide availability of certified organic products support high expenditure per child despite falling births. Domestic companies increasingly compete alongside imported brands, with Feihe, Junlebao and Yili operating organic or premium formula portfolios while Bellamy’s Organic provides one of the most visible dedicated organic offerings.
India is projected to grow at approximately 12.5% annually through 2031, making it the fastest-growing BRIC market. The country combines a large child population, increasing digital retail access and expanding certified organic agricultural production. Local companies can also differentiate through culturally familiar ingredients such as ragi, millets, rice and fruit-based complementary foods rather than competing only in conventional milk formula.
Brazil represents an estimated USD 125–130 million market in 2026. Demand is supported by urban middle-income consumers, established pharmacy and supermarket channels and a regulated organic certification system. The country also remains strategically important to multinational infant-nutrition manufacturers. In September 2026, Nestlé announced CHF 310 million of nutrition and health investment in Brazil through 2028, including a new infant-formula facility in Minas Gerais intended to serve domestic and potential export demand.
Russia remains the smallest of the four markets in value and grows more slowly because of demographic pressure and a less developed premium organic category. Domestic baby-food manufacturing remains substantial, however, with PROGRESS describing FrutoNyanya as a leading Russian baby-food brand with more than 200 products. Organic purees have previously formed part of the portfolio, while 2026 launches continue to emphasize natural ingredients and no added sugar.
Recent Developments
September 2026, Nestlé announced approximately CHF 310 million of investment in nutrition and health in Brazil through 2028, including a new infant-formula facility at Ituiutaba in Minas Gerais. The facility is intended to increase Brazilian supply and provide potential export capacity.
July 2026, China’s State Administration for Market Regulation issued a revised draft production-licensing framework for infant complementary foods for public consultation. The proposal followed the nationwide “Guarding Growth” infant complementary-food safety programme introduced in May and focuses on licensing, raw-material control, production, digital supervision and enforcement.
June 2026, PROGRESS reported that multiple FrutoNyanya baby-food products had received vegan certification under Russia’s GOST R 71528-2024 standard. The certification covered fruit and vegetable purees, porridges, desserts and other products and reflects wider demand for transparent ingredient and dietary claims in the baby-food category.
June 2026, FrutoNyanya launched a no-added-sugar water-and-juice line for infants from four to five months onward, continuing the Russian market’s shift toward products positioned around simpler formulations and reduced added sugar.
During 2026, China strengthened infant-formula supervision following a precautionary recall involving selected Nestlé products. SAMR required infant-formula manufacturers to strengthen testing, raw-material inspection and finished-product quality controls, reinforcing the importance of traceability and quality systems within premium infant nutrition.
Competitive Environment
The BRIC organic baby food market combines multinational infant-nutrition companies, specialist organic manufacturers and large domestic producers. Nestlé, Danone, Abbott and Reckitt remain important across infant formula and complementary nutrition, while HiPP, Holle and Bellamy’s Organic have stronger direct associations with certified organic baby food. These companies compete through product safety, ingredient quality, certification, pediatric nutrition expertise and established healthcare or retail distribution rather than through price alone.
China contains the deepest domestic competitive base. Feihe, Yili, Junlebao, Beingmate and Ausnutria compete across premium infant formula, while Bellamy’s Organic and Biostime strengthen the premium and organic segment. Junlebao’s organic infant formula and Feihe’s dedicated organic products demonstrate that certified organic positioning is no longer confined to imported brands.
India has a more fragmented emerging organic complementary-food market. Happa competes in purees, cereals and snacks, while specialized local brands are increasingly using millets, fruit and traditional ingredients to differentiate themselves from formula-led multinational portfolios. India’s growing certified organic supply base provides additional scope for domestic sourcing.
Russia maintains substantial domestic baby-food capacity through PROGRESS/FrutoNyanya, while Brazil remains more strongly influenced by multinational infant nutrition companies and established local food producers. Competitive advantage through 2031 is likely to depend on the ability to combine certified sourcing with regulatory compliance, trusted quality systems, age-specific formulation, digital distribution and product formats that fit local feeding practices.
Analyst View
The BRIC Organic Baby Food Market is projected to increase, but growth will not be evenly distributed across the four countries. China remains the largest market because premium infant-nutrition expenditure and organic product availability are well developed, yet declining births limit the pace of volume expansion. India provides the strongest growth opportunity because of its much larger infant cohort, expanding organic ingredient base and increasing ability of digital channels to connect specialized brands with urban households.
The product mix is also becoming broader. Organic formula remains the largest value category, but the strongest incremental growth increasingly comes from purees, pouches, prepared foods and cereal-based complementary nutrition. This favours companies capable of combining certified sourcing with convenient formats rather than relying solely on premium dairy formula.
Organic baby food should therefore remain a premium category rather than becoming the dominant form of infant nutrition in BRIC by 2031. High prices, breastfeeding policy, home-prepared foods and demographic pressure limit mass-market penetration. Nevertheless, the combination of parental quality concerns, stronger certification systems and wider retail access creates a structurally faster-growing segment than conventional baby food. Companies that can demonstrate genuine certification, strong contaminant control and locally relevant formulations are likely to capture the greatest share of this growth.
BRIC Organic Baby Food Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 839 million |
| Total Market Size in 2031 | USD 1,280 million |
| Forecast Unit | Million |
| Growth Rate | 8.8% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Distribution Channel, Geography |
| Companies |
|
Market Segmentation
By Product Type
Ready-to-Eat Purees & Pouches
Prepared Baby Meals
Milk Formula
Dried Baby Food
Others
By Distribution Channel
Chemists/Pharmacies/Drug Stores
Online
Specialty Outlets
Supermarkets
Others
By Geography
Brazil
Russia
India
China
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
1.8. Key Benefits for Stakeholders
2. RESEARCH METHODOLOGY
2.1. Research Data
2.2. Sources
2.3. Research Design
3. EXECUTIVE SUMMARY
3.1. Research Highlights
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Market Opportunities
4.4. Porter’s Five Forces Analysis
4.4.1. Bargaining Power of Suppliers
4.4.2. Bargaining Power of Buyers
4.4.3. Threat of New Entrants
4.4.4. Threat of Substitutes
4.4.5. Competitive Rivalry in the Industry
4.5. Industry Value Chain Analysis
4.6. Analyst View
5. BRIC ORGANIC BABY FOOD MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Ready-to-Eat Purees & Pouches
5.3. Prepared Baby Meals
5.4. Milk Formula
5.5. Dried Baby Food
5.6. Others
6. BRIC ORGANIC BABY FOOD MARKET BY DISTRIBUTION CHANNEL
6.1. Introduction
6.2. Chemists/Pharmacies/Drug Stores
6.3. Online
6.4. Specialty Outlets
6.5. Supermarkets
6.6. Others
7. BRIC ORGANIC BABY FOOD MARKET BY GEOGRAPHY
7.1. Introduction
7.2. Brazil
7.3. Russia
7.4. India
7.5. China
8. COMPETITIVE ENVIRONMENT AND ANALYSIS
8.1. Major Players and Strategy Analysis
8.2. Market Share Analysis
8.3. Mergers, Acquisitions, Agreements and Collaborations
8.4. Competitive Dashboard
9. COMPANY PROFILES
9.1. Nestlé S.A.
9.2. Danone S.A.
9.3. Abbott Laboratories
9.4. Mead Johnson Nutrition
9.5. HiPP GmbH & Co. Vertrieb KG
9.6. Hero Group
9.7. Holle baby food AG
9.8. China Mengniu Dairy Company Limited
9.9. H&H Group
9.10. China Feihe Limited
9.11. Inner Mongolia Yili Industrial Group Co., Ltd.
9.12. Junlebao Dairy Group
9.13. Beingmate Co., Ltd.
9.14. Ausnutria Dairy Corporation Ltd.
9.15. Royal FrieslandCampina N.V.
9.16. Arla Foods amba
9.17. JSC PROGRESS
9.18. Nutrimental S.A.
9.19. Nascens Global Private Limited
9.20. Wholsum Foods
10. APPENDIX
10.1. Currency
10.2. Assumptions
10.3. Base and Forecast Years Timeline
10.4. Key Benefits for Stakeholders
10.5. Research Methodology
10.6. Abbreviations
Navigate
Trusted by the world's leading organizations











