
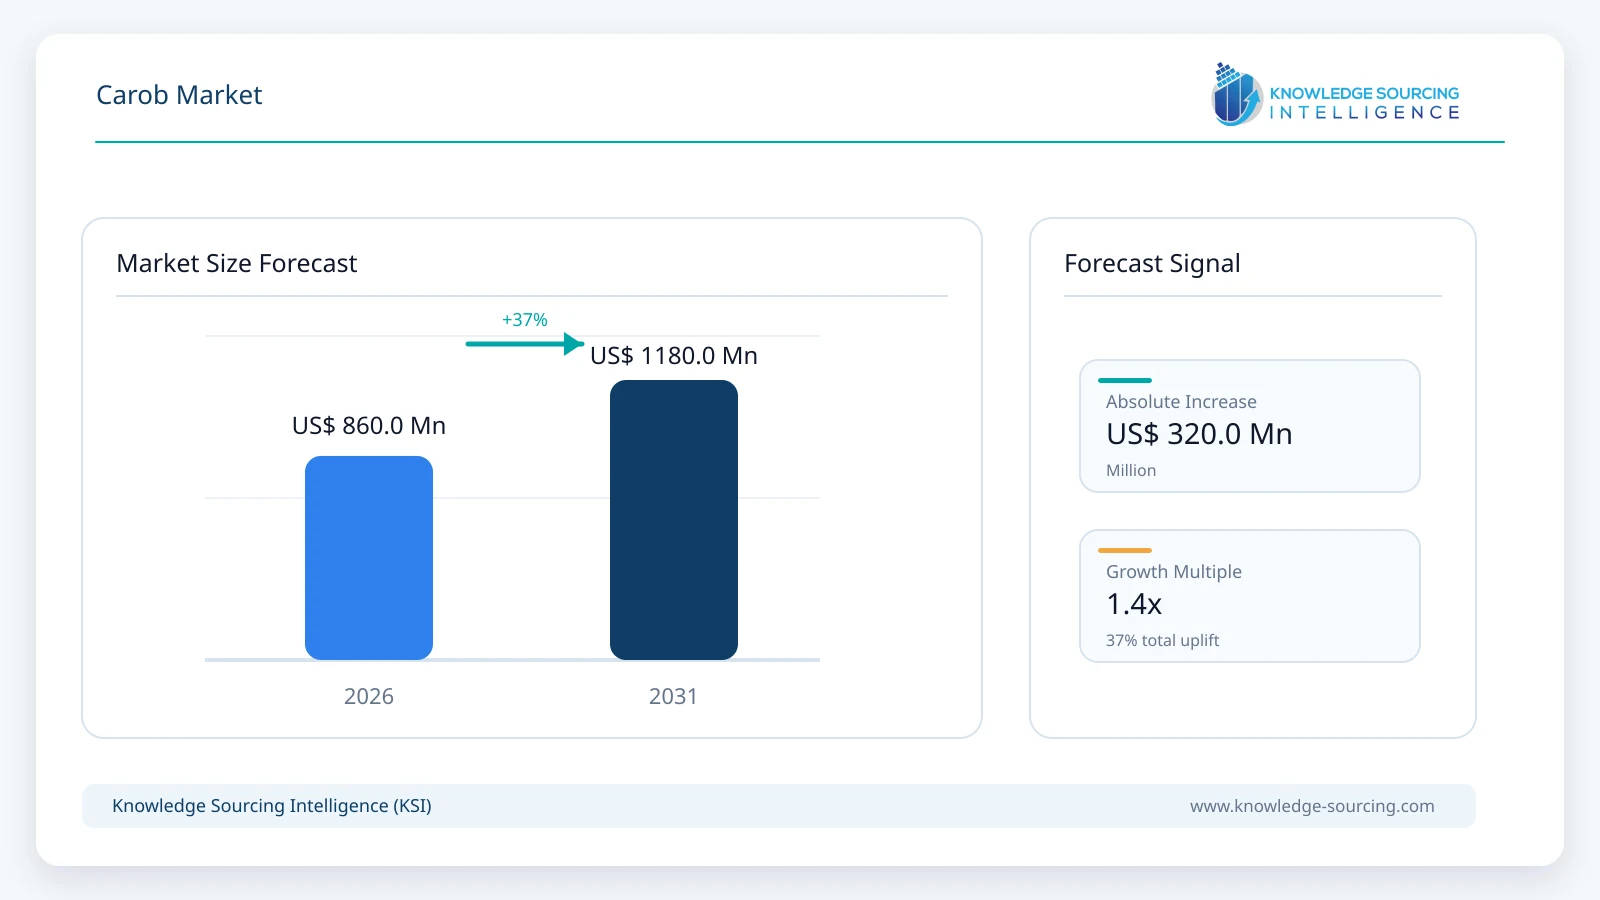
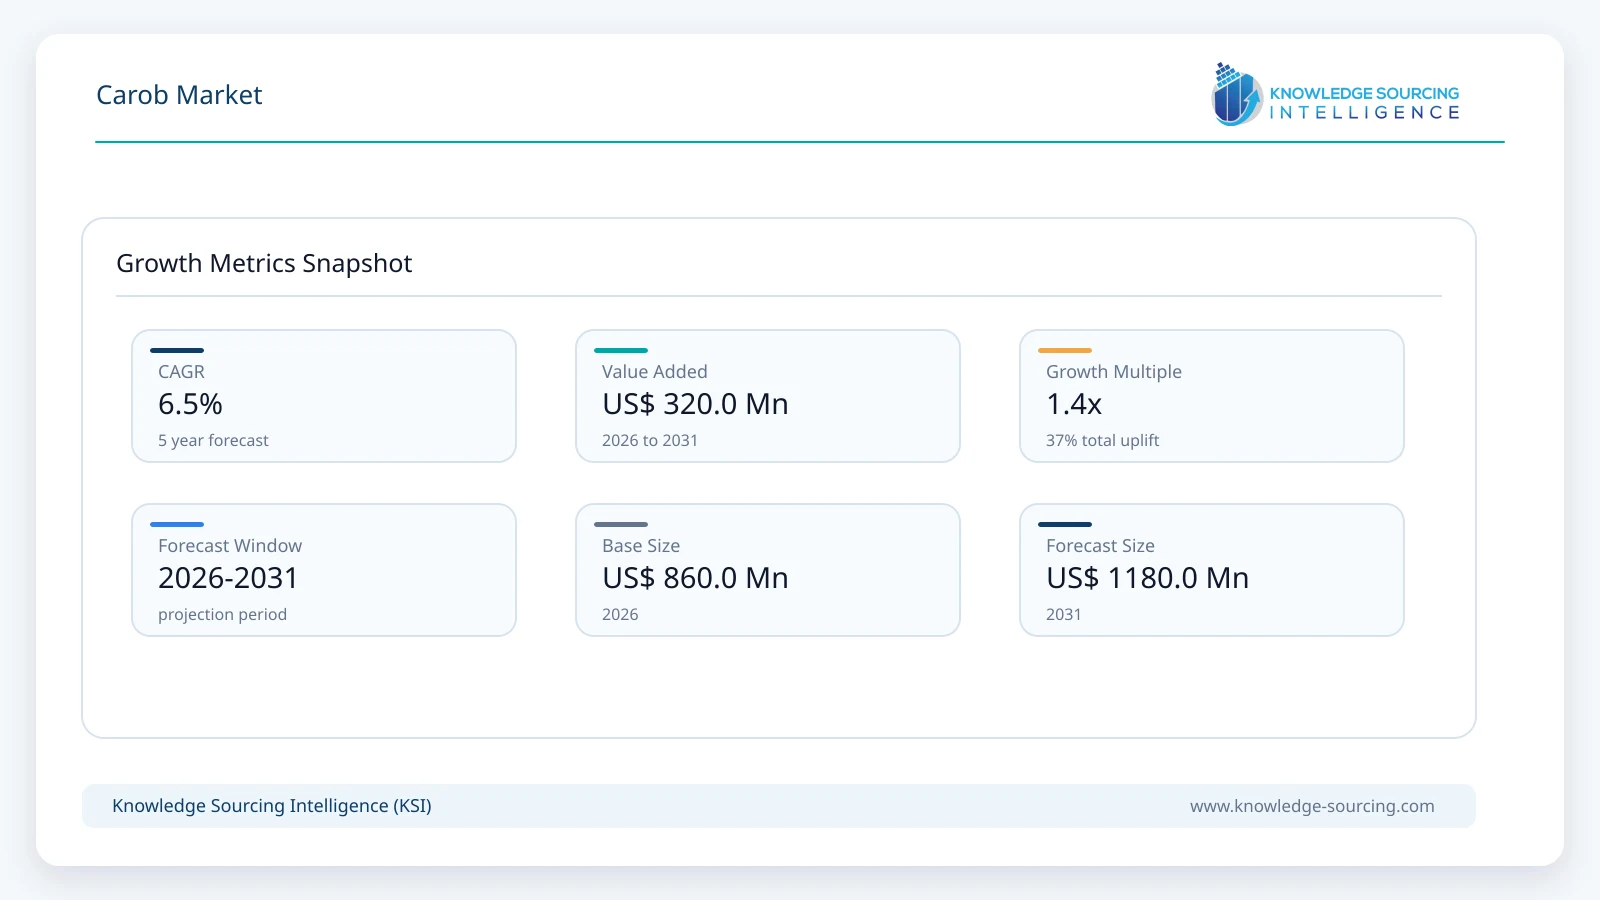
The global carob market is forecast to grow from USD 860 million in 2026 to USD 1,180 million by 2031, representing a CAGR of approximately 6.5% during the forecast period.
Highlights:
- 1Locust bean gum accounts for approximately 36% of global carob market value in 2026, reflecting its higher unit value and broad use as a natural texturizer and stabilizer.
- 2Food and beverages account for approximately 71% of global demand in 2026, led by dairy, frozen desserts, bakery, confectionery, plant-based foods and sauces.
- 3Conventional carob accounts for approximately 79% of market value in 2026, while organic grades gain share in premium powder, syrup and functional-ingredient applications.
- 4Europe accounts for approximately 45% of global market value in 2026, supported by its proximity to Mediterranean supply and established food-ingredient processing base.
- 5Spain accounts for approximately 15% of global market value in 2026, combining domestic cultivation with a strong locust bean gum and food-ingredient manufacturing industry.
The revenue from carobs is generated across two principal product streams. Locust bean gum, derived from carob seeds, accounts for the higher-value segment because of its role in food stabilization, texture modification and specialized ingredient systems, where performance consistency and processing quality are critical. The pulp-derived segment includes powder, flour, syrup and fiber ingredients, with manufacturers extending their use beyond conventional cocoa substitution into natural sweetening, functional nutrition and high-fiber formulations. This broader utilization of the fruit is improving raw-material economics and allowing processors to capture value from a larger proportion of each harvested pod.
Raw-material supply remains centered in the Mediterranean, with Morocco and Spain representing two of the most important commercial bases. Morocco has expanded its role in carob sourcing and primary processing, while Spain retains a well-established position in locust bean gum and other higher-value carob ingredients. Portugal, Cyprus, Greece and Turkey provide additional regional supply, while Australia serves a smaller premium and organic segment. Demand is more widely distributed than production, with Europe continuing to account for the largest share of consumption and processing activity, while North America is gaining importance in functional food, nutrition and specialty ingredient applications.
Market Trends
Locust Bean Gum Supply Moves Closer to Origin
Ingredient companies are increasing direct control over sourcing and primary processing. Nexira's 2026 acquisition of Morocco-based Keragum brought carob sourcing, seed selection and locust bean gum production closer to one of the industry's most important raw-material bases. The move follows a wider shift toward traceable supply chains because gum quality depends heavily on seed selection, processing and storage before final milling and refinement. Integrated sourcing also reduces exposure to spot-market volatility and gives suppliers greater control over organic certification, food-safety standards and consistency across crop years.
Carob Pulp Moves Into Functional Nutrition
Carob pulp is gaining commercial value beyond conventional powder and syrup. CarobWay is developing carob-derived prebiotic fiber and low-glycemic sweetening ingredients for metabolic health, satiety and gut-health applications, while Nexira is positioning carob fibers alongside its broader natural-ingredient portfolio. These products use more of the fruit and create higher-value outlets for pulp that has historically been directed toward lower-value food or feed uses. Functional nutrition also gives suppliers access to dietary-supplement and specialized food customers where formulation value is higher than in commodity powder.
Cocoa Replacement Gains Formulation Interest
Volatility in cocoa supply and pricing is encouraging food manufacturers to evaluate carob as a partial cocoa replacement in bakery, confectionery, beverages and snack formulations. IFF markets GRINDSTED Carob for cocoa-replacement applications, while powder producers continue to emphasize carob's naturally sweet profile and absence of caffeine and theobromine. Carob does not reproduce cocoa flavor in every formulation, so the strongest opportunity is in blended products where manufacturers can reduce cocoa usage, adjust sweetness and retain a brown color profile without positioning carob as a complete one-for-one substitute.
Hydrocolloid Suppliers Broaden LBG Portfolios
Locust bean gum is being positioned within broader texturizer systems rather than as an isolated gum. Tate & Lyle, IFF, Cargill, CEAMSA, Nexira and Ingredion market LBG alongside carrageenan, guar, xanthan, pectin and other hydrocolloids, allowing customers to optimize texture and cost across complete formulations. This favors suppliers with application laboratories and formulation expertise because buyers often evaluate gums as combinations rather than standalone ingredients. The commercial advantage increasingly comes from predictable functionality, supply security and technical support as much as from raw gum availability.
Market Drivers
Clean-Label Texturizers Support LBG Demand
Food manufacturers continue to use locust bean gum in dairy, ice cream, plant-based foods, sauces, confectionery and pet food where viscosity, stabilization and synergy with carrageenan or xanthan are required. CAROB S.A., IFF, Tate & Lyle, Cargill, CEAMSA and other suppliers maintain dedicated LBG portfolios for these applications. Its long commercial history and plant origin make it suitable for formulations seeking familiar ingredient declarations, particularly where manufacturers want to reduce dependence on more heavily modified stabilizer systems.
Functional Fiber Creates a New Value Pool
The market is gaining incremental demand from prebiotic and fiber-focused products. CarobWay's CarobWell Biome is being commercialized in North America as a carob-based prebiotic ingredient, while other suppliers are exploring carob fiber and germ fractions for nutrition applications. This changes the economics of carob processing because pulp and processing fractions can be directed into higher-value formulations rather than lower-value feed or bulk food uses. Growth is strongest where suppliers can support health positioning with composition data, processing consistency and application support.
Mediterranean Supply Investments Improve Commercial Availability
Processing investment in Morocco and Spain is strengthening availability of higher-grade carob ingredients. Keragum commissioned modern carob-processing capacity in Morocco before its acquisition by Nexira, while CAROB S.A. maintains dedicated LBG processing and organic production capability in Mallorca. Portugal also has industrial carob processors with sizeable throughput, including Chorondo & Filhos. Greater processing capacity does not eliminate crop variability, but it improves cleaning, seed separation, storage and quality control, which supports more reliable supply to multinational food customers.
Market Restraints and Challenges
Supply Is Concentrated in a Limited Growing Belt
Commercial carob supply remains concentrated in Mediterranean climates, exposing the market to regional crop variability, harvesting economics and competition for high-quality seeds. Locust bean gum production is particularly sensitive because only a portion of the seed becomes usable endosperm. Polygal notes that the LBG yield from carob seed is around 35%, which means processors require materially more seed input than final gum output. Shortfalls in pod or seed availability can therefore move through the value chain quickly and create pronounced price changes in refined gum.
Alternative Hydrocolloids Limit Pricing Power
Guar gum, xanthan gum, tara gum, carrageenan, cellulose systems and blended stabilizers can replace part of the functional role of LBG in selected formulations. Cargill and other suppliers actively formulate alternatives when customers need lower-cost or more supply-stable systems. LBG retains advantages in specific dairy, frozen-dessert and gel systems, but large buyers can reformulate when price differentials become too wide. This limits the ability of suppliers to pass all raw-material inflation through to customers.
Carob Is Not a Universal Cocoa Substitute
Carob powder can reduce cocoa use in certain bakery, snack and beverage formulations, but its naturally sweeter and different flavor profile limits full substitution in products where cocoa taste is central. Manufacturers may also need to reformulate sugar, fat and flavor systems when introducing carob. The opportunity is therefore larger in mixed formulations, health-positioned products and novel applications than in direct replacement of established premium chocolate products.
Carob Market Segment Analysis
By Product Type
Locust Bean Gum
Locust bean gum is expected to generate approximately USD 440 million by 2031, retaining the largest product-value position. The category benefits from higher unit value than bulk powder or syrup and from established use in ice cream, dairy, plant-based products, sauces, pet food and specialized nutrition. Competition is concentrated among hydrocolloid suppliers and dedicated carob processors with the ability to control viscosity, purity, particle size and color. The 2026 acquisition of Keragum by Nexira highlights the strategic value of direct sourcing and processing control in this part of the market.
By Application
Food and Beverages
Food and beverage applications are forecast to generate approximately USD 835 million by 2031. Demand spans LBG in dairy and frozen desserts, carob powder in bakery and snacks, syrup in beverages and sweetening, and functional fibers in nutrition products. The segment benefits from several distinct demand streams rather than a single end market, which reduces dependence on traditional chocolate-alternative positioning. Product development is moving toward clean-label texture, cocoa reduction, high-fiber formulations and plant-based products where carob can provide both functionality and ingredient-story value.
By Production Method
Conventional
Conventional carob is expected to account for approximately USD 900 million by 2031, remaining dominant because the majority of commercial pod and seed supply enters standard food and ingredient channels. Organic products are growing faster in consumer-facing powders, syrups and functional foods, and several major processors offer certified organic LBG or carob derivatives. The premium is most defensible where organic certification is part of the finished-product positioning rather than in industrial formulations where functionality and price are the primary purchasing criteria.
Major Region
Europe
Europe is forecast to generate approximately USD 505 million in carob-market revenue by 2031. The region combines processing capacity, established hydrocolloid suppliers and close access to Mediterranean raw material. Spain is important in both cultivation and LBG processing, while Portugal, Greece, Cyprus and Italy support additional pod supply and finished carob products.
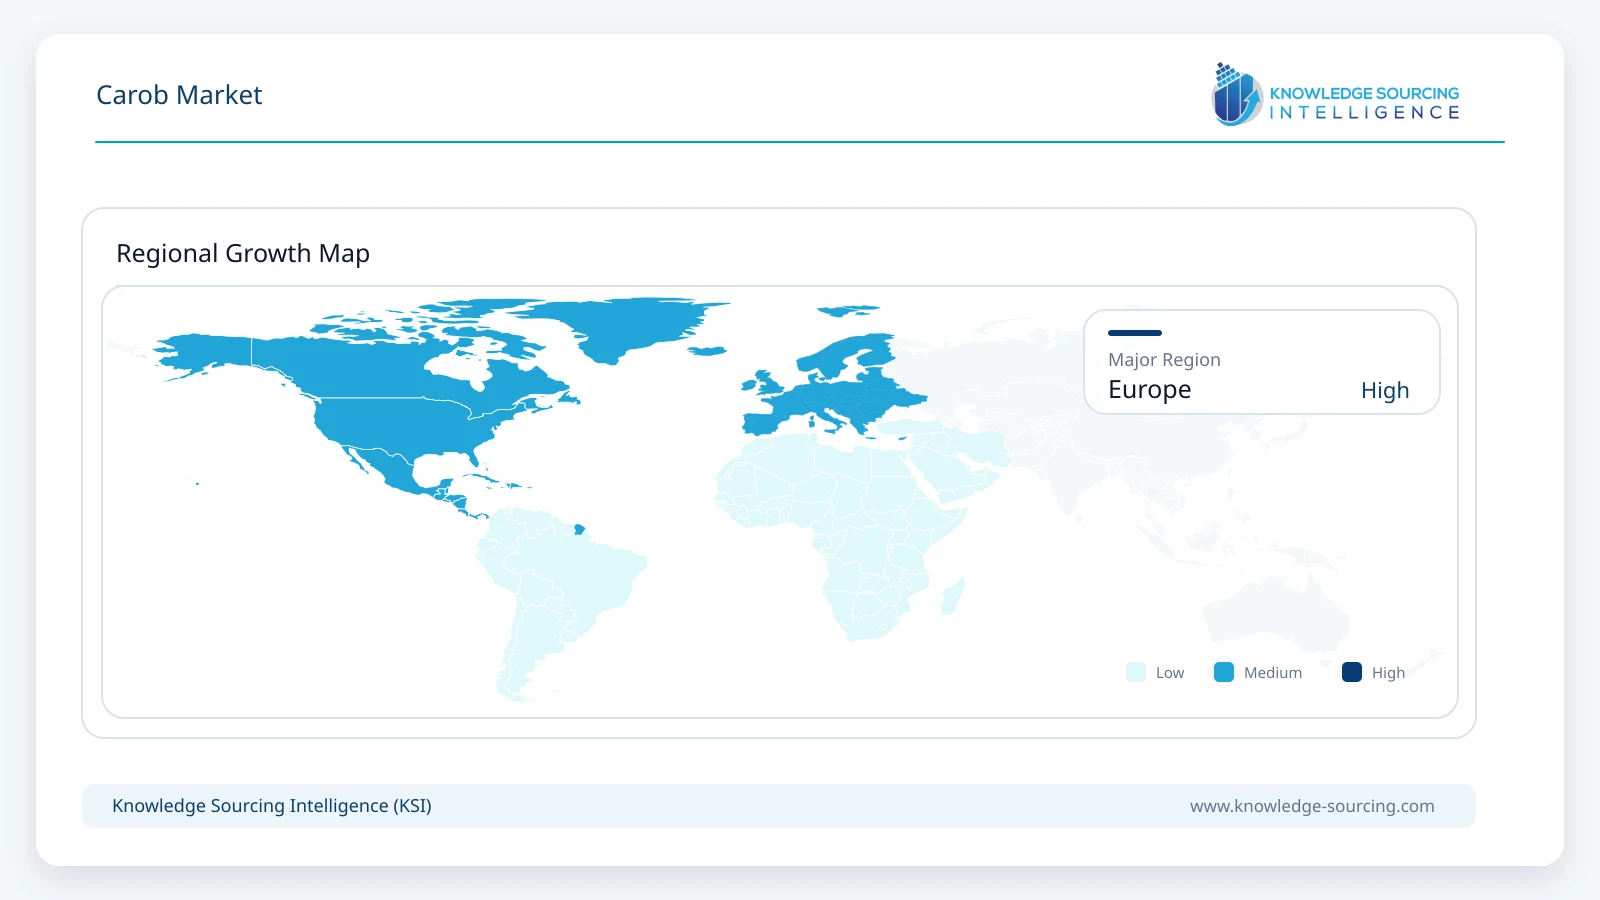
European food manufacturers also provide a stable demand base across dairy, frozen desserts, confectionery and specialty nutrition. Growth is expected to be steady rather than rapid as North America and other regions expand functional-food applications from smaller bases.
Major Country
Spain
Spain is expected to generate approximately USD 170 million in market value by 2031, supported by carob cultivation in Mediterranean regions and a dense group of processors including CAROB S.A., CEAMSA and Alimentaria ADIN. The country also serves as an ingredient-export base for LBG and related hydrocolloid systems. Investment in seed quality, organic production and processing efficiency is helping Spanish suppliers compete with expanding capacity in Morocco. The domestic market is smaller than the country's production role suggests, so a material share of industry value is tied to export-oriented processing rather than local consumption.
Competitive Environment and Analysis
Competition spans large global hydrocolloid companies, specialized locust bean gum processors and smaller carob-product manufacturers. Tate & Lyle, IFF, Cargill, Ingredion and Nexira participate through global ingredient portfolios and formulation support, while CAROB S.A., CEAMSA, Polygal and Alimentaria ADIN maintain more specialized positions in LBG and Mediterranean sourcing. These suppliers compete on viscosity performance, purity, color, food-safety certification, technical support and supply reliability rather than on raw-carob volume alone.
The 2026 acquisition of Keragum by Nexira is the most significant recent structural development in the sector. It gives Nexira direct access to Moroccan sourcing and modern LBG production while adding local cooperative relationships and traceability at origin. Morocco's increasing importance also creates a stronger competitive counterweight to the established Spanish processing base. Large food-ingredient companies can source globally, but access to high-quality seed remains a strategic advantage because final gum yield and performance depend on the quality of the starting material.
The pulp-derived side of the market is more fragmented. Creta Carob, The Australian Carob Co., Chorondo & Filhos, Stavros Parpis Foodstuffs and other regional processors sell powder, flour, syrup and related products, while CarobWay is moving toward higher-value functional ingredients. The distinction between seed and pulp economics is becoming more important because companies are trying to monetize a greater portion of each pod. Suppliers that can develop profitable outlets for gum, powder, fiber, germ and syrup are better positioned to absorb raw-material price fluctuations.
Recent Developments
· August 2026: Nexira detailed the integration of Keragum's Moroccan sourcing and LBG processing into its carob value chain, strengthening direct access to traceable raw material at origin.
· July 2026: Nexira acquired Morocco-based Keragum, adding modern locust bean gum production and local carob sourcing to its natural-ingredients business.
· 2026: CarobWay began North American commercialization of its carob-derived prebiotic platform through GRA Nutra Corp, including CarobWell Biome for functional-food and nutrition applications.
· January 2026: The European Commission amended specifications for locust bean gum (E410) under Regulation (EU) 2026/196, updating compositional and processing requirements for the food additive.
Market Outlook
The market through 2031 will become less dependent on carob's traditional positioning as a chocolate alternative and more dependent on differentiated ingredient functions. Locust bean gum will continue to generate the largest high-value revenue pool, while pulp-derived fibers, low-glycemic sweetening ingredients and specialty powders create additional outlets for the remainder of the fruit. This should improve processing economics and encourage greater integration between raw-material sourcing and ingredient development.
Supply-chain control will remain important. Recent investment in Morocco shows that leading ingredient suppliers want greater visibility over cooperatives, seed quality and primary processing rather than relying entirely on open-market sourcing. Spain should retain a strong position in processing and technical expertise, but Morocco is gaining strategic importance as both a growing and manufacturing base.
Growth will stay moderate because carob competes with several established hydrocolloids, sweeteners and cocoa alternatives. The stronger opportunities will be in applications where carob provides a specific combination of texture, fiber, natural sweetness or clean-label positioning rather than where it is used simply as a lower-cost substitute.
Carob Market Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 860 million |
| Total Market Size in 2031 | USD 1,180 million |
| Forecast Unit | Million |
| Growth Rate | 6.5% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Product Type, Application, Production Method, Geography |
| Companies |
|
Market Segmentation
By Product Type
Locust Bean Gum
Carob Powder and Flour
Carob Syrups and Concentrates
Functional Extracts, Fibers and Other Derivatives
By Application
Food and Beverages
Animal Feed and Pet Food
Nutraceuticals and Dietary Supplements
Pharmaceuticals and Medical Nutrition
Personal Care and Cosmetics
Others
By Production Method
Conventional
Organic
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Others
Europe
Spain
Portugal
Italy
Greece
United Kingdom
Germany
France
Others
Middle East and Africa
Morocco
Turkey
Israel
Saudi Arabia
UAE
Others
Asia Pacific
Australia
China
Japan
India
South Korea
Others
Table of Contents
1. INTRODUCTION
1.1. Market Overview
1.2. Market Definition
1.3. Scope of the Study
1.4. Market Segmentation
1.5. Currency
1.6. Assumptions
1.7. Base and Forecast Years Timeline
2. RESEARCH METHODOLOGY
2.1. Research Design
2.2. Research Process
3. EXECUTIVE SUMMARY
3.1. Key Findings
4. MARKET DYNAMICS
4.1. Market Drivers
4.2. Market Restraints
4.3. Market Opportunities
4.4. Porter's Five Forces Analysis
4.5. Industry Value Chain Analysis
4.6. Analyst View
5. CAROB MARKET BY PRODUCT TYPE
5.1. Introduction
5.2. Locust Bean Gum
5.3. Carob Powder and Flour
5.4. Carob Syrups and Concentrates
5.5. Functional Extracts, Fibers and Other Derivatives
6. CAROB MARKET BY APPLICATION
6.1. Introduction
6.2. Food and Beverages
6.3. Animal Feed and Pet Food
6.4. Nutraceuticals and Dietary Supplements
6.5. Pharmaceuticals and Medical Nutrition
6.6. Personal Care and Cosmetics
6.7. Others
7. CAROB MARKET BY PRODUCTION METHOD
7.1. Introduction
7.2. Conventional
7.3. Organic
8. CAROB MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. United States
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Brazil
8.3.2. Argentina
8.3.3. Others
8.4. Europe
8.4.1. Spain
8.4.2. Portugal
8.4.3. Italy
8.4.4. Greece
8.4.5. United Kingdom
8.4.6. Germany
8.4.7. France
8.4.8. Others
8.5. Middle East and Africa
8.5.1. Morocco
8.5.2. Turkey
8.5.3. Israel
8.5.4. Saudi Arabia
8.5.5. UAE
8.5.6. Others
8.6. Asia Pacific
8.6.1. Australia
8.6.2. China
8.6.3. Japan
8.6.4. India
8.6.5. South Korea
8.6.6. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Players and Strategy Analysis
9.2. Market Share Analysis
9.3. Mergers, Acquisitions, Agreements, and Collaborations
9.4. Competitive Dashboard
10. COMPANY PROFILES
10.1. Nexira
10.2. Tate & Lyle PLC
10.3. International Flavors & Fragrances Inc. (IFF)
10.4. Ingredion Incorporated
10.5. Cargill, Incorporated
10.6. CAROB S.A.
10.7. CEAMSA
10.8. Polygal AG
10.9. Alimentaria ADIN
10.10. CarobWay GmbH
10.11. Creta Carob
10.12. The Australian Carob Co.
10.13. Chorondo & Filhos, Lda.
10.14. Altrafine Gums
10.15. Lucid Colloids Limited
10.16. Stavros Parpis Foodstuffs Ltd.
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Research Methodology
11.5. Abbreviations
Navigate
Trusted by the world's leading organizations











