
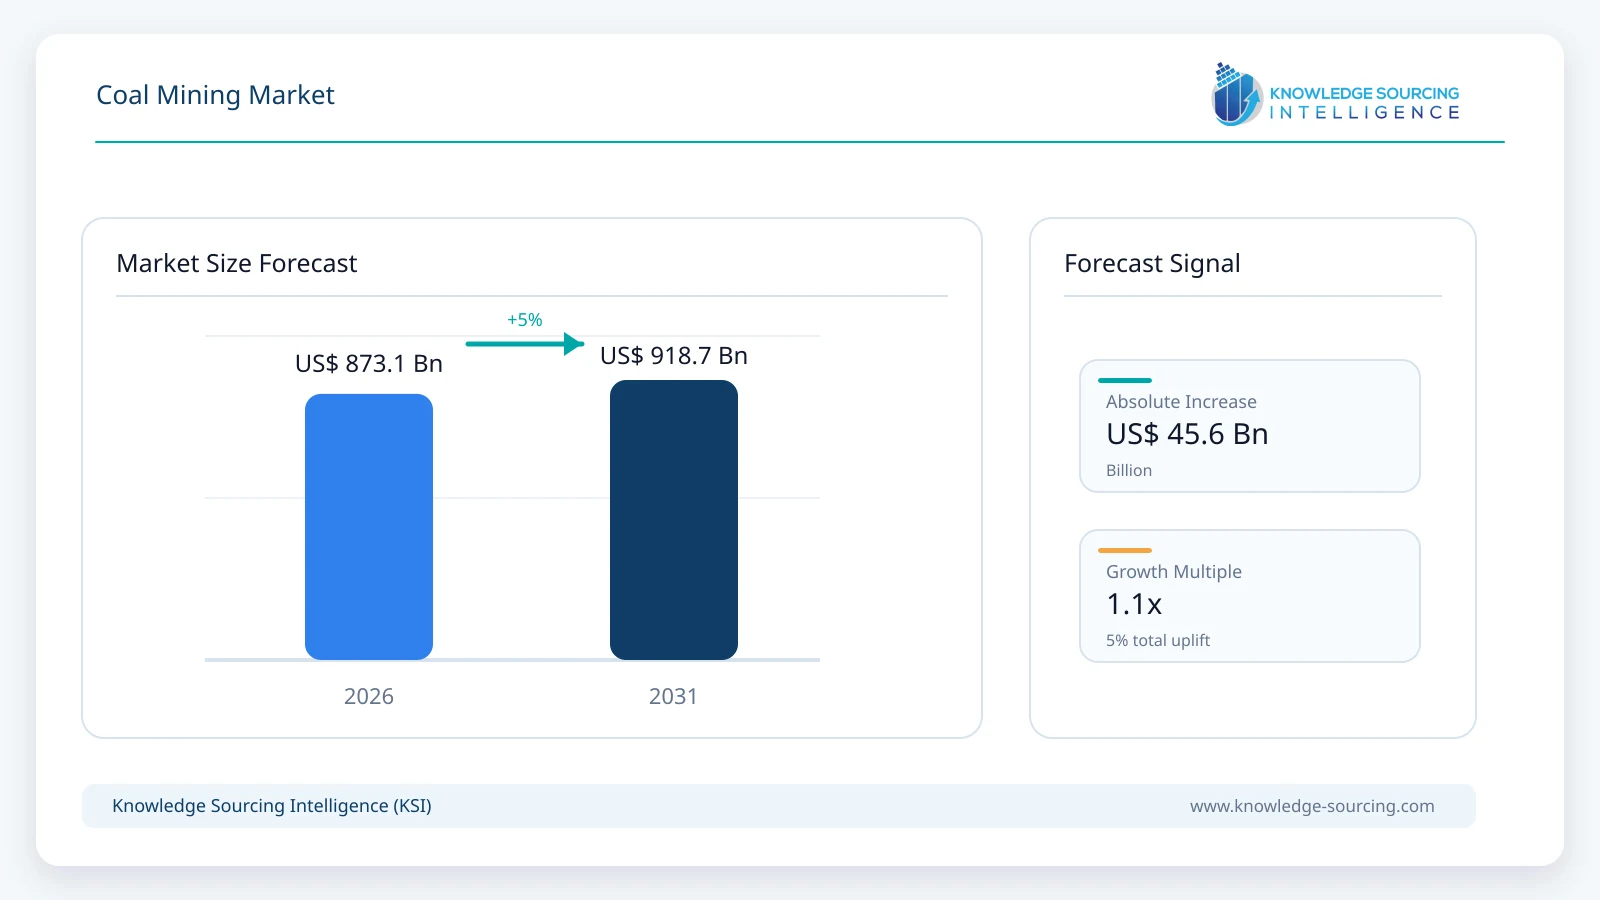
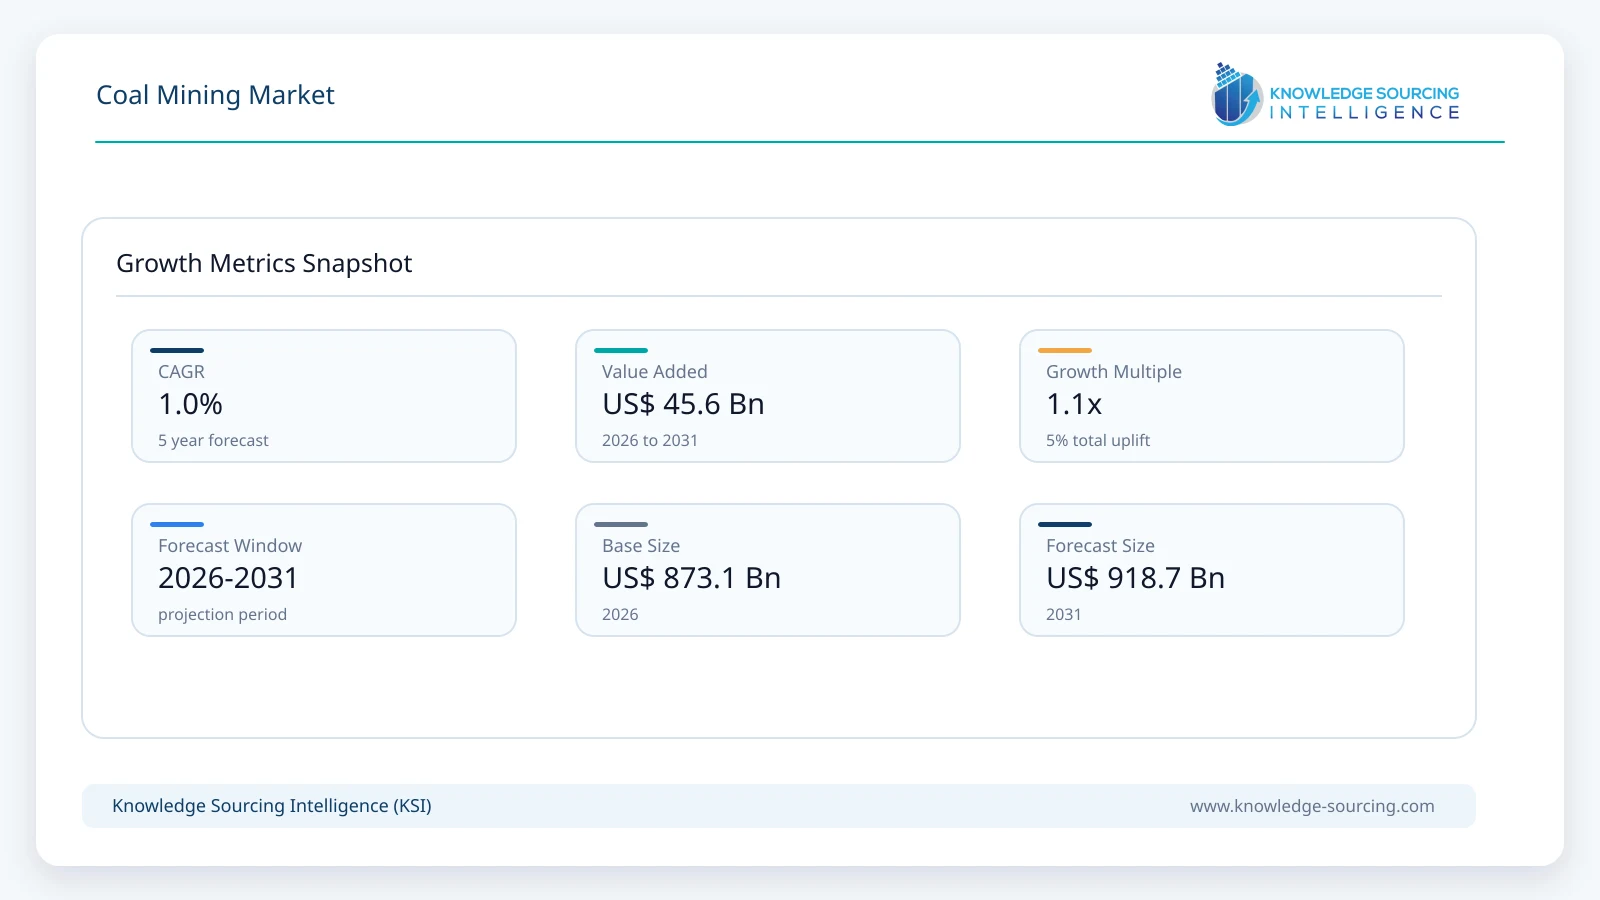
The global coal mining market is estimated at USD 873.1 billion in 2026 and is projected to reach USD 918.7 billion by 2031, representing a CAGR of approximately 1.0% during the forecast period.
Highlights:
- 1Global coal production remained near a record 9.1 billion tonnes in 2025 and is expected to stay above 9 billion tonnes in 2026.
- 2China remains the world's largest coal producer, with 2026 output expected to exceed 4.6 billion tonnes.
- 3India is expected to produce about 1.10 billion tonnes of coal in 2026, supported by energy-security policy.
- 4International thermal and metallurgical coal prices strengthened in 2026 as supply tightened and gas-market volatility increased.
- 5Seaborne coal trade fell in 2025 after a record 2024, increasing the importance of domestic production in China and India.
- 6The competitive landscape has materially changed through consolidation and asset transfers since 2024.
Coal remains one of the world's largest mined commodities by volume and an important input for both electricity generation and steelmaking. The International Energy Agency estimates that global coal production remained close to a record 9.1 billion tonnes in 2025 and is likely to stay above 9 billion tonnes again in 2026 despite a modest decline in output. China alone produced about 4.71 billion tonnes in 2025 and is expected to exceed 4.62 billion tonnes in 2026, while India's production is forecast near 1.10 billion tonnes. These two countries account for most global output and increasingly prioritize domestic supply security over import dependence.
Demand has also moved into a plateau rather than a uniform decline. The IEA reports global coal demand of 8.84 billion tonnes in 2025, up 0.3% year over year. Power generation still accounts for roughly two-thirds of global coal consumption, but demand trends differ sharply by region. China remained broadly flat, India dipped temporarily in 2025 but is supported by long-term electricity and industrial growth, while coal use continues to decline structurally across Europe and parts of North America.
The price environment improved in 2026 after weak conditions in 2025. Glencore reported a realized energy-coal price of USD 93.9 per tonne and a realized steelmaking-coal price of USD 206.9 per tonne in the first half of 2026. This difference illustrates why market value cannot be derived from one benchmark price across all tonnes. Domestic Chinese and Indian coal is generally sold at different prices and qualities from seaborne Newcastle thermal coal or premium hard coking coal, so the KSI estimate uses a weighted producer-revenue approach rather than multiplying global production by a single benchmark.
Market Trends
Domestic Production Is Becoming More Important Than International Trade
Coal markets are becoming more domestically oriented as China and India prioritize energy security. Global coal trade declined by around 4% in 2025 to about 1.48 billion tonnes after reaching a record in 2024. China's imports fell materially as strong domestic production and inventories reduced its need for foreign coal, while India's imports also softened. This means future market growth depends increasingly on domestic mining systems, captive and commercial mines, and local logistics rather than only seaborne exports.
Metallurgical Coal Retains a More Defensible Long-Term Role
Thermal coal faces the strongest substitution pressure from renewables, gas, storage and nuclear generation. Metallurgical coal has a more resilient demand base because blast-furnace steelmaking still relies on coking coal at large scale. Glencore's acquisition of the former Teck steelmaking-coal assets, Whitehaven's acquisition of Blackwater and Daunia and Warrior Met Coal's Blue Creek ramp-up all reflect continued investment in premium steelmaking coal. Metallurgical coal volumes are smaller than thermal coal, but higher realized prices increase their contribution to market value.
Portfolio Consolidation Is Reshaping the Competitive Landscape
The global producer universe has changed rapidly since 2024. Arch Resources and CONSOL Energy completed their merger in January 2025 to form Core Natural Resources. Glencore acquired Teck's steelmaking-coal business and now operates those Canadian assets within its coal portfolio. Whitehaven acquired the Blackwater and Daunia mines from BHP Mitsubishi Alliance and completed a partial sell-down of Blackwater to Nippon Steel and JFE Steel in 2025. These changes make several legacy company lists obsolete and concentrate more seaborne coal production in fewer scaled operators.
Coal Mining Is Increasingly Linked to Gasification and Value-Added Conversion
Coal-producing countries are exploring additional pathways beyond direct combustion. India approved a INR 37,500 crore program in 2026 to promote surface coal and lignite gasification projects and launched commercial-scale coal-to-ammonium-nitrate development. These initiatives do not reverse long-term decarbonization pressure, but they create demand for specific coal grades and support mine development in regions where domestic coal is treated as a strategic industrial feedstock.
Market Drivers
Electricity Security Sustains Thermal Coal Demand in Asia
Coal remains deeply embedded in power systems across China, India, Indonesia, South Africa and several Southeast Asian economies. In markets where electricity demand is rising quickly, domestic coal provides dispatchable generation and reduces exposure to imported natural gas. This role has been reinforced during periods of gas-market volatility, including the 2026 Middle East disruption, when higher gas prices increased coal's relative competitiveness in some importing markets.
Steelmaking Supports Premium Coking-Coal Demand
Blast-furnace steel production requires metallurgical coal with specific coking properties. Although scrap-based electric arc furnaces and direct-reduction technologies are growing, integrated steelmaking still represents a large share of global steel output. Premium hard coking coal therefore maintains a strategically important demand base, supporting mines in Australia, Canada, the United States and Poland even when thermal coal demand is weaker.
Energy-Security Policies Support Domestic Mine Development
Governments in major consuming countries continue to support domestic coal supply. India is expanding commercial mining, captive production and gasification, while Coal India retains a production target above 800 million tonnes. China continues to prioritize domestic output despite tighter mine-safety enforcement in 2026. These policies reduce import dependence and support mining investment even as long-term power-sector policy gradually shifts toward lower-carbon sources.
Market Restraints
Decarbonization, Financing Constraints and Overcapacity Limit Long-Term Growth
Coal faces structural pressure from renewable-energy deployment, carbon pricing, emissions regulation and coal-plant retirement in advanced economies. Financing and insurance are also more restrictive than for many other mining sectors, which can limit development of new export-oriented thermal mines. At the same time, China and India have expanded domestic output rapidly, creating periods of high inventories and weak import demand. The combination of policy pressure and supply abundance limits the ability of the market to sustain high long-term value growth even when short-term prices rise.
Global Coal Mining Market Segment Analysis
By Coal Rank
Bituminous Coal
Bituminous coal is estimated at approximately USD 500 billion in 2026 and remains the largest coal-rank segment by market value. The category includes a substantial share of globally traded thermal coal and nearly all premium metallurgical coal, giving it higher average value per tonne than lignite or lower-grade sub-bituminous material. Sub-bituminous coal remains important in Indonesia, the United States and parts of Asia, while lignite is concentrated in domestic power markets such as Germany, Turkey, parts of Eastern Europe and India. Anthracite represents a much smaller specialty market.
By Mining Method
Surface Mining
Surface mining is estimated to account for approximately USD 550 billion of market value in 2026 and remains the dominant mining method because many of the world's largest coal basins support large-scale open-cut or strip-mining operations. Australia, Indonesia, the western United States and South Africa have extensive surface production. Underground mining remains essential in China, India, Poland and parts of the United States and is especially important for selected coking-coal seams, but it generally carries higher operating and safety costs.
By End User
Power Generation
Power generation is estimated to account for approximately USD 520 billion of coal mining revenue in 2026 and remains the largest end-use segment. Thermal coal is consumed by utility and captive power plants, particularly in Asia. Steel and iron manufacturing form the second major value pool and account for a disproportionately high share of revenue because metallurgical coal trades at substantially higher prices than most thermal coal. Cement, chemicals and other industrial applications make up a smaller residual share.
By Geography
Asia Pacific
Asia Pacific is estimated at approximately USD 610 billion in 2026 and dominates global coal mining by both volume and value. China and India together account for the majority of global production, while Indonesia and Australia remain major exporters.
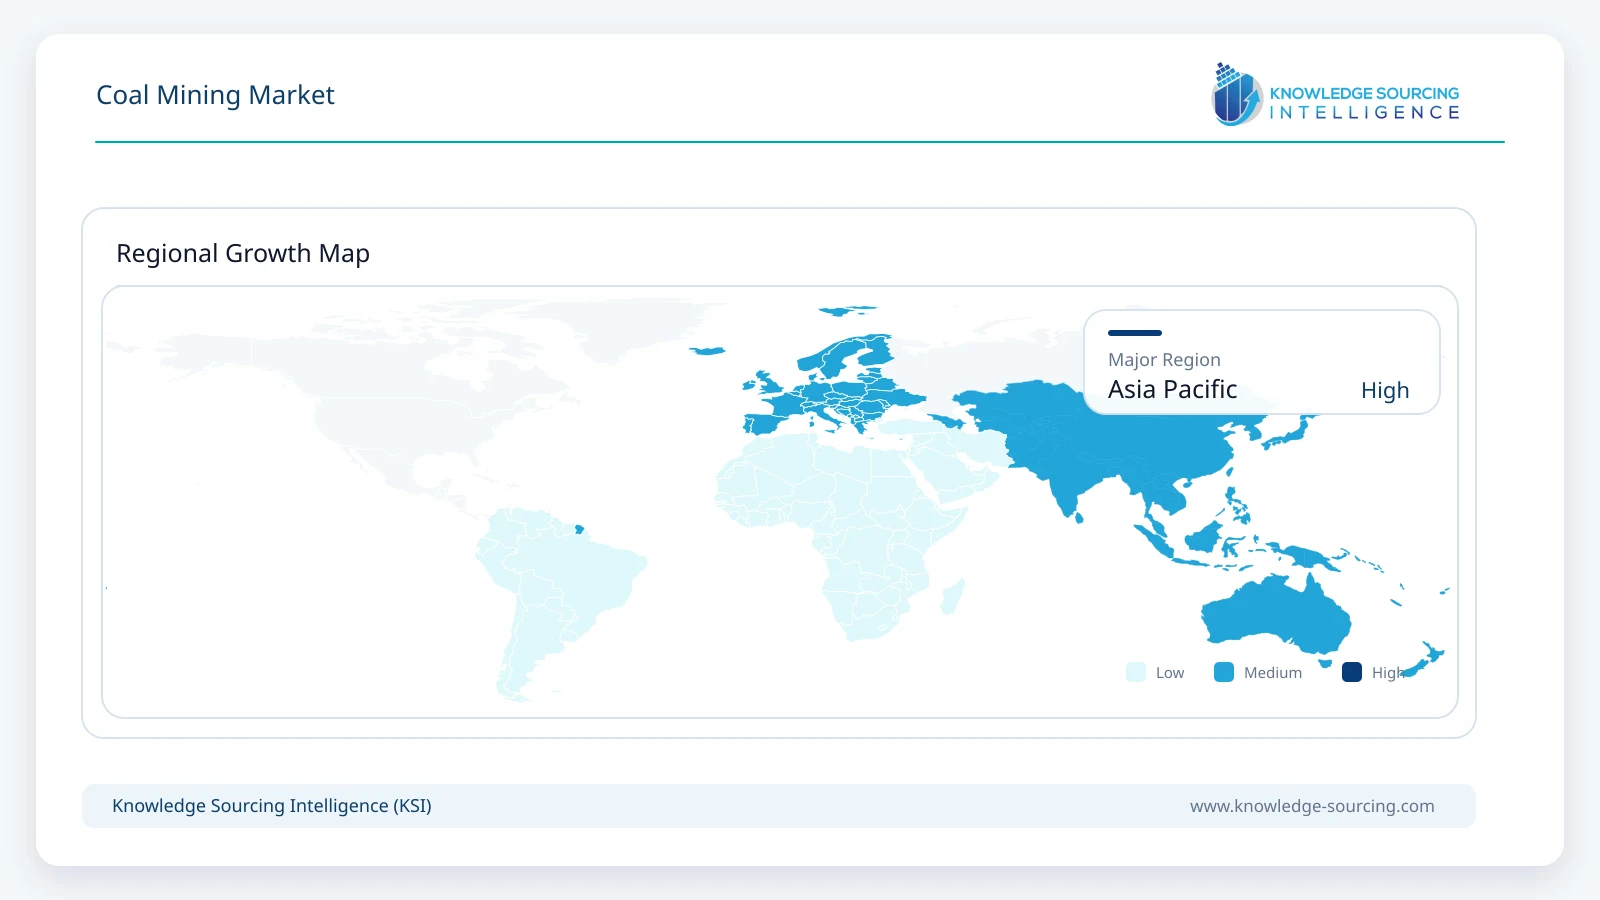
North America contributes a smaller but strategically important mix of thermal and metallurgical coal, while South Africa, Russia and Colombia remain relevant export suppliers. Europe continues to contract as coal phase-outs reduce both mining and consumption.
Competitive Environment
The coal mining market includes state-backed domestic producers, diversified global miners and specialized export-oriented companies. Coal India, China Shenhua Energy, China Coal Energy and Yankuang Energy dominate very large domestic production systems in Asia. Glencore, Peabody, Whitehaven, Core Natural Resources, Thungela, Exxaro and Adaro Andalan Indonesia combine export exposure with large operating portfolios. Warrior Met Coal, Stanmore Resources and JSW are more concentrated in metallurgical coal, while New Hope remains an important Australian thermal-coal producer.
Recent Developments
September 2026: The IEA reported that global coal production is expected to remain above 9 billion tonnes in 2026 despite a modest decline from 2025.
August 2026: Exxaro reported first-half coal production of 21.5 million tonnes, up 11%, with export sales rising 15%.
August 2026: Whitehaven reported FY2026 managed ROM production of 40.3 million tonnes and 26.0 million tonnes of equity coal sales.
August 2026: Warrior Met Coal reported 45% year-over-year production growth in Q2 as the Blue Creek mine continued to ramp up.
July 2026: Glencore reported H1 production of 47.4 million tonnes of energy coal and 13.5 million tonnes of steelmaking coal.
July 2026: Core Natural Resources continued operating as the combined company formed from Arch Resources and CONSOL Energy following the January 2025 merger.
Coal Mining Market Scope:
| Report Metric | Details |
|---|---|
| Total Market Size in 2026 | USD 873.1 billion |
| Total Market Size in 2031 | USD 918.7 billion |
| Forecast Unit | Billion |
| Growth Rate | 1.0% |
| Study Period | 2021 to 2031 |
| Historical Data | 2021 to 2024 |
| Base Year | 2025 |
| Forecast Period | 2026 – 2031 |
| Segmentation | Coal Rank, Mining Method, End User, Geography |
| Companies |
|
Market Segmentation
By Coal Rank
Lignite
Sub-Bituminous Coal
Bituminous Coal
Anthracite
By Mining Method
Surface Mining
Underground Mining
By End User
Power Generation
Steel and Iron
Cement and Industrial Heat
Chemicals and Other Uses
By Geography
North America
United States
Canada
Mexico
South America
Colombia
Brazil
Others
Europe
Poland
Germany
Czech Republic
Others
Middle East & Africa
South Africa
Botswana
Mozambique
Others
Asia Pacific
China
India
Indonesia
Australia
Mongolia
Vietnam
Others
Table of Contents
1. EXECUTIVE SUMMARY
2. MARKET SNAPSHOT
2.1. Market Overview
2.2. Market Definition
2.3. Scope of the Study
2.4. Market Segmentation
3. BUSINESS LANDSCAPE
3.1. Market Drivers
3.1.1. Electricity Security Sustains Thermal Coal Demand in Asia
3.1.2. Steelmaking Supports Premium Coking-Coal Demand
3.1.3. Energy-Security Policies Support Domestic Mine Development
3.2. Market Restraints
3.2.1. Decarbonization, Financing Constraints and Overcapacity Limit Long-Term Growth
3.3. Market Opportunities
3.4. Porter's Five Forces Analysis
3.5. Industry Value Chain Analysis
3.6. Policies and Regulations
3.7. Strategic Recommendations
4. TECHNOLOGICAL OUTLOOK
4.1. Mine Automation and Autonomous Haulage
4.2. Underground Mine Digitization and Safety Systems
4.3. Coal Beneficiation and Preparation
4.4. Methane Monitoring and Emissions Reduction
4.5. Coal and Lignite Gasification
4.6. Electrification and Renewable Power at Mine Sites
5. GLOBAL COAL MINING MARKET BY COAL RANK
5.1. Introduction
5.2. Lignite
5.3. Sub-Bituminous Coal
5.4. Bituminous Coal
5.5. Anthracite
6. GLOBAL COAL MINING MARKET BY MINING METHOD
6.1. Introduction
6.2. Surface Mining
6.3. Underground Mining
7. GLOBAL COAL MINING MARKET BY END USER
7.1. Introduction
7.2. Power Generation
7.3. Steel and Iron
7.4. Cement and Industrial Heat
7.5. Chemicals and Other Uses
8. GLOBAL COAL MINING MARKET BY GEOGRAPHY
8.1. Introduction
8.2. North America
8.2.1. United States
8.2.2. Canada
8.2.3. Mexico
8.3. South America
8.3.1. Colombia
8.3.2. Brazil
8.3.3. Others
8.4. Europe
8.4.1. Poland
8.4.2. Germany
8.4.3. Czech Republic
8.4.4. Others
8.5. Middle East & Africa
8.5.1. South Africa
8.5.2. Botswana
8.5.3. Mozambique
8.5.4. Others
8.6. Asia Pacific
8.6.1. China
8.6.2. India
8.6.3. Indonesia
8.6.4. Australia
8.6.5. Mongolia
8.6.6. Vietnam
8.6.7. Others
9. COMPETITIVE ENVIRONMENT AND ANALYSIS
9.1. Major Producers and Strategy Analysis
9.2. Thermal versus Metallurgical Coal Positioning
9.3. Domestic versus Export Market Exposure
9.4. Consolidation, Asset Transfers and Mine Development
9.5. Competitive Dashboard
10. COMPANY PROFILES
10.1. Coal India Limited
10.2. China Shenhua Energy Company Limited
10.3. China Coal Energy Company Limited
10.4. Yankuang Energy Group Company Limited
10.5. Glencore plc
10.6. Core Natural Resources, Inc.
10.7. Peabody Energy Corporation
10.8. Whitehaven Coal Limited
10.9. Exxaro Resources Limited
10.10. Thungela Resources Limited
10.11. Warrior Met Coal, Inc.
10.12. New Hope Corporation Limited
10.13. Stanmore Resources Limited
10.14. Jastrz?bska Spó?ka W?glowa S.A. (JSW)
10.15. PT Adaro Andalan Indonesia Tbk
11. APPENDIX
11.1. Currency
11.2. Assumptions
11.3. Base and Forecast Years Timeline
11.4. Key Benefits for Stakeholders
11.5. Research Methodology
11.6. Abbreviations
Navigate
Trusted by the world's leading organizations











